
 Commercial Aircraft Propeller Systems Market | 2026-2036
Commercial Aircraft Propeller Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Propeller Systems Market Outlook
A capital-intensity divergence between integrated aerospace conglomerates and specialized propeller manufacturers is reorganizing competitive dynamics in commercial aircraft propeller systems. Dowty Propellers leverages its parent company's aerostructures footprint to sustain composite blade programs with captive materials science. MT-Propeller Entwicklung GmbH anchors its position through handcrafted five-blade designs for high-performance turboprops. Hartzell Propeller competes by controlling aftermarket distribution channels across North American general aviation.
Commercial aircraft propeller systems convert engine shaft power into aerodynamic thrust through variable-pitch or constant-speed blade configurations, typically spanning 2.0 to 4.2 meters in diameter and operating at rotational speeds between 1,200 and 2,400 RPM depending on airframe category. Aluminum and composite materials dominate blade construction, with carbon-fiber reinforced polymers displacing traditional alloys in newer designs seeking weight reduction and fatigue resistance. Constant-speed propeller systems command the largest installed base among product types due to their prevalence in regional turboprop platforms, while composite material adoption accelerates fastest as manufacturers pursue longer inspection intervals and corrosion immunity. Military aviation application demand remains structurally constrained by procurement cycles, whereas MRO providers represent an expanding margin pool as aging fleets extend service lives.
FAA Part 35 airworthiness standards and EASA CS-P certification requirements govern blade strength, fatigue life, and ice-protection testing, compelling manufacturers to maintain dual-approval testing infrastructure for transatlantic market access. EPA and ICAO-aligned noise regulations progressively tighten maximum perceived noise levels during takeoff and approach phases, pushing OEMs toward swept-tip and multi-blade configurations. Stakeholders must monitor emerging sustainable aviation fuel compatibility requirements and their implications for propeller elastomer seal and hub material specifications.
Market Dynamics
Composite blade architectures are fragmenting the installed base of aluminum-dominant propeller fleets as regional carriers pursue extended inspection intervals and corrosion immunity under tightening EASA and FAA mandates.
Growth Catalysts
- EASA CS-P Certification Harmonization:Dual-approval testing infrastructure investments by manufacturers unlock transatlantic market access and accelerate platform certification timelines for new regional turboprop entrants.
- Indonesia's Inter-Island Network Expansion:Archipelago geography drives fleet modernization for short-haul connectivity, concentrating demand for high-cycle-capable constant-speed propeller systems.
- Carbon-Fiber Reinforced Polymer Adoption:Weight reduction and fatigue resistance properties enable longer service intervals, reducing lifecycle operating costs for agricultural aviation operators in Brazil.
Market Restraints
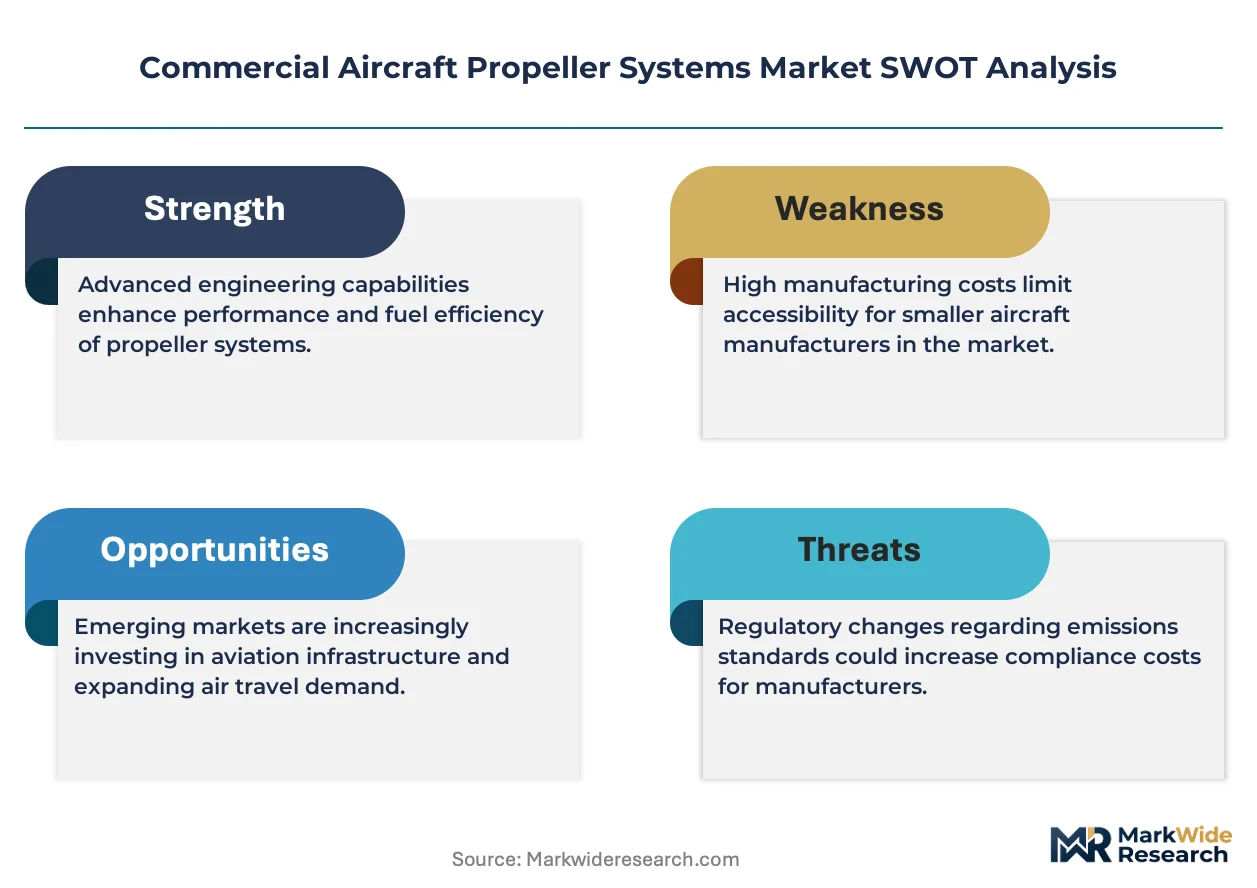
- Titanium and Nickel Alloy Input Volatility:Hub and retention component material costs fluctuate with aerospace-grade metal supply constraints, compressing margin structures for specialized manufacturers without captive sourcing.
- Dual-Approval Testing Burden:FAA Part 35 and EASA CS-P parallel certification requirements impose redundant validation infrastructure, raising fixed cost barriers for market entry.
- Turbofan Substitution in 70-Seat Segments:Jet engine efficiency improvements erode turboprop economics on longer stage lengths, constraining addressable market expansion for propeller OEMs.
Strategic Opportunities
- Sustainable Aviation Fuel Compatibility Mandates:Emerging elastomer seal and hub material specifications create first-mover advantage for suppliers with advanced materials science capabilities.
- MRO Provider Channel Integration:Aging fleet extension programs concentrate aftermarket revenue pools, rewarding manufacturers with captive distribution networks.
- Ice-Protection System Convergence:Electro-thermal and pneumatic de-icing technology integration with composite blade architectures opens platform differentiation for cold-climate operators.
Industry Challenges
- Composite Repair Technician Scarcity:Specialized laminate restoration and non-destructive testing expertise shortages constrain MRO throughput capacity.
- Variable-Pitch Mechanism Certification Timelines:Hub and blade retention system fatigue testing protocols extend new product introduction cycles beyond 24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Propeller Systems Market |
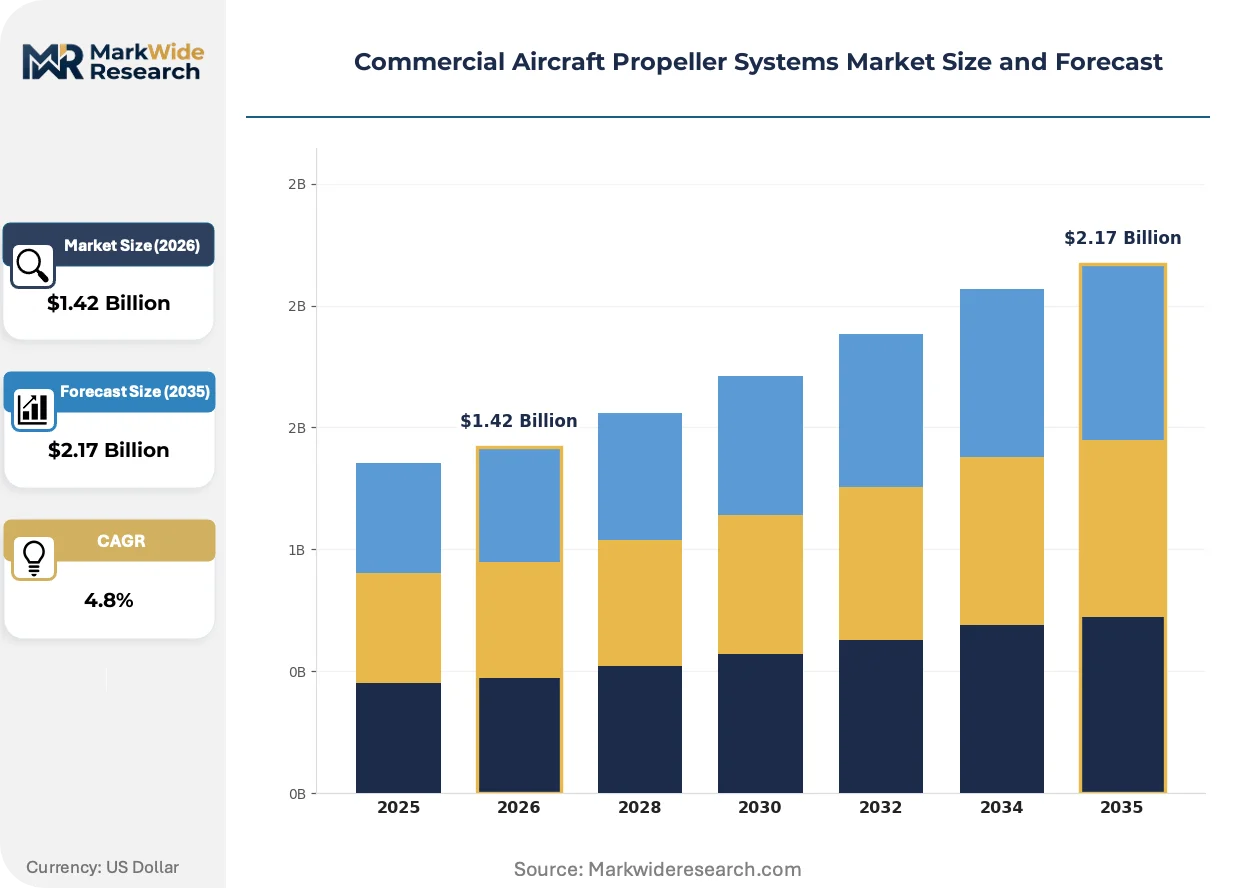
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Speed, Variable Pitch, Fixed Pitch, Retractable End User: Aircraft Manufacturers, MRO Providers, Fleet Operators, Defense Forces Material: Aluminum, Composite, Steel, Magnesium Application: Commercial Aviation, General Aviation, Military Aviation, Agricultural Aviation |
| Companies Covered | Hartzel Propeller, Dowty Propellers, McCauley Propeller Systems, Hartzell Propeller, MT-Propeller Entwicklung GmbH, Ratier-Figeac, UTC Aerospace Systems, Collins Aerospace, Aermacchi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Propeller Systems Market Strategic Shifts
Swept-tip aerodynamic configurations and multi-blade density architectures are actively reshaping noise-compliance strategies as regulatory perceived-noise limits tighten across takeoff and approach phases.
Carbon-fiber reinforced polymer blade construction is fragmenting traditional aluminum-dominated fleet compositions. Regional turboprop operators in Southeast Asia adopt composite architectures at accelerated replacement cycles. The technology is fragmenting aftermarket service revenue toward specialized composite repair facilities and away from legacy metal-working MRO providers.
EPA and ICAO-aligned noise regulations are progressively tightening maximum perceived noise levels during critical flight phases. OEMs respond with swept-tip geometries and five-blade configurations that reduce acoustic signature without sacrificing thrust efficiency. High-density urban approach corridors in the United States and European Union impose the strictest operational constraints, forcing fleet operators toward earlier-generation aircraft retirement.
After-sales service unbundling is separating propeller overhaul from engine maintenance contracts. Regional carriers and agricultural operators now procure blade inspection and hub refurbishment through independent MRO channels rather than OEM-integrated programs. Brazil's agricultural aviation sector exhibits the most pronounced shift, with operators negotiating component-level service agreements to optimize seasonal utilization rates.
Commercial Aircraft Propeller Systems Market Segmentation
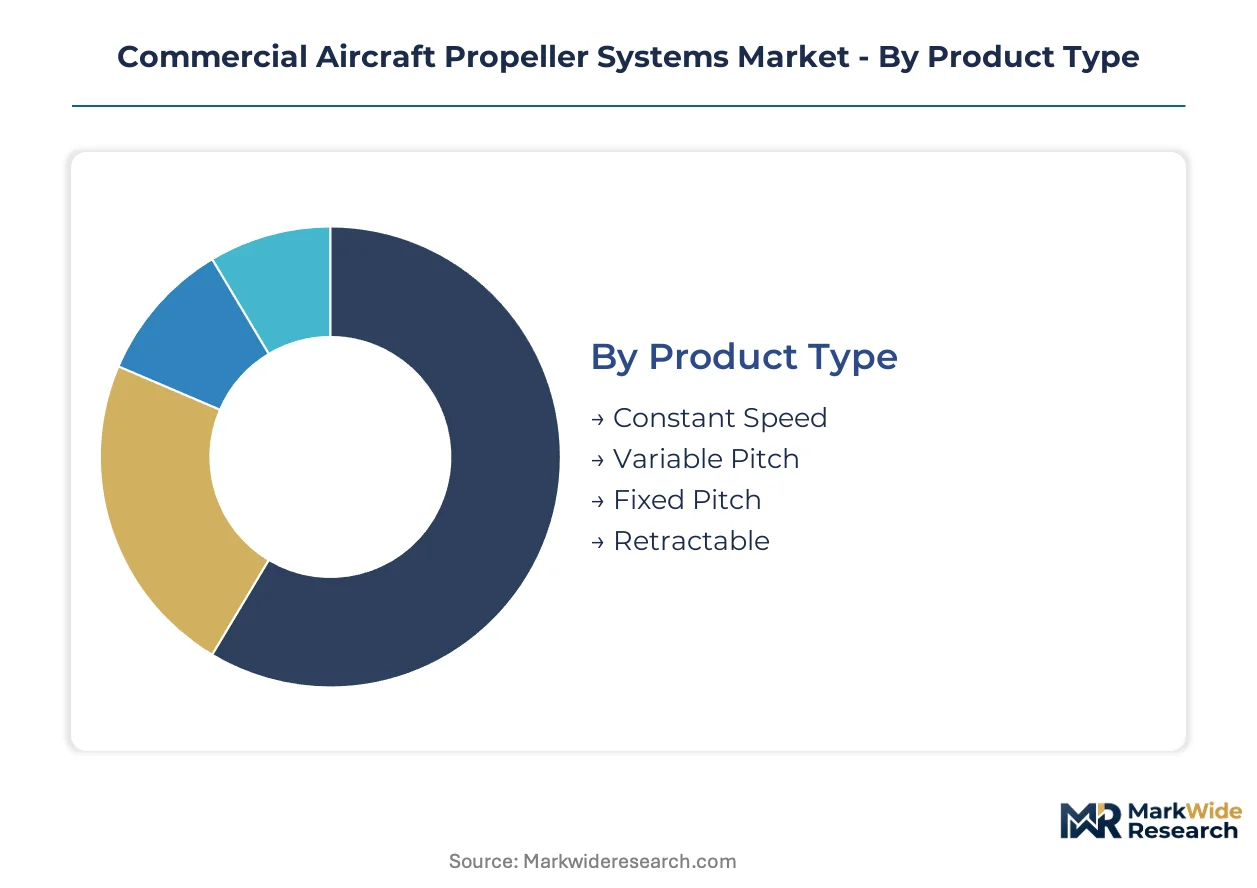
Propeller system segmentation reveals divergent procurement patterns across operator types and certification requirements. Material composition and pitch control architecture determine lifecycle economics and regulatory compliance pathways for each end-use category.
Product Type:
Domestic fleet modernization concentrates demand for constant-speed systems in Indonesia and Brazil, while export-led contracts from European turboprop OEMs drive variable-pitch and retractable configurations.
- Constant Speed:Blade pitch adjusts automatically to maintain optimal RPM across varying flight conditions and power settings. Regional turboprop operators in Indonesia's inter-island networks favor these systems for high-cycle operations under EASA CS-P fatigue requirements. Demand concentrates where stage lengths remain below 300 nautical miles.
- Variable Pitch:Pilot-actuated blade angle control enables thrust modulation independent of engine speed. Agricultural aviation operators in Brazil specify these configurations for precision maneuvering during crop-dusting operations. The segment tracks seasonal utilization patterns tied to planting and harvest cycles.
- Fixed Pitch:Simpler hub architecture with factory-set blade angle serves cost-sensitive general aviation training fleets.
- Retractable:Folding-blade mechanisms for amphibious and special-mission aircraft occupy niche military and search-rescue applications.
Constant speed commands the established base. The steepest expansion runs through variable pitch.
End User:
Cost tier stratification separates OEM-integrated procurement from independent aftermarket channels, with fleet operators occupying the mid-tier negotiation position.
- Aircraft Manufacturers:Airframe OEMs specify propeller systems during platform certification, locking in multi-year supply agreements. Composite blade programs at Dowty Propellers and Hartzell flow through this channel for new ATR and Dash 8 production.
- MRO Providers:Independent overhaul facilities now unbundle propeller maintenance from engine contracts. Brazil's agricultural operators negotiate component-level service agreements to optimize seasonal cash flows. The segment captures margin pools from aging fleet extensions.
- Fleet Operators:Regional carriers in Southeast Asia procure replacement blades and hub refurbishment through direct manufacturer relationships.
- Defense Forces:Military procurement cycles constrain volume, with specialized ice-protection and stealth-coating requirements extending certification timelines.
Aircraft manufacturers anchor procurement volume. MRO providers are climbing the fastest as fleet age extends.
Material:
Volume concentration favors aluminum in legacy fleets, while margin accrues to composite suppliers with certified repair networks.
- Composite:Carbon-fiber reinforced polymer construction delivers weight reduction and corrosion immunity for extended inspection intervals. Regional turboprop operators in Indonesia adopt these architectures to minimize downtime under high-frequency schedules. FAA Part 35 fatigue testing protocols govern blade certification.
- Aluminum:Traditional alloy construction dominates existing installed base with established MRO infrastructure and technician training pathways. Agricultural aviation in Brazil retains aluminum for cost-sensitive operations where damage tolerance outweighs weight considerations.
- Steel:Hub and retention components utilize aerospace-grade alloys for strength-to-weight ratios in high-stress installations.
- Magnesium:Lightweight hub applications persist in legacy general aviation platforms with limited new production.
Aluminum retains the installed base. Composite gains share fastest on replacement cycles and regulatory pressure.
Application:
Customer type fragmentation separates commercial certification requirements from agricultural operational patterns and military procurement constraints.
- Commercial Aviation:Regional turboprop platforms require constant-speed systems with swept-tip geometries for noise compliance under EPA and ICAO-aligned regulations. Indonesia's archipelago networks drive fleet density for short-haul connectivity.
- Agricultural Aviation:Crop-dusting and aerial application operators in Brazil prioritize variable-pitch maneuverability and damage-resistant aluminum blades. Seasonal utilization peaks concentrate maintenance demand in pre-planting windows.
- General Aviation:Training and private aircraft fleets balance acquisition cost against simplicity in fixed-pitch configurations.
- Military Aviation:Procurement cycle timing and specialized mission requirements constrain addressable volume for standard commercial architectures.
Commercial aviation commands the established base. Agricultural aviation expands most quickly on fleet modernization in Brazil.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with European suppliers serving FAA-certification requirements, while Indonesian and Brazilian operators absorb premium differentials for composite blade architectures under tightening EASA CS-P mandates.
United States
Regional turboprop modernization drives constant-speed system procurement for short-haul networks. FAA Part 35 fatigue testing protocols govern blade certification timelines for new platform entries. Wichita, Kansas anchors general aviation propeller manufacturing clusters where Hartzell Propeller maintains captive distribution infrastructure.
Indonesia
Archipelago geography forces inter-island fleet expansion with high-cycle operational profiles. EASA CS-P harmonization requirements accelerate dual-approval testing investments by suppliers serving Garuda Indonesia subsidiaries. Jakarta and Surabaya concentrate MRO provider networks unbundling propeller overhaul from engine contracts.
Brazil
Agricultural aviation operators modernize crop-dusting fleets under ANVISA aerial application safety mandates. Variable-pitch configurations dominate seasonal utilization patterns tied to soybean and sugarcane planting windows. São Paulo state clusters independent MRO facilities negotiating component-level service agreements.
Germany
MT-Propeller Entwicklung GmbH anchors European handcrafted five-blade production for high-performance turboprops. REACH chemical compliance and EU Green Deal sustainable aviation fuel compatibility requirements reshape elastomer seal specifications. Baden-Württemberg hosts composite materials science R&D tied to swept-tip aerodynamic programs.
United Kingdom
Dowty Propellers leverages parent-company aerostructures integration for composite blade programs with captive supply chains. CAA alignment with EASA CS-P certification streamlines transatlantic market access for new regional platform suppliers. Gloucestershire manufacturing clusters concentrate on carbon-fiber reinforced polymer production for ATR and Dash 8 integration.
Commercial Aircraft Propeller Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated aerospace conglomerates commanding composite materials science capabilities while specialized manufacturers compete on handcrafted production and aftermarket channel control. The vendor base organizes into three strategic tiers: parent-company-integrated suppliers with captive aerostructures footprints, independent specialists with certification depth in specific blade architectures, and aftermarket-focused distributors controlling North American general aviation service networks. Dominant competitive moves include M&A-driven portfolio diversification into ice-protection system integration and strategic partnerships locking multi-year supply agreements with regional turboprop OEMs during platform certification windows.
Within the integrated-tier archetype, Dowty Propellers and Collins Aerospace represent parent-company-leveraged positioning where aerostructures integration enables composite program sustainability. MT-Propeller Entwicklung GmbH occupies the specialist-manufacturer position exemplifying handcrafted five-blade design depth for high-performance applications. Hartzell Propeller anchors the aftermarket-distribution archetype through channel control across North American general aviation service networks. These three player types collectively illustrate how capital-intensity divergence between conglomerate and specialized manufacturing reorganizes competitive dynamics without requiring specific product or technology claims about individual entities.
| Leading Market Players |
|---|
| Hartzel Propeller |
| Dowty Propellers |
| McCauley Propeller Systems |
| Hartzell Propeller |
| MT-Propeller Entwicklung GmbH |
| Ratier-Figeac |
| UTC Aerospace Systems |
| Collins Aerospace |
| Aermacchi |
| Others |
Value Chain & Pricing Dynamics
Composite blade lead-times stretching 180-240 days from order placement to certified delivery concentrate pricing power with manufacturers holding dual FAA Part 35 and EASA CS-P approval infrastructure. Inventory carrying costs for aerospace-grade carbon-fiber prepreg and titanium hub alloys amplify working capital intensity, compressing margin structures for specialized suppliers without parent-company balance sheet backing.
Pricing Analysis
Configured-to-order pricing for swept-tip five-blade composite systems commands 35-50% premiums over standard aluminum four-blade configurations. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation anchored in certification tier (FAA Part 35 fatigue rating) and after-sales service bundling. Cost compression in the aluminum segment intensifies as Brazilian agricultural operators negotiate component-level MRO contracts. Fleet operators in Indonesia's inter-island networks exhibit lowest price sensitivity due to operational downtime costs.
Supply Chain Analysis
Inventory cycles for carbon-fiber prepreg and titanium forgings extend 90-120 days, exposing manufacturers to aerospace-grade metal price volatility. Supply concentrates in the United States, Germany, and the United Kingdom for blade fabrication, with Japan and South Korea feeding specialized resin systems. Raw material dependencies include carbon-fiber tow, epoxy resin systems, and aerospace-grade titanium alloys. Single-source vulnerability for FAA-certified hub castings from specialized foundries elevates supply risk. Distribution runs through OEM-integrated channels for new platforms and independent MRO networks for aftermarket refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft propeller systems function as a service-attach opportunity where MRO revenue pools expand faster than new-blade hardware sales as aging fleets extend service lives. Aftermarket channel control and composite repair certification capabilities now determine enterprise value more than production volume.
For Market Incumbents: Secure composite repair network certification before technician scarcity hardens into structural constraint. Lock multi-year supply agreements with ATR and Dash 8 platform OEMs during certification windows to defend against turbofan substitution in 70-seat segments. Build backward integration into carbon-fiber prepreg processing to offset aerospace-grade titanium alloy cost volatility. For New Entrants and Emerging Players: Differentiate on ice-protection system integration with electro-thermal composite blade architectures for cold-climate operators. Target Brazil's agricultural aviation MRO segment, where independent facilities negotiating component-level service agreements remain underpenetrated by OEM-integrated programs. Pursue strategic partnerships with regional turboprop lessors seeking bundled propeller overhaul capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because aftermarket channel fragmentation rewards scale in composite repair certification and technician training infrastructure. Acquisition candidates include independent MRO providers with EASA CS-P repair station approvals and captive distribution in Southeast Asian archipelago networks. Monitor sustainable aviation fuel compatibility mandate timing as inflection indicator for elastomer seal and hub material specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Repair Network Certification | FAA Part 35 repair station approvals capture MRO margin pools from aging aluminum fleet conversions. |
| Dual-Approval Testing Infrastructure Investment | EASA CS-P and FAA Part 35 parallel certification unlocks transatlantic platform supply agreements. |
| Ice-Protection System Integration | Electro-thermal blade architectures differentiate offerings for Scandinavian and Canadian cold-climate operators. |
| Sustainable Aviation Fuel Compatibility Program | Advanced elastomer seal specifications align with EU Green Deal and EPA emission reduction pathways. |
| MRO Channel Unbundling | Independent overhaul contracts separate propeller maintenance from engine service agreements in Brazil and Indonesia. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA type certificate data, EASA CS-P certification filings, and regional turboprop fleet registries. Primary interviews engaged propulsion system procurement directors at regional airlines, composite repair station managers, and agricultural aviation fleet operators. Secondary validation drew from customs trade databases for carbon-fiber and titanium alloy flows, SEC filings from parent-company aerostructures suppliers, and ANVISA aerial application safety mandate documentation. Bottom-up triangulation across blade replacement cycle assumptions and top-down reconciliation against OEM production schedules anchored volume estimates.
Segmentation dimensions modeled include product type (constant-speed, variable-pitch, fixed-pitch, retractable), material composition (composite, aluminum, steel, magnesium), end-user category (aircraft manufacturers, MRO providers, fleet operators, defense forces), and application (commercial aviation, agricultural aviation, general aviation, military aviation). CAGRs derived from regression analysis against regional turboprop delivery forecasts and fleet age distributions. Industry-specific inputs incorporated EASA CS-P harmonization timeline assumptions and sustainable aviation fuel seal compatibility mandate progression.
The analysis sits within stated boundaries; outcomes outside current FAA Part 35 and EASA CS-P regulatory frameworks would require recalibration. Forecasts reflect assumptions regarding composite blade replacement cycle acceleration and technician training pipeline expansion. Specific risk factors include titanium alloy supply disruption, turbofan efficiency improvements in 70-seat segments, and delays in sustainable aviation fuel certification standards. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Actuator Market