
 Military Power Solutions Market | 2026-2036
Military Power Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Military Power Solutions Market Intelligence
Buyer concentration is expanding across NATO defense procurement agencies as joint capability requirements consolidate demand under framework contracts. EnerSys leverages its global manufacturing footprint to supply sealed lead-acid and lithium-ion battery systems for tactical vehicles across multiple allied forces. Cummins Inc. anchors the generator segment with battle-hardened diesel power units purpose-built for forward operating bases. SAFT Groupe SA specializes in high-energy-density cell chemistry for submarine and aerospace applications where thermal stability governs specification compliance.
Military power solutions encompass portable, mobile, and fixed electrical energy systems engineered to deliver regulated output between 12V and 400V DC or 120V/208V AC under extreme temperature, shock, and electromagnetic interference conditions. These systems integrate chemical storage, combustion prime movers, or photovoltaic harvesters with power conditioning electronics to sustain command networks, weapon platforms, and life-support equipment in denied logistics environments. Batteries and fuel cells represent the fastest-expanding technology pair as silent-signature requirements displace small tactical generators from reconnaissance and special operations missions. Conventional generator sets retain margin concentration in heavy armor and naval propulsion auxiliaries where load density exceeds current fuel cell output ceilings. Ground forces and aerial platforms split the application growth trajectory between dismounted soldier power and more-electric aircraft architectures.
The US Department of Defense mandates MIL-STD-810H environmental compliance and MIL-STD-461G electromagnetic compatibility certification for all fielded power equipment, creating a de facto barrier for non-domestic suppliers absent testing partnerships. NATO's Standardization Agreement 4370 for interoperable electrical interfaces shapes multinational procurement specifications and limits proprietary connector architectures. The EU Green Deal's defense carve-out under the European Defence Fund is channeling development contracts toward hybrid renewable-diesel systems for expeditionary use. Stakeholders must weigh certification cost recovery against the strategic premium of dual-use energy platforms that bridge military specification and civilian resilience markets.
Market Dynamics
Silent-watch power requirements are compressing procurement cycles for chemical energy storage across NATO expeditionary forces, while the US Department of Defense's tactical electrification mandate redirects program budgets from combustion prime movers toward battery-diesel hybrid architectures.
Growth Catalysts
- EU Green Deal carve-out:The European Defence Fund channels development contracts toward hybrid renewable-diesel systems, accelerating expeditionary power modernization across Bundeswehr and allied continental forces.
- MIL-STD-810H compliance:Environmental certification mandates from the US Department of Defense create captive demand for domestic testing partnerships, reinforcing supplier relationships with established defense contractors.
- Fuel cell chemistry advances:High-energy-density cell architectures from submarine applications are migrating into armored vehicle silent-watch systems, extending operational endurance without thermal signature.
Market Restraints
- Lithium supply concentration:Cathode material processing clusters in East Asian chemical hubs expose NATO defense procurement to concentrated supply risk for high-rate battery cells.
- MIL-STD-461G certification cost:Electromagnetic compatibility testing for conducted emissions and radiated susceptibility adds six-figure qualification expenses that non-domestic suppliers struggle to recover.
- Load density ceilings:Current solid-oxide fuel cell output limits prevent displacement of diesel generator sets in heavy armor and naval propulsion auxiliaries where power demand exceeds available cell stack density.
Strategic Opportunities
- More-electric aircraft architectures:Converging power electronics and high-temperature superconductors enable distributed power management in next-generation aerial platforms, opening specification windows for integrated energy system suppliers.
- Poland's defense modernization:Accelerated procurement under the country's technical modernization plan creates uncontracted demand for portable power systems supporting forward-based NATO formations.
- Photovoltaic-diesel hybrids:Expeditionary microgrid contracts under NATO's Standardization Agreement 4370 reward suppliers with dual-use renewable platforms bridging military specification and civilian resilience markets.
Industry Challenges
- Power electronics integration:Synchronizing wide-bandgap semiconductor controls with legacy 28V DC vehicle bus architectures demands specialized firmware talent scarce in traditional battery system houses.
- Multi-standard certification timelines:Parallel qualification against MIL-STD-810H, MIL-STD-461G, and NATO STANAG 4370 stretches product development cycles while program offices compress fielding schedules.
Report Scope
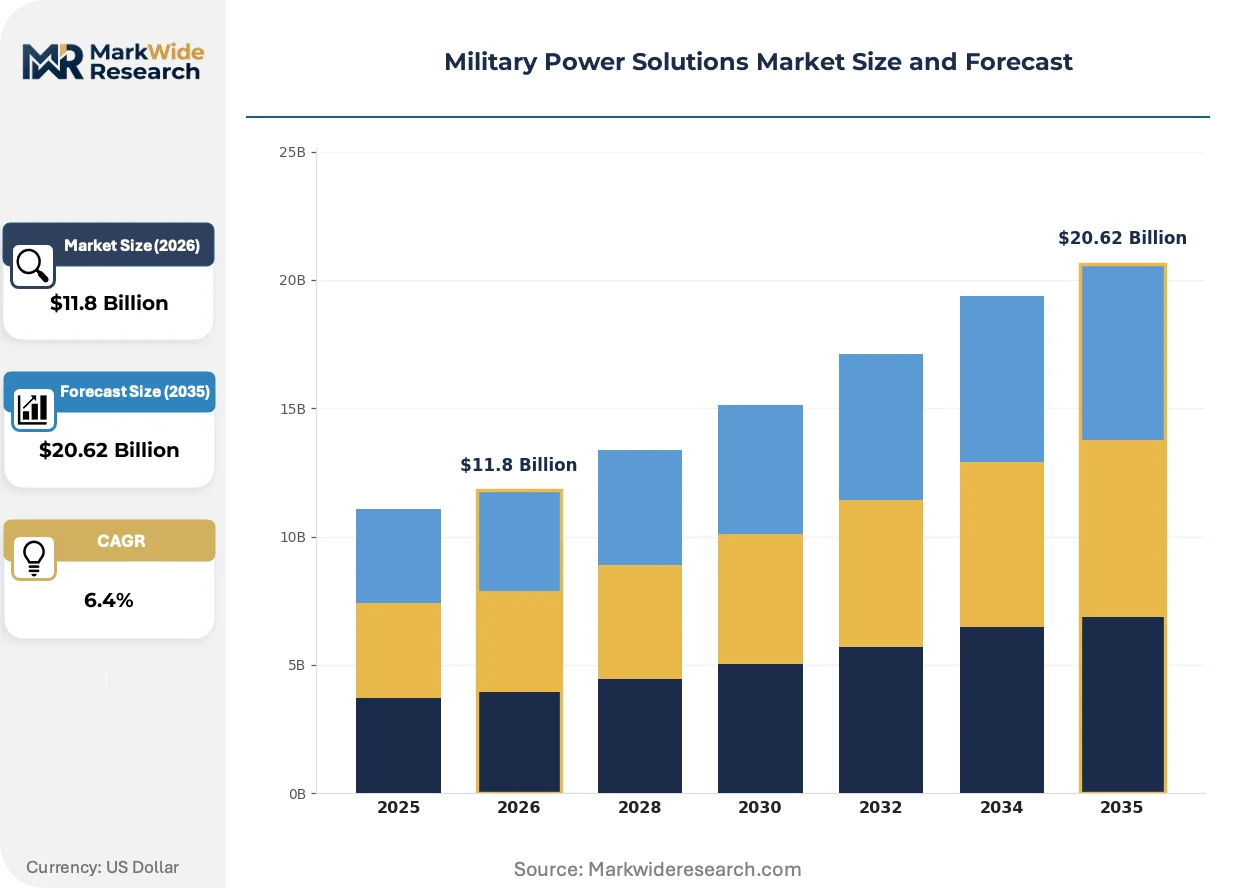
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Power Solutions Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Batteries, Fuel Cells, Inverters Technology: Conventional, Renewable, Hybrid, Advanced Energy Storage Application: Ground Forces, Naval Operations, Aerial Platforms, Tactical Vehicles End User: Defense Contractors, Military Agencies, Government Divisions, Research Institutions |
| Companies Covered | EnerSys, RTX Corporation, SAFT Groupe SA, Cummins Inc., SFC Energy AG, Arotech Corporation, BAE Systems, General Dynamics, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Power Solutions Market Strategic Shifts & Innovations
Solid-state battery architectures and wide-bandgap power electronics are compressing the performance gap between chemical storage and combustion generation, while procurement offices rewrite contracting models to favor modular, upgradeable energy platforms over fixed-configuration systems.
Solid-state lithium-metal cells with ceramic electrolyte separators are rewriting silent-watch endurance benchmarks for reconnaissance vehicle fleets. Special operations commands across NATO forces are piloting these systems for seventy-two-hour missions without generator support. The technology is compressing the tradable space between signature management and operational range, forcing diesel generator incumbents to defend position through hybrid integration rather than standalone sales.
The US Department of Defense's climate adaptation strategy mandates MIL-STD-810H environmental compliance for all fielded power equipment while directing program budgets toward tactical electrification. This dual pressure accelerates phase-out of small tactical generators from dismounted soldier power applications. Suppliers without established domestic testing partnerships face exclusion from framework contracts regardless of technical performance.
Buyer concentration across NATO defense procurement agencies is consolidating demand under multi-year framework agreements with embedded upgrade clauses. Traditional spot-purchasing through national stock numbers is yielding to performance-based logistics contracts where energy system vendors retain ownership through operational leasing. Germany's Bundeswehr modernization funds exemplify this shift, channeling silent-watch procurement toward suppliers capable of through-life power management rather than discrete hardware delivery.
Military Power Solutions Market Segmentation
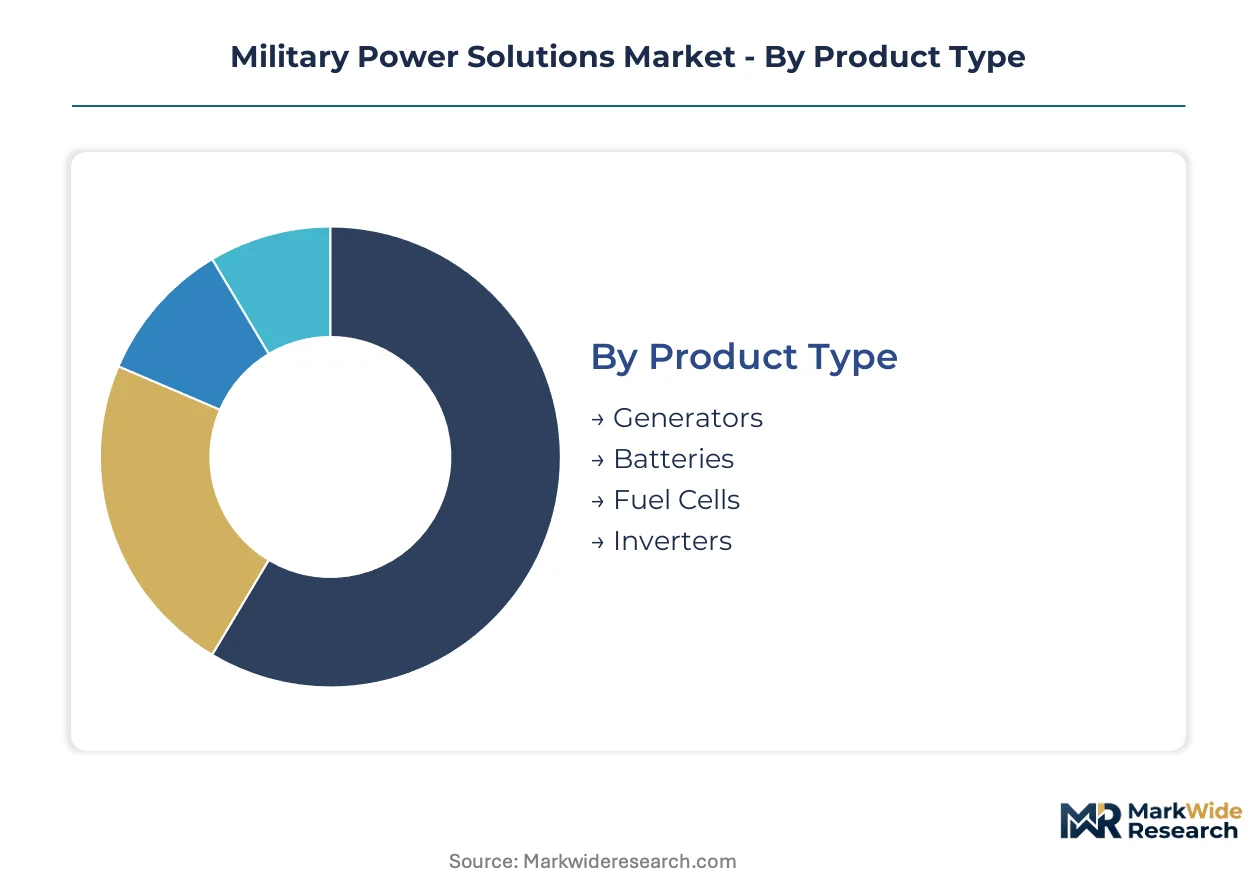
Military power solutions fragment across four critical dimensions that determine procurement pathways and supplier qualification requirements. Product type and technology classifications govern MIL-STD certification scope, while application and end-user segments dictate performance specifications and contracting vehicles.
Product Type:
Supply concentration in sealed lead-acid and lithium-ion cell manufacturing clusters shapes competitive access across NATO procurement frameworks.
- Batteries:Sealed lead-acid and lithium-ion electrochemical systems deliver 12V to 400V DC output for silent-watch operations. Bundeswehr armored vehicle modernization concentrates procurement in Germany for extended endurance without thermal signature. Demand from NATO expeditionary forces accelerates as small tactical generators face phase-out from reconnaissance missions.
- Generators:Diesel prime movers provide 120V/208V AC output for forward operating bases and heavy armor auxiliaries. Cummins Inc. anchors this segment with battle-hardened units purpose-built for denied logistics environments. Load density requirements in naval propulsion prevent fuel cell displacement of these systems.
- Fuel Cells:Solid-oxide and proton-exchange membrane architectures convert hydrogen or hydrocarbon fuels to electricity with minimal acoustic and thermal signature. Submarine-derived high-energy-density cell chemistry migrates into armored vehicle applications.
- Inverters:Power conditioning electronics synchronize DC storage with AC distribution buses, integrating wide-bandgap semiconductor controls with legacy 28V vehicle architectures.
Today's leader: Batteries. Tomorrow's challenger: Fuel Cells.
Technology:
Cost tier differentiation separates established combustion platforms from emerging electrochemical systems requiring six-figure MIL-STD-461G qualification investment.
- Advanced Energy Storage:Solid-state lithium-metal cells with ceramic electrolyte separators achieve seventy-two-hour silent-watch endurance for special operations missions. NATO reconnaissance commands pilot these systems as diesel generator incumbents defend position through hybrid integration.
- Hybrid:Battery-diesel architectures combine chemical storage with combustion backup for expeditionary microgrids. EU Green Deal carve-outs through the European Defence Fund channel development contracts toward these configurations for Bundeswehr and allied continental forces.
- Conventional:Pure combustion prime movers retain margin concentration where load density exceeds current fuel cell output ceilings, particularly in heavy armor and naval propulsion auxiliaries.
- Renewable:Photovoltaic harvesters integrated with diesel generation create photovoltaic-diesel hybrids for expeditionary use under NATO STANAG 4370 interoperability standards.
Established incumbent: Conventional. Steepest expansion trajectory: Advanced Energy Storage.
Application:
Volume concentration splits between dismounted soldier power and platform-integrated systems as more-electric aircraft architectures rewrite specification requirements.
- Ground Forces:Dismounted soldier power and tactical vehicle integration dominate procurement volume. The US Department of Defense's tactical electrification mandate redirects program budgets from small tactical generators toward portable battery systems.
- Aerial Platforms:More-electric aircraft architectures enable distributed power management through converging power electronics and high-temperature superconductors. This application opens specification windows for integrated energy system suppliers.
- Naval Operations:Submarine and surface vessel propulsion auxiliaries demand thermal-stable high-energy-density cells where SAFT Groupe SA specializes. Load density requirements sustain diesel generator retention.
- Tactical Vehicles:Silent-watch power systems for armored fleets concentrate procurement in Germany under Bundeswehr modernization funds.
Current volume anchor: Ground Forces. Emerging priority: Aerial Platforms.
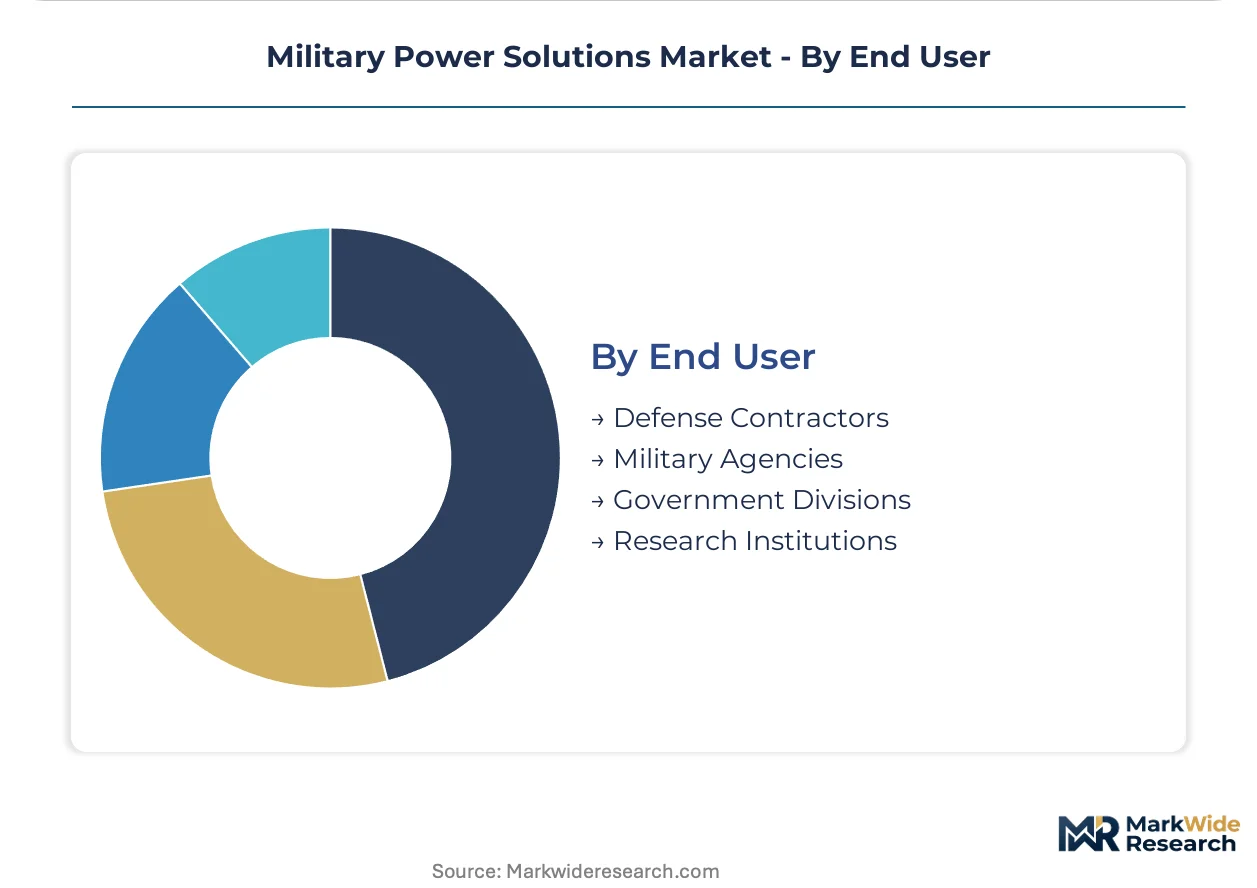
End User:
Customer type determines contracting modality, with framework agreements replacing spot-purchasing across concentrated NATO defense procurement agencies.
- Military Agencies:National defense ministries and service branches issue multi-year framework agreements with embedded upgrade clauses. Performance-based logistics contracts transfer ownership risk to vendors through operational leasing structures.
- Defense Contractors:Prime integrators and subsystem suppliers procure power solutions for platform integration. EnerSys leverages global manufacturing footprint to supply multiple allied forces under these procurement channels.
- Government Divisions:Civil defense and homeland security agencies acquire dual-use energy platforms bridging military specification and civilian resilience markets.
- Research Institutions:National laboratories and defense research organizations fund advanced chemistry and solid-state architecture development.
Contracting gravity centers on: Military Agencies. Fastest-growing procurement channel: Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany channels Bundeswehr modernization funds into silent-watch systems while the United States redirects program budgets under tactical electrification mandates, creating divergent procurement rhythms across NATO's largest defense markets.
United States
The Department of Defense's climate adaptation strategy compresses fielding schedules for battery-diesel hybrid architectures. MIL-STD-810H environmental compliance and MIL-STD-461G electromagnetic compatibility certification create captive demand for domestic testing partnerships. Michigan and Ohio industrial corridors concentrate prime integrator activity around vehicle power integration.
Germany
Bundeswehr armored vehicle fleets drive concentrated procurement of extended-endurance silent-watch systems under framework agreements with embedded upgrade clauses. The European Defence Fund channels development contracts toward hybrid renewable-diesel configurations through EU Green Deal carve-outs. Bavaria's defense industrial cluster anchors subsystem supplier networks for NATO expeditionary formations.
United Kingdom
More-electric aircraft architectures for next-generation aerial platforms open specification windows for integrated energy system suppliers. The Ministry of Defence's procurement consolidation under multi-year framework agreements favors vendors with through-life power management capabilities. Southwest England's aerospace corridor hosts prime contractor activity for distributed power electronics.
France
Naval propulsion auxiliaries and submarine applications sustain demand for thermal-stable high-energy-density cell systems. NATO Standardization Agreement 4370 interoperability requirements shape multinational procurement specifications for expeditionary microgrids. The Provence-Alpes-Côte d'Azur region concentrates maritime defense research institutions advancing solid-state chemistry.
Poland
Accelerated technical modernization plan procurement creates uncontracted demand for portable power systems supporting forward-based NATO formations. Defense budget expansion redirects toward expeditionary capabilities compatible with allied interoperability standards. Warsaw and the Silesian industrial basin concentrate emerging defense contractor activity for tactical vehicle integration.
Military Power Solutions Market Key Industry Players
North American producers anchor one tier with established defense contractor relationships; European specialists hold position through NATO standardization alignment and submarine-derived cell chemistry expertise. The vendor base separates into three strategic archetypes: integrated prime contractors with platform ownership, subsystem suppliers with MIL-STD certification depth, and emerging chemistry developers migrating military technology into dual-use markets. Competitive dynamics center on capacity expansion for solid-state cell manufacturing and strategic partnerships bridging battery system houses with wide-bandgap semiconductor controls.
Within the established supplier tier, EnerSys exemplifies global manufacturing footprint scale across sealed lead-acid and lithium-ion systems, while SAFT Groupe SA occupies a position specializing in high-energy-density configurations for thermal-critical applications. Cummins Inc. anchors the combustion prime mover segment with purpose-built diesel units for denied logistics environments.
| Leading Market Players |
|---|
| EnerSys |
| RTX Corporation |
| SAFT Groupe SA |
| Cummins Inc. |
| SFC Energy AG |
| Arotech Corporation |
| BAE Systems |
| General Dynamics |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
Captive cathode material processing in East Asian chemical hubs anchors both supply security and pricing power for NATO defense procurement, creating a structural dependency that concentrates cost leverage among integrated battery system houses with backward control over lithium refining.
Pricing Analysis
Capacity additions in South Korean and Japanese cell manufacturing are reshaping price floors for high-rate lithium-ion systems, compressing margins for sealed lead-acid incumbents. Three-tier pricing structure across MIL-STD certified, commercial-industrial, and spot-market tiers separates defense-grade cells with electromagnetic compatibility testing from uncertified alternatives. Pricing pressure stems from six-figure MIL-STD-461G qualification expenses that non-domestic suppliers struggle to recover. Defense contractors exhibit lowest price sensitivity due to performance-based logistics contracts, while research institutions face tightest budget constraints.
Supply Chain Analysis
Refurbishment flows for battlefield-damaged battery systems are creating secondary supply channels that extend asset life cycles and compress replacement demand. Raw material dependencies center on lithium carbonate from Chile and Australia, cobalt hydroxide from the Democratic Republic of Congo, and nickel sulfate from Indonesia. Single-source vulnerability concentrates in East Asian cathode active material processing, exposing NATO procurement to logistics chokepoints through maritime transit corridors. Distribution runs through prime defense contractor integration facilities in Michigan, Bavaria, and Southwest England.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German Bundeswehr modernization premiums and Polish technical modernization cost baselines, exploiting a 40-60% contracting differential under allied interoperability standards.
For Market Incumbents: Lock in cathode material supply through offtake agreements with Australian and Chilean mining operators, securing feedstock ahead of competing battery system houses. Deepen MIL-STD-810H and MIL-STD-461G certification depth to exclude emerging solid-state chemistry developers from framework contract eligibility. Threat substitution from wide-bandgap semiconductor power electronics demands firmware talent acquisition.
For New Entrants and Emerging Players: Direct-to-defense-procurement digital platforms offer route-to-market bypassing traditional prime contractor gatekeeping, enabling specification influence before integration lock-in. Poland's uncontracted demand for forward-based NATO portable power systems represents the most penetrable geography. Target photovoltaic-diesel hybrid configurations under EU Green Deal carve-outs where incumbents lack renewable integration experience.
For Investors and Strategic Acquirers: Roll-up economics work for subsystem suppliers with MIL-STD certification depth because buyer concentration across NATO procurement agencies favors vendors with multi-standard qualification portfolios. Five-to-ten year viability hinges on solid-state manufacturing scale-up. Watch fuel cell output density breakthroughs as inflection signal for diesel generator displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium supply secures NATO defense contract eligibility against East Asian processing concentration. |
| MIL-STD-461G Certification Investment | Electromagnetic compatibility testing creates six-figure barrier excluding non-domestic competitors from framework agreements. |
| Photovoltaic-Diesel Hybrid Development | EU Green Deal carve-outs through European Defence Fund channel development contracts toward renewable expeditionary systems. |
| Wide-Bandgap Semiconductor Acquisition | Power electronics integration capability addresses firmware talent scarcity in traditional battery system houses. |
| Poland Defense Market Entry | Accelerated technical modernization plan creates uncontracted demand for NATO-interoperable portable power systems. |
Research Approach
Multiple input streams — program office budget documentation, defense contractor procurement disclosures, and national modernization plan filings — were reconciled against primary interviews with battery system procurement leads, electromagnetic compatibility test engineers, and expeditionary logistics officers. Secondary validation drew from NATO Standardization Agreement registers, Bundeswehr equipment announcements, US Department of Defense climate strategy directives, and EU European Defence Fund award databases. Bottom-up project pipeline aggregation and top-down defense budget allocation analysis were triangulated to cross-verify volume estimates.
Data-stream reconciliation across product type, technology maturity, application platform, and end-user contracting modality produced segmented forecasts over the projection horizon. CAGRs were derived from equipment retirement-replacement cycles, modernization funding trajectories, and technology substitution elasticities. Industry-specific inputs included silent-watch endurance requirements, fuel cell output density improvement curves, and more-electric aircraft architecture adoption schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state lithium-metal cell commercialization would alter the outlook for diesel generator displacement timelines. Forecasts reflect assumptions regarding NATO interoperability standard adherence, EU defense funding continuity, and lithium supply chain geographic diversification. Practitioners should monitor solid-state manufacturing yield improvements, wide-bandgap semiconductor cost curves, and Polish defense procurement acceleration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market