
 Americas Aircraft Lighting Market | 2026-2036
Americas Aircraft Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Aircraft Lighting Market Outlook
Market Context
DO-160G environmental qualification standards for airborne equipment is collapsing the gap between legacy incandescent systems and next-generation solid-state lighting across North and South American fleets. Honeywell International Inc. leverages its integrated avionics platform to bundle lighting controls with flight-deck systems, sustaining aftermarket pull through its global service network. Collins Aerospace anchors the exterior lighting segment with proprietary LED landing and taxi light architectures that dominate Boeing and Airbus programs serving American carriers. Safran SA competes through specialized position and anti-collision light packages engineered for narrow-body retrofit campaigns.
Technical Definition and Structural Segments
Americas Aircraft Lighting encompasses electroluminescent and photonic systems engineered to operate across temperature extremes from minus 55 degrees Celsius to 70 degrees Celsius, providing illumination for flight decks, passenger cabins, exterior navigation, and emergency egress pathways on fixed-wing and rotary platforms certified by regulators across the Western Hemisphere. Interior Lights and Exterior Lights command the largest installed base, while Emergency Lights concentrates margin pools as airlines face shorter replacement cycles driven by airworthiness directive compliance. LED technology leads technology adoption across commercial and military end users, displacing HALOGEN and FLUORESCENT architectures in retrofit programs where energy efficiency and mean-time-between-failure metrics determine procurement awards.
Regulatory Frame and Outlook
FAA airworthiness directives and Transport Canada Civil Aviation certification requirements shape product specifications, testing protocols, and market access timelines for suppliers targeting North American operators. The U.S. Department of Defense MIL-STD-3009 and Brazil's ANAC lighting standards further segment procurement pathways between civil and military aviation channels. Stakeholders must monitor evolving photobiological safety standards and harmonization gaps between FAA and ANAC certification timelines to anticipate retrofit scheduling and inventory positioning across the Americas.
Market Dynamics
LED solid-state architectures are collapsing the installed base of incandescent and fluorescent systems across North and South American fleets, forcing suppliers to restructure aftermarket service networks around longer mean-time-between-failure metrics and compressed replacement cycles driven by FAA airworthiness directives.
Growth Catalysts
- FAA Airworthiness Directives:Mandated compliance timelines for emergency egress lighting systems are accelerating retrofit schedules across US commercial fleets, concentrating demand in the 2024-2028 window.
- DO-160G Environmental Qualification:Standardized testing protocols for temperature extremes and vibration resistance are reducing certification friction for LED suppliers entering the Brazilian and Canadian markets.
- Military LED Modernization:US Department of Defense MIL-STD-3009 compliance requirements for NVIS-compatible cockpit lighting are driving procurement volumes for fixed-wing and rotary platforms.
Market Restraints
- Aluminum and Rare-Earth Price Volatility:LED phosphor substrates and heat-sink materials face input cost swings that compress margin pools for tier-two suppliers without captive sourcing.
- Supply Concentration in Southeast Asian Component Hubs:Driver electronics and solid-state emitters concentrate in single-source regions, exposing American assemblers to logistics disruption and extended lead times.
- Legacy System Interoperability Limits:Analog dimming architectures in aging Boeing 737 and Airbus A320 fleets resist digital control integration, forcing hybrid system designs that raise engineering overhead.
Strategic Opportunities
- ANAC Certification Harmonization Gaps:Brazil's divergent timeline for photobiological safety standards creates first-mover positioning for suppliers willing to front-load testing investment against deferred competitor entry.
- Connected Lighting-Flight Deck Convergence:Integration of cabin mood systems with avionics data buses enables predictive maintenance contracts and recurring software revenue streams.
- Rotary Platform Underpenetration:Oil-and-gas and emergency medical helicopter operators in Colombia and Mexico lag fixed-wing LED adoption, presenting volume expansion for specialized anti-collision and searchlight packages.
Industry Challenges
- DO-160G Section 22 Certification Bottlenecks:Lightning-induced transient susceptibility testing for solid-state power supplies extends qualification timelines by 8-14 months, delaying program revenue recognition.
- Legacy Incandescent Technical Talent Scarcity:Maintenance organizations face retirement-driven attrition in analog system troubleshooting, complicating mixed-fleet support contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Aircraft Lighting Market |
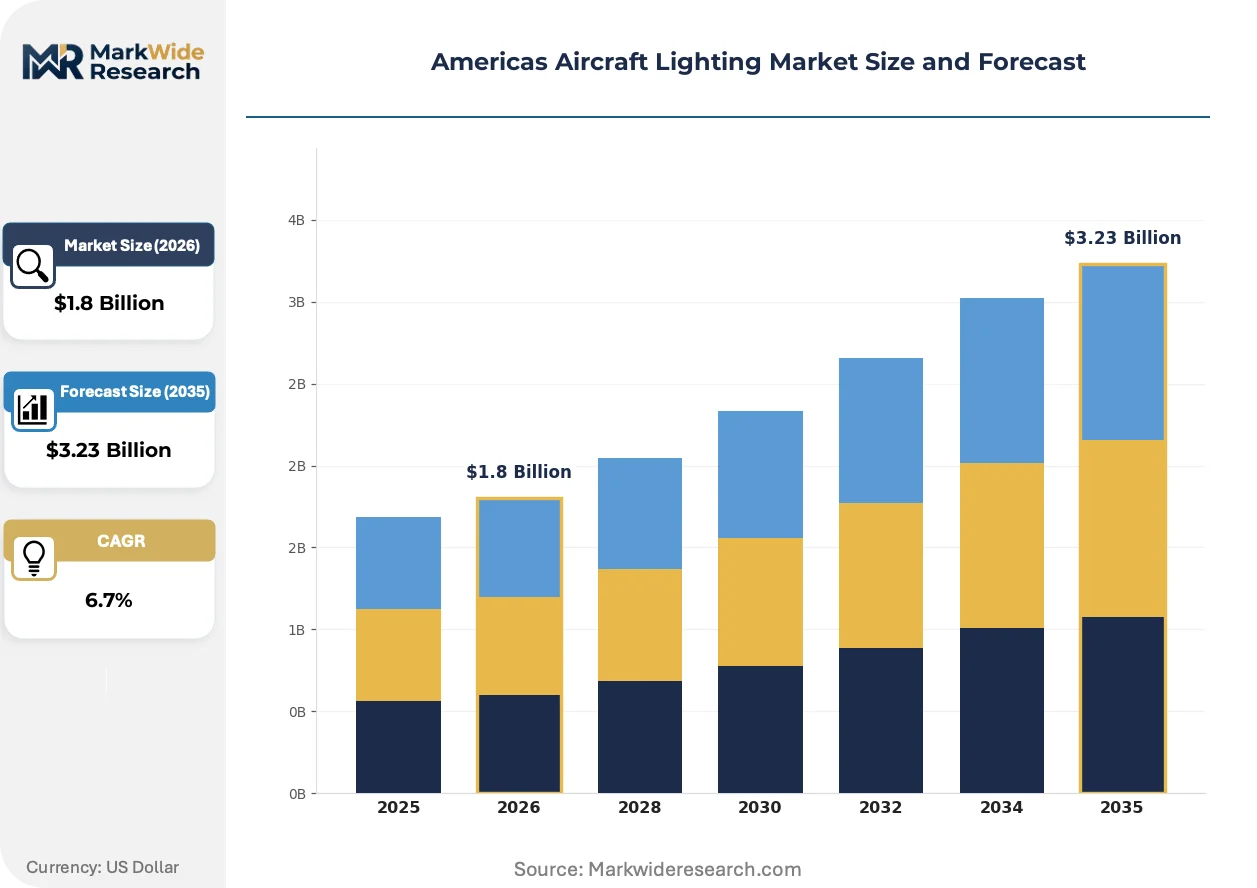
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Lights, Exterior Lights, Emergency Lights, Signaling Lights Technology: LED, HALOGEN, FLUORESCENT, HID End User: Commercial Aviation, General Aviation, Military Aviation, Cargo Aviation Installation Type: Line Fit, Retrofit, Maintenance Replacement, Aftermarket |
| Companies Covered | Honeywell International Inc., Collins Aerospace, Astronics Corporation, Safran SA, Diehl Stiftung & Co. KG, Luminator Aerospace, STG Aerospace Limited, Thales, Oxley Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Aircraft Lighting Market Strategic Shifts
Solid-state photonic systems are fragmenting competitive positioning across the Americas as energy efficiency mandates and connected aircraft architectures force simultaneous investment in hardware miniaturization and software-defined control layers.
OLED flexible panel technology is bifurcating the interior lighting value chain between rigid LED retrofits for narrow-body programs and conformable surface illumination for next-generation cabin designs. Airbus A220 and Embraer E2 operators in Canada and the United States are piloting curved-panel installations for sidewall wash lighting. This technology is bifurcating supplier tiers into discrete hardware fabricators versus integrated system architects capable of delivering both photonic output and control software.
Transport Canada Civil Aviation's adoption of FAA-aligned photobiological safety testing protocols is compressing certification duplication for suppliers seeking dual market access. The harmonization eliminates redundant retinal hazard assessment for LED cabin systems, reducing time-to-revenue by approximately one quarter. Narrow-body retrofit specialists targeting transborder operator fleets capture the greatest efficiency gains from this regulatory convergence.
Airline technical procurement departments are consolidating vendor relationships around full-service lighting system integrators capable of delivering line-fit, retrofit, and spares through single contract vehicles. Maintenance, repair, and overhaul channels in Miami and São Paulo are absorbing discrete component distributors as operators demand unified warranty and logistics accountability. This consolidation is most visible among ultra-low-cost carriers operating mixed-generation Airbus fleets across Mexico and Central America.
Americas Aircraft Lighting Market Segmentation
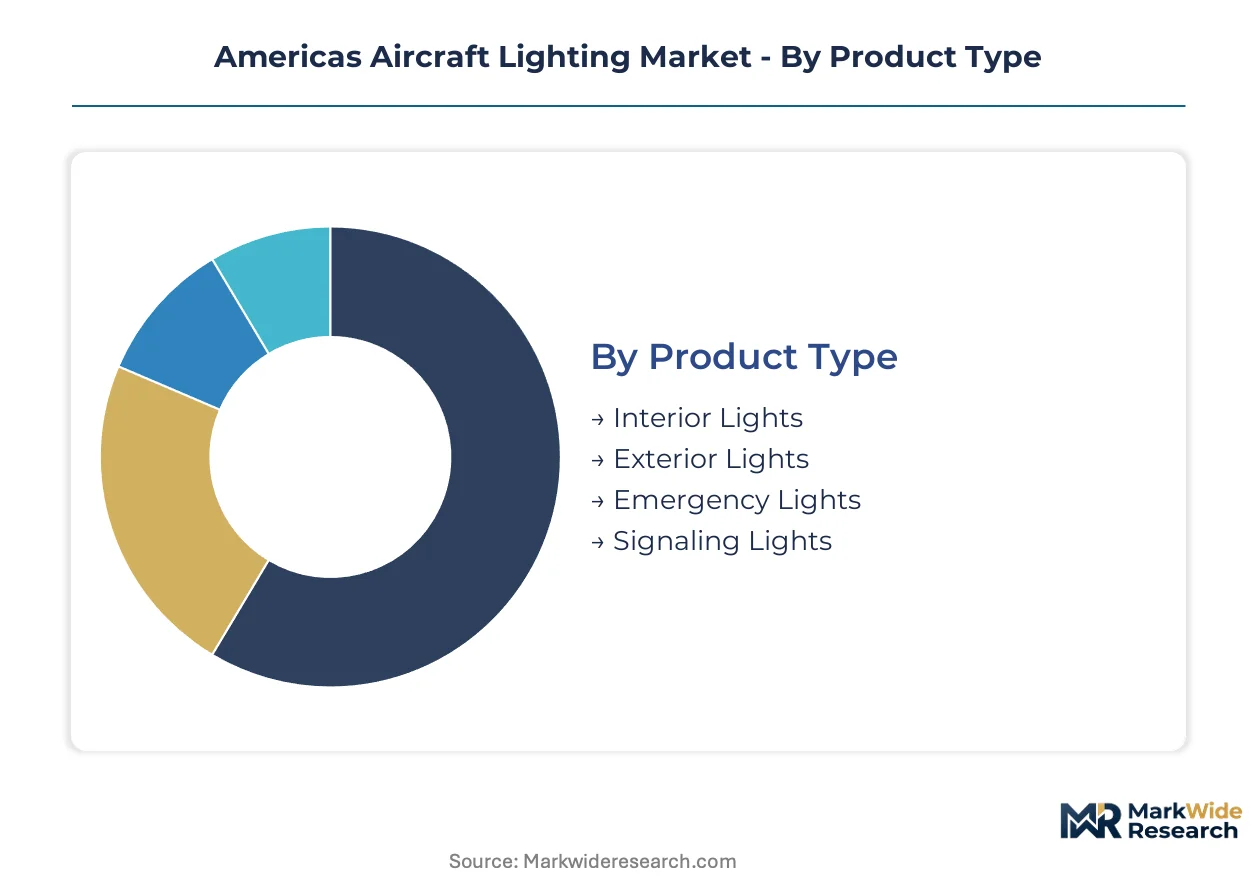
Segmentation in the Americas Aircraft Lighting Market reflects divergent certification pathways between FAA, Transport Canada Civil Aviation, and ANAC jurisdictions. Procurement patterns cluster around retrofit urgency driven by airworthiness directives and line-fit specifications for new aircraft programs across North and South American assembly lines.
Product Type:
FAA emergency egress mandates and ANAC photobiological safety timelines create divergent replacement cycles across lighting categories, concentrating supplier engineering resources on compliance-critical segments first.
- Interior Lights:LED cabin illumination systems operate across temperature extremes from minus 55 degrees Celsius to 70 degrees Celsius, providing sidewall wash and overhead reading functions. Demand concentrates in narrow-body retrofit campaigns across United States ultra-low-cost carriers modernizing mixed-generation Airbus fleets; energy efficiency metrics and mean-time-between-failure specifications determine procurement awards against legacy fluorescent architectures.
- Exterior Lights:Navigation, landing, and taxi light assemblies engineered for vibration resistance per DO-160G Section 8 standards. Brazilian and Canadian operators of Embraer E2 and Airbus A220 platforms drive line-fit specifications; proprietary LED architectures dominate Boeing and Airbus programs serving American carriers through integrated avionics bundling.
- Emergency Lights:Egress path illumination systems subject to compressed replacement cycles under FAA airworthiness directives.
- Signaling Lights:Position and anti-collision packages specialized for rotary platforms in Colombian and Mexican oil-and-gas operations.
Interior Lights handles the majority of throughput; Emergency Lights is the fastest mover on share.
Technology:
Cost tier stratification separates premium solid-state systems from legacy incumbent technologies facing accelerated phase-out across military and commercial channels.
- LED:Solid-state photonic systems with phosphor substrates and heat-sink architectures displacing incandescent and fluorescent installed bases. HALOGEN and FLUORESCENT architectures resist digital control integration in aging Boeing 737 and Airbus A320 fleets, forcing hybrid designs that raise engineering overhead for retrofit specialists.
- HALOGEN:Tungsten-filament systems with analog dimming architectures prevalent in pre-2010 airframes.
- FLUORESCENT:Gas-discharge tube assemblies for cabin overhead illumination in legacy narrow-body configurations.
- HID:High-intensity discharge systems for exterior searchlight applications in military rotary platforms.
LED commands the dominant revenue position; HID retains niche military volume despite steepest contraction trajectory.
End User:
Customer type determines procurement pathway concentration between civil certification channels and MIL-STD-3009 military compliance frameworks.
- Commercial Aviation:Scheduled passenger carriers operating FAA-certificated fleets across United States, Canada, and Brazil. General Aviation and Cargo Aviation segments follow divergent replacement timelines driven by flight-hour accumulation patterns rather than regulatory mandate density.
- General Aviation:Private and business aircraft operators with discretionary modernization schedules.
- Military Aviation:US Department of Defense fixed-wing and rotary platforms requiring NVIS-compatible cockpit lighting per MIL-STD-3009.
- Cargo Aviation:Dedicated freighter operators with extended airframe utilization cycles deferred from passenger fleet retrofit waves.
Commercial Aviation anchors procurement volume; Military Aviation is expanding most quickly on modernization program acceleration.
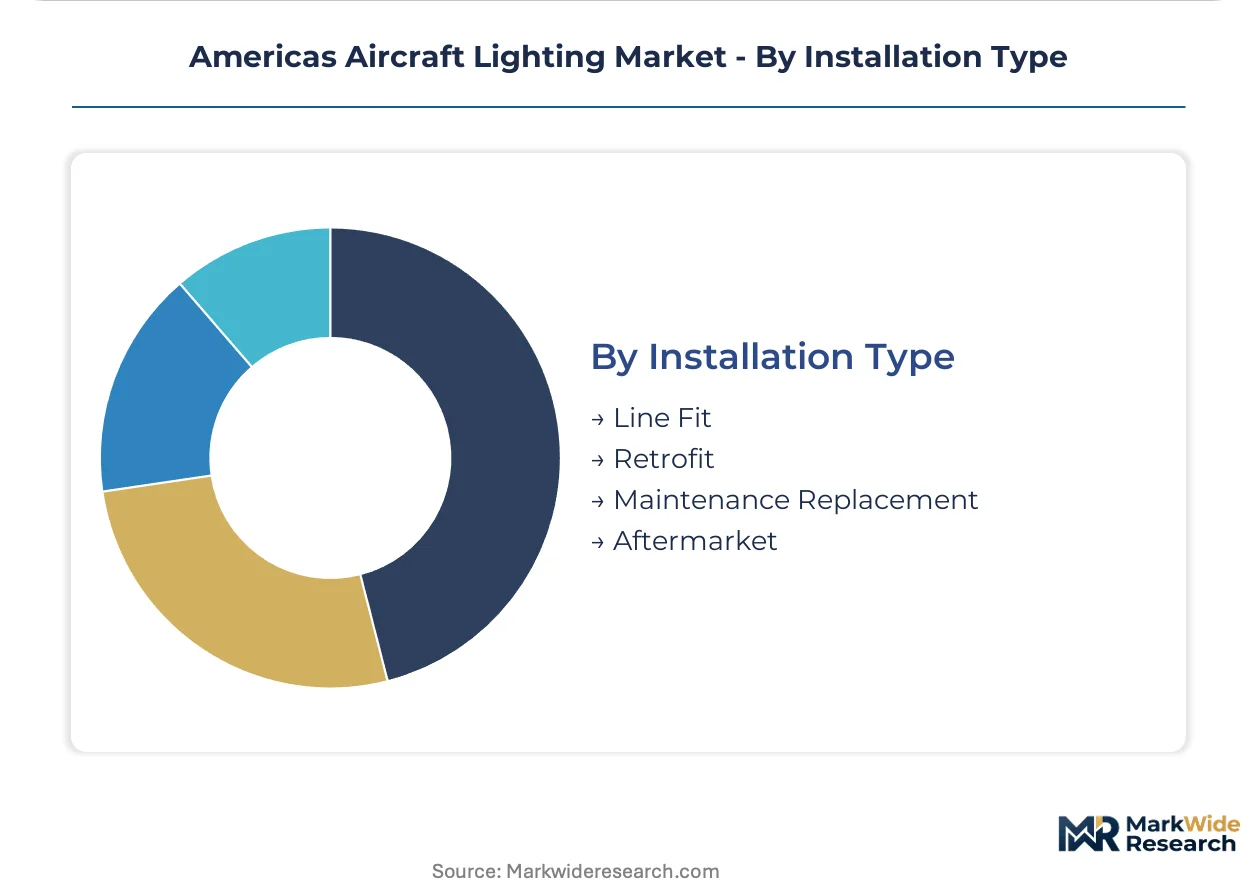
Installation Type:
Supply concentration in Miami and São Paulo MRO channels shapes distribution economics between original equipment line-fit and aftermarket replacement pathways.
- Line Fit:Factory-integrated lighting systems installed during airframe assembly at Boeing, Airbus, and Embraer facilities serving American carriers. Retrofit and Maintenance Replacement channels absorb discrete component distributors as operators demand unified warranty accountability.
- Retrofit:Post-delivery system upgrades mandated by FAA airworthiness directives.
- Maintenance Replacement:Scheduled component exchange during routine airframe servicing.
- Aftermarket:Spare parts procurement through consolidated vendor relationships.
Line Fit captures the largest contract values; Retrofit is gaining share fastest on directive-driven replacement waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in aircraft lighting components favor net-import positions across South American markets, while the United States and Canada maintain integrated supply chains with domestic assembly capacity serving regional airline procurement.
United States
FAA airworthiness directives for emergency egress systems are compressing retrofit timelines across US commercial fleets. The US Department of Defense MIL-STD-3009 requirements for NVIS-compatible cockpit lighting drive military procurement volumes. Miami's maintenance, repair, and overhaul corridor absorbs discrete component distributors as operators consolidate vendor relationships.
Canada
Transport Canada Civil Aviation's adoption of FAA-aligned photobiological safety testing protocols eliminates redundant certification steps for LED cabin systems. Airbus A220 operators in Montreal and Toronto pilot curved-panel OLED installations for sidewall wash lighting. Vancouver's aerospace engineering cluster specializes in environmental qualification testing per DO-160G standards.
Brazil
ANAC's divergent timeline for photobiological safety standards creates first-mover positioning for suppliers front-loading testing investment. Embraer E2 production in São José dos Campos anchors line-fit lighting specifications for regional jet programs. São Paulo's MRO channels consolidate aftermarket distribution as ultra-low-cost carriers demand unified warranty accountability.
Mexico
Ultra-low-cost carriers operating mixed-generation Airbus fleets across Mexico City and Guadalajara drive narrow-body retrofit demand for LED cabin illumination. The country's central bank monitors peso volatility affecting imported LED phosphor substrate costs. Querétaro's aerospace manufacturing corridor supports line-fit integration for Boeing and Airbus programs serving North American operators.
Colombia
Oil-and-gas and emergency medical helicopter operators in Bogotá lag fixed-wing LED adoption, presenting volume expansion for specialized anti-collision packages. The national civil aviation regulator enforces airworthiness standards converging with FAA frameworks. Medellín's aviation services cluster develops maintenance capabilities for rotary platform lighting systems.
Americas Aircraft Lighting Market Competitive Environment
Concentration sits with diversified avionics conglomerates bundling lighting controls with integrated flight-deck platforms. Three structural tiers organize competitive positioning: full-service system integrators delivering line-fit, retrofit, and spares through single contract vehicles; specialized lighting houses focusing on narrow-body retrofit campaigns; and component fabricators supplying driver electronics and solid-state emitters. Dominant competitive moves include strategic partnerships with airframe OEMs for factory-integrated specifications and geographic expansion into São Paulo and Miami MRO channels.
Among diversified conglomerates, Honeywell International Inc. and Collins Aerospace exemplify the integrated avionics archetype, while Safran SA occupies a position within the specialized lighting tier. These entities anchor competitive dynamics through their representation of divergent strategic approaches—bundled platform integration versus focused retrofit specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| Astronics Corporation |
| Safran SA |
| Diehl Stiftung & Co. KG |
| Luminator Aerospace |
| STG Aerospace Limited |
| Thales |
| Oxley Group |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month qualification timelines for DO-160G Section 22 lightning transient testing concentrate inventory risk among tier-two LED suppliers, compressing their pricing power against integrated avionics bundlers while forcing strategic stockpile commitments on critical driver electronics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across line-fit and retrofit channels. Pricing stratifies across FAA-certified premium tiers, DO-160G-qualified standard tiers, and uncertified economy tiers for non-critical cabin applications. Cost compression in retrofit LED modules is intensifying because aluminum heat-sink and rare-earth phosphor substrates face commodity volatility. Ultra-low-cost carriers operating mixed-generation Airbus fleets exhibit highest price sensitivity; military NVIS-compliant cockpit programs show lowest sensitivity due to MIL-STD-3009 mandate rigidity.
Supply Chain Analysis
Strategic stockpile preferences dominate over just-in-time approaches for solid-state emitters and driver electronics given Southeast Asian component hub concentration. Supply draws from China, Malaysia, and Vietnam for LED phosphor substrates, heat-sink aluminum, and power supply assemblies. Single-source vulnerability in gallium nitride wafer fabrication exposes American assemblers to logistics disruption. Distribution runs through Miami and São Paulo MRO corridors where consolidated vendor relationships absorb discrete component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against OLED flexible panel architectures threatening to bifurcate the interior lighting value chain away from rigid LED retrofits.
For Market Incumbents: Shield line-fit positioning at Boeing, Airbus, and Embraer facilities through exclusive avionics bundling contracts that raise switching costs for airframe OEMs. Deepen backward integration into driver electronics fabrication to reduce exposure to Southeast Asian single-source vulnerability. Prioritize DO-160G Section 22 pre-certification investment to collapse competitor qualification timelines. For New Entrants and Emerging Players: Differentiate on ANAC certification front-loading for Brazil's divergent photobiological safety timeline, capturing first-mover positioning against deferred competitor entry. Target Colombian and Mexican rotary platform operators where oil-and-gas and emergency medical helicopter fleets lag fixed-wing LED adoption. Pursue predictive maintenance software contracts as the go-to-market anchor for connected lighting-flight deck convergence. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because FAA airworthiness directive density and ANAC harmonization gaps create sustained retrofit demand visibility. Acquisition target archetype: specialized lighting houses with narrow-body retrofit expertise and Transport Canada Civil Aviation dual-certification capability. Watch DO-160G Section 22 testing backlog duration as the inflection signal for supplier margin expansion versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| DO-160G Pre-Certification Investment | Collapses competitor entry timelines by 8-14 months for lightning transient qualification. |
| ANAC Testing Front-Loading | Captures Brazilian market access before photobiological safety standard harmonization completes. |
| Avionics Platform Integration | Bundles lighting controls with flight-deck systems to sustain aftermarket pull through service networks. |
| Rotary Platform Specialization | Addresses underpenetrated Colombian and Mexican oil-and-gas helicopter operator demand. |
| Predictive Maintenance Software Development | Enables recurring revenue streams through cabin mood system avionics data bus integration. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with avionics procurement directors, MRO operations managers, FAA certification engineers, and airline technical fleet planners; and secondary validation against FAA airworthiness directive databases, Transport Canada Civil Aviation certification filings, ANAC regulatory notices, and DO-160G test house qualification records. Bottom-up triangulation across installation type volumes and top-down cross-check against OEM production schedules anchored market sizing.
Across the projection horizon, the analytical framework modeled product type, technology architecture, end-user channel, and installation pathway segmentation. CAGRs derived from fitted trend extrapolation adjusted for regulatory mandate timing and fleet age distribution. Forecast inputs included Embraer E2 and Airbus A220 production rates, MIL-STD-3009 program acceleration schedules, and ultra-low-cost carrier fleet modernization commitments.
The analysis sits within stated boundaries; outcomes outside sustained FAA directive issuance or aluminum and rare-earth price stability would require recalibration. Forecasts reflect documented assumptions on certification timeline convergence and OEM bundling contract renewal rates. Revision becomes warranted when ANAC-FAA photobiological safety harmonization accelerates beyond modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market