
 Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market | 2026-2036
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market Analysis
Market Context with Strategic Players
Aftermarket service revenue is rewriting margin capture across the EWIS value chain as airlines extend airframe lifecycles. GKN Aerospace Services leverages its Bristol-based aerostructures footprint to dominate harness production for Airbus and Boeing wide-body programs. Safran sustains vertical integration from wire extrusion through final harness assembly at its Villaroche facility. TE Connectivity anchors the connector segment through MIL-DTL-qualified product lines that penetrate both OEM and MRO channels.
Technical Definition and Structural Segments
Commercial Aviation Electrical Wiring Interconnection System (EWIS) denotes the complete network of wires, cables, connectors, and protective conduits that distribute electrical power and signals throughout an aircraft, typically operating at voltages from 28V DC to 230V AC and subject to temperature extremes from minus 55°C to 200°C depending on installation zone. Copper Wiring remains the volume backbone across narrow-body and regional jet platforms, though Fiber Optic Systems are displacing legacy copper in high-bandwidth avionics backbone applications where electromagnetic interference immunity is critical. Wiring Harnesses command the largest share of product-type value pools due to labor-intensive custom fabrication requirements, while Hybrid Systems represent the fastest-growing technology segment as OEMs blend copper power distribution with fiber optic data transmission in next-generation architectures. AS9100 certification functions as a non-negotiable market access threshold, filtering supplier participation and concentrating procurement among aerospace-qualified manufacturing networks.
Regulatory Frame and Forward-Looking Close
FAA Part 25.1701-1733 EWIS-specific regulations, EASA CS-25 Subpart H amendments, and ISO 19600 compliance management standards collectively mandate enhanced arc-fault protection, wire separation, and installation accessibility across transport category aircraft. These frameworks compel airlines to retrofit aging fleets with compliant harness configurations and drive OEMs to design integrated EWIS architectures during preliminary aircraft development. Stakeholders must monitor evolving STC pathway requirements for aftermarket modification packages, as regulatory divergence between FAA and EASA certification timelines threatens to fragment supplier development roadmaps and strain dual-approval budgets.
Market Dynamics
Fleet modernization mandates and arc-fault regulatory enforcement are compressing replacement cycles across aging narrow-body and wide-body platforms, forcing simultaneous harness upgrades at multiple lifecycle stages rather than staggered intervals.
Growth Catalysts
- FAA Part 25.1701-1733 arc-fault mandates:Retrofit obligations at US-based carriers are accelerating aftermarket harness demand as operators face compliance deadlines on pre-2010 airframes.
- High-bandwidth avionics architectures:Fiber optic backbone deployments in next-generation flight decks are creating hybrid harness specifications that blend power distribution with data transmission.
- Southwest Asia-Pacific corridor:IndiGo's narrow-body expansion and AirAsia's fleet renewal are concentrating procurement volume in Singapore and Kuala Lumpur maintenance hubs.
Market Restraints
- Copper price volatility:Harness manufacturers face margin compression when London Metal Exchange copper futures swing beyond hedging thresholds, particularly affecting low-volume regional jet suppliers.
- AS9100 certification scarcity:The limited pool of aerospace-qualified wire extrusion facilities in Western Europe creates single-source dependencies for specialized insulation compounds.
- Polyimide insulation technical ceiling:Temperature ratings above 260°C remain unachievable without ceramic-coated conductor alternatives that fragment supplier qualification pathways.
Strategic Opportunities
- Saudi Arabia fleet expansion:Riyadh-based Saudia and flyadeal growth plans are creating demand for localized harness assembly capacity to reduce import lead times.
- EASA CS-25 Subpart H amendment trajectory:Anticipated wire separation rules will mandate redesigned harness routing on in-service A320 and B737 families, opening modification package markets.
- Additive manufacturing convergence:3D-printed connector housings combined with automated wire laying are enabling lot-size-one harness production for low-rate initial production programs.
Industry Challenges
- IPC/WHMA-A-620 specialist technician shortage:Crimping and soldering certification programs are failing to replenish retiring workforce cohorts at US and UK MRO facilities.
- Dual FAA-EASA STC timeline divergence:Supplemental type certificate approval gaps between Washington and Cologne offices are stretching development budgets for aftermarket harness kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market |
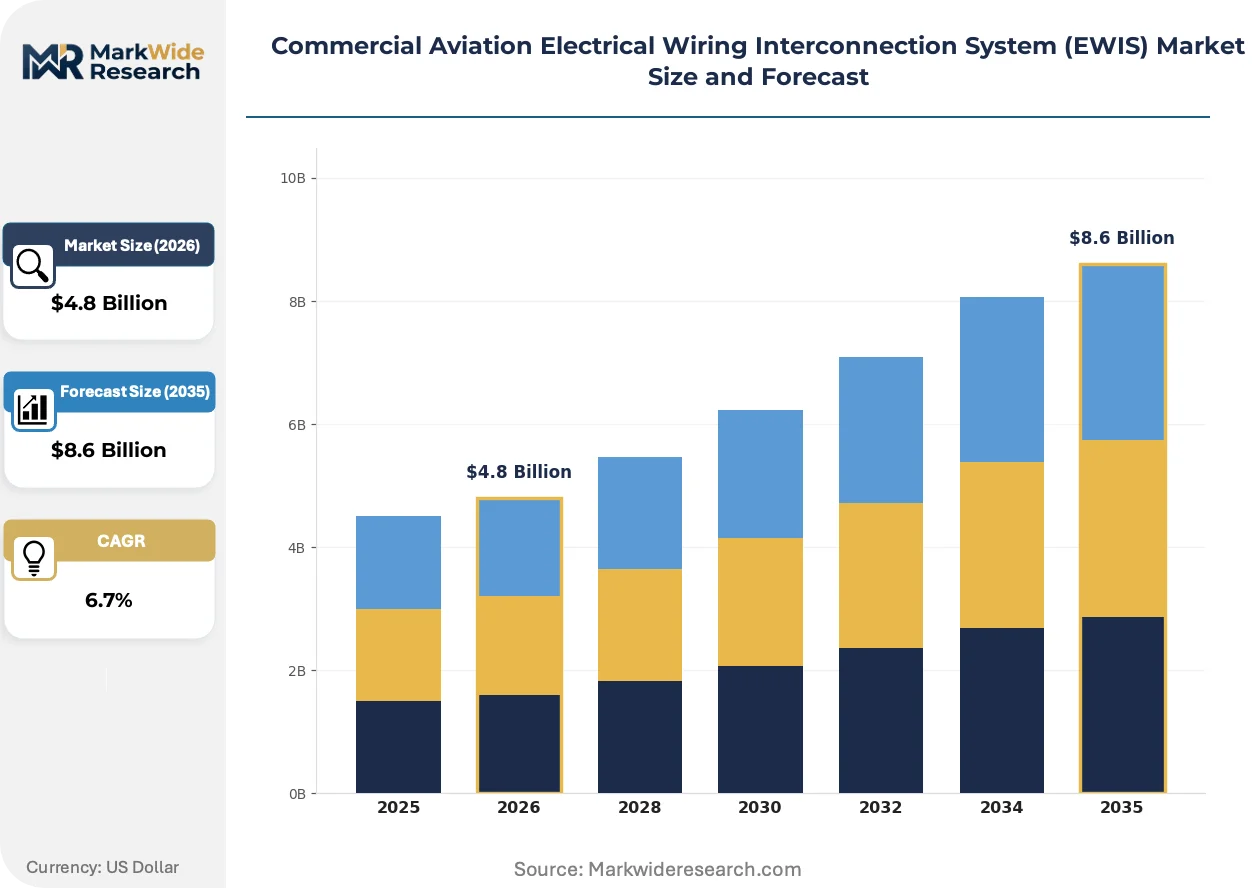
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wiring Harnesses, Connectors, Cable Assemblies, Terminals End User: Commercial Airlines, OEMs, Maintenance Providers, Aftermarket Suppliers Technology: Fiber Optic Systems, Copper Wiring, Hybrid Systems, Advanced Materials Certification: AS9100, FAA Certified, EASA Approved, STC |
| Companies Covered | GKN Aerospace Services, Ducommun Incorporated, Safran, InterConnect Wiring, Collins Aerospace, TE Connectivity, Latécoère, Esterline Technologies, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market Emerging Trajectories
Electromagnetic interference mitigation requirements and weight reduction imperatives are driving material substitution and architecture redesign across power distribution and avionics backbone networks.
Carbon nanotube-infused wire insulation is collapsing the trade-off between thermal endurance and weight in engine nacelle installations. Boeing's 777X program specifications now require these compounds for fire-zone harnesses, and adoption is spreading to A350 line-fit configurations. The technology is collapsing the historical 15-20% weight penalty that accompanied high-temperature polyimide alternatives.
EASA CS-25 Subpart H amendments on wire separation and installation accessibility are forcing redesign of center wing box harness routing during heavy maintenance visits. European operators face compressed downtime windows as Cologne-based certification timelines extend. MRO providers in Germany and France are responding with modular harness replacement kits that reduce on-aircraft labor hours.
Airline engineering departments are consolidating supplier panels from twelve-plus harness vendors to three or four strategic partners with full lifecycle capabilities. The shift concentrates procurement leverage at carriers like Delta and United while displacing smaller regional specialists from narrow-body programs. This consolidation is most visible in US-based fleet management organizations where total cost of ownership modeling now dominates source selection criteria.
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market Segmentation
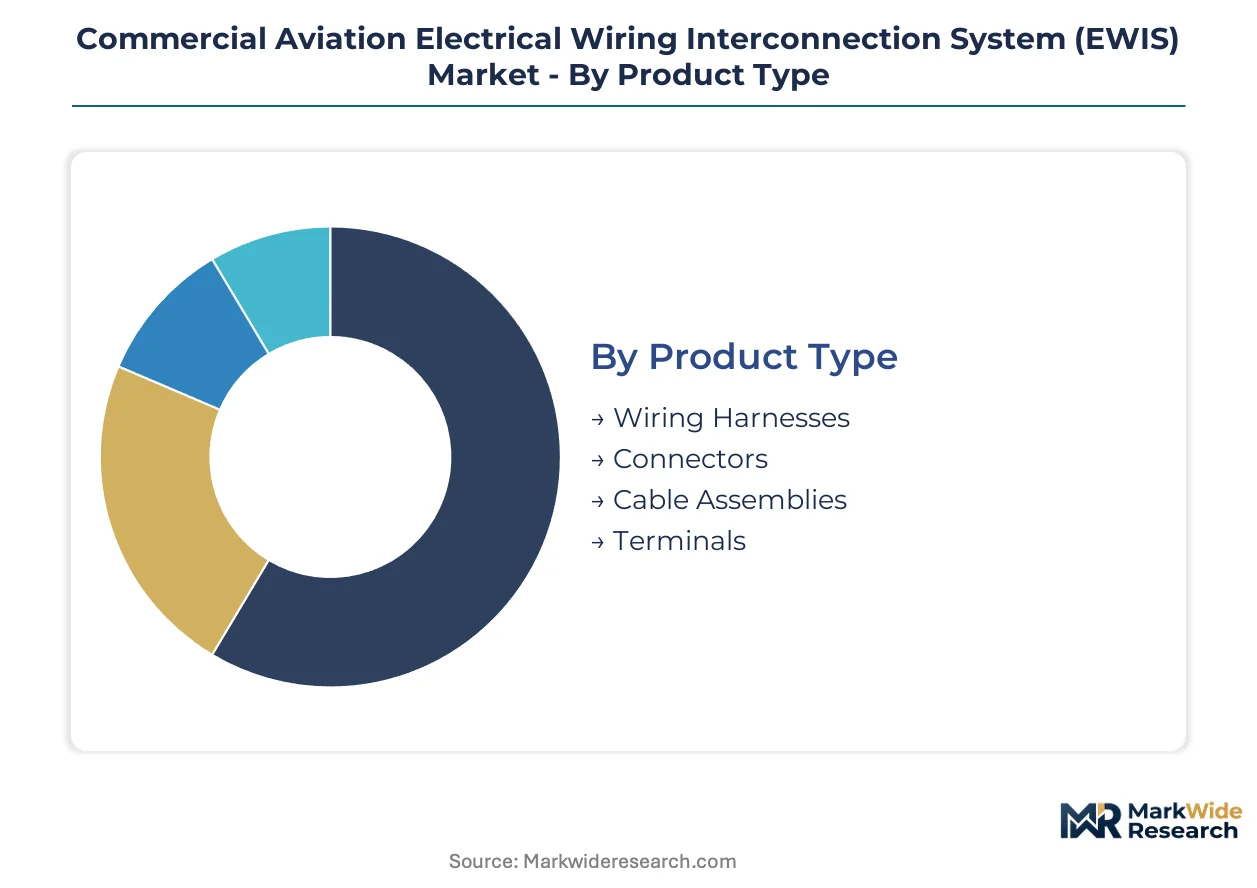
EWIS procurement patterns diverge sharply across product architectures, customer types, and compliance pathways. Understanding these fault lines reveals where margin pools concentrate and where supplier qualification barriers create defendable positions.
Product Type:
Use-case spectrum spans from labor-intensive custom harness fabrication to standardized connector commoditization.
- Wiring Harnesses:Custom-fabricated cable bundles with precise length, termination, and routing specifications dominate aftermarket replacement cycles. Narrow-body fleet renewal at US carriers and IndiGo's expansion in India concentrate procurement volume in high-mix, low-volume production environments where IPC/WHMA-A-620 certification filters supplier participation.
- Connectors:MIL-DTL-qualified interconnect products from TE Connectivity and Amphenol penetrate both OEM line-fit and MRO channels. FAA Part 25 arc-fault mandates are accelerating retrofit demand for sealed, vibration-resistant connector families in aging Boeing 737 and Airbus A320 harness upgrades.
- Cable Assemblies:Pre-terminated power and signal distribution segments serve regional jet platforms where standardization limits customization requirements.
- Terminals:Crimp and solder termination hardware represent the most price-sensitive product tier, with copper price volatility directly pressuring margin structures.
Established volume favors Wiring Harnesses; emerging adoption favors Connectors as regulatory retrofit cycles accelerate.
End User:
Customer archetypes range from capital-constrained MRO facilities to specification-driving OEM engineering departments.
- Commercial Airlines:Delta, United, and Southwest fleet management organizations consolidate supplier panels from twelve-plus vendors to three or four strategic partners with full lifecycle capabilities. Total cost of ownership modeling now dominates source selection criteria for narrow-body programs.
- OEMs:Boeing's 777X and Airbus A350 programs specify carbon nanotube-infused insulation for fire-zone harnesses, pushing material innovation requirements upstream to qualified wire extruders. Design authority retention at Wichita and Toulouse engineering centers limits aftermarket supplier design influence.
- Maintenance Providers:Lufthansa Technik and ST Engineering face compressed downtime windows as EASA CS-25 wire separation amendments force center wing box harness redesign during heavy maintenance visits.
- Aftermarket Suppliers:Independent distributors and PMA part developers target aging fleet segments where OEM intellectual property restrictions have lapsed.
Procurement leverage concentrates at Commercial Airlines; technical specification control rests with OEMs.
Technology:
Material and architecture choices trade electromagnetic immunity, weight, and thermal endurance against qualification cost and supply base maturity.
- Copper Wiring:Volume backbone across narrow-body and regional jet platforms, though temperature ratings above 260°C remain unachievable without ceramic-coated conductor alternatives that fragment supplier qualification pathways. GKN Aerospace and Safran maintain captive extrusion capacity for specialized insulation compounds.
- Fiber Optic Systems:Displacing legacy copper in high-bandwidth avionics backbone applications where electromagnetic interference immunity is critical. Boeing 787 and Airbus A350 flight deck architectures mandate fiber optic data transmission for sensor fusion and display systems.
- Hybrid Systems:Blending copper power distribution with fiber optic data transmission represents the steepest expansion trajectory as next-generation aircraft architectures consolidate wiring counts.
- Advanced Materials:Carbon nanotube and ceramic-coated conductors address fire-zone installations where polyimide insulation technical ceilings constrain legacy alternatives.
Copper retains installed base dominance; Hybrid Systems capture specification momentum in new program development.
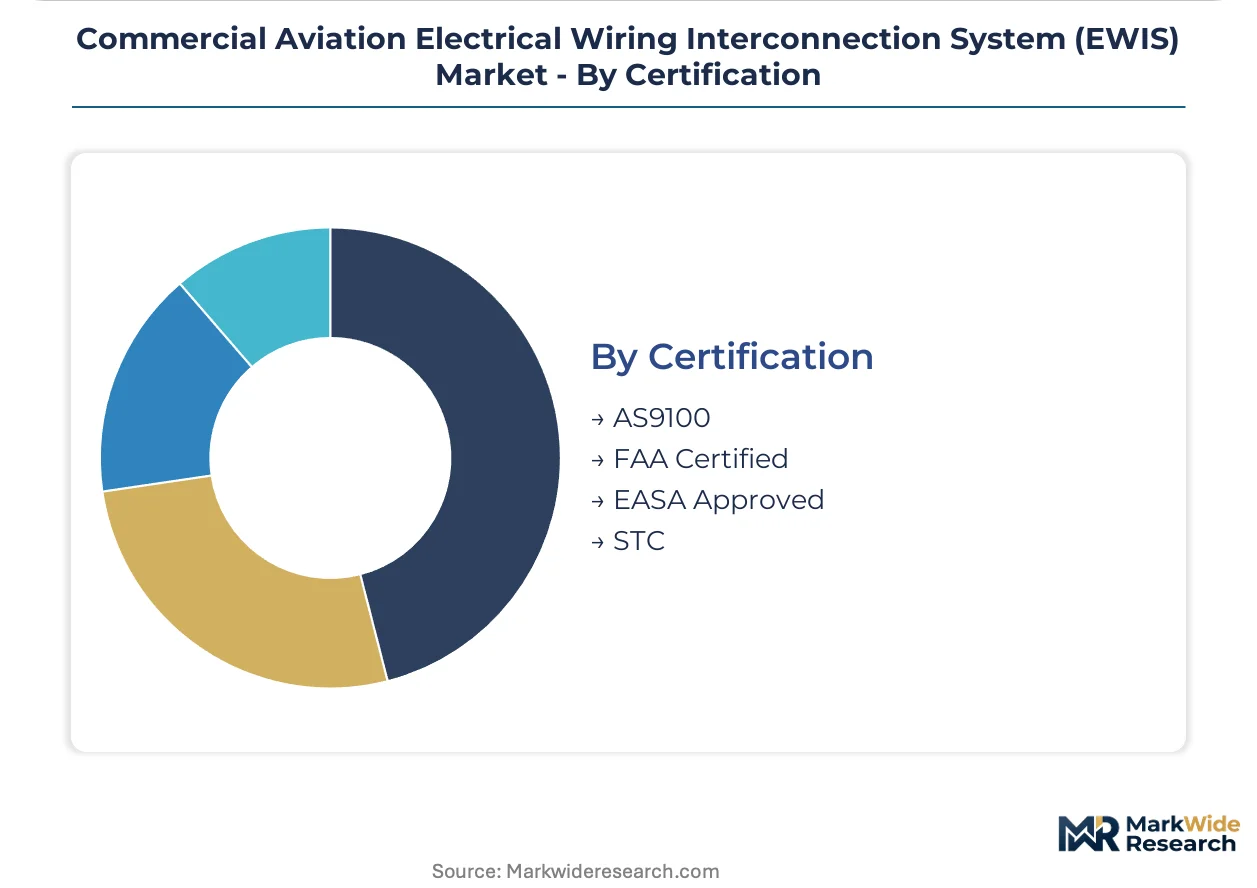
Certification:
Compliance tier determines market access and pricing power across the value chain.
- AS9100:Non-negotiable aerospace quality management threshold filtering supplier participation to qualified manufacturing networks. Certification scarcity in Western Europe wire extrusion creates single-source dependencies for specialized compounds.
- FAA Certified:Part 25.1701-1733 EWIS-specific regulations mandate enhanced arc-fault protection and wire separation for US-registered transport category aircraft.
- EASA Approved:CS-25 Subpart H amendments on installation accessibility compel European operators to retrofit aging fleets with compliant harness configurations.
- STC:Supplemental type certificate pathway for aftermarket modification packages, though approval timeline divergence between FAA and EASA offices strains dual-approval development budgets.
AS9100 functions as universal gatekeeper; STC complexity favors specialists with bilateral regulatory relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EWIS procurement patterns diverge sharply by geography. US carriers prioritize aftermarket retrofit compliance, European operators face compressed downtime windows from regulatory amendments, and Asian-Pacific airlines concentrate volume in Singapore and Kuala Lumpur maintenance corridors.
United States
Southwest Airlines and Delta Air Lines fleet renewal programs are accelerating harness replacement cycles across narrow-body platforms. FAA Part 25.1701-1733 arc-fault mandates compel retrofit obligations on pre-2010 airframes. Seattle and Charleston anchor the highest-volume procurement corridors through Boeing's final assembly lines in Washington and South Carolina.
Germany
Lufthansa Technik faces compressed downtime windows as EASA CS-25 Subpart H wire separation amendments force center wing box harness redesign during heavy maintenance visits. The country's national aviation regulator enforces installation accessibility standards that exceed baseline European requirements. Hamburg and Frankfurt concentrate MRO provider capacity for modular harness replacement kit deployment.
France
Airbus engineering centers at Toulouse retain design authority over A350 and A320 family EWIS specifications, limiting aftermarket supplier design influence. EASA CS-25 amendments on wire separation compel retrofit demand for in-service narrow-body fleets. Safran's Villaroche facility sustains captive wire extrusion through final harness assembly for OEM line-fit programs.
India
IndiGo's narrow-body expansion concentrates procurement volume in Delhi and Mumbai maintenance hubs. The country's national aviation regulator aligns certification timelines with EASA standards, streamlining dual-approval pathways for European suppliers. Bangalore and Hyderabad emerging as assembly capacity clusters for localized harness production to reduce import lead times.
Singapore
ST Engineering and AirAsia fleet renewal programs channel aftermarket demand through Singapore and Kuala Lumpur maintenance corridors. The Civil Aviation Authority of Singapore enforces AS9100 certification thresholds that filter supplier participation to qualified manufacturing networks. Seletar Aerospace Park concentrates regional MRO capacity for hybrid system upgrades blending copper power distribution with fiber optic data transmission.
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market Vendor Landscape
Capability concentration sits with vertically integrated wire extruders; scale advantage sits with harness assemblers serving multiple OEM programs. The market structures around three tiers: aerospace-qualified manufacturers with AS9100 certification, specialized harness fabricators with IPC/WHMA-A-620 technician pools, and connector specialists with MIL-DTL qualification. Strategic moves concentrate on backward integration into insulation compound production and geographic expansion toward Saudi Arabia and India fleet growth corridors.
Among UK-based aerostructures specialists, GKN Aerospace Services exemplifies the vertically integrated tier with Bristol-based harness production for wide-body programs. Safran occupies a position within the captive supply archetype through its Villaroche facility's control from wire extrusion through final assembly. TE Connectivity anchors the connector segment with MIL-DTL-qualified product lines penetrating both OEM and MRO channels.
| Leading Market Players |
|---|
| GKN Aerospace Services |
| Ducommun Incorporated |
| Safran |
| InterConnect Wiring |
| Collins Aerospace |
| TE Connectivity |
| Latécoère |
| Esterline Technologies |
| Amphenol Corporation |
| Others |
Supply Flow & Price Mechanics
Copper price volatility on the London Metal Exchange determines both pricing tier spreads and supply chain shape across the EWIS value chain, compressing margins at regional jet suppliers while concentrating procurement leverage at carriers with long-term offtake agreements.
Pricing Analysis
Long-term offtake contracts dominate OEM line-fit procurement, insulating Boeing and Airbus assembly lines from spot market swings in copper and polyimide insulation compounds. Price differentiation rests on AS9100 certification grade and harness customization depth, with IPC/WHMA-A-620 qualified fabricators commanding premiums over uncertified competitors. Cost compression in regional jet cable assemblies is intensifying because LME copper futures routinely breach hedging thresholds. Maintenance providers at Lufthansa Technik and ST Engineering exhibit highest price sensitivity due to compressed downtime windows, while OEM engineering departments at Toulouse and Wichita show lowest sensitivity given design authority retention.
Supply Chain Analysis
Contract manufacturing concentration sits with Safran's Villaroche facility and GKN Aerospace's Bristol operations, which control captive wire extrusion through final harness assembly for wide-body programs. Geographic supply concentration centers on France, the United Kingdom, and the United States, with emerging assembly clusters in Bangalore and Hyderabad drawing from localized production incentives. Raw material dependencies hinge on copper cathode from Chilean and Peruvian mining operations, polyimide resin from Japanese chemical specialists, and carbon nanotube feedstock from South Korean suppliers. Single-source vulnerability permeates Western European wire extrusion capacity for specialized insulation compounds. Distribution runs through Boeing's Seattle and Charleston final assembly corridors, Airbus Toulouse line-fit channels, and Singapore-Kuala Lumpur MRO hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet modernization mandates across narrow-body platforms signal early-cycle expansion, with FAA Part 25 arc-fault retrofit obligations creating sustained aftermarket demand tailwinds.
For Market Incumbents: Insulate margin structures by deepening backward integration into polyimide insulation compound production and expanding IPC/WHMA-A-620 certified technician pools at US and UK MRO facilities. Carbon nanotube-infused wire qualification pathways represent a critical defensive lever against emerging material specialists threatening fire-zone harness specifications. For New Entrants and Emerging Players: Build out modular harness replacement kit capabilities targeting EASA CS-25 wire separation amendment cycles at European maintenance providers. Saudi Arabia's fleet expansion corridor offers the most penetrable geography, with Riyadh-based Saudia and flyadeal growth plans creating demand for localized assembly capacity. A direct sales model to airline engineering departments bypasses entrenched OEM supply relationships. For Investors and Strategic Acquirers: The market sits at a fleet renewal phase that favors vertically integrated wire extruders with AS9100 certification and established OEM line-fit relationships. Long-term viability centers on suppliers controlling insulation compound production through final harness assembly. The signal to watch is EASA-FAA STC approval timeline convergence, which would reduce dual-certification burdens and expand aftermarket addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Insulation Compounds | Safran's Villaroche captive extrusion capacity eliminates single-source dependencies for specialized fire-zone materials. |
| IPC/WHMA-A-620 Technician Certification Expansion | Lufthansa Technik's modular kit deployment reduces on-aircraft labor hours during compressed EASA amendment windows. |
| Localized Assembly Capacity in Saudi Arabia | Riyadh-based harness production shortens import lead times for Saudia and flyadeal narrow-body expansion programs. |
| Carbon Nanotube Wire Qualification | Boeing 777X specifications drive adoption across engine nacelle installations, collapsing historical weight penalties. |
| Hybrid System Architecture Development | Airbus A350 flight deck mandates blend copper power distribution with fiber optic data transmission for sensor fusion. |
Methodological Framework
Operator-level perspectives from fleet engineering directors, MRO procurement managers, OEM platform engineers, and wire extrusion facility managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA Part 25.1701-1733 regulatory filings, EASA CS-25 Subpart H amendment documentation, and AS9100 certification registry data. Bottom-up harness demand modeling triangulated against top-down aircraft production forecasts from Boeing and Airbus assembly line disclosures.
Scenario-bracketing across regulatory compliance timelines, copper price volatility bands, and fleet renewal acceleration cases framed the analytical envelope over the projection horizon. Segmentation dimensions modeled include product architecture, customer archetype, technology material, and certification tier. CAGRs derived from installed base attrition rates and new program line-fit specifications. Industry-specific forecast inputs encompassed narrow-body fleet age distributions and EASA amendment implementation schedules.
Stress conditions across LME copper futures volatility, dual FAA-EASA STC approval divergence, and IPC/WHMA-A-620 technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM design authority retention. Quarterly review of fleet renewal program announcements and certification timeline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Military Power Solutions Market