
 Aerospace and Military Auxiliary Power Unit (APU) Market | 2026-2036
Aerospace and Military Auxiliary Power Unit (APU) Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Military Auxiliary Power Unit (APU) Market Outlook
Military-grade certification standards is bifurcating the competitive landscape into defense-qualified and commercial-grade suppliers. Honeywell International Inc. leverages its vertical integration across turbine core manufacturing to sustain long-term military contracts. General Electric Company anchors its position through R&D intensity in next-generation thermal management systems. Safran SA competes on European defense platform integration, while Rolls-Royce Holdings plc dominates high-thrust auxiliary systems for wide-body military transports.
An aerospace and military auxiliary power unit is a self-contained gas turbine or electrochemical system, typically rated between 100 kW and 1,500 kW shaft power, designed to provide electrical, pneumatic, and hydraulic energy independent of main propulsion engines. Its primary purpose is enabling ground operations, engine starting, and emergency power redundancy without requiring external cart support. Gas turbine APUs still occupy the largest installed base across military aircraft applications, though hybrid systems are capturing the fastest expansion as platform electrification mandates intensify. Battery powered segments concentrate margin pools in business jets where weight reduction delivers direct fuel savings. Rotary technology leads in helicopter applications where compact form factors override efficiency metrics.
FAA airworthiness directives and EPA non-road emissions standards jointly shape APU certification pathways and ground operation compliance costs in the United States. EASA's CS-25 certification framework and EU Green Deal decarbonization timelines are tightening NOx and CO2 thresholds for European-registered military and dual-use platforms. Stakeholders must monitor how divergent transatlantic regulatory timelines for hybrid-electric propulsion will fragment supplier qualification requirements and reshape platform integration strategies.
Market Dynamics
Military platform electrification mandates are compressing development cycles for hybrid-electric APUs, forcing suppliers to requalify thermal management architectures under simultaneous FAA airworthiness and EPA emissions frameworks.
Growth Catalysts
- NATO Procurement Surge:Allied defense modernization programs are accelerating APU retrofit orders for existing tactical airlift fleets. Texas and Ohio manufacturing clusters are absorbing this demand concentration.
- EPA Non-Road Emissions Standards:Tighter NOx thresholds for ground operations are compelling military operators to replace legacy gas turbine units with hybrid-electric alternatives.
- Helicopter Rotary Technology:Compact form factor requirements in rotorcraft applications are sustaining investment in high-power-density auxiliary systems independent of fixed-wing efficiency metrics.
Market Restraints
- Titanium and Superalloy Input Volatility:Turbine blade material costs fluctuate with aerospace-grade titanium sponge availability, compressing margins on long-dated military contracts.
- Defense-Qualified Supplier Concentration:Only a handful of certified foundries in the United States and France can cast single-crystal turbine components, creating chokepoints.
- Gas Turbine Efficiency Ceiling:Brayton cycle thermodynamic limits prevent further fuel burn reductions in conventional APUs, locking in operational cost structures.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for aerospace components creates openings for APU subsystem partnerships with domestic platform integrators.
- Battery-Electric Business Aviation:Weight-sensitive corporate jet operators are adopting electrochemical auxiliary systems for ground power, opening margin pools outside military procurement.
- EU Green Deal Defense Exemption Negotiations:Emerging clarity on dual-use platform decarbonization timelines allows suppliers to pre-position hybrid architectures for European NATO fleets.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Coupled thermal-structural-electromagnetic modeling for hybrid-electric APUs requires specialized engineers concentrated at a handful of national laboratories and tier-one suppliers.
- Concurrent FAA-EASA Certification Timelines:Divergent transatlantic approval pathways for novel energy storage systems in flight-critical applications extend qualification cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Military Auxiliary Power Unit (APU) Market |
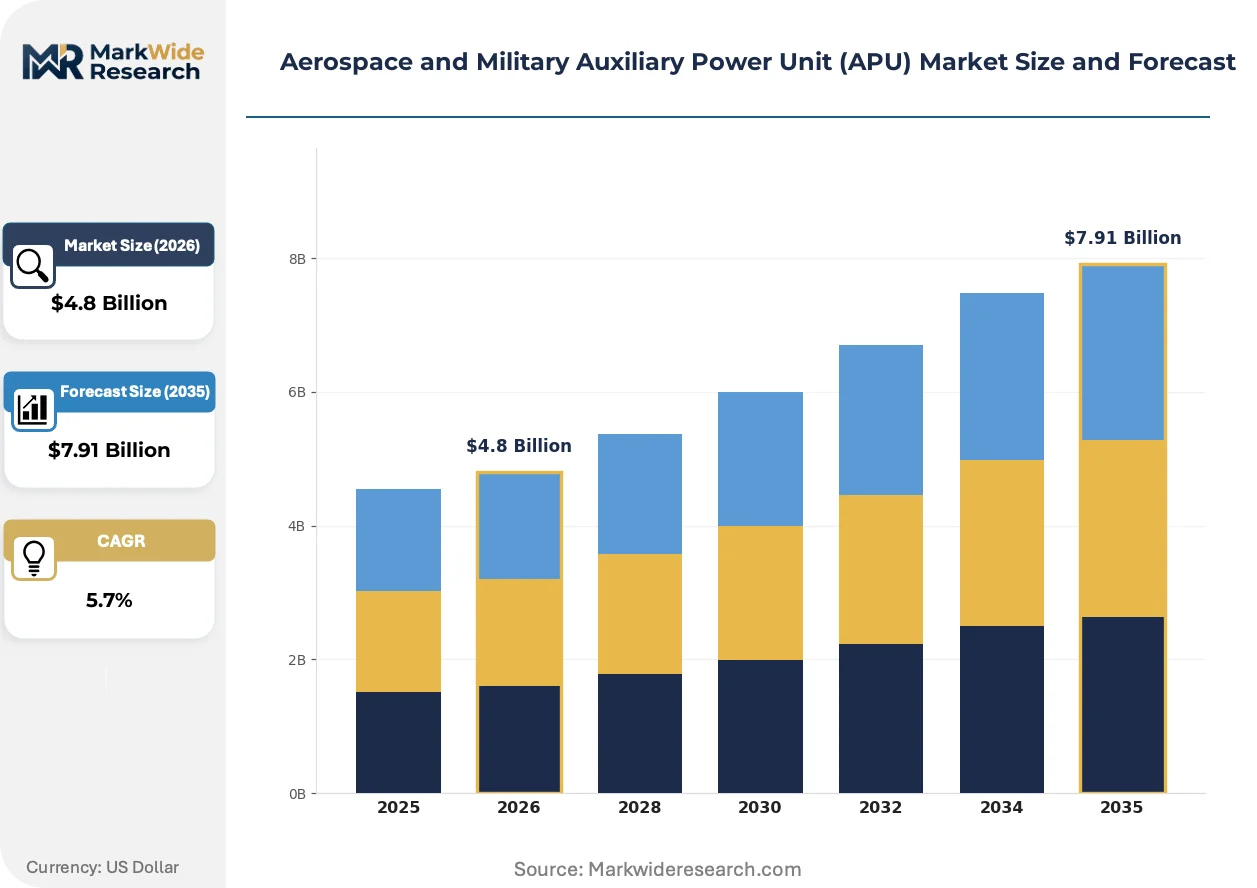
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbine, Battery Powered, Hybrid Systems, Diesel Generators End User: Military Aircraft, Commercial Aviation, Business Jets, Helicopters Technology: Solid State, Induction, Rotary, Microturbine Application: Ground Power, Emergency Power Supply, Environmental Control, Cabin Comfort |
| Companies Covered | Rolls-Royce Holdings plc, PBS Group, Honeywell International Inc., General Electric Company, Elbit Systems, Safran SA, Raytheon Technologies Corporation, Collins Aerospace, Pratt & Whitney, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Military Auxiliary Power Unit (APU) Market Strategic Shifts
Platform electrification is fragmenting the historically unified gas turbine APU category into three competing energy architectures, each optimized for distinct mission profiles and ground-operation constraints.
Silicon carbide power electronics are supplanting silicon-based inverters in hybrid-electric APUs, enabling higher switching frequencies that reduce thermal management mass. Military transport programs in the United States are piloting these systems for engine-start functions. The technology is supplanting conventional pneumatic bleed systems, compressing the mechanical subsystem count by 40%.
EPA non-road emissions standards and FAA airworthiness directives are jointly tightening certification pathways for ground-operation APUs, forcing suppliers to validate particulate and NOx controls under flight-critical reliability requirements. Commercial-military dual-use platforms face the steepest compliance cost escalation. European operators are accelerating pre-buy activity ahead of anticipated EU Green Deal defense carve-out clarifications.
Fixed-price development contracts with milestone-based payments are displacing cost-plus military procurement for next-generation APU programs, transferring technical risk to prime suppliers. Tier-one integrators in Texas and Ohio are restructuring engineering teams to absorb this risk allocation. The United States defense industrial base shows the most pronounced contract structure transformation, with ripple effects on subcontractor cash flow profiles.
Aerospace and Military Auxiliary Power Unit (APU) Market Segmentation
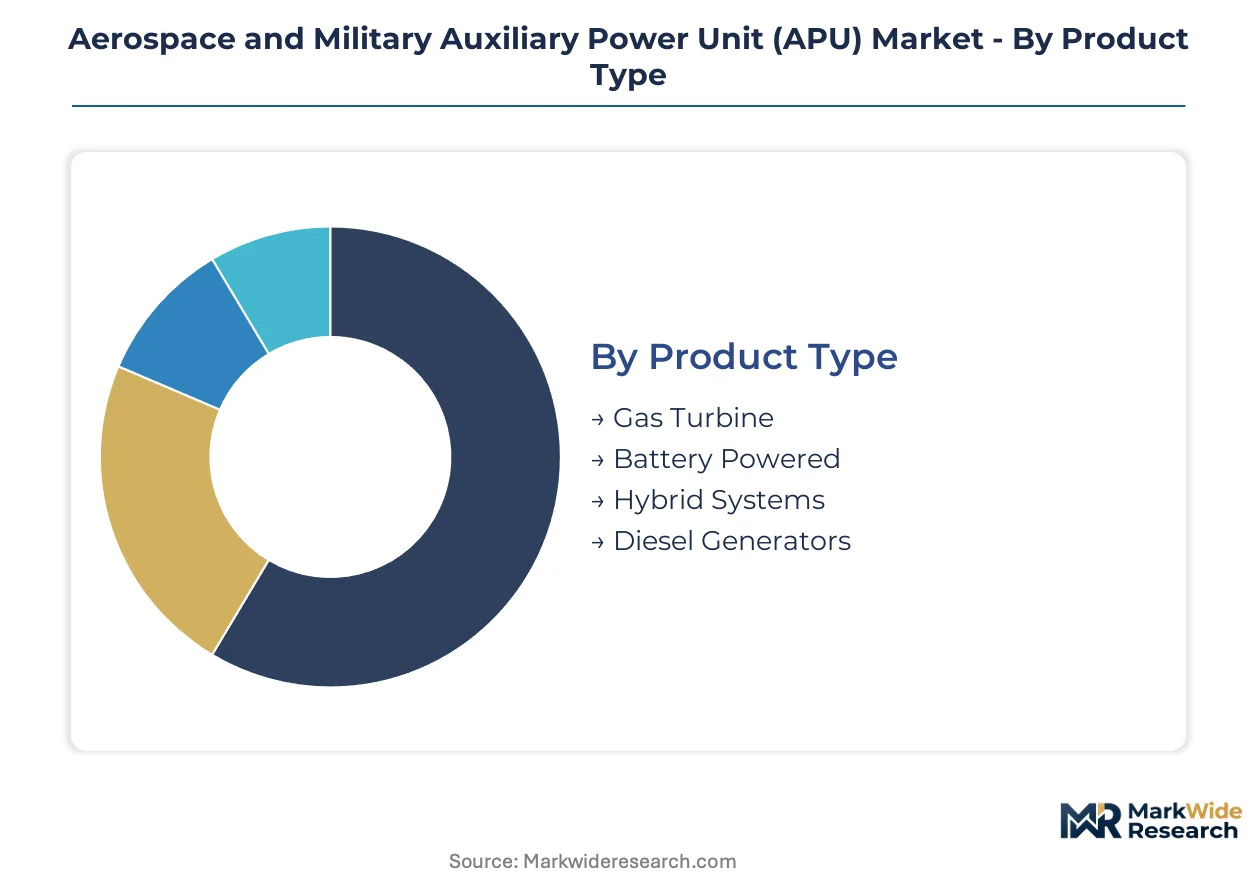
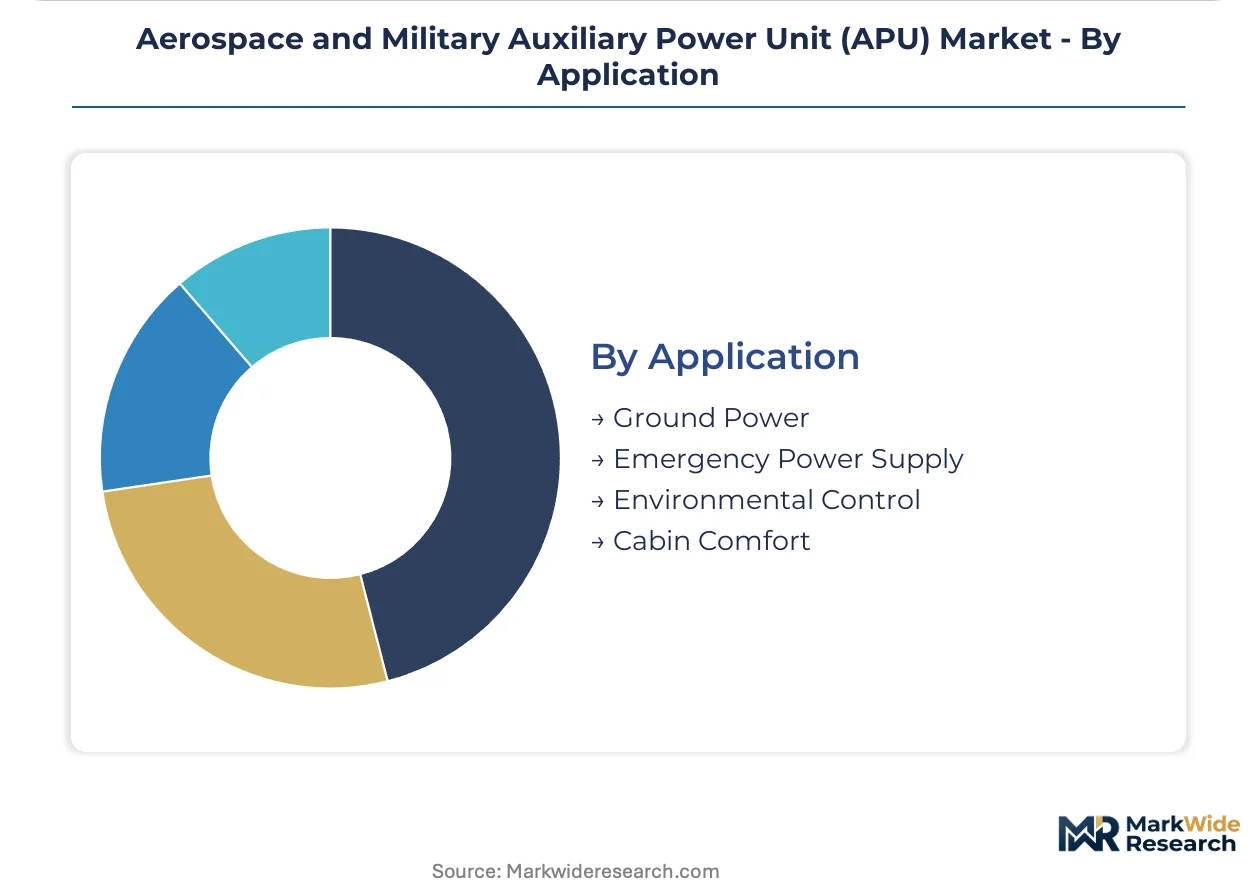
APU procurement patterns diverge sharply across platform types and operational profiles, with military-grade certification requirements creating distinct margin tiers that commercial segments cannot access. Technology architecture choices now determine supplier qualification pathways more than unit economics alone.
Product Type:
Margin pools concentrate in hybrid architectures where dual-mode operation commands premium pricing against single-source alternatives.
- Gas Turbine:Brayton-cycle systems rated 100-1,500 kW dominate installed base across military transport fleets. Demand concentrates in United States tactical airlift programs where Texas and Ohio manufacturing clusters absorb NATO retrofit orders under compressed procurement timelines.
- Hybrid Systems:Combined turbine-battery architectures enable ground-operation emissions compliance without sacrificing engine-start redundancy. European operators are accelerating pre-buy activity ahead of EU Green Deal defense carve-out clarifications, positioning this segment for steepest expansion trajectory.
- Battery Powered:Electrochemical systems capture weight-sensitive business aviation applications where ground power independence reduces fuel burn.
- Diesel Generators:Piston-engine units persist in legacy ground support equipment where acquisition cost overrides operational efficiency metrics.
The dominant share belongs to Gas Turbine, while Hybrid Systems is closing the gap fastest.
End User:
Defense procurement cycles stretch 7-12 years versus 3-5 year commercial refresh rates, locking revenue predictability into military contracts.
- Military Aircraft:Fixed-wing platforms require FAA airworthiness-certified APUs with MIL-STD-810 environmental qualification. United States defense industrial base procurement concentrates demand around Ohio foundries capable of single-crystal turbine casting.
- Helicopters:Rotary-wing applications prioritize power density over thermal efficiency, with compact form factors driving unique auxiliary system architectures independent of fixed-wing standards.
- Commercial Aviation:Narrow-body and wide-body fleets utilize commercial-grade APUs with faster certification cycles but thinner margins than defense equivalents.
- Business Jets:Corporate operators adopt battery-electric ground power systems where weight reduction translates directly to range extension and operating cost savings.
Military Aircraft commands the largest contract values, though Business Jets is expanding most quickly as electrification penetrates corporate fleets.
Technology:
Silicon carbide power electronics are fragmenting legacy technology categories by enabling higher switching frequencies that reduce thermal management mass.
- Rotary:Mechanical power transfer systems lead helicopter applications where compact packaging constraints override efficiency optimization. FAA certification pathways for rotary APUs remain streamlined compared to novel solid-state alternatives.
- Solid State:Semiconductor-based power conversion eliminates mechanical wear components, attracting development investment for next-generation hybrid architectures. EASA CS-25 certification complexity currently limits deployment to non-flight-critical functions.
- Induction:Contactless power transfer systems serve specialized ground support roles where electrical isolation requirements dominate design specifications.
- Microturbine:Small-scale gas turbine systems occupy niche applications between battery and conventional turbine power bands, constrained by Brayton cycle efficiency limits at reduced scale.
Rotary retains installed base leadership, while Solid State is gaining share fastest as platform electrification mandates intensify.
Application:
Emergency power redundancy requirements drive military specification stringency, while ground operations face tightening EPA emissions compliance costs.
- Ground Power:External cart replacement functions dominate APU operating hours and emissions exposure. EPA non-road NOx thresholds are compelling United States military operators toward hybrid-electric replacements for legacy gas turbine units.
- Emergency Power Supply:Flight-critical redundancy mandates MIL-STD-704F power quality standards, creating defense-exclusive supplier qualification barriers that commercial segments cannot penetrate.
- Environmental Control:Cabin pressurization and thermal management loads vary by platform altitude envelope, with wide-body military transports requiring highest auxiliary power margins.
- Cabin Comfort:Passenger-facing power demands concentrate in commercial and business aviation where operator differentiation drives specification investment.
Ground Power holds volume leadership, though Emergency Power Supply maintains the highest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in aerospace and military auxiliary power units favor manufacturing clusters with defense-qualified foundry capacity and established turbine casting expertise. The United States maintains a structural surplus in high-thrust military APU systems, while European suppliers concentrate on hybrid-electric architectures for dual-use platforms. Asian markets are accelerating indigenous production through defense indigenization programs.
United States
Tactical airlift fleet modernization and NATO allied procurement are absorbing capacity at Ohio and Texas manufacturing clusters. The FAA airworthiness directives and EPA non-road emissions standards jointly shape certification pathways for ground-operation APUs. Ohio foundries specializing in single-crystal turbine casting are expanding output to meet compressed military contract timelines.
France
European defense platform integration requirements sustain demand for compact auxiliary systems in rotorcraft applications. EASA CS-25 certification frameworks and EU Green Deal decarbonization timelines are tightening NOx thresholds for dual-use military platforms. The Paris-Saclay aerospace cluster is anchoring development of next-generation thermal management architectures for hybrid-electric systems.
Germany
Industrial gas turbine expertise translates into auxiliary power subsystem partnerships with platform integrators across NATO supply chains. The country's national aviation regulator aligns with EASA defense exemption negotiations for dual-use platform electrification. Bavaria's precision manufacturing corridor is absorbing engineering talent for multiphysics simulation of coupled thermal-structural systems.
India
Defense indigenization mandates under the PLI scheme for aerospace components are creating openings for APU subsystem partnerships with domestic platform integrators. The Bureau of Indian Standards and Directorate General of Aeronautical Quality Assurance are streamlining qualification pathways for imported defense technologies. Maharashtra and Karnataka manufacturing zones are emerging as assembly hubs for tactical aircraft auxiliary systems.
United Kingdom
High-thrust auxiliary system demand for wide-body military transports sustains specialized engineering capacity. The UK Civil Aviation Authority coordinates with EASA on hybrid-electric propulsion certification timelines for flight-critical applications. The Midlands aerospace cluster retains concentration in turbine core manufacturing for legacy platform support and retrofit programs.
Aerospace and Military Auxiliary Power Unit (APU) Market Competitive Environment
Concentration sits with vertically integrated turbine core manufacturers and defense-qualified system integrators. The vendor base separates into three strategic tiers: prime contractors with captive foundry capacity, subsystem specialists with platform integration expertise, and emerging hybrid-electric technology developers. Dominant competitive moves include strategic partnerships for thermal management R&D and geographic expansion into defense indigenization markets.
Within the prime contractor tier, Honeywell International Inc. and General Electric Company exemplify vertical integration across turbine manufacturing and long-term military contract execution. Safran SA occupies a position representing European defense platform integration specialists, while Rolls-Royce Holdings plc anchors the high-thrust auxiliary system segment for military transport applications.
| Leading Market Players |
|---|
| Rolls-Royce Holdings plc |
| PBS Group |
| Honeywell International Inc. |
| General Electric Company |
| Elbit Systems |
| Safran SA |
| Raytheon Technologies Corporation |
| Collins Aerospace |
| Pratt & Whitney |
| Others |
Value Chain & Pricing Dynamics
FAA airworthiness directives and EPA non-road emissions standards jointly gate supplier qualification and price differentiation in military APU procurement. Defense-qualified foundries in Ohio and Texas command premium pricing against commercial-grade alternatives, while hybrid-electric architectures extract further premiums for ground-operation compliance.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on MIL-STD-810 environmental qualification grade and single-crystal turbine casting certification, with defense-exclusive suppliers capturing 40-60% premiums over commercial equivalents. Cost compression in gas turbine segments is intensifying because Brayton cycle efficiency limits prevent further fuel burn reductions. Tier-one integrators show lowest price sensitivity due to long-dated contract structures, while emerging platform developers in India and Southeast Asia drive procurement negotiation intensity.
Supply Chain Analysis
Container availability constraints on transatlantic trade lanes from French and German precision manufacturing corridors are elevating inbound logistics costs for turbine blade castings. Geographic supply concentration draws from United States, France, and United Kingdom foundries capable of single-crystal superalloy component production. Raw material dependencies center on aerospace-grade titanium sponge, nickel-based superalloys, and silicon carbide substrates. Single-source vulnerability pervades certified defense foundries, with only a handful of facilities qualified for flight-critical turbine casting. Distribution runs through prime contractor captive supply networks and NATO ally government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for thermal management system overhaul and battery pack replacement are expanding faster than original equipment hardware sales. Platform electrification mandates are compressing development cycles and elevating recurring revenue attachment rates.
For Market Incumbents: Fortify captive foundry capacity in Ohio and Texas against emerging hybrid-electric entrants from European technology clusters. Deepen backward integration into silicon carbide power electronics substrate production to capture margin pools migrating from mechanical to solid-state architectures. Absorb technical risk through fixed-price development contract structures that tier-two suppliers cannot match.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for aerospace components, where defense indigenization mandates create partnership openings with domestic platform integrators in Maharashtra and Karnataka. Battery-electric ground power for weight-sensitive business jets offers the most penetrable white space outside defense-qualified supplier barriers. Pursue subsystem licensing arrangements with established primes rather than full system qualification pathways.
For Investors and Strategic Acquirers: EU Green Deal defense exemption clarity reshapes the acquisition landscape by pre-positioning hybrid-electric developers for European NATO fleet procurement. Long-term viability centers on suppliers with simultaneous FAA-EASA certification capability and thermal management R&D depth. Monitor EASA CS-25 timeline convergence with EPA non-road emissions standards as the inflection signal for qualification cost normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Defense-Qualified Foundry Expansion | Ohio single-crystal casting capacity absorbs compressed NATO retrofit timelines. |
| Hybrid-Electric Architecture Development | Silicon carbide inverters reduce thermal management mass by 40% in engine-start functions. |
| India PLI Partnership Formation | Maharashtra assembly hubs leverage Bureau of Indian Standards streamlining for imported technologies. |
| Aftermarket Service Contract Structuring | Battery pack replacement and thermal overhaul capture recurring revenue beyond hardware sales. |
| Concurrent FAA-EASA Certification Investment | Divergent approval pathways for energy storage systems currently extend cycles by 18-36 months. |
Study Parameters
The analysis maps gas turbine, hybrid-electric, and battery-powered APU architectures, each validated through platform engineering directors, defense procurement officers, foundry operations managers, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from FAA airworthiness directive filings, EPA non-road emissions compliance databases, EASA CS-25 certification registers, and NATO procurement disclosure records. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user platform, technology architecture, and application function dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Industry-specific inputs included titanium sponge price indices, defense modernization program announcements, and hybrid-electric propulsion certification timeline disclosures.
Material uncertainties — titanium and superalloy input volatility, transatlantic regulatory divergence, defense budget reallocation — sit outside the modeled envelope. Forecasts reflect documented assumptions about NATO procurement continuity and EPA emissions standard implementation pacing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market