
 Global Aircraft Electrification Market | 2026-2036
Global Aircraft Electrification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Electrification Market Foresight
EU Green Deal is restructuring the cost-of-entry calculus for new aircraft electrification programs by binding emissions targets to fleet renewal timelines. Honeywell International Inc. leverages its aerospace actuator heritage to dominate integrated power distribution architectures. Safran anchors European supply chains through its ENGINeUS electric motor family. GE Aerospace competes on megawatt-class power systems derived from its turbofan inverter expertise.
Aircraft electrification encompasses the substitution of pneumatic, hydraulic, and mechanical power systems with electric equivalents, typically operating at 270 VDC or 540 VDC in advanced architectures and employing silicon carbide power electronics to achieve specific power densities above 10 kW/kg. Its primary purpose is to reduce fuel burn, maintenance intervals, and emissions while enabling novel propulsion topologies. Battery power sources currently lead installed base but fuel cell segments are recording the fastest expansion in regional aircraft programs. Electric motor technology occupies concentrated margin pools as OEMs pursue integrated motor-inverter designs.
FAA certification standards under Part 33 and Part 35 are evolving to address thermal runaway containment in lithium-ion aircraft batteries, while EASA's SC-VTOL framework governs electric vertical takeoff air taxi designs. The EU AI Act and CSRD disclosure rules are layering algorithmic transparency and emissions reporting obligations onto autonomous flight control systems. Stakeholders must monitor how overlapping jurisdiction between aviation regulators and environmental agencies reshapes product development timelines and market access conditions.
Market Dynamics
The transition from 270 VDC to 540 VDC architectures is compressing development cycles as OEMs race to qualify silicon carbide power electronics for megawatt-class propulsion systems before 2030 fleet renewal deadlines.
Growth Catalysts
- EU Green Deal Fit for 55:Binding aviation emissions targets are forcing regional carriers to accelerate hybrid-electric fleet procurement timelines.
- Silicon carbide semiconductors:These wide-bandgap devices enable power densities above 10 kW/kg, reducing thermal management mass in distributed propulsion designs.
- France-Germany-UK cluster:Concentrated government R&D funding for electric aircraft demonstrators is pulling supplier investment into European supply chains.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in China, creating geopolitical exposure for battery pack OEMs.
- FAA-EASA certification divergence:Differing thermal runaway containment standards under Part 33 and SC-VTOL frameworks extend validation timelines for dual-certification programs.
- Specific energy ceiling:Current lithium-ion chemistry limits electric range to sub-500 nautical miles, excluding transcontinental route applications.
Strategic Opportunities
- India's UDAN regional connectivity scheme:Subsidized short-haul routes create a testbed for sub-megawatt electric turboprops with lower certification barriers.
- Fuel cell-battery hybrid architectures:Converging hydrogen storage and solid-oxide fuel cell technologies unlock hour-long endurance extensions for 19-seat aircraft.
- Vertiport infrastructure mandates:Urban air mobility landing site regulations in the UAE and Singapore are pre-positioning demand for electric VTOL charging standards.
Industry Challenges
- Power electronics talent scarcity:Electromagnetic compatibility design for 540 VDC systems requires skills concentrated in automotive and rail sectors, not traditional aerospace.
- Integrated motor-inverter certification:Combined hardware-software validation under EASA's SC-VTOL and EU AI Act algorithmic transparency rules creates documentation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Electrification Market |
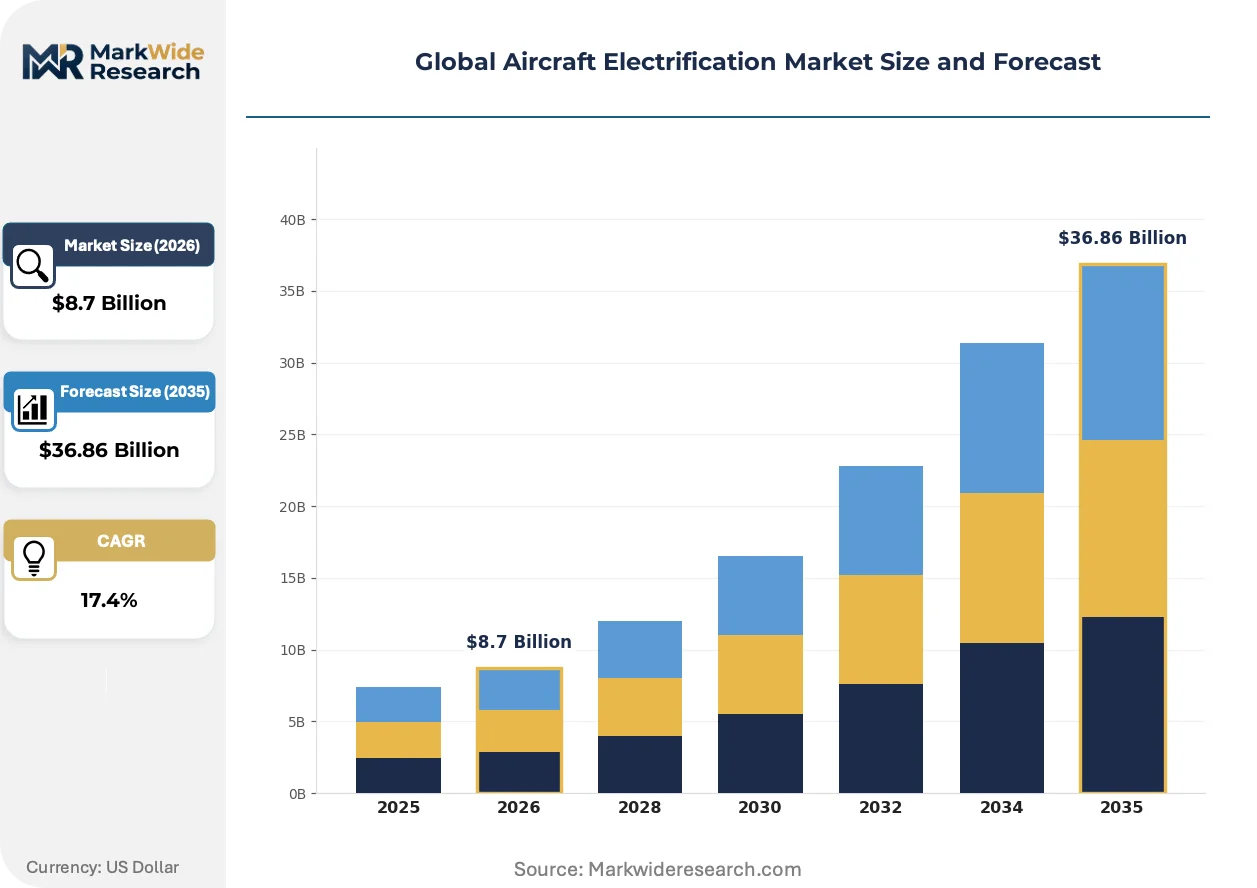
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Battery, Fuel Cell, Hybrid, Solar Aircraft Type: Commercial, Military, Cargo, UAV Application: Propulsion, Auxiliary Power, Ground Support, Drone Operations Technology: Regenerative Braking, Energy Storage Systems, Electric Motors, Inverters |
| Companies Covered | Honeywell International Inc., Safran, GE Aerospace, Thales Group, BAE Systems, RTX Corporation, AMETEK Inc., Astronics Corporation, Crane Aerospace & Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Electrification Market Shifts & Advancements
Power semiconductor evolution and regulatory disclosure requirements are rewriting component sourcing criteria, while procurement organizations restructure supplier relationships around integrated system performance rather than discrete part specifications.
Silicon carbide MOSFET modules function as the switching backbone for 540 VDC distribution buses in advanced more-electric aircraft. Tier-1 suppliers in Germany and Japan are qualifying these devices for 15-year service lives under aerospace thermal cycling profiles. This technology is absorbing development budgets previously allocated to incremental hydraulic system improvements, starving legacy architectures of engineering resources.
EASA's SC-VTOL special condition framework mandates redundant flight control computers with deterministic latency bounds for electric air taxi certification. The regulation forces avionics OEMs to segregate safety-critical code from machine-learning-based path planning under EU AI Act risk classification rules. Urban air mobility developers in France and Germany are responding by partnering with automotive sensor suppliers to accelerate hardware qualification.
Airlines are consolidating electric propulsion procurement under power-by-the-hour contracts that transfer battery degradation risk to system integrators. This unbundles capital expenditure from operational expenditure for regional carriers in Scandinavia and the Pacific Northwest. Lessors in Ireland and Singapore are piloting residual value guarantees for electric aircraft to overcome financing friction in secondary markets.
Global Aircraft Electrification Market Segmentation
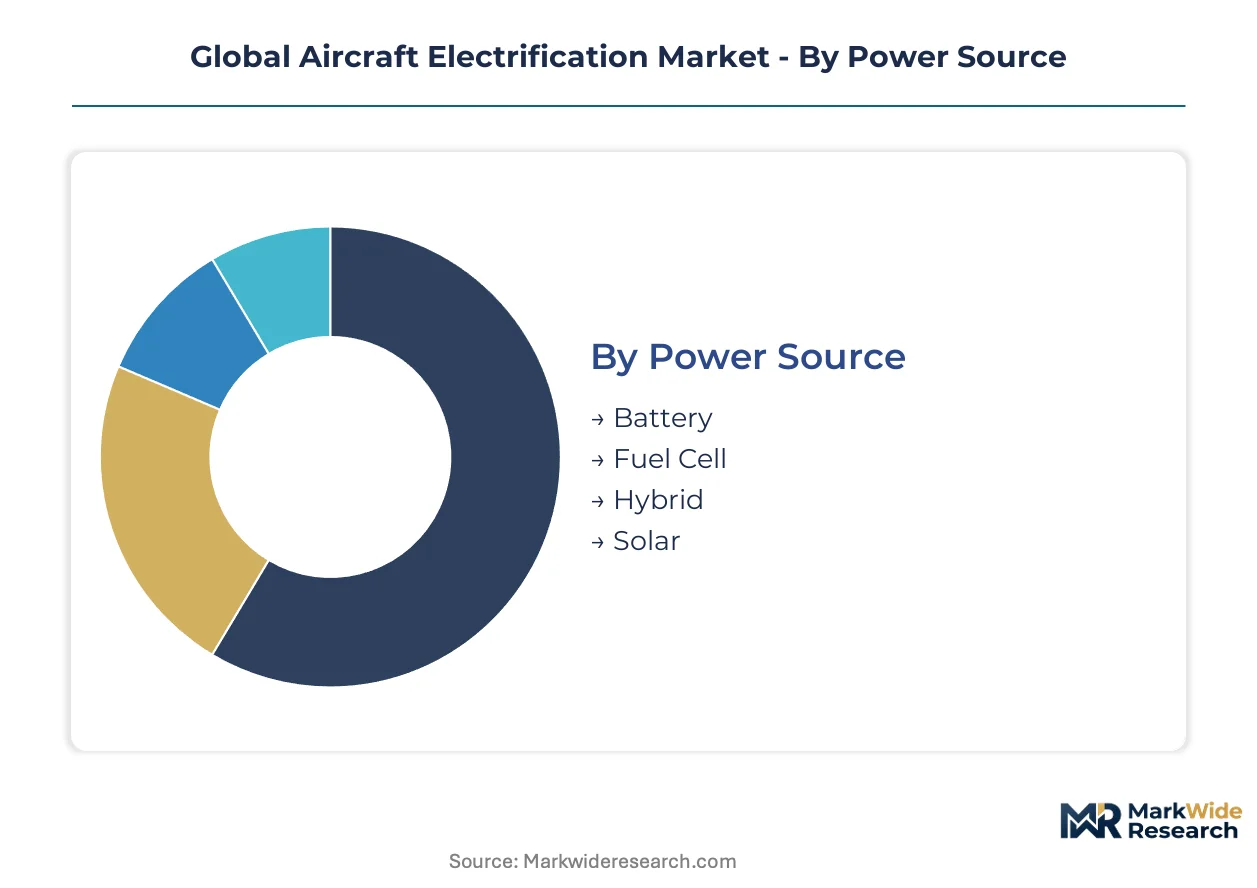
Electrification architectures demand precise segment alignment between voltage classes, mission profiles, and certification pathways. Procurement decisions cascade from power source selection through to motor-inverter integration requirements.
Power Source:
Route distance and charging infrastructure availability dominate airline procurement calculus for propulsion energy storage.
- Battery:Lithium-ion cell packs operating at 270-540 VDC supply primary energy for regional turboprops and urban air mobility platforms. Scandinavian carriers and Pacific Northwest operators concentrate procurement under power-by-the-hour contracts that transfer degradation risk to integrators.
- Fuel Cell:Solid-oxide and proton-exchange membrane systems convert hydrogen to electricity for hour-long endurance extensions in 19-seat aircraft. France-Germany-UK government R&D funding accelerates demonstrator programs targeting sub-megawatt hybrid architectures.
- Hybrid:Turbogenerator-battery combinations preserve range flexibility for regional airlines transitioning from conventional turboprops. The EU Green Deal Fit for 55 package tightens emissions standards that favor hybrid-electric fleet procurement timelines.
- Solar:Photovoltaic arrays on wing surfaces supplement auxiliary power for high-altitude long-endurance UAVs. Experimental applications concentrate in stratospheric platform developers.
Volume sits with Battery; growth tilts toward Fuel Cell.
Aircraft Type:
Certification complexity and operational intensity shape investment allocation across airframe categories.
- Commercial:Single-aisle and regional jets drive megawatt-class power system demand. EASA SC-VTOL and FAA Part 33 thermal runaway standards extend validation timelines for dual-certification programs.
- Military:Stealth and distributed propulsion requirements accelerate more-electric architectures in tactical airlifters. Defense procurement prioritizes electromagnetic compatibility hardening over commercial fuel efficiency metrics.
- Cargo:Short-haul feeder routes and last-mile logistics create entry points for electric freighters with reduced payload-range requirements. India's UDAN regional connectivity scheme subsidizes testbed operations.
- UAV:Urban air mobility and long-endurance surveillance platforms absorb silicon carbide inverter production at scale. Vertiport infrastructure mandates in the UAE and Singapore pre-position charging standard demand.
Commercial aircraft absorb the largest capital deployment; UAV segments climb the fastest.
Application:
System redundancy requirements and duty cycle profiles determine component specification tiers.
- Propulsion:Megawatt-class electric motors and inverters replace turbofan mechanical power take-off systems. Silicon carbide MOSFET modules enable power densities above 10 kW/kg in 540 VDC distribution buses.
- Auxiliary Power:Electric generators and environmental control systems displace pneumatic bleed air in more-electric architectures. This substitution reduces fuel burn and maintenance intervals for hydraulic actuation systems.
- Ground Support:Battery-electric tugs and preconditioned air units eliminate apron emissions during turnarounds. Airport operators in France and Germany face binding emissions disclosure under CSRD rules.
- Drone Operations:Swarm coordination and beyond-visual-line-of-sight missions demand compact energy storage with rapid swap capability. EU AI Act algorithmic transparency requirements layer onto autonomous flight control validation.
Propulsion commands the dominant equipment budget; Drone Operations gain share fastest.
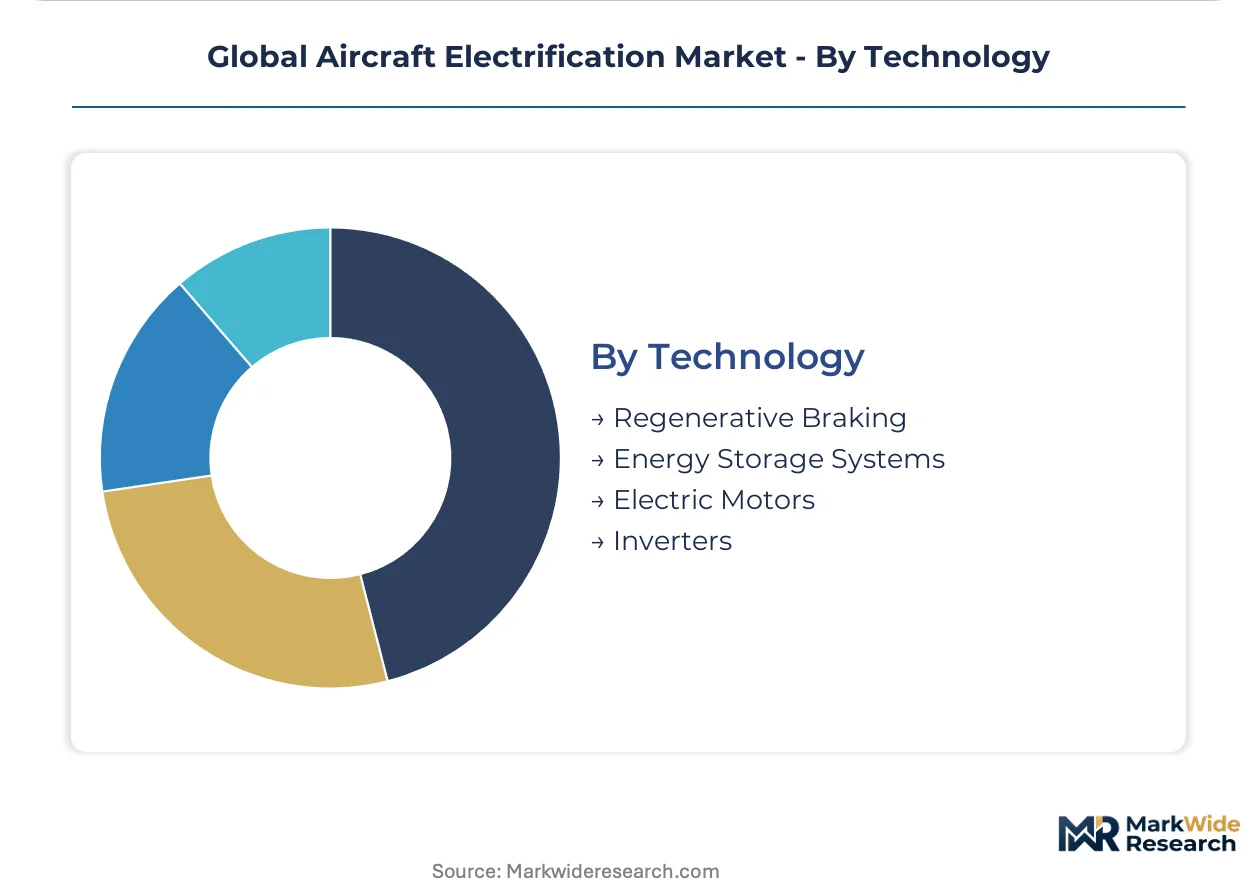
Technology:
Integration depth and semiconductor material selection differentiate supplier value capture.
- Regenerative Braking:Kinetic energy recovery during descent and landing reduces brake wear while topping battery reserves. This function requires bidirectional power converters qualified for aerospace thermal cycling profiles.
- Energy Storage Systems:Battery management electronics and thermal runaway containment structures dominate pack mass and cost. Cathode material processing concentration in China creates geopolitical exposure for OEMs.
- Electric Motors:Integrated motor-inverter designs concentrate margin pools as suppliers compete on specific power and torque density. Electromagnetic compatibility design talent scarcity constrains 540 VDC system development.
- Inverters:Silicon carbide power electronics replace silicon IGBTs in advanced architectures, compressing development cycles before fleet renewal deadlines. Tier-1 suppliers in Germany and Japan qualify devices for 15-year service lives.
Electric Motors capture concentrated margins; Inverters show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's aerospace special economic zones around Toulouse and Bordeaux concentrate electric propulsion R&D through targeted tax credits for clean aviation demonstrators.
United States
FAA certification timelines for 540 VDC architectures and megawatt-class inverters drive supplier location decisions around Wichita and Seattle industrial clusters. The Inflation Reduction Act's clean energy manufacturing credits pull battery pack assembly toward the Southeast. Honeywell and GE Aerospace anchor integrated power distribution development in Phoenix and Cincinnati metro areas.
France
EASA SC-VTOL special conditions and EU AI Act algorithmic transparency rules shape avionics validation requirements for electric air taxi developers. The France 2030 investment plan channels public funds into hybrid-electric regional aircraft demonstrators. Safran's ENGINeUS motor family production concentrates in the Toulouse aerospace cluster with supplier spillover into Bordeaux.
Germany
Bavarian and Baden-Württemberg industrial policy prioritizes silicon carbide semiconductor qualification for aerospace thermal cycling profiles. The national aerospace research program funds fuel cell-battery hybrid architectures for 19-seat aircraft. Munich and Stuttgart host Tier-1 power electronics suppliers racing to meet 2030 fleet renewal deadlines.
United Kingdom
UK Research and Innovation's Future Flight Challenge subsidizes electric propulsion integration for regional connectivity schemes. The Civil Aviation Authority's evolving VTOL certification framework attracts urban air mobility developers to London and Bristol. Southwest England clusters battery management system specialists serving Scandinavian power-by-the-hour contracts.
India
The UDAN regional connectivity scheme subsidizes short-haul routes that lower certification barriers for sub-megawatt electric turboprops. Bureau of Civil Aviation Safety standards for lithium-ion thermal runaway containment are adapting from FAA Part 33 precedents. Bangalore and Hyderabad concentrate avionics software talent for autonomous flight control systems facing EU AI Act compliance requirements.
Global Aircraft Electrification Market Competitive Landscape
United States producers anchor one tier; French and German specialists hold integrated motor-inverter capabilities. The vendor base splits between consolidated aerospace conglomerates with actuator heritage and emerging power electronics firms from automotive and rail sectors. Three archetypes dominate: legacy avionics integrators, wide-bandgap semiconductor suppliers, and fuel cell system developers. Competitive moves center on strategic partnerships for certification bundling and backward integration into cathode material processing.
Within the legacy avionics tier, Honeywell International Inc. and GE Aerospace exemplify consolidated players leveraging turbofan inverter expertise for megawatt-class transitions. Safran occupies a position bridging European supply chain anchoring with integrated electric motor families. These three conglomerates represent distinct geographic anchoring strategies—American dual-coast positioning, French southwestern cluster concentration, and transatlantic certification arbitrage.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran |
| GE Aerospace |
| Thales Group |
| BAE Systems |
| RTX Corporation |
| AMETEK Inc. |
| Astronics Corporation |
| Crane Aerospace & Electronics |
| Others |
Supply & Pricing Matrix
Captive cathode material processing in China anchors battery pack OEM cost positions while compressing margin pools for European and North American integrators facing EU Green Deal emissions disclosure requirements. Power-by-the-hour contracting transfers degradation risk downstream, restructuring how regional carriers capitalize electric propulsion assets.
Pricing Analysis
Short-lead-time premiums for silicon carbide MOSFET modules qualified to aerospace thermal cycling profiles separate Tier-1 suppliers from spot-market semiconductor traders. Pricing stratifies across certification-grade tiers, with EASA SC-VTOL and FAA Part 33 dual-certified components commanding substantial premiums over single-jurisdiction equivalents. Cost compression in battery management electronics runs through cathode material supply constraints, not manufacturing scale. Scandinavian regional carriers exhibit highest price sensitivity due to power-by-the-hour contract structures that unbundle capital from operational expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle megawatt-class inverter demand from France-Germany-UK demonstrator programs, while distributor networks serve aftermarket maintenance, repair, and overhaul segments. Cathode material processing concentrates in China, silicon carbide wafer fabrication in Germany and Japan, and final battery pack assembly in the United States and South Korea. Raw material dependencies span lithium carbonate, cobalt sulfate, and high-purity silicon carbide substrates. Single-source vulnerability in wide-bandgap semiconductor qualification creates procurement risk as 2030 fleet renewal deadlines approach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated motor-inverter capabilities as certification complexity under EASA SC-VTOL and EU AI Act transparency rules forces weaker component suppliers toward acquisition or exit. Talent scarcity in 540 VDC electromagnetic compatibility design accelerates this filtering mechanism.
For Market Incumbents: Lock in captive cathode material supply through backward integration or long-term offtake agreements with Chinese processors to defend against geopolitical tariff exposure. Consolidate electromagnetic compatibility design talent from automotive and rail sectors before 2030 qualification deadlines compress development cycles further. Priority lever rests on certification bundling partnerships that dual-track FAA Part 33 and EASA SC-VTOL submissions. For New Entrants and Emerging Players: India's UDAN regional connectivity scheme offers the most penetrable entry point for sub-megawatt electric turboprop integrators facing lower certification barriers than European or North American markets. Fuel cell-battery hybrid architectures for 19-seat aircraft represent adjacent white space where French-German government R&D funding has pre-validated technical feasibility. Go-to-market angle should emphasize power-by-the-hour contract structures that transfer operational risk from capital-constrained regional carriers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to consolidated aerospace conglomerates seeking integrated motor-inverter capabilities, not IPO windows given certification timeline uncertainty. Long-term viability favors suppliers with demonstrated silicon carbide qualification to aerospace thermal cycling profiles and established relationships with France-Germany-UK government demonstrator programs. Signal to watch: EASA-FAA convergence or divergence on thermal runaway containment standards under Part 33 and SC-VTOL frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Qualification Partnership | Tier-1 suppliers in Germany and Japan secure 15-year service life certifications for 540 VDC aerospace applications. |
| Cathode Material Backward Integration | Battery pack OEMs reduce China supply concentration exposure through captive lithium carbonate processing capacity. |
| Dual-Certification Bundling | Avionics developers compress validation timelines by parallel-tracking EASA SC-VTOL and FAA Part 33 submissions. |
| Power-by-the-Hour Contract Expansion | System integrators capture Scandinavian and Pacific Northwest regional carrier demand through operational expenditure structures. |
| Electromagnetic Compatibility Talent Acquisition | Motor-inverter specialists recruit from automotive and rail sectors to address 540 VDC design scarcity constraints. |
Research Methodology
Document review covered EASA certification filings, FAA Part 33 and SC-VTOL docket records, EU Green Deal Fit for 55 regulatory impact assessments, and SEC 10-K disclosures from listed aerospace suppliers, complemented by interviews with electric propulsion program directors, battery management system engineers, airline fleet procurement managers, and vertiport infrastructure planners. Secondary validation drew from customs trade data on lithium-ion cell imports, national aerospace research program funding announcements, and silicon carbide semiconductor production capacity reports. Bottom-up segment sizing triangulated against top-down market value estimates from OEM announced order backlogs and demonstrator program budgets.
Historical certification timeline data cross-referenced against expert panel input on 540 VDC architecture qualification trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include power source technology, aircraft type certification pathway, application system redundancy tier, and voltage class architecture. CAGRs were derived from installed base replacement curves tied to EU Green Deal fleet renewal deadlines and regional carrier procurement cycle analysis. Forecast inputs incorporated silicon carbide device yield learning curves and cathode material price elasticity assumptions.
Revisions become necessary when EASA-FAA regulatory divergence on thermal runaway containment intensifies, China export restrictions on cathode materials materialize, or silicon carbide foundry capacity expansion lags aircraft OEM demand. Forecasts reflect assumptions on government R&D funding continuity for France-Germany-UK demonstrator programs and power-by-the-hour contract adoption rates among regional carriers. Periodic stress-testing of base assumptions against actual certification timeline realization and battery degradation performance in commercial service is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aviation High Speed Motor Market