
 Aircraft Wheel Bead Breakers Market | 2026-2036
Aircraft Wheel Bead Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Wheel Bead Breakers Market Analytics
Commercial airline maintenance, repair, and overhaul operations is repositioning procurement priorities toward faster tire changeover equipment as narrow-body fleet utilization rates climb. Meyer Hydraulics leverages its hydraulic product specialization to anchor supply relationships with European MRO networks. Tronair competes through extensive channel control across North American airport service equipment distribution. Columbus Jack sustains manufacturing scale advantages in heavy-duty stationary systems for military and cargo operators.
Aircraft wheel bead breakers are mechanical or powered devices designed to break the seal between a tire bead and wheel rim flange, typically generating radial or lateral force in the 5,000 to 15,000-pound range depending on aircraft class, enabling safe demounting of tubeless and bias-ply tires during maintenance cycles. Hydraulic variants dominate installed base volume due to force reliability and compatibility with existing ground support equipment infrastructure, though automated technology segments are gaining fastest as hangars integrate programmable bead-breaking sequences into connected maintenance workflows. Manual systems retain margin pools in emerging aviation markets and remote airfields where capital constraints and intermittent use patterns limit powered equipment investment.
FAA airworthiness standards, EASA continuing airworthiness requirements, and ISO 9001 quality management frameworks collectively mandate documented tire maintenance traceability, compelling equipment suppliers to embed digital logging capabilities and calibration certification protocols. The EU AI Act and emerging machine-learning equipment classifications in Europe are beginning to shape automated system validation requirements for predictive maintenance integration. Stakeholders must monitor how regulatory divergence between FAA and EASA digital equipment standards reshapes product development roadmaps and certification investment thresholds.
Market Dynamics
Commercial aviation maintenance facilities face mounting pressure to compress tire changeover cycles as narrow-body fleet utilization intensifies and regulatory documentation requirements tighten under FAA and EASA mandates.
Growth Catalysts
- Aging Fleet Demographics:MRO networks serving Boeing 737 and Airbus A320 families require higher-frequency tire servicing as aircraft accumulate flight hours, expanding installed base demand for force-calibrated bead-breaking equipment.
- ISO 9001 Quality Mandates:Certification frameworks now require documented calibration histories and traceable maintenance logs, compelling hangar operators to upgrade from unlogged manual systems to digitally equipped hydraulic units.
- Hub Concentration in China:COMAC assembly lines and expanding domestic MRO infrastructure around Shanghai and Tianjin are generating procurement volume for both OEM-integrated and aftermarket wheel service equipment.
Market Restraints
- Hydraulic Fluid Cost Volatility:Specialized aviation-grade hydraulic fluids face petrochemical feedstock price swings, compressing margin predictability for equipment operators maintaining large installed fleets.
- Supply Concentration Risk:Precision force sensors and programmable logic controllers for automated systems concentrate among German and Japanese component suppliers, exposing lead time vulnerabilities.
- Manual System Substitution:Emerging aviation markets and remote airfields retain capital-efficient manual bead breakers for intermittent use, limiting powered equipment penetration in price-sensitive segments.
Strategic Opportunities
- Underpenetrated Southeast Asian MRO:Vietnam, Indonesia, and the Philippines lack dedicated wide-body tire service infrastructure, creating first-mover positioning for automated equipment providers establishing regional distribution.
- Predictive Maintenance Convergence:Integration of force sensors with machine-learning diagnostics enables real-time bead-seal integrity monitoring, opening recurring software revenue streams alongside hardware sales.
- EASA Digital Equipment Standards:Emerging validation requirements for connected maintenance equipment create certification barriers that favor established suppliers with regulatory affairs capabilities.
Industry Challenges
- Calibration Technician Scarcity:FAA and EASA mandate documented force calibration at prescribed intervals, yet certified metrology specialists remain concentrated in established aviation hubs, creating service bottlenecks.
- Legacy GSE Integration Complexity:Automated bead breakers must interface with existing hydraulic power carts and nitrogen service systems, requiring custom protocol adaptation that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Wheel Bead Breakers Market |
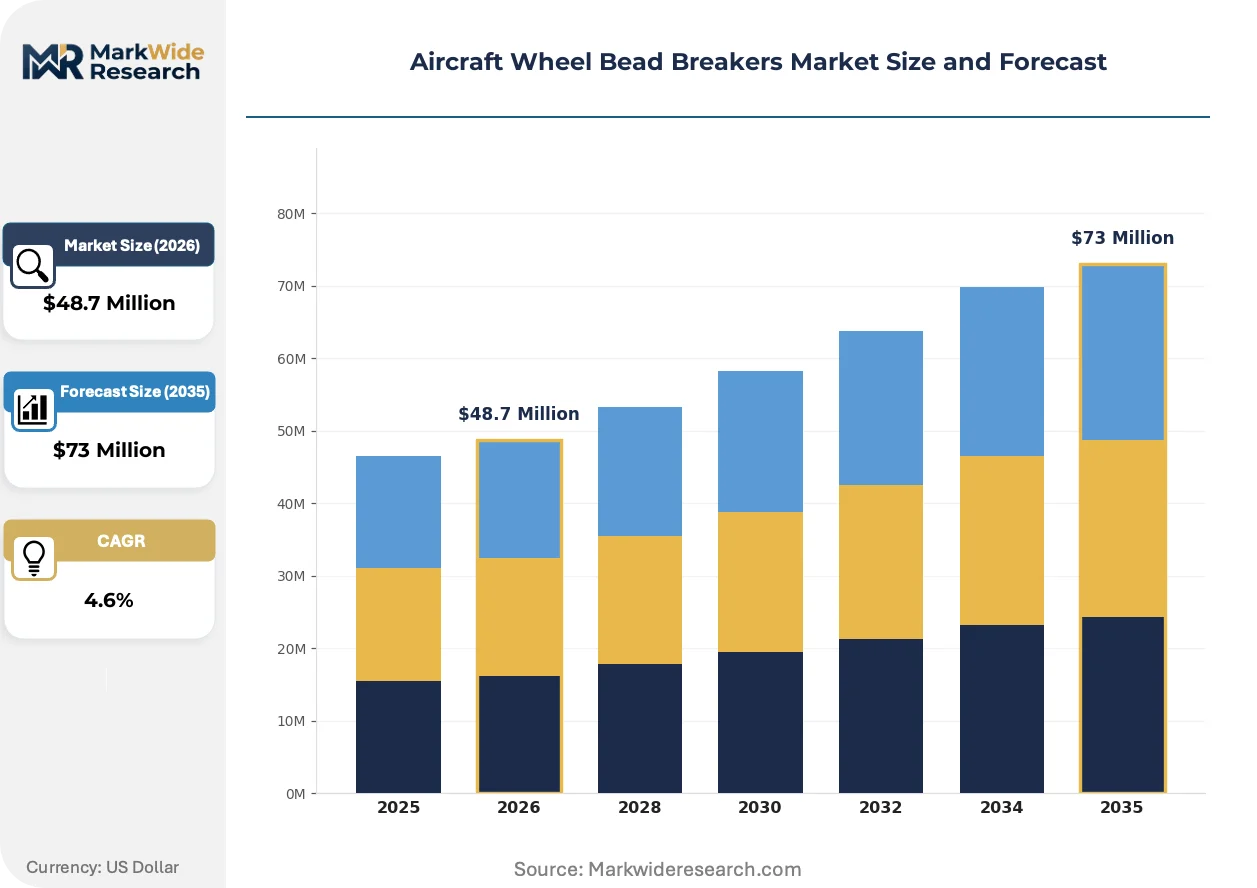
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $73 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Hydraulic, Pneumatic, Electric End User: Aerospace Manufacturers, Maintenance Facilities, Service Providers, Airlines Deployment: On-Site, Workshop-Based, Mobile Unit, Stationary Technology: Mechanical, Automated, Digital, Hybrid |
| Companies Covered | Meyer Hydraulics, Columbus Jack, Boeing, Tronair, Allied International, Bauer, U.S. Industrial Tool, AME International, Tolin Design Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Wheel Bead Breakers Market Evolving Landscape
Equipment architecture is fragmenting into interoperable subsystems as hangar operators demand flexible configurations that adapt to mixed aircraft fleets and evolving regulatory data requirements.
Programmable force control systems are modularizing bead-breaking operations into discrete, repeatable sequences that MRO facilities can reconfigure across narrow-body, regional jet, and cargo aircraft wheel formats without hardware swap-outs. Tier-one maintenance providers in Germany and the United States are adopting these units fastest, replacing fixed-parameter hydraulic systems that required manual adjustment between aircraft classes. This modularity is compressing technician training curves and reducing equipment redundancy across multi-type hangars.
EASA continuing airworthiness regulations now explicitly reference digital maintenance record integrity, compelling equipment suppliers to embed tamper-evident data logging and cloud-synced calibration certificates. The regulatory consequence is a bifurcation between connected units qualifying for airline MRO contracts and unlogged systems relegated to general aviation and remote field operations. European maintenance networks are responding fastest, specifying programmable bead breakers with integrated audit trails in procurement tenders.
Airline procurement departments are unbundling equipment purchase from lifecycle service contracts, negotiating separate agreements for calibration, software updates, and spare parts. This behavior is disrupting traditional bundled distribution through airport service equipment dealers, with direct manufacturer relationships capturing growing share among large MRO chains. The shift is most visible in the United States, where consolidated airline maintenance subsidiaries wield sufficient volume to justify dedicated supplier account structures bypassing regional distributors.
Aircraft Wheel Bead Breakers Market Segmentation
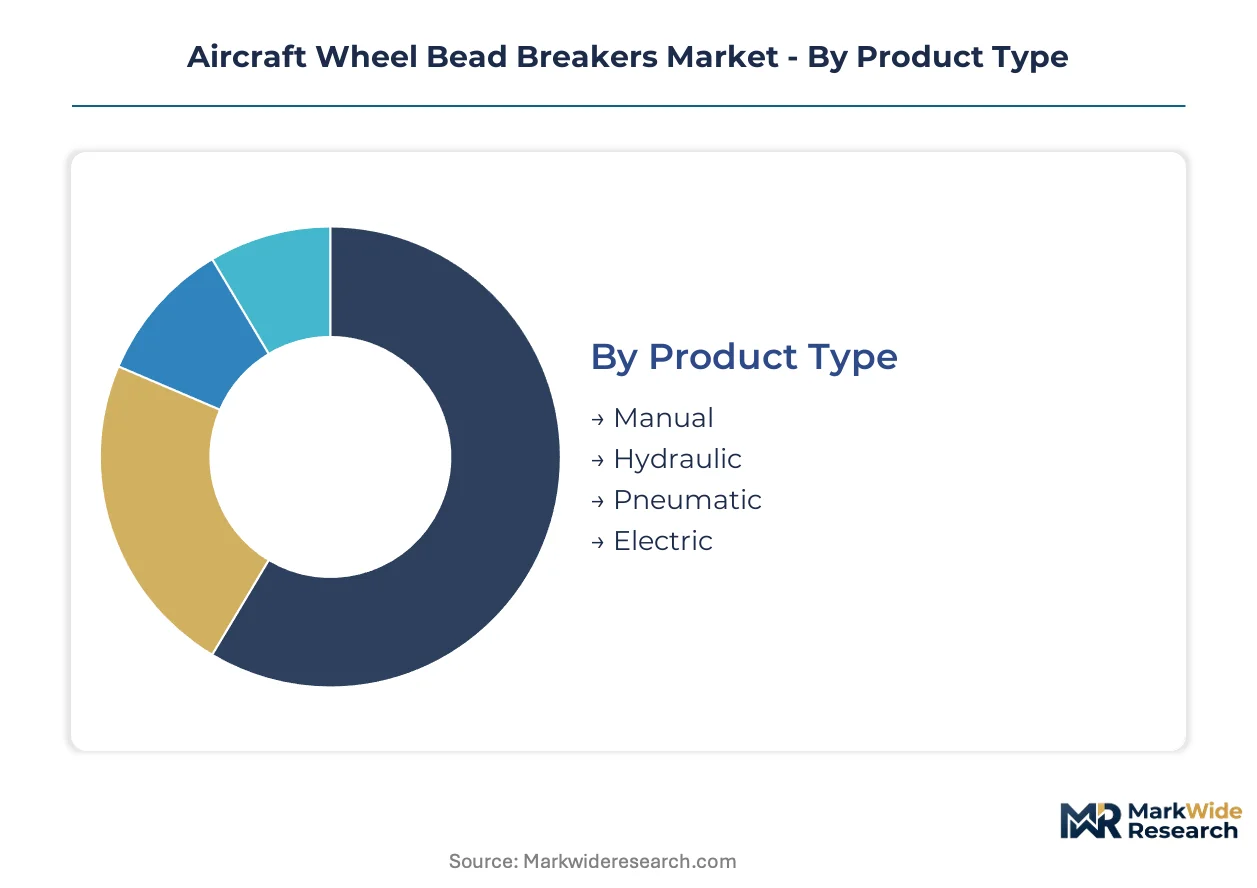
Segmentation in the aircraft wheel bead breaker market reveals how procurement priorities diverge across operational contexts. Equipment specifications, deployment models, and technology tiers each create distinct competitive arenas with different margin structures and customer loyalty patterns.
Product Type:
Supply concentration in hydraulic component manufacturing anchors procurement decisions for force-intensive applications, while electric and pneumatic alternatives fragment across specialized use cases.
- Manual:Lever-operated mechanical units generate radial force through screw or cam mechanisms without external power. Demand concentrates in remote airfields across Indonesia, the Philippines, and sub-Saharan Africa where capital constraints and intermittent maintenance schedules limit powered equipment investment.
- Hydraulic:External power cart-driven systems deliver calibrated force from 5,000 to 15,000 pounds through piston or wedge mechanisms. MRO facilities in Germany and the United States anchor procurement volume for these units as FAA and EASA documentation mandates push hangar operators toward force-traceable equipment with embedded pressure sensors and calibration logging.
- Pneumatic:Compressed-air systems integrate with existing airport infrastructure for lighter aircraft classes. Regional operators in Brazil and Mexico favor these units for compatibility with nitrogen service carts already deployed for tire inflation.
- Electric:Servo-motor driven units with programmable force curves are gaining specification in greenfield MRO facilities. Chinese COMAC assembly lines and Shanghai-area maintenance hubs are piloting these systems for integration with connected factory architectures.
Hydraulic units absorb the bulk of installed capacity; electric systems are expanding most quickly in digitally integrated hangar environments.
End User:
Customer type determines contract structure, with consolidated airline maintenance subsidiaries extracting volume pricing while fragmented service providers prioritize equipment mobility.
- Aerospace Manufacturers:OEM assembly line procurement emphasizes throughput consistency and integration with production scheduling systems. Boeing and Airbus final assembly facilities in Washington State and Toulouse specify automated units with programmable sequences for mixed aircraft families.
- Maintenance Facilities:Independent MRO networks face compressed turnaround windows as narrow-body fleet utilization intensifies. Lufthansa Technik and ST Engineering facilities prioritize hydraulic units with rapid reconfiguration between wheel formats.
- Service Providers:Third-party ground handlers at congested airports require mobile deployment flexibility. Swissport and dnata operations at Heathrow and Dubai International favor trailer-mounted systems with rapid repositioning capability.
- Airlines:In-house maintenance subsidiaries of major carriers leverage fleet scale for direct manufacturer relationships. American Airlines and Delta TechOps procurement departments are unbundling equipment purchase from lifecycle service contracts, negotiating separate calibration and software update agreements.
Maintenance facilities command the largest equipment installed base; airline in-house operations are gaining procurement sophistication fastest.
Deployment:
Deployment configuration directly shapes equipment architecture, with stationary systems optimizing force precision and mobile units trading calibration stability for operational flexibility.
- On-Site:Ramp-adjacent installations at major hubs enable immediate tire service without aircraft repositioning. Frankfurt and Atlanta airport operators specify weather-hardened hydraulic units with rapid-connect power cart interfaces.
- Workshop-Based:Controlled-environment hangar installations support precision overhaul operations. These configurations dominate military and cargo operator procurement, with Columbus Jack and similar suppliers anchoring relationships through heavy-duty stationary system specialization.
- Mobile Unit:Trailer or vehicle-mounted systems serve dispersed operations and emergency response. Australian outback stations and Canadian Arctic resupply routes specify these configurations for seasonal accessibility constraints.
- Stationary:Fixed-installation systems with dedicated power and calibration infrastructure maximize throughput for high-volume operations. These units concentrate at major MRO hubs in Singapore, Amsterdam, and Dallas-Fort Worth where tire changeover volume justifies permanent allocation.
Workshop-based deployment holds the deepest installed base penetration; mobile configurations are climbing fastest as point-to-point route networks expand into secondary airports.
Technology:
Technology tier selection increasingly bifurcates between connected systems qualifying for airline MRO contracts and unlogged alternatives relegated to general aviation.
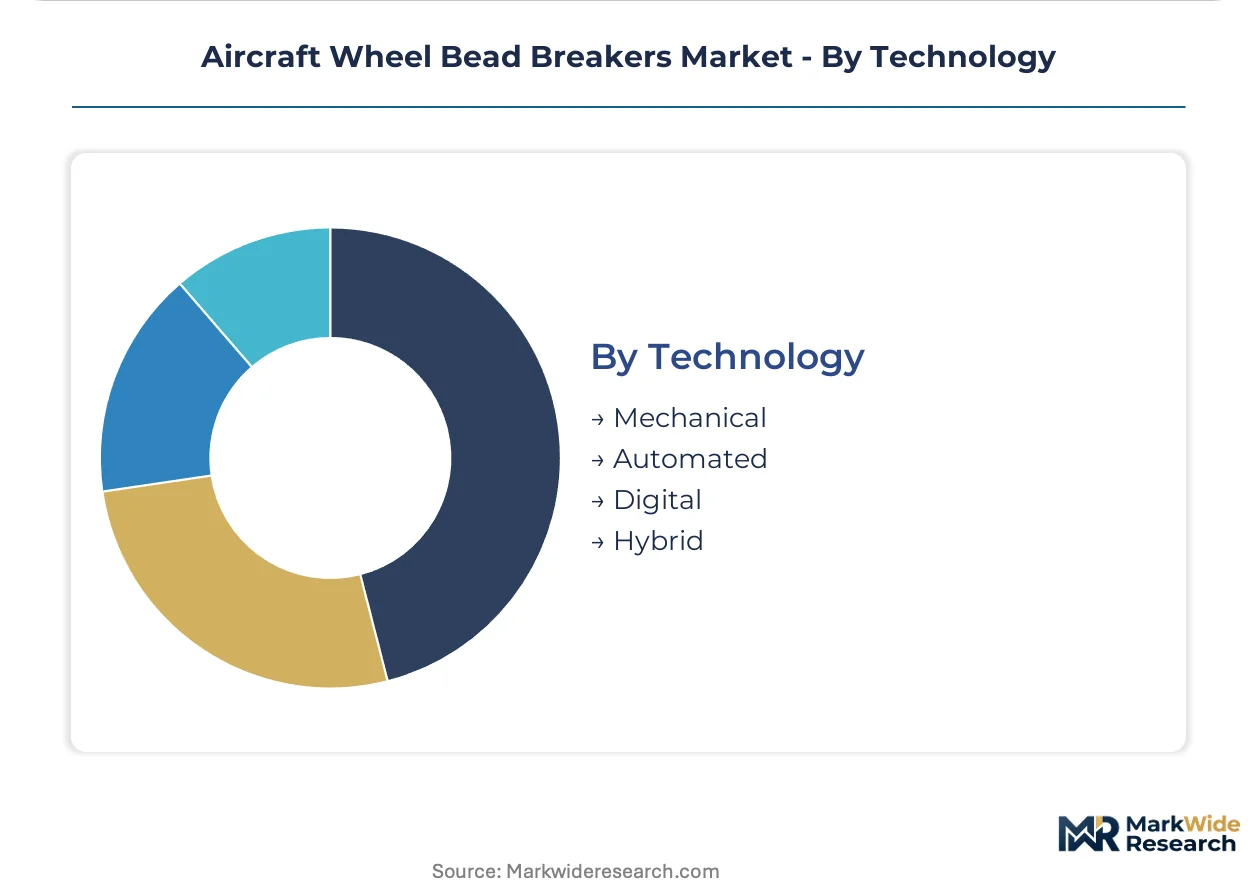
- Mechanical:Purely mechanical force multiplication without electronic control or data capture. These systems retain position in price-sensitive segments and regulatory environments with limited documentation requirements.
- Automated:Programmable logic controllers manage force application through stored sequences for specific aircraft wheel formats. EASA continuing airworthiness regulations now explicitly reference digital maintenance record integrity, compelling European maintenance networks to specify these units in procurement tenders.
- Digital:Cloud-connected systems with tamper-evident logging, remote calibration monitoring, and predictive maintenance algorithms. The EU AI Act is beginning to shape validation requirements for machine-learning equipment classifications in this segment.
- Hybrid:Combinations of hydraulic force generation with electronic control and data capture. These systems balance force reliability with regulatory compliance, capturing specification from MRO facilities transitioning from legacy hydraulic infrastructure.
Mechanical technology retains volume in emerging markets; digital systems are gaining specification fastest where EASA and FAA documentation mandates apply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while fleet expansion and MRO network growth in China and Southeast Asia are reshaping demand geography. Regulatory divergence between FAA and EASA digital equipment standards is fragmenting procurement specifications across major aviation hubs.
United States
FAA airworthiness directives mandate documented tire maintenance traceability, compelling hangar operators toward digitally equipped hydraulic units. Consolidated airline maintenance subsidiaries at Dallas-Fort Worth and Atlanta hubs wield procurement volume to negotiate direct manufacturer relationships bypassing regional distributors. American Airlines and Delta TechOps operations anchor specification trends for programmable bead-breaking sequences.
Germany
EASA continuing airworthiness regulations explicitly reference digital maintenance record integrity, accelerating automated system adoption. Lufthansa Technik facilities around Hamburg and Frankfurt specify connected units with tamper-evident logging and cloud-synced calibration certificates. Meyer Hydraulics anchors supply relationships with European MRO networks through hydraulic specialization.
China
COMAC assembly lines and expanding domestic MRO infrastructure around Shanghai and Tianjin generate procurement volume for OEM-integrated and aftermarket equipment. The country's aviation regulator mandates alignment with international airworthiness standards for export-certified aircraft. Greenfield facilities pilot electric servo-motor units for integration with connected factory architectures.
Singapore
ST Engineering and third-party MRO clusters at Changi anchor Southeast Asian tire service capacity. The Civil Aviation Authority of Singapore enforces calibration documentation protocols matching EASA stringency. Workshop-based stationary systems dominate procurement for high-volume wide-body overhaul operations.
United Arab Emirates
Emirates and Etihad maintenance subsidiaries at Dubai International and Abu Dhabi drive demand for mobile trailer-mounted systems with rapid repositioning capability. The General Civil Aviation Authority aligns equipment certification with ICAO standards. Dnata ground handling operations favor configurations compatible with congested ramp environments.
Aircraft Wheel Bead Breakers Market Competitive Landscape
Top-tier vendors anchor airline MRO and OEM assembly line procurement, while mid-tier specialists serve regional maintenance networks and military operators. The vendor base stratifies across hydraulic force specialists, automated system integrators, and diversified ground support equipment manufacturers. Three archetypes dominate: European precision engineering houses, North American full-line GSE providers, and diversified aerospace conglomerates with captive maintenance equipment units. Competitive moves concentrate on strategic partnerships for sensor integration and geographic expansion through regional distribution agreements.
Within the hydraulic specialization tier, Meyer Hydraulics and Columbus Jack exemplify contrasting scale positions—Meyer anchors European MRO network relationships through force-calibrated product lines, while Columbus Jack occupies heavy-duty stationary system manufacturing for military and cargo operator procurement. Tronair represents the North American full-line GSE provider archetype, competing through channel control across airport service equipment distribution networks. These three companies illustrate how competitive positioning fragments across technical specialization breadth, geographic anchoring, and customer segment focus.
| Leading Market Players |
|---|
| Meyer Hydraulics |
| Columbus Jack |
| Boeing |
| Tronair |
| Allied International |
| Bauer |
| U.S. Industrial Tool |
| AME International |
| Tolin Design Inc. |
| Others |
Value Network & Pricing Analysis
Captive hydraulic component production in Germany and the United States anchors premium pricing power for force-calibrated bead breakers, while outsourced precision sensor sourcing from Japanese and German suppliers compresses margin flexibility for automated system tiers. This integration divergence separates manufacturers commanding specification premiums from assemblers exposed to input cost volatility.
Pricing Analysis
Short-lead-time premiums for force sensors and programmable logic controllers compress as spot inventory accumulates at regional distributors serving North American MRO hubs. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified automated units with tamper-evident logging from unlogged hydraulic systems and manual lever-operated alternatives. Pricing pressure stems from petrochemical feedstock volatility affecting aviation-grade hydraulic fluids, with emerging aviation markets in Indonesia and the Philippines exhibiting highest price sensitivity due to capital constraints and intermittent utilization patterns.
Supply Chain Analysis
Precision force sensor supply rests on German and Japanese specialty component producers, while hydraulic piston manufacturing concentrates in Germany and the United States. Raw material dependencies include aviation-grade hydraulic fluids, high-strength alloy steels for force-bearing components, and industrial-grade programmable logic controllers. Single-source vulnerability in sensor calibration equipment exposes lead time risks for automated system assemblers. Distribution runs through airport service equipment dealers and direct manufacturer relationships with consolidated airline maintenance subsidiaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft wheel bead breaker market sits in a technology-transition phase as programmable automated systems displace fixed-parameter hydraulic units across EASA-regulated European MRO networks.
For Market Incumbents: Acquire precision sensor calibration capabilities to secure supply chain autonomy against Japanese and German component concentration. Consolidate channel control through dedicated account structures with American Airlines and Delta TechOps procurement departments as these airline subsidiaries bypass regional distributors. Invest in EASA digital equipment certification to erect regulatory barriers against emerging automated system competitors. For New Entrants and Emerging Players: Technology-first positioning in electric servo-motor bead breakers opens specification opportunities at COMAC assembly lines and Shanghai-area greenfield MRO facilities piloting connected factory architectures. Target Vietnam, Indonesia, and the Philippines where dedicated wide-body tire service infrastructure remains underdeveloped. Pursue regional distribution partnerships with established ground support equipment dealers rather than direct sales investment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified aerospace conglomerates seeking captive maintenance equipment units. Long-term viability favors suppliers with regulatory affairs capabilities navigating diverging FAA and EASA digital equipment standards. Watch EASA validation requirements for machine-learning equipment classifications as the inflection signal for predictive maintenance integration premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Force sensor collaboration with German metrology specialists secures calibration traceability for EASA compliance. |
| Regional Distribution Expansion | Vietnam and Indonesia dealership networks capture first-mover positioning in underpenetrated Southeast Asian MRO. |
| Digital Certification Investment | EASA tamper-evident logging validation qualifies equipment for airline procurement tenders specifying audit trails. |
| Software-Enabled Service Contract | Predictive maintenance algorithms generate recurring revenue alongside hardware sales at Lufthansa Technik facilities. |
| Backward Integration into Hydraulics | In-house piston manufacturing insulates margin from petrochemical feedstock price swings affecting aviation fluid costs. |
Research Methodology
Multi-period observation of fleet utilization rates, regulatory directive issuance patterns, and MRO procurement contract structures anchored the trend analysis, supplemented by interviews with maintenance directors at European and North American airline subsidiaries, aftermarket service heads at ground support equipment distributors, hydraulic system engineers at component manufacturers, and regulatory affairs specialists at EASA and FAA. Secondary validation drew from FAA airworthiness directive databases, EASA continuing airworthiness regulatory filings, ISO 9001 certification registries, and customs trade data for aviation ground support equipment. Bottom-up equipment shipment tracking and top-down MRO spending estimates were triangulated to cross-verify volume assumptions.
Input-output matrices modeled relationships between narrow-body fleet flight hours, tire changeover frequency, and equipment replacement cycles across the projection horizon. Segmentation dimensions included product type, end-user category, deployment configuration, and technology tier. CAGRs were derived from equipment installed base growth adjusted for replacement demand and technology substitution effects. Forecast inputs incorporated COMAC production ramp schedules and EASA digital equipment standard implementation timelines.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions affecting German and Japanese component flows, abrupt shifts in aviation fuel costs altering fleet utilization patterns, and regulatory harmonization between FAA and EASA digital equipment standards. Forecasts reflect documented assumptions about maintenance documentation mandate enforcement intensity and MRO hub expansion trajectories. A small set of named triggers warrants ongoing watch: EASA machine-learning equipment classification rulings, COMAC export certification alignment with international airworthiness standards, and hydraulic fluid petrochemical feedstock price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market