
 Aircraft Turboprop Propeller System Market | 2026-2036
Aircraft Turboprop Propeller System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Turboprop Propeller System Market Analysis
Poland is rewriting regional supply dynamics for turboprop propeller systems through expanded aerospace manufacturing clusters near Rzeszów. Hartzell Propeller Inc. leverages its Ohio-based foundry capacity to sustain North American aftermarket dominance. Hoffmann Propeller GmbH & Co. KG anchors European general aviation with specialized wood-composite blade expertise. MT-Propeller Entwicklung GmbH differentiates through five-blade designs that compete on noise reduction metrics.
An aircraft turboprop propeller system converts engine shaft power into thrust through aerodynamic blade action, typically operating at rotational speeds between 1,500 and 2,500 RPM with diameters spanning 2 to 4.5 meters depending on aircraft class. These systems serve as the critical thrust interface for turboprop engines used in regional commercial transport, military trainer platforms, and utility aircraft where jet efficiency proves uneconomical at lower altitudes and slower airspeeds. Composite propeller blades represent the fastest-expanding material category as manufacturers pursue weight reduction and corrosion resistance, though aluminum retains margin strength in the high-volume general aviation replacement segment. Variable-pitch mechanisms command premium positioning due to their integration complexity with engine control systems, while fixed-pitch configurations occupy the cost-sensitive training aircraft niche.
FAA airworthiness standards under Part 35 govern propeller structural integrity and fatigue testing protocols in the United States, directly shaping product development timelines and certification costs for manufacturers targeting North American operators. EASA certification requirements in Europe impose additional bird-strike and lightning-strike resilience benchmarks that filter market access for smaller suppliers lacking dedicated test infrastructure. Military procurement specifications from NATO member defense ministries further segment demand through unique hub retention and de-icing system mandates. Stakeholders must monitor evolving noise certification stringency from ICAO Chapter 14 provisions, as these standards will determine which blade architectures retain fleet eligibility across major operating regions.
Market Dynamics
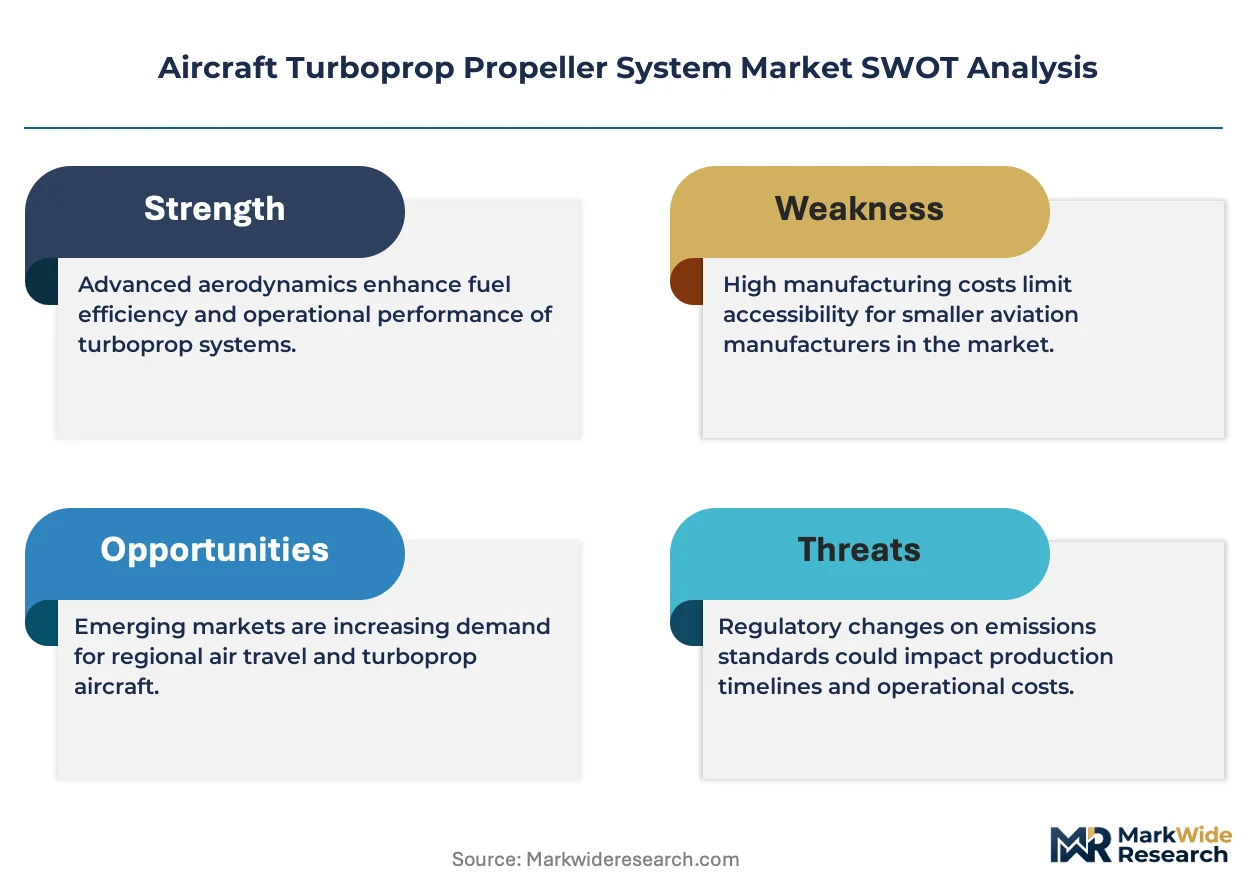
Composite blade manufacturing is collapsing traditional aluminum supply chains as regional carriers in Southeast Asia and Brazil's agricultural aviation sector demand corrosion-resistant, lighter-weight propeller systems for high-cycle operations.
Growth Catalysts
- FAA Part 35 fatigue testing protocols:Certification standards for propeller structural integrity are accelerating replacement cycles among North American regional operators upgrading aging fleets.
- Five-blade noise reduction architectures:Advanced blade count configurations are displacing three-blade designs in European general aviation where ICAO Chapter 14 compliance determines airport access.
- Brazil:Agricultural and executive aircraft operators are driving concentrated demand for variable-pitch systems in the world's largest turboprop general aviation market.
Market Restraints
- Carbon fiber prepreg input volatility:Composite blade manufacturers face margin compression from aerospace-grade material supply constraints concentrated in Japanese and German chemical suppliers.
- EASA bird-strike resilience mandates:European certification requirements filter market access for smaller suppliers lacking dedicated impact test infrastructure.
- Electric propulsion substitution threat:Battery-electric and hydrogen fuel cell propulsion systems are capturing early-stage urban air mobility investment that might otherwise flow to turboprop efficiency improvements.
Strategic Opportunities
- Poland's Rzeszów aerospace cluster:Expanded manufacturing infrastructure in Eastern Europe offers white-space capacity for suppliers seeking EU regulatory proximity without German labor costs.
- Military trainer platform convergence:NATO defense ministry specifications for hub retention and de-icing systems are creating dual-use technology pathways between commercial and defense procurement.
- Direct-to-operator digital distribution:Online parts catalog platforms are compressing traditional aftermarket distributor margins while enabling faster turnaround for AOG (aircraft on ground) situations.
Industry Challenges
- Propeller aerodynamics and composite layup engineering:Specialized talent scarcity in blade design and automated fiber placement is extending development timelines for new entrants.
- FAA-EASA certification divergence:Differing lightning-strike test protocols between US and European regulators force redundant validation campaigns that strain mid-cap manufacturer balance sheets.
- Legacy hydromechanical pitch control integration:Modern digital engine control systems require extensive adaptation to interface with existing turboprop fleets, complicating retrofit market penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Turboprop Propeller System Market |
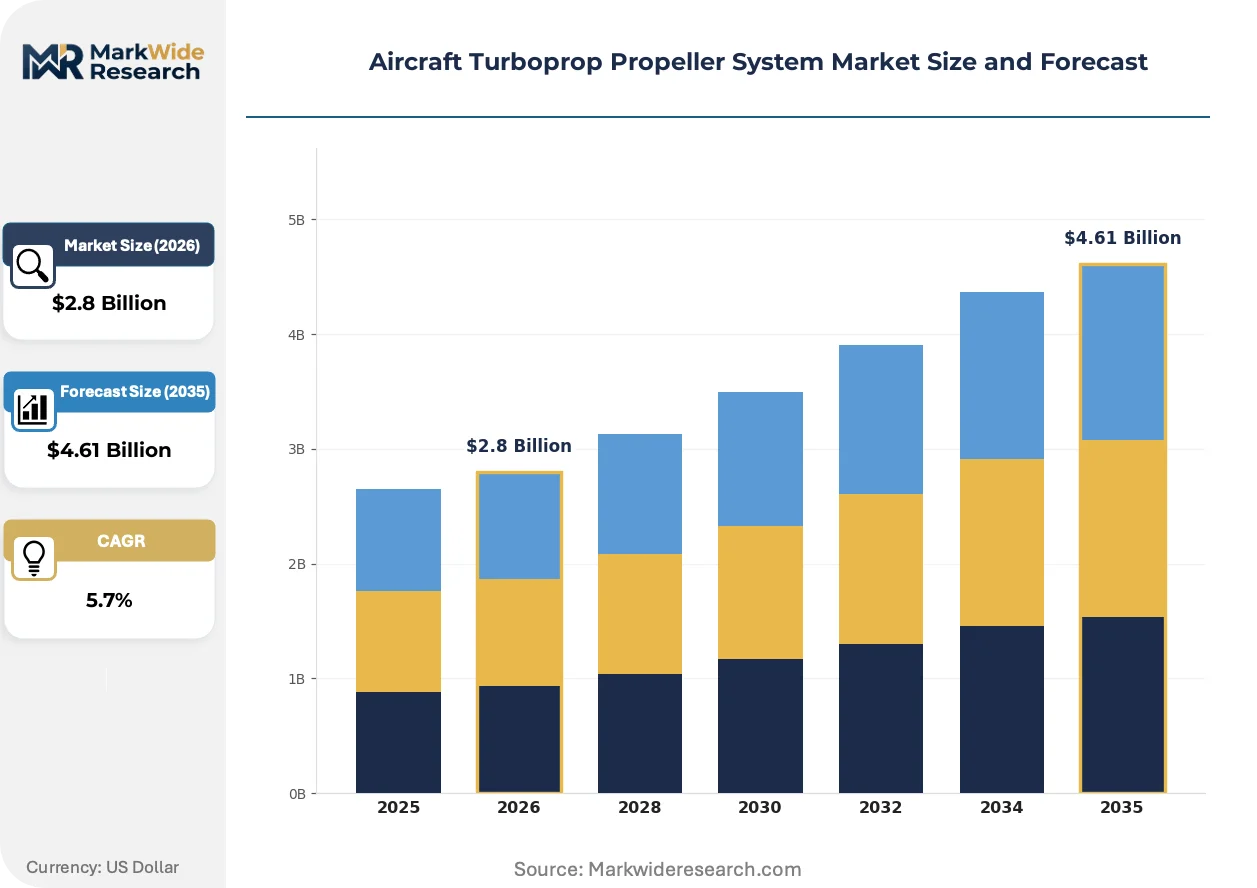
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propeller Type: Fixed-Pitch, Variable-Pitch, Constant-Speed, Feathering Material: Aluminum, Composite, Steel, Titanium Power Rating: 500 HP, 750 HP, 1000 HP, 1200 HP Application: General Aviation, Military Aviation, Commercial Aviation, Cargo Transport |
| Companies Covered | McCauley Propeller Systems, Hoffmann Propeller GmbH & Co. KG, Hartzell Propeller Inc., Aerosila JSC SPE, Ratier-Figeac, Dowty Propellers, Avia Propeller, s.r.o., DUC Helices Propellers, MT-Propeller Entwicklung GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Turboprop Propeller System Market Emerging Trajectories
Material science advances and regulatory noise stringency are compressing traditional propeller design cycles while digital manufacturing methods rewrite supply chain economics for blade production.
Continuous fiber thermoplastic composites are collapsing conventional autoclave curing timelines for propeller blade manufacturing. Regional carriers operating ATR and Dash 8 fleets are adopting these lighter, damage-tolerant blades to reduce fuel burn on short-haul sectors. The technology is collapsing the historical trade-off between blade durability and weight reduction that constrained aluminum designs.
ICAO Chapter 14 noise certification provisions are tightening operational eligibility thresholds for older blade architectures across EU member states. Airlines and lessors now prioritize five-blade and swept-tip designs that deliver 3-5 EPNdB reductions during takeoff and approach phases. European regional operators are accelerating pre-emptive fleet upgrades to avoid slot restrictions at noise-sensitive airports.
Operator purchasing patterns are fragmenting across lease-versus-own decisions for propeller life-limited parts. Large regional carriers are negotiating power-by-the-hour contracts that bundle blade overhaul with engine maintenance, while independent agricultural operators retain traditional transactional spares procurement. Brazil's crop-dusting sector exhibits the sharpest divergence, with cooperatives pooling inventory against individual owner-operators seeking immediate availability.
Aircraft Turboprop Propeller System Market Segmentation
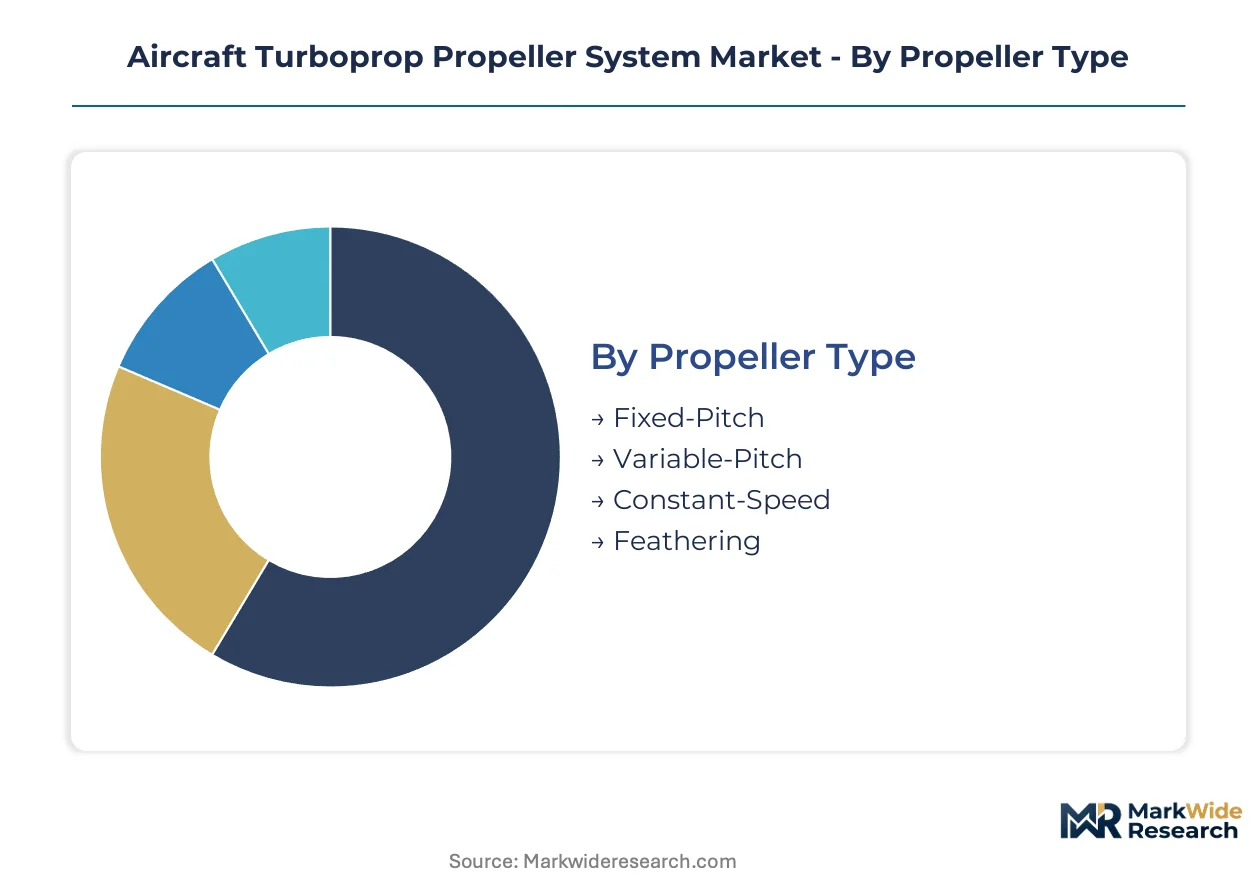
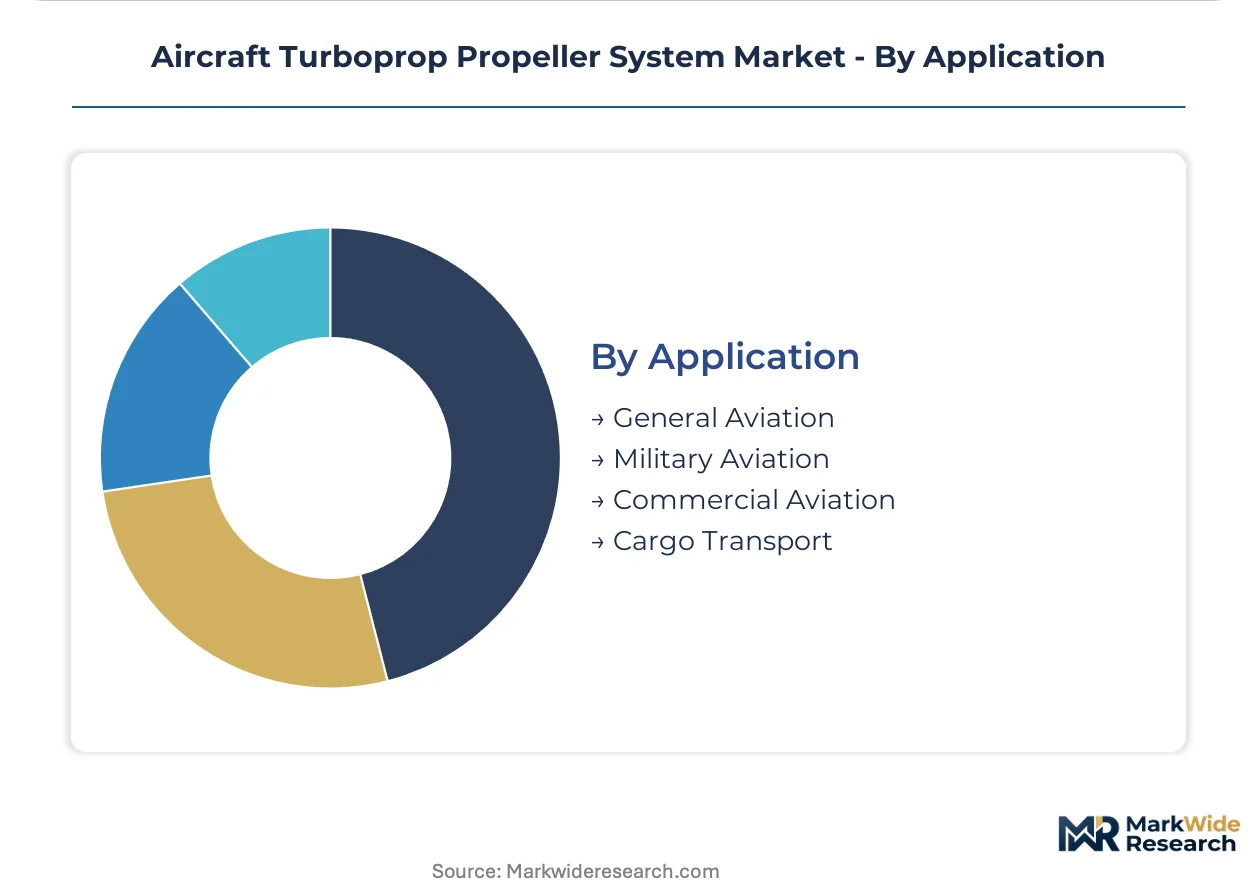
Propeller system segmentation reveals divergent aftermarket service intensities across configurations, with variable-pitch mechanisms demanding specialized overhaul infrastructure and fixed-pitch systems sustaining commoditized spare parts flows. Material and power rating distinctions further stratify procurement patterns between corrosion-sensitive agricultural operators and high-cycle regional carriers.
Propeller Type:
Aftermarket service intensity varies dramatically across mechanism architectures, with hydraulically actuated systems requiring dedicated MRO partnerships and mechanical designs supporting broader technician pools.
- Variable-Pitch:Hydraulically actuated blade angle adjustment enables optimal engine efficiency across flight phases. Demand concentrates among Brazil's agricultural aviation cooperatives where payload flexibility governs operational economics. FAA Part 35 certification complexity sustains premium pricing for hub and actuator assemblies.
- Fixed-Pitch:Single-angle blade geometry delivers mechanical simplicity and lower acquisition cost. Southeast Asian flight schools favor this configuration for ab-initio training where capital constraints outweigh performance optimization. Replacement cycles accelerate in high-dust environments lacking paved runways.
- Constant-Speed:Governor-controlled pitch maintenance preserves engine RPM across altitude changes. European general aviation operators prioritize this technology for IFR-capable aircraft requiring precise power management.
- Feathering:Emergency blade alignment parallel to airflow eliminates windmilling drag during engine failure. Military trainer platforms mandate this capability for multi-engine safety certification.
Variable-pitch configurations hold the largest share; momentum sits with feathering systems as defense procurement accelerates dual-engine platform adoption.
Material:
Cost tier stratification separates premium corrosion-resistant formulations from standard alloys, with procurement decisions tracking operating environment severity and regulatory pressure on structural inspection intervals.
- Composite:Carbon fiber and glass-reinforced polymers deliver 15-25% weight reduction versus metallic alternatives. Regional carriers operating ATR fleets in Southeast Asian coastal zones specify these blades for salt-air corrosion immunity. Continuous fiber thermoplastic processing is collapsing traditional autoclave lead times.
- Aluminum:Forged aluminum alloys retain dominance in high-volume general aviation replacement channels where unit economics favor standardization over performance optimization. Brazilian crop-dusting operators source aluminum blades through pooled cooperative procurement to minimize per-unit logistics costs.
- Steel:High-strength steel alloys serve niche applications requiring extreme impact resistance. Agricultural operators in Brazil's Cerrado region specify steel leading edges for debris tolerance during low-altitude spraying operations.
- Titanium:Aerospace-grade titanium delivers superior strength-to-weight ratios for high-performance military platforms. NATO defense ministries specify titanium hub components for trainer aircraft subject to repetitive high-G maneuvering.
Aluminum retains volume leadership; composite materials are climbing the fastest as fuel efficiency mandates and corrosion resistance requirements intensify.
Power Rating:
Application scale determines procurement channel structure, with high-horsepower systems flowing through airframe OEM bundling agreements and lower ratings supporting independent distributor networks.
- 1000 HP:Mid-range turboprop power band serves regional commercial transport and utility aircraft. ATR 42 and Dash 8-100 operators in Southeast Asia specify 1000 HP-class propellers for 30-50 seat sector economics. Lease agreements increasingly bundle propeller overhaul with engine maintenance contracts.
- 500 HP:Entry-level turboprop power supports single-engine training and light utility aircraft. Flight schools across Brazil's interior states favor this rating for fuel cost containment and simplified maintenance access.
- 750 HP:Intermediate power band bridges single-engine utility and light twin applications. European general aviation manufacturers specify 750 HP systems for six-seat executive transport platforms.
- 1200 HP:High-output configuration serves 70-seat regional aircraft and military transport variants. Polish aerospace clusters near Rzeszów are expanding capacity for 1200 HP blade manufacturing to capture EU regulatory proximity.
1000 HP systems hold the largest share; 1200 HP configurations are expanding most quickly as regional aircraft capacity requirements escalate.
Application:
Customer type fragmentation separates institutional procurement with long-term service contracts from transactional owner-operator purchasing with immediate availability requirements.
- Commercial Aviation:Scheduled regional airlines operating turboprop fleets prioritize total cost of ownership metrics including propeller life-limited part cycles. Southeast Asian carriers negotiate power-by-the-hour agreements that transfer overhaul risk to OEM service networks.
- General Aviation:Private and corporate operators in Brazil's agricultural and executive segments drive replacement demand through direct spares procurement. Individual owner-operators favor immediate availability over bundled service contracts.
- Military Aviation:Defense ministry specifications impose unique hub retention, de-icing, and ballistic tolerance requirements. NATO trainer platform convergence is creating dual-use technology pathways with commercial applications.
- Cargo Transport:Freight operators prioritize dispatch reliability and rapid turnaround over fuel optimization. Short-haul cargo feeders in Southeast Asian archipelagos specify robust blade designs for unimproved airfield operations.
Commercial aviation holds the largest share; military aviation is gaining share fastest as defense procurement accelerates fleet modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal's intermodal connectivity underwrites Brazil's role as the primary turboprop propeller demand hub for Latin American agricultural aviation, while Poland's Rzeszów-Jasionka airport corridor anchors Eastern European manufacturing expansion.
United States
FAA Part 35 fatigue testing mandates are accelerating replacement cycles among regional operators upgrading aging Dash 8 and ATR fleets. The Ohio-based foundry cluster near Dayton sustains North American aftermarket dominance through integrated blade casting and CNC machining capacity. Hartzell Propeller Inc. leverages this infrastructure to serve commuter airlines across the Great Lakes and Southeast corridors.
Brazil
Agricultural aviation cooperatives in Mato Grosso and Goiás are pooling procurement for variable-pitch systems to optimize payload flexibility during crop-dusting operations. ANVISA's parallel import regulations for aero-derivative components are compressing traditional distributor margins. São Paulo state's executive aircraft operators are driving concentrated demand for corrosion-resistant composite blades in high-humidity operating environments.
Poland
The Rzeszów aerospace cluster is expanding blade manufacturing capacity to capture EU regulatory proximity without German labor cost structures. EASA bird-strike resilience mandates are filtering market access for smaller suppliers lacking dedicated impact test infrastructure. Subcarpathian Voivodeship's technical universities are feeding specialized composite layup engineering talent into regional supply chains.
Germany
MT-Propeller Entwicklung GmbH's five-blade noise reduction architectures are displacing three-blade designs where ICAO Chapter 14 compliance determines airport access. The Bavarian manufacturing belt around Straubing anchors European general aviation with automated fiber placement capabilities. German chemical suppliers are constraining carbon fiber prepreg availability for competing blade manufacturers.
Japan
METI's aerospace technology roadmap is prioritizing continuous fiber thermoplastic composite processing for regional aircraft applications. Nagoya's Chubu Centrair corridor hosts specialized MRO infrastructure for ATR fleet operators across Southeast Asian archipelagos. Japanese carbon fiber producers are concentrating aerospace-grade material supply, creating input volatility for downstream blade manufacturers.
Aircraft Turboprop Propeller System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in blade manufacturing and hub assembly. The vendor base stratifies between full-system providers with FAA-EASA dual certification and regional fabricators serving single-market agricultural operators. Two strategic archetypes dominate: foundry-integrated manufacturers with captive aluminum casting capacity, and composite-focused specialists leveraging automated fiber placement. Competitive moves concentrate on geographic expansion into Poland's Rzeszów corridor and technology licensing agreements for thermoplastic blade processing.
Among German GmbH-structured specialists, Hoffmann Propeller GmbH & Co. KG and MT-Propeller Entwicklung GmbH occupy positions within the European general aviation tier, with the former exemplifying wood-composite blade expertise and the latter representing multi-blade noise reduction architectures. Hartzell Propeller Inc. anchors the North American aftermarket through its Ohio-based manufacturing footprint. These three entities illustrate the geographic bifurcation between EU regulatory-proximate specialists and US-scale aftermarket operators.
| Leading Market Players |
|---|
| McCauley Propeller Systems |
| Hoffmann Propeller GmbH & Co. KG |
| Hartzell Propeller Inc. |
| Aerosila JSC SPE |
| Ratier-Figeac |
| Dowty Propellers |
| Avia Propeller, s.r.o. |
| DUC Helices Propellers |
| MT-Propeller Entwicklung GmbH |
| Others |
Supply Flow & Price Mechanics
Carbon fiber prepreg supply concentration in Japanese and German chemical suppliers determines both the tiered cost structure across composite versus aluminum blade categories and the geographic clustering of manufacturing capacity near raw material entry points. FAA-EASA certification divergence amplifies pricing spreads by forcing redundant validation campaigns that smaller suppliers cannot absorb.
Pricing Analysis
Volume-discount tiering separates large regional carriers negotiating power-by-the-hour bundled contracts from individual agricultural operators purchasing transactional spares. Three-tier pricing structure across premium certified, standard aftermarket, and economy replacement levels tracks certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as Brazilian cooperatives pool procurement to minimize per-unit logistics costs. Agricultural owner-operators exhibit highest price sensitivity, while NATO defense ministries demonstrate lowest sensitivity due to unique hub retention and de-icing mandates.
Supply Chain Analysis
Extended payment terms from Japanese carbon fiber producers to downstream blade manufacturers are compressing working capital cycles across the value chain. Manufacturing capacity concentrates in the United States, Germany, and Poland, drawing from aerospace-grade carbon fiber, forged aluminum alloys, and specialized thermoplastic resins. Single-source vulnerability in Japanese carbon fiber prepreg supply creates exposure to input volatility. Distribution runs through airframe OEM bundling agreements for high-horsepower systems and independent distributor networks for general aviation replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital engine control interoperability is rewiring competitive boundaries between propeller system integrators and engine OEMs.
For Market Incumbents: Build certification moats by securing simultaneous FAA-EASA dual certification for five-blade noise reduction architectures before ICAO Chapter 14 enforcement tightens. Deepen backward integration into continuous fiber thermoplastic processing to escape carbon fiber prepreg margin compression from Japanese suppliers. Anchor aftermarket dominance through captive MRO networks serving ATR and Dash 8 fleets. For New Entrants and Emerging Players: Establish a beachhead in Poland's Rzeszów aerospace cluster where EU regulatory proximity intersects with lower labor costs than German manufacturing belts. Target Brazil's agricultural aviation cooperatives with variable-pitch systems optimized for payload flexibility during crop-dusting operations. Pursue direct-to-operator digital distribution to compress traditional aftermarket distributor margins and capture AOG turnaround demand. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors foundry-integrated manufacturers with captive aluminum casting capacity and automated fiber placement capabilities. Long-term viability hinges on dual-use technology pathways between commercial regional aircraft and NATO military trainer platforms. Watch for electric propulsion substitution signals in urban air mobility funding flows as the inflection indicator for turboprop demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fiber Thermoplastic Processing Adoption | Collapses autoclave curing timelines for ATR fleet operators seeking fuel burn reduction. |
| FAA-EASA Dual Certification Investment | Secures market access across North American and European regional carrier procurement channels. |
| Poland Manufacturing Footprint Expansion | Captures EU regulatory proximity without German labor cost structures for blade production. |
| Power-by-the-Hour Service Contract Launch | Transfers overhaul risk to OEM networks for Southeast Asian lease-fleet operators. |
| Five-Blade Noise Reduction Architecture Development | Displaces three-blade designs where ICAO Chapter 14 compliance determines airport slot eligibility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regional airline fleet managers, agricultural aviation cooperative procurement leads, MRO facility directors, and composite blade manufacturing engineers. Secondary validation drew from FAA Part 35 airworthiness directives, EASA certification databases, ICAO noise certification annexes, and customs trade data for carbon fiber prepreg imports. Bottom-up triangulation across individual operator purchase records and top-down reconciliation against airframe OEM production schedules anchored volume estimates.
Calibration against historical replacement cycle data and fleet age distributions across the projection horizon ensured trajectory plausibility. Segmentation dimensions modeled include propeller type, material composition, power rating, and application category alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves adjusted for fleet expansion plans and retirement schedules. Forecast inputs incorporated ICAO Chapter 14 implementation timelines and defense ministry trainer platform procurement pipelines.
Sensitivities concentrate around carbon fiber supply disruption, FAA-EASA regulatory divergence acceleration, and electric propulsion technology maturation. Forecasts reflect documented assumptions regarding regional carrier fleet renewal rates and agricultural aviation operating hour recovery. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Military Aircraft Actuation System Market