
 Global Aircraft Micro Turbine Market | 2026-2036
Global Aircraft Micro Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Micro Turbine Market Foresight
Long-term maintenance contracts and performance-based logistics agreements are restructuring how aircraft micro turbine value gets captured across the ownership lifecycle. Honeywell International Inc. leverages its integrated avionics-turbine ecosystem to lock in aftermarket revenue streams on business jet and helicopter platforms. GE Aerospace anchors military micro turbine development through its sustained R&D investment in compact propulsion architectures for unmanned systems. Safran SA differentiates via European supply chain control and specialized turboshaft expertise serving both civil rotorcraft and defense UAV programs.
Aircraft micro turbines are compact gas turbine engines typically producing under 1,000 shaft horsepower, employing centrifugal compressors and single-stage turbines with pressure ratios between 4:1 and 8:1, designed for auxiliary power generation or primary propulsion in weight-constrained aerial vehicles. Their industrial purpose centers on delivering high power-to-weight ratios for applications where piston engines lack sufficient specific power or turbine reliability is operationally critical. The turboshaft product category dominates installed base value given its entrenched position in helicopter main propulsion and military UAV endurance missions, while auxiliary power units concentrate margin pools through overhaul-intensive aftermarket cycles. Unmanned aerial vehicles represent the fastest-expanding application segment as military operators and commercial survey platforms demand extended loiter times that only efficient micro turbine architectures can sustain.
FAA Part 33 certification mandates and EASA CS-E standards enforce strict fuel efficiency and emissions thresholds that shape new engine development budgets and timeline risk for OEM programs. The EU Green Deal aviation decarbonization framework and ICAO Carbon Offsetting and Reduction Scheme for International Aviation are pressuring micro turbine manufacturers to demonstrate compatibility with sustainable aviation fuel blends and hybrid-electric architectures. Stakeholders must monitor how dual-use military-civil certification pathways evolve, as defense procurement flexibility increasingly determines which engineering teams can amortize development costs across both regulatory environments.
Market Dynamics
Defense procurement for unmanned systems is compressing development cycles and forcing micro turbine OEMs to amortize certification costs across dual-use civil-military platforms. FAA Part 33 and EASA CS-E standards now require simultaneous fuel efficiency and emissions compliance, restructuring R&D allocation and supplier qualification timelines.
Growth Catalysts
- Military UAV endurance requirements:Loiter time specifications for intelligence-gathering missions now exceed piston engine thermal limits, pulling turboshaft architectures into tactical unmanned platforms.
- EU Green Deal aviation framework:Sustainable aviation fuel blend mandates create engineering pull for micro turbine combustor redesigns compatible with drop-in biofuels.
- Centrifugal compressor manufacturing:Five-axis machining advances in the United States and France are reducing time-to-first-article for high-pressure ratio impellers below 100mm diameter.
Market Restraints
- Superalloy supply concentration:Single-crystal turbine blade casting capacity concentrates in a handful of specialized foundries, creating input bottlenecks during demand surges.
- FAA Part 33 certification timeline:Airworthiness validation for new turbine designs stretches 48-60 months, freezing development capital and deterring venture-backed entrants.
- Hybrid-electric substitution threat:Battery energy density improvements in the 300-400 Wh/kg range threaten micro turbine auxiliary power unit economics on short-haul platforms.
Strategic Opportunities
- Urban air mobility propulsion:eVTOL developers in Germany and the United Kingdom seek certified turbogenerators for range-extender configurations, opening a new equipment category.
- India defense localization:The country's PLI scheme for aerospace components creates incentive structures for micro turbine assembly joint ventures serving regional UAV programs.
- Performance-based logistics contracts:Power-by-the-hour arrangements for military rotorcraft fleets shift revenue capture toward aftermarket availability guarantees rather than hardware margins.
Industry Challenges
- Turbine aerodynamicist scarcity:Specialized computational fluid dynamics expertise for micro-scale radial turbines concentrates at a handful of university programs and incumbent OEMs, constraining hiring pipelines.
- Legacy avionics integration:New micro turbine digital engine controls must interface with analog FADEC architectures on in-service helicopter platforms, extending qualification test matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Micro Turbine Market |
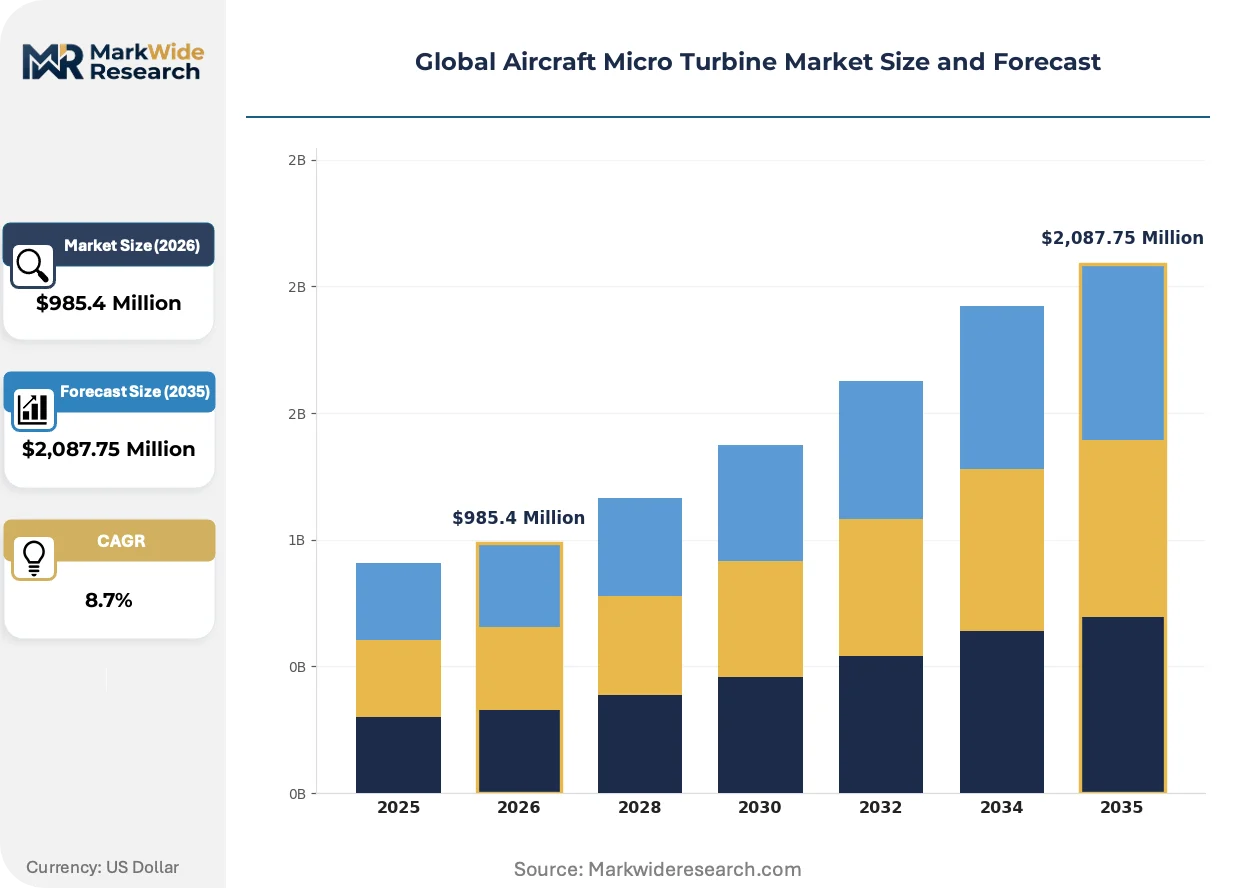
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
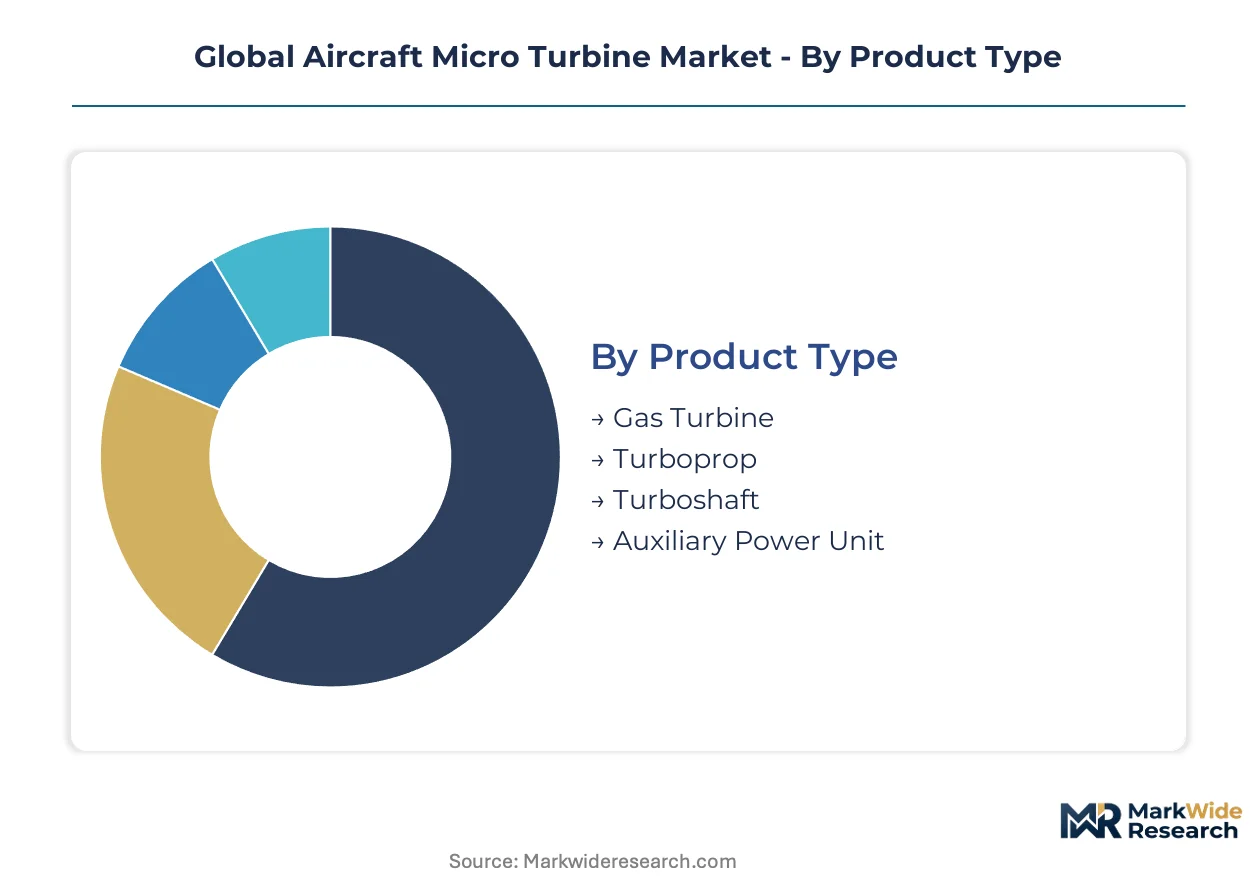
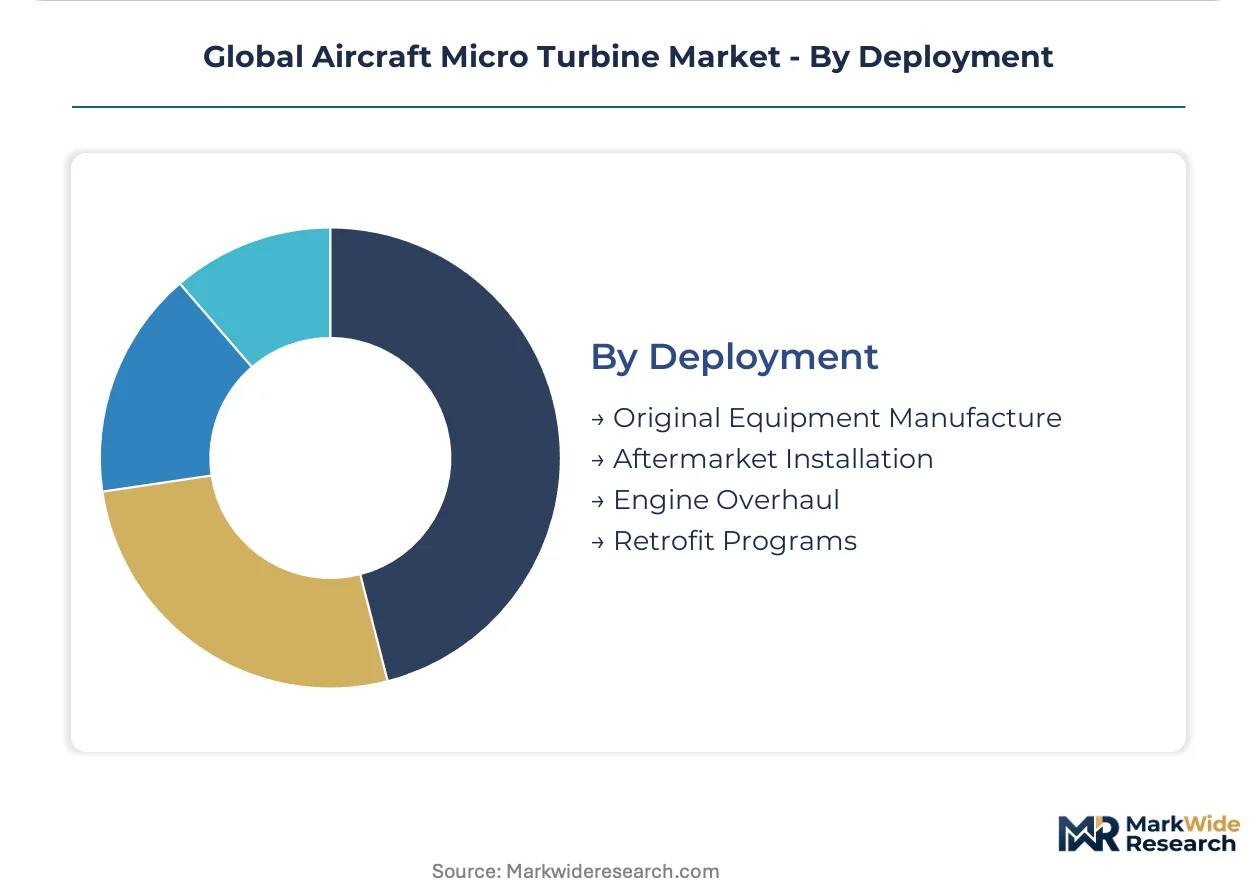
| Segmentation | Product Type: Gas Turbine, Turboprop, Turboshaft, Auxiliary Power Unit Application: Commercial Aviation, Military Aviation, Business Jets, Unmanned Aerial Vehicles, Helicopters End User: Aircraft Manufacturers, Defense Agencies, Charter Operators, Cargo Carriers, Maintenance Providers Deployment: Original Equipment Manufacture, Aftermarket Installation, Engine Overhaul, Retrofit Programs |
| Companies Covered | Honeywell International Inc., GE Aerospace, Safran SA, RTX Corporation, Williams International, UAV Turbines Inc., Kratos Defense & Security Solutions Inc., PBS Group, Turbotech SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Micro Turbine Market Shifts & Advancements
Additive manufacturing of nickel superalloy turbine wheels is collapsing lead times for prototype iterations and enabling geometries impossible through conventional investment casting. This shift is redrawing supplier qualifications and compressing the competitive window for new entrants.
Ceramic matrix composite hot-section components are consolidating thermal management strategies in next-generation micro turbines. Military UAV developers in the United States and Israel are adopting CMC combustor liners to push turbine inlet temperatures above 1,200°C without proportional cooling flow penalties. The technology is consolidating the trade space between specific power and service interval duration, forcing incumbent OEMs to requalify entire engine families.
EASA CS-E Amendment 6 emissions thresholds are tightening NOx and particulate matter limits for sub-1,000 shp turbines. Engine manufacturers must now demonstrate compliance through full-authority digital engine control mapping rather than hardware-only fixes. The turboshaft segment serving European civil rotorcraft faces the steepest redesign burden, with certification deadlines compressing engineering resource allocation.
Power-by-the-hour contracting is displacing traditional time-between-overhaul sales in military procurement. Defense operators in the United Kingdom and Australia now specify availability metrics rather than engine unit pricing, transferring operational risk to OEM service organizations. The shift concentrates margin capture in aftermarket logistics networks and predictive maintenance analytics capabilities.
Global Aircraft Micro Turbine Market Segmentation
Micro turbine procurement patterns diverge sharply between defense programs demanding rapid fielding cycles and commercial operators prioritizing lifecycle cost predictability. Segmentation reveals how engineering specifications, certification pathways, and aftermarket economics reshape competitive positioning across buyer categories.
Product Type:
Buyers differentiate primarily by thrust-to-weight requirements and mission endurance profiles rather than unit economics alone.
- Turboshaft:These engines convert gas turbine output to shaft power for rotorcraft propulsion, achieving pressure ratios up to 8:1 in sub-1,000 shp configurations. Demand concentrates in United States and United Kingdom military UAV programs where loiter specifications exceed piston engine thermal limits, though superalloy blade casting bottlenecks constrain surge production capacity.
- Auxiliary Power Unit:Compact turbines providing electrical and pneumatic power on aircraft ground operations and emergency backup, typically 100-500 shp range. Commercial aviation operators in France and Germany prioritize these units for their overhaul-intensive revenue cycles, with EASA CS-E Amendment 6 emissions thresholds forcing combustor redesigns for European-registered fleets.
- Gas Turbine:Direct thrust configurations for small unmanned platforms and experimental aircraft.
- Turboprop:Powerplants combining turbine core with propeller reduction gearbox for light aircraft applications.
Volume sits with turboshaft architectures given entrenched helicopter and military UAV positions; growth tilts toward auxiliary power units as sustainable aviation fuel compatibility mandates accelerate replacement cycles.
Application:
Operational tempo and regulatory exposure create distinct procurement behaviors across mission types.
- Unmanned Aerial Vehicles:Tactical and endurance platforms spanning intelligence-gathering to commercial survey operations. Israeli and United States defense agencies drive specifications demanding turbine inlet temperatures above 1,200°C enabled by ceramic matrix composite liners, compressing development cycles through dual-use certification pathways.
- Military Aviation:Crewed rotorcraft and fixed-wing platforms requiring battlefield reliability under Part 33 airworthiness mandates. Procurement through United Kingdom and Australia defense ministries now specifies availability metrics rather than unit pricing, transferring operational risk to OEM service organizations.
- Commercial Aviation:Regional and narrow-body aircraft auxiliary power systems.
- Business Jets:Light and mid-size corporate aircraft propulsion and power generation.
- Helicopters:Civil rotorcraft main and auxiliary power applications.
Military applications command the dominant installed base; unmanned aerial vehicles are climbing the fastest as battery energy density improvements remain insufficient for multi-hour loiter requirements.
End User:
Contracting mechanisms and technical integration depth separate buyer categories.
- Defense Agencies:National procurement authorities specifying performance-based logistics with power-by-the-hour structures. India's PLI scheme for aerospace components is reshaping supplier qualification for regional UAV programs, creating joint venture incentives for foreign micro turbine OEMs.
- Aircraft Manufacturers:OEMs integrating turbines at original equipment stage with full authority digital engine controls. These buyers demand backward integration into avionics-turbine ecosystems to lock in aftermarket revenue across business jet and helicopter platforms.
- Charter Operators:Fleet managers prioritizing time-between-overhaul predictability.
- Cargo Carriers:Express freight operators with high-cycle utilization profiles.
- Maintenance Providers:Independent service organizations capturing overhaul margins.
Defense agencies concentrate procurement volume through consolidated military programs; aircraft manufacturers represent the steepest expansion trajectory as urban air mobility developers seek certified turbogenerator suppliers.
Deployment:
Revenue timing and margin capture mechanics diverge across equipment lifecycle stages.
- Original Equipment Manufacture:Factory installation during aircraft assembly with integrated FADEC architecture. Five-axis machining advances in United States and France centrifugal compressor production are collapsing lead times for high-pressure ratio impellers below 100mm diameter.
- Engine Overhaul:Scheduled maintenance events restoring turbine performance to specification. FAA Part 33 certification timelines stretching 48-60 months freeze development capital, concentrating overhaul demand on incumbent OEM service networks with established airworthiness documentation.
- Aftermarket Installation:Post-delivery powerplant additions and upgrades.
- Retrofit Programs:In-service aircraft modification for emissions compliance or performance enhancement.
Original equipment manufacture captures the largest revenue pool per unit; engine overhaul is gaining share fastest as power-by-the-hour contracts displace traditional time-between-overhaul sales in military procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the United States, France, and the United Kingdom while procurement demand spreads across defense ministries in Israel, India, and Australia. This production-consumption divide shapes cross-border supply relationships and certification reciprocity negotiations.
United States
Defense procurement for endurance UAVs drives turboshaft demand beyond piston engine thermal limits. FAA Part 33 certification mandates enforce fuel efficiency and emissions benchmarks that compress development timelines. Connecticut and Arizona host established propulsion clusters where five-axis machining advances reduce centrifugal compressor lead times.
France
Commercial rotorcraft operators prioritize auxiliary power unit overhaul cycles for lifecycle cost predictability. EASA CS-E Amendment 6 emissions thresholds force combustor redesigns for European-registered fleets. The Toulouse aerospace corridor anchors manufacturing investment through specialized turboshaft expertise and supply chain control.
United Kingdom
Military procurement now specifies availability metrics rather than unit pricing under power-by-the-hour structures. The country's defense ministry transfers operational risk to OEM service organizations through performance-based logistics. Bristol and Derby manufacturing centers concentrate on ceramic matrix composite integration for turbine inlet temperature advancement.
Israel
Tactical UAV programs demand turbine inlet temperatures above 1,200°C enabled by ceramic matrix composite liners. The country's defense agencies compress development cycles through dual-use certification pathways. Tel Aviv-area engineering clusters specialize in compact propulsion architectures for unmanned systems.
India
Domestic UAV program expansion creates procurement pull for localized micro turbine assembly. The PLI scheme for aerospace components incentivizes joint ventures between foreign OEMs and domestic manufacturers. Bangalore and Hyderabad defense corridors attract investment through production-linked incentive structures.
Global Aircraft Micro Turbine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the micro turbine value chain. Foundry-dependent OEMs anchor manufacturing in superalloy casting clusters while specialized engineering houses concentrate on digital engine control integration. The market structure tiers across integrated avionics-turbine ecosystems, standalone turboshaft specialists, and defense-focused compact propulsion developers. Dominant competitive moves include strategic partnerships for ceramic matrix composite sourcing and geographic expansion through India's PLI scheme joint ventures.
Within the integrated ecosystem tier, Honeywell International Inc. and GE Aerospace exemplify archetypes that combine avionics and turbine development under unified certification pathways. Safran SA occupies a position representing European supply chain control and specialized turboshaft expertise. Williams International and UAV Turbines Inc. sit within the compact propulsion specialist category, anchoring demand from unmanned aerial vehicle programs where weight constraints dominate procurement specifications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| GE Aerospace |
| Safran SA |
| RTX Corporation |
| Williams International |
| UAV Turbines Inc. |
| Kratos Defense & Security Solutions Inc. |
| PBS Group |
| Turbotech SAS |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FAA Part 33-certified turboshafts and uncertified experimental powerplants manifests in both pricing premiums and supplier qualification burdens. Tier-one OEMs in Connecticut and Arizona command hardware margins three to four times higher than commodity producers, while superalloy foundry capacity constraints in the United States and France force buyers into 18-month order backlogs that prop pricing power.
Pricing Analysis
Cost-down pressure on auxiliary power units accelerates as EASA CS-E Amendment 6 compliance forces combustor redesign investments. Contract-based long-term offtake structures dominate military procurement through power-by-the-hour arrangements, while commercial operators face transactional per-unit pricing with steep certification premiums. Price differentiation separates Part 33-certified architectures from experimental-grade alternatives, with brand premiums and after-sales service bundling widening spreads. Defense agencies show lowest price sensitivity given mission-critical reliability requirements; charter operators face acute sensitivity due to high-cycle utilization economics.
Supply Chain Analysis
Specialized turbine aerodynamicist scarcity in the United States, France, and United Kingdom constrains engineering throughput for impeller design iterations. Manufacturing draws from single-crystal superalloy castings, ceramic matrix composite liners, and five-axis machined centrifugal compressors. Single-source vulnerability concentrates in nickel superalloy foundries serving blade and vane production. Distribution runs through OEM-captive service networks for military overhaul, with independent maintenance providers capturing commercial auxiliary power unit cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-crystal turbine blade casting capacity shortages in specialized foundries prop pricing power and extend order backlogs across the value chain. This supply-constrained structure favors incumbents with captive casting relationships and disadvantages venture-backed entrants facing 48-60 month certification timelines.
For Market Incumbents: Cement aftermarket lock-in through performance-based logistics contracts that transfer operational risk from defense agencies to OEM service organizations. Deepen backward integration into superalloy foundry capacity in Connecticut or Arizona to defend against single-source input vulnerability. Prioritize ceramic matrix composite combustor liner R&D to maintain turbine inlet temperature leadership against emerging compact propulsion specialists. For New Entrants and Emerging Players: Begin with India's PLI scheme joint ventures for aerospace components, where production-linked incentives reduce capital barriers for regional UAV program supply. Target urban air mobility turbogenerator development in Germany and the United Kingdom, where eVTOL developers seek certified range-extender configurations absent established supply relationships. Pursue dual-use certification pathways that amortize development costs across civil and military regulatory environments. For Investors and Strategic Acquirers: Re-rating potential sits with ceramic matrix composite specialists given EASA CS-E emissions thresholds forcing hot-section redesigns across European-registered fleets. Long-term viability favors asset-light engineering houses with computational fluid dynamics capabilities rather than foundry-dependent hardware producers. Watch FAA-EASA certification reciprocity negotiations as inflection indicators for cross-border market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Matrix Composite Integration | CMC combustor liners enable turbine inlet temperatures above 1,200°C without cooling flow penalties. |
| Dual-Use Certification Pathway | Amortizes development costs across FAA Part 33 and military airworthiness mandates. |
| Performance-Based Logistics Contract | Shifts revenue capture from hardware margins to availability guarantees in UK and Australian defense procurement. |
| India PLI Joint Venture | Production-linked incentives attract foreign OEM assembly investment for regional UAV programs. |
| Additive Manufacturing Qualification | Nickel superalloy 3D printing collapses prototype lead times for turbine wheel iterations. |
Research Methodology
Document review covered FAA Type Certificate Data Sheets, EASA CS-E Amendment 6 regulatory filings, and defense procurement announcements, complemented by interviews with propulsion engineering directors, military program procurement officers, and aftermarket service heads. Primary fieldwork engaged turboshaft product managers at helicopter OEMs, UAV platform integrators in Israel and the United States, and superalloy foundry operations managers. Secondary validation drew from SEC 10-K aerospace segment disclosures, customs import records for turbine components, and industry association production surveys. Bottom-up unit economics triangulated against top-down defense budget allocation models.
Segment-level outputs across the projection horizon reflect modeled deployment splits between original equipment manufacture and engine overhaul, with product type segmentation capturing turboshaft, auxiliary power unit, and emerging turbogenerator categories. Application segmentation distinguished unmanned aerial vehicle, military aviation, and urban air mobility demand pools. CAGRs derived from regression against historical defense procurement cycles and sustainable aviation fuel mandate implementation timelines. Forecast inputs incorporated centrifugal compressor manufacturing lead time compression, ceramic matrix composite adoption curves, and power-by-the-hour contract penetration rates.
Underlying measurement precision varies by segment; unmanned aerial vehicle forecasts carry tighter precision than urban air mobility given established procurement programs versus speculative eVTOL certification timelines. Forecasts reflect assumptions on FAA-EASA regulatory harmonization, superalloy foundry capacity expansion, and battery energy density substitution thresholds. Material deviation in defense budget appropriations, emissions standard acceleration, or hybrid-electric propulsion breakthrough warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aerospace Electrical Inserts Market