
 Aviation Actuator System Market | 2026-2036
Aviation Actuator System Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Actuator System Market Analysis
Defense procurement is bifurcating from commercial retrofit cycles as the dominant demand archetype in aviation actuator systems. Moog Inc. leverages its electro-hydraulic heritage to anchor military fly-by-wire programs across multiple platforms. Honeywell International Inc. competes through integrated flight control architectures that span actuation, sensing, and computing layers. Curtiss-Wright Corporation specializes in ruggedized electromechanical units for severe-service aerospace environments.
An aviation actuator system converts control signals into mechanical force to position flight surfaces, landing gear, or engine components, typically operating at pressures exceeding 3,000 psi in hydraulic configurations and requiring fault-tolerant redundancy per DO-178C software standards. Electric actuators are displacing hydraulic architectures in next-generation narrow-body programs due to weight reduction targets and elimination of centralized hydraulic infrastructure. Smart actuator technology leads margin pools through embedded prognostics that reduce unscheduled maintenance intervals. Flight control systems remain the largest application segment by installed base, though landing gear electrification represents the fastest-growing retrofit opportunity.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate fail-safe or fail-operational actuator performance for transport category aircraft, directly shaping R&D allocation toward redundant motor winding and jam-tolerant mechanical designs. The EU AI Act and emerging machine-learning guidance from EASA are introducing new validation protocols for adaptive control algorithms in smart actuator systems. Stakeholders must monitor the divergence between military MIL-STD-810 qualification paths and commercial RTCA DO-160 environmental test standards as product development timelines compress.
Market Dynamics
Electrification of flight control architectures is compressing hydraulic infrastructure requirements across narrow-body and regional jet programs, forcing incumbent suppliers to reconfigure motor-winding capabilities and thermal management portfolios.
Growth Catalysts
- FAA Part 25 Fail-Operational Mandates:Transport category aircraft certification now requires jam-tolerant actuator designs with redundant position feedback loops. Airframers in the United States and Germany are accelerating procurement of dual-channel electromechanical units.
- More Electric Aircraft (MEA) Roadmaps:Boeing and Airbus narrow-body platforms are eliminating centralized hydraulic distribution. Electric actuator demand concentrates at final assembly lines in Charleston, Toulouse, and Tianjin.
- Smart Actuator Embedded Prognostics:Health monitoring algorithms reduce unscheduled maintenance intervals. Airlines operating high-cycle narrow-body fleets in China are prioritizing these units for landing gear retrofits.
Market Restraints
- Rare Earth Magnet Supply Concentration:High-performance permanent magnets for brushless DC motors source predominantly from Chinese processing facilities. Western actuator manufacturers face input cost volatility and export licensing friction.
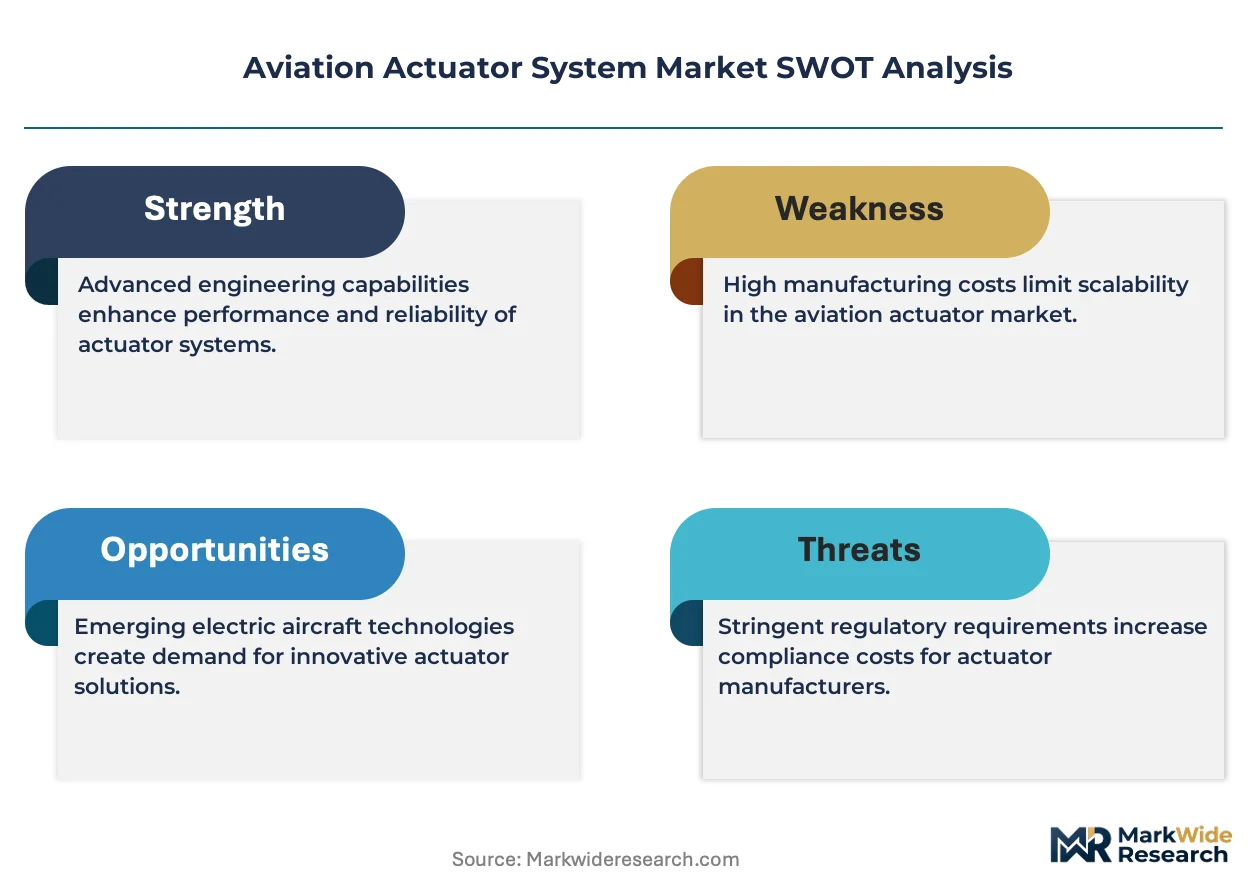
- Dual Certification Burden:RTCA DO-178C software standards and EU AI Act algorithmic validation create parallel compliance tracks. Development timelines for adaptive control actuators extend by 18-24 months.
- Hydraulic System Lock-In:Existing wide-body fleets require backward-compatible spares. Retrofit electric actuators must interface with legacy 3,000 psi hydraulic architectures, constraining design freedom.
Strategic Opportunities
- Urban Air Mobility Electrification:eVTOL platforms require distributed electromechanical actuation with sub-millisecond response times. Certification pathways through FAA Special Class airworthiness rules are stabilizing for 6-9 seat configurations.
- India Defense Localization:Indigenization mandates under the country's defense procurement procedures create captive demand for ruggedized actuators. Joint ventures with HAL and private aerospace clusters in Bangalore offer market entry.
- Power-by-Wire Convergence:Integration of silicon carbide power electronics with fault-tolerant motor drives enables 270V DC bus architectures. This technology pairing supports next-generation flight control surface actuation.
Industry Challenges
- Embedded Software Talent Scarcity:DO-178C DAL-A certification expertise resides with a limited pool of engineers in Wichita, Toulouse, and Hamburg. Compensation inflation is compressing R&D margins.
- Supply Chain Reconfiguration Costs:Qualifying alternative magnet suppliers outside China requires 36-48 month validation cycles. Actuator OEMs must dual-source while maintaining performance consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Actuator System Market |
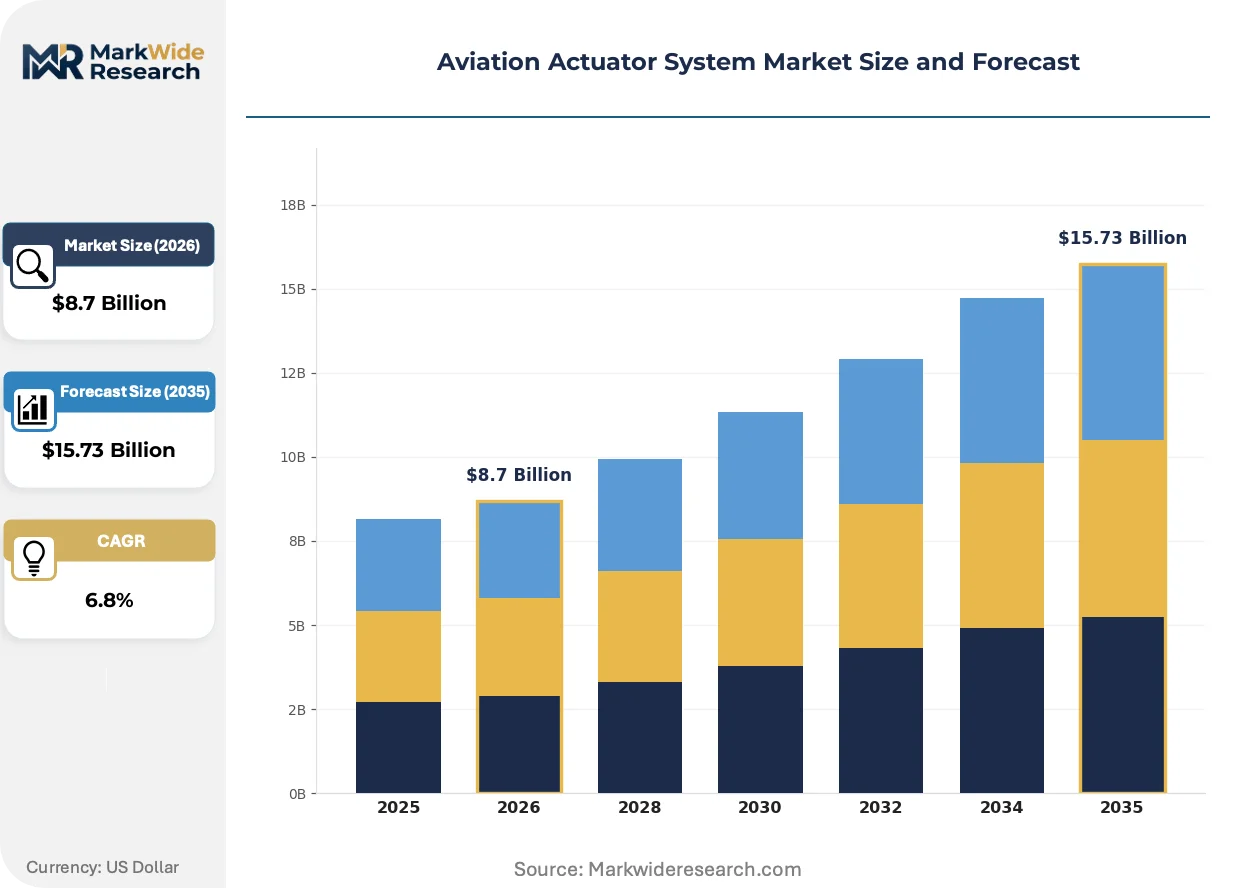
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators Application: Flight Control Systems, Landing Gear Systems, Engine Controls, Cabin Pressure Control End User: Commercial Aviation, Military Aviation, Business Aircraft, Helicopters Technology: Fly-by-Wire, Electro-Mechanical, Hydraulic Systems, Smart Actuators |
| Companies Covered | Curtiss-Wright Corporation, AMETEK Inc., Honeywell International Inc., Collins Aerospace, Parker-Hannifin Corporation, Safran SA, Liebherr Group, Rockwell Collins, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Actuator System Market Emerging Trajectories
Actuator technology trajectories center on three vectors: power density compression, regulatory validation of adaptive algorithms, and procurement model fragmentation between OEM direct sales and airline MRO channels.
Integrated motor-drive units with silicon carbide switching elements are miniaturizing power conversion stages while maintaining 270V DC isolation ratings. Regional jet manufacturers in Brazil and Canada are adopting these compact architectures for slat and flap actuation. The technology is miniaturizing actuator envelope dimensions by 40%, enabling wing-surface integration previously blocked by hydraulic line routing constraints.
EASA CS-25 Amendment 27 and the EU AI Act are imposing formal validation requirements on machine-learning-based prognostic algorithms. Smart actuator suppliers must now submit training data lineage and edge-case performance documentation. Narrow-body programs with European type certificates are responding by segregating deterministic control loops from adaptive health-monitoring functions to simplify certification scope.
Airline procurement departments are unbundling actuator overhaul services from OEM power-by-the-hour contracts. Third-party MRO providers in Singapore and the United Arab Emirates are capturing landing gear actuator refurbishment volume through DER-approved repair schemes. This behavioral shift is most visible among Gulf carriers operating mixed Airbus-Boeing fleets seeking cost arbitrage between OEM and independent channel pricing.
Aviation Actuator System Market Segmentation
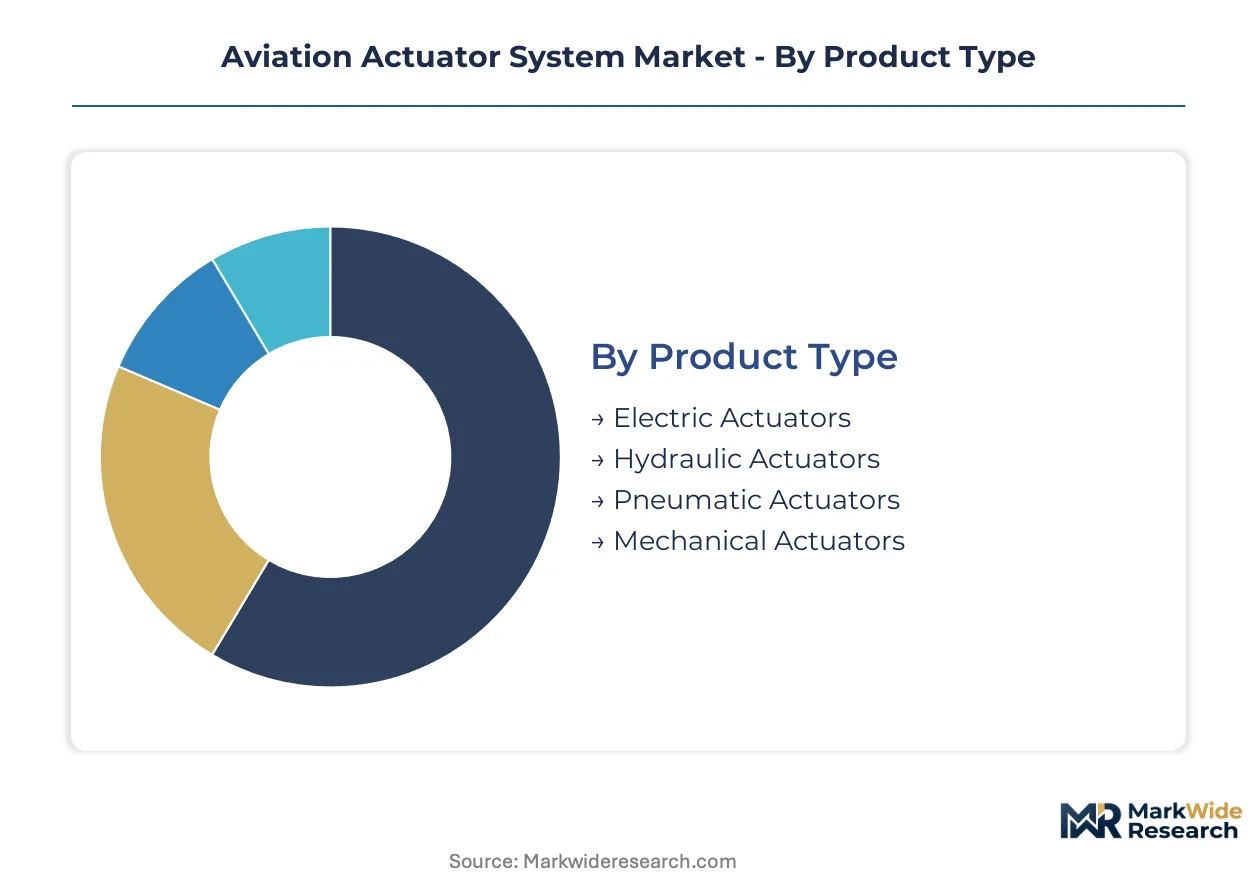
Aviation actuator procurement channels diverge sharply by segment: OEM direct sales dominate flight control and engine applications, while airline MRO channels capture landing gear retrofits. Segment-specific certification requirements and fleet replacement cycles create distinct margin profiles across product types and end-use categories.
Product Type:
Channel allocation varies by actuator architecture. Electric units flow predominantly through OEM direct contracts for new narrow-body programs, while hydraulic actuators sustain aftermarket spares channels serving legacy wide-body fleets.
- Electric Actuators:Brushless DC motor architectures with integrated power electronics convert electrical energy to mechanical force without hydraulic infrastructure. Final assembly lines in Charleston, Toulouse, and Tianjin concentrate procurement for Boeing and Airbus narrow-body platforms pursuing weight reduction targets.
- Hydraulic Actuators:Pressurized fluid systems operating above 3,000 psi deliver high force density for flight control surfaces. Existing wide-body fleets in the United States and Germany generate sustained aftermarket demand for backward-compatible spares.
- Pneumatic Actuators:Compressed air systems serve auxiliary functions where response speed requirements are moderate.
- Mechanical Actuators:Direct mechanical linkages persist in legacy platforms and certain backup control pathways.
By volume, Hydraulic Actuators leads. By growth pace, Electric Actuators is climbing the fastest.
Application:
Cost tier stratification separates flight control applications—where fail-operational mandates drive premium pricing—from cabin pressure systems with less stringent redundancy requirements.
- Flight Control Systems:Primary and secondary surface actuation demands jam-tolerant redundancy per FAA Part 25 and EASA CS-25 standards. Dual-channel electromechanical units with redundant position feedback dominate procurement for transport category aircraft.
- Landing Gear Systems:Electrification retrofits concentrate among high-cycle narrow-body operators in China seeking reduced unscheduled maintenance. Smart actuator embedded prognostics command price premiums in this segment.
- Engine Controls:Thrust reverser and variable geometry actuation operates in high-temperature environments.
- Cabin Pressure Control:Outflow valve actuation requires less force density than flight-critical applications.
Flight Control Systems captures the largest installed base. Landing Gear Systems shows the steepest expansion trajectory.
End User:
Customer type determines procurement rhythm: commercial airlines follow fleet replacement cycles, while military programs operate on defense procurement timelines with indigenization mandates in select geographies.
- Commercial Aviation:Narrow-body fleet expansion in China and final assembly concentration in the United States and Germany drive volume. Airlines prioritize total cost of ownership metrics including fuel burn reduction from weight-optimized electric architectures.
- Military Aviation:Fly-by-wire programs require ruggedized actuators qualified to MIL-STD-810 environmental standards. India's defense procurement localization mandates create joint venture opportunities with HAL and Bangalore aerospace clusters.
- Business Aircraft:Lower production volumes with higher customization requirements.
- Helicopters:Cyclic and collective control actuation in rotary-wing platforms.
Commercial Aviation holds the revenue concentration. Military Aviation is gaining share fastest.
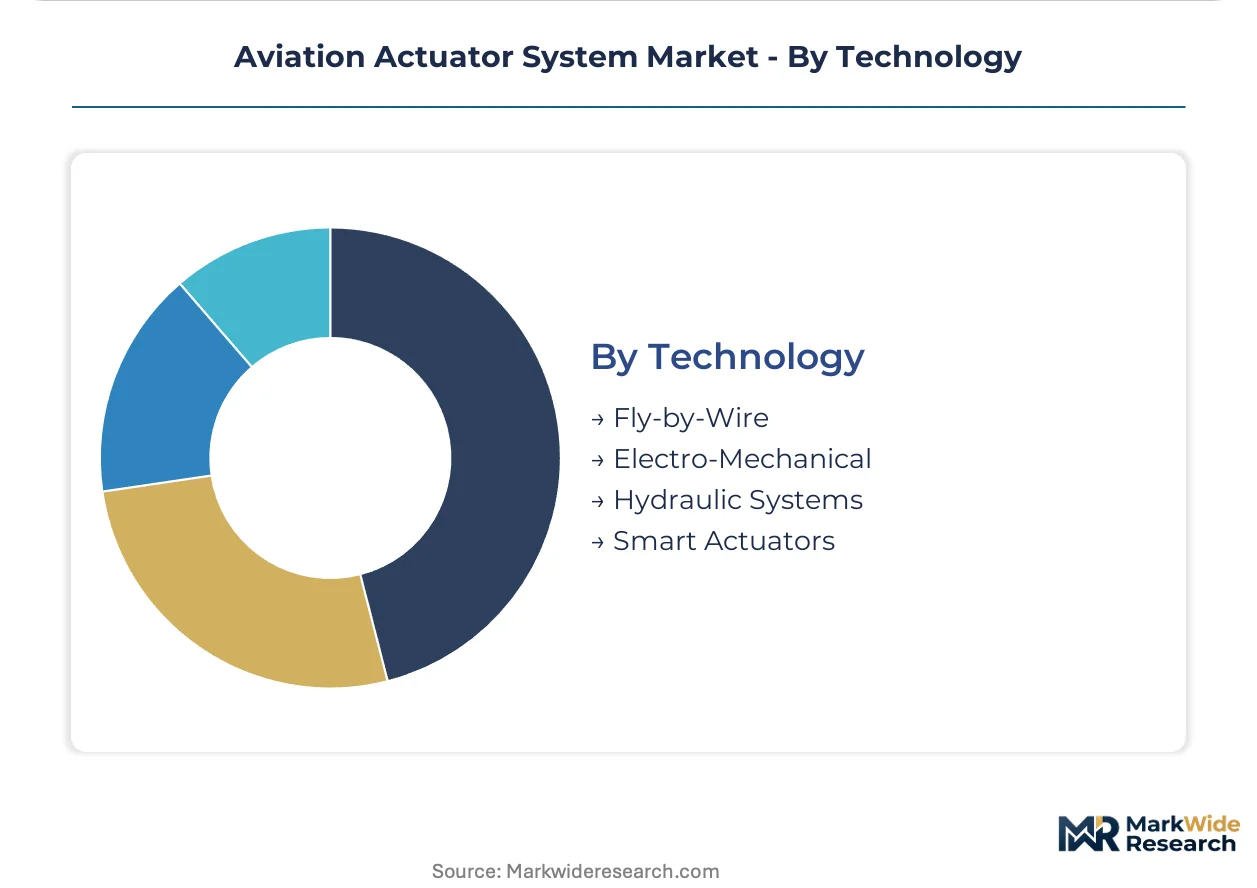
Technology:
Supply concentration for permanent magnets and silicon carbide power electronics shapes technology adoption curves, with alternative sourcing validation cycles extending 36-48 months.
- Fly-by-Wire:Digital flight control with no mechanical backup requires fault-tolerant actuation with redundant electronic pathways. Moog anchors military programs while Honeywell competes through integrated sensing-computing-actuation architectures.
- Smart Actuators:Embedded health monitoring algorithms with edge-case performance documentation satisfy EASA CS-25 Amendment 27 and EU AI Act validation protocols. Airlines in China prioritize these units for landing gear retrofits.
- Electro-Mechanical:Motor-driven mechanical linkages displacing hydraulic alternatives.
- Hydraulic Systems:Centralized fluid power architectures with distributed servo valves.
Fly-by-Wire maintains the largest deployment base. Smart Actuators is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Final assembly concentration in three countries shapes procurement flows for aviation actuator systems. Boeing, Airbus, and COMAC production lines anchor demand patterns across distinct regulatory environments.
United States
Charleston and Everett final assembly lines drive narrow-body actuator procurement volumes. FAA Part 25 fail-operational mandates accelerate dual-channel electromechanical unit adoption. Wichita clusters host DO-178C certification expertise pools where Honeywell and Moog anchor military fly-by-wire development.
China
COMAC C919 production at Tianjin and Shanghai facilities concentrates domestic actuator demand. The country's rare earth magnet processing dominance creates supply-chain leverage over Western motor manufacturers. High-cycle narrow-body operators in Guangdong prioritize smart actuator retrofits for landing gear systems.
Germany
Hamburg and Bremen Airbus final assembly lines sustain hydraulic-to-electric transition demand. EASA CS-25 Amendment 27 imposes algorithmic validation requirements on smart actuator health-monitoring functions. Bavaria's aerospace supply base clusters around Munich-anchored electromechanical component manufacturing.
France
Toulouse final assembly operations coordinate Airbus narrow-body actuator procurement. EU AI Act compliance protocols extend development timelines for adaptive control algorithms. Occitanie's aerospace ecosystem supports electromechanical actuator testing and qualification infrastructure.
India
Defense procurement localization mandates under DPP procedures create captive demand for ruggedized actuators. HAL Bangalore partnerships offer market entry pathways for electromechanical specialists. Tamil Nadu and Telangana private aerospace clusters are developing component qualification capabilities.
Aviation Actuator System Market Vendor Landscape
Concentration sits with diversified aerospace conglomerates and specialized motion control firms. The vendor base spans three tiers: integrated flight control architects, electromechanical component specialists, and hydraulic heritage suppliers managing transition portfolios. Strategic moves center on silicon carbide power electronics integration and dual-source magnet supply chain reconfiguration.
Among diversified conglomerates, Honeywell International Inc. and Safran SA exemplify integrated sensing-computing-actuation architectures. Moog Inc. occupies a distinct position within the precision motion control tier. Curtiss-Wright Corporation represents the ruggedized electromechanical specialist archetype serving severe-service aerospace environments.
| Leading Market Players |
|---|
| Curtiss-Wright Corporation |
| AMETEK Inc. |
| Honeywell International Inc. |
| Collins Aerospace |
| Parker-Hannifin Corporation |
| Safran SA |
| Liebherr Group |
| Rockwell Collins |
| Moog Inc. |
| Others |
Supply Flow & Price Mechanics
Thirty-six to forty-eight month magnet supplier qualification cycles concentrate pricing power with incumbent actuator OEMs who have already secured dual-source arrangements. FAA Part 25 fail-operational mandates and EASA CS-25 certification requirements create tiered cost structures where jam-tolerant electromechanical units command substantial premiums over standard hydraulic alternatives.
Pricing Analysis
FAA Part 25 dictates the pricing tier structure through its fail-operational and fail-safe performance mandates for transport category aircraft. Three-tier pricing stratifies across DAL-A certified smart actuators, dual-channel electromechanical units, and legacy hydraulic spares. Price differentiation centers on software certification grade and redundant motor winding architecture. Cost compression in the hydraulic aftermarket intensifies because airlines unbundle MRO services from OEM power-by-hour contracts. Low-cost carriers operating high-cycle narrow-body fleets in China exhibit the highest price sensitivity, while defense procurement offices in India and Germany demonstrate the lowest.
Supply Chain Analysis
Thirty-six to forty-eight month alternative magnet validation cycles expose Western actuator manufacturers to input cost volatility. Rare earth magnet processing concentrates in China, with secondary concentration in Japan and emerging capabilities in Australia. Brushless DC motor architectures draw from neodymium-iron-boron magnets, silicon carbide power electronics, and fault-tolerant motor windings. Single-source vulnerability in Chinese rare earth processing creates tariff exposure and export licensing friction for Western OEMs. Distribution runs through OEM direct sales for flight control and engine applications, with third-party MRO channels capturing landing gear retrofit volume in Singapore and the United Arab Emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aviation actuator system market sustains defensive moats through regulatory entrenchment. FAA Part 25 and EASA CS-25 certification requirements create switching costs that lock airframers into qualified supplier relationships spanning decades.
For Market Incumbents: Compound certification portfolio depth by accelerating DO-178C DAL-A capability expansion in Wichita and Toulouse engineering clusters. Threats from rare earth magnet supply concentration and embedded software talent scarcity demand backward integration into silicon carbide power electronics and captive magnet sourcing partnerships outside China. Priority investment in jam-tolerant mechanical designs preserves positioning against emerging electromechanical specialists. For New Entrants and Emerging Players: Anchor in India's defense procurement localization mandates under DPP procedures, where HAL Bangalore joint ventures offer the most penetrable entry pathway. Urban air mobility eVTOL platforms present white-space demand for distributed electromechanical actuation with sub-millisecond response times. Go-to-market execution should target FAA Special Class airworthiness certification for 6-9 seat configurations before pursuing transport category approvals. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified aerospace conglomerates with non-core actuator divisions lacking smart actuator embedded prognostics capabilities. Long-term viability centers on suppliers with demonstrated EASA CS-25 Amendment 27 algorithmic validation expertise and dual-source magnet supply chains. Watch for inflection signals in airline procurement department unbundling behavior, particularly among Gulf carriers seeking cost arbitrage between OEM and independent MRO channel pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Enables 270V DC bus architectures that compress actuator envelope dimensions by 40%. |
| Dual-Source Magnet Supply Chain Reconfiguration | Reduces rare earth processing concentration risk from Chinese facilities through 36-48 month validation cycles. |
| Smart Actuator Embedded Prognostics Development | Satisfies EASA CS-25 Amendment 27 and EU AI Act validation protocols for health-monitoring algorithms. |
| India Defense Localization Joint Venture | Captures captive demand from DPP indigenization mandates through HAL Bangalore partnerships. |
| Urban Air Mobility Certification Pathway | Stabilizes FAA Special Class airworthiness rules for 6-9 seat eVTOL distributed actuation platforms. |
Methodological Framework
Cross-validation between primary interviews with flight control system engineers, airline procurement directors, defense procurement officers, and MRO service managers anchors the qualitative findings. Secondary validation draws from FAA type certificate databases, EASA certification documentation, SEC 10-K filings from listed aerospace suppliers, and customs records tracking rare earth magnet trade flows. Bottom-up triangulation across actuator unit shipment estimates and top-down reconciliation against airframe production schedules ensures consistency.
Sensitivity analysis around rare earth magnet price assumptions and narrow-body delivery timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include actuator architecture, application criticality, end-user procurement rhythm, and technology maturity tier. CAGRs derive from installed base replacement cycles and fleet expansion trajectories. Forecast inputs incorporate COMAC C919 production ramp schedules and Boeing-Airbus narrow-body delivery commitments.
Decision-makers should treat outputs as directional under assumptions of stable FAA-EASA regulatory convergence and continued rare earth supply concentration; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Battery Market