
 Aircraft Hydraulic Seat Actuation Systems Market | 2026-2036
Aircraft Hydraulic Seat Actuation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Hydraulic Seat Actuation Systems Market Analysis
Aftermarket maintenance contracts and software-defined diagnostics is shifting how hydraulic seat actuation systems generate recurring revenue. Moog Inc. leverages its flight control heritage to anchor positions in integrated electromechanical seats. Safran sustains European manufacturing scale through vertical integration into precision hydraulic components. Parker Hannifin competes on channel control, extending its distribution network across MRO providers globally.
Aircraft hydraulic seat actuation systems employ pressurized fluid—typically phosphate ester-based hydraulic fluid operating at 3,000 psi—to translate linear motion for seat positioning, lumbar support, and crash-energy absorption in crew and passenger seating. These systems integrate servo valves, accumulators, and position feedback sensors to achieve millimeter-level adjustment precision under dynamic flight loads. Among product types, custom systems command the widest margin pools as airframers specify unique envelope geometries for premium cabin configurations. Within applications, commercial aircraft dominates installed base volume, though business jets represent the fastest-growing retrofit segment as owners demand lie-flat seat conversions. Electro-hydraulic technology leads new OEM installations, displacing purely mechanical linkages in next-generation narrowbody programs.
The FAA governs crashworthiness through dynamic testing standards under 14 CFR 25.562, while EASA enforces parallel CS 25.561 certification requirements that shape product development cycles for dual-continent suppliers. ISO 7137 and SAE ARP4754A further constrain design methodologies, forcing manufacturers to maintain rigorous traceability across hydraulic component lifecycles. Stakeholders must weigh the capital intensity of electro-hydraulic R&D against the extended service horizons of legacy hydraulic architectures still prevalent in military platforms.
Market Dynamics
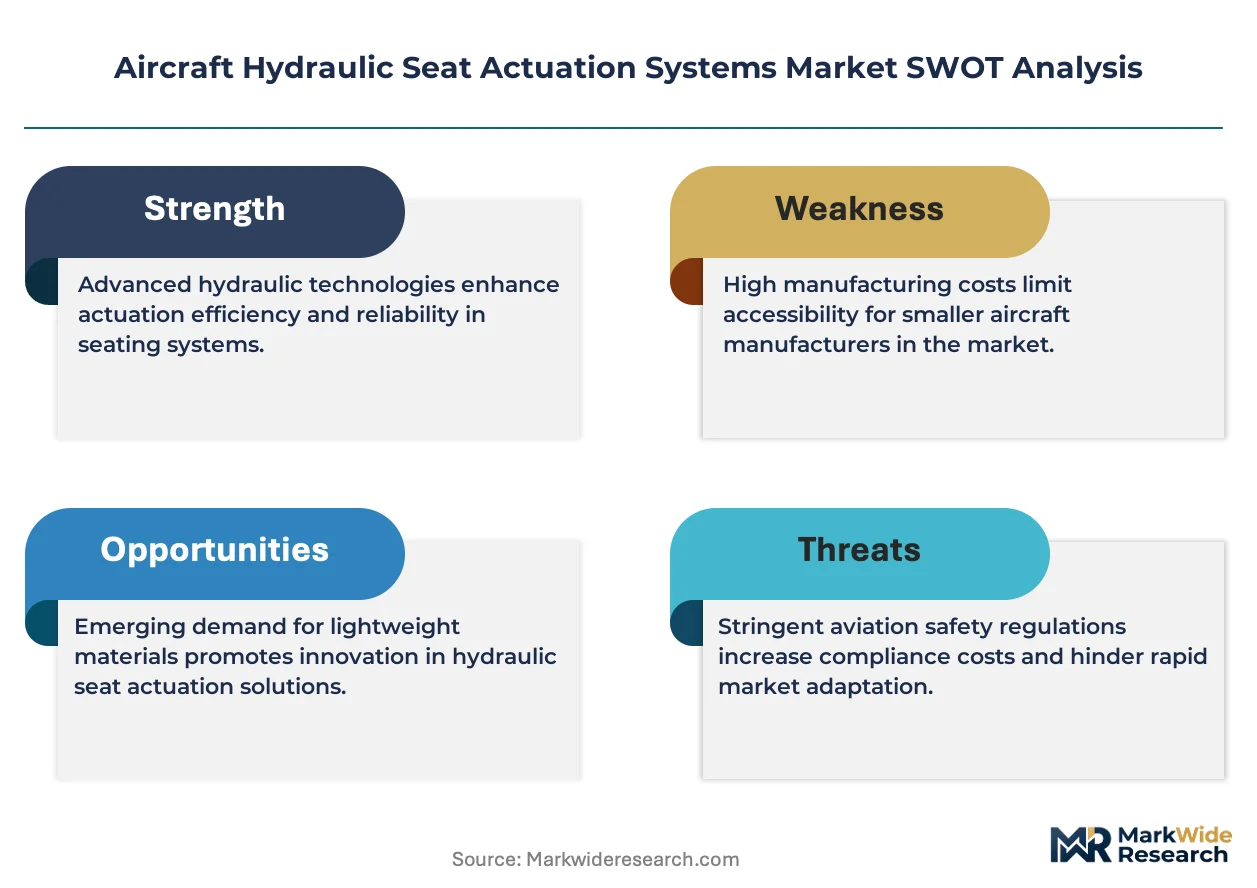
Fleet retrofit cycles and crashworthiness mandates are compressing product development timelines while elevating certification costs for hydraulic seat actuation suppliers serving commercial aviation.
Growth Catalysts
- FAA 14 CFR 25.562:Dynamic testing standards for crashworthy seating are mandating upgraded energy-absorption mechanisms in narrowbody retrofits across US carrier fleets.
- Phosphate ester hydraulic fluids:Fire-resistant formulations operating at 3,000 psi are enabling lighter accumulator designs that reduce overall seat mass in premium cabin configurations.
- Business jet lie-flat conversions:Owner-operators in the United Arab Emirates and Saudi Arabia are demanding full-flat sleeping surfaces that require multi-axis hydraulic articulation.
Market Restraints
- Specialized servo valve supply:Precision-machined flow control components concentrate among a limited set of European and North American precision hydraulics suppliers, creating input bottlenecks.
- SAE ARP4754A compliance costs:Rigorous traceability requirements across hydraulic component lifecycles extend development timelines and inflate engineering overhead for new entrants.
- Electromechanical substitution:Integrated electromechanical seat actuators are capturing share in next-generation OEM programs, threatening legacy hydraulic architecture demand.
Strategic Opportunities
- Military platform service extensions:Extended service horizons for legacy hydraulic architectures in US and allied defense fleets create aftermarket refurbishment demand.
- Software-defined diagnostics:Predictive maintenance algorithms embedded in seat control modules enable recurring revenue streams through performance-based service contracts.
- Indian narrowbody expansion:IndiGo and Air India's fleet growth programs are generating first-fit demand for certified crashworthy seating systems.
Industry Challenges
- ISO 7137 environmental testing:Vibration and temperature qualification protocols for airborne equipment extend certification timelines and strain validation resources.
- Electro-hydraulic integration complexity:Hybrid architectures combining hydraulic power with electronic control require rare cross-functional expertise in fluid power and embedded systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Hydraulic Seat Actuation Systems Market |
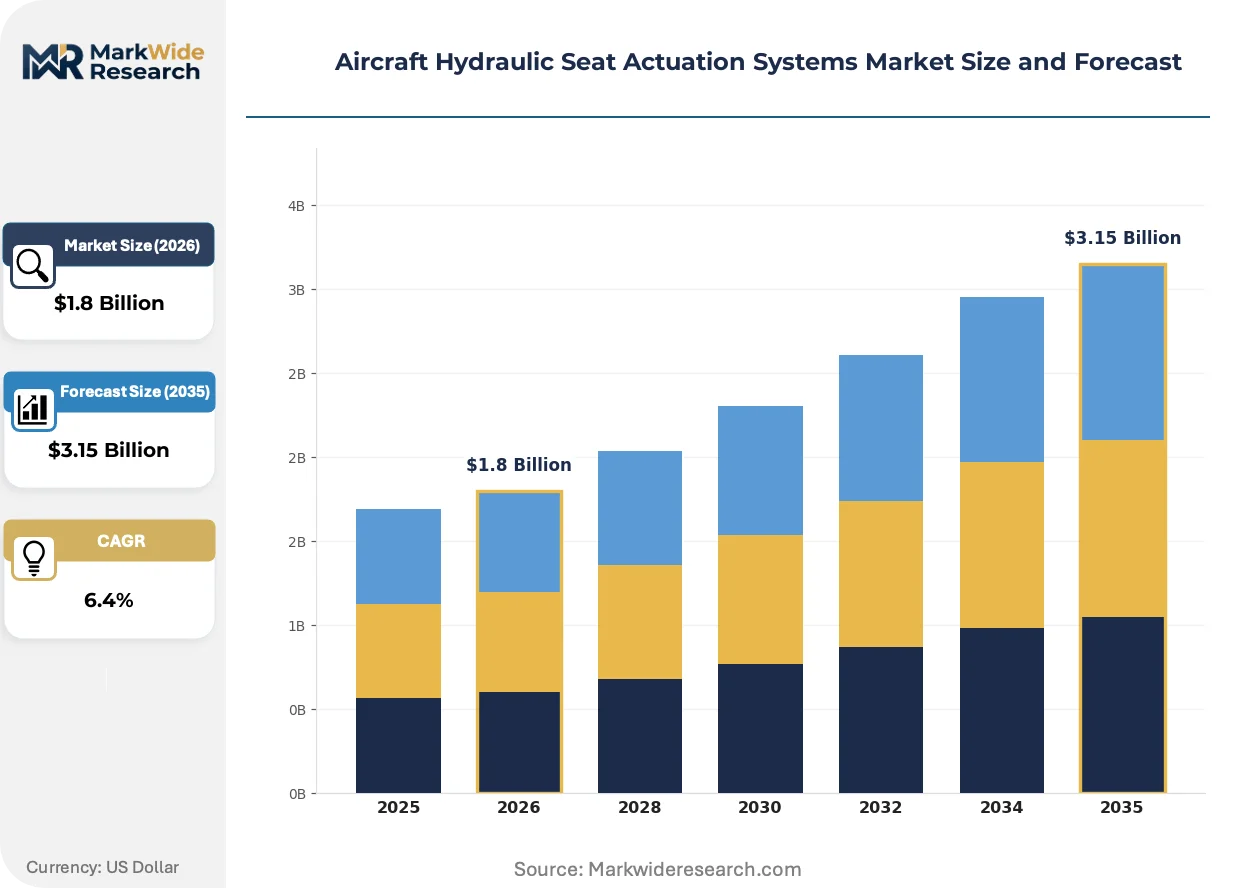
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Systems, Custom Systems, Advanced Systems, Retrofits Application: Commercial Aircraft, Military Aircraft, Business Jets, Helicopters End User: OEMs, Airlines, Military, Maintenance Providers Technology: Electro-Hydraulic, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Moog Inc., Astronics Corporation, Crane Aerospace & Electronics, ITT Inc., Safran, Honeywell International Inc., Parker Hannifin, Collins Aerospace, Bühler Motor GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Hydraulic Seat Actuation Systems Market Emerging Trajectories
Electro-hydraulic architectures and predictive maintenance software are redefining how seat actuation systems deliver performance, compliance, and lifecycle value.
Electro-hydraulic actuation is overtaking purely mechanical linkages in next-generation narrowbody programs. Boeing and Airbus OEM specifications now prioritize electronically controlled hydraulic positioning for millimeter-level adjustment precision. This convergence is compressing the supplier base toward firms with dual competencies in fluid power and embedded control systems.
EASA's CS 25.561 certification requirements are tightening parallel to FAA standards, forcing dual-continent suppliers to maintain redundant testing protocols. European airframers now demand identical dynamic test documentation for seats installed on A320-family aircraft. Suppliers serving both markets face amplified compliance overhead but gain competitive insulation against single-continent rivals.
Airline procurement teams are unbundling aftermarket service contracts from initial hardware purchases. MRO providers now contract directly with hydraulic component specialists for position sensor recalibration and accumulator replacement. This channel fragmentation is most visible in North America, where Delta and United have shifted seat maintenance oversight from OEMs to specialized third-party facilities.
Aircraft Hydraulic Seat Actuation Systems Market Segmentation
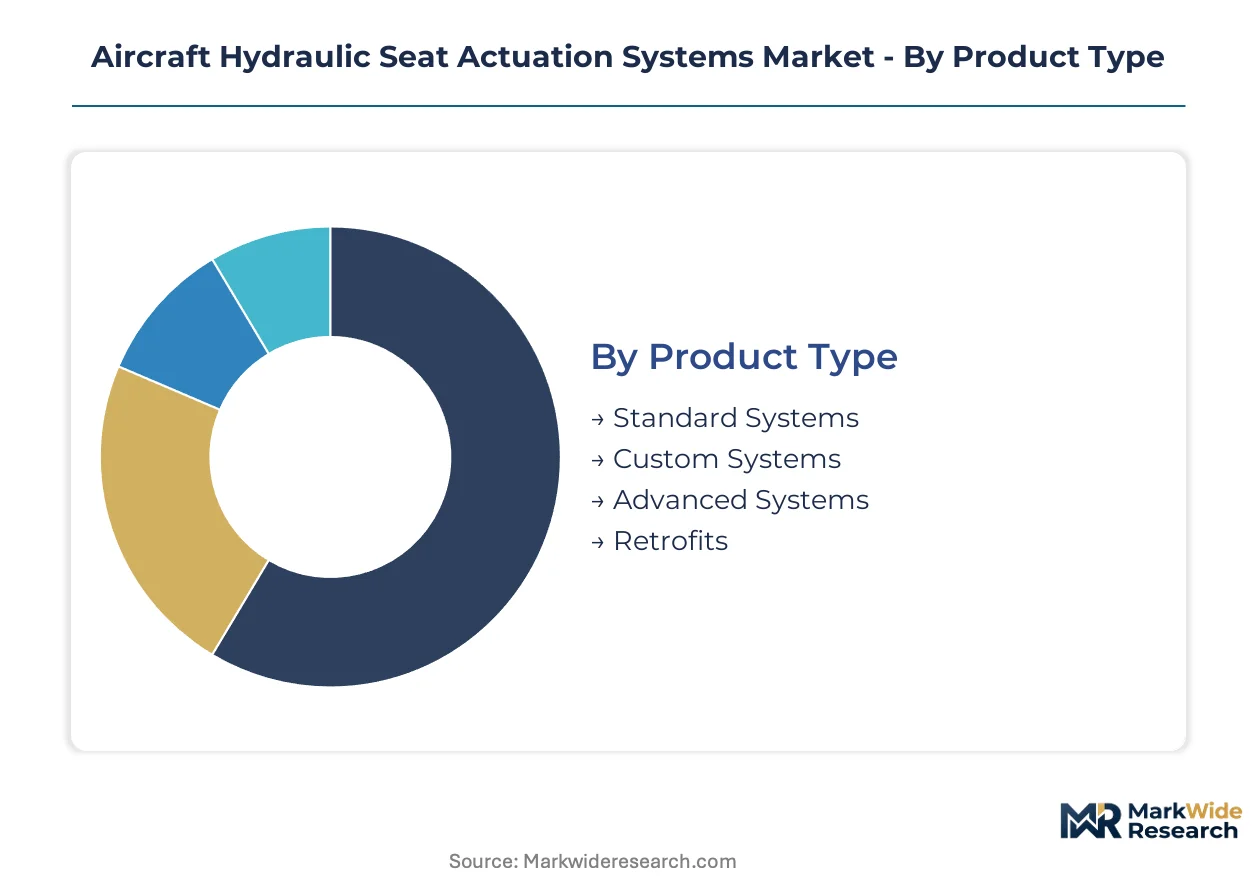
Hydraulic seat actuation architectures fragment across integration depth, from standalone mechanical units to fully embedded electro-hydraulic networks. Understanding these divisions exposes where certification burdens concentrate and which configurations capture premium pricing in fleet modernization cycles.
Product Type:
Standalone hydraulic modules serve basic adjustment functions, while embedded custom systems integrate with cabin management networks and predictive diagnostics.
- Standard Systems:Fixed-geometry actuation units with predefined stroke lengths and load ratings serve high-volume narrowbody configurations. Airlines in the United States specify these for economy cabin retrofits where FAA 14 CFR 25.562 compliance must balance cost against crash-energy absorption.
- Custom Systems:Tailored envelope geometries with servo-controlled positioning enable multi-axis articulation for lie-flat premium seating. Airframers specify unique hydraulic circuits for first-class suites on widebody platforms, concentrating margin capture among suppliers with in-house precision machining.
- Advanced Systems:Integrated sensor feedback and software-defined control modules support predictive maintenance algorithms.
- Retrofits:Drop-in replacement kits extend service life of legacy seat frames without full cabin reconfiguration.
Volume placements concentrate in Standard Systems; the faster expansion belongs to Custom Systems.
Application:
Platform-specific load profiles and duty cycles reshape hydraulic component specifications across fixed-wing and rotary-wing operations.
- Commercial Aircraft:Narrowbody and widebody fleets generate the dominant installed base, with 3,000 psi phosphate ester systems supporting passenger loads from taxi through turbulence. United States carriers drive retrofit demand as fleet age triggers mandatory seat replacement cycles under updated FAA dynamic testing protocols.
- Business Jets:Owner-operators in the United Arab Emirates and Saudi Arabia demand full-flat sleeping surfaces requiring multi-axis hydraulic articulation. These platforms prioritize weight reduction and silent operation over cost minimization.
- Military Aircraft:Extended service horizons for legacy hydraulic architectures create aftermarket refurbishment demand from US and allied defense fleets.
- Helicopters:Severe vibration environments necessitate hardened accumulators and redundant position sensing for crew seat crashworthiness.
Commercial Aircraft dominates current placements; Business Jets are climbing the fastest.
End User:
Procurement authority shifts between airframers, operators, and maintenance providers reshape contract structures and technical specification control.
- OEMs:Boeing and Airbus specifications govern first-fit hydraulic seat systems, with electro-hydraulic architectures now standard on next-generation narrowbody programs. These contracts demand dual-continent certification documentation for FAA and EASA compliance.
- Airlines:Delta and United have unbundled aftermarket seat maintenance from OEM service agreements, contracting directly with hydraulic component specialists for position sensor recalibration.
- Military:Defense procurement offices prioritize service life extension over technology refresh for legacy platform fleets.
- Maintenance Providers:Specialized MRO facilities now control accumulator replacement and servo valve overhaul workflows.
Contract value concentrates with OEMs; the steepest expansion trajectory sits with Maintenance Providers.
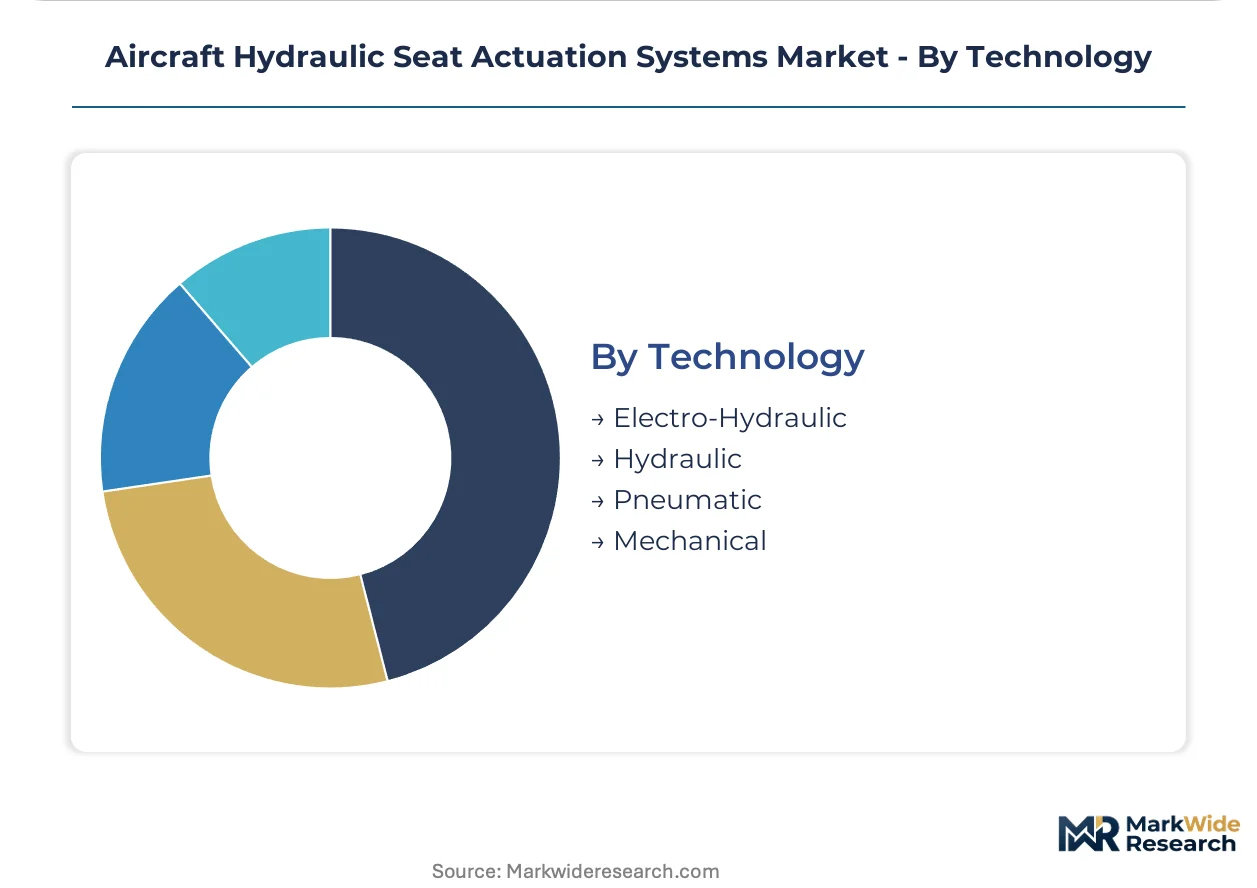
Technology:
Power transmission mechanisms range from purely fluid-driven to hybrid electromechanical architectures with embedded electronic control.
- Electro-Hydraulic:Electronically controlled servo valves achieve millimeter-level positioning precision under dynamic flight loads. Boeing and Airbus OEM specifications now prioritize this convergence, compressing the supplier base toward firms with dual competencies in fluid power and embedded systems.
- Hydraulic:Purely fluid-driven actuation persists in military platforms where extended service horizons and conservative certification cycles delay technology transition.
- Pneumatic:Compressed air systems serve limited auxiliary functions where fire resistance requirements are less stringent.
- Mechanical:Cable and linkage systems retain niche presence in legacy helicopter crew seating.
New installations favor Electro-Hydraulic; Hydraulic maintains largest legacy installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States and Western Europe, while fleet expansion in the Middle East and South Asia is accelerating consumption growth. Regulatory divergence between FAA and EASA certification protocols is fragmenting supplier qualification requirements across continents.
United States
Narrowbody retrofit cycles at Delta and United are driving aftermarket demand for crashworthy seat systems. FAA 14 CFR 25.562 mandates dynamic testing standards that compress supplier development timelines. Wichita, Kansas anchors precision hydraulics fabrication for military and commercial platforms.
Germany
Airbus A320-family production in Hamburg sustains first-fit demand for electro-hydraulic seat architectures. EASA CS 25.561 certification requirements parallel FAA standards, forcing redundant testing protocols. Bavaria hosts specialized servo valve machining clusters serving Tier-1 seat integrators.
United Arab Emirates
Business jet lie-flat conversions for owner-operators in Dubai and Abu Dhabi require multi-axis hydraulic articulation systems. The country's civil aviation regulator enforces seat crashworthiness aligned with international standards. Dubai South aerospace cluster is expanding MRO capacity for premium cabin retrofits.
India
IndiGo and Air India fleet expansion programs are generating first-fit demand for certified seating systems. The Directorate General of Civil Aviation mandates compliance with ICAO safety standards for imported seat assemblies. Bangalore's aerospace manufacturing corridor is attracting hydraulic component suppliers for offset partnerships.
Saudi Arabia
Private aviation growth in Riyadh and Jeddah is stimulating demand for luxury seat configurations with full-flat articulation. The General Authority of Civil Aviation oversees airworthiness certification for aftermarket installations. King Abdulaziz City for Science and Technology is funding local aerospace manufacturing initiatives.
Aircraft Hydraulic Seat Actuation Systems Market Vendor Landscape
Top-tier vendors anchor OEM first-fit contracts, while mid-tier specialists capture aftermarket refurbishment workflows. The supplier base compresses toward firms with dual competencies in fluid power and embedded control systems. Two strategic archetypes dominate: vertically integrated precision hydraulics manufacturers and flight control heritage firms extending into seating. Competitive moves center on backward integration into servo valve production and software-defined diagnostics licensing.
Among US-based incumbents, Moog Inc. and Parker Hannifin occupy positions reflecting flight control and distribution heritage respectively. Safran represents European manufacturing scale through captive supply of precision components. Crane Aerospace & Electronics exemplifies the diversified aerospace electronics archetype serving multiple cabin system categories.
| Leading Market Players |
|---|
| Moog Inc. |
| Astronics Corporation |
| Crane Aerospace & Electronics |
| ITT Inc. |
| Safran |
| Honeywell International Inc. |
| Parker Hannifin |
| Collins Aerospace |
| Bühler Motor GmbH |
| Others |
Supply Flow & Price Mechanics
Electro-hydraulic integration complexity is simultaneously elevating R&D cost structures and compressing the supplier base toward firms with dual competencies in fluid power and embedded systems. This technological convergence concentrates pricing power among vertically integrated precision hydraulics manufacturers while fragmenting procurement authority across OEMs, airlines, and specialized MRO providers.
Pricing Analysis
Cost-down pressure on standard systems accelerates because airline procurement teams unbundle aftermarket service contracts from initial hardware purchases. Three-tier pricing structure across custom, standard, and retrofit levels stratifies by certification grade and volume scale, with FAA 14 CFR 25.562 compliance tiers commanding premium positioning. Pricing pressure stems from electromechanical substitution threats in next-generation OEM programs. Narrowbody retrofit buyers exhibit highest price sensitivity; business jet owner-operators in the United Arab Emirates and Saudi Arabia demonstrate lowest sensitivity due to weight and silent operation priorities.
Supply Chain Analysis
Regional distribution centers in Wichita, Kansas and Hamburg, Germany anchor hub-and-spoke patterns serving North American and European airframer clusters. Precision-machined servo valve production concentrates in Germany, the United States, and France, drawing from specialty steel alloys, phosphate ester hydraulic fluids, and high-tolerance position sensors. Single-source vulnerability in European servo valve machining clusters creates structural risk. Distribution runs through OEM direct channels for first-fit contracts and specialized MRO facilities for aftermarket refurbishment workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FAA 14 CFR 25.562 dynamic testing standards erect barrier-to-entry moats favoring incumbent suppliers with established certification documentation and traceability infrastructure.
For Market Incumbents: Lock in aftermarket revenue streams by embedding software-defined diagnostics modules that enable performance-based service contracts with Delta, United, and other unbundling carriers. Deepen backward integration into servo valve production to mitigate European supply bottlenecks. Electromechanical substitution from Moog Inc. and integrated electromechanical seat architectures represents the core technology threat requiring R&D investment in hybrid electro-hydraulic control systems. For New Entrants and Emerging Players: Predictive maintenance algorithms offer a technology-first wedge into the maintenance provider channel where contract value expansion concentrates. Target Indian narrowbody expansion programs at IndiGo and Air India as the most penetrable geography, where first-fit demand for certified crashworthy seating systems outpaces established supplier capacity. Pursue offset partnerships with Bangalore's aerospace manufacturing corridor as the go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by flight control heritage firms seeking seating diversification or precision hydraulics roll-ups. Long-term viability favors suppliers with captive servo valve machining and dual-continent FAA-EASA certification infrastructure. Watch for electromechanical capture rates in next-generation Boeing and Airbus narrowbody programs as the inflection signal indicating hydraulic architecture obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Valve Production | Mitigates European supply bottlenecks and secures margin capture in custom systems. |
| Software-Defined Diagnostics Licensing | Enables recurring revenue streams through predictive maintenance contracts with unbundling airlines. |
| Dual-Continent Certification Investment | Creates competitive insulation against single-continent rivals serving Boeing and Airbus programs. |
| MRO Channel Partnership Expansion | Captures aftermarket refurbishment workflows as Delta and United shift maintenance oversight. |
| Electro-Hydraulic R&D Scale-Up | Defends against electromechanical substitution in next-generation narrowbody OEM specifications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hydraulic system engineering directors, airline fleet procurement managers, MRO facility operations heads, and precision machining specialists. FAA certification databases, EASA CS 25.561 submission records, and SAE ARP4754A compliance documentation provided regulatory traceability benchmarks. Bottom-up triangulation across component-level bill-of-materials analysis converged with top-down airframe production forecasts.
Data-stream reconciliation across OEM delivery schedules, fleet retrofit cycle announcements, and aftermarket contract awards calibrated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type integration depth, platform application, end-user procurement authority, and technology architecture. CAGRs derived from fitted growth curves against historical installation patterns and fleet age demographics. Industry-specific inputs incorporated phosphate ester hydraulic fluid specifications and 3,000 psi operating pressure standards.
Several conditions sit outside the modeled scope, including military platform classified procurement volumes and speculative next-generation airframe program launch dates. Forecasts reflect documented assumptions around fleet modernization timelines and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market