
 Commercial Aircraft Honeycomb Core Market | 2026-2036
Commercial Aircraft Honeycomb Core Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Honeycomb Core Market Insights
Advanced specification-grade honeycomb core is bifurcating the commercial aircraft supply base. Hexcel Corporation leverages its integrated carbon fiber and composite core portfolio to dominate qualification-intensive programs. Plascore, Inc anchors North American aftermarket demand through specialized repair-grade cell geometries.
Commercial aircraft honeycomb core consists of bonded hexagonal cell structures manufactured from aluminum foil, aramid paper, or thermoplastic resin, engineered to deliver high stiffness-to-weight ratios in sandwich panel configurations. Cell wall thicknesses range from 0.001 to 0.005 inches with densities between 1.5 and 15 pounds per cubic foot, enabling tailored crush resistance and shear modulus for primary and secondary aerostructures. Nomex honeycomb leads fuselage and interior applications where flame-smoke-toxicity compliance governs selection, while aluminum honeycomb retains cost advantages in non-pressurized control surfaces. Thermoplastic honeycomb represents the fastest-expanding category as out-of-autoclave processing gains traction among Tier 1 aerostructure suppliers seeking cycle time reduction.
FAA airworthiness standards under Part 25, EASA CS-25 certification requirements, and ISO 9705 reaction-to-fire testing collectively dictate material qualification pathways and OEM approval timelines. These frameworks elevate barriers for uncertified entrants while rewarding incumbents with sustained type certificate amendments and supplemental type certificate authority. Stakeholders must monitor emerging sustainable aviation fuel compatibility requirements and their downstream implications for thermal management in next-generation composite architectures.
Market Dynamics
Out-of-autoclave processing is compressing qualification timelines for thermoplastic honeycomb cores, forcing incumbent suppliers to revalidate legacy aramid-based portfolios while Tier 1 aerostructure manufacturers reconfigure capital equipment footprints.
Growth Catalysts
- Narrow-body production ramp:Boeing 737 MAX and Airbus A320neo assembly rates drive specification-grade honeycomb consumption for flight control surfaces and interior monuments. OEM qualification locks create multi-year offtake commitments.
- FAA Part 25 flammability amendments:Revised fire-smoke-toxicity testing protocols under Appendix F mandate next-generation phenolic resin systems, accelerating material substitution cycles in retrofit programs.
- Aramid fiber supply localization:DuPont and Teijin capacity expansions in the United States and Japan reduce import dependency for Nomex honeycomb precursor materials, stabilizing input cost structures.
Market Restraints
- Aluminum foil price volatility:LME aluminum fluctuations between 2022 and 2024 compressed margins for commodity-grade honeycomb producers serving non-pressurized applications.
- Single-source aramid paper dependency:DuPont maintains effective monopoly on aerospace-grade Nomex substrate, creating concentration risk for qualified cell geometries.
- Thermoset processing limitations:Autoclave cure cycles exceeding four hours constrain throughput for legacy phenolic-impregnated honeycomb, disadvantaging capacity-constrained suppliers against thermoplastic alternatives.
Strategic Opportunities
- Urban air mobility airframes:eVTOL manufacturers require damage-tolerant core configurations for composite fuselage structures, opening qualification pathways outside traditional Part 25 certification frameworks.
- Sustainable aviation fuel thermal management:Higher combustion temperatures from SAF blends necessitate improved core-to-skin thermal conductivity in engine nacelle applications.
- Direct-to-MRO distribution channels:Specialized repair-grade cell geometries bypass OEM-approved vendor lists for supplemental type certificate modifications, capturing aftermarket margin pools.
Industry Challenges
- Composite technician certification gaps:FAA repair station requirements for bonded sandwich structures outpace vocational training program throughput, constraining MRO capacity expansion.
- Type certificate amendment timelines:OEM validation of alternative core materials for existing airframe programs requires 18-36 month qualification cycles, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Honeycomb Core Market |
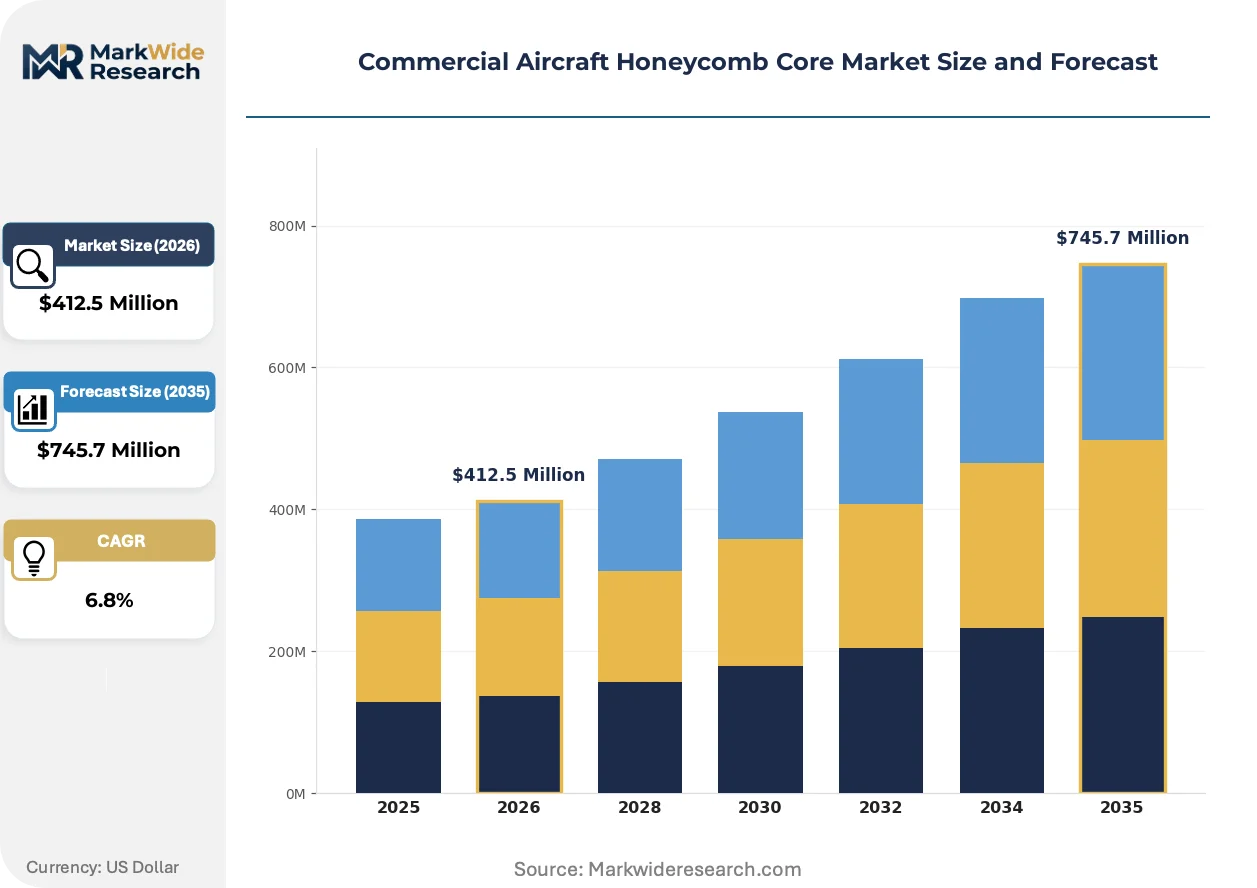
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Honeycomb, Nomex Honeycomb, Thermoplastic Honeycomb, Titanium Honeycomb, Composite Honeycomb Core Size: 1/8 inch, 1/4 inch, 3/8 inch, 1/2 inch, Custom Dimensions Application: Fuselage Panels, Wing Structures, Floor Panels, Tail Assemblies, Interior Components End Use Customer: Aircraft Manufacturers, Maintenance Repair Organizations, Aerospace Suppliers, Engineering Firms |
| Companies Covered | Hexcel Corporation, Plascore, Inc, Euro-Composites S.A, The Gill Corporation, Toray Industries, Inc, Corex Honeycomb, TenCate Advanced Composites, Core Composites, EconCore NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Honeycomb Core Market Trends and Innovations
Material processing and certification frameworks are converging to redefine competitive positioning in aerospace-grade cellular structures. Three developments warrant particular attention from supply chain stakeholders.
Thermoplastic honeycomb core is miniaturizing cell geometries below 1/8-inch configurations while maintaining shear strength parity with legacy aramid alternatives. Tier 1 suppliers including Spirit AeroSystems and GKN Aerospace are qualifying these materials for wing fixed trailing edge panels, displacing thermoset prepregs in high-rate production environments. The technology is miniaturizing processing equipment footprints, enabling cell manufacturing co-location with aerostructure assembly lines rather than centralized core production.
EASA CS-25 amendments incorporating ISO 9705 full-scale fire test protocols are extending qualification timelines for interior applications. European OEMs now require supplemental smoke density documentation beyond FAA Appendix F minimums, creating bifurcated certification pathways for global suppliers. Cabin monument manufacturers serving dual-certification programs face expanded testing budgets and extended program gates.
Airline procurement organizations are consolidating specification authority at fleet technical services divisions, compressing supplier negotiation cycles. Long-term material agreements with cell manufacturers now bypass traditional distributor intermediaries for high-volume narrow-body programs. This concentration is most visible among low-cost carriers operating standardized 737 MAX fleets, where technical procurement teams negotiate direct mill relationships for repair station networks.
Commercial Aircraft Honeycomb Core Market Segmentation
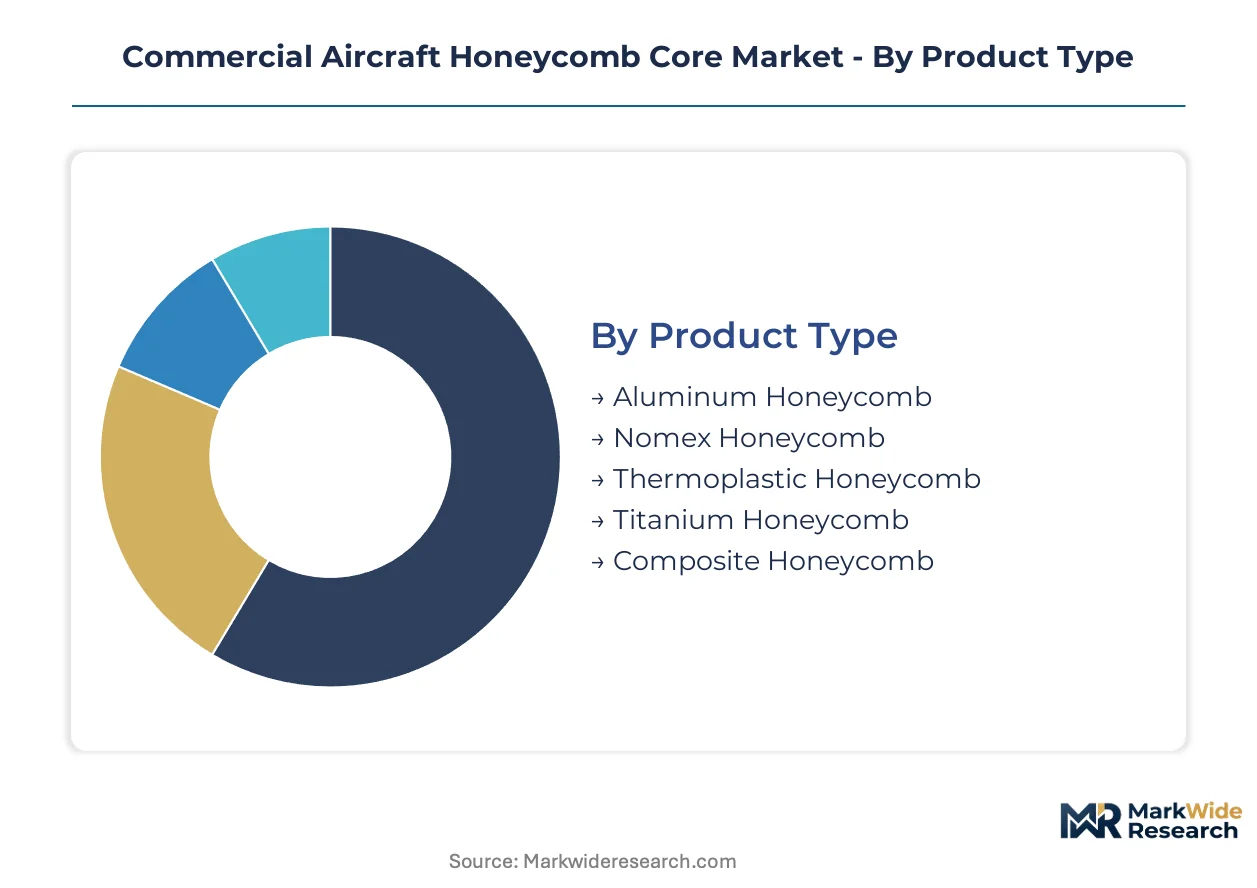
Segmentation in commercial aircraft honeycomb core markets reveals how material specifications, cell geometries, and certification requirements channel demand through distinct procurement pathways. Understanding these divisions exposes where qualification investments concentrate and where aftermarket margin pools form.
Product Type:
Channel flows diverge sharply by material chemistry: aramid-based cores move through OEM-approved vendor lists with multi-year offtake agreements, while aluminum grades reach MRO distributors through spot-market procurement.
- Nomex Honeycomb:Aramid fiber paper impregnated with phenolic resin delivers flame-smoke-toxicity compliance for pressurized cabin applications. Boeing and Airbus narrow-body programs in the United States and France anchor specification-grade procurement through locked supplier qualifications. FAA Part 25 Appendix F amendments accelerate material substitution toward next-generation resin systems.
- Thermoplastic Honeycomb:Polyetherimide and polyphenylsulfide cell walls enable out-of-autoclave processing with sub-30-minute cycle times. Spirit AeroSystems and GKN Aerospace facilities in Kansas and Bristol are qualifying these cores for wing fixed trailing edge panels. The segment climbs the fastest as Tier 1 suppliers reconfigure capital equipment footprints.
- Aluminum Honeycomb:5052 or 5056 aluminum foil bonded with epoxy adhesives retains cost advantages in non-pressurized control surfaces and repair applications.
- Titanium Honeycomb:CP Grade 1 or Grade 2 titanium foil construction serves engine nacelle and exhaust fairing applications requiring elevated temperature resistance.
- Composite Honeycomb:Hybrid fiber-reinforced thermoset or thermoplastic cell walls address specialized stiffness requirements in satellite launch vehicle adapter structures.
By volume, Nomex honeycomb leads through entrenched OEM qualifications. By growth pace, thermoplastic alternatives are ahead.
Core Size:
Cell dimension selection tracks structural loading requirements: smaller cells concentrate in primary aerostructures demanding high shear modulus, while larger configurations dominate secondary applications where weight reduction outweighs stiffness optimization.
- 1/8 inch:Miniaturized cell geometry delivers maximum specific shear strength for wing fixed leading edges and control surface skins. Airbus A350 and Boeing 787 programs in France and the United States specify this dimension for high-rate production environments.
- 1/4 inch:The most widely specified cell size balances manufacturing yield with structural performance across floor panels and interior monuments. Narrow-body assembly lines in Renton and Toulouse standardize on this geometry to minimize inventory complexity.
- 3/8 inch:Intermediate sizing serves cargo compartment liners and non-structural fairings where crush resistance governs selection.
- 1/2 inch:Large cell configurations reduce core weight in low-load interior applications including overhead bin shells and galley structures.
- Custom Dimensions:Non-standard cell geometries address repair station requirements for supplemental type certificate modifications and damage-tolerant patch configurations.
By installed volume, 1/4 inch cells dominate. By specification expansion, 1/8 inch miniaturization is gaining share fastest.
Application:
Application segmentation maps directly to certification burden: primary structure qualifications require 18-36 month OEM validation cycles, while interior applications face accelerated FAA Part 25 Appendix F amendment timelines.
- Wing Structures:Fixed trailing edge panels and control surfaces demand specification-grade cores with documented fatigue life under cyclic loading. Boeing 737 MAX and Airbus A320neo production rates in Washington State and Hamburg drive concentrated offtake commitments.
- Fuselage Panels:Pressure-bearing sandwich constructions require damage tolerance certification under FAA Part 25.571 damage tolerance criteria. Wide-body programs in South Carolina and Toulouse anchor demand for large-format core sheets.
- Floor Panels:High-load bearing surfaces in passenger and cargo compartments specify crush-resistant cell configurations with demonstrated post-impact residual strength.
- Tail Assemblies:Horizontal and vertical stabilizer skins employ optimized density gradients to manage aerodynamic flutter characteristics.
- Interior Components:Cabin monuments, lavatories, and galleys prioritize flame-smoke-toxicity compliance over structural loading, enabling broader qualified supplier bases.
By revenue concentration, wing structures lead. By qualification velocity, interior components are expanding most quickly.
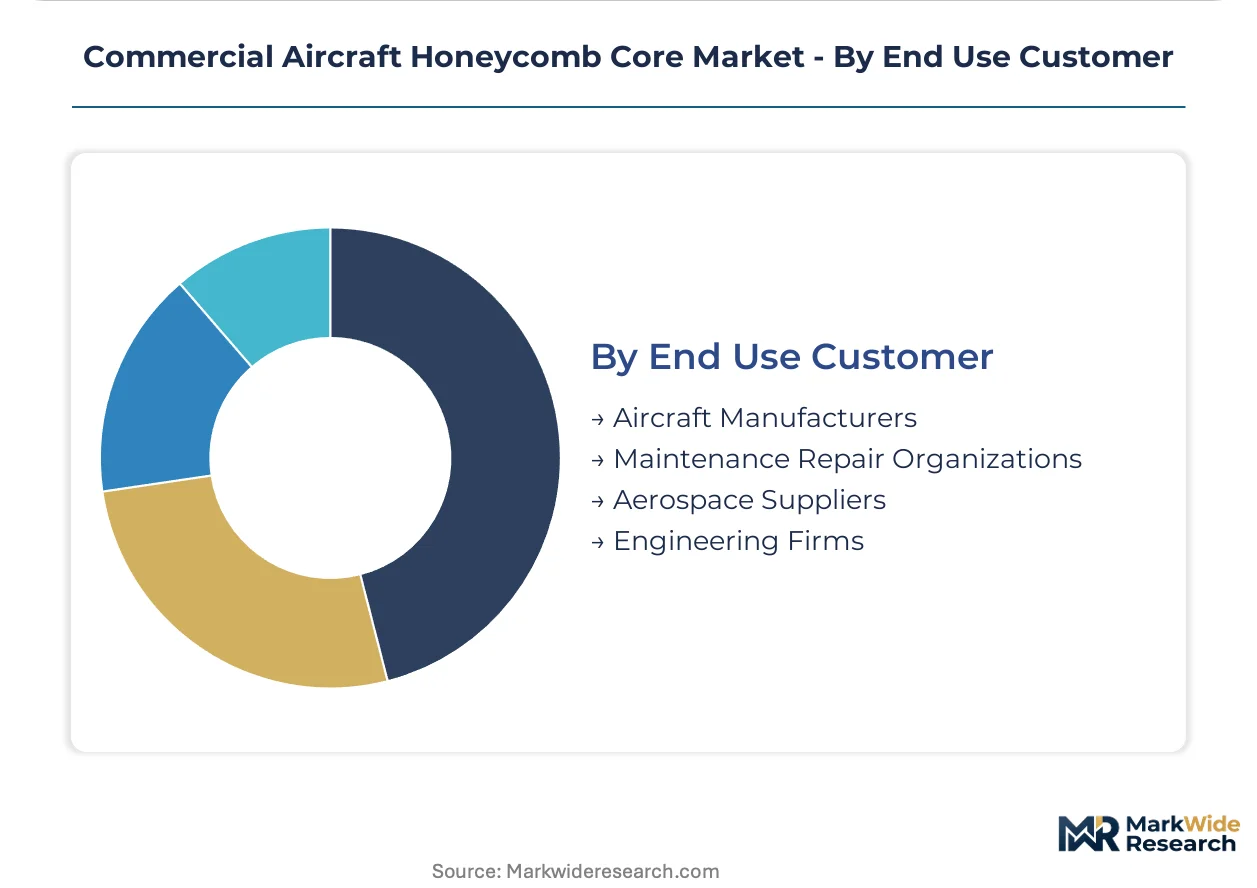
End Use Customer:
Customer type determines contract structure: aircraft manufacturers negotiate multi-year material agreements with price-volume bands, while MRO procurement operates through approved vendor lists with spot-buy flexibility.
- Aircraft Manufacturers:Boeing, Airbus, and Embraer assembly operations specify qualified core materials through integrated supply chain agreements. Direct mill relationships bypass traditional distributor intermediaries for high-volume narrow-body programs.
- Maintenance Repair Organizations:FAA-certified repair stations and EASA Part 145 organizations procure repair-grade cell geometries for damage remediation and supplemental type certificate modifications. Southwest Airlines and Ryanair technical services divisions consolidate specification authority for standardized fleet configurations.
- Aerospace Suppliers:Tier 1 aerostructure manufacturers including Spirit AeroSystems and GKN Aerospace qualify core materials for subassembly integration.
- Engineering Firms:Design consultancies specify core materials for prototype development and custom modification programs outside standard OEM catalogs.
By procurement volume, aircraft manufacturers lead. By margin expansion, MRO channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in aerospace-grade honeycomb core tilt heavily toward manufacturing jurisdictions with established OEM assembly footprints. The United States, France, Germany, Japan, and China concentrate both production capacity and qualification authority, creating distinct regional supply hierarchies.
United States
Boeing 737 MAX and 787 production lines in Renton and Charleston drive specification-grade Nomex honeycomb consumption through locked supplier qualifications. FAA Part 25 Appendix F flammability amendments accelerate material substitution cycles for retrofit programs. Wichita, Kansas hosts Spirit AeroSystems facilities where thermoplastic core qualification for wing structures is advancing fastest.
France
Airbus A320neo and A350 final assembly in Toulouse anchors European demand for aramid-based honeycomb in fuselage and interior applications. EASA CS-25 amendments incorporating ISO 9705 full-scale fire test protocols extend qualification timelines for cabin monument suppliers. The Toulouse-Blagnac aerospace cluster concentrates Tier 1 aerostructure integration capabilities.
Germany
Airbus wing component manufacturing in Hamburg and Bremen drives specialized core demand for fixed trailing edge panels. German aerospace suppliers navigate dual FAA-EASA certification requirements for export-oriented programs. The Hamburg Finkenwerder facility qualifies damage-tolerant core configurations for next-generation narrow-body programs.
Japan
Toray Industries' integrated carbon fiber and composite core portfolio supports Boeing and Airbus supply chain requirements through Japanese manufacturing partnerships. METI industrial policy prioritizes aerospace materials localization to reduce import dependency. Nagoya's Chubu region concentrates autoclave and out-of-autoclave processing capabilities for Tier 2 aerostructure suppliers.
China
COMAC C919 production ramp and narrow-body import substitution programs stimulate domestic honeycomb core qualification efforts. MIIT standards harmonization with FAA and EASA frameworks accelerates material certification pathways for indigenous airframe programs. Xi'an and Shanghai aerospace clusters develop thermoplastic core manufacturing capabilities for regional jet applications.
Commercial Aircraft Honeycomb Core Market Competitive Landscape
Concentration sits with integrated composite material suppliers possessing qualification-intensive OEM relationships and captive precursor supply. The vendor base separates into three tiers: multinational carbon fiber-honeycomb integrators, specialized cellular structure fabricators, and regional repair-grade suppliers. Dominant competitive moves include backward integration into aramid fiber precursor production and geographic co-location with Tier 1 aerostructure assembly facilities.
Within the integrated materials tier, Hexcel Corporation and Toray Industries occupy positions spanning carbon fiber, resin systems, and qualified honeycomb configurations. Plascore, Inc exemplifies the specialized fabricator archetype focused on repair-grade cell geometries and aftermarket distribution channels. Euro-Composites S.A represents European-based qualification holders navigating bifurcated FAA-EASA certification requirements.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Plascore, Inc |
| Euro-Composites S.A |
| The Gill Corporation |
| Toray Industries, Inc |
| Corex Honeycomb |
| TenCate Advanced Composites |
| Core Composites |
| EconCore NV |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Boeing, Airbus, and qualified honeycomb suppliers lock in multi-year price visibility while securing production slots for specification-grade Nomex and thermoplastic cores. These contracts insulate Tier 1 aerostructure manufacturers from aluminum foil commodity volatility while embedding volume-price bands that reward scale commitments from narrow-body program procurement teams.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command qualification-intensive aramid cores with locked OEM approvals, while standard grades serve Tier 1 subassembly contracts and economy tiers capture spot-market aluminum honeycomb for non-pressurized repair applications. Price differentiation rests on FAA Part 25 certification status and DuPont Nomex substrate access. Pricing pressure stems from thermoplastic core cycle-time advantages compressing legacy phenolic-impregnated margins. Low-cost carriers operating standardized 737 MAX fleets exhibit highest price sensitivity through consolidated technical procurement negotiations.
Supply Chain Analysis
The United States and France anchor specification-grade honeycomb production, with Germany and Japan feeding specialized wing component and carbon fiber integration capabilities. Raw material dependencies draw from DuPont aramid fiber precursor, LME-traded aluminum foil, and Toray Industries carbon fiber portfolios. Single-source vulnerability concentrates in aerospace-grade Nomex substrate supply. Distribution runs through OEM-approved vendor lists for original equipment, bypassing traditional intermediaries, while MRO channels utilize spot-buy flexibility through specialized repair-grade distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Narrow-body production ramp cycles position this market for recovery, with Boeing 737 MAX and Airbus A320neo assembly rate normalization driving specification-grade honeycomb demand through locked supplier qualifications.
For Market Incumbents: Compound qualification authority through captive precursor supply and geographic co-location with Tier 1 aerostructure assembly facilities. Threats from thermoplastic core displacement of legacy phenolic-impregnated portfolios demand accelerated out-of-autoclave processing validation. Priority levers include backward integration into aramid fiber precursor production and capacity reservation agreements with Spirit AeroSystems and GKN Aerospace facilities. For New Entrants and Emerging Players: Anchor in urban air mobility airframe qualifications outside traditional FAA Part 25 certification frameworks, where eVTOL manufacturers seek damage-tolerant core configurations. The most penetrable white space sits in direct-to-MRO distribution channels for supplemental type certificate modifications. Go-to-market execution should target repair station networks with specialized cell geometries bypassing OEM-approved vendor lists. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated composite material suppliers possessing locked OEM relationships and captive precursor supply. Long-term viability over a multi-year horizon favors acquisition targets with sustained type certificate amendment authority and geographic positioning within Boeing-Airbus supply chain clusters. The signal to watch is thermoplastic core qualification velocity at Tier 1 aerostructure facilities as an inflection indicator for material substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Precursor | DuPont Nomex supply concentration creates captive sourcing advantages for qualified cell manufacturers. |
| Out-of-Autoclave Processing Qualification | Thermoplastic core cycle-time reduction displaces legacy phenolic-impregnated portfolios at Spirit AeroSystems. |
| Geographic Co-location with Tier 1 Assembly | Wichita and Bristol facility proximity compresses logistics costs for wing fixed trailing edge panel programs. |
| Direct-to-MRO Distribution Channel | Southwest Airlines and Ryanair technical services divisions consolidate specification authority for standardized fleets. |
| eVTOL Qualification Pathway Development | Urban air mobility airframes open certification frameworks outside traditional FAA Part 25 damage tolerance criteria. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA type certificate amendments, EASA CS-25 certification databases, and OEM supplier qualification records. Primary interviews engaged aerostructure procurement directors, composite material R&D leads, MRO repair station managers, and honeycomb manufacturing plant engineers. Secondary validation drew from SEC 10-K filings of integrated composite suppliers, aerospace trade customs data, and ISO 9705 fire testing documentation. Bottom-up volume modeling triangulated against top-down OEM production rate disclosures.
Segmentation dimensions modeled include material chemistry tier, cell geometry specification, application structural classification, and end-use customer type across the projection horizon. CAGRs derived from production rate forecasts for Boeing 737 MAX, Airbus A320neo, and emerging COMAC C919 programs, cross-referenced with thermoplastic core adoption curves at Tier 1 aerostructure facilities. Industry-specific inputs incorporated FAA Part 25 Appendix F amendment timelines and EASA ISO 9705 protocol adoption rates.
Underlying assumptions cover narrow-body production rate normalization and aramid fiber supply localization, with deviation risk concentrated in aluminum foil commodity volatility and thermoplastic core qualification delays. Recalibration cycles align with material shifts in FAA airworthiness directive issuance and OEM supplier consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market