
 Liquid Hydrogen-Powered Aircraft Market | 2026-2036
Liquid Hydrogen-Powered Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Hydrogen-Powered Aircraft Market Insights
The capital-intensity divergence between full-system integrators and component specialists is redrawing competitive boundaries in liquid hydrogen aviation. Airbus SE leverages its existing airframe certification infrastructure to anchor development timelines for hydrogen-combustion demonstrators. H2FLY specializes in fuel-cell powertrain integration, sustaining German leadership in flight-test milestones. ZeroAvia Inc competes through powertrain retrofit architectures designed for existing regional airframes.
Liquid hydrogen-powered aircraft utilize cryogenic hydrogen stored at minus 253 degrees Celsius, vaporized and fed into modified gas turbines or fuel cells to generate thrust or electrical power for propulsion. The technology targets decarbonization of medium-haul aviation where battery weight renders all-electric propulsion impractical. Regional jets dominate current development pipelines, with cryogenic tank systems absorbing disproportionate engineering resources due to boil-off management and structural integration complexity. Freight carriers represent an emerging end-user segment where route predictability and centralized refueling infrastructure offset higher capital costs.
The FAA and EASA maintain parallel certification frameworks for hydrogen propulsion systems, with EASA's special condition publications currently shaping design standards for cryogenic tank crashworthiness. Japan's METI coordinates domestic hydrogen aviation roadmaps with JIS standards development for ground fueling protocols. Stakeholders must monitor which regulator achieves full certification reciprocity first, as that jurisdiction will attract disproportionate flight-test investment and early fleet deployment commitments.
Market Dynamics
The EU Green Deal's ReFuelEU Aviation mandate is compressing fleet procurement timelines, forcing operators to pre-commit to zero-emission platforms before synthetic fuel quotas harden. This regulatory pressure is bifurcating development resources between hydrogen-combustion retrofits and clean-sheet fuel-cell architectures.
Growth Catalysts
- Japan's METI funding mechanism:Accelerated domestic certification timelines for hydrogen-ready regional jets are pulling forward fleet deployment schedules. Airlines in Tokyo and Osaka are expanding pre-orders to secure early delivery slots.
- Cryogenic tank engineering breakthroughs:Advances in vacuum-insulated structural integration are reducing boil-off rates below 1% per day. German test corridors are validating these systems at altitude.
- Freight route predictability:Cargo carriers with fixed hub-and-spoke networks are absorbing higher capital costs through centralized liquid hydrogen refueling infrastructure at major sorting facilities.
Market Restraints
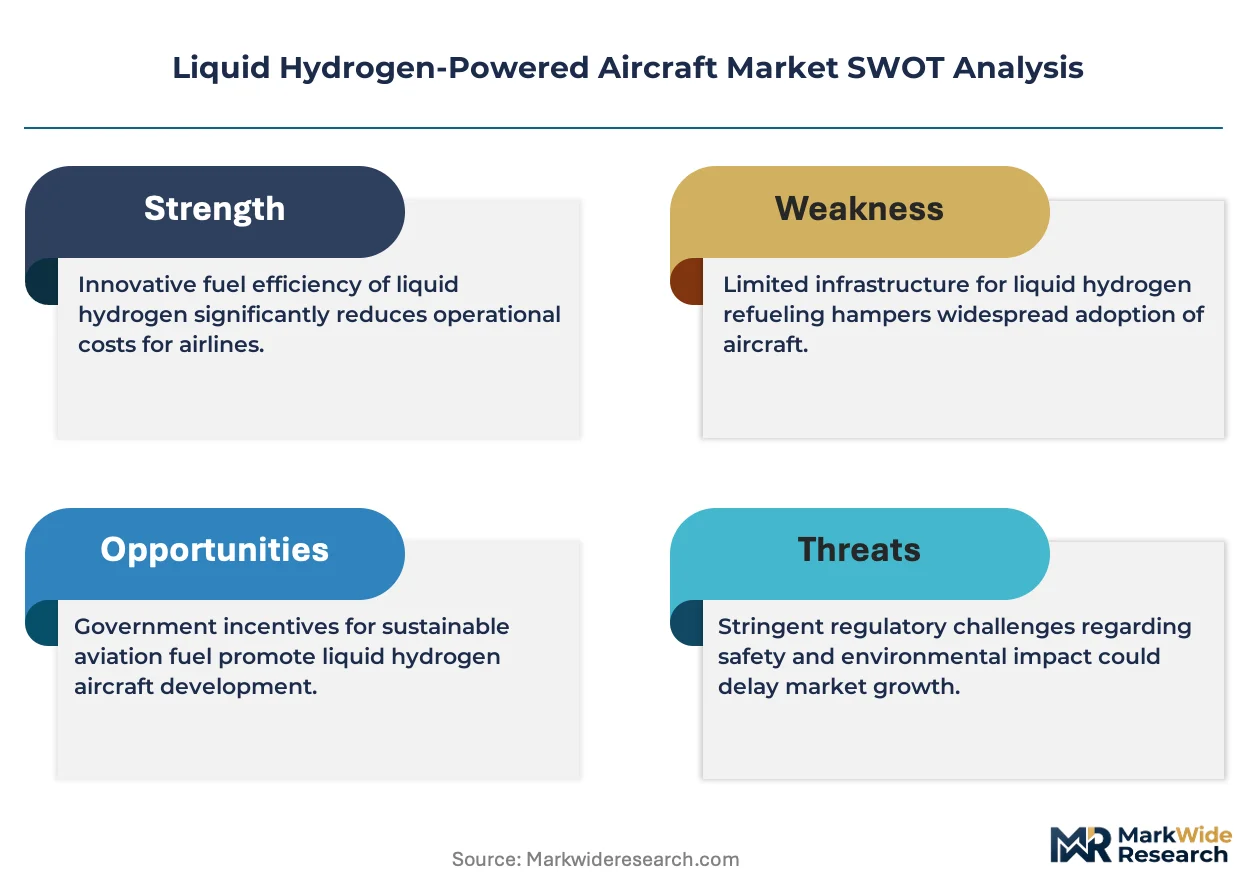
- Liquid hydrogen production cost volatility:Electrolyzer capacity constraints and renewable electricity price swings are compressing fuel cost predictability for operators.
- EASA-FAA certification divergence:Parallel special condition frameworks for cryogenic tank crashworthiness are forcing duplicate test programs and timeline uncertainty.
- Battery-electric substitution threat:Solid-state battery density improvements below 500 nautical miles are capturing short-haul routes that hydrogen targets.
Strategic Opportunities
- Underpenetrated UAE freight corridors:Emirates and Etihad Cargo are evaluating liquid hydrogen for Dubai-Abu Dhabi feeder routes with government-backed hydrogen hub investments.
- Convergence of fuel-cell stacks and cryogenic cooling:Integrated thermal management systems are opening weight reductions in powertrain packaging.
- India's PLI scheme for green hydrogen:Domestic production subsidies are creating feedstock cost advantages for future aviation offtake agreements.
Industry Challenges
- Cryogenic systems engineering talent scarcity:Specialized expertise in minus 253-degree Celsius storage and vaporization is concentrating among a handful of German and Japanese research institutes.
- Ground fueling protocol standardization delays:JIS standards development in Japan is running ahead of ICAO harmonization, creating equipment interoperability risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Hydrogen-Powered Aircraft Market |
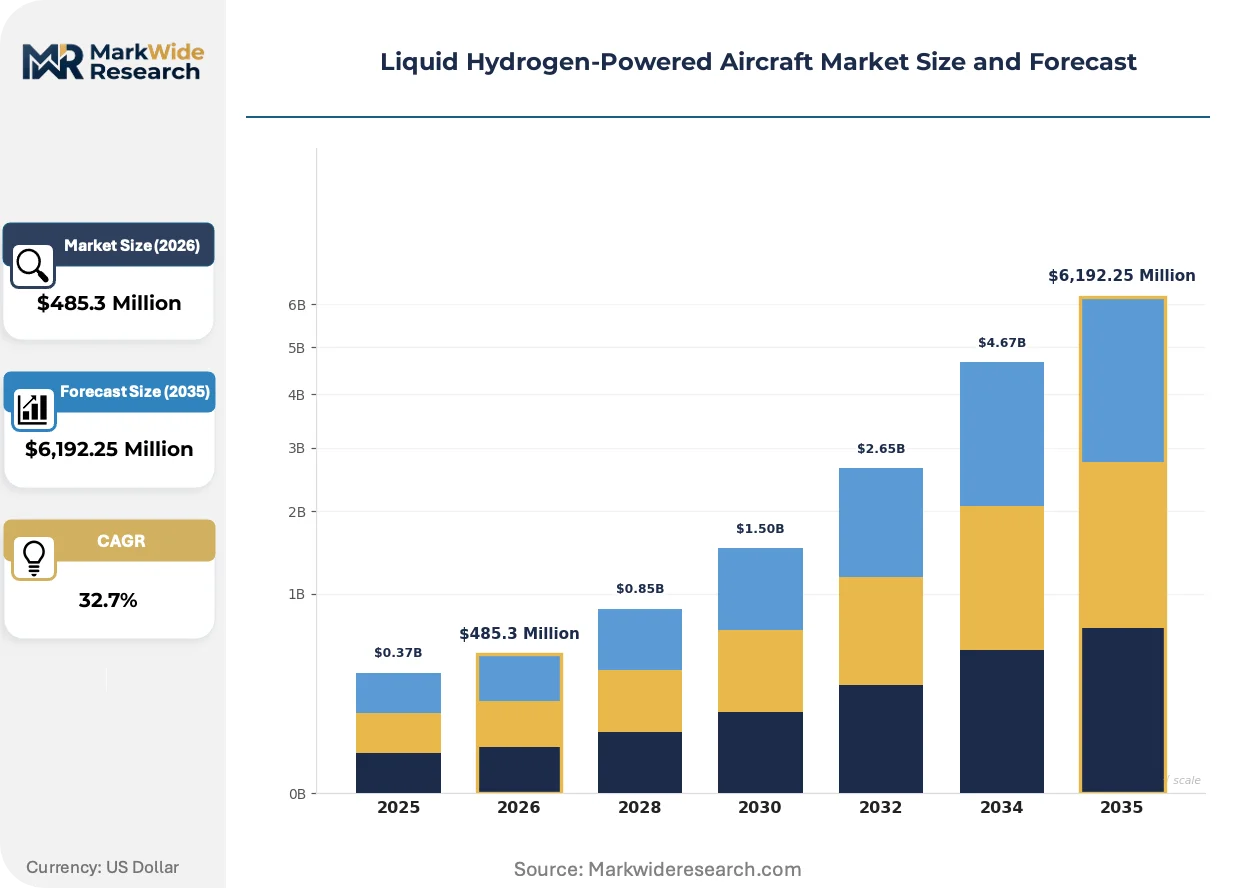
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $6,192.25 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Regional Jets, Narrow-body, Wide-body, Cargo Planes, Business Jets Fuel Storage Technology: Cryogenic Tanks, Composite Cylinders, Insulated Dewars, Metal Hydrides End User: Airlines, Freight Carriers, Leasing Companies, Government Agencies Application: Passenger Transport, Air Cargo, Pilot Training, Research Flights |
| Companies Covered | Airbus SE, GKN Aerospace, ZeroAvia Inc, Urban Aeronautics Ltd, AeroDelft, Pipistrel, H2FLY, HES Energy Systems, Alaka'i Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Hydrogen-Powered Aircraft Market Trends and Innovations
Propulsion architecture is splitting between modified gas turbines and fuel-cell electric systems, with each path demanding incompatible supply chain investments. This divergence is fragmenting engineering talent and test infrastructure commitments.
Cryogenic hydrogen storage is bifurcating between integrated wing tank designs and fuselage-mounted cylindrical systems. Regional jet manufacturers in Germany are adopting wing-integrated solutions to preserve cabin volume, while retrofit specialists favor fuselage mounting for airframe compatibility. This technical split is concentrating engineering resources in divergent certification pathways and compressing interoperability between platforms.
EASA's special condition publications on cryogenic tank crashworthiness are mandating new structural fire containment standards that exceed existing kerosene requirements. Aircraft OEMs must demonstrate 15-minute thermal protection in post-crash scenarios. German and French test facilities are absorbing disproportionate validation workloads as EASA leads rulemaking ahead of FAA alignment.
Freight carrier procurement committees are unbundling airframe and powertrain sourcing decisions that legacy passenger jet contracts treated as integrated packages. Cargo operators in the Middle East are negotiating separate tank system and engine contracts to accelerate retrofit timelines. This pattern is most visible in Dubai and Abu Dhabi, where Emirates SkyCargo and Etihad Cargo are piloting split-vendor structures for hydrogen-ready freighters.
Liquid Hydrogen-Powered Aircraft Market Segmentation
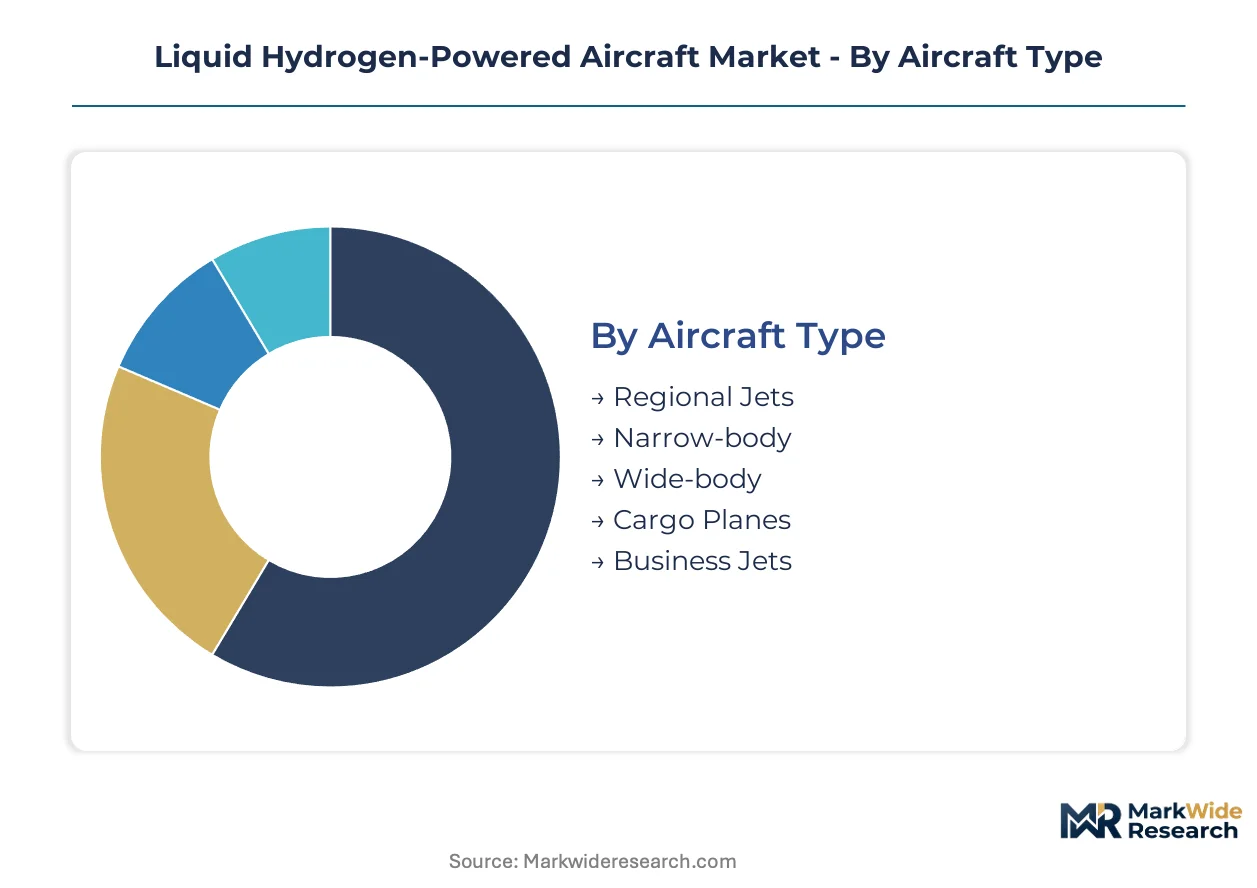
Liquid hydrogen aviation development concentrates investment in segments where energy density requirements exclude battery alternatives. Segmentation reveals which airframes justify cryogenic infrastructure costs and which end-users absorb operational complexity premiums.
Aircraft Type:
Substitution pressure from solid-state batteries concentrates most intensely on shorter-haul segments, leaving medium-range categories as the primary hydrogen battleground.
- Regional Jets:Cryogenic tank integration dominates engineering priorities for 50-100 seat platforms. German test corridors validate wing-integrated storage designs that preserve cabin volume. Airlines in Japan are expanding pre-orders to secure early delivery slots as METI funding accelerates domestic certification.
- Cargo Planes:Fixed hub-and-spoke networks enable centralized liquid hydrogen refueling infrastructure at major sorting facilities. Emirates SkyCargo and Etihad Cargo in the UAE are piloting split-vendor procurement structures to accelerate retrofit timelines.
- Narrow-body:Single-aisle platforms face battery substitution threats below 500 nautical miles.
- Wide-body:Long-haul range requirements exceed current cryogenic tank gravimetric efficiency.
- Business Jets:Low-volume production limits dedicated hydrogen platform development.
Regional jets retain volume leadership; cargo planes hold the steepest expansion curve.
Fuel Storage Technology:
Cost tier stratification separates billion-dollar cryogenic development programs from lower-capital composite alternatives.
- Cryogenic Tanks:Vacuum-insulated structural integration achieves boil-off rates below 1% per day. EASA special conditions mandate 15-minute thermal protection in post-crash scenarios, concentrating validation workloads in German and French test facilities.
- Composite Cylinders:Fuselage-mounted architectures dominate retrofit compatibility requirements. ZeroAvia's powertrain integration programs favor cylindrical geometries for existing regional airframe adaptation.
- Insulated Dewars:Ground support equipment applications outpace flight-qualified deployment.
- Metal Hydrides:Gravimetric density penalties restrict aviation uptake despite ambient temperature storage advantages.
Cryogenic tanks command the premium tier; composite cylinders scale most rapidly through retrofit channels.
End User:
Customer type determines procurement risk tolerance and infrastructure investment sequencing.
- Freight Carriers:Route predictability enables dedicated refueling infrastructure amortization across fixed networks. Cargo operators unbundle airframe and powertrain sourcing decisions that legacy passenger contracts treated as integrated packages.
- Airlines:ReFuelEU Aviation mandates force zero-emission platform pre-commitments before synthetic fuel quotas tighten. Fleet operators face compressed procurement timelines across Germany, France, and Nordic markets.
- Leasing Companies:Residual value uncertainty delays portfolio hydrogen exposure.
- Government Agencies:Research flight programs absorb technology demonstration risks.
Freight carriers lead infrastructure commitment; airlines face the steepest regulatory compliance pressure.
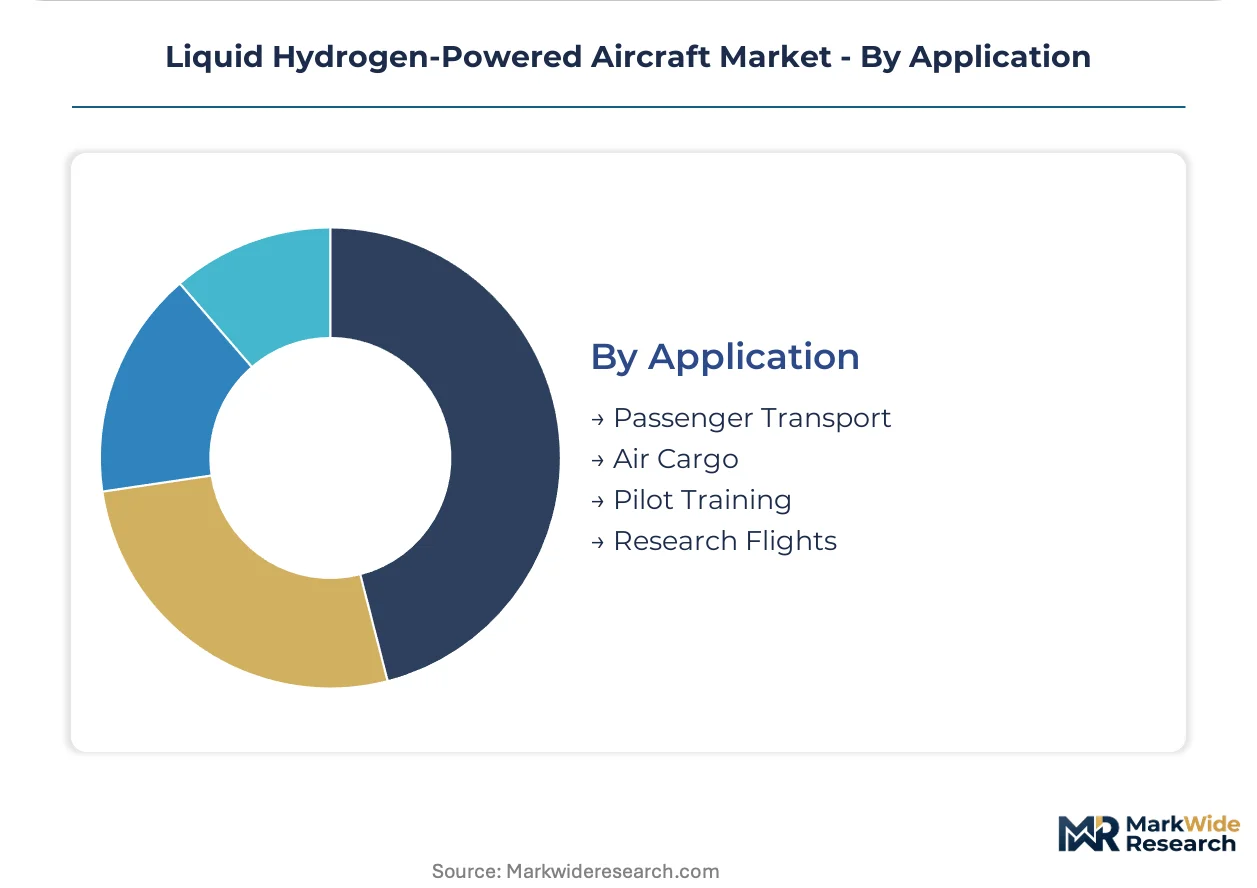
Application:
Volume concentration tracks operational predictability and certification pathway clarity.
- Air Cargo:Hub-and-spoke density enables ground fueling protocol standardization before ICAO harmonization completes. Dubai-Abu Dhabi feeder routes are absorbing government-backed hydrogen hub investments.
- Passenger Transport:Medium-haul networks between 500-1500 nautical miles escape battery density constraints while remaining within cryogenic tank range envelopes. Japanese domestic routes are prioritizing hydrogen-ready regional jet deployment.
- Pilot Training:Flight school adoption awaits powertrain maturity milestones.
- Research Flights:H2FLY and Airbus demonstrator programs concentrate validation activity in German test corridors.
Air cargo anchors near-term deployment; passenger transport scales through fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing power through EASA-aligned certification infrastructure, while Japan leverages METI subsidies to compress domestic deployment timelines. This asymmetry concentrates flight-test investment in Central Europe while pulling forward fleet commitments in East Asia.
United States
FAA parallel certification frameworks for hydrogen propulsion systems attract Boeing and startup activity to Washington state and California clusters. The IRA hydrogen production tax credits reduce feedstock cost uncertainty for prospective operators. Mojave Desert test ranges host altitude validation programs for cryogenic tank systems.
Germany
H2FLY and Airbus SE anchor dedicated liquid hydrogen test corridors in Bavaria and Hamburg. EASA special conditions on cryogenic tank crashworthiness mandate 15-minute thermal protection standards. Stuttgart and Munich engineering institutes concentrate scarce minus 253-degree Celsius systems expertise.
Japan
ANA and JAL pre-orders for hydrogen-ready regional jets accelerate as METI funding compresses domestic certification timelines. JIS standards development for ground fueling protocols runs ahead of ICAO harmonization. Tokyo-Osaka domestic route density enables early fleet deployment economics.
United Arab Emirates
Emirates SkyCargo and Etihad Cargo pilot split-vendor procurement structures for hydrogen-ready freighters on Dubai-Abu Dhabi feeder routes. Government-backed hydrogen hub investments at Al Maktoum International anchor centralized refueling infrastructure. Route predictability absorbs higher capital costs through hub-and-spoke density.
France
Airbus SE leverages Toulouse airframe certification infrastructure to anchor hydrogen-combustion demonstrator timelines. EU Green Deal ReFuelEU Aviation mandates force Air France-KLM fleet pre-commitments before synthetic fuel quotas tighten. Paris-Saclay research clusters validate cryogenic structural integration concepts.
Liquid Hydrogen-Powered Aircraft Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across the value chain. Full-system integrators leverage existing certification infrastructure to compress development timelines, while component specialists capture disproportionate engineering margins in cryogenic subsystems. Two archetypes dominate: airframe-anchored platforms and powertrain retrofit architectures. Competitive moves concentrate on strategic partnerships for test corridor access and geographic expansion into hydrogen hub clusters.
Within the airframe-anchored tier, Airbus SE occupies a position exemplifying full-system integration capability. Among powertrain specialists, H2FLY and ZeroAvia Inc represent divergent technical paths—German fuel-cell integration expertise versus Anglo-American retrofit architectures for existing regional airframes. These three companies anchor the competitive structure without yet consolidating market share.
| Leading Market Players |
|---|
| Airbus SE |
| GKN Aerospace |
| ZeroAvia Inc |
| Urban Aeronautics Ltd |
| AeroDelft |
| Pipistrel |
| H2FLY |
| HES Energy Systems |
| Alaka'i Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between freight carriers and cryogenic tank suppliers lock in both supply access and price visibility for liquid hydrogen aviation programs. These structures transfer electrolyzer cost volatility risk from airlines to fuel producers while securing dedicated capacity for early fleet deployments.
Pricing Analysis
Configured-to-order pricing for cryogenic tank systems commands substantial premiums over standardized fuselage-mounted composite cylinders. Three-tier pricing structure across flight-qualified, ground-support, and prototype-grade certification levels separates EASA-validated systems from pre-certification alternatives. Pricing pressure stems from electrolyzer capacity constraints compressing hydrogen feedstock cost predictability. Freight carriers exhibit lowest price sensitivity due to route predictability enabling infrastructure amortization, while regional airlines face acute margin pressure from compressed procurement timelines.
Supply Chain Analysis
Germany and Japan anchor cryogenic systems engineering through Stuttgart institutes and METI-funded research clusters. Vacuum-insulated tank fabrication draws from specialized stainless steel alloys and multi-layer insulation materials sourced from aerospace-qualified suppliers. Single-source vulnerability concentrates in minus 253-degree Celsius vaporization expertise held by limited German and Japanese research institutes. Distribution runs through dedicated hydrogen hub clusters at major sorting facilities and test corridor anchor points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against solid-state battery density improvements capturing sub-500 nautical mile routes. Incumbents must navigate bifurcated propulsion architecture commitments that fragment engineering talent and test infrastructure.
For Market Incumbents: Consolidate cryogenic systems engineering talent through exclusive partnerships with Stuttgart and Munich institutes before scarcity intensifies. Anchor certification investment in EASA-aligned test corridors to compress timeline advantage over FAA-parallel frameworks. Vertical integration into vacuum-insulated tank fabrication reduces single-source vulnerability for flight-qualified systems.
For New Entrants and Emerging Players: Retrofit compatibility services for existing regional airframes represent a service-layer gap where incumbents under-serve. Target UAE freight corridors where Emirates SkyCargo and Etihad Cargo pilot split-vendor procurement structures with minimal incumbent lock-in. Position through powertrain retrofit architectures that preserve airframe residual value and accelerate deployment timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward component specialists commanding disproportionate engineering margins in cryogenic subsystems rather than full-system integrators facing capital-intensity pressure. Long-term viability across the projection horizon hinges on certification reciprocity achievement between EASA and FAA. Monitor which regulator publishes full crashworthiness standards first as the inflection indicator for flight-test investment concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Tank Certification Investment | EASA special conditions on 15-minute thermal protection mandate new validation workloads in German and French test facilities. |
| Hydrogen Hub Infrastructure Partnership | Government-backed investments at Al Maktoum International anchor centralized refueling for UAE freight corridors. |
| Retrofit Powertrain Architecture Development | Fuselage-mounted cylindrical tank designs preserve existing regional airframe compatibility and accelerate deployment. |
| Research Institute Talent Consolidation | Exclusive partnerships with Stuttgart engineering institutes secure scarce minus 253-degree Celsius systems expertise. |
| Split-Vendor Procurement Structure | Unbundled airframe and powertrain contracts accelerate retrofit timelines for cargo operators in Dubai and Abu Dhabi. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EASA special condition publications, METI hydrogen aviation roadmaps, and EU Green Deal regulatory filings. Primary interviews captured perspectives from cryogenic systems engineers, airline fleet procurement directors, freight carrier operations heads, and hydrogen hub infrastructure planners. Secondary validation drew from ICAO harmonization progress reports, JIS standards development documentation, and national hydrogen production subsidy disclosures. Bottom-up segment sizing triangulated against top-down market envelope calculations.
Aircraft type, fuel storage technology, and end-user category segmentation dimensions modeled demand concentration across the analysis window. Cryogenic tank gravimetric efficiency curves and battery energy density improvement trajectories informed substitution boundary assumptions. CAGRs derived from fleet replacement cycle timing, certification pathway clarity, and infrastructure deployment sequencing. Electrolyzer capacity expansion forecasts and renewable electricity price trajectories anchored hydrogen feedstock cost modeling.
Forecasts assume regulatory continuity in EASA and FAA parallel frameworks; material divergence in crashworthiness standards would require re-modeling. Policy shifts in Japan's METI funding mechanisms or EU ReFuelEU Aviation mandate enforcement timelines represent specific revision triggers. Recalibration cycles align with material shifts in certification reciprocity achievement and electrolyzer cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Circuit Breakers Market