
 Aircraft Auxiliary Power Unit Market | 2026-2036
Aircraft Auxiliary Power Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Auxiliary Power Unit Market Analysis
Capital-intensity divergence between full-system OEMs and component specialists is bifurcating the competitive landscape. Honeywell International Inc. leverages its integrated turbine controls and digital health monitoring to sustain aftermarket revenue streams. Safran SA anchors European supply chains through Liebherr International Deutschland GmbH's gearbox and air management subsystems. Rolls-Royce Plc competes on high-thrust derivatives that extend platform life cycles for wide-body retrofits.
An aircraft auxiliary power unit is a self-contained gas turbine engine that generates electrical power and compressed bleed air for main engine starting, cabin conditioning, and avionics when the primary propulsion system is offline, typically producing 90 to 500 shaft horsepower depending on aircraft class. Gas turbine APUs dominate commercial aviation installations due to power-to-weight ratios that reciprocating units cannot match at altitude. Military aviation demand tilts toward ground power unit and mobile installation configurations that prioritize rapid deployability over fuel efficiency. Jet fuel remains the standard energy source, though biofuel compatibility is gaining traction as airframe OEMs negotiate scope-three emissions targets with carriers.
FAA airworthiness directives and EASA certification specifications govern APU noise, fire containment, and emissions compliance, with both agencies tightening particulate matter thresholds through the ICAO Annex 16 framework. EPA stationary source rules and MEE dual carbon goals in China are extending regulatory pressure to ground-based auxiliary power systems at airports. Stakeholders must monitor how sustainable aviation fuel certification pathways reshape APU combustor design requirements and aftermarket overhaul economics.
Market Dynamics
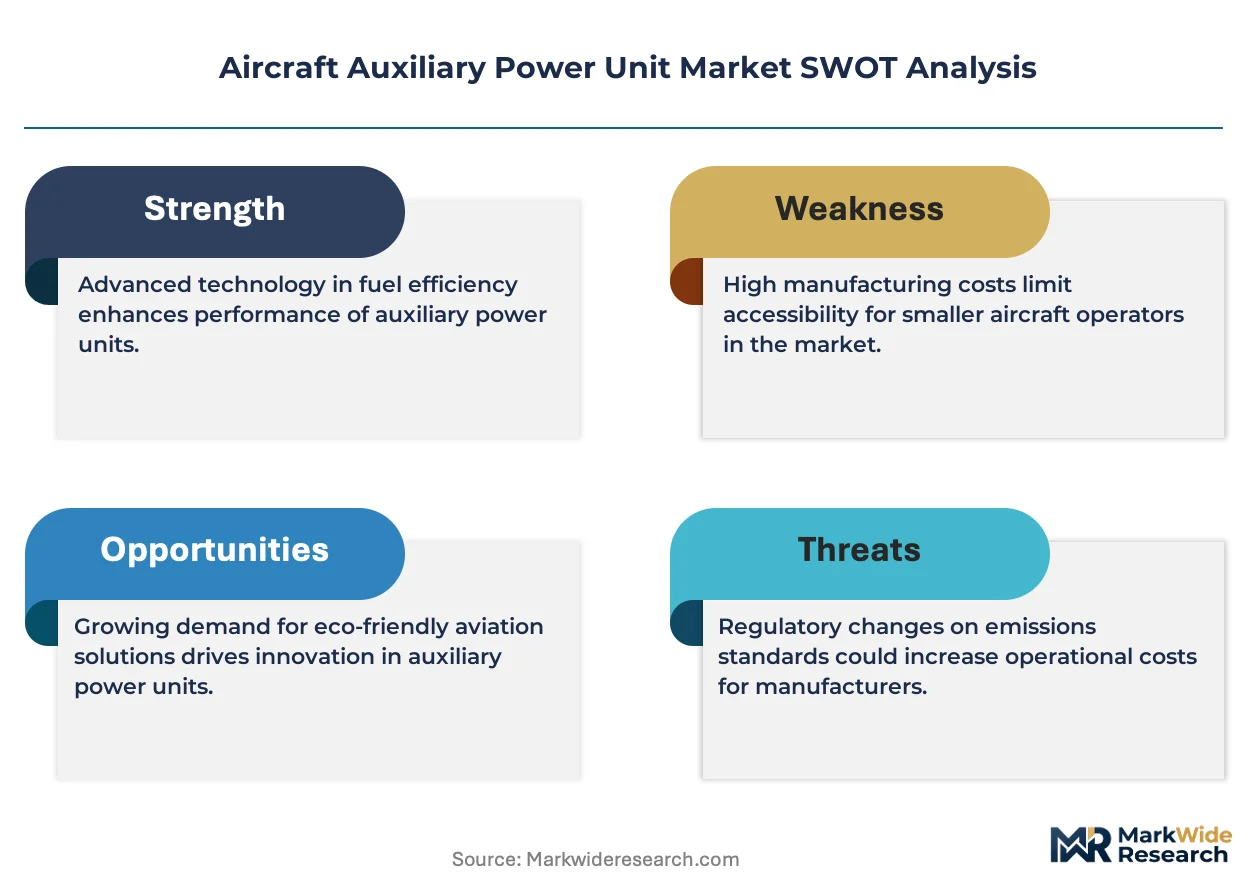
Narrow-body fleet expansion and tightening NOx thresholds under ICAO Annex 16 are forcing APU manufacturers to redesign combustor architectures while maintaining backward compatibility with installed bases.
Growth Catalysts
- ICAO Annex 16 Emissions Framework:Tightening NOx and particulate matter limits for auxiliary power systems are mandating next-generation combustor designs across commercial aviation fleets.
- Narrow-Body Retrofit Cycles:Airlines operating Boeing 737 and Airbus A320 families are accelerating APU replacement programs to meet extended-range operational requirements.
- Sustainable Aviation Fuel Pathways:ASTM D7566 certification standards for biofuel compatibility are creating upgrade demand for fuel system seals and injector nozzles in legacy units.
Market Restraints
- Superalloy Supply Concentration:Single-source dependence on precision-cast turbine blades from specialized foundries in the United States and France creates input bottlenecks.
- Technical Obsolescence Risk:Digital engine control architectures in 1990s-era APUs lack data bus compatibility with modern health monitoring systems.
- Substitution by Ground Power:Fixed electrical ground power units and pre-conditioned air systems at major hubs reduce APU operating hours per turnaround.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India's narrow-body order backlogs will require indigenous MRO capacity for APU overhaul services.
- Hybrid-Electric Architectures:Convergence of high-power density batteries with turbine APUs enables load-leveling configurations for next-generation regional aircraft.
- Performance-Based Logistics:Power-by-the-hour contracts with integrated digital health monitoring are displacing traditional time-between-overhaul maintenance models.
Industry Challenges
- Specialized Technician Scarcity:Gas turbine APU overhaul requires FAA-certified airframe and powerplant mechanics with specific turbine engine ratings.
- Certification Timeline Compression:EASA CS-APU and FAA Part 33 amendment cycles for new emissions-compliant designs extend type certification by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Auxiliary Power Unit Market |
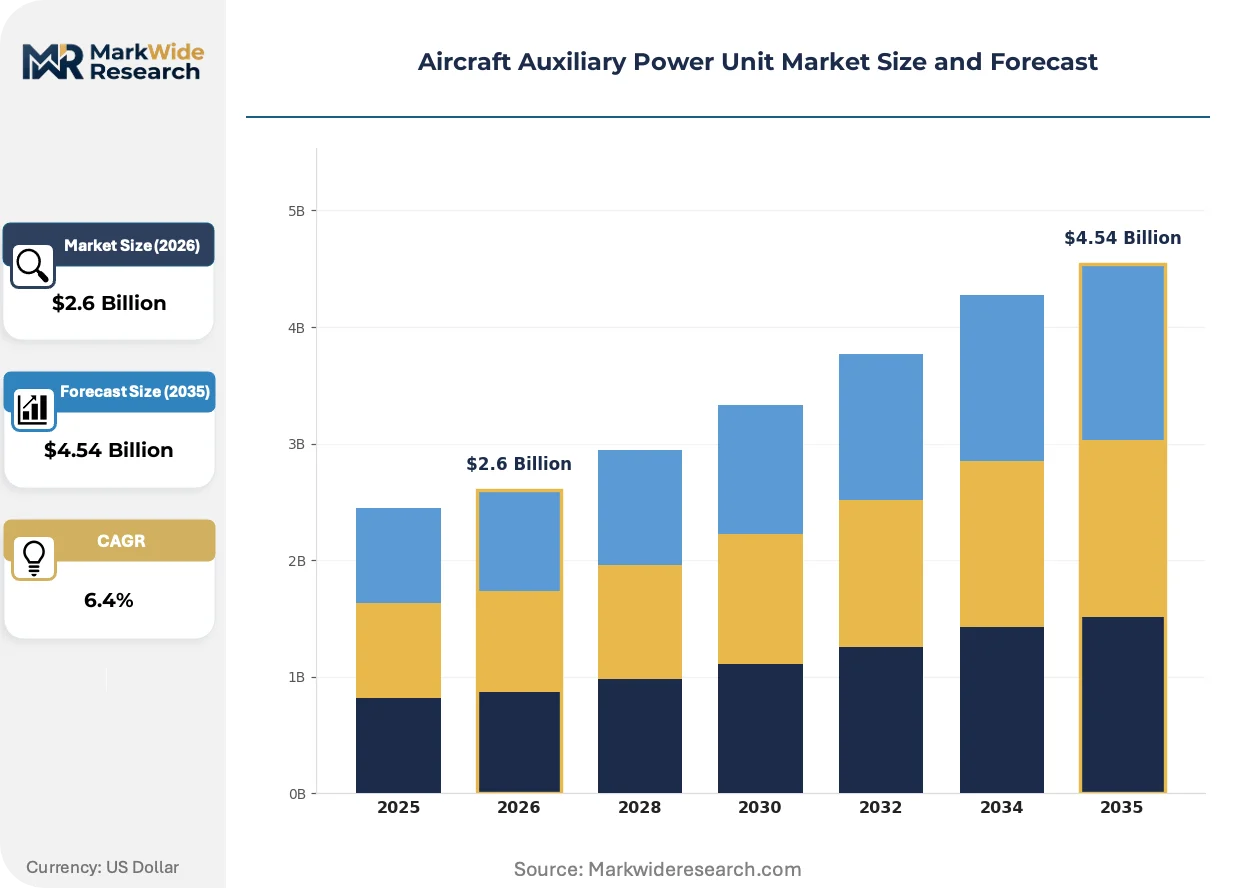
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gas Turbine, Reciprocating, Ground Power Unit, Portable Power Unit Application: Commercial Aviation, Military Aviation, Business Jets, Helicopters Fuel Type: Jet Fuel, Aviation Gasoline, Diesel, Biofuel Installation: Onboard Installation, Ground-Based Installation, Mobile Installation, Hybrid Installation |
| Companies Covered | Collins Aerospace, Rolls-Royce Plc, Honeywell International Inc., Lufthansa Technik, PBS Group, Pratt & Whitney, RTX Corporation, Liebherr International Deutschland GmbH, Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Auxiliary Power Unit Market Emerging Trajectories
Digitalization of APU health management and sustainable fuel compatibility are restructuring aftermarket economics and OEM service architectures across commercial aviation.
Additive manufacturing of nickel-based superalloy turbine nozzles is bifurcating the supplier base between conventional investment casting houses and direct metal laser sintering specialists. MRO providers in the United States and Germany are qualifying printed replacement parts for non-critical airfoil geometries. This technology is bifurcating procurement patterns, as carriers with in-house engineering capabilities bypass traditional OEM spares channels for certifiable printed alternatives.
EASA certification specifications for CS-APU noise and emissions are tightening test-cell measurement protocols for new type designs. Manufacturers must now demonstrate compliance across expanded altitude and temperature envelopes. Wide-body platform derivatives face the steepest redesign burden, as their higher-thrust APUs generate disproportionate NOx per unit output.
Airline technical procurement departments are consolidating vendor relationships through integrated powerplant support agreements that bundle APU, main engine, and LRU management. Full-service leasing companies are displacing fragmented component sourcing for regional carriers in Southeast Asia and Latin America. This concentration is most visible in Indonesia and Vietnam, where rapid fleet growth outstocks indigenous technical purchasing capacity.
Aircraft Auxiliary Power Unit Market Segmentation
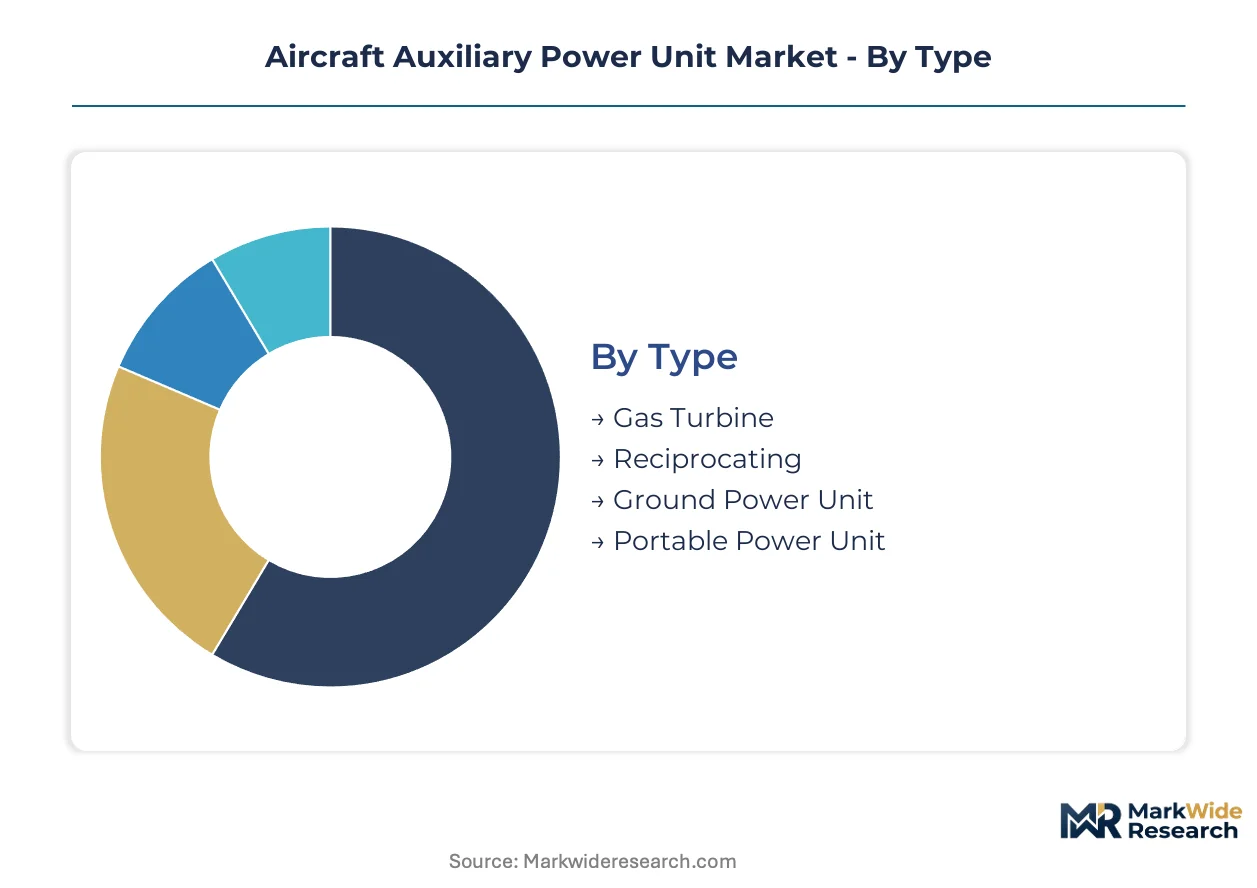
Aircraft Auxiliary Power Unit market segmentation reveals how substitution pressures from ground power infrastructure and hybrid architectures are reshaping procurement priorities across aircraft platforms. Understanding these dimensional splits enables suppliers to align combustor redesign investments with fleet replacement cycles and regulatory compliance timelines.
Type:
Ground power units and portable configurations face the strongest substitution threat from fixed electrical infrastructure at major hubs, forcing onboard turbine manufacturers to defend their installed base through emissions-compliant upgrades.
- Gas Turbine:Self-contained turbine engines deliver 90-500 shaft horsepower with superior power-to-weight ratios for main engine starting and cabin conditioning at altitude. Narrow-body commercial fleets in the United States concentrate replacement demand as FAA NOx limits tighten under ICAO Annex 16.
- Reciprocating:Piston-driven units serve lower-power applications in general aviation where acquisition cost outweighs fuel efficiency penalties. Demand clusters in legacy business aircraft retrofits where airframe longevity exceeds turbine upgrade economics.
- Ground Power Unit:Fixed electrical systems at airport gates displace APU operating hours per turnaround.
- Portable Power Unit:Mobile cart-mounted configurations support remote airfield operations and military forward deployment.
Gas turbine APUs anchor the volume base while ground power units gain share at the steepest rate.
Application:
Cost tier differentiation separates high-utilization commercial operators from mission-critical military buyers with divergent maintenance contracting models.
- Commercial Aviation:Scheduled carriers operating Boeing 737 and Airbus A320 families drive retrofit program volumes. Airlines in India and Southeast Asia are consolidating vendor relationships through integrated powerplant support agreements.
- Military Aviation:Defense operators prioritize rapid deployability and field repairability over fuel efficiency. Ground power and mobile installation configurations dominate tactical airlift and fighter support missions.
- Business Jets:Fractional ownership fleets demand compact, low-signature units for executive transport.
- Helicopters:Rotorcraft APUs require specialized mounting and vibration isolation for offshore and emergency medical services.
Commercial aviation anchors the volume base while military applications expand most quickly in Asia-Pacific defense procurement.
Fuel Type:
Supply concentration in jet fuel logistics networks constrains alternative fuel penetration despite carrier sustainability commitments.
- Jet Fuel:Kerosene-based Jet A and Jet A-1 remain the standard energy source for turbine APUs across all commercial platforms. ASTM D7566 certification pathways for biofuel blends are forcing fuel system seal and injector nozzle upgrades.
- Biofuel:Hydrotreated esters and fatty acids gain traction as airframe OEMs negotiate scope-three emissions targets with carriers. EASA and FAA certification specifications for sustainable aviation fuel compatibility are extending combustor qualification timelines.
- Aviation Gasoline:Reciprocating engines in general aviation retain 100LL and unleaded formulations.
- Diesel:Ground power units and portable configurations utilize diesel for logistics commonality with military fuel stocks.
Jet fuel anchors the volume base while biofuel compatibility is climbing the fastest as emissions frameworks harden.
Installation:
Customer type segmentation distinguishes airframe-integrated OEM specifications from aftermarket MRO flexibility requirements.
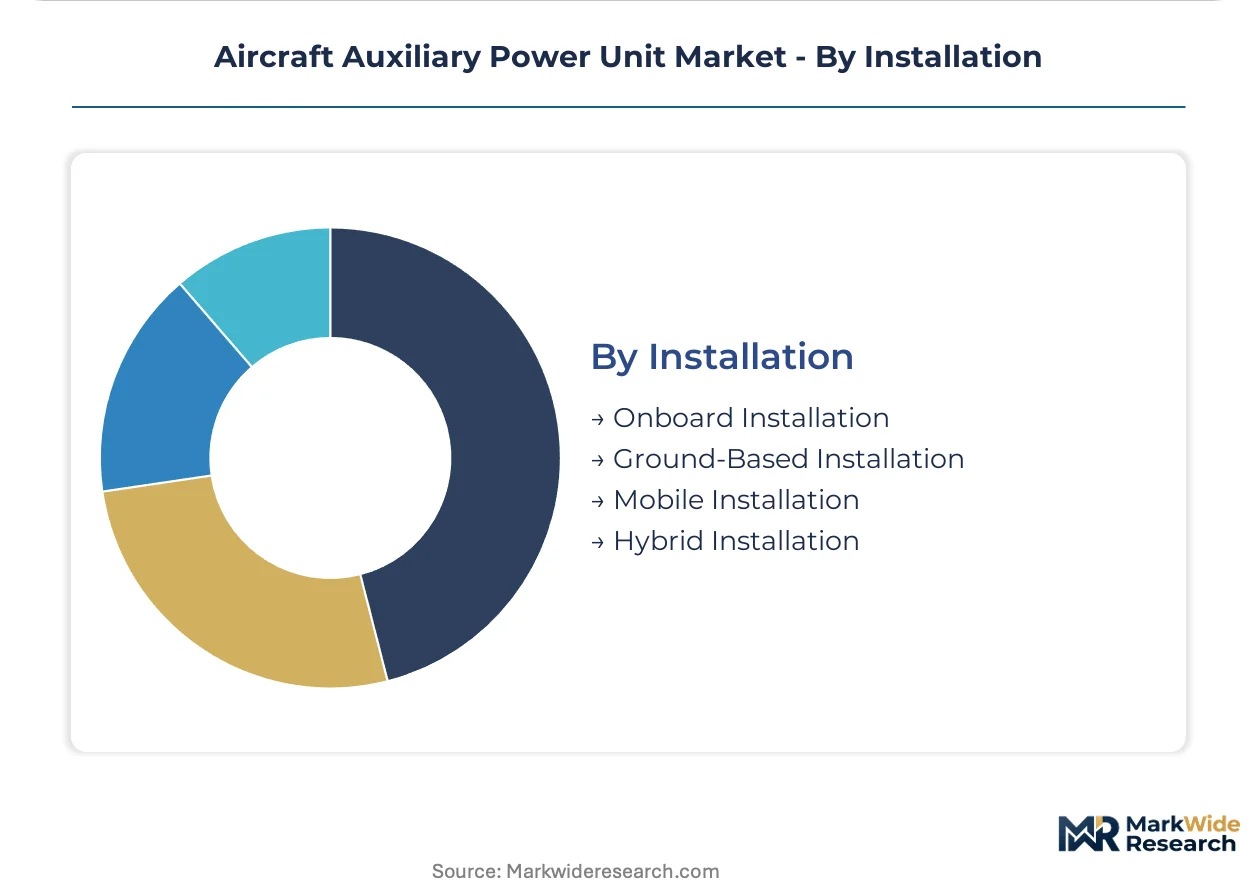
- Onboard Installation:Tail-cone mounted turbine APUs integrate with aircraft bleed air and electrical distribution systems. EASA CS-APU and FAA Part 33 certification cycles for new emissions-compliant designs extend type approval timelines.
- Hybrid Installation:Convergence of high-power density batteries with turbine APUs enables load-leveling for next-generation regional aircraft architectures. Battery-turbine configurations are displacing conventional units in electric-propulsion development programs.
- Ground-Based Installation:Fixed infrastructure at major hubs reduces APU operating hours through pre-conditioned air and electrical ground power.
- Mobile Installation:Trailer-mounted and towable units serve expeditionary military operations and remote civilian airfields.
Onboard installation anchors the volume base while hybrid configurations are gaining share fastest at the technology frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates APU replacement demand around narrow-body retrofit cycles, while India and Southeast Asia build indigenous MRO capacity to match fleet expansion. China pursues dual carbon compliance through ground power substitution. France and Germany anchor European supply chains for precision-cast turbine components.
United States
American carriers operating Boeing 737 and Airbus A320 families accelerate APU replacement programs to meet extended-range operational requirements. FAA airworthiness directives under ICAO Annex 16 tighten NOx and particulate matter thresholds for auxiliary power systems. MRO networks and OEM final assembly lines cluster around Georgia, Ohio, and Arizona, concentrating technical expertise and aftermarket infrastructure.
India
IndiGo and Air India's narrow-body order backlogs will require indigenous MRO capacity for APU overhaul services. The country's PLI scheme incentivizes domestic manufacturing of aerospace components and maintenance infrastructure. Technical procurement departments in Mumbai and Delhi consolidate vendor relationships through integrated powerplant support agreements.
China
MEE dual carbon goals and EPA-aligned stationary source rules extend regulatory pressure to ground-based auxiliary power systems at major airports. Domestic carriers negotiate scope-three emissions targets with airframe OEMs, driving biofuel compatibility requirements. Shanghai and Beijing hubs expand fixed electrical ground power and pre-conditioned air infrastructure to reduce APU operating hours per turnaround.
Germany
EASA CS-APU certification specifications tighten test-cell measurement protocols for new type designs across expanded altitude and temperature envelopes. Precision-cast turbine blade foundries in Baden-Württemberg and Bavaria supply specialized superalloy components to European OEMs. Hamburg and Munich MRO providers qualify additive-manufactured replacement parts for non-critical airfoil geometries.
France
EASA emissions standards mandate next-generation combustor designs while maintaining backward compatibility with installed commercial fleets. Toulouse and Paris aerospace clusters integrate gearbox and air management subsystems into European supply chains. Liebherr International Deutschland GmbH anchors regional component sourcing through specialized manufacturing partnerships.
Aircraft Auxiliary Power Unit Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Full-system OEMs leverage digital health monitoring and integrated turbine controls to capture aftermarket revenue streams. Component specialists concentrate on precision-cast superalloy parts and gearbox subsystems. Dominant competitive moves include strategic partnerships for sustainable aviation fuel certification and geographic expansion into emerging MRO markets.
Within the integrated systems tier, Honeywell International Inc. and Safran SA exemplify full-service architectures spanning design through aftermarket support. Rolls-Royce Plc occupies a position emphasizing high-thrust derivatives for wide-body platform life extension. Liebherr International Deutschland GmbH represents the component specialist archetype, anchoring European supply chains through precision manufacturing of gearbox and air management subsystems. These three entities illustrate how capital-intensity divergence between full-system and component-focused strategies bifurcates competitive positioning.
| Leading Market Players |
|---|
| Collins Aerospace |
| Rolls-Royce Plc |
| Honeywell International Inc. |
| Lufthansa Technik |
| PBS Group |
| Pratt & Whitney |
| RTX Corporation |
| Liebherr International Deutschland GmbH |
| Safran SA |
| Others |
Supply Flow & Price Mechanics
Ninety-day turbine blade lead times from specialized foundries in the United States and France concentrate procurement leverage among incumbent OEMs, compressing margin flexibility for second-tier assemblers while amplifying pricing power at the superalloy source. This inventory-to-pricing transmission mechanism rewards carriers with long-term offtake agreements and penalizes spot-market buyers during certification cycle crunches.
Pricing Analysis
Long-term power-by-the-hour contracts dominate commercial aviation procurement, displacing transactional spares purchasing as carriers prioritize predictable operating economics over capital expenditure control. Price differentiation separates FAA-certified new-production units from DER-approved overhaul alternatives, with volume-scale discounts concentrating among full-service leasing companies. Cost compression in the aftermarket tier is intensifying because additive-manufactured replacement parts bypass traditional OEM channels. Regional carriers in Southeast Asia exhibit highest price sensitivity, while flag carriers in India and the United States prioritize reliability guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of nickel-based superalloy castings dominates inventory strategy among tier-one OEMs, insulating against single-source foundry bottlenecks while inflating working capital requirements relative to just-in-time assemblers. Precision-cast turbine blades draw from specialized foundries in the United States, France, and Germany, with gearbox subsystems anchoring in Bavaria and Baden-Württemberg. Single-source vulnerability concentrates in precision-cast airfoil geometries where EASA and FAA dual-certification requirements limit qualified suppliers. Distribution runs through OEM-controlled service centers and independent MRO networks clustered around Georgia, Ohio, and Arizona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-by-the-hour contracts and integrated digital health monitoring are expanding faster than hardware shipments, repositioning aftermarket service attach as the primary value capture mechanism. This service-layer acceleration rewards stakeholders who control data infrastructure and penalizes pure-manufacturing plays.
For Market Incumbents: Secure exclusive superalloy foundry capacity through long-term offtake agreements with Baden-Württemberg and Arizona precision-casters, insulating against single-source vulnerability while denying feedstock access to emerging competitors. Deepen backward integration into additive-manufacturing qualification for non-critical airfoil geometries, capturing margin that currently leaks to independent MRO channels. Hybrid-electric architecture substitution represents the priority threat requiring preemptive battery-turbine partnership positioning. For New Entrants and Emerging Players: Lead with ASTM D7566 biofuel compatibility certification as the differentiated entry credential, targeting IndiGo and Air India narrow-body retrofit programs where indigenous MRO capacity gaps create procurement openness. Concentrate initial penetration on fuel system seal and injector nozzle upgrades rather than full-system competition, exploiting combustor redesign cycles that incumbent OEMs cannot accelerate. Direct sales to technical procurement departments in Mumbai and Delhi bypasses entrenched OEM distribution. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because power-by-the-hour contract concentration and digital health monitoring infrastructure create winner-take-most dynamics that favor scaled incumbents over fragmented specialists. Acquisition targets should display captive MRO network access in India or Southeast Asia alongside FAA/EASA dual-certification capabilities. The signal to watch is EASA CS-APU amendment timing for next-generation emissions standards, which will trigger 18-24 month certification timeline compression and strand undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-the-Hour Contract Expansion | Carriers in India consolidate vendor relationships through bundled APU, main engine, and LRU management agreements. |
| Additive Manufacturing Qualification | MRO providers in Germany and the United States bypass OEM spares channels for certifiable printed turbine nozzles. |
| Biofuel Compatibility Certification | ASTM D7566 pathways force fuel system seal and injector nozzle upgrades across legacy commercial fleets. |
| Indigenous MRO Capacity Buildout | IndiGo and Air India narrow-body backlogs require domestic overhaul infrastructure to match fleet expansion. |
| Hybrid-Electric Architecture Development | Battery-turbine load-leveling configurations displace conventional units in next-generation regional aircraft programs. |
Methodological Framework
Desk research of FAA airworthiness directives, EASA certification specifications, and ICAO Annex 16 regulatory filings preceded structured interviews with APU program directors at full-system OEMs, MRO operations managers in Georgia and Arizona, and technical procurement leads at narrow-body carriers in India and Southeast Asia. Secondary validation drew from customs trade data for superalloy castings, SEC 10-K disclosures from integrated aerospace suppliers, and production databases for Boeing 737 and Airbus A320 family aircraft. Bottom-up fleet replacement modeling and top-down emissions compliance scenario analysis provided triangulation.
Variance decomposition across the projection horizon isolates narrow-body retrofit cycle timing, ICAO Annex 16 amendment implementation schedules, and sustainable aviation fuel certification pathway adoption as primary uncertainty sources. Segmentation dimensions modeled include gas turbine versus ground power unit type, commercial versus military application, jet fuel versus biofuel compatibility, and onboard versus hybrid installation configuration. CAGRs derive from unit shipment forecasts cross-referenced against average selling price trajectories informed by power-by-the-hour contract penetration and additive-manufacturing cost disruption.
Underlying assumptions cover EASA and FAA regulatory harmonization on NOx thresholds, with deviation risk concentrated in MEE dual carbon goal acceleration in China and superalloy foundry capacity constraints in France and the United States. Revision becomes warranted when sustainable aviation fuel blend mandates cross operational compatibility thresholds that force premature legacy APU retirement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market