
 Aerospace Fluoropolymers Market | 2026-2036
Aerospace Fluoropolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Fluoropolymers Market Analysis
Specialty chemical distribution for aerospace fluoropolymers is fragmenting as regional distributors lose ground to direct procurement contracts and platform-specific supply agreements. Daikin Industries leverages its captive polymerization capacity in Japan to sustain long-term contracts with Asian airframe programs. Solvay SA anchors European supply through its vertically integrated PFA and ETFE production chain, while The Chemours Company competes aggressively on North American defense qualification programs.
Aerospace fluoropolymers constitute a family of perfluorinated and partially fluorinated thermoplastics—principally PTFE, FEP, ETFE, and PFA—engineered for continuous service temperatures exceeding 260°C, chemical inertness, and dielectric stability under aerospace environmental stress. These materials function primarily as barrier layers, friction-reducing surfaces, and electrical insulators in propulsion, fuel, and avionics systems. PTFE occupies the mature volume position across seals and gasket applications where legacy qualification standards resist substitution, while PFA captures expanding share in coating formulations demanding melt-processability without thermal performance sacrifice. Defense end users generate concentrated margin pools due to extended qualification cycles and specification lock-in, whereas commercial aviation volume growth concentrates in next-generation narrowbody platforms.
Regulatory pressure from the EPA on per- and polyfluoroalkyl substance emissions and evolving REACH restrictions under ECHA oversight are reshaping material qualification pathways and regional production economics. FAA airworthiness directives and EASA certification requirements further constrain substitution timelines, embedding incumbent fluoropolymer grades within approved type designs. Stakeholders must monitor regulatory divergence between jurisdictions and pre-position reformulation investments before qualification gates close on legacy chemistries.
Market Dynamics
REACH restrictions on perfluorinated substances and EPA guidelines on PFAS emissions are forcing immediate reformulation investments across aerospace fluoropolymer supply chains, compressing qualification timelines for legacy chemistries while opening pathways for alternative polymer architectures.
Growth Catalysts
- Next-generation narrowbody platforms:Commercial aviation OEMs specify fluoropolymers for fuel system components and engine seals to achieve weight reduction targets without thermal performance sacrifice.
- Defense procurement concentration:Extended qualification cycles and specification lock-in within NASA space programs and military aerospace sustain specialized fluoropolymer consumption at premium margins.
- ETFE coating formulations:Melt-processable alternatives to PTFE capture expanding share in barrier layer applications where thermal stability must coexist with manufacturing efficiency.
Market Restraints
- Fluorspar supply concentration:Captive mining assets in China and Mexico create input cost volatility and geopolitical exposure for polymerization feedstocks.
- ECHA authorization timelines:REACH substance evaluation delays extend reformulation investment horizons beyond typical aerospace program development cycles.
- Ceramic matrix composites:High-temperature engine applications above 400°C increasingly specify CMC seals over fluoropolymer alternatives in next-generation propulsion architectures.
Strategic Opportunities
- Urban air mobility infrastructure:Electric vertical take-off and landing platforms in the United States and Germany create demand for lightweight electrical insulation and thermal barrier systems.
- Japan's hydrogen aviation roadmap:METI-funded programs specify fluoropolymer seals and gaskets for cryogenic fuel systems in prototype hydrogen-powered regional aircraft.
- Direct platform contracting:Tier-1 component manufacturers bypass regional distributors to secure long-term supply agreements with airframe OEMs, collapsing traditional chemical distribution margins.
Industry Challenges
- Polymerization process engineering:Reformulation of PFA and ETFE grades to eliminate long-chain PFAS while maintaining molecular weight distribution requires scarce fluoroorganic synthesis expertise.
- FAA-EASA divergence risk:Asynchronous airworthiness directive timelines between US and European regulators force parallel qualification tracks for single-source aerospace components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Fluoropolymers Market |
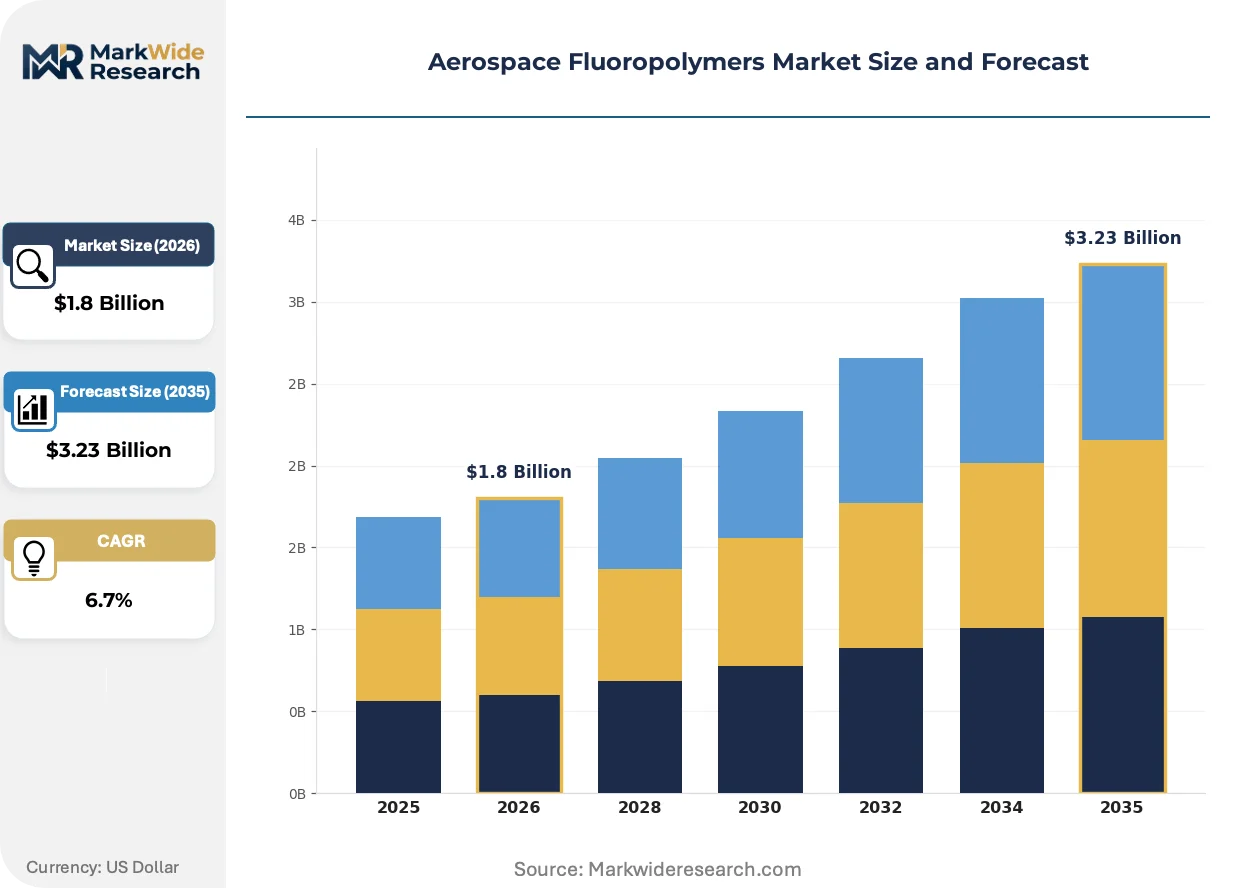
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, ETFE, PFA Application: Seals, Gaskets, Coatings, Insulations End User: Defense, Commercial Aviation, Space, Manufacturing Delivery Mode: Direct, Online, Distributors, Others |
| Companies Covered | Daikin Industries, Ltd., The Chemours Company, 3M Company, Solvay SA, Arkema S.A., AGC Inc., Saint-Gobain S.A., HaloPolymer Holding, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Fluoropolymers Market Emerging Trajectories
Reformulation chemistry is accelerating across aerospace fluoropolymer value chains as regulatory pressure on legacy perfluorinated substances intersects with thermal performance requirements that resist easy substitution.
Perfluoroalkoxy alkane variants with shortened fluorinated side chains are collapsing the traditional trade-off between melt processability and continuous service temperature. Tier-1 seal manufacturers in commercial propulsion systems adopt these reformulated grades at pilot scale, compressing the qualification timeline for legacy PTFE in fuel system applications where FEP previously dominated.
EPA enforcement discretion on PFAS reporting under TSCA Section 8(a)(7) tightens through 2025, compelling aerospace compounders to establish emissions monitoring infrastructure at polymerization facilities. European suppliers face parallel pressure from ECHA's restriction proposal on PFAS as a class, forcing dual-track reformulation investments that strain R&D allocation across Atlantic and Pacific regulatory jurisdictions.
Platform-specific supply agreements displace spot purchasing and regional distributor relationships for critical fluoropolymer grades. Airframe OEMs in the United States consolidate procurement through direct long-term contracts with qualified compounders, unbundling after-sales technical service from material supply and compressing margin capture for intermediaries without captive polymerization assets.
Aerospace Fluoropolymers Market Segmentation
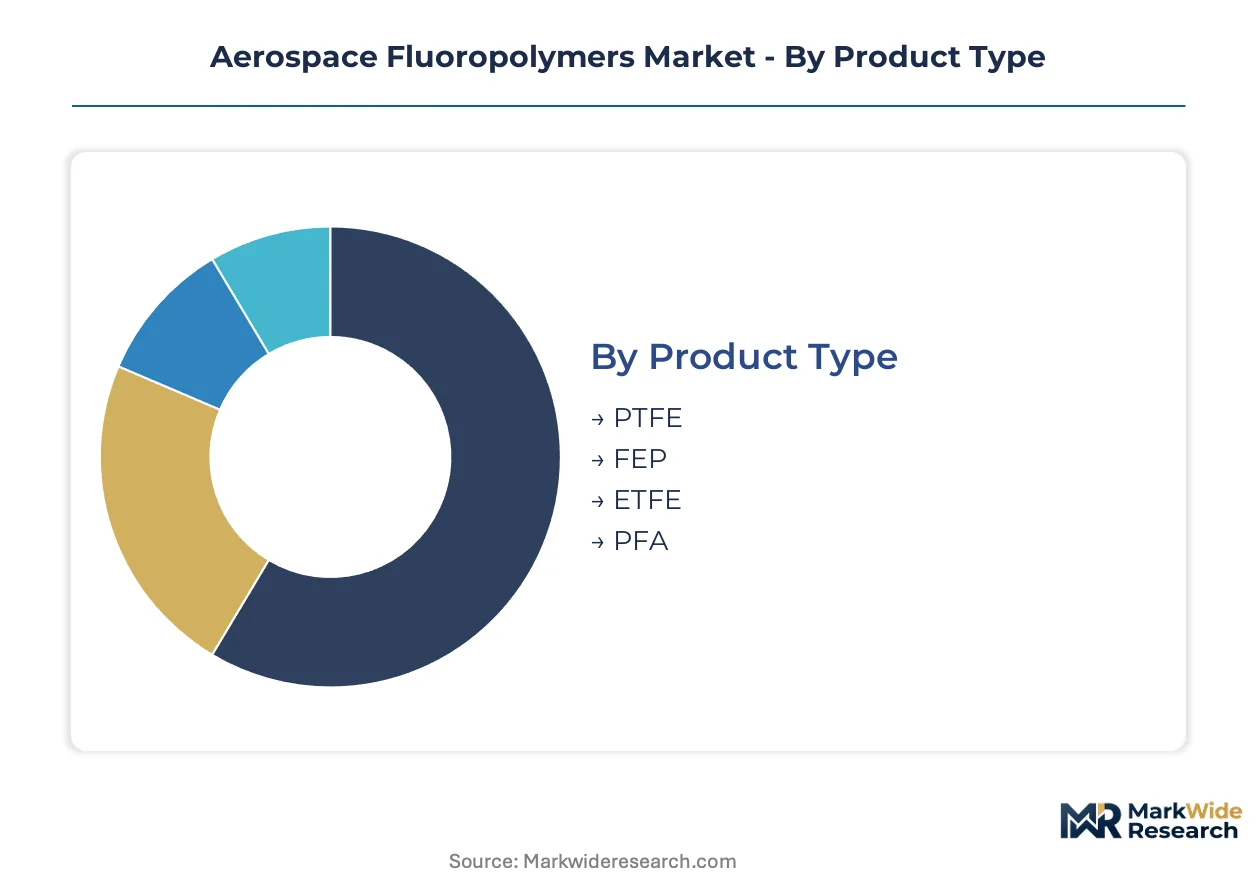
Aerospace fluoropolymers serve distinct thermal, chemical, and electrical functions across propulsion, fuel, and avionics systems. Segment boundaries reflect qualification standards, polymer architecture trade-offs, and procurement channel economics that shape supplier positioning.
Product Type:
Use-case spectra span legacy seals demanding maximum thermal tolerance versus melt-processable coatings prioritizing manufacturing throughput.
- PTFE:Perfluorinated thermoplastic with the highest continuous service temperature rating among commercial fluoropolymers. Demand concentrates in legacy engine seals and gasket applications where FAA and EASA qualification standards resist substitution. Defense procurement sustains premium pricing despite processing limitations.
- PFA:Melt-processable perfluoroalkoxy alkane retaining thermal performance near PTFE levels. Commercial aviation OEMs specify PFA for fuel system coatings where manufacturing efficiency must coexist with 260°C service requirements. ETFE captures expanding share in barrier layer formulations where reduced fluorine content meets emerging regulatory thresholds.
- FEP:Fully fluorinated copolymer with lower viscosity than PTFE, enabling thin-wall extrusion for wire insulation and cable jacketing.
- ETFE:Partially fluorinated ethylene-tetrafluoroethylene copolymer balancing chemical resistance with mechanical toughness for architectural and protective films.
The dominant share belongs to PTFE, while PFA is closing the gap fastest.
Application:
Cost tiers separate flight-critical components with extended qualification cycles from replaceable consumables with shorter approval pathways.
- Seals:Dynamic and static sealing elements in propulsion and fuel systems. NASA space programs and military aerospace specifications lock in PTFE-based formulations for cryogenic and high-temperature service. Reformulation pressure from EPA PFAS enforcement is compressing supplier margins on legacy chemistries.
- Coatings:Barrier and release layers applied through powder, liquid, or film deposition. ETFE and PFA grades capture volume in commercial aviation fuel system components where OEMs pursue weight reduction targets. ECHA restriction proposals on PFAS as a class are forcing dual-track qualification investments.
- Gaskets:Static compression seals for fluid and pressure containment in airframe assemblies.
- Insulations:Dielectric barriers for wire, cable, and electronic component protection in avionics systems.
Seals command the highest margin tier, while coatings are expanding most quickly.
End User:
Customer type determines specification authority, contract duration, and technical service intensity across the value chain.
- Defense:Military aerospace and space agency procurement with extended qualification cycles and specification lock-in. NASA programs sustain specialized fluoropolymer consumption for thermal protection systems and cryogenic seals. Premium margins compensate for low volume and stringent documentation requirements.
- Commercial Aviation:Airframe OEMs and Tier-1 suppliers driving volume through next-generation narrowbody platforms. Boeing and Airbus specifications for fuel system components and engine seals concentrate demand for lighter, thermally stable materials.
- Space:Satellite and launch vehicle manufacturers with extreme thermal cycling and radiation exposure requirements.
- Manufacturing:General industrial applications with less stringent aerospace qualification standards.
Defense retains the highest value per kilogram, while commercial aviation delivers the steepest volume expansion trajectory.
Delivery Mode:
Supply concentration is shifting from fragmented distribution toward direct platform contracting with qualified compounders.
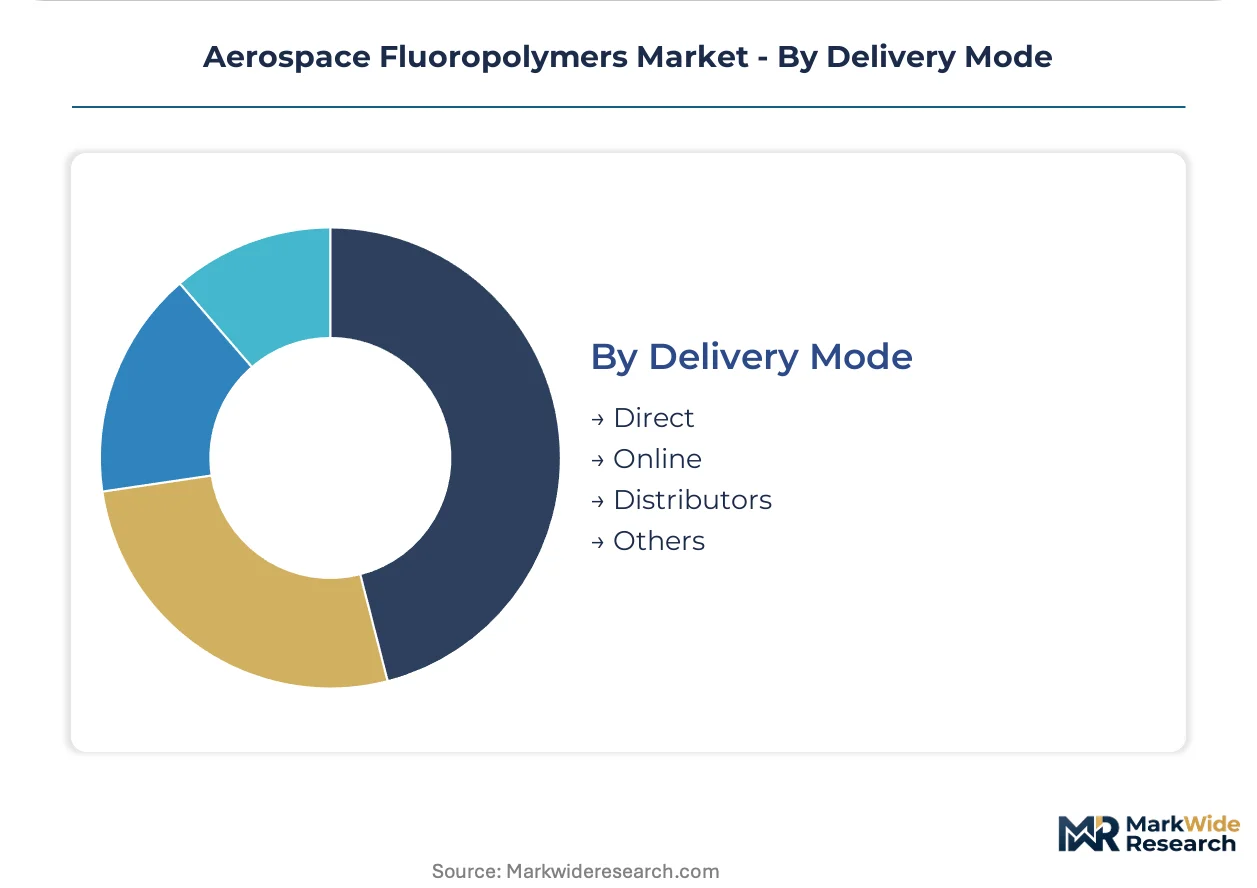
- Direct:Long-term supply agreements between airframe OEMs and fluoropolymer compounders with captive polymerization assets. Boeing, Airbus, and defense primes consolidate procurement through qualified supplier lists, collapsing traditional chemical distribution margins.
- Distributors:Regional specialty chemical intermediaries losing share to direct contracts and platform-specific supply agreements. Daikin Industries and Solvay SA bypass distributor networks for major Asian and European airframe programs.
- Online:Digital procurement platforms for standard grades and consumables with established specifications.
- Others:Consignment inventory, vendor-managed stock, and technical service bundled arrangements.
Direct contracting dominates high-value aerospace grades, while distributors retain residual share in maintenance, repair, and overhaul channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor anchors North American fluoropolymer feedstock access, while Japan's Chubu International Airport logistics cluster underwrites Asian supply chain velocity for aerospace-grade polymer distribution.
United States
NASA space programs and Pentagon procurement sustain specialized fluoropolymer consumption for thermal protection systems and cryogenic seals. EPA enforcement discretion on PFAS reporting under TSCA Section 8(a)(7) tightens through 2025, compelling emissions monitoring infrastructure at polymerization facilities. The Gulf Coast petrochemical corridor concentrates captive polymerization capacity serving defense qualification programs.
Japan
METI-funded hydrogen aviation roadmap programs specify fluoropolymer seals for cryogenic fuel systems in prototype regional aircraft. Domestic fluoropolymer producers leverage captive polymerization assets to sustain long-term contracts with Asian airframe programs. The Chubu region around Nagoya anchors aerospace manufacturing clusters demanding high-purity fluoropolymer grades.
Germany
Urban air mobility infrastructure development creates demand for lightweight electrical insulation in electric vertical take-off and landing platforms. ECHA's restriction proposal on PFAS as a class forces dual-track reformulation investments across Atlantic regulatory jurisdictions. The Bavarian aerospace cluster around Munich concentrates Tier-1 component manufacturer procurement decisions.
China
Expanding commercial aviation fleets drive fluoropolymer adoption in engine seals and fuel system components as OEMs pursue lighter materials. The country's national chemical regulator maintains evolving guidelines on perfluorinated substance emissions affecting polymerization facility operations. The Yangtze River Delta manufacturing corridor concentrates fluoropolymer compounding capacity serving domestic airframe programs.
France
Airbus specifications for next-generation narrowbody platforms concentrate demand for thermally stable fuel system coatings. REACH substance evaluation timelines extend reformulation investment horizons beyond typical aerospace program development cycles. The Toulouse aerospace cluster anchors European airframe OEM procurement consolidation through direct long-term supply agreements.
Aerospace Fluoropolymers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where qualification standards and specification lock-in create defensive moats. The vendor base organizes around three archetypes: diversified chemical conglomerates with captive polymerization assets, mid-cap fluoropolymer compounders serving niche defense programs, and regional distributors losing ground to direct procurement channels. Consolidation pressure concentrates among compounders seeking backward integration into fluorspar feedstocks and polymerization capacity. Strategic partnerships between seal manufacturers and airframe OEMs displace spot purchasing relationships.
Within the diversified chemical conglomerate tier, Daikin Industries exemplifies geographic anchoring through Japan-based captive production, while Solvay SA represents European vertical integration across PFA and ETFE grades. The Chemours Company occupies a position within North American defense qualification ecosystems where extended certification cycles embed incumbent supplier relationships.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| The Chemours Company |
| 3M Company |
| Solvay SA |
| Arkema S.A. |
| AGC Inc. |
| Saint-Gobain S.A. |
| HaloPolymer Holding |
| DuPont |
| Others |
Supply Flow & Price Mechanics
The Gulf Coast petrochemical corridor around Houston concentrates captive polymerization capacity for aerospace fluoropolymer feedstocks, embedding pricing power with compounders holding backward integration into fluorspar derivatives while distributors without asset ownership absorb margin compression.
Pricing Analysis
Three-tier pricing structure across defense-qualified, commercial aviation, and industrial grades separates premium capture in NASA specification lock-in from standard commercial aviation contracts and economy-tier maintenance consumables. Price differentiation hinges on certification grade against FAA airworthiness directives and volume scale in long-term platform agreements. Cost compression in commercial aviation tiers is intensifying because OEMs consolidate procurement through direct contracting. Defense end users exhibit least price sensitivity due to extended qualification cycles, while maintenance repair operations channels face highest buyer pressure.
Supply Chain Analysis
Fluorspar mining concentration in China and Mexico anchors upstream feedstock access, with polymerization capacity clustering in the United States, Japan, and Germany. The supply chain draws from acid-grade fluorspar, hydrogen fluoride, and chlorodifluoromethane as critical inputs. Single-source vulnerability runs through Chinese fluorspar export licensing and geopolitical exposure. Distribution runs through direct platform contracting with qualified compounders, displacing regional specialty chemical intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace fluoropolymers constitute a high-growth disruption as regulatory pressure on legacy PFAS chemistries forces simultaneous reformulation and qualification investments that favor asset-heavy incumbents with captive polymerization.
For Market Incumbents: Build specification moats by accelerating FAA-EASA dual-track qualification for shortened-chain PFA variants before regulatory gates close on legacy chemistries. Deepen upstream control over fluorspar feedstocks through offtake agreements with Mexican mining assets to offset Chinese supply concentration. Ceramic matrix composite substitution in propulsion seals above 400°C represents the primary technology threat requiring monitoring. For New Entrants and Emerging Players: Build out urban air mobility electrical insulation capabilities targeting eVTOL platforms in Germany and the United States where qualification timelines remain compressed versus commercial aviation. Hydrogen aviation seals for cryogenic fuel systems under Japan's METI roadmap offer the most penetrable white space. A technical service bundling go-to-market angle can differentiate against compounders lacking application engineering depth. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because extended aerospace qualification cycles embed incumbent supplier relationships beyond typical private equity holding periods. Acquisition targets should display captive polymerization assets with defense program qualifications. The signal to watch is ECHA's PFAS restriction implementation timeline, which will force consolidation among reformulation-lagging compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Feedstocks | Mitigates Chinese supply concentration and secures input cost stability for polymerization operations. |
| Dual-Track FAA-EASA Qualification Investment | Pre-positions reformulated grades before regulatory divergence locks out single-jurisdiction suppliers. |
| Urban Air Mobility Partnership Development | Captures eVTOL platform specifications in nascent segments with compressed approval pathways. |
| Hydrogen Aviation Seal Development | Aligns with METI-funded cryogenic fuel system programs in prototype regional aircraft. |
| Direct Platform Contracting Consolidation | Collapses distributor margins while securing long-term offtake with Boeing, Airbus, and defense primes. |
Methodological Framework
Initial hypotheses were tested against primary input from fluoropolymer compounding plant managers, aerospace OEM procurement leads, Tier-1 seal manufacturer technical directors, and defense qualification program officers and refined through secondary validation against SEC 10-K filings, customs and trade flow databases, ACC and Cefic chemical industry reports, and FAA airworthiness directive filings. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling volume and value through product type, application, end user, and delivery mode segmentation dimensions. CAGRs were derived from segment-level growth trajectory synthesis. Forecast inputs incorporated REACH substance evaluation timelines and EPA PFAS enforcement discretion tightening patterns alongside commercial aviation fleet expansion assumptions.
Sensitivities concentrate around ECHA authorization delays extending beyond aerospace program development cycles and fluorspar export restriction implementation from Chinese regulators. Cross-checking against IHS Markit aerospace production forecasts and ECHA restriction proposal revision tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market