
 Aviation Crew Management System Market | 2026-2036
Aviation Crew Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Crew Management System Market Analysis
Multi-source vendor strategies is expanding across major airlines as carriers diversify away from single-platform dependencies. Jeppesen leverages its heritage in flight operations data to anchor crew scheduling workflows for North American flag carriers. Sabre Corporation sustains competitive pressure through integrated airline IT portfolios that bundle crew management with revenue optimization. Lufthansa Systems dominates European deployment with region-specific regulatory compliance modules embedded in its platform architecture.
An aviation crew management system constitutes a software platform that automates pilot and cabin crew scheduling, pairing, rostering, and duty-time tracking against flight operations requirements, typically processing crew qualification matrices, fatigue-risk algorithms, and union agreement rules in real-time. The system serves airlines and charter operators by minimizing crew-related flight disruptions while ensuring regulatory adherence across complex route networks. Cloud-based deployment leads segment momentum as carriers retire legacy mainframe installations for elastic infrastructure that scales with seasonal capacity swings. Scheduling software occupies the largest product category by installed base, though compliance management tools are gaining share fastest as regulators tighten fatigue-monitoring mandates. Airlines represent the dominant end-user category, yet cargo carriers present concentrated growth opportunity given their round-the-clock network complexity and expanding freighter fleets.
The FAA governs U.S. crew rest and duty limitations under Part 117, forcing domestic carriers to adopt automated tracking or face operational penalties, while EASA's EU-OPS Subpart Q shapes parallel compliance architecture across European operators. ICAO standards further harmonize cross-border requirements, creating demand for multi-jurisdictional compliance engines in vendor roadmaps. Stakeholders must evaluate whether platform investments prioritize modular API architectures that accommodate emerging biometric fatigue-monitoring inputs or deepen vertical integration with existing flight operations suites.
Market Dynamics
Airlines face acute pilot and cabin crew shortages that force carriers to extract maximum productivity from existing staff pools. Automated crew management platforms have shifted from back-office efficiency tools to mission-critical infrastructure for maintaining flight schedules.
Growth Catalysts
- FAA Part 117 mandates:U.S. carriers must automate duty-time tracking or face operational penalties, accelerating replacement of manual compliance systems.
- Cloud elasticity:Seasonal capacity swings at network carriers demand infrastructure that scales without mainframe upgrade cycles.
- Union agreement complexity:Multi-base crew contracts with work-rule variations require algorithmic rostering that manual processes cannot execute.
Market Restraints
- Legacy system entrenchment:Decades-old mainframe installations at flag carriers create switching costs that delay platform modernization.
- Data sovereignty requirements:Crew records containing biometric fatigue data face cross-border transfer restrictions under GDPR and parallel frameworks.
- Specialized talent scarcity:Aviation operations research analysts with both crew scheduling and regulatory expertise command premium compensation.
Strategic Opportunities
- Cargo carrier penetration:Round-the-clock freighter operations present concentrated demand for fatigue-risk algorithms that passenger airline platforms under-serve.
- Biometric integration:Wearable sleep monitors and predictive fatigue models create white space for platforms with modular API architectures.
- EASA CSRD alignment:Sustainability reporting mandates for crew positioning emissions create demand for carbon-optimized rostering modules.
Industry Challenges
- Multi-jurisdictional certification:Platforms must simultaneously satisfy FAA, EASA, and ICAO standards without code forks for each deployment.
- Real-time disruption recovery:Irregular operations from weather or mechanical failures demand sub-minute crew reallocation that strains legacy architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Crew Management System Market |
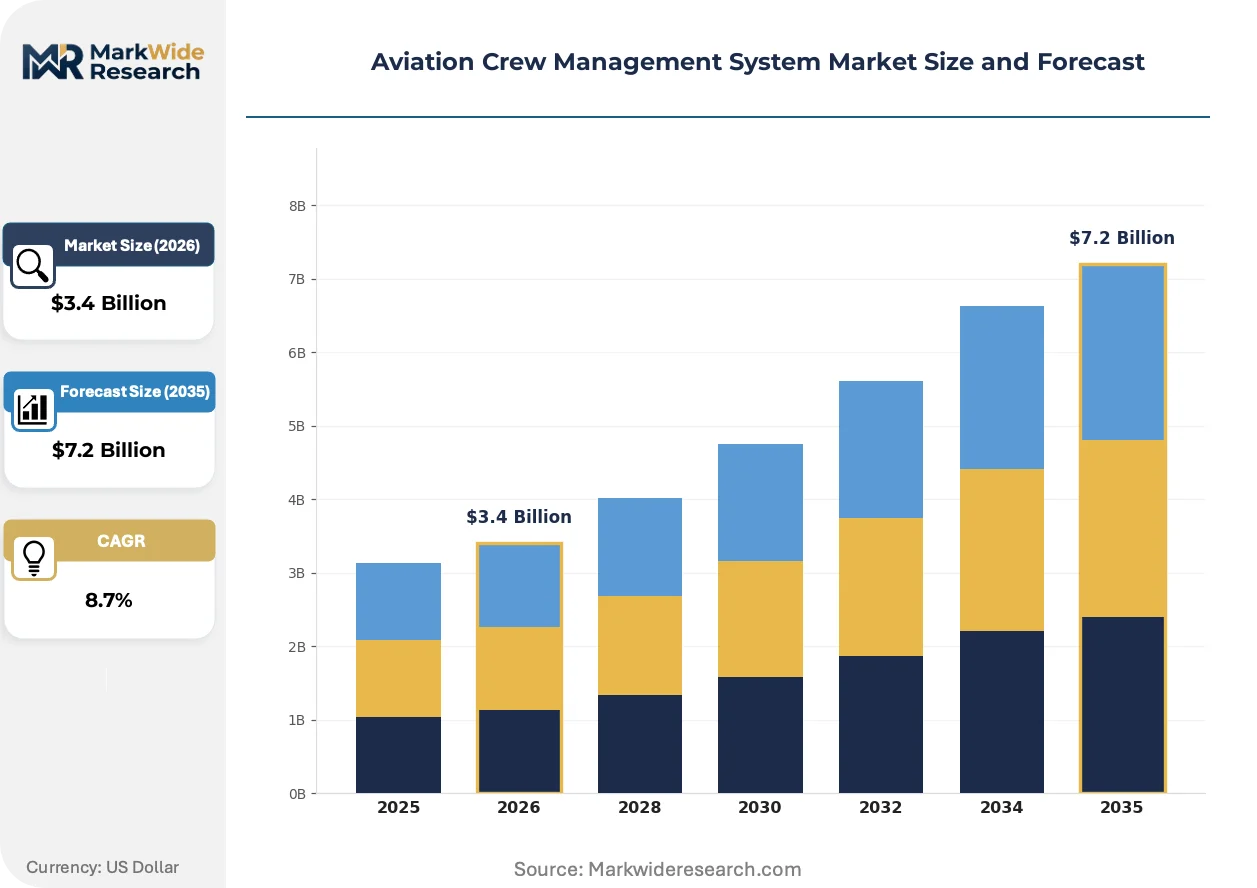
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Crew Planning Tool, Resource Management System, Compliance Management Tool Deployment: On-Premise, Cloud-Based, Hybrid, Mobile-Based End User: Airlines, Charter Operators, Cargo Carriers, Maintenance Providers Functionality: Resource Allocation, Time Management, Reporting & Analytics, Compliance Tracking |
| Companies Covered | Jeppesen, RAMCO Systems, AIMS, Oracle, Collins Aerospace, Sabre Corporation, Honeywell International Inc., Symphony Solutions, Lufthansa Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Crew Management System Market Emerging Trajectories
Artificial intelligence is compressing the crew pairing optimization window from overnight batch processing to continuous real-time adjustment. This shift is redrawing competitive boundaries between incumbent aviation IT vendors and specialized optimization startups.
Machine learning-based fatigue prediction is rewriting how airlines manage crew alertness. Carriers including major U.S. network operators are piloting platforms that ingest wearable sleep data and circadian rhythm models to block high-risk assignments before roster publication. The technology is compressing the gap between scientific sleep research and operational crew planning.
EASA's updated EU-OPS Subpart Q implementation is forcing European carriers to demonstrate predictive fatigue management rather than retrospective duty logging. Operators must now model crew alertness across multi-sector duties with mathematical transparency. Low-cost carriers with high aircraft utilization rates face the steepest compliance redesign.
Subscription-based platform access is displacing perpetual license models among mid-size charter operators. These buyers prefer operational expenditure treatment and vendor-managed infrastructure over capital-intensive on-premise deployments. The shift is most visible in the United States where regional carriers and corporate flight departments seek predictable monthly costs without IT headcount expansion.
Aviation Crew Management System Market Segmentation
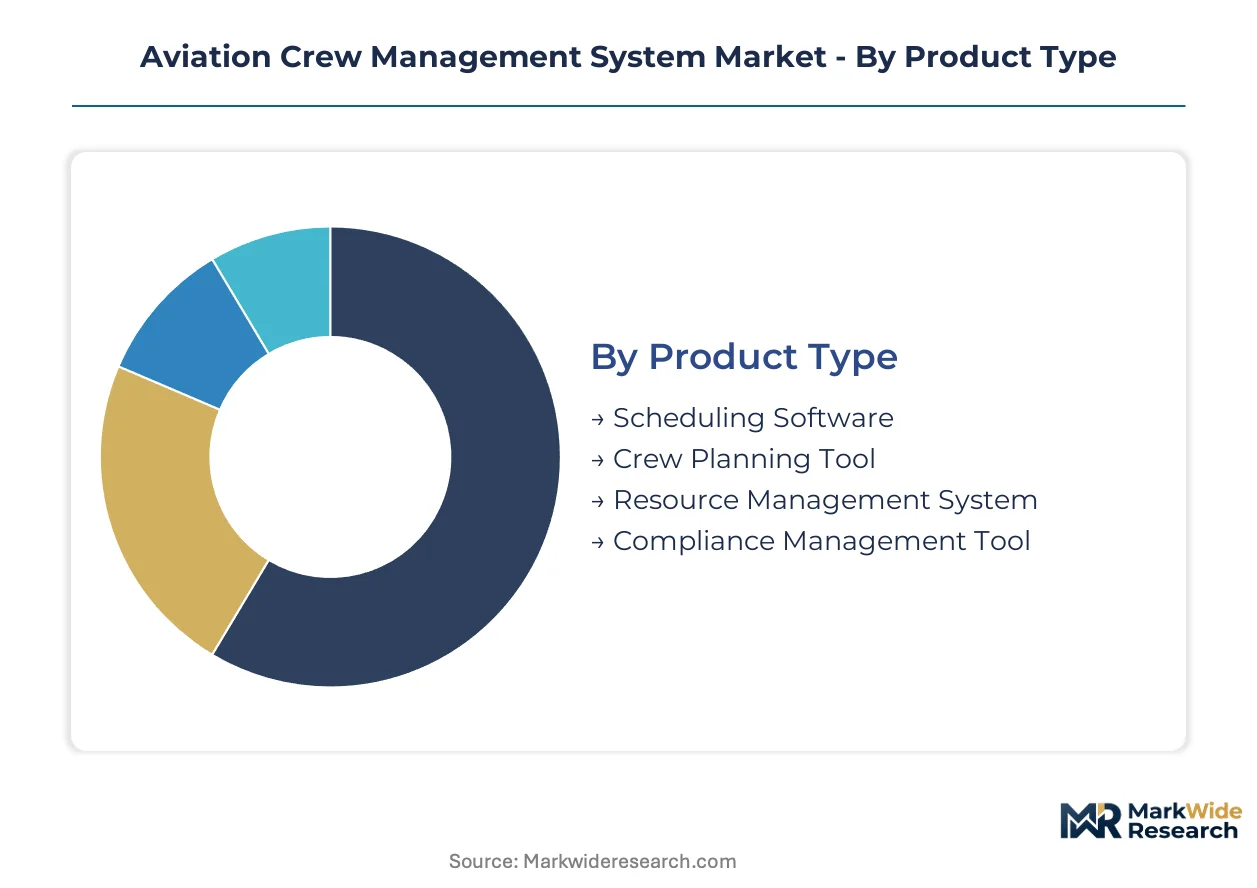
Airline procurement teams evaluate crew management platforms through four distinct lenses: product capability, infrastructure flexibility, operational role, and functional depth. Each segmentation axis reveals divergent buyer priorities between network carriers optimizing thousand-person crew bases and regional operators seeking lean compliance coverage.
Product Type:
Carrier IT budgets allocate disproportionately toward modules that directly reduce crew-related flight disruptions and regulatory penalties.
- Scheduling Software:Core platforms automate crew pairing, roster generation, and bid-line management against aircraft rotations and qualification matrices. Full-service airlines in the United States deploy these systems across pilot and cabin crew pools exceeding 10,000 staff to minimize uncovered flights during peak seasons.
- Compliance Management Tool:Specialized modules track duty-time limits, rest-period mandates, and fatigue-risk thresholds against FAA Part 117 and EASA EU-OPS Subpart Q requirements. These tools are gaining procurement priority fastest as regulators shift from retrospective logging to predictive alertness modeling.
- Crew Planning Tool:Long-term capacity planning software models crew hiring, training pipelines, and base restructuring against fleet expansion timelines.
- Resource Management System:Integrated platforms combining crew scheduling with aircraft maintenance and ground handling resource optimization.
Scheduling software leads on scale; compliance management tools lead on momentum.
Deployment:
Infrastructure decisions hinge on data sovereignty constraints, seasonal volatility exposure, and legacy system entrenchment.
- Cloud-Based:Elastic infrastructure scales compute resources during summer schedule peaks without capital-intensive mainframe upgrades. Network carriers retiring decades-old on-premise installations favor vendor-managed SaaS architectures that shift crew data storage and backup liability to platform providers.
- On-Premise:Self-hosted deployments persist at flag carriers with stringent data residency requirements or deep customization of optimization algorithms. These installations demand dedicated IT operations staff and multi-year hardware refresh cycles.
- Hybrid:Split architectures keep sensitive crew qualification records on-premise while pushing elastic roster computation to cloud instances.
- Mobile-Based:Lightweight crew-facing applications enabling schedule viewing, trip trading, and fatigue reporting through smartphone interfaces.
Cloud-based deployments are expanding most quickly; on-premise retains the largest installed base among legacy carriers.
End User:
Operational complexity and regulatory exposure vary sharply across buyer categories, driving divergent platform requirements.
- Airlines:Scheduled passenger carriers operate the largest crew bases and most intricate union agreement structures, demanding algorithmic rostering that manual processes cannot execute. Their procurement concentrates on integrated platforms bundling crew management with flight operations and revenue optimization.
- Cargo Carriers:Round-the-clock freighter networks with rapid timezone transitions and minimal ground time present concentrated demand for fatigue-risk algorithms. These operators require predictive crew alertness modeling that passenger airline platforms historically under-serve.
- Charter Operators:Ad-hoc flight providers with irregular scheduling patterns prioritize flexible crew assignment tools over long-term planning modules.
- Maintenance Providers:MRO facilities managing technician certifications and shift coverage apply adapted crew management frameworks to licensed personnel tracking.
Airlines dominate absolute spend; cargo carriers present the steepest expansion trajectory.
Functionality:
Module selection prioritizes capabilities that compress decision cycles and demonstrate regulatory defensibility.
- Resource Allocation:Optimization engines assign qualified crew to flight legs while respecting base constraints, training currencies, and union work rules. These systems process multi-objective functions balancing cost minimization, crew quality-of-life metrics, and operational robustness.
- Compliance Tracking:Automated monitoring of duty-time accumulations, rest-period sufficiency, and cumulative fatigue limits against jurisdiction-specific regulations. Carriers facing FAA enforcement actions or EASA audit findings treat this functionality as non-negotiable.
- Time Management:Clock-in/clock-out tracking, pay-rule calculation, and absence management for crew payroll integration.
- Reporting & Analytics:Dashboards and drill-down tools for crew utilization metrics, disruption root-cause analysis, and regulatory submission preparation.
Resource allocation commands the deepest feature investment; compliance tracking shows the fastest procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies as compliance-cost differentials between jurisdictions drive platform architecture decisions. Carriers in high-regulation markets demand predictive fatigue engines, while operators in emerging aviation hubs prioritize cost-efficient scheduling modules.
United States
Network carriers operate the world's largest crew bases, with American Airlines and Delta Air Lines each managing over 15,000 pilots and cabin crew. FAA Part 117 mandates automated duty-time tracking, forcing replacement of legacy compliance systems. Seattle hosts Jeppesen's flight operations data center, anchoring crew scheduling workflows for North American flag carriers.
Germany
Lufthansa Group's multi-hub structure drives demand for integrated crew planning across Frankfurt, Munich, and Zurich bases. EASA EU-OPS Subpart Q implementation requires predictive fatigue management with mathematical transparency. Lufthansa Systems dominates regional deployment from its Frankfurt headquarters, embedding jurisdiction-specific compliance modules.
United Kingdom
British Airways and easyJet operate complex multi-base crew contracts with work-rule variations requiring algorithmic rostering. CAA alignment with EASA post-Brexit maintains regulatory continuity while preserving UK-specific audit protocols. London Gatwick serves as a testing ground for biometric fatigue-monitoring pilots among low-cost carriers.
United Arab Emirates
Emirates and Etihad manage rapid timezone transitions across round-the-clock long-haul networks. GCAA regulations mirror ICAO standards with additional heat-stress provisions for summer operations. Dubai International Airport's crew logistics hub concentrates demand for elastic cloud-based rostering that scales with seasonal capacity swings.
Singapore
Singapore Airlines and Scoot operate high-utilization fleets with minimal ground time between sectors. CAAS fatigue-risk guidelines emphasize circadian rhythm disruption modeling for ultra-long-haul routes. Changi Aviation Park hosts regional crew training centers, creating adjacent demand for qualification-tracking modules.
Aviation Crew Management System Market Vendor Landscape
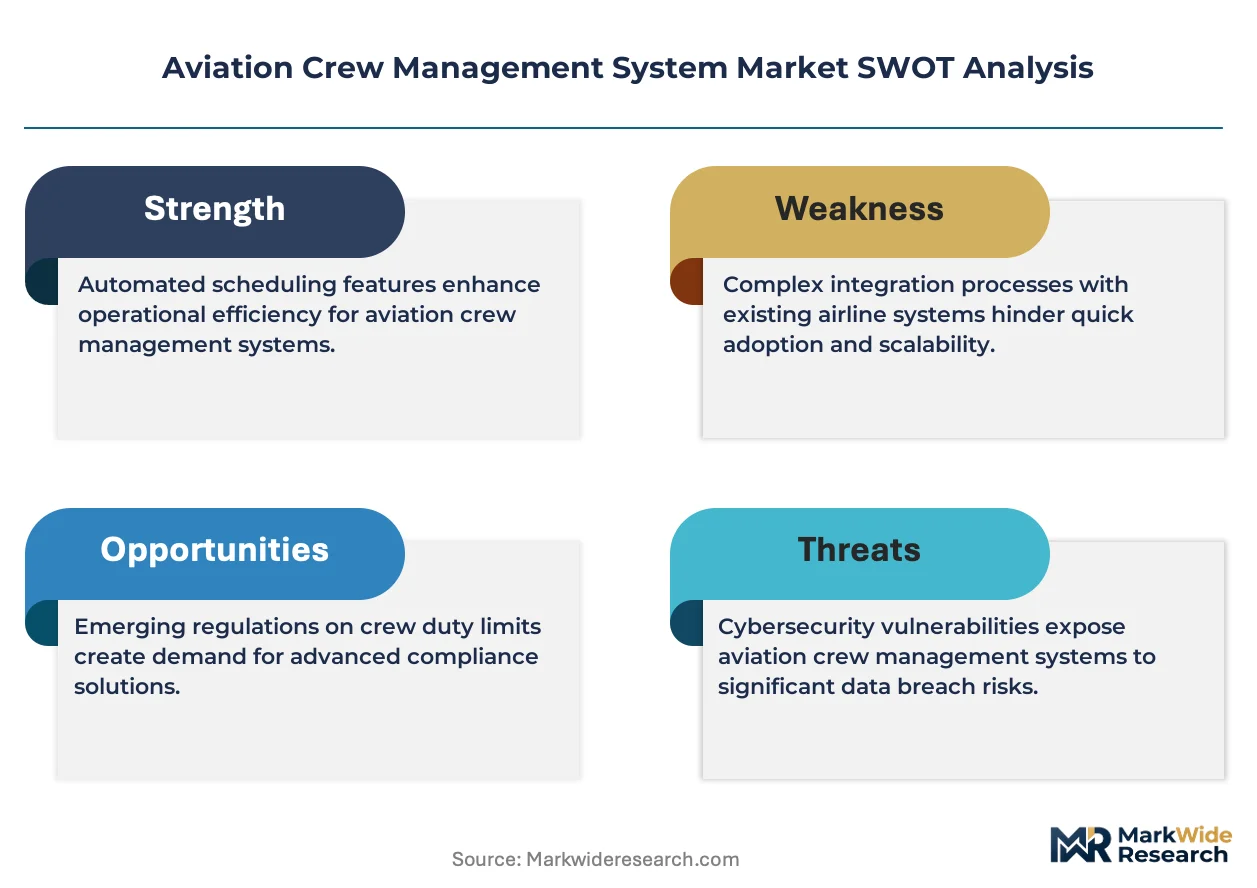
Established producers occupy the standard tier; emerging entrants pursue modular API architectures and biometric integration partnerships. The vendor base clusters around three strategic archetypes: aviation IT incumbents bundling crew management with flight operations suites, specialized optimization firms delivering algorithmic rostering engines, and airline-owned technology units commercializing proprietary platforms. Dominant competitive moves include strategic partnerships with wearable device manufacturers and geographic expansion through regulatory certification in secondary aviation markets.
Within the incumbent aviation IT tier, Jeppesen leverages its heritage in flight operations data to anchor crew scheduling workflows, while Sabre Corporation sustains competitive pressure through integrated airline IT portfolios. Lufthansa Systems exemplifies the airline-owned technology archetype, having commercialized proprietary platforms developed for internal Lufthansa Group operations. These three entities represent distinct competitive positioning strategies: data-anchored specialization, portfolio bundling, and captive-to-commercial platform evolution.
| Leading Market Players |
|---|
| Jeppesen |
| RAMCO Systems |
| AIMS |
| Oracle |
| Collins Aerospace |
| Sabre Corporation |
| Honeywell International Inc. |
| Symphony Solutions |
| Lufthansa Systems |
| Others |
Supply Flow & Price Mechanics
Captive software development at major airline IT divisions anchors supply positions while creating pricing power through bundled platform architectures. Jeppesen, Sabre Corporation, and Lufthansa Systems leverage in-house optimization engines to command premium positioning against modular competitors, with FAA Part 117 compliance requirements reinforcing buyer lock-in and supporting subscription pricing resilience.
Pricing Analysis
Direct-to-airline enterprise sales with volume-scaled SaaS tiers dominate the channel structure. Three-tier pricing stratifies across enterprise flag carriers, mid-size network operators, and regional charter fleets based on crew base scale and integration complexity. Certification depth—particularly FAA Part 117 and EASA EU-OPS Subpart Q validation tiers—drives price differentiation alongside after-sales implementation support. Pricing pressure stems from cloud-native entrants offering modular APIs at lower entry points. Regional carriers and corporate flight departments exhibit highest price sensitivity, while full-service network carriers prioritize compliance defensibility over cost minimization.
Supply Chain Analysis
Returns and refurbishment flows are minimal given software-as-a-service delivery, though legacy mainframe migration creates upgrade-cycle revenue streams for incumbent vendors. Development talent concentrates in the United States, Germany, and India, with Seattle, Frankfurt, and Bangalore hosting primary engineering centers. Cloud infrastructure draws from AWS, Azure, and Google Cloud regions, while specialized aviation operations research expertise remains scarce and geographically clustered. Single-source vulnerability persists in fatigue-risk algorithm development where PhD-level operations research talent is concentrated. Distribution runs through direct enterprise sales teams and aviation IT systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA Part 117 mandates and EASA EU-OPS Subpart Q updates continuously expand compliance-addressable demand.
For Market Incumbents: Acquire specialized fatigue-prediction algorithm teams to counter biometric-integrated entrants. Consolidate position by embedding predictive alertness modules deeper into flight operations suites before modular APIs gain traction. Prioritize certification investment in secondary aviation markets where regulatory harmonization with ICAO standards creates expansion pathways. For New Entrants and Emerging Players: Cargo carriers with round-the-clock freighter operations represent the most penetrable buyer archetype, as incumbent platforms historically under-serve their fatigue-risk modeling requirements. Target charter operators seeking subscription-based access with vendor-managed infrastructure over capital-intensive deployments. Pursue wearable device partnerships as the primary go-to-market angle, offering biometric data ingestion as a differentiated module. For Investors and Strategic Acquirers: Roll-up economics work for specialized optimization firms because airline procurement teams increasingly favor best-of-breed algorithmic engines over monolithic suites. Long-term viability hinges on regulatory certification moats deepening through multi-jurisdictional validation. Monitor EASA CSRD alignment for crew positioning emissions reporting as the inflection signal indicating carbon-optimized rostering module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Integration Partnership | Wearable sleep monitor alliances enable predictive fatigue blocking for FAA Part 117 compliance. |
| Multi-Jurisdictional Certification | Simultaneous FAA, EASA, and ICAO validation eliminates code forks and accelerates airline deployment. |
| Cargo Carrier Platform Adaptation | Specialized fatigue algorithms for freighter networks address underserved round-the-clock operations. |
| Cloud Migration Services | Legacy mainframe retirement programs capture seasonal elasticity demand from network carriers. |
| Carbon-Optimized Rostering Module | EASA CSRD alignment for crew positioning emissions creates sustainability-linked procurement criteria. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, United Arab Emirates, and Singapore, with primary inputs from each regional aviation authority cluster. The analysis combines structured interviews with airline crew planning directors, aviation IT procurement officers, flight operations executives, and regulatory compliance leads with secondary validation from FAA enforcement actions, EASA certification databases, ICAO standards documentation, and airline annual reports. Bottom-up crew base sizing and top-down IT spending allocation triangulate market estimates across deployment models and end-user categories.
Granularity-level modeling addresses product type, deployment architecture, end-user segment, and functional module depth, with crew base scale and union agreement complexity treated as cross-cutting variables. CAGRs derive from segment-specific adoption curves weighted by regulatory mandate timing and cloud migration velocity. Forecast inputs include airline fleet expansion schedules, pilot training pipeline forecasts, and fatigue-risk algorithm development trajectories from aviation research institutions.
Underlying measurement precision varies by segment; cloud-based deployment and compliance management tool categories carry tighter precision than hybrid infrastructure and resource management system estimates due to vendor disclosure patterns. Forecasts reflect assumptions regarding regulatory harmonization pace and mainframe retirement timelines. Practitioners should monitor EASA audit finding trends and biometric pilot program outcomes for early signals of platform architecture preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Middle-East Aviation Market
Aircraft
Global Business Aircraft Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
GCC Business Jet Market
Aircraft
Firefighting Aircraft Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
Europe General Aviation Market
Aircraft
Tanker Aircraft Market
Aircraft
Air Speed Indicator Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Airplane Brackets Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Air Deflector Market