
 Coated Fabrics for Defense Market | 2026-2036
Coated Fabrics for Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Fabrics for Defense Market Outlook
United States production capacity is narrowing the gap between domestic supply and military procurement requirements. DuPont leverages its aramid fiber heritage to anchor premium ballistic fabric lines for armor covers. Teijin Aramid competes through sustained R&D intensity in high-tenacity polyethylene composites. Sioen Industries NV specializes in multi-layer coating architectures that dominate European tactical shelter supply.
Coated fabrics for defense are textile substrates impregnated with polymer layers—typically polyurethane, silicone, or fluoropolymer at 0.1–2.0 mm coating thickness—to achieve ballistic resistance, chemical protection, or environmental sealing for military equipment. Flame-retardant technology commands the widest deployment across tent and tarpaulin applications where NFPA 701 and MIL-PRF-44103 compliance is mandatory. Polyurethane coated fabrics retain cost advantages in vehicle interiors, though silicone coated variants capture margin pools in extreme-climate armor cover programs where thermal stability exceeds 200°C.
FDA oversight of per- and polyfluoroalkyl substances intersects with EPA toxicity assessments to restrict legacy fluoropolymer chemistries in defense textiles, compelling reformulation across supplier bases. REACH registration requirements in Europe and MIL-SPEC conformity in the United States create divergent compliance pathways that fragment procurement standards. Stakeholders must monitor evolving chemical restriction lists and dual-use export controls to anticipate which coating platforms will retain military qualification status.
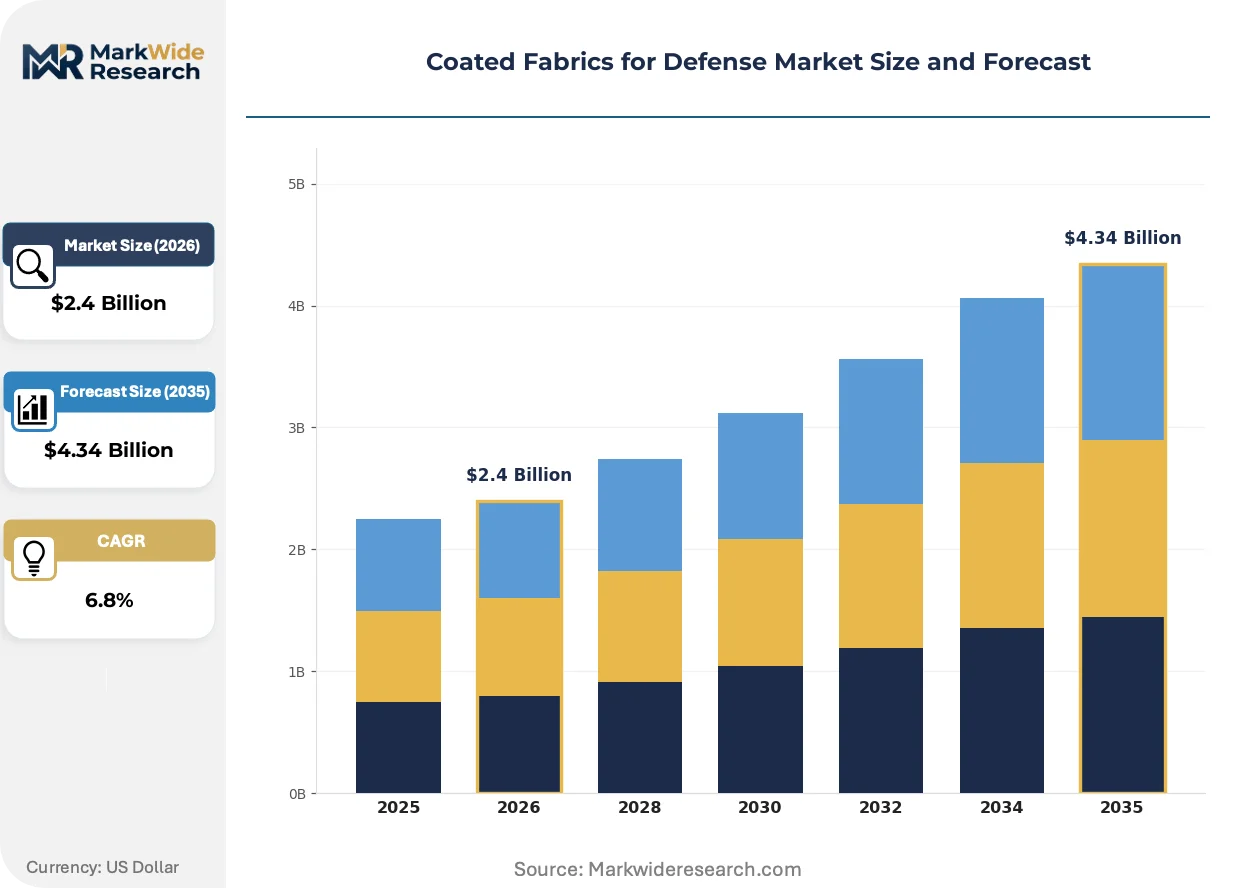
Market Dynamics
REACH chemical restrictions are forcing polyurethane-dependent suppliers to rebuild coating platforms around silicone and fluoropolymer alternatives, compressing formulation timelines while NATO procurement volumes expand.
Growth Catalysts
- Expeditionary Infrastructure Modernization:NATO allies are accelerating flame-retardant tent system acquisitions to replace aging field shelters. MIL-PRF-44103 compliance requirements are tightening specification standards across allied procurement.
- REACH Chemical Phase-Out:The EU's framework is eliminating legacy polyurethane chemistries from defense textile supply chains. Suppliers investing in silicone alternatives are securing qualification advantages in European tactical shelter programs.
- Extreme-Climate Armor Programs:Thermal stability demands exceeding 200°C are pulling demand toward silicone-coated variants. Vehicle interior specifications in Arctic and desert deployments are specifying these materials for ballistic cover applications.
Market Restraints
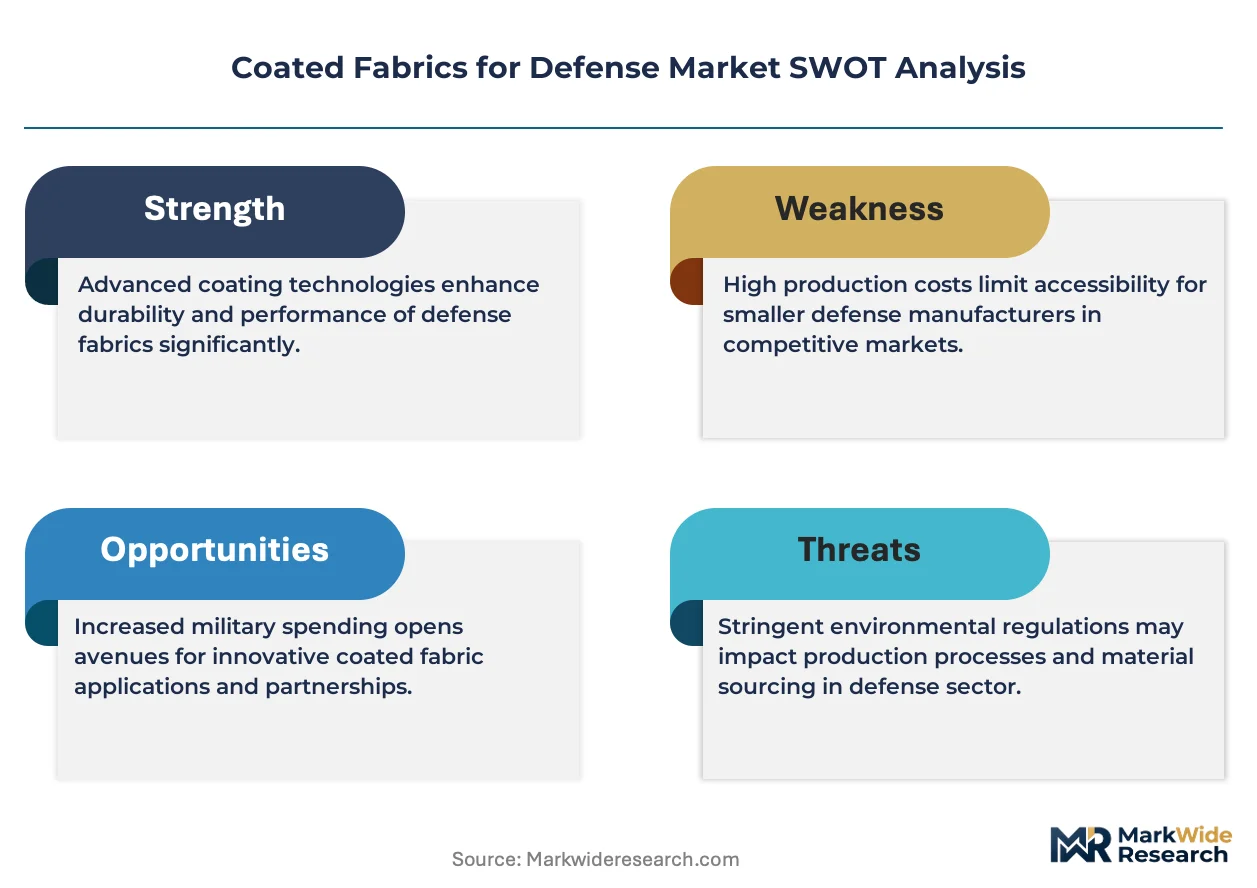
- Aramid Fiber Supply Concentration:High-tenacity para-aramid production clusters in the United States and Japan create single-source vulnerability for ballistic fabric substrates. Disruption risks concentrate in precursor chemical supply from these geographies.
- Fluoropolymer Toxicity Assessments:EPA evaluations of per- and polyfluoroalkyl substances are restricting legacy fluoropolymer chemistries despite their military performance advantages. Reformulation costs are absorbing R&D budgets without immediate volume returns.
- Dual-Use Export Control Friction:Wassenaar Arrangement classification of high-performance coated fabrics complicates cross-border supplier relationships. Licensing delays extend qualification timelines for multinational defense contractors.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for technical textiles is creating localized coating capacity for ballistic applications. Domestic suppliers are qualifying under BIS standards for army vehicle interior programs.
- Multi-Layer Architecture Convergence:Integration of conductive coatings with traditional ballistic substrates is enabling electromagnetic shielding functions. This hybrid approach opens electronic warfare protection applications previously served by separate material systems.
- Digital Specification Platforms:Military procurement agencies are migrating vendor qualification to centralized digital portals. Early platform adopters are compressing sales cycles and reducing specification friction in multi-year vehicle programs.
Industry Challenges
- MIL-SPEC Certification Timelines:Qualification protocols for new coating chemistries extend 18-36 months before volume procurement authorization. Suppliers face working capital strain during pre-revenue qualification phases.
- Coating Technician Skill Scarcity:Precision thickness control at 0.1-2.0 mm specifications requires specialized polymer processing expertise. Defense textile manufacturers compete with automotive and aerospace sectors for this limited talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Fabrics for Defense Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Coated, Polyurethane Coated, Silicone Coated, Fluoropolymer Coated End User: Military, Defense Contractors, OEMs, Government Agencies Application: Tents, Tarpaulins, Armor Covers, Vehicle Interiors Technology: Digital Printing, Flame Retardant, Water Resistant, UV Resistant |
| Companies Covered | DuPont, Teijin Aramid, Toray Industries, Sioen Industries NV, Saint-Gobain Performance Plastics, Koninklijke Ten Cate NV, Serge Ferrari Group, Glen Raven, Kolon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Fabrics for Defense Market Strategic Shifts
Computational materials design is compressing formulation development cycles while regulatory chemistry restrictions are fragmenting coating technology roadmaps across defense procurement zones.
Digital twin platforms are virtualizing coated fabric performance prediction before physical prototyping. Defense contractors in the United States are adopting these simulation tools to compress MIL-SPEC qualification timelines. This virtualization is reducing iteration costs for multi-layer ballistic architectures while accelerating supplier selection decisions.
ECHA substance restriction proposals are expanding beyond legacy fluoropolymers to scrutinize silicone crosslinking agents used in extreme-temperature armor covers. European defense textile suppliers are pre-emptively reformulating coating platforms to maintain REACH registration validity. The tactical shelter segment faces the most immediate compliance pressure given its higher surface-area-to-mass ratios.
Consolidated buying through defense ministry digital procurement portals is compressing vendor relationship cycles. Large-volume armor cover contracts in the United States are migrating to centralized Defense Logistics Agency platforms. This channel shift favors suppliers with existing platform integration over traditional field-sales-dependent competitors.
Coated Fabrics for Defense Market Segmentation
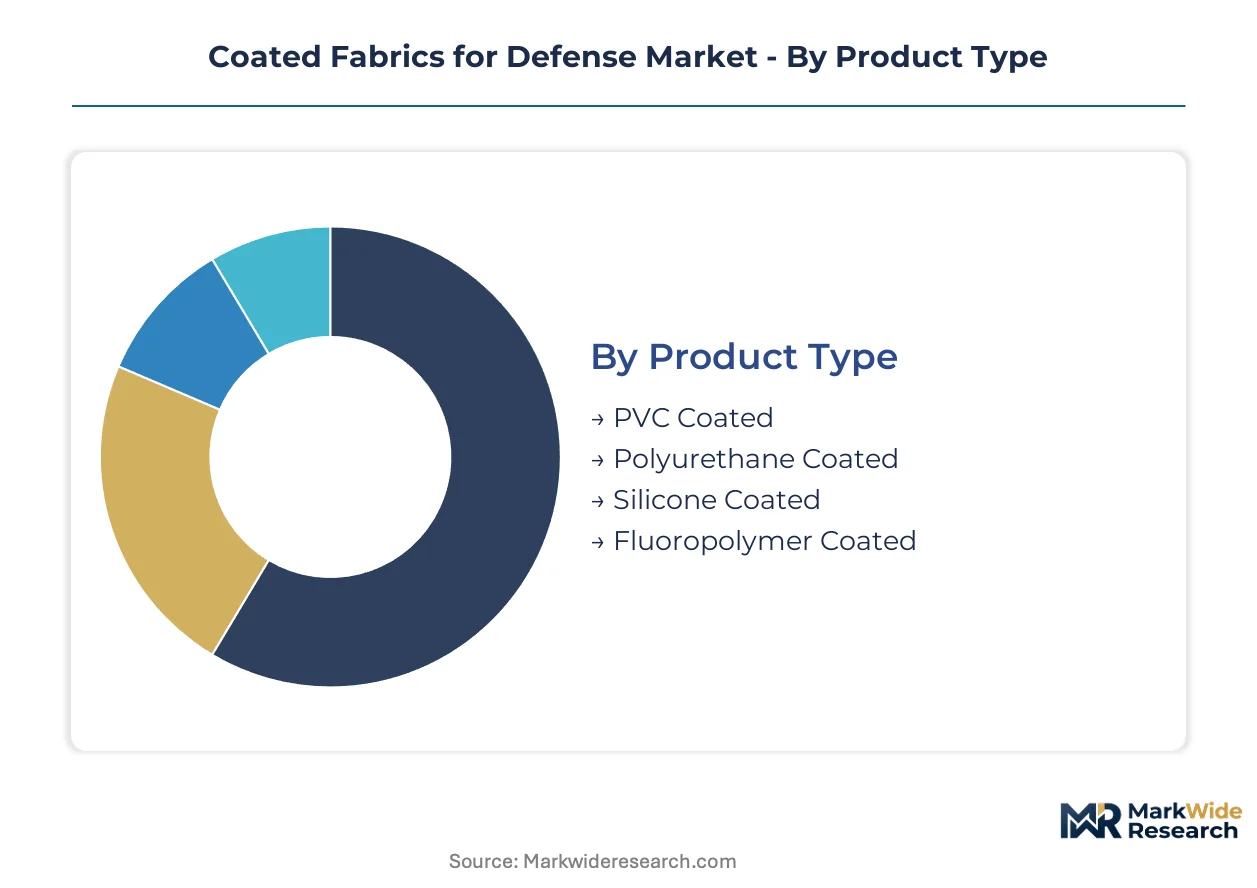
Defense procurement fragmentation demands precise segment targeting. Specification divergence between NATO allies and national military standards creates distinct qualification pathways for each coating platform and end-use category.
Product Type:
After-sales service intensity varies sharply across coating chemistries, with silicone and fluoropolymer platforms requiring specialized field repair protocols that military maintenance units must certify.
- Polyurethane Coated:These fabrics combine polyester or nylon substrates with 0.1–2.0 mm polyurethane layers, delivering cost-efficient abrasion resistance for vehicle interior programs. Demand concentrates in United States Department of Defense contracts where MIL-PRF-44103 compliance is mandatory, though EPA toxicity assessments are forcing reformulation timelines.
- Silicone Coated:Thermal stability exceeding 200°C positions these variants for extreme-climate armor cover applications. Arctic and desert deployment specifications in NATO expeditionary programs are pulling procurement toward silicone platforms as REACH restrictions eliminate competing polyurethane chemistries.
- PVC Coated:Legacy formulations retain position in training equipment and non-combat shelters where cost minimization overrides performance thresholds.
- Fluoropolymer Coated:Chemical resistance supremacy sustains niche deployment in CBRN protection systems despite FDA and EPA restrictions on per- and polyfluoroalkyl substances.
By volume, polyurethane coated fabrics lead. By growth pace, silicone coated variants are expanding most quickly.
End User:
Contracting authority concentration shapes procurement velocity, with direct military acquisition moving faster than delegated contractor channels.
- Military:National defense ministries issue large-volume, multi-year contracts for tent systems and armor covers. United States Defense Logistics Agency platforms are consolidating vendor qualification, compressing sales cycles for integrated suppliers.
- Defense Contractors:Tier-1 systems integrators source coated fabrics for platform integration, requiring dual-use export control compliance under Wassenaar Arrangement classifications that extend qualification timelines.
- OEMs:Vehicle manufacturers specify coated fabrics for original equipment programs, with BIS standards governing Indian army vehicle interior qualifications under PLI scheme incentives.
- Government Agencies:Civil defense and emergency management procurement operates outside MIL-SPEC frameworks, accepting commercial-grade flame-retardant alternatives.
By contract value, military end users dominate. By qualification flexibility, government agencies permit fastest supplier entry.
Application:
Surface-area-to-mass ratios determine coating thickness precision requirements, with tent systems demanding uniform large-format processing that strains production capacity.
- Tents:Flame-retardant expeditionary shelters require NFPA 701 and MIL-PRF-44103 compliance across NATO modernization programs. REACH chemical restrictions are eliminating legacy polyurethane formulations from European tactical shelter supply chains.
- Armor Covers:Ballistic protection substrates integrate with multi-layer coating architectures for vehicle and personnel protection. Thermal stability specifications in extreme-climate deployments are specifying silicone-coated variants.
- Tarpaulins:General-purpose equipment covers prioritize cost efficiency over performance margins in non-combat logistics applications.
- Vehicle Interiors:Cabin lining specifications balance acoustic dampening with abrasion resistance, with polyurethane platforms retaining cost advantages in high-volume programs.
By procurement volume, tent systems lead. By margin capture, armor covers command premium positioning.
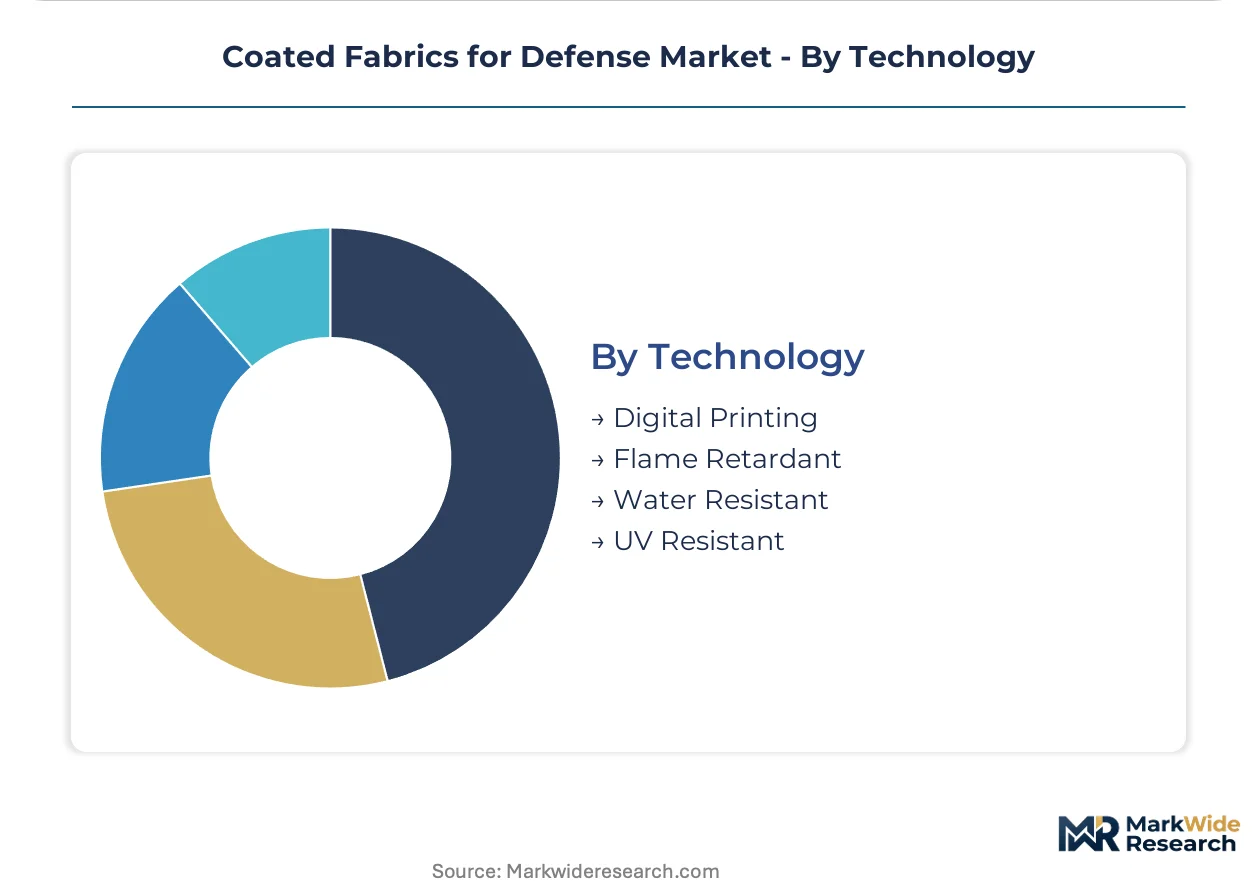
Technology:
Functional coating integration determines platform qualification status, with flame-retardant chemistry mandatory across all defense applications.
- Flame Retardant:Halogen-free formulations are displacing legacy chemistries as ECHA substance restrictions expand scrutiny to crosslinking agents. European tactical shelter suppliers face immediate compliance pressure.
- Water Resistant:Hydrophobic coating layers protect electronic equipment and medical supplies in field deployment, with specification tightening under MIL-PRF-44103 revisions.
- UV Resistant:Photostabilizer additives extend service life in desert and high-altitude deployments where solar degradation accelerates substrate failure.
- Digital Printing:Camouflage pattern application enables rapid theater-specific adaptation, with defense contractors adopting digital twin platforms to virtualize performance before physical prototyping.
By specification ubiquity, flame-retardant technology leads. By innovation investment, digital printing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European defense logistics, channeling coated fabric shipments to NATO expeditionary programs. The Trans-Siberian Railway corridor links Russian Far East production to Central Asian military supply chains. The Port of Long Beach handles Pacific Rim polymer imports feeding United States armor cover manufacturing.
United States
The Defense Logistics Agency consolidates large-volume contracts for tent systems and vehicle interior programs. EPA toxicity assessments of per- and polyfluoroalkyl substances are restricting legacy fluoropolymer chemistries in military textiles. DuPont maintains aramid fiber production in Virginia, anchoring premium ballistic fabric supply for armor cover applications.
Germany
Bundeswehr modernization drives demand for flame-retardant expeditionary shelters meeting MIL-PRF-44103 standards. ECHA substance restrictions under REACH are eliminating polyurethane formulations from tactical shelter supply chains. Industrial clusters in North Rhine-Westphalia host specialized coating facilities serving NATO procurement channels.
India
Army vehicle interior programs are accelerating under the PLI scheme for technical textiles. BIS standards govern domestic supplier qualification for ballistic fabric applications. Manufacturing corridors in Gujarat are attracting coating capacity investments targeting defense indigenization mandates.
Japan
Self-Defense Forces procurement specifies high-tenacity polyethylene composites for extreme-climate armor covers. METI industrial policy supports advanced materials R&D in polymer processing technologies. Osaka-based industrial zones concentrate precision coating expertise for military specification compliance.
United Kingdom
Strategic Command modernization prioritizes multi-layer coating architectures for CBRN protection systems. Ministry of Defence digital procurement portals are compressing vendor qualification timelines. Defense textile suppliers in the Midlands are securing platform integration contracts for vehicle shelter programs.
Coated Fabrics for Defense Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate and polymer supply. The market structures around three tiers: aramid fiber heritage players, multi-layer coating architects, and regional qualification specialists. Consolidation pressures concentrate in European tactical shelter supply where REACH compliance barriers favor incumbents with reformulation capabilities. Competitive moves center on silicone platform investments and digital procurement portal integration.
Within the fiber heritage tier, DuPont and Teijin Aramid exemplify substrate-to-fabric vertical control. Sioen Industries NV occupies a position among European multi-layer specialists. These three anchors represent divergent strategic postures: DuPont leverages United States military contract concentration; Teijin Aramid anchors high-tenacity polyethylene innovation; Sioen dominates tactical shelter qualification pathways under ECHA regulatory frameworks.
| Leading Market Players |
|---|
| DuPont |
| Teijin Aramid |
| Toray Industries |
| Sioen Industries NV |
| Saint-Gobain Performance Plastics |
| Koninklijke Ten Cate NV |
| Serge Ferrari Group |
| Glen Raven |
| Kolon Industries |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's specialized coating facilities channel polyurethane and silicone formulations into NATO procurement streams, with capacity utilization rates directly transmitting into contract pricing power for European tactical shelter suppliers. DuPont's Virginia aramid fiber operations and Teijin's high-tenacity polyethylene lines in Japan anchor premium ballistic fabric pricing through substrate scarcity rather than coating competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MIL-SPEC-qualified armor covers from commercial-grade tarpaulins and training equipment. Certification grade under REACH and MIL-PRF-44103 standards drives price differentiation alongside volume scale in Defense Logistics Agency contracts. Cost compression in polyurethane formulations is intensifying because EPA toxicity assessments are forcing reformulation timelines without immediate volume returns. Defense contractors show least price sensitivity for extreme-climate armor programs, while government agencies for civil defense procurement exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability in para-aramid precursor supply dominates risk exposure between United States and Japanese production clusters. Raw material dependencies center on aramid fibers, high-tenacity polyethylene resins, and specialized silicone crosslinking agents. Distribution runs through defense ministry digital procurement portals that compress vendor relationship cycles and favor platform-integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across NATO allies and divergent REACH-MIL-SPEC compliance pathways is fragmenting the market into qualification-niche opportunities. Digital specification platform migration by military agencies accelerates this niche creation by rewarding early integrators.
For Market Incumbents: Insulate qualification advantages by accelerating silicone platform investments ahead of ECHA substance restriction expansions. Deepen backward integration into aramid fiber supply through captive production or long-term offtake agreements with Virginia and Japanese precursor facilities. Channel control through Defense Logistics Agency platform integration defends against emerging multi-layer coating specialists.
For New Entrants and Emerging Players: Pursue India's PLI scheme technical textile incentives as the most penetrable geography, where BIS standard qualification offers faster entry than NATO MIL-SPEC pathways. Target army vehicle interior programs under domestic indigenization mandates. Digital procurement portal adoption serves as the critical go-to-market angle for compressing sales cycles against field-sales-dependent incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-layer coating architects with REACH reformulation capabilities over legacy polyurethane-dependent suppliers. Long-term viability rests on electromagnetic shielding integration and conductive coating convergence for electronic warfare applications. Watch ECHA substance restriction proposal expansion beyond fluoropolymers to silicone crosslinking agents as the inflection signal for coating platform obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Platform Investment | REACH compliance advantage secures European tactical shelter procurement against polyurethane phase-out. |
| Digital Procurement Portal Integration | Defense Logistics Agency platform adoption compresses vendor qualification timelines for armor cover contracts. |
| Aramid Fiber Backward Integration | Captive substrate supply insulates against United States-Japan production concentration risk. |
| Conductive Coating Convergence | Electromagnetic shielding integration opens electronic warfare protection applications for multi-layer architectures. |
| India PLI Scheme Localization | BIS qualification under technical textile incentives captures army vehicle interior indigenization demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, EPA toxicity assessment filings, and ECHA substance restriction proposals. Primary interviews engaged coating technology directors, defense textile procurement officers at NATO ministries, polymer processing plant managers, and REACH compliance specialists. Secondary validation drew from customs trade data, SEC 10-K disclosures by listed suppliers, and MIL-SPEC revision documentation. Bottom-up segment sizing triangulates against top-down defense budget allocation analysis.
Forecast inputs span coating chemistry platform, end-user contracting authority, application surface-area requirements, and regional regulatory framework clusters. Modeled segmentation dimensions include product type, end user, application, and technology functional integration. CAGRs derive from volume trajectory analysis across the projection horizon, incorporating NATO expeditionary infrastructure modernization schedules and REACH chemical phase-out timelines as defense-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in defense budget cycles or polymer feedstock commodity volatility would shift the trajectory. Forecasts reflect documented assumptions regarding qualification timeline stability and regulatory restriction implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Russia Space Electronics Market