
 High-Temperature Composite Exhaust and Thrust Reverser External Panels Market | 2026-2036
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market Insights
The gap between thermoset and thermoplastic processing for high-temperature engine-adjacent structures is narrowing as resin chemistry advances. Collins Aerospace leverages its vertical integration across nacelle systems to sustain design-to-manufacture control. Safran Nacelles anchors European supply through its Le Havre production complex. GKN Aerospace competes on automated fiber placement scale for complex-curvature exhaust components.
High-temperature composite exhaust and thrust reverser external panels are laminated or molded structures, typically carbon fiber reinforced with bismaleimide or polyimide resin matrices, designed to withstand sustained operating temperatures exceeding 180°C while maintaining structural integrity under aerodynamic and acoustic loading. These panels enclose and protect propulsion system aft sections, manage thermal gradients, and contribute to airframe noise attenuation during takeoff and landing operations. Carbon fiber panels dominate current procurement volumes given their specific strength and established qualification pathways, while ceramic matrix composite segments capture premium positions where sustained temperatures exceed 220°C and oxidation resistance becomes critical. Commercial jets absorb the majority of panel demand, though military fighter programs are shifting toward resin transfer molding techniques to reduce autoclave bottlenecks and accelerate fabrication cycles.
FAA Part 25 Appendix F fireworthiness standards and EASA CS-25 certification requirements govern material flammability, heat release, and smoke density specifications for these panels, effectively filtering supplier eligibility to firms with sustained airworthiness qualification investment. The EPA's National Emission Standards for Hazardous Air Pollutants also shape manufacturing facility compliance costs for resin curing operations. Stakeholders must monitor evolving OEM sustainability mandates around recycled fiber content and out-of-autoclave process validation, as these criteria increasingly determine contract eligibility rather than serving as optional differentiators.
Market Dynamics
Autoclave throughput constraints at Tier-1 aerostructures suppliers are forcing a process technology pivot toward out-of-autoclave curing methods for bismaleimide exhaust panels. This bottleneck concentrates procurement leverage with OEMs holding captive autoclave capacity.
Growth Catalysts
- FAA Part 25 Appendix F:Tightening flammability thresholds for heat release and smoke density are disqualifying legacy phenolic resin formulations, opening procurement slots for qualified bismaleimide and polyimide suppliers.
- Single-aisle commercial jet ramp:Boeing and Airbus production rate increases for narrowbody programs are pulling panel demand through multi-year procurement agreements with nacelle integrators.
- Ceramic matrix composites:Sustained operating temperatures above 220°C in next-generation turbofan architectures are expanding addressable applications beyond carbon fiber limits.
Market Restraints
- Acrylonitrile price volatility:Precursor carbon fiber costs fluctuate with oil-derived feedstock markets, compressing margin predictability for panel laminators without long-term resin supply hedges.
- Seattle-Wichita supply concentration:Aerostructures fabrication clusters in the United States concentrate qualified autoclave capacity, creating geographic vulnerability to regional labor disruptions or weather events.
- Thermoplastic qualification timelines:Polyaryletherketone resin systems for reusable tooling face multi-year FAA certification cycles that delay cost-reduction pathways versus thermoset baselines.
Strategic Opportunities
- Out-of-autoclave process validation:Electron beam and microwave curing technologies are compressing cycle times and enabling facility footprints outside legacy aerospace clusters.
- Recycled fiber content mandates:OEM sustainability scorecards are creating contract eligibility thresholds for reclaimed carbon fiber integration in non-structural exhaust fairings.
- Military fighter programs:Resin transfer molding adoption for thrust reverser components offers faster fabrication cycles and lower capital intensity than commercial autoclave methods.
Industry Challenges
- Airworthiness qualification expertise:FAA Designated Engineering Representative scarcity extends certification timelines for new material formulations, particularly for small and mid-tier suppliers.
- Automated fiber placement integration:Complex-curvature exhaust geometries require programming specialization that outpaces current workforce training pipelines at fabrication facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Temperature Composite Exhaust and Thrust Reverser External Panels Market |
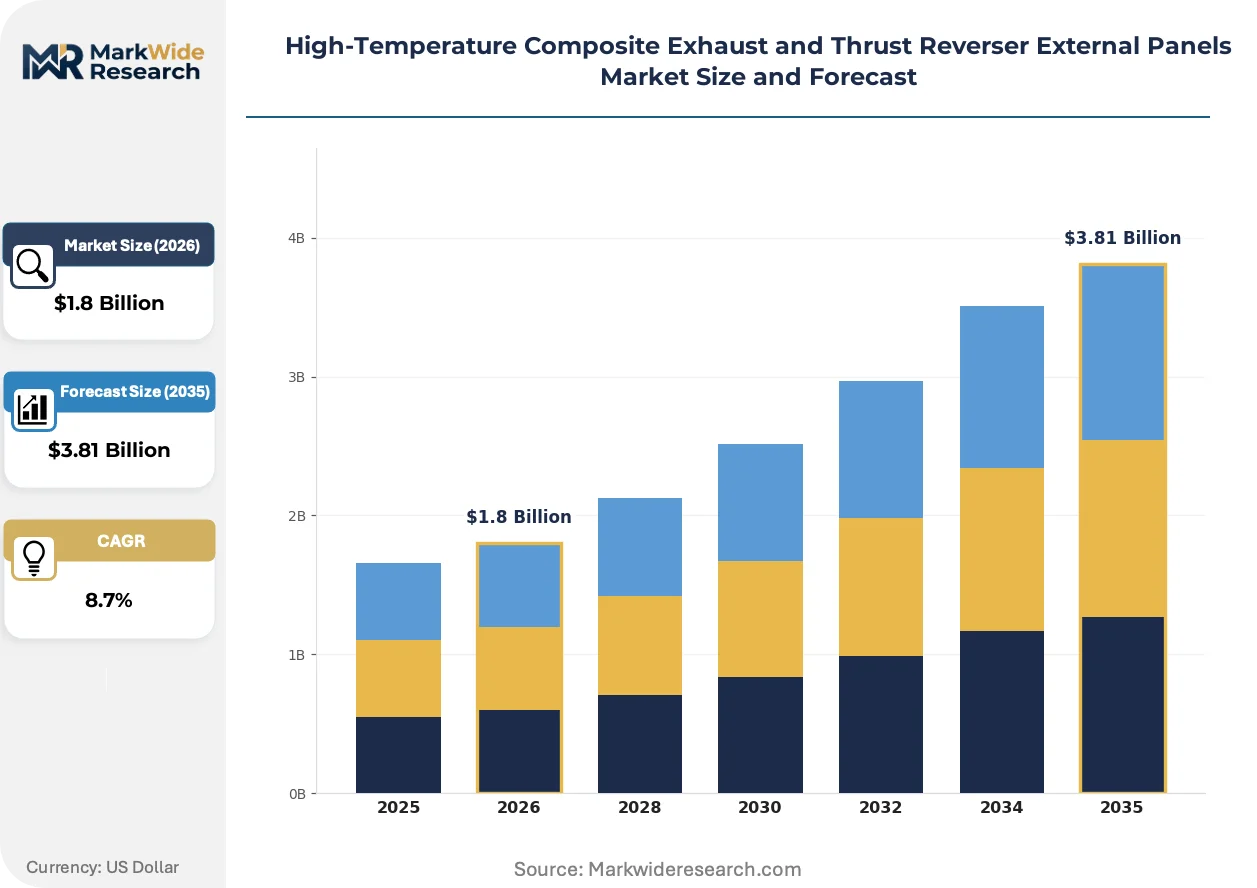
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Ceramic Matrix Composite, Glass Fiber, Aramid Fiber Panel Function: Exhaust Systems, Thrust Reverser, Acoustic Liners, Thermal Shielding Aircraft Class: Commercial Jets, Business Jets, Military Fighters, Regional Airliners Manufacturing Technique: Resin Transfer Molding, Autoclave, Filament Winding, Compression Molding |
| Companies Covered | Collins Aerospace, Safran Nacelles, Spirit AeroSystems, FACC AG, GKN Aerospace, Aernnova Aerospace, Magellan Aerospace, The NORDAM Group, Royal Engineered Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market Trends and Innovations
Process chemistry advances are collapsing the performance gap between thermoset and thermoplastic matrices for engine-adjacent structures. Three developments are restructuring supplier capabilities and procurement criteria.
Out-of-autoclave bismaleimide formulations with vacuum-assisted resin transfer molding are rendering obsolete traditional autoclave curing for large-curvature exhaust fairings. Tier-1 nacelle integrators are validating these processes for single-aisle programs to bypass capacity constraints. The shift is compressing supplier qualification hierarchies toward firms with electron beam or microwave curing infrastructure.
EASA CS-25 smoke toxicity amendments are tightening hydrogen cyanide emission limits for cabin-proximate nacelle materials. European OEM procurement specifications now require third-party testing beyond baseline FAA Appendix F compliance. This regulatory layering favors suppliers with dual-certification laboratory partnerships in France and Germany.
Long-term throughput agreements are displacing spot procurement for high-temperature composite panels. Airlines and lessors are pushing risk onto OEMs, who then mandate fixed-price multi-year contracts from nacelle system suppliers. This concentration of procurement leverage is most visible in United States-based single-aisle final assembly lines.
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market Segmentation
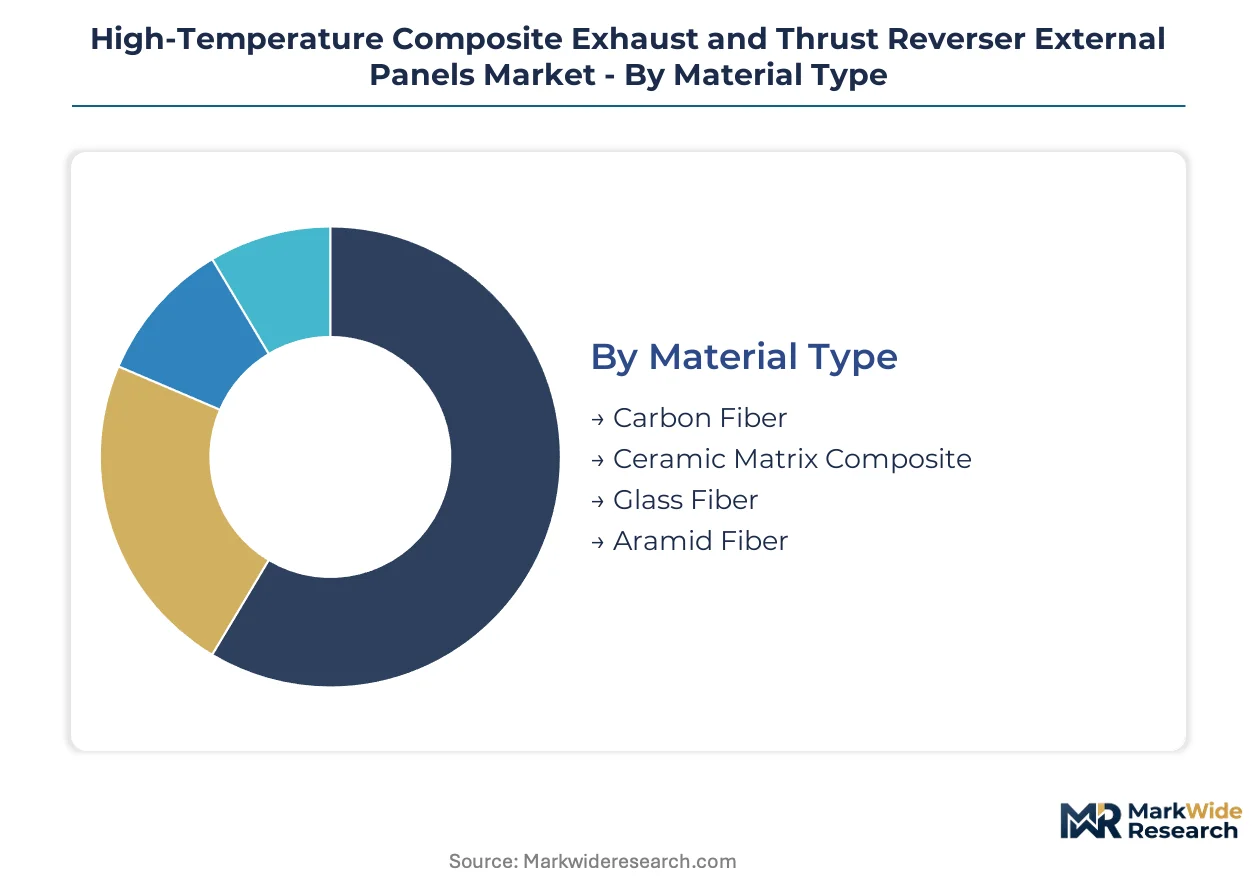
Segmentation in high-temperature composite panels reveals how material chemistry, functional location, and fabrication method intersect to determine contract eligibility and margin structure. Each dimension filters supplier capabilities against airworthiness qualification requirements and OEM procurement specifications.
Material Type:
Cost tier differentiation separates commodity fiber positions from premium matrix systems qualified for sustained thermal loading.
- Carbon Fiber:Bismaleimide and polyimide resin matrices dominate procurement volumes given established FAA Appendix F qualification pathways and specific strength performance. Demand concentrates at Boeing and Airbus single-aisle final assembly lines where multi-year procurement agreements favor qualified laminators with captive autoclave capacity in Wichita and Seattle.
- Ceramic Matrix Composite:Silicon carbide fiber reinforced with ceramic matrices withstand sustained operating temperatures exceeding 220°C where oxidation resistance becomes critical. Applications are rotating up the share rankings in next-generation turbofan architectures pushing thermal management limits.
- Glass Fiber:Lower-cost phenolic formulations retain positions in non-structural fairings where flammability thresholds are less stringent.
- Aramid Fiber:Kevlar-reinforced panels occupy niche acoustic attenuation roles in thrust reverser cascades requiring impact resistance.
Carbon fiber holds installed capacity. Ceramic matrix composite is rotating up the share rankings.
Panel Function:
Application location within the propulsion system determines thermal gradient exposure and regulatory scrutiny intensity.
- Exhaust Systems:Aft-fuselage panels enclose core engine sections where temperatures exceed 180°C continuously. Collins Aerospace and Safran Nacelles anchor supply through vertical integration across nacelle system architectures.
- Thrust Reverser:External cascades deploy during landing operations and must maintain structural integrity under aerodynamic loading plus acoustic fatigue. Military fighter programs are accelerating resin transfer molding adoption here to bypass autoclave bottlenecks.
- Acoustic Liners:Perforated composite honeycomb structures manage takeoff and landing noise attenuation for FAA Stage 5 compliance.
- Thermal Shielding:Interlayer panels manage heat flux between engine core and pylon attachment structures.
Exhaust systems command premium pricing. Thrust reverser applications are climbing the fastest as military procurement shifts fabrication methods.
Aircraft Class:
Customer type segmentation aligns production scale with certification pathway complexity and contract structure.
- Commercial Jets:Narrowbody programs at Boeing and Airbus absorb majority panel demand through fixed-price multi-year agreements. EASA CS-25 smoke toxicity amendments are layering additional qualification requirements beyond baseline FAA compliance.
- Military Fighters:Resin transfer molding techniques reduce autoclave dependency and accelerate fabrication cycles for lower-volume, higher-variability procurement.
- Business Jets:Gulfstream and Bombardier programs specify customized panel geometries with shorter qualification timelines.
- Regional Airliners:Embraer and ATR procurement concentrates on cost-optimized autoclave processes for smaller nacelle footprints.
Commercial jets anchor volume. Military fighters are expanding most quickly through process technology substitution.
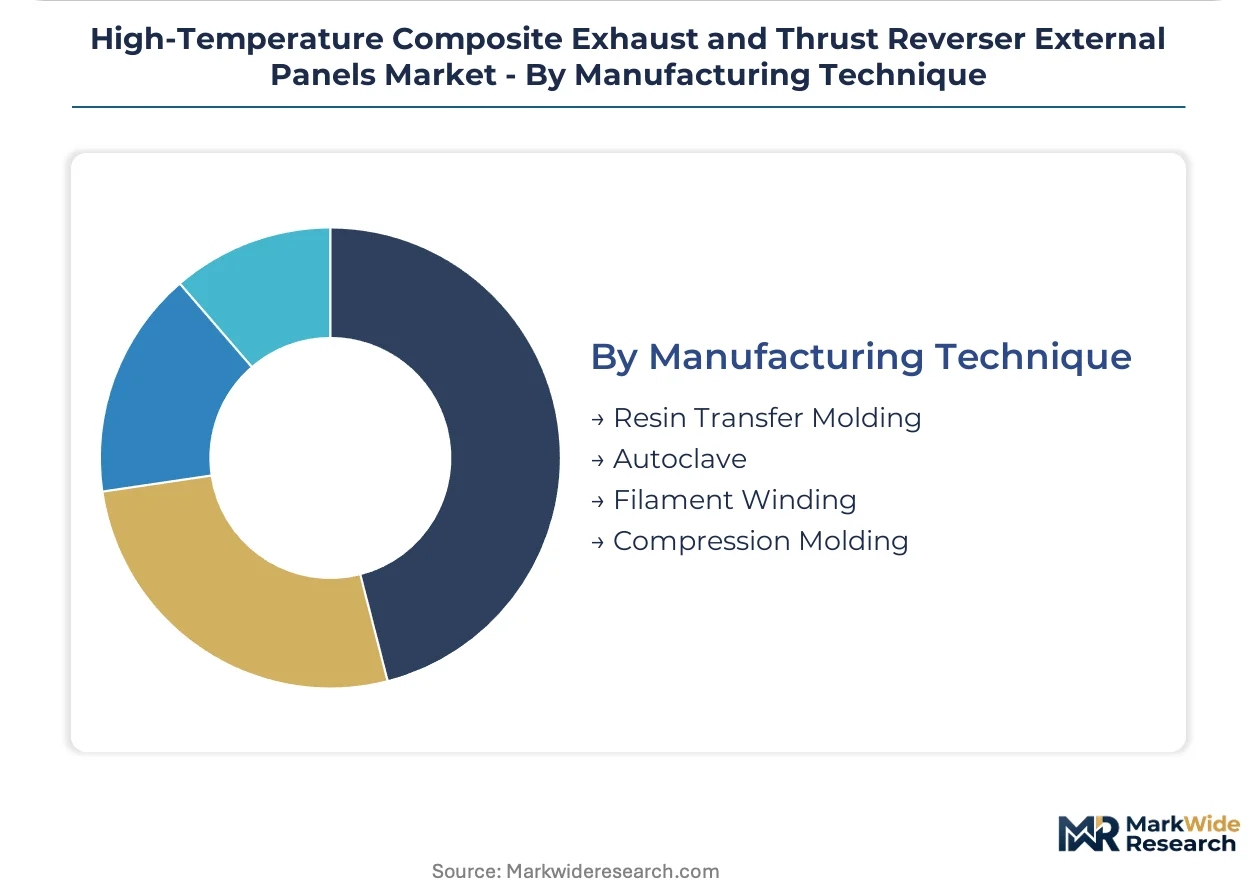
Manufacturing Technique:
Process maturity determines capital intensity, cycle time, and geographic flexibility of supplier footprints.
- Autoclave:Traditional pressure-cured bismaleimide panels retain dominance where complex curvature and porosity control are critical. Capacity constraints at Tier-1 suppliers are forcing OEMs toward captive vertical integration.
- Resin Transfer Molding:Closed-mold injection processes compress cycle times and enable out-of-cluster facility placement. Microwave and electron beam curing validation is expanding addressable supplier pools.
- Filament Winding:Axisymmetric exhaust duct geometries leverage automated fiber placement for cylindrical sections.
- Compression Molding:Thermoplastic matrix systems use heated press forming for high-rate production of standardized panel geometries.
Autoclave maintains qualification heritage. Resin transfer molding is gaining share fastest through capacity relief and sustainability scorecard alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of high-temperature composite exhaust panels track the geographic distribution of final aircraft assembly, with the United States, France, and Germany running structural trade surpluses in qualified aerostructures while Japan and the United Kingdom remain import-dependent for nacelle system integration.
United States
Boeing's single-aisle production ramp at Renton and final assembly expansion in Charleston pull carbon fiber panel demand through multi-year procurement agreements. FAA Part 25 Appendix F fireworthiness standards govern material qualification, tightening smoke density thresholds that favor established bismaleimide suppliers. The Seattle-Wichita corridor concentrates captive autoclave capacity at Tier-1 nacelle integrators, creating geographic chokepoints for qualified fabrication.
France
Airbus final assembly lines at Toulouse and Hamburg-bound component flows sustain European demand for thrust reverser external panels. EASA CS-25 smoke toxicity amendments layer hydrogen cyanide emission limits beyond baseline FAA compliance, requiring dual-certification laboratory partnerships. The Le Havre production complex anchors Safran's vertical integration across nacelle system architectures, concentrating qualified resin transfer molding capacity.
Germany
Premium automotive composite expertise migrates toward aerospace applications as Munich and Hamburg facilities adapt automated fiber placement for complex-curvature exhaust geometries. REACH chemical registration requirements shape resin formulation choices for European market access. The Bavaria-Baden-Württemberg corridor hosts specialized testing laboratories supporting EASA qualification pathways for out-of-autoclave process validation.
Japan
Domestic aerospace procurement concentrates on Mitsubishi Heavy Industries regional jet programs and military fighter sustainment, with limited indigenous nacelle system integration. METI industrial policy supports carbon fiber precursor development through Toray's national champion status, reducing acrylonitrile import dependency. The Nagoya aerospace cluster maintains qualification heritage for ceramic matrix composite thermal protection systems in next-generation turbofan architectures.
United Kingdom
GKN Aerospace's Bristol and Cowes facilities retain design-to-manufacture capabilities for complex exhaust fairings, serving both Airbus and military platforms. The Civil Aviation Authority maintains harmonized certification with EASA post-Brexit, preserving market access for UK-qualified suppliers. The Southwest England composites corridor faces capacity constraints as autoclave throughput limits force process technology pivots toward electron beam curing validation.
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market Competitive Landscape
On the supply side, the industry is consolidating around nacelle system integrators with captive autoclave capacity and sustained airworthiness qualification investment. Three strategic archetypes dominate: vertically integrated OEM-affiliated suppliers controlling design-to-manufacture workflows; independent Tier-1 aerostructures fabricators competing on automated fiber placement scale; and specialized ceramic matrix composite producers serving thermal management extremes. Competitive moves center on backward integration into resin formulation and multi-year throughput agreements that lock in procurement slots at expanding single-aisle production lines.
Among North American and European nacelle integrators, Collins Aerospace exemplifies the vertically integrated archetype through its control across nacelle system architectures, while Safran Nacelles anchors European supply through its Le Havre production complex. GKN Aerospace occupies a position competing on automated fiber placement scale for complex-curvature exhaust components. These three represent the dominant competitive positions shaping procurement leverage and qualification hierarchies in high-temperature composite panel supply.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran Nacelles |
| Spirit AeroSystems |
| FACC AG |
| GKN Aerospace |
| Aernnova Aerospace |
| Magellan Aerospace |
| The NORDAM Group |
| Royal Engineered Composites |
| Others |
Pricing and Supply Chain Analysis
The Seattle-Tacoma freight corridor funnels carbon fiber prepreg shipments from Toray's US operations to Wichita fabrication clusters, concentrating logistics costs that compound with autoclave capacity scarcity to stratify panel pricing across certification tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around multi-year fixed-price agreements that lock in bismaleimide panel supply for single-aisle programs. Pricing stratifies across premium, standard, and economy tiers based on FAA Designated Engineering Representative qualification status and captive autoclave access. Cost compression in standard-grade carbon fiber panels is intensifying as resin transfer molding validates out-of-autoclave alternatives. Military procurement offices exhibit highest price sensitivity due to program budget volatility, while commercial nacelle integrators prioritize qualification heritage over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and Japan on carbon fiber precursor chemicals dominates supply chain risk planning for panel laminators. Manufacturing concentrates in the United States, France, and Germany where qualified autoclave capacity and EASA dual-certification laboratories cluster. Raw material sourcing draws from acrylonitrile feedstock markets, bismaleimide resin formulations, and silicon carbide fiber for ceramic matrix variants. Single-source vulnerability persists around FAA Designated Engineering Representative availability. Distribution runs through nacelle system integrators with backward integration into resin formulation and captive fabrication assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring this market as nacelle system architectures standardize across Boeing and Airbus single-aisle programs, forcing suppliers to interoperate with OEM digital thread requirements or face procurement exclusion.
For Market Incumbents: Harden qualification moats by expanding captive electron beam curing capacity outside Seattle-Wichita chokepoints and deepening FAA Designated Engineering Representative bench strength to extend certification timeline advantages against resin transfer molding entrants. Threat substitution from out-of-autoclave process validation demands preemptive capacity positioning in electron beam infrastructure. For New Entrants and Emerging Players: Pursue military fighter program thrust reverser contracts where resin transfer molding acceptance bypasses commercial autoclave qualification barriers and accelerates revenue cycles. The penetrable segment sits in European acoustic liner applications where EASA CS-25 smoke toxicity amendments have disqualified legacy phenolic suppliers. Go-to-market leverage centers on dual-certification laboratory partnerships in France and Germany. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core nacelle component divisions as OEMs consolidate procurement leverage. Long-term viability hinges on suppliers controlling both resin formulation intellectual property and out-of-autoclave process validation. The signal to watch is electron beam curing equipment orders at fabrication facilities outside legacy clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Process Validation | Electron beam curing compresses cycle times and unlocks facility placement outside Seattle-Wichita corridors. |
| Dual-Certification Laboratory Partnership | EASA CS-25 smoke toxicity amendments require French and German testing capabilities beyond FAA baselines. |
| Recycled Fiber Content Integration | OEM sustainability scorecards are creating contract eligibility thresholds for reclaimed carbon fiber in non-structural fairings. |
| Resin Formulation Backward Integration | In-house bismaleimide production insulates margin pressure from acrylonitrile feedstock volatility. |
| Military Program Resin Transfer Molding Adoption | Closed-mold injection processes accelerate fabrication cycles for fighter thrust reverser procurement. |
Research Methodology
Cross-validation between nacelle system procurement leads and FAA certification database records anchors the qualitative findings in this analysis. Primary interviews with nacelle integrator procurement officers, Tier-1 fabrication plant managers, resin formulation technical directors, and FAA Designated Engineering Representatives combined with secondary validation against EASA certification bulletins, customs trade data for carbon fiber imports, SEC filings from aerostructures suppliers, and OEM multi-year procurement agreement disclosures. Bottom-up panel demand modeling triangulates against top-down single-aisle production rate projections.
Calibration against historical autoclave capacity utilization and resin transfer molding adoption curves informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, panel functional location within propulsion systems, aircraft class procurement structure, and manufacturing technique maturity. CAGRs derive from regression analysis of procurement volume against production rate announcements. Industry-specific forecast inputs incorporate FAA Part 25 Appendix F amendment timelines and EASA CS-25 smoke toxicity regulatory layering.
Sensitivities concentrate around Boeing and Airbus production rate adjustments, acrylonitrile price volatility, and FAA Designated Engineering Representative availability bottlenecks. Forecasts reflect assumptions about resin transfer molding validation timelines and electron beam curing equipment deployment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market