
 Aircraft Insulation Materials Market | 2026-2036
Aircraft Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Insulation Materials Market Analysis
Aerogel composites replacing legacy fiberglass blankets is realigning product economics in thermal barrier systems. DuPont leverages its polymer science heritage to sustain high-performance insulation formulations for next-generation engine nacelles. Evonik Industries anchors European supply through specialized foam chemistry, while Zotefoams competes on closed-cell polymer expertise for acoustic lining applications.
Aircraft insulation materials encompass engineered substrates—fiberglass, foam, mineral wool, and aerogel—manufactured to thermal conductivity thresholds below 0.04 W/m·K and fire-resistance ratings per FAR 25.856, serving to manage heat flux, acoustic transmission, and flame propagation in airframe cavities. Thermal insulation leads material-type revenue due to engine-zone and fuselage requirements, yet aerogel represents the fastest-expanding category as OEMs pursue weight reductions. Acoustic application segments concentrate margin pools around cabin comfort upgrades, while MRO providers drive retrofit volume through aging-fleet overhaul cycles.
FAA Part 25.856 and EASA CS-25 govern flammability and thermal performance standards, compelling manufacturers to certify new materials through costly burn-test protocols that shape R&D allocation and market access timelines. The EU Green Deal's aviation decarbonization framework adds pressure for lighter, recyclable insulation substrates. Stakeholders must monitor regulatory divergence between FAA and EASA certification pathways when scaling production across dual-jurisdiction supply chains.
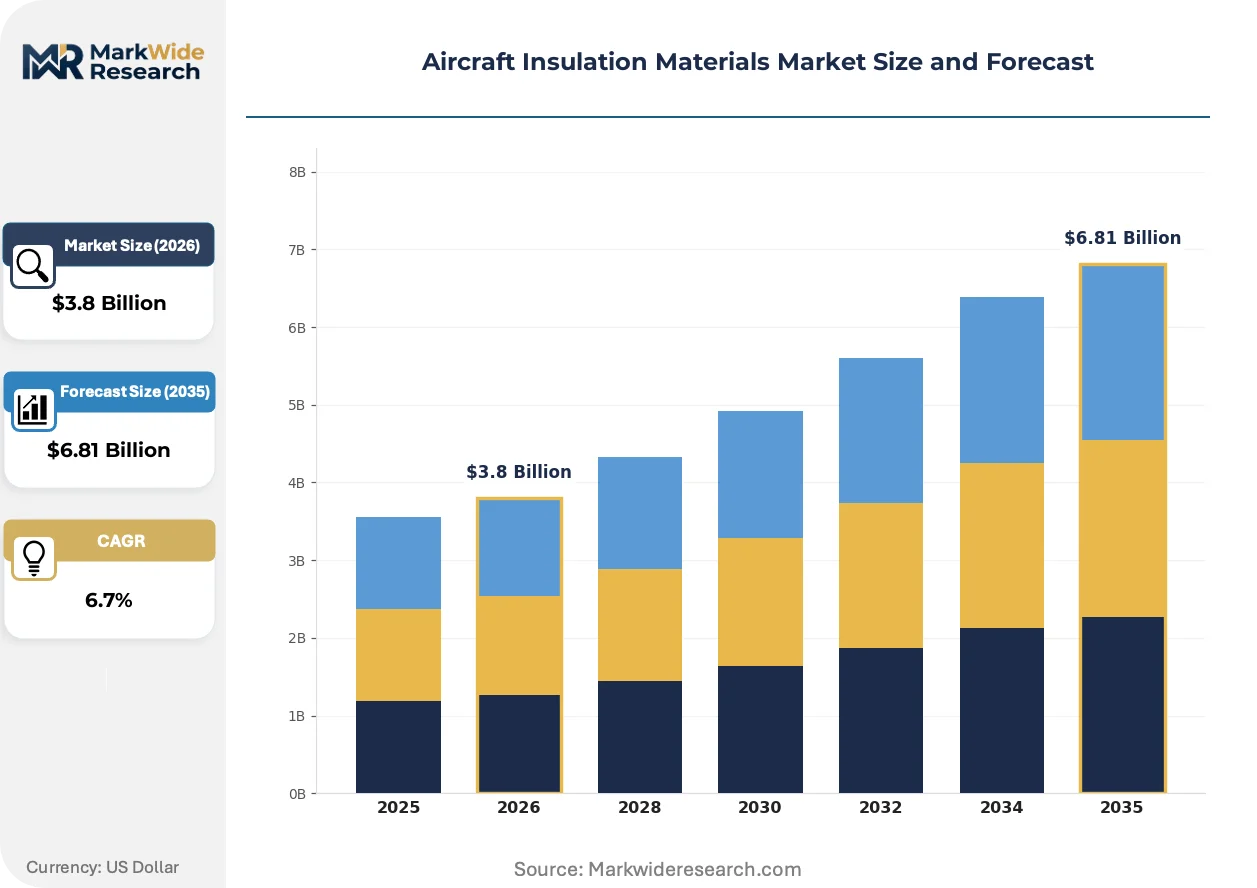
Market Dynamics
Aerogel composites are compressing thermal conductivity thresholds below 0.04 W/m·K while FAA Part 25.856 burn-test protocols extend certification timelines, forcing manufacturers to front-load R&D spending before securing OEM purchase orders.
Growth Catalysts
- Narrow-body fleet retrofits:Airlines retrofit aging A320 and 737 families with lightweight insulation blankets to meet fuel efficiency targets, generating aftermarket volume through MRO channels.
- EU Green Deal aviation framework:Decarbonization mandates pressure OEMs to adopt recyclable, lower-mass substrates in new airframe designs, accelerating material substitution cycles.
- Aerogel manufacturing scale-up:Specialized production lines for silica-based aerogel blankets achieve cost parity with fiberglass at volume, unlocking adoption in engine nacelle applications.
Market Restraints
- Specialized precursor costs:Silica aerogel production requires alkoxide feedstocks subject to chemical supply chain volatility, compressing gross margins for non-integrated manufacturers.
- Dual-jurisdiction certification burden:FAA and EASA maintain divergent burn-test protocols for thermal/acoustic materials, forcing duplicate testing spends for suppliers serving both Boeing and Airbus.
- Legacy fleet replacement inertia:Wide-body operators defer insulation overhaul cycles amid parked-aircraft overcapacity, delaying aftermarket demand recovery for thermal barrier retrofits.
Strategic Opportunities
- Unmanned aerial vehicle thermal management:High-altitude long-endurance drones require extreme-temperature insulation solutions, opening a design-in channel outside traditional commercial aviation procurement.
- Urban air mobility cabin comfort:eVTOL OEMs prioritize acoustic and thermal comfort for passenger acceptance, creating specification pull for advanced foam and aerogel composites.
- REACH-compliant recycling infrastructure:European MRO providers invest in closed-loop recovery systems for mineral wool and fiberglass, capturing value from regulatory-driven waste reduction mandates.
Industry Challenges
- Flammability engineering talent scarcity:Specialized expertise in FAR 25.856 certification testing commands premium compensation, constraining supplier scale-up velocity.
- Legacy airframe integration complexity:New lightweight materials require structural modification to attachment schemes in retrofit applications, extending installation downtime and labor cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Insulation Materials Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Foam, Mineral Wool, Aerogel Application: Thermal, Acoustic, Fire Protection, Vibration Dampening End User: Commercial Aviation, Military Aviation, General Aviation, MRO Providers Installation Mode: OEM, Retrofit, Modular, Custom |
| Companies Covered | Zotefoams, Evonik Industries, DuPont, Duracote Corporation, Polymer Technologies Inc., BASF SE, Rogers Corporation, Safran Group, Triumph Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Insulation Materials Market Emerging Trajectories
Material science breakthroughs are collapsing the weight-performance tradeoff that historically governed insulation specification, while regulatory pressure on fire safety and recyclability forces concurrent innovation across substrate chemistry and manufacturing process.
Aerogel composite technology is expanding into engine nacelle and auxiliary power unit compartments where legacy fiberglass blankets previously dominated thermal protection. OEMs including next-generation narrow-body programs specify aerogel for zones exceeding 200°C operational temperatures, compressing the addressable market for conventional mineral wool solutions. The structural consequence is a bifurcation in supplier capability requirements, with aerogel-specialized firms capturing specification authority in high-temperature zones while fiberglass incumbents defend lower-temperature fuselage applications.
EASA CS-25 amendment proposals tightening smoke and toxicity standards for cabin interior materials are forcing reformulation of acoustic foam substrates across European-registered fleets. Manufacturers serving Airbus supply chains must certify alternative blowing agents and flame retardants ahead of anticipated adoption timelines, compressing product development cycles. Thermal insulation segments in premium cabin configurations face the steepest compliance burden, as these zones combine dense material deployment with stringent passenger exposure limits.
Airline technical procurement teams are consolidating insulation purchasing under airframe overhaul contracts rather than discrete material orders, shifting specification authority from individual MRO shops to OEM-authorized service centers. This concentration favors suppliers with Boeing and Airbus approved vendor status, marginalizing independent MRO material distributors. The United States exhibits the most advanced procurement consolidation, where major carriers route retrofit decisions through centralized engineering departments aligned with manufacturer service programs.
Aircraft Insulation Materials Market Segmentation
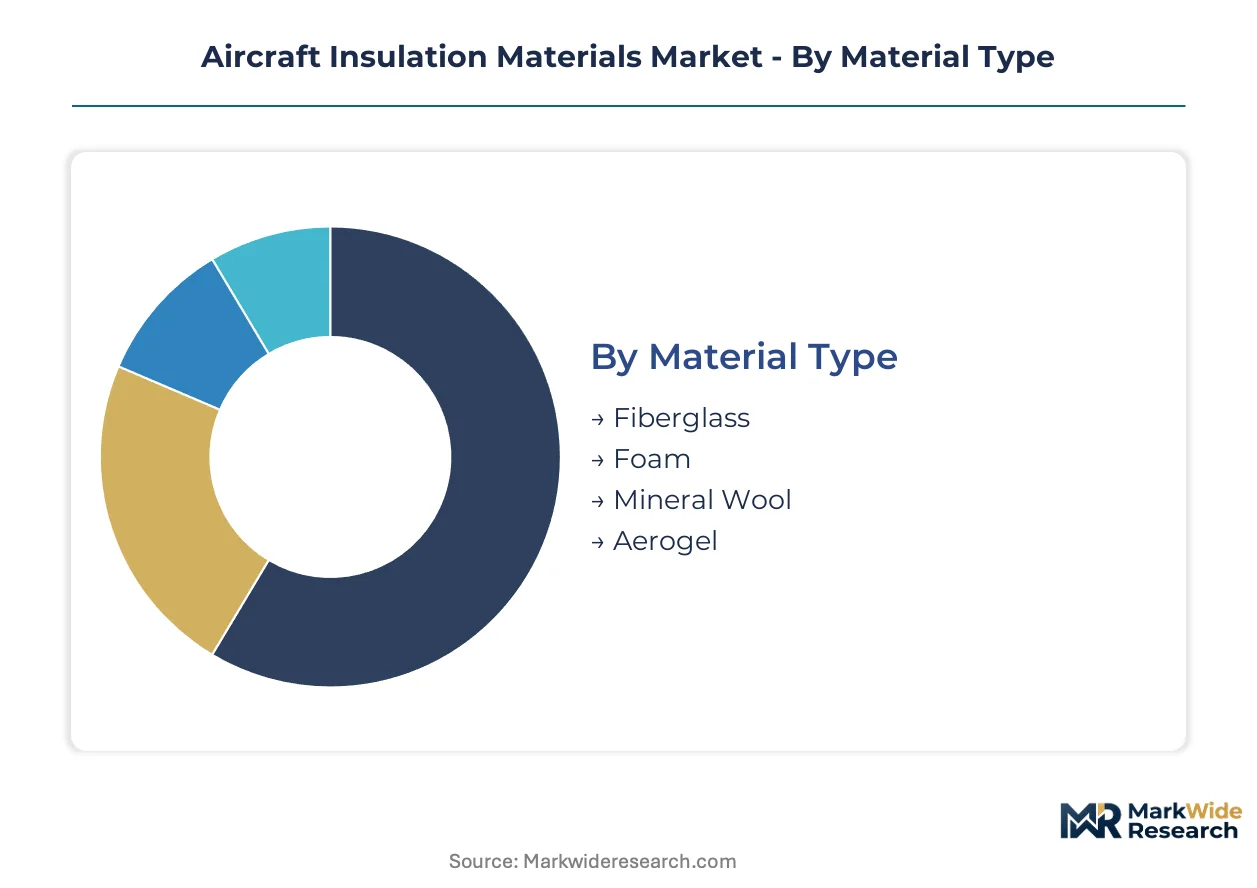
Insulation specification authority fragments across material chemistry, regulatory zone, and procurement channel. Buyers prioritize weight reduction in new airframe programs while MRO channels defend installed-base economics through retrofit compatibility.
Material Type:
Cost tier separates specification authority between legacy substrates and advanced composites.
- Fiberglass:Woven silica-alumina blankets dominate fuselage thermal barriers with established FAR 25.856 certification pathways. Demand concentrates in narrow-body retrofit programs across the United States, where MRO providers prioritize installation familiarity over marginal weight savings.
- Aerogel:Silica-based composites achieve thermal conductivity below 0.04 W/m·K in engine nacelle applications exceeding 200°C operational thresholds. OEM specification pull from next-generation narrow-body programs in the United States is displacing mineral wool in high-temperature zones, though alkoxide feedstock costs compress margins for non-integrated manufacturers.
- Foam:Closed-cell polymer formulations serve acoustic lining applications with tunable density gradients for cabin comfort optimization.
- Mineral Wool:Basalt-based substrates retain specification in auxiliary power unit compartments where cost sensitivity outweighs weight optimization priorities.
Volume sits with fiberglass; growth tilts toward aerogel.
Application:
Margin structure follows the regulatory intensity of each functional zone.
- Thermal:Engine-zone and fuselage cavity requirements anchor material-type revenue through extreme-temperature performance specifications. Demand concentrates in commercial aviation OEM programs, where FAA Part 25.856 burn-test protocols extend certification timelines and front-load R&D spending.
- Acoustic:Cabin comfort upgrades in premium configurations concentrate margin pools around foam and composite substrates with tunable transmission loss coefficients. EASA CS-25 amendment proposals tightening smoke and toxicity standards are forcing reformulation of blowing agents and flame retardants across European-registered fleets.
- Fire Protection:Flame-barrier specifications in fuel tank proximity zones require multi-layer composite architectures with char-resistant surface chemistries.
- Vibration Dampening:Isolation of auxiliary equipment from airframe resonance demands viscoelastic interlayers with frequency-matched damping coefficients.
Revenue concentrates in thermal; specification velocity peaks in acoustic.
End User:
Procurement consolidation patterns diverge between fleet operators and service providers.
- Commercial Aviation:Airlines retrofit aging A320 and 737 families with lightweight insulation blankets to meet fuel efficiency targets, generating aftermarket volume through centralized engineering departments aligned with manufacturer service programs.
- MRO Providers:Independent maintenance shops drive retrofit volume through aging-fleet overhaul cycles, though specification authority is shifting toward OEM-authorized service centers under consolidated airframe overhaul contracts.
- Military Aviation:Defense procurement prioritizes multi-threat survivability specifications with integrated thermal-acoustic-fire barrier systems.
- General Aviation:Smaller fleet operators defer insulation overhaul cycles amid utilization volatility, delaying aftermarket demand recovery.
Volume sits with commercial aviation; margin expansion favors MRO consolidation.
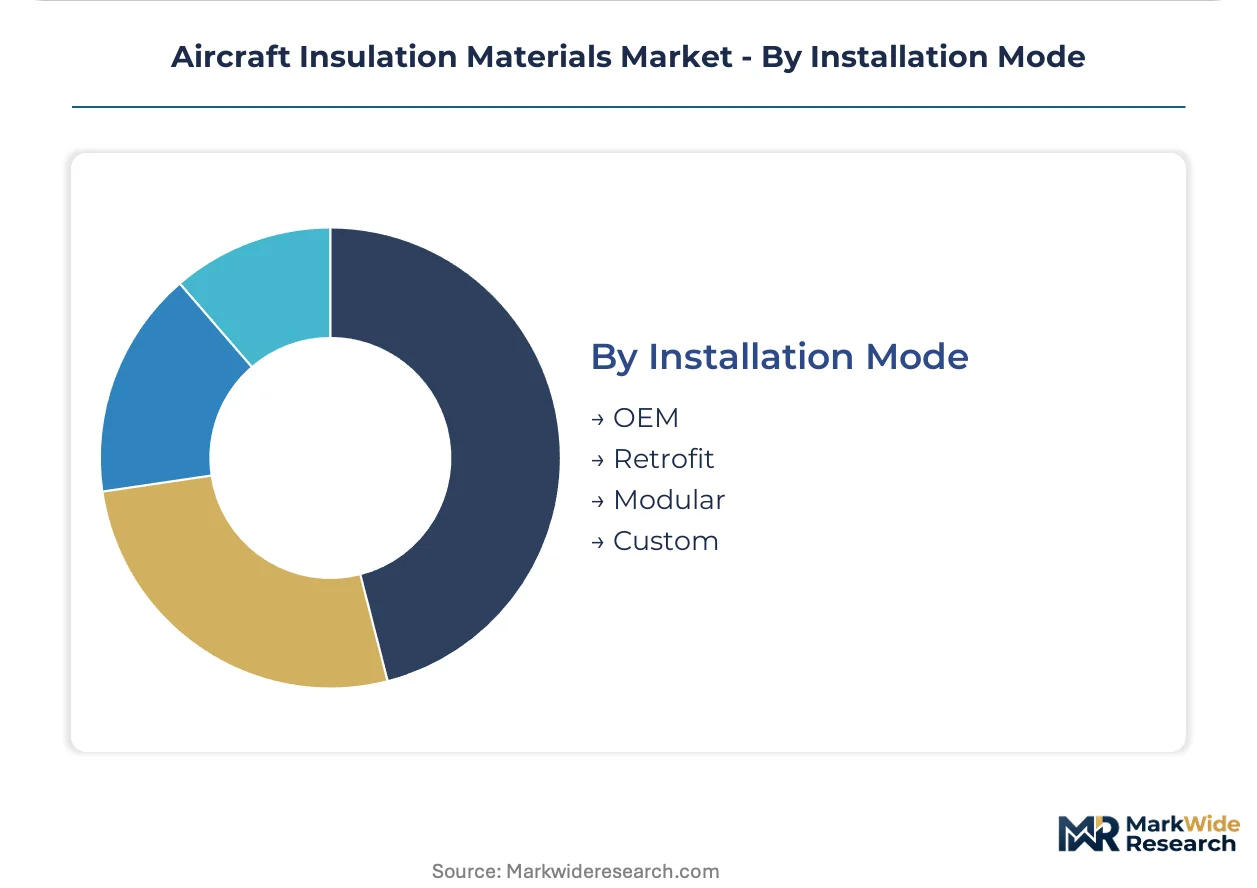
Installation Mode:
Supply chain configuration separates captive OEM flows from aftermarket flexibility.
- OEM:Airframe manufacturers specify insulation architectures during design phase, locking material suppliers into long-term purchase agreements with Boeing and Airbus approved vendor status requirements.
- Retrofit:Legacy airframe integration complexity extends installation downtime and labor cost, as new lightweight materials require structural modification to attachment schemes.
- Modular:Pre-fabricated blanket assemblies reduce installation labor for high-volume narrow-body programs with standardized cavity geometries.
- Custom:Specialized configurations serve wide-body VIP completions and military platforms with non-standard compartment layouts.
Volume sits with OEM; retrofit channels face consolidation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline fleet renewal programs and OEM production footprints concentrate demand in the United States, Germany, China, France, and Japan. Regulatory divergence between FAA and EASA certification pathways shapes procurement patterns across jurisdictions.
United States
Boeing's production footprint in Washington and South Carolina anchors thermal insulation demand for narrow-body and wide-body programs. FAA Part 25.856 burn-test protocols govern material certification timelines, extending R&D cycles before OEM purchase orders materialize. The Dallas-Fort Worth metroplex hosts dense MRO provider networks driving retrofit volume through aging-fleet overhaul cycles.
Germany
Airbus Hamburg final assembly lines generate specification pull for acoustic and thermal barrier systems across A320 and A350 families. EASA CS-25 amendments tightening smoke and toxicity standards force reformulation of foam substrates ahead of anticipated adoption timelines. The Bavarian industrial corridor around Munich concentrates specialized chemical suppliers serving aerogel precursor requirements.
China
COMAC C919 production ramp-up at Shanghai Pudong creates indigenous demand for fire-resistant insulation architectures meeting CAAC certification. MIIT industrial policy prioritizes domestic material substitution in aerospace supply chains, pressuring foreign supplier market access. The Yangtze River Delta manufacturing cluster integrates composite insulation fabrication with broader aviation component ecosystems.
France
Safran and Airbus operations in Toulouse anchor thermal management specification authority for engine nacelle and APU compartment applications. REACH compliance requirements drive investment in closed-loop recycling infrastructure for mineral wool and fiberglass recovery. The Occitanie aerospace cluster coordinates between OEM engineering centers and specialized insulation subcontractors.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries sustain demand for vibration-dampening and thermal barrier systems in regional jet and defense programs. METI technology roadmaps prioritize lightweight material development aligning with next-generation aircraft weight reduction targets. The Nagoya aerospace manufacturing hub integrates insulation procurement with broader tier-1 supplier networks.
Aircraft Insulation Materials Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with material science heritage firms capturing specification authority in high-temperature zones while volume producers defend fuselage applications. The vendor base concentrates around three strategic archetypes: integrated chemical conglomerates with polymer science depth, specialized foam and composite fabricators, and aerospace-tier suppliers with OEM-approved vendor status. Competitive positioning hardens through dual-jurisdiction certification capabilities and long-term purchase agreements with Boeing and Airbus. M&A activity targets aerogel manufacturing scale-up, while strategic partnerships lock in alkoxide feedstock supply security.
Within the integrated chemical tier, BASF SE and Evonik Industries exemplify European suppliers leveraging specialized foam chemistry and polymer science heritage to sustain high-performance formulations. DuPont occupies a position among North American material science conglomerates with legacy certification pathways in engine nacelle applications. Zotefoams represents the specialized fabricator archetype, with closed-cell polymer expertise anchoring acoustic lining specification in cabin comfort upgrades. These three entities collectively illustrate how competitive positioning fragments across material chemistry, thermal performance tier, and geographic regulatory alignment.
| Leading Market Players |
|---|
| Zotefoams |
| Evonik Industries |
| DuPont |
| Duracote Corporation |
| Polymer Technologies Inc. |
| BASF SE |
| Rogers Corporation |
| Safran Group |
| Triumph Group Inc. |
| Others |
Supply Flow & Price Mechanics
Aerogel manufacturing scale-up in the United States and Germany is collapsing legacy cost structures while concentrating supply authority among alkoxide-integrated chemical conglomerates, simultaneously compressing unit economics for fiberglass incumbents and elevating pricing power for high-temperature specification holders.
Pricing Analysis
Volume concentrates in fiberglass fuselage blankets where MRO procurement teams prioritize installation familiarity over marginal performance gains, while margins pool in aerogel engine nacelle specifications where thermal conductivity below 0.04 W/m·K commands certification-linked premiums. Price differentiation rests on FAR 25.856 burn-test tier and OEM-approved vendor status, with dual-jurisdiction certification holders capturing standard-tier premiums. Cost compression in fiberglass runs through alkoxide feedstock volatility and Chinese mineral wool import competition. Narrow-body retrofit channels exhibit highest price sensitivity as airlines consolidate purchasing under airframe overhaul contracts.
Supply Chain Analysis
Domestic-content mandates under China's MIIT industrial policy and the EU Green Deal's aviation decarbonization framework are reshaping sourcing patterns, pressuring foreign supplier market access in Shanghai Pudong and Hamburg final assembly corridors. Supply concentrates in the United States, Germany, and China, with specialized aerogel precursor production anchored in the Bavarian industrial corridor around Munich. Raw material dependencies center on silica alkoxides, basalt fiber feedstocks, and closed-cell polymer resins. Single-source vulnerability concentrates in alkoxide supply chains tethered to chemical conglomerate integration. Distribution runs through OEM-authorized service centers consolidating retrofit procurement authority away from independent MRO shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with aerogel manufacturing capacity bottlenecks propping pricing power for integrated chemical conglomerates while non-integrated fabricators face margin compression from feedstock volatility.
For Market Incumbents: Hedge against fiberglass displacement by securing alkoxide supply agreements or captive production in the Bavarian corridor, while front-loading R&D spending to capture next-generation narrow-body aerogel specifications before certification timelines extend. Defend MRO channel position through OEM-approved vendor status maintenance as procurement consolidation accelerates. For New Entrants and Emerging Players: EASA CS-25 amendment proposals in Europe open a window for REACH-compliant foam substrate specialists to capture acoustic lining reformulation cycles ahead of anticipated adoption timelines. Target unmanned aerial vehicle thermal management segments outside traditional commercial aviation procurement, leveraging design-in relationships with high-altitude drone OEMs as a beachhead for specification authority. For Investors and Strategic Acquirers: Exit pathways concentrate in aerogel manufacturing scale-up acquisitions by integrated chemical conglomerates seeking feedstock security. Long-term viability favors vertically positioned specialists with dual-jurisdiction certification capabilities and Boeing or Airbus approved vendor status. Watch for inflection in COMAC C919 production ramp-up as signal for Chinese domestic substitution pressure on foreign supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Aerogel Manufacturing Scale-Up | Captures engine nacelle specifications from next-generation narrow-body programs at Boeing and Airbus. |
| Dual-Jurisdiction Certification Investment | Unlocks simultaneous FAA Part 25.856 and EASA CS-25 access without duplicate burn-test spending. |
| Alkoxide Feedstock Integration | Secures margin protection against chemical supply chain volatility in silica aerogel production. |
| OEM-Authorized Service Center Partnership | Aligns with procurement consolidation routing retrofit decisions through centralized engineering departments. |
| REACH-Compliant Recycling Infrastructure | Captures value from EU Green Deal waste reduction mandates in European MRO networks. |
Methodological Framework
Multi-period observation of aerogel manufacturing capacity additions, FAA and EASA certification timelines, and narrow-body fleet retrofit cycles anchored the trend analysis, supplemented by interviews with thermal insulation procurement directors at major carriers, MRO engineering managers, aerogel R&D leads at chemical conglomerates, and regulatory compliance officers. Secondary validation drew from FAA Part 25.856 amendment dockets, EASA CS-25 proposal documentation, OEM supplier qualification records, and customs trade data for silica alkoxide feedstocks. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Segment-weighting across material type, application zone, and procurement channel dimensions shaped the analytical framework across the analysis window. Thermal conductivity thresholds, burn-test certification status, and OEM-approved vendor penetration rates served as industry-specific forecast inputs. CAGRs derived from installed-base retrofit cycle modeling and new airframe program ramp schedules.
The model assumes a particular technology adoption path; alternative pathways for aerogel composite manufacturing cost parity would alter the outlook for fiberglass displacement timelines. Forecasts reflect assumptions around fleet renewal rates, regulatory amendment adoption schedules, and feedstock supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market