
 Business Jet Mro Market | 2026-2036
Business Jet Mro Market Size, Share, and Industry Trends Forecast 2026-2036
Business Jet Mro Market Analysis
Airframe heavy-check certification standards are bifurcating the competitive landscape into OEM-authorized networks and independent Part 145 repair stations. Lufthansa Technik AG leverages its Hamburg-based MRO campus to dominate wide-cabin airframe overhauls for Bombardier Global and Dassault Falcon platforms. StandardAero specializes in engine MRO for Rolls-Royce and Honeywell powerplants, sustaining deep teardown capabilities across North American and European facilities. Gulfstream Aerospace Corporation controls aftermarket access through proprietary technical publications and exclusive tooling licenses for its G650 and G700 programs.
Business Jet MRO encompasses the inspection, repair, overhaul, and modification of corporate aircraft airframes, engines, avionics, and interior components to maintain airworthiness and operational reliability, with heavy maintenance events typically triggered by flight-hour or calendar-interval thresholds specified in manufacturer maintenance planning documents. The primary purpose is to ensure continuous operational availability while extending economic service life beyond original design expectations. Engine Maintenance commands the largest value pool within Service Type segmentation due to powerplant life-limited part replacement cycles and turbine blade restoration economics. Corporate Fleets within End User segmentation represent the fastest-growing demand channel as fractional ownership programs and flight departments expand managed maintenance agreements. Avionics Upgrades within Technology segmentation is displacing traditional analog retrofit activity as NextGen mandates and synthetic vision requirements drive panel modernization.
FAA airworthiness directives and EASA Part-M regulations shape inspection intervals and documentation standards, with both agencies intensifying focus on aging aircraft structural integrity programs and corrosion prevention. EPA oversight of hazardous material handling in paint stripping and plating operations influences shop-floor process economics and facility certification requirements. Stakeholders must monitor evolving OEM data-rights litigation and its impact on independent repair station access to proprietary maintenance manuals and diagnostic software.
Market Dynamics
FAA airworthiness directives are compressing inspection intervals for aging airframes, forcing fleet operators to accelerate heavy maintenance cycles while OEMs tighten proprietary data access. This regulatory pressure is concentrating demand toward authorized service networks capable of meeting compressed turnaround requirements.
Growth Catalysts
- NextGen Avionics Mandates:FAA ADS-B Out and synthetic vision requirements are triggering panel modernization across legacy business jet fleets, creating sustained retrofit demand for integrated flight deck systems.
- Corporate Fleet Expansion:Fractional ownership programs in the United States are extending managed maintenance agreements to cover predictive engine monitoring and scheduled airframe events.
- Engine Life-Limited Part Cycles:Rolls-Royce and Honeywell powerplants require turbine blade restoration and hot-section replacement at defined intervals, generating recurring overhaul revenue.
Market Restraints
- OEM Data Rights Concentration:Gulfstream and Bombardier restrict access to proprietary maintenance manuals and diagnostic software, limiting independent Part 145 repair station capabilities.
- Specialized Technician Scarcity:Airframe heavy-check certification requires FAA-qualified inspectors with composite repair and corrosion control expertise, constraining shop-floor throughput.
- EPA Hazardous Material Compliance:Paint stripping and plating operations face escalating environmental compliance costs for chromium and solvent handling, compressing facility margins.
Strategic Opportunities
- Avionics Upgrade White Space:Analog-to-digital cockpit conversions for pre-2000 airframes represent underpenetrated demand as EASA Part-M documentation standards intensify.
- Predictive Maintenance Platforms:Engine health monitoring systems converging with satellite connectivity enable condition-based overhaul scheduling, reducing unscheduled downtime.
- Interior Refurbishment Cycles:Cabin management system modernization and connectivity upgrades are creating aftermarket revenue independent of airworthiness mandates.
Industry Challenges
- Certification Timeline Compression:FAA field approval processes for major alterations stretch 90-180 days, delaying revenue recognition for modification centers.
- Legacy System Integration:New avionics architectures must interface with analog flight control systems, requiring custom engineering and extended ground testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Jet Mro Market |
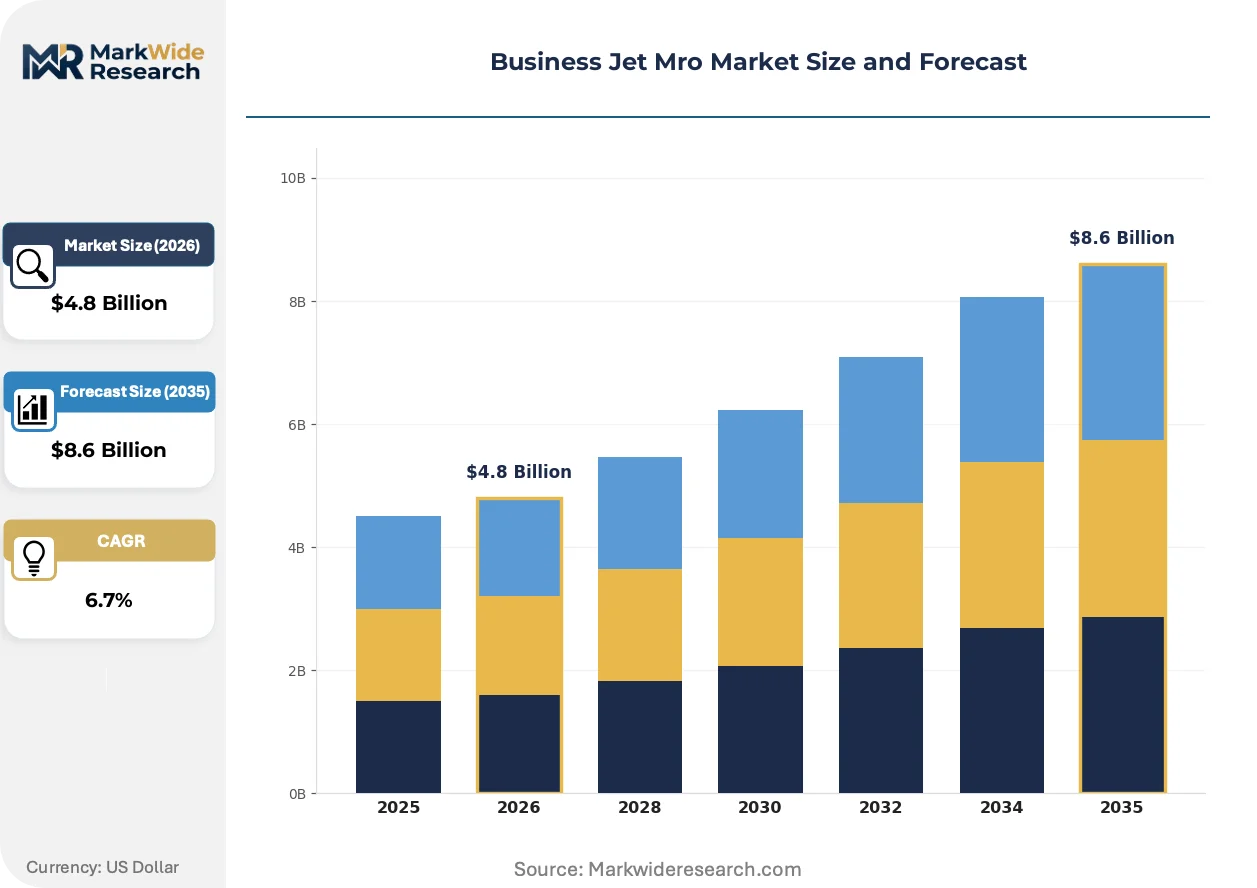
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Maintenance, Component Maintenance, Line Maintenance End User: Private Owners, Charter Operators, Corporate Fleets, Government Agencies Maintenance Type: Scheduled Maintenance, Unscheduled Maintenance, Modification, Refurbishment Technology: Traditional, Advanced Materials, Avionics Upgrades, Eco-Friendly Solutions |
| Companies Covered | Bombardier Inc., Lufthansa Technik AG, General Dynamics Corporation, RTX Corporation, Rolls-Royce Holdings plc, Gulfstream Aerospace Corporation, Dassault Aviation, Textron Aviation Inc., StandardAero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Jet Mro Market Emerging Trajectories
Digital thread technologies are penetrating maintenance documentation, enabling real-time airworthiness tracking while regulatory agencies intensify data integrity requirements for aging aircraft programs.
Additive manufacturing is bifurcating the aftermarket parts supply chain. OEMs like GE Aviation certify 3D-printed turbine components for engine MRO, reducing lead times for obsolete castings. Independent repair stations adopt polymer and metal deposition for non-structural cabin components. This capability is bifurcating competitive positioning between authorized networks with design authority and independent shops limited to cosmetic applications.
EASA Part-M regulations now mandate electronic continuing airworthiness records, replacing paper logbooks. This policy shift forces maintenance providers to invest in blockchain-verified documentation systems. European-registered business jets face the most aggressive compliance timelines, with operators selecting MRO partners based on digital audit trail capabilities.
Corporate flight departments are consolidating maintenance spend under single-source agreements with OEM-authorized networks, displacing the fragmented spot-repair model. This behavioral shift concentrates purchasing power with fleet management companies and fractional providers. The United States exhibits the most pronounced consolidation, as flight departments prioritize downtime guarantees over unit cost minimization.
Business Jet Mro Market Segmentation
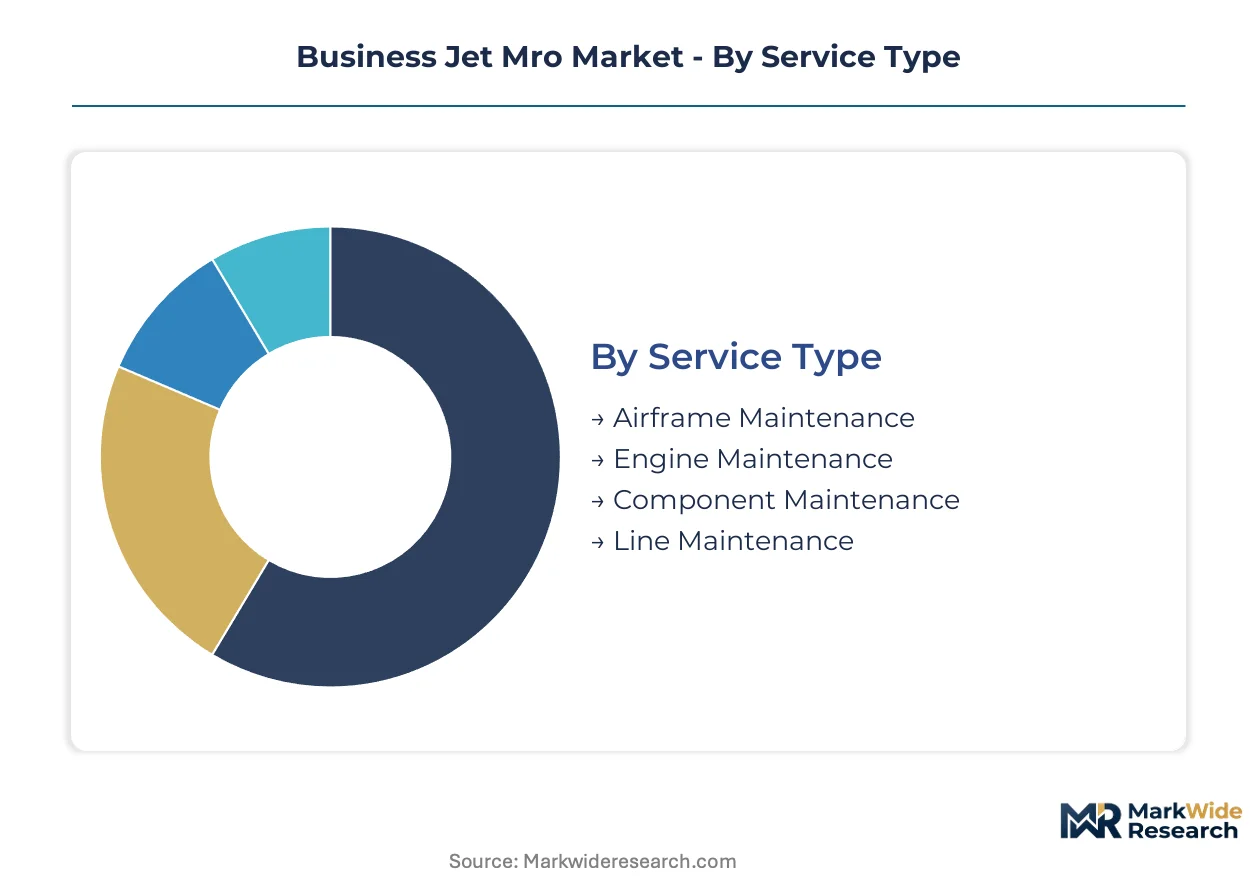
Business jet MRO segmentation reveals how regulatory pressure, fleet composition, and operational models concentrate value across distinct service categories. Understanding these divisions exposes where FAA and EASA mandates create premium pricing power versus commoditized competition.
Service Type:
FAA airworthiness directives differentiate mandatory inspection cycles across service categories, with life-limited components triggering the most stringent documentation requirements.
- Engine Maintenance:Hot-section overhauls and turbine blade restoration for Rolls-Royce and Honeywell powerplants demand specialized teardown facilities. Corporate fleets in the United States concentrate demand here as flight-hour agreements shift overhaul risk to MRO providers.
- Airframe Maintenance:Heavy-check events involving corrosion prevention and structural integrity programs require FAA-certified inspectors with composite repair qualifications. Aging Gulfstream and Bombardier airframes in North American corporate fleets drive volume as calendar-interval mandates compress turnaround windows.
- Component Maintenance:Landing gear, hydraulics, and auxiliary power unit servicing follows condition-based triggers rather than fixed schedules.
- Line Maintenance:Pre-flight and transit checks occur at fixed-base operators with minimal regulatory differentiation.
Established volume favors Engine Maintenance; emerging adoption favors Airframe Maintenance as aging fleet mandates intensify.
End User:
Customer procurement patterns split between cost-sensitive spot purchases and premium guaranteed-availability contracts.
- Corporate Fleets:Fractional ownership programs and flight departments negotiate comprehensive managed maintenance agreements covering predictive monitoring and scheduled events. These operators in the United States prioritize downtime guarantees over unit cost, consolidating spend with OEM-authorized networks capable of meeting compressed turnaround requirements.
- Charter Operators:High-utilization fleets require rapid component exchange programs and overnight engine changes to maintain aircraft availability. Their demand concentrates at independent Part 145 stations with inventory pooling arrangements.
- Private Owners:Individual aircraft operators typically pursue discrete heavy-check events with extended scheduling flexibility.
- Government Agencies:Military and executive transport fleets follow separate procurement protocols with security-cleared facility requirements.
Procurement consolidation is accelerating most quickly among Corporate Fleets; Charter Operators retain the most fragmented sourcing patterns.
Maintenance Type:
Margin structures diverge sharply between regulatory-mandated work and discretionary upgrades.
- Scheduled Maintenance:Calendar-interval and flight-hour-triggered inspections specified in manufacturer maintenance planning documents generate predictable revenue streams. FAA field approval processes for major alterations extend 90-180 days, delaying revenue recognition for modification centers performing this work.
- Refurbishment:Cabin management system modernization and connectivity upgrades create aftermarket revenue independent of airworthiness mandates. Corporate flight departments in the United States increasingly bundle these discretionary spends with mandatory maintenance under single-source agreements.
- Unscheduled Maintenance:AOG events command premium pricing but unpredictable volume.
- Modification:STC-based alterations require extensive engineering documentation and extended ground testing.
Revenue stability concentrates in Scheduled Maintenance; margin expansion favors Refurbishment as cabin technology cycles accelerate.
Technology:
Certification requirements and parts availability create tiered competitive access across technology categories.
- Avionics Upgrades:Analog-to-digital cockpit conversions for pre-2000 airframes address NextGen mandates including FAA ADS-B Out and synthetic vision requirements. EASA Part-M documentation standards intensify compliance complexity for European-registered aircraft undergoing panel modernization.
- Advanced Materials:Composite repair and carbon fiber restoration capabilities require specialized tooling and technician certification that OEM-authorized networks control through proprietary licenses.
- Traditional:Conventional aluminum airframe repair and mechanical system overhaul faces commoditization as technician supply expands.
- Eco-Friendly Solutions:Water-based paint systems and chromium-free plating operations respond to EPA hazardous material compliance pressures.
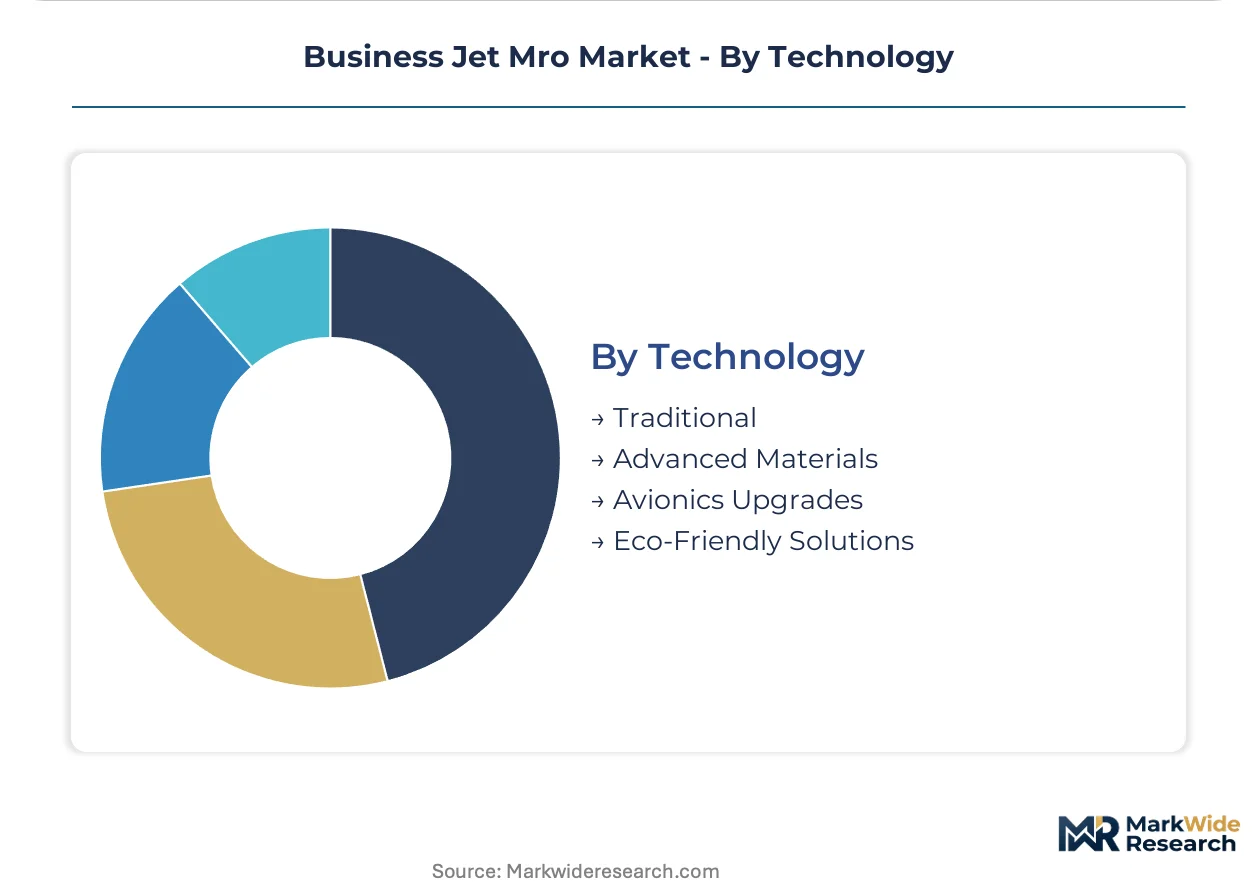
Technical differentiation persists in Avionics Upgrades; cost pressure dominates Traditional service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based MRO providers export heavy maintenance services to European and Middle Eastern corporate fleets, establishing transatlantic trade corridors for Gulfstream and Bombardier platform overhauls.
United States
Corporate flight departments in Florida, Georgia, and Texas drive demand for scheduled airframe events and engine overhauls. FAA airworthiness directives on aging Gulfstream airframes compress inspection intervals, forcing operators toward authorized service networks. Savannah, Georgia anchors Gulfstream's integrated MRO campus, while Dallas and West Palm Beach host independent Part 145 stations specializing in Rolls-Royce powerplant teardowns.
Germany
European-registered business jets concentrate heavy maintenance demand at Lufthansa Technik's Hamburg facility for Bombardier Global and Dassault Falcon platforms. EASA Part-M electronic continuing airworthiness record mandates accelerate digital documentation investments. Hamburg's MRO cluster dominates wide-cabin airframe overhauls, with Munich and Frankfurt serving as secondary hubs for line maintenance and avionics upgrades.
United Kingdom
London-based fractional ownership programs and charter operators source predictive engine monitoring and rapid component exchange services. CAA alignment with EASA documentation standards drives blockchain-verified maintenance record adoption. Cranfield and London Biggin Hill host specialized facilities for legacy airframe heavy-checks and NextGen avionics retrofitting.
United Arab Emirates
Dubai and Abu Dhabi flight departments demand guaranteed-availability contracts covering hot-section overhauls and cabin refurbishment cycles. GCAA regulations mirror EASA Part-M standards for electronic airworthiness records, selecting MRO partners based on digital audit capabilities. Dubai South's aviation district attracts OEM-authorized networks seeking Middle Eastern corporate fleet contracts.
Switzerland
Geneva and Zurich corporate flight operations prioritize discretion and compressed turnaround windows for heavy maintenance events. FOCA maintenance documentation requirements align with EASA standards, favoring providers with integrated digital record systems. Geneva's MRO cluster specializes in Dassault Falcon and Bombardier Challenger platform overhauls for private banking and luxury sector clients.
Business Jet Mro Market Vendor Landscape
Listed aerospace conglomerates compete with private MRO specialists across service network authorization tiers, creating a bifurcated structure between OEM-captive facilities and independent repair stations. Three archetypes dominate: integrated OEM networks controlling proprietary technical data, engine-focused teardown specialists with deep component capabilities, and independent Part 145 stations competing on turnaround speed. Consolidation concentrates through exclusive tooling licenses and strategic partnerships for satellite facility expansion.
Within the OEM-authorized tier, Gulfstream Aerospace Corporation and Bombardier Inc. exemplify vertical control over aftermarket access through proprietary maintenance manuals and exclusive diagnostic software licensing. Lufthansa Technik AG anchors the European heavy-maintenance segment, representing the integrated aviation group model with captive airline heritage. StandardAero occupies a position among independent specialists, exemplifying the engine-focused archetype with distributed North American and European teardown capabilities.
| Leading Market Players |
|---|
| Bombardier Inc. |
| Lufthansa Technik AG |
| General Dynamics Corporation |
| RTX Corporation |
| Rolls-Royce Holdings plc |
| Gulfstream Aerospace Corporation |
| Dassault Aviation |
| Textron Aviation Inc. |
| StandardAero |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Gulfstream's Savannah campus and Lufthansa Technik's Hamburg facility shapes both supply concentration and price floors across heavy maintenance categories. OEM-authorized networks command premium pricing through exclusive tooling licenses while independent Part 145 stations compete on turnaround speed at compressed margins.
Pricing Analysis
Next-generation avionics upgrades command substantial premiums over legacy analog retrofits and emerging synthetic vision installations. Three-tier pricing structure across OEM-authorized, independent certified, and non-certified service levels reflects certification grade and proprietary data access. Cost compression in independent airframe heavy-checks is intensifying because EPA hazardous material compliance escalates facility overhead. Charter operators exhibit highest price sensitivity due to high-utilization cost absorption, while corporate flight departments prioritize downtime guarantees over unit cost minimization.
Supply Chain Analysis
The United States and Germany anchor specialized teardown capabilities for Rolls-Royce and Honeywell powerplants, with Switzerland and the United Arab Emirates serving as secondary hubs for cabin refurbishment and line maintenance. The aftermarket parts ecosystem draws from titanium forgings, composite prepregs, and avionics semiconductor components. Single-source vulnerability concentrates in proprietary diagnostic software licenses controlled by Gulfstream and Bombardier. Distribution runs through OEM-captive networks, independent Part 145 stations, and fractional ownership program procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery as corporate flight departments rebuild maintenance backlogs deferred during fleet utilization contractions. FAA airworthiness directive compression on aging airframes provides the cyclical impetus.
For Market Incumbents: Shield proprietary technical data access through exclusive licensing arrangements and accelerated certification investments at satellite facilities. Gulfstream and Bombardier OEM networks should deepen backward integration into predictive maintenance software to counter independent repair station encroachment. Consolidate purchasing power with fractional ownership programs through guaranteed-availability contracting.
For New Entrants and Emerging Players: Differentiate on avionics upgrade velocity for pre-2000 airframes facing NextGen mandate deadlines. The most penetrable white space sits in analog-to-digital cockpit conversions for European-registered aircraft under EASA Part-M electronic documentation requirements. Pursue strategic partnerships with blockchain-verified maintenance record platforms to bypass OEM data gatekeeping.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among engine-focused teardown specialists with flight-hour agreement portfolios. Long-term viability centers on facilities with composite repair certifications and EPA hazardous material handling permits. Monitor FAA field approval timeline compression as the inflection signal for modification center revenue recognition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Data Rights Expansion | Exclusive technical manual licensing fortifies Gulfstream's aftermarket control against independent Part 145 competition. |
| Predictive Maintenance Platform Launch | Engine health monitoring convergence with satellite connectivity enables condition-based overhaul scheduling for corporate fleets. |
| Blockchain Documentation Investment | EASA Part-M electronic airworthiness mandates force MRO providers toward verified audit trail capabilities. |
| Composite Repair Certification | FAA-qualified inspector scarcity for carbon fiber restoration creates bottlenecked capacity at authorized networks. |
| Interior Refurbishment Capability Buildout | Cabin management modernization cycles generate aftermarket revenue independent of airworthiness mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directive filings, EASA Part-M regulatory updates, and OEM maintenance planning documents. Primary interviews engaged MRO operations directors, corporate flight department maintenance managers, fractional ownership program procurement leads, and Part 145 repair station certification officers. Secondary validation drew from SEC 10-K aerospace disclosures, FAA field approval databases, and industry maintenance cost benchmarking studies. Bottom-up triangulation across service type demand curves and top-down reconciliation against fleet installed base projections ensured analytical consistency.
Segmentation dimensions modeled span service type, end user procurement pattern, maintenance event category, and technology generation across the projection horizon. CAGRs derive from regression analysis of historical maintenance event frequency against flight-hour accumulation patterns and calendar-interval regulatory compression. Forecast inputs incorporate aging fleet structural integrity program mandates, NextGen avionics retrofit penetration curves, and EPA hazardous material compliance cost escalations.
Decision-makers should treat outputs as directional under base assumptions of sustained corporate fleet utilization recovery and stable regulatory inspection interval compression; material deviation in fractional ownership growth or OEM data rights litigation outcomes would warrant model refresh. Recalibration cycles align with material shifts in FAA airworthiness directive issuance patterns and EASA documentation standard amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market