
 Aerospace Plastics Market | 2026-2036
Aerospace Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Plastics Market Analytics
The EU Green Deal is broadening the addressable market for sustainable aerospace polymers as European carriers face binding emissions reduction mandates. SABIC leverages its Ultem and Lexan portfolios to dominate high-heat thermoplastic solutions for cabin interiors. Solvay sustains leadership in specialty polyamides and fluoropolymers through captive resin synthesis and qualification depth with tier-one aerostructures suppliers.
Aerospace plastics encompass high-performance polymers engineered to withstand extreme temperatures, UV radiation, and mechanical stress while delivering weight reductions of 30-50% versus aluminum alloys in non-structural applications. These materials primarily serve to reduce aircraft operating costs through fuel savings and extend component service life in corrosive atmospheric conditions. Thermoplastics command the largest volume share due to their reprocessability and shorter cycle times in injection molding operations, while reinforced plastics capture premium margin pools in primary structural applications where carbon-fiber loading exceeds 60% by volume. Composites represent the fastest-expanding category as automated fiber placement and out-of-autoclave curing reduce labor content in wing and fuselage segments.
FAA certification standards under 14 CFR Part 25 govern flammability and smoke toxicity requirements that shape material selection across all US-registered aircraft programs. EASA's CS-25 framework and REACH chemical restrictions in Europe jointly determine polymer formulation choices and supplier qualification pathways for OEMs serving dual-jurisdiction operators. Stakeholders must monitor evolving MEE and SAMR standards in China as COMAC expands its C919 production footprint and develops indigenous supply chain alternatives to incumbent Western compounders.
Market Dynamics
Commercial aviation's metal-to-polymer substitution drive is restructuring aerospace plastics demand, as OEMs pursue 30-50% weight reductions in non-structural components to meet fuel efficiency mandates and extend fleet operational lifespans.
Growth Catalysts
- EU Green Deal Emissions Targets:Binding carbon reduction mandates for European carriers are accelerating certification pathways for recycled and bio-based aerospace-grade polymers, expanding the addressable market for sustainable materials.
- Automated Fiber Placement:Advanced manufacturing processes are reducing labor content in wing and fuselage segments, enabling broader adoption of carbon-fiber reinforced composites in primary structural applications.
- German Aerospace Corridor Concentration:Airbus supply chains and specialized compounders clustering around Hamburg and Munich are creating dense innovation ecosystems that shorten qualification cycles for new polymer formulations.
Market Restraints
- Petrochemical Feedstock Volatility:Aerospace-grade polymer production depends on specialized monomer supplies whose pricing fluctuates with crude oil and natural gas derivatives, compressing compounder margins during energy price spikes.
- Western Supplier Concentration:High-performance thermoplastic and thermoset qualification depth resides with a limited set of incumbent compounders in Germany, the United States, and Japan, creating supply vulnerability for emerging OEM programs.
- FAA-EASA Certification Divergence:Differences between 14 CFR Part 25 flammability standards and EASA CS-25 smoke toxicity requirements force dual qualification investments, extending time-to-market for global polymer launches.
Strategic Opportunities
- China Indigenous Supply Chain Development:COMAC's C919 production expansion and MEE/SAMR regulatory evolution are creating openings for qualified compounders to establish local production and bypass Western import dependencies.
- Out-of-Autoclave Curing Convergence:Combining resin transfer molding with automated fiber placement is enabling thermoset composite production without capital-intensive autoclave infrastructure, lowering barriers for tier-two aerostructures suppliers.
- Cabin Interior Retrofit Cycles:Accelerated airline refurbishment schedules to meet refreshed FAA and EASA fire safety standards are generating aftermarket demand for thermoplastic solutions in seating, paneling, and ducting applications.
Industry Challenges
- Polymer Synthesis Talent Scarcity:Specialized expertise in high-heat thermoplastic formulation and aerospace-grade fluoropolymer synthesis is concentrating among retiring cohorts at incumbent suppliers, constraining R&D throughput.
- Dual-Jurisdiction Certification Timelines:Simultaneous FAA and EASA qualification for new polymer grades requires 18-36 month test programs, delaying revenue recognition and freezing formulation investments during regulatory review periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Plastics Market |
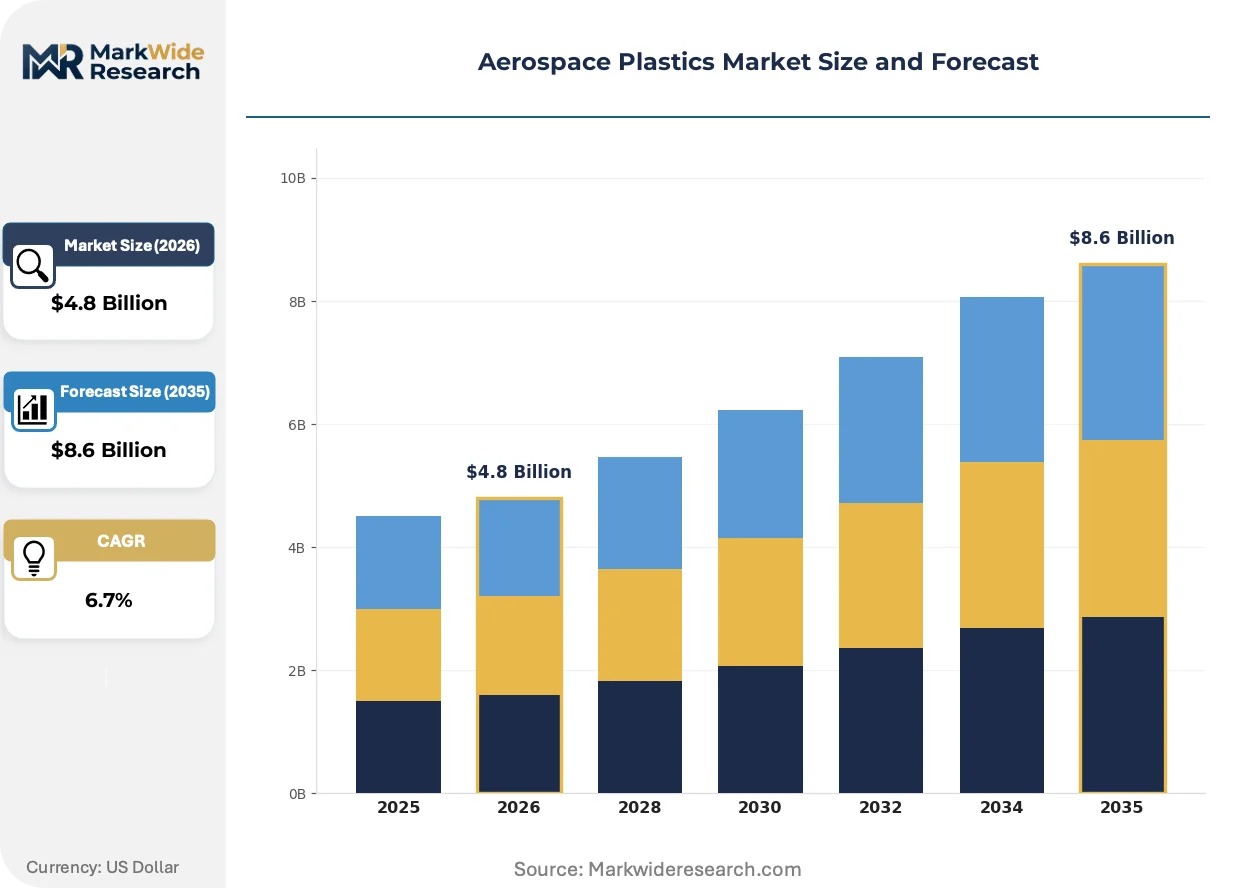
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosetting Plastics, Reinforced Plastics, Composites End User: Commercial Aviation, Military Aviation, Spacecraft, Unmanned Aerial Vehicles Application: Interior Components, Exterior Components, Structural Components, Electrical Components Manufacturing Stage: Injection Molding, Compression Molding, 3D Printing, Automated Layup |
| Companies Covered | SABIC, Solvay, BASF SE, Victrex plc, Evonik Industries AG, DuPont, PPG Industries, Inc., Hexcel Corporation, Ensinger GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Plastics Market Evolving Landscape
Advanced manufacturing integration and regulatory stringency are compressing development cycles while expanding the performance envelope of aerospace polymers beyond traditional thermoset dominance.
Thermoplastic composites are consolidating structural applications previously reserved for thermosets, as PEEK and PEKK matrices deliver comparable mechanical properties with reprocessability and weldability advantages. Tier-one aerostructures suppliers in Germany and the United States are adopting these materials for wing ribs, brackets, and fuselage frames. This consolidation is compressing the supplier base around compounders with captive resin synthesis and automated placement equipment.
REACH chemical restrictions and the EU F-Gas Regulation are forcing reformulation of legacy fluoropolymer and polyamide systems used in fuel systems and thermal management applications. ECHA substance of very high concern designations are triggering substitution mandates for specific plasticizers and flame retardants. European compounders are responding with bio-based feedstock integration and closed-loop recycling certifications to maintain OEM qualification status.
Airline procurement departments are unbundling material specification from component manufacturing, creating direct contracting relationships with qualified polymer suppliers for long-term resin supply agreements. This disintermediation bypasses traditional tier-two fabricator margins and shifts volume commitment risk to compounders. The pattern is most visible among low-cost carriers in Europe and Southeast Asia with centralized fleet management operations.
Aerospace Plastics Market Segmentation
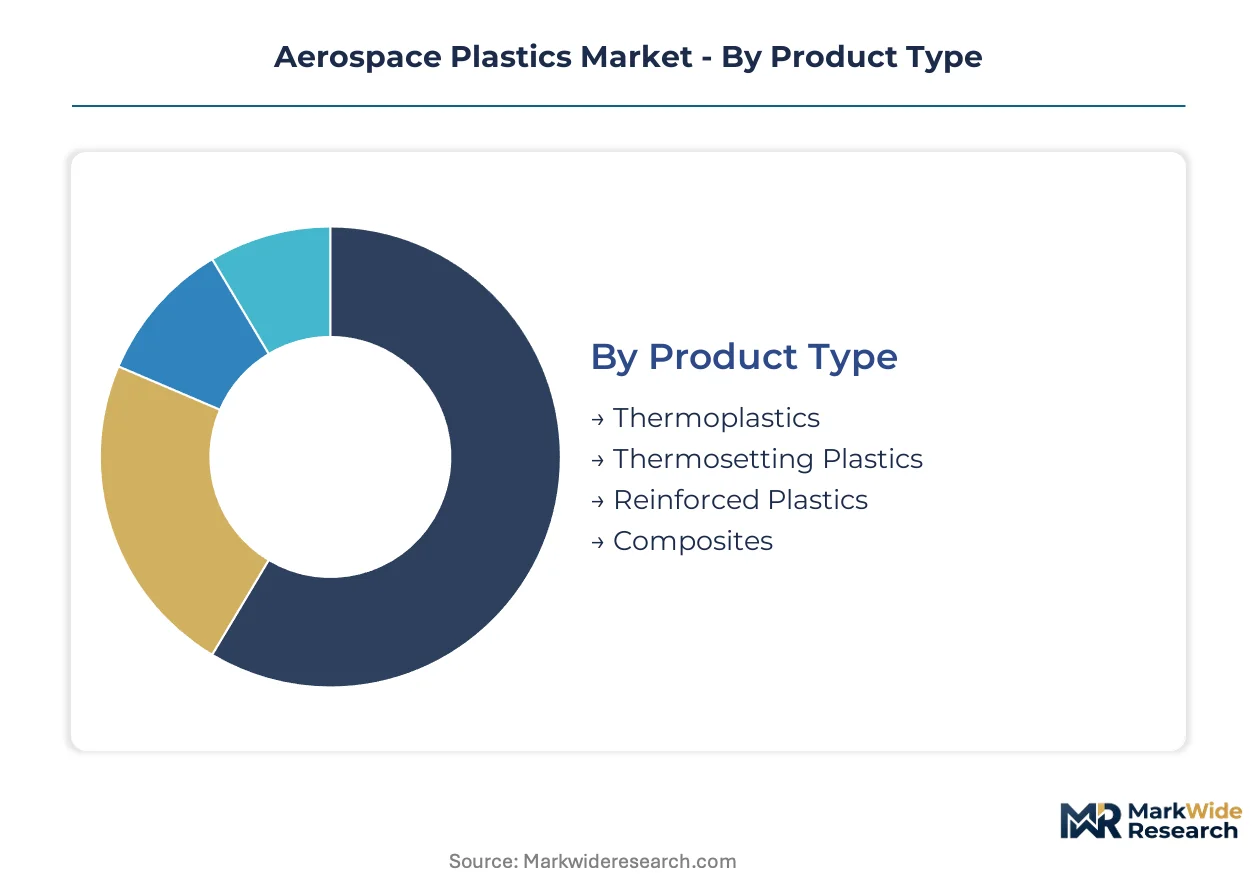
Segmentation reveals how capital deployment, regulatory pathways, and manufacturing economics diverge across aerospace plastics categories. Each dimension carries distinct qualification burdens and margin structures that shape supplier strategy and customer procurement patterns.
Product Type:
Capital intensity varies sharply across polymer families, with continuous-fiber composites demanding the heaviest upfront investment in autoclaves and automated placement equipment while thermoplastics offer lower barriers through reprocessability.
- Thermoplastics:PEEK, PEKK, and PPS matrices deliver melt-processability and weldability advantages that slash cycle times versus thermosets. Demand concentrates in cabin interiors and secondary structures where German compounders around Hamburg supply Airbus programs with fire-rated formulations meeting EASA CS-25 smoke toxicity limits.
- Composites:Carbon-fiber reinforced polymers with thermoset or thermoplastic matrices dominate wing ribs, fuselage frames, and empennage structures. Automated fiber placement and out-of-autoclave curing are compressing labor content and expanding adoption beyond Boeing and Airbus to tier-one aerostructures suppliers in Japan and the United States.
- Thermosetting Plastics:Epoxy and phenolic systems retain cost advantages in legacy aircraft programs and repair operations. Curing infrastructure requirements limit new market entrants.
- Reinforced Plastics:Short-fiber and particulate-filled polymers bridge performance gaps between neat resins and continuous-fiber composites. Injection molding compatibility drives volume in bracketry and non-structural hardware.
Thermoplastics absorb the bulk of installed capacity; composites are expanding most quickly.
End User:
Customer procurement patterns split between long-cycle OEM programs with decade-long qualification timelines and aftermarket operators with compressed refurbishment schedules.
- Commercial Aviation:Narrow-body and wide-body fleet renewal drives polymer substitution in seating, ducting, and overhead bins. EU Green Deal emissions targets are accelerating recycled-content mandates for European carrier procurement specifications.
- Military Aviation:Stealth coatings, radar-transparent radomes, and armor-grade composites command premium pricing through specialized defense contractors. ITAR and EAR export controls constrain supplier pools.
- Unmanned Aerial Vehicles:Rapid design iteration and lower certification burdens enable thermoplastic adoption in airframes and propulsion housings. Chinese manufacturers leverage domestic PEEK supply chains for cost positioning.
- Spacecraft:Outgassing requirements and extreme thermal cycling narrow qualified material sets to fluoropolymers and high-performance thermoplastics. NASA-STD-6016 and ESA ECSS-Q-ST-70-02 govern polymer selection for satellite and launch vehicle applications.
Commercial aviation commands the dominant revenue share; unmanned aerial vehicles are climbing the fastest as defense and logistics applications multiply.
Application:
Fire safety regulations create tiered qualification barriers that segment the market by risk exposure and replacement liability.
- Interior Components:Seating, paneling, and galley systems face the most stringent FAA 14 CFR Part 25.853 flammability and smoke density requirements. Thermoplastic solutions from SABIC's Ultem portfolio dominate retrofit cycles as carriers refresh cabins to meet refreshed safety standards.
- Structural Components:Primary load-bearing applications require damage tolerance certification and fatigue testing protocols that extend development timelines. Automated layup and resin transfer molding are displacing hand layup in wing and fuselage production.
- Exterior Components:Radomes, fairings, and nacelles balance aerodynamic performance with UV and moisture resistance. Fluoropolymer coatings protect underlying substrates in harsh atmospheric conditions.
- Electrical Components:Wire insulation, connectors, and circuit housings demand dielectric stability across temperature extremes. REACH chemical restrictions are forcing reformulation of legacy plasticizers and flame retardants in European-sourced systems.
Interior components capture the largest volume commitment; structural components are gaining share fastest as automated manufacturing reduces composite cost penalties.
Manufacturing Stage:
Process selection determines scrap rates, labor content, and scalability for different production volumes and part geometries.
- Automated Layup:Fiber placement and tape laying systems reduce touch labor in large aerostructures while improving repeatability. German and American equipment suppliers dominate machine tool installation bases.
- Injection Molding:High-throughput processing of thermoplastics and reinforced compounds suits bracketry, fasteners, and interior hardware. Tooling costs amortize across high-volume commercial aviation programs.
- 3D Printing:Powder bed fusion and filament deposition enable topology-optimized geometries and low-volume spare part production. FAA qualification of printed flight-critical components remains limited to non-structural applications.
- Compression Molding:Sheet molding compound and bulk molding compound processes serve legacy thermoset applications in radomes and electrical housings where tool simplicity outweighs cycle time penalties.
Injection molding retains the broadest installed base; automated layup is expanding most quickly as primary structure composites penetrate new aircraft programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors aerospace plastics demand through Airbus final assembly lines and dense supplier corridors stretching toward Munich. German compounders cluster around these nodes to shorten qualification cycles for cabin interior and structural polymer programs. This corridor concentration shapes procurement patterns across European aviation supply chains.
Germany
Airbus Hamburg and Munich production lines drive specification authority for thermoplastic cabin components and composite aerostructures. REACH chemical restrictions and EU Green Deal emissions mandates force reformulation of legacy fluoropolymer systems. Specialized compounders in the Hamburg-Munich corridor maintain captive resin synthesis capabilities to secure OEM qualification status.
United States
Boeing Seattle and Charleston operations sustain demand for carbon-fiber reinforced composites in primary structures alongside aftermarket retrofit programs. FAA 14 CFR Part 25 flammability standards govern material selection across all US-registered fleets. Tier-one aerostructures suppliers in Wichita and Dallas-Fort Worth deploy automated fiber placement to reduce composite labor content.
China
COMAC Shanghai final assembly for the C919 narrow-body program is developing indigenous polymer supply chains to reduce Western import dependency. MEE environmental standards and SAMR certification frameworks are evolving to accommodate domestic aerospace-grade compounders. Yangtze River Delta chemical parks near Shanghai host emerging thermoplastic and thermoset production investments.
France
Airbus Toulouse headquarters and Saint-Nazaire long-range aircraft facilities concentrate demand for high-heat thermoplastics in engine nacelles and interior systems. EASA CS-25 smoke toxicity requirements intersect with REACH substance restrictions to shape formulation choices. Aeroclusters in Occitanie and Nouvelle-Aquitaine host specialized composite fabricators serving Dassault and Safran programs.
Japan
Toray and Teijin carbon fiber operations in Nagoya and Osaka underpin composite feedstock supply for Boeing and Airbus tier-one suppliers. METI industrial policy supports aerospace materials R&D through designated technology zones. Chubu region automated equipment manufacturers export fiber placement and tape laying systems to German and American aerostructures facilities.
Aerospace Plastics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification depth and captive synthesis capabilities. The vendor base concentrates among European and American compounders with decade-long OEM approval histories, while Asian entrants cluster in lower-tier reinforced plastics. Three archetypes dominate: integrated resin-to-component suppliers, specialized high-heat thermoplastic compounders, and carbon-fiber prepreg manufacturers. Competitive moves center on backward integration into monomer production and strategic partnerships with automated equipment vendors to secure placement technology access.
Within the integrated chemical conglomerate tier, SABIC and Solvay occupy positions exemplifying qualification breadth across cabin interior and structural applications. Among specialized high-performance polymer manufacturers, Victrex plc represents the focused compounder archetype with concentrated expertise in PEEK matrices. German fabricators including Ensinger GmbH anchor the mid-tier reinforced plastics segment serving bracketry and hardware applications.
| Leading Market Players |
|---|
| SABIC |
| Solvay |
| BASF SE |
| Victrex plc |
| Evonik Industries AG |
| DuPont |
| PPG Industries, Inc. |
| Hexcel Corporation |
| Ensinger GmbH |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FAA-qualified and non-certified polymer batches creates a bifurcated pricing architecture that feeds directly into supply chain configuration. Premium pricing accrues to compounders with captive resin synthesis and dual-jurisdiction qualification depth, while commodity-grade reinforced plastics trade on volume scale through distributor networks anchored in German and American aerospace corridors.
Pricing Analysis
Value-based pricing anchored to airframe weight-reduction outcomes dominates long-term supply agreements between tier-one aerostructures suppliers and OEM procurement departments. Price differentiation separates fire-rated thermoplastic formulations meeting EASA CS-25 smoke toxicity limits from standard industrial grades lacking aerospace certification. Cost compression in reinforced plastics is intensifying as Chinese domestic compounders expand PEEK production capacity and challenge Western incumbents on bracketry and hardware applications. Low-cost carriers in Southeast Asia exhibit the highest price sensitivity, demanding unbundled resin supply contracts that bypass traditional tier-two fabricator markups.
Supply Chain Analysis
Dual-sourcing requirements mandated by Boeing and Airbus procurement protocols force compounders to maintain redundant production qualifications across Germany, the United States, and Japan. Raw material dependencies center on specialized monomer feedstocks from petrochemical complexes, Toray carbon fiber prepreg from Nagoya, and fluoropolymer resin from Solvay's Belgian synthesis facilities. Single-source vulnerability concentrates in high-heat thermoplastic matrices where Victrex and Solvay control qualified PEEK and PEKK supply. Distribution runs through long-term offtake agreements with tier-one aerostructures suppliers rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive monomer production represents the decisive competitive lever as compounders race to secure margin control and qualification autonomy against feedstock volatility.
For Market Incumbents: Deploy backward integration into specialized monomer synthesis to defend margin structures against petrochemical feedstock volatility. Incumbents should accelerate automated fiber placement partnerships with German equipment vendors to lock in placement technology access before tier-two suppliers achieve cost parity. SABIC and Solvay must extend EASA qualification depth for bio-based formulations ahead of EU Green Deal recycled-content mandates tightening in European carrier procurement specifications. For New Entrants and Emerging Players: Digital-channel direct contracting with low-cost carrier procurement departments offers the most penetrable route around entrenched tier-two distributor relationships. New entrants should target unmanned aerial vehicle airframe applications where certification burdens remain lower and Chinese domestic PEEK supply chains enable cost positioning. A go-to-market angle emphasizing rapid design iteration support and lower minimum order quantities can dislodge legacy compounders from defense and logistics UAV programs. For Investors and Strategic Acquirers: Re-rating potential sits with specialized high-heat thermoplastic compounders possessing captive resin synthesis and existing FAA-EASA dual qualification given accelerating metal-to-polymer substitution in primary aerostructures. Long-term viability over the next decade hinges on positioning ahead of COMAC C919 supply chain indigenization and out-of-autoclave curing convergence lowering barriers for tier-two entrants. The signal to watch is MEE and SAMR regulatory evolution enabling domestic Chinese compounders to achieve aerospace-grade certification parity with Western incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive feedstock supply insulates compounder margins from petrochemical volatility and secures OEM qualification continuity. |
| Automated Fiber Placement Partnership | Equipment vendor alliances with Chubu region manufacturers compress labor content in composite aerostructures production. |
| Dual-Jurisdiction Certification Investment | Simultaneous FAA 14 CFR Part 25 and EASA CS-25 qualification opens access to Boeing and Airbus supply chains. |
| Bio-Based Feedstock Integration | REACH-compliant reformulation maintains OEM qualification status as ECHA substance restrictions tighten on legacy plasticizers. |
| Out-of-Autoclave Curing Adoption | Resin transfer molding convergence enables tier-two suppliers to produce thermoset composites without capital-intensive autoclave infrastructure. |
Research Methodology
SEC 10-K filings, ECHA substance restriction databases, and customs trade data formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with polymer procurement managers at tier-one aerostructures suppliers, technical R&D directors at German compounders, and airline fleet management executives validated demand assumptions and qualification timeline estimates. Bottom-up triangulation across product type, end user, and application segments was cross-checked against top-down aerospace production forecasts from Boeing and Airbus order backlogs.
Historical trendline analysis of aerospace polymer consumption patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include polymer family, manufacturing process, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year market values, with adjustments for EU Green Deal emissions acceleration and COMAC C919 production ramp assumptions. Industry-specific forecast inputs incorporated automated fiber placement adoption rates and out-of-autoclave curing penetration in primary structures.
The model holds under stable FAA-EASA regulatory convergence and continued Airbus-Boeing duopoly in commercial aviation; deviation in COMAC supply chain indigenization timelines or REACH substance restriction acceleration would shift the outlook materially. Deviation in petrochemical feedstock volatility or polymer synthesis talent scarcity would compress compounder margins and extend qualification cycles beyond modeled assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market