
 Aerospace Radome Market | 2026-2036
Aerospace Radome Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Radome Market Intelligence
Aftermarket services for radome repair and upgrades is reshaping the profit landscape for manufacturers. General Dynamics Mission Systems leverages its deep integration with military platforms to secure long-term contracts. Raytheon Technologies Corporation differentiates through its advanced material science, while Northrop Grumman Corporation specializes in radomes for low-observable aircraft platforms.
An aerospace radome is a structural, weatherproof enclosure designed to protect radar and communication antennas on aircraft, satellites, and ground stations. Constructed from materials with specific dielectric properties, its primary function is to provide environmental protection while remaining transparent to radio frequencies. While the military aircraft segment constitutes a mature and high-value application area, demand from the UAV sector is expanding rapidly. Fiber reinforced composites, particularly glass and quartz fiber variants, dominate material selection due to their optimal balance of structural strength and electromagnetic performance.
Product certification and airworthiness are governed by stringent regulations, including those from the U.S. Federal Aviation Administration (FAA) and requirements for CE marking in Europe. These standards dictate material traceability, manufacturing processes, and performance validation, creating high barriers to entry. Stakeholder success will depend on developing radomes that support multi-band functionality and withstand the extreme conditions of hypersonic flight.
Market Dynamics
The imperative to support higher frequency satellite communications, particularly in the Ka-band and Ku-band, is the central force shaping the aerospace radome market. This technological necessity, driven by demand for inflight connectivity and advanced military data links, dictates material science choices and product development priorities.
Growth Catalysts
- Satellite Constellation Expansion:The rapid deployment of Low Earth Orbit (LEO) satellite networks for broadband internet is creating a substantial new source of demand for compatible radomes on commercial and business aircraft.
- UAV Proliferation:Expanding military and civilian applications for Unmanned Aerial Vehicles, from reconnaissance to package delivery, require a growing volume of smaller, lightweight, and aerodynamically efficient radomes.
- Next-Generation Aircraft Programs:Government investment in advanced combat aircraft in the United States and Europe necessitates the development of highly specialized radomes that integrate stealth features and support complex sensor suites.
Market Restraints
- Material Cost and Scarcity:High-performance materials essential for advanced radomes, such as quartz fiber and specialized ceramic matrix composites, are characterized by high costs and supply chains concentrated in a few specialized suppliers.
- Multi-Band Design Complexity:Engineering a single radome structure that remains electromagnetically transparent across a wide range of frequencies without performance trade-offs presents a significant and persistent technical barrier.
- Stringent Certification Cycles:The extensive and costly airworthiness certification processes mandated by regulators like the FAA and the European Union Aviation Safety Agency (EASA) create long development timelines and high barriers to entry for new manufacturers.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging market for electric vertical take-off and landing (eVTOL) aircraft for intra-city transport represents a new application frontier, requiring radomes optimized for sense-and-avoid radar systems.
- Smart Radome Structures:Integrating antenna elements and sensor functionalities directly into the radome's composite structure offers a pathway to reduce aircraft weight, complexity, and aerodynamic drag, creating a new value proposition.
- Aftermarket Upgrades:A significant opportunity exists in upgrading legacy commercial and military aircraft fleets with modern radomes that enable access to new high-throughput satellite communication networks.
Industry Challenges
- Specialized Talent Shortage:A scarcity of engineers and technicians with combined expertise in radio frequency (RF) engineering, composite materials science, and aerospace manufacturing constrains product development and innovation.
- Electromagnetic Interference Management:Ensuring that new radome installations do not interfere with other sensitive avionics systems on increasingly crowded aircraft platforms is a major integration challenge for designers and installers.
- High-Cost Testing Infrastructure:The capital investment required for building and maintaining sophisticated anechoic chambers and other facilities for radome performance testing is substantial, limiting the number of qualified vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Radome Market |
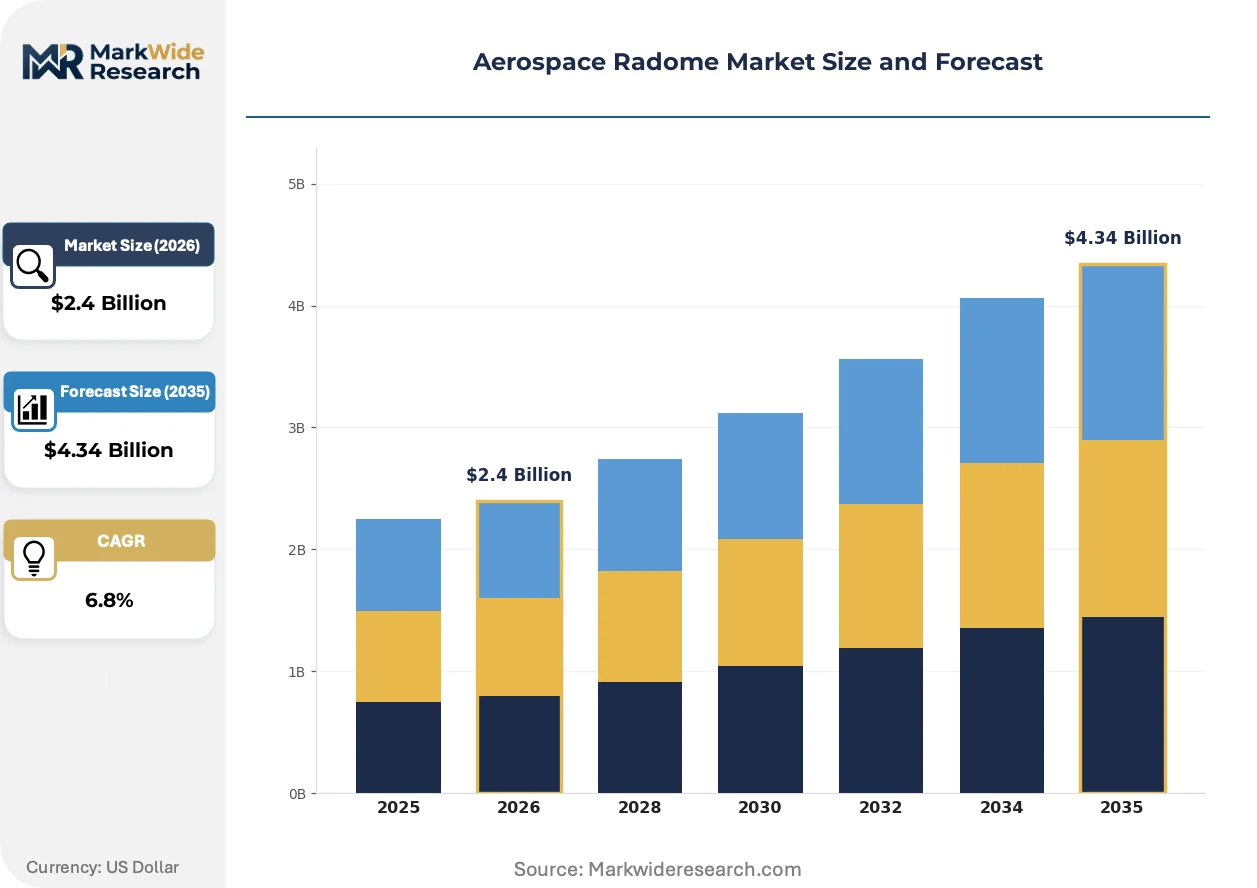
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Radomes, Active Radomes, Ground-Based Radomes, Spaceborne Radomes Application: Commercial Aircraft, Military Aircraft, UAVs, Weather Monitoring Material Type: Fiber Reinforced Composites, Thermoplastics, Metals, Other Materials End User: Aerospace Manufacturers, Defense Contractors, Airlines, Research Institutions |
| Companies Covered | General Dynamics Mission Systems, Inc, Raytheon Technologies Corporation, Saint-Gobain Aerospace, Cobham Limited, Northrop Grumman Corporation, L3Harris Technologies, Inc, Israel Aerospace Industries Ltd, The NORDAM Group LLC, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Radome Market Strategic Shifts & Innovations
Material science advancements are enabling the development of multi-function radomes that go beyond simple environmental protection. These innovations are a direct response to new operational requirements for stealth, multi-band connectivity, and performance in extreme flight environments like hypersonic speeds.
Metamaterials, which are artificially structured composites, provide unprecedented control over electromagnetic waves. These materials are seeing initial adoption within classified military programs for their ability to create highly directional antenna beams and advanced stealth profiles. The unique capability of metamaterials to achieve frequency-selective performance is rendering obsolete prior generations of radomes that relied solely on geometric shaping for low-observability.
European Union regulations, including the Corporate Sustainability Reporting Directive (CSRD) and the REACH framework governing chemicals, are influencing material selection. This regulatory pressure compels manufacturers to evaluate the entire lifecycle impact of their products, from raw material sourcing to end-of-life disposal. The aerospace composites segment is most affected, accelerating research into thermoplastic composites and bio-resins as more sustainable alternatives to traditional thermoset materials.
Aircraft operators are increasingly pursuing performance-based service agreements for radome maintenance and repair, moving away from simple transactional acquisitions. This model disrupts the conventional approach where an airline buys a component and then separately manages its MRO cycle. The trend is most visible within large commercial airline fleets in North America and Europe, which seek to achieve predictable maintenance expenditures and guaranteed component availability.
Aerospace Radome Market Segmentation
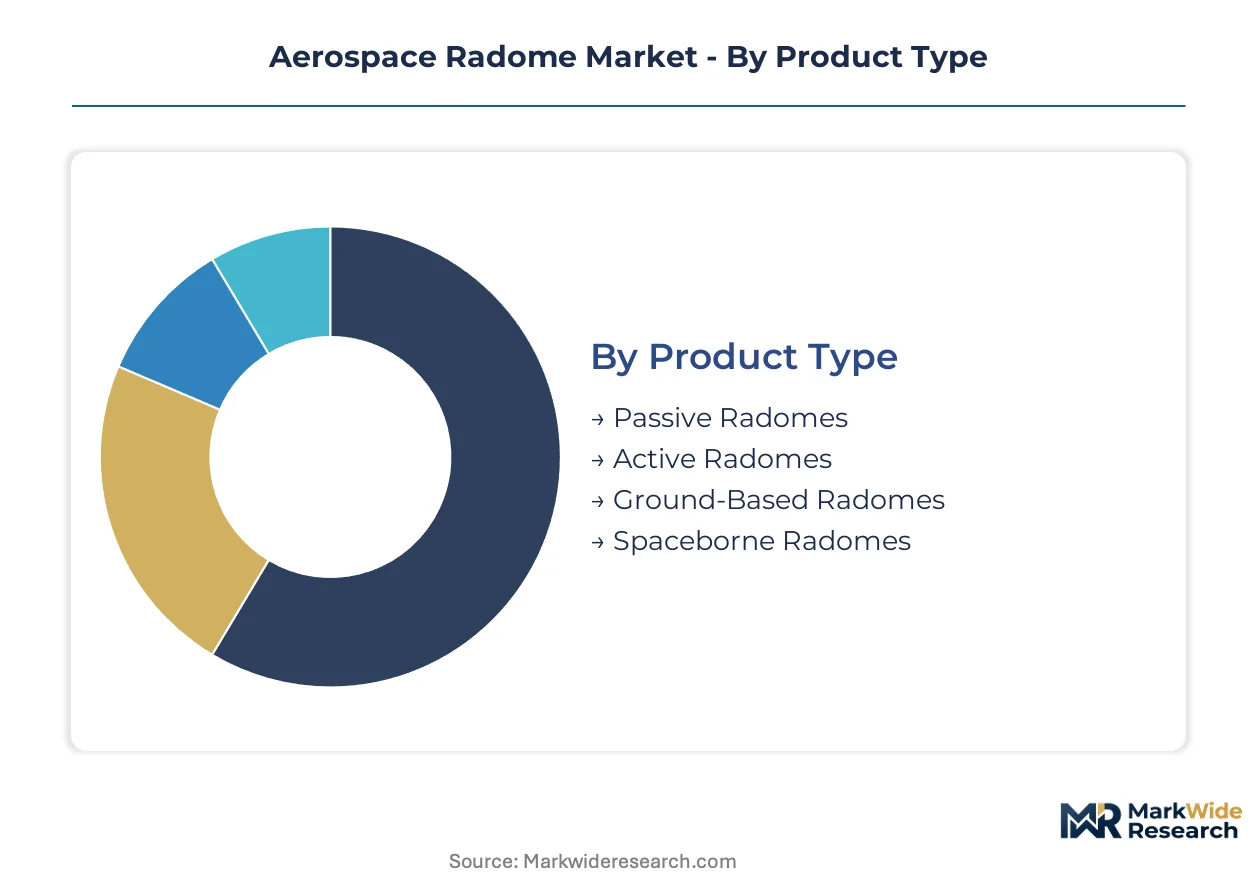
The aerospace radome market exhibits distinct segmentation across product type, application, material, and end-user categories. Understanding these segments is critical for stakeholders to identify specific demand patterns and technological requirements. Each segment reflects unique operational demands and regulatory compliance needs within the broader aviation and defense sectors.
Product Type:
Product types differentiate by their operational lifecycle and integration complexity, influencing replacement cycles. Radomes for fixed-wing aircraft generally have longer service intervals than those on rapidly evolving satellite platforms. The design sophistication also dictates development and certification timelines for new product generations.
- Passive Radomes:These structures primarily protect antennas without contributing to their electromagnetic function, focusing on structural integrity and signal transparency. Demand concentrates in commercial aviation for weather radar and communication systems, driven by fleet upgrades and new aircraft deliveries.
- Active Radomes:Integrating antenna elements or other active components directly into the radome structure, these offer enhanced performance and reduced weight. Military aircraft platforms, especially those requiring advanced stealth characteristics, drive the development and adoption of active radome technologies.
- Ground-Based Radomes:These large, stationary enclosures protect terrestrial radar and communication arrays, emphasizing durability against severe environmental conditions.
- Spaceborne Radomes:Designed for satellite and spacecraft applications, these require extreme thermal stability and radiation resistance for reliable extraterrestrial operation.
Passive Radomes dominate the installed base across commercial fleets. Active Radomes represents the fastest-growing trajectory, driven by advanced military platform requirements and emerging sensor integration needs.
Application:
Application segments are differentiated by operational environment and performance requirements, ranging from high-volume commercial use to specialized military and scientific missions. Each application demands specific aerodynamic profiles and electromagnetic transparency characteristics. The complexity of integration varies significantly across these distinct use cases.
- Military Aircraft:Radomes for military platforms prioritize stealth, multi-band functionality, and resistance to extreme flight conditions, including hypersonic speeds. Investment in advanced combat aircraft programs in the United States and Europe drives this high-value segment.
- UAVs:This segment requires lightweight, aerodynamically efficient, and often smaller radomes to support diverse missions from reconnaissance to package delivery. The proliferation of unmanned systems across military and civilian sectors fuels significant volume expansion.
- Commercial Aircraft:Radomes for commercial aviation focus on durability, cost-efficiency, and compliance with stringent airworthiness certifications for passenger safety.
- Weather Monitoring:This application utilizes radomes for protecting meteorological radar systems, requiring excellent signal transparency across specific weather detection frequencies.
Military aircraft applications command the highest value per unit due to advanced performance demands. UAV applications are expanding most quickly, reflecting the rapid growth in unmanned systems deployment.
Material Type:
Material selection is heavily influenced by performance requirements, manufacturing complexity, and supply chain availability. High-performance materials like quartz fiber and specialized ceramic matrix composites often face supply concentration challenges. Regulatory pressures, such as EU CSRD, also influence the adoption of sustainable alternatives.
- Fiber Reinforced Composites:These materials, particularly glass and quartz fiber variants, offer an optimal balance of structural strength and electromagnetic performance. They dominate radome construction due to their light weight and customizable dielectric properties, essential for modern aircraft.
- Thermoplastics:Emerging as a more sustainable alternative to traditional thermoset materials, thermoplastics offer advantages in recyclability and faster manufacturing cycles. Research into thermoplastic composites is accelerating due to European Union regulations on lifecycle impact.
- Metals:Limited to specific applications where electromagnetic transparency is not paramount, metals provide high structural rigidity and impact resistance.
- Other Materials:This category includes specialized ceramics and advanced metamaterials, used in highly niche or classified applications requiring unique electromagnetic properties.
Fiber Reinforced Composites constitute the largest volume of material used in radome manufacturing. Thermoplastics are gaining share fastest, driven by sustainability initiatives and manufacturing efficiency improvements.
End User:
End-user segments are defined by their procurement patterns and specific integration needs within their operational frameworks. Aerospace manufacturers focus on initial equipment integration, while airlines prioritize aftermarket services and upgrades. Defense contractors require long-term support for their integrated military platforms.
- Aerospace Manufacturers:These entities integrate radomes into new aircraft, satellite, and UAV platforms during the initial build phase, requiring close collaboration on design and certification. Demand is tied to new aircraft program cycles and production rates.
- Defense Contractors:Specializing in military platforms, these contractors procure radomes for highly specialized applications, often involving classified programs and long-term service agreements. General Dynamics Mission Systems exemplifies this strategic procurement approach.
- Airlines:Airlines primarily procure radomes for maintenance, repair, and overhaul (MRO) activities, focusing on aftermarket upgrades and performance-based service agreements.
- Research Institutions:These organizations acquire radomes for experimental purposes, prototype development, and advanced material testing, contributing to future technological advancements.
Aerospace Manufacturers represent the foundational demand for new radome units. Defense Contractors drive the highest value per unit, reflecting the complexity and strategic importance of their platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aerospace radome market exhibits distinct consumption mixes across major global regions. United States demand concentrates on military applications and advanced research and development. European markets prioritize commercial aircraft upgrades and next-generation air mobility solutions. Asian nations like Japan and South Korea focus on domestic aerospace expansion and satellite communication platforms.
United States
Military aircraft upgrades and expanding UAV proliferation drive significant demand for aerospace radomes. The U.S. Federal Aviation Administration (FAA) mandates stringent airworthiness certifications. Major aerospace manufacturing hubs in Seattle, Washington, and Wichita, Kansas, host radome integration activities.
France
Commercial aircraft production and defense export contracts propel the aerospace radome market. The European Union Aviation Safety Agency (EASA) standards govern material traceability and performance validation. Toulouse, France, serves as a primary European aerospace manufacturing center for radome integration.
Germany
Advanced material science research and commercial aircraft maintenance sustain radome demand in Germany. CE marking requirements influence product compliance for radomes entering the European market. Hamburg, Germany, supports significant commercial aircraft MRO operations and component manufacturing.
Japan
Domestic defense modernization and spaceborne radome development contribute to Japan's market. The Japan Civil Aviation Bureau (JCAB) oversees airworthiness standards for aerospace components. Nagoya, Japan, is a key aerospace manufacturing region, contributing to domestic and international programs.
South Korea
Expanding UAV sector requirements and satellite communication infrastructure development fuel radome demand. The country's national aviation safety authority ensures rigorous certification for new aerospace parts. Daejeon, South Korea, supports advanced research and development in aerospace composites and electronics.
Aerospace Radome Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. This market features a mix of highly specialized defense contractors, material science innovators, and large commercial MRO providers. Technology licensing and strategic partnerships for co-development are common among firms seeking to integrate multi-band functionality. Portfolio diversification across military and commercial applications also represents a dominant competitive move.
Specialists in advanced military platforms and material science exemplify the high-value segment of the market. General Dynamics Mission Systems, Inc. occupies a position anchored by deep integration with military programs and long-term government contracts. Raytheon Technologies Corporation represents a leader in advanced material science for radome applications, particularly for higher frequency communications. Northrop Grumman Corporation sits within the tier focusing on low-observable aircraft platforms and stealth technology integration, demanding highly specialized radome designs. These companies often leverage extensive R&D capabilities to meet stringent performance requirements.
| Leading Market Players |
|---|
| General Dynamics Mission Systems, Inc |
| Raytheon Technologies Corporation |
| Saint-Gobain Aerospace |
| Cobham Limited |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc |
| Israel Aerospace Industries Ltd |
| The NORDAM Group LLC |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
The Trans-Atlantic air freight corridor's cost dynamics significantly influence both specialized material supply concentration and downstream radome price differentiation. This corridor facilitates the movement of high-performance components between key aerospace manufacturing clusters, impacting overall product costs.
Pricing Analysis
Long-term contract-based offtake agreements dominate radome procurement, particularly for military platforms and new aircraft programs. Price differentiation stems from the customization level required for stealth integration and the stringent certification level mandated by the FAA or EASA. Pricing softness affects the commercial aftermarket due to increasing adoption of performance-based service agreements by airlines. Defense contractors exhibit the least price sensitivity, prioritizing performance and reliability, while commercial airlines remain the most price-sensitive buyers.
Supply Chain Analysis
Supply chain vulnerability for specialized materials like quartz fiber and advanced ceramic matrix composites represents a significant structural risk. Geographic supply concentration for these high-performance inputs largely resides in the United States and specific European Union nations. Key raw material dependencies include high-purity silica and specialized resins. Distribution runs through direct sales channels to aerospace manufacturers and defense contractors, complemented by established MRO networks for aftermarket services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace radome market sits at a platform-economics inflection point, driven by the integration of multi-band functionality and advanced sensor suites within aircraft ecosystems.
For Market Incumbents: Insulate core market share by deepening integration with next-generation military aircraft programs and investing heavily in advanced materials R&D. This strategy defends against emerging metamaterial specialists challenging traditional radome designs. Pursue certification investment for new material applications under FAA and EASA standards to maintain a competitive edge and expand market reach.
For New Entrants and Emerging Players: Pursue white-space opportunities in the Urban Air Mobility (UAM) sector, developing optimized radomes for sense-and-avoid radar systems. Another avenue involves specialized aftermarket upgrades for commercial aircraft accessing new Low Earth Orbit satellite networks. The most penetrable segment remains smaller, lightweight radomes for the proliferating UAV sector, leveraging rapid prototyping and certification for niche applications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized material science firms with strong intellectual property in RF engineering. The aerospace radome market demonstrates strong long-term viability, driven by defense modernization and commercial connectivity demands. Acquisition targets should include companies capable of addressing multi-band design complexity. Accelerated adoption of thermoplastic composites in commercial fleets serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Metamaterial Research | Secures leadership in next-generation stealth and multi-band radome technologies for military platforms. |
| Expand Thermoplastic Composite Production | Addresses European Union sustainability regulations and demand for lighter commercial aircraft components. |
| Form LEO Satellite Radome Partnerships | Captures new revenue streams from expanding Low Earth Orbit satellite network deployments. |
| Acquire RF Engineering Specialists | Strengthens capabilities in multi-band design complexity and electromagnetic interference management. |
| Develop Hypersonic Flight Radomes | Positions for future high-value defense contracts requiring extreme environmental resilience. |
Research Approach
Desk research of regulatory filings, technical journals, and aerospace industry reports preceded structured interviews with aerospace engineers, procurement managers, and regulatory compliance officers. This approach combined primary insights with secondary validation. Bottom-up and top-down triangulation ensured comprehensive market sizing and segmentation across various parameters.
The forecast framework held fixed current geopolitical stability and technological development trajectories across the analysis window. Quantitative modeling and qualitative analysis were performed across segmentation dimensions including product type, application, material, end-user, and geographic region. Compound annual growth rates were derived from historical trends, market drivers, and projected technology adoption rates for UAV unit shipments and satellite constellation deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth rates or defense spending could shift the trajectory. Forecasts reflect assumptions documented through extensive primary and secondary research. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aerospace Sealants Market