
 Aerospace and Defense Metal Stamping Market | 2026-2036
Aerospace and Defense Metal Stamping Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Metal Stamping Market Intelligence
Integrated certification and traceability services are broadening the scope of what original equipment manufacturers procure from stamping specialists. American Industrial Company leverages its extensive tooling capabilities for complex structural components. Keats Manufacturing Company specializes in high-volume, precision stamping for smaller avionics parts. Hudson Technologies positions itself with expertise in deep draw stamping for specialized enclosures and housings used in communication equipment.
Aerospace and defense metal stamping involves forming sheet metal, such as aluminum, titanium, or Inconel, into high-precision components using a die and press. This process creates parts that meet stringent flight-critical specifications for strength and fatigue resistance. Progressive die stamping dominates high-volume production of fasteners and brackets, while deep draw stamping is essential for creating seamless engine parts and electrical enclosures. Structural components represent a significant value segment due to the material costs and manufacturing complexity involved.
Strict regulatory oversight from bodies like the FAA in the United States and EASA in Europe mandates material traceability and process validation for all flight-critical parts. Frameworks such as the US International Traffic in Arms Regulations (ITAR) govern the production and export of defense-related stamped components. Supplier selection will increasingly hinge on demonstrated capabilities in advanced materials processing and adherence to evolving cybersecurity protocols for digital design data.
Market Dynamics
The imperative to reduce aircraft weight for fuel efficiency and extend operational range for defense platforms is the central force shaping the aerospace and defense metal stamping market. This drive necessitates a transition to advanced, lightweight alloys which, in turn, increases manufacturing complexity and intensifies certification requirements.
Growth Catalysts
- Expanded Satellite and UAV Programs:The rapid deployment of next-generation satellite constellations and the expanded use of unmanned aerial vehicles (UAVs) in both commercial and defense roles create substantial, high-volume demand for precision stamped components.
- Defense Industrial Base Policies:Government initiatives in the United States and Europe to re-shore critical defense manufacturing are directing contracts toward domestic stamping specialists, particularly for components governed by regulations like ITAR.
- Adoption of High-Strength Alloys:The shift toward advanced materials like titanium alloys and nickel-based superalloys for engine and structural applications allows specialized stampers to capture higher value-add contracts that require specific metallurgical and forming expertise.
Market Restraints
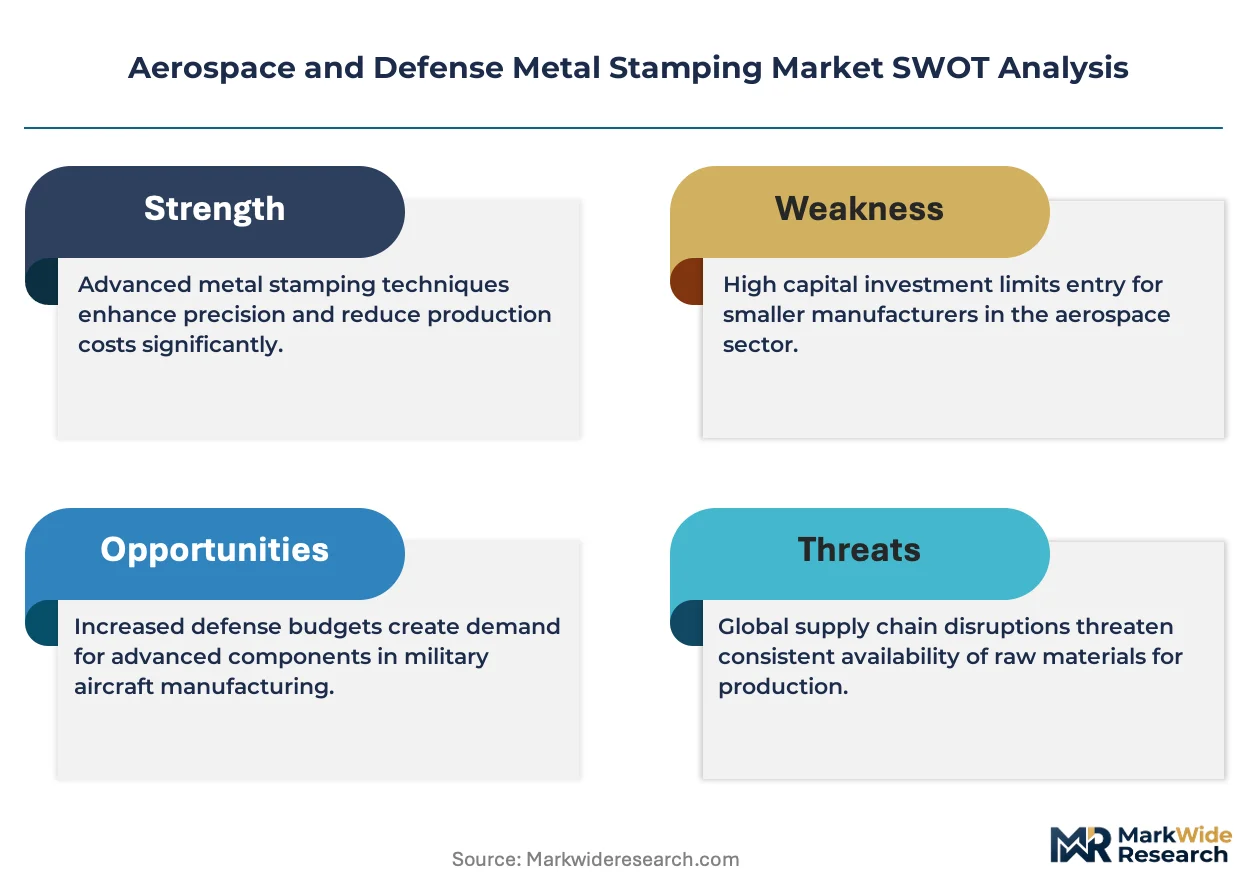
- Raw Material Volatility:The market is exposed to significant price fluctuations and supply chain disruptions for key metals such as titanium and cobalt, with sourcing often concentrated in a few geopolitical regions, creating input cost instability.
- Stringent Certification Barriers:The lengthy and costly processes for part qualification and production approval from regulatory bodies like the FAA and EASA create high barriers to entry and slow the introduction of new materials or processes.
- High Capital Investment:Processing advanced, hard-to-form alloys requires substantial capital expenditure on high-tonnage presses, specialized tooling, and advanced thermal management systems, limiting the number of capable suppliers.
Strategic Opportunities
- Urban Air Mobility (UAM) Sector:The emerging market for electric vertical take-off and landing (eVTOL) aircraft presents a greenfield opportunity for stampers to develop novel, lightweight structural components and battery enclosures for these new platforms.
- Digital Twin Integration:Offering digital twin services that model a stamped part's performance and fatigue life based on its specific material and production data creates a significant value-add, moving suppliers into lifecycle management.
- Additive Manufacturing for Tooling:Utilizing 3D printing to rapidly create and iterate complex forming dies reduces development lead times and costs, enabling faster response to new component designs, especially for low-volume, high-complexity parts.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of experienced tool and die makers, as well as press operators with the expertise to work with exotic alloys and complex progressive dies, constrains production capacity and inflates labor costs.
- Cybersecurity Compliance Costs:Adherence to evolving cybersecurity protocols for protecting digital design data, such as the CMMC framework in the US defense sector, imposes significant administrative and technological costs on suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Metal Stamping Market |
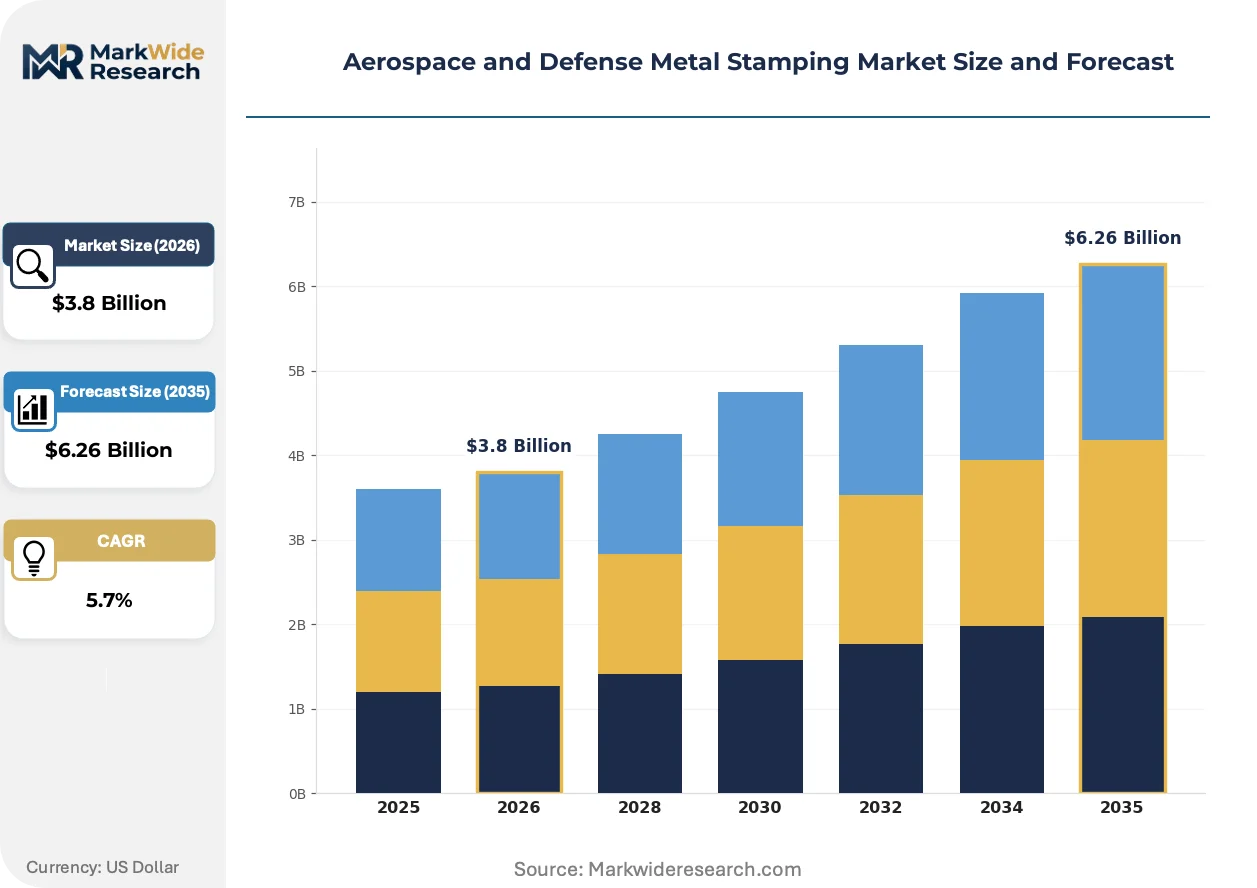
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Components, Engine Parts, Electrical Enclosures, Fasteners, Brackets, Panels Technology: Progressive Die Stamping, Transfer Die Stamping, Deep Draw Stamping, Fine Blanking, Coining, Embossing Application: Flight Control Systems, Weapon Systems, Communication Equipment, Landing Gear, Avionics, Surveillance Devices End User: Original Equipment Manufacturers, Defense Contractors, Aerospace Subcontractors, Military Forces, Government Agencies, Security Providers |
| Companies Covered | American Industrial Company, Keats Manufacturing Company, Wiegel Tool Works Inc., Hudson Technologies, Tempco Manufacturing Company, Inc., D&H Industries Inc., Klesk Metal Stamping Co., Clow Stamping Company, ACRO Metal Stamping Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Metal Stamping Market Strategic Shifts & Innovations
The competitive landscape is being defined by a move toward providing integrated, data-rich manufacturing solutions. Stamping specialists are transitioning from being component suppliers to becoming certified partners who deliver fully traceable and validated parts, embedding digital records directly into their production workflows.
Progressive die stamping integrated with in-die sensing technology is a key process innovation. This allows for the real-time measurement of critical part dimensions and material properties during the high-speed forming process. It is being rapidly adopted by producers of fasteners and electrical contacts for satellite constellations. This real-time quality assurance is overtaking traditional post-production batch inspection, significantly reducing scrap rates.
European Union regulations, particularly the Corporate Sustainability Reporting Directive (CSRD), are introducing new compliance layers. The directive compels large aerospace manufacturers and their suppliers to provide detailed, auditable reports on supply chain energy consumption, material origins, and waste management. This requirement most affects suppliers to European primes like Airbus, forcing investment in data collection systems to prove environmental compliance and retain preferred vendor status.
A notable behavioral change is the OEM preference for sourcing complete sub-assemblies rather than discrete components. This approach disrupts traditional transactional purchasing, favoring strategic suppliers who can manage a portfolio of processes including stamping, welding, finishing, and assembly. This trend is most visible within the commercial airframe supply chains in the United States and France, where major OEMs are actively consolidating their supplier base.
Aerospace and Defense Metal Stamping Market Segmentation
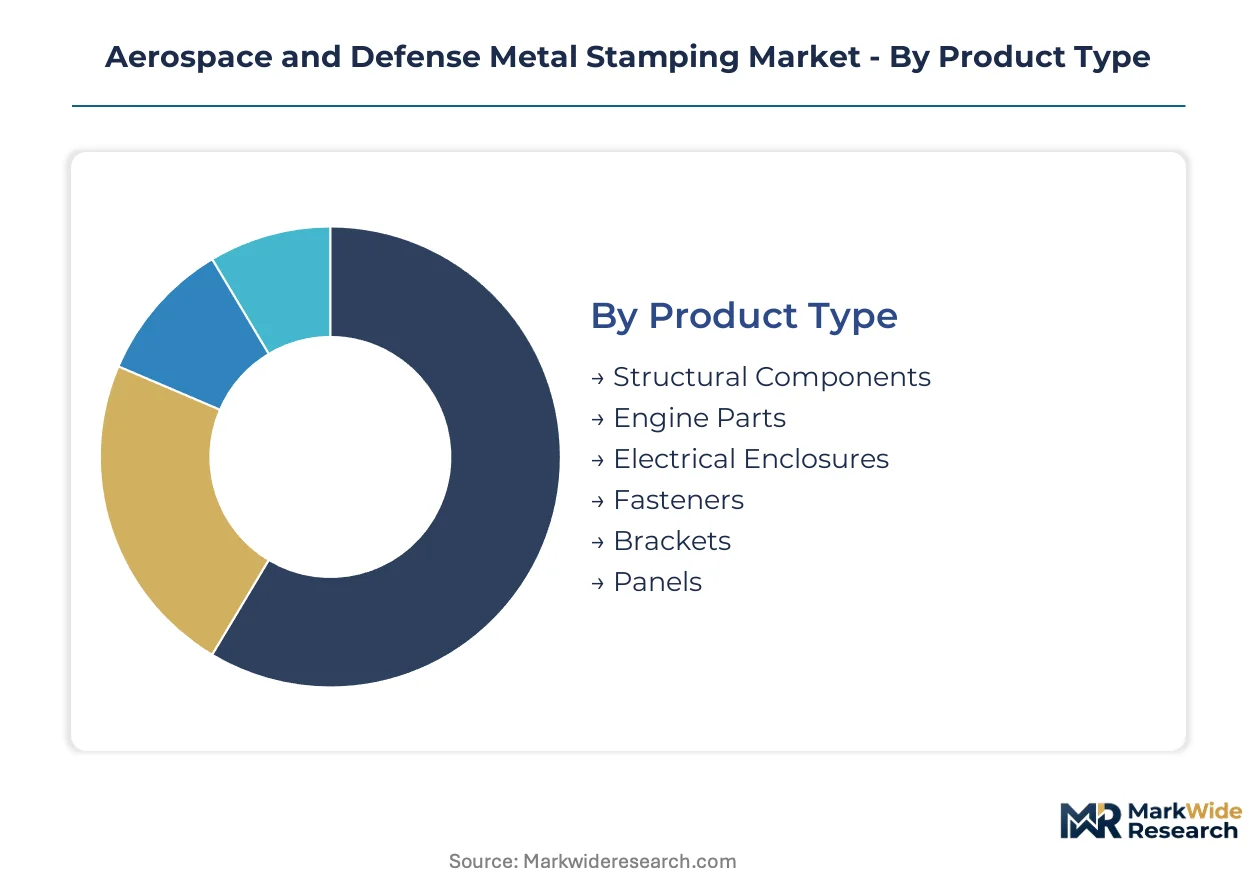
The aerospace and defense metal stamping market differentiates across product types, manufacturing technologies, end-use applications, and customer segments. Understanding these distinctions is critical for suppliers seeking to align their capabilities with specific market needs and regulatory demands within this high-precision industry.
Product Type:
Product types in this market span a spectrum from highly standardized parts to custom-engineered, flight-critical components.
- Structural Components:These complex, high-strength parts are often formed from titanium or advanced nickel-based superalloys, crucial for airframe integrity and fatigue resistance. Demand concentrates in established aerospace manufacturing clusters in the United States and France for next-generation aircraft programs focused on fuel efficiency.
- Engine Parts:Precision-stamped seamless components for aircraft engines frequently utilize deep draw stamping and high-temperature alloys like Inconel. New engine development programs and the imperative to extend operational range for defense platforms drive demand for these specialized parts.
- Electrical Enclosures:These parts protect sensitive avionics and communication equipment, often requiring deep draw stamping for sealed, lightweight designs.
- Fasteners:High-volume production of fasteners, critical for assembly, relies heavily on progressive die stamping for consistent quality.
- Brackets:Various brackets support internal systems and cabling, often produced through progressive die stamping for cost-effectiveness.
- Panels:Exterior and interior panels are formed from lightweight aluminum alloys, contributing to overall aircraft weight reduction.
Most installed capacity flows through Fasteners. Expansion is steepest in Structural Components.
Technology:
Technology selection is driven by the part's geometric complexity, required precision, and production volume, ranging from high-speed presses to specialized forming methods.
- Progressive Die Stamping:This high-volume, automated process integrates multiple operations into a single die, ideal for producing smaller, intricate parts like fasteners and electrical contacts for satellite constellations. In-die sensing technology is increasingly integrated for real-time quality assurance.
- Deep Draw Stamping:Essential for creating seamless, hollow, or cup-shaped components such as engine parts, specialized enclosures, and battery housings for urban air mobility platforms. Hudson Technologies specializes in this complex forming method.
- Transfer Die Stamping:This method moves a part through a series of dies, suitable for medium to high volumes of larger, more complex parts than progressive stamping.
- Fine Blanking:This precision stamping technique produces parts with smooth, square edges and tight tolerances, eliminating secondary finishing operations.
- Coining:A cold-forming process used to produce precise, high-definition features on a part, often for intricate details or surface hardness.
- Embossing:This technique creates raised or recessed designs on sheet metal, primarily for aesthetic or functional markings rather than structural integrity.
Process efficiency is a primary selection criterion for Progressive Die Stamping. Deep Draw Stamping is gaining share fastest for specialized applications.
Application:
Aerospace and defense applications dictate stringent material requirements, design specifications, and regulatory compliance for stamped components.
- Flight Control Systems:Components for these critical systems require extreme precision and material integrity, meeting stringent FAA and EASA certification for strength and fatigue resistance. These parts are integral to aircraft safety and operational reliability.
- Communication Equipment:Stamped enclosures and internal components are vital for satellite constellations and UAV communication systems, demanding lightweight materials and robust environmental protection. The rapid deployment of these platforms creates substantial demand.
- Weapon Systems:Precision-stamped parts contribute to the functionality and structural integrity of various defense armaments, often governed by ITAR regulations.
- Landing Gear:High-strength, fatigue-resistant components are necessary for landing gear assemblies, enduring significant stress during take-off and landing.
- Avionics:Stamped enclosures and connectors protect sensitive electronic systems within aircraft, requiring high precision and often specialized materials for shielding.
- Surveillance Devices:Components for optical and electronic surveillance equipment demand lightweight construction and precise dimensions for optimal performance.
Safety-critical components in Flight Control Systems require extensive validation. Emerging platforms drive demand for Communication Equipment.
End User:
End-user categories influence procurement patterns, volume requirements, and the necessity for integrated services, from component supply to full sub-assembly provision.
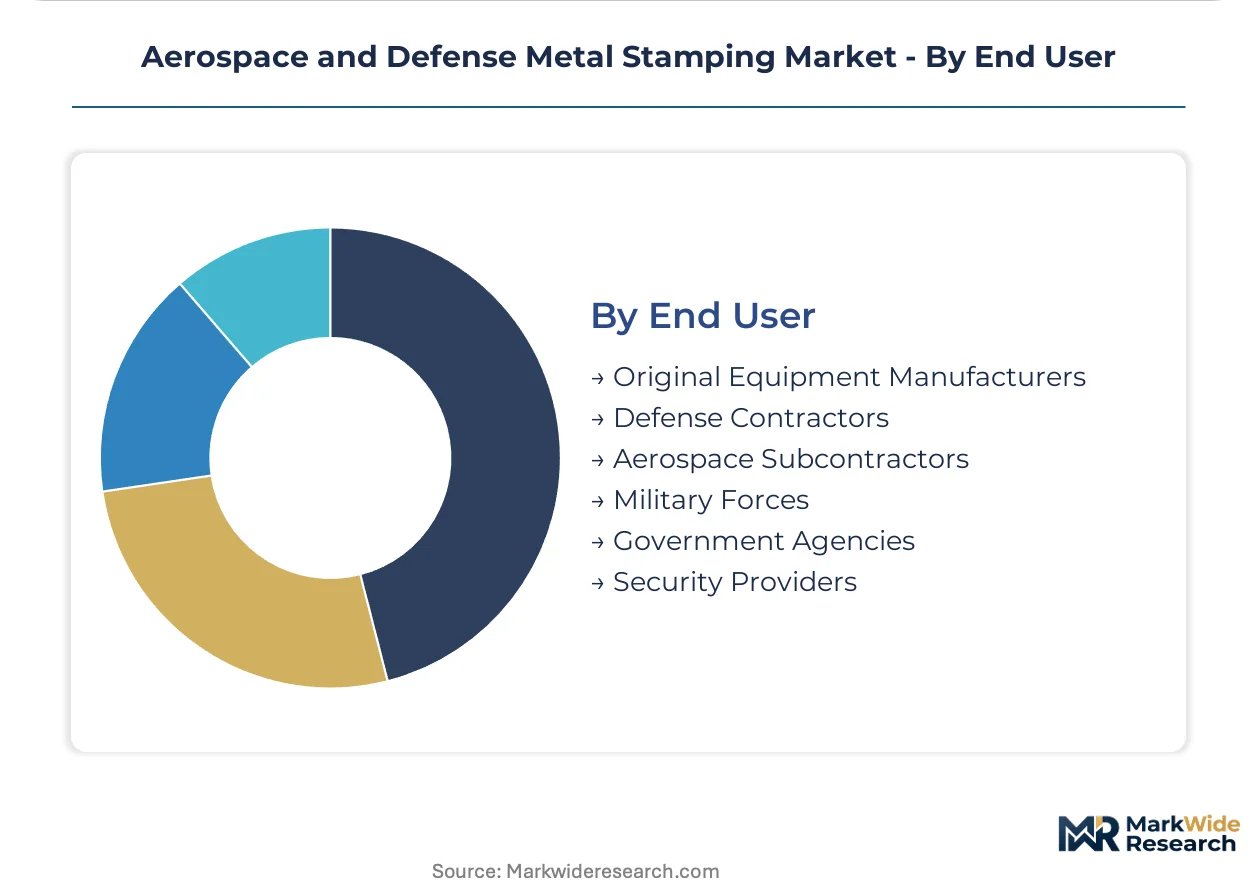
- Original Equipment Manufacturers:OEMs prefer strategic suppliers who can provide complete sub-assemblies and integrated, data-rich manufacturing solutions, moving beyond discrete component purchasing. This trend is visible in commercial airframe supply chains in the United States.
- Defense Contractors:These entities procure components for military aircraft, weapon systems, and other defense platforms, often prioritizing suppliers with ITAR compliance and cybersecurity protocols like CMMC. Government initiatives to re-shore critical defense manufacturing benefit domestic suppliers.
- Aerospace Subcontractors:These companies specialize in specific manufacturing processes, supplying components or sub-assemblies to larger OEMs and defense contractors.
- Military Forces:Direct procurement by military branches focuses on maintenance, repair, and overhaul (MRO) parts, alongside components for specialized defense projects.
- Government Agencies:Various government bodies, beyond direct military, procure stamped parts for research, development, and specialized aerospace projects.
- Security Providers:Components for security-related aerospace applications, such as surveillance drones or specialized transport, are sourced by these providers.
Long-term partnerships define engagement with Original Equipment Manufacturers. New procurement models are emerging with Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States leads in aerospace and defense metal stamping innovation, while France maintains a strong position in European airframe manufacturing. Both nations drive demand for high-precision components in their defense and commercial aviation sectors. Market trajectory is influenced by national defense strategies and commercial aerospace production cycles.
United States
The United States market benefits from robust demand for next-generation aircraft programs and expanded UAV deployment. Strict FAA regulations mandate material traceability for flight-critical parts, ensuring high standards. Manufacturing clusters in states like Kansas and Washington concentrate on complex structural components for major airframers.
France
France exhibits strong demand, driven by commercial airframe production and national defense platform requirements. EASA regulations govern part qualification, influencing supplier capabilities across the European supply chain. The Toulouse region, a core aerospace cluster, focuses on high-precision metal stamping for Airbus programs.
China
China's aerospace and defense metal stamping market expands with its rapidly growing domestic aviation industry and ambitious satellite constellation projects. Government policies from MIIT support local manufacturing and adherence to national GB standards. Industrial centers in Xi'an and Shanghai are developing advanced stamping expertise for civil and military applications.
Germany
Germany's market for aerospace and defense metal stamping emphasizes high-precision engineering and advanced material processing for engine and structural components. Adherence to EASA certification processes is paramount for suppliers. The Hamburg and Munich regions, with their strong industrial heritage, focus on sophisticated stamping for aircraft systems and defense applications.
United Kingdom
The United Kingdom sustains demand through its robust defense industrial base and specialized aerospace system development. UK Civil Aviation Authority standards ensure stringent safety and performance for flight-critical stamped parts. Aerospace clusters around Bristol and Derby contribute significantly to engine component manufacturing and advanced structural assemblies.
Aerospace and Defense Metal Stamping Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the aerospace and defense metal stamping market. The market exhibits a tiered structure, with a few large players offering integrated solutions alongside numerous smaller, specialized fabricators. Strategic archetypes include high-volume precision stampers, deep draw specialists, and complex structural component providers requiring advanced material expertise. Suppliers increasingly engage in strategic partnerships and portfolio diversification to meet evolving OEM demands for complete sub-assemblies.
Within the specialized stamping tier, Keats Manufacturing Company exemplifies high-volume, precision stamping for smaller avionics parts, critical for satellite constellations. Hudson Technologies occupies a position with expertise in deep draw stamping for specialized enclosures and housings used in communication equipment. American Industrial Company represents a provider leveraging extensive tooling capabilities for complex structural components, catering to demanding aerospace and defense airframe applications. These firms demonstrate the focused capabilities required to meet stringent industry standards and evolving customer needs for advanced, traceable components.
| Leading Market Players |
|---|
| American Industrial Company |
| Keats Manufacturing Company |
| Wiegel Tool Works Inc. |
| Hudson Technologies |
| Tempco Manufacturing Company, Inc. |
| D&H Industries Inc. |
| Klesk Metal Stamping Co. |
| Clow Stamping Company |
| ACRO Metal Stamping Co. |
| Others |
Cost & Logistics Intelligence
Skilled tool and die makers in established aerospace manufacturing clusters drive labor-cost differentials, directly influencing pricing tiers for specialized aerospace and defense metal stamping. This scarcity elevates costs for high-precision components.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume, standardized aerospace components, while contract-based long-term offtake defines pricing for complex parts. Pricing differentiation stems from stringent FAA and EASA certification levels and specific material expertise in alloys like Inconel. Raw material volatility for titanium and cobalt creates cost compression, particularly for suppliers of structural components. OEMs exhibit lower price sensitivity for integrated, value-added sub-assemblies, prioritizing traceability and certified solutions.
Supply Chain Analysis
Logistics and freight costs for high-strength alloys significantly impact the overall cost structure of aerospace and defense metal stamping components. Supply concentrates in established aerospace manufacturing clusters within the United States, France, and China, drawing heavily from critical inputs like titanium, Inconel, and cobalt. Raw material volatility for these specialized metals presents a significant supply chain risk due to geopolitical sourcing concentration. Distribution runs through strategic suppliers providing complete sub-assemblies directly to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace and defense metal stamping market acts as a regulatory compounder, with stringent FAA and EASA certifications driving demand for highly specialized and traceable components. This regulatory oversight ensures quality and performance for flight-critical applications.
For Market Incumbents: Anchor existing market share by investing heavily in advanced material processing for titanium and nickel-based superalloys. Deepen capabilities in digital twin integration to offer lifecycle management services, countering the threat of new entrants leveraging additive manufacturing for tooling. Prioritize cybersecurity compliance under frameworks like CMMC to protect digital design data, maintaining preferred vendor status with defense contractors. Consolidate smaller specialists to expand geographic reach and technology portfolios.
For New Entrants and Emerging Players: Enter via specialized niches like the Urban Air Mobility (UAM) sector, developing novel, lightweight structural components and battery enclosures for eVTOL aircraft. Target the rapidly expanding demand for precision stamped components in next-generation satellite constellations. A strong go-to-market angle involves leveraging additive manufacturing for tooling to provide rapid prototyping and faster response to new component designs. Focus on areas requiring less legacy certification.
For Investors and Strategic Acquirers: Original Equipment Manufacturers are the most active acquirers in this space, seeking to consolidate supplier bases and internalize advanced capabilities. This market offers long-term viability, as metal stamping remains essential for next-generation aerospace and defense platforms. Acquisition targets should include specialized stampers with proven expertise in advanced materials processing or deep draw capabilities. The signal to watch is increased investment by smaller firms in digital twin integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US/Europe | Addresses re-shoring policies and expanded UAV demand. |
| Digital Twin Integration Services | Offers value-add lifecycle management for flight-critical components. |
| Advanced Material R&D Collaboration | Enables processing of new titanium and nickel-based superalloys. |
| Cybersecurity Protocol Implementation | Ensures compliance with CMMC for defense-related digital design data. |
| Investment in Additive Manufacturing for Tooling | Reduces lead times for complex dies, accelerating new component designs. |
Research Approach
Bottom-up end-use application modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with OEM procurement leads, stamping specialists, regulatory compliance officers, and defense contractors provided qualitative insights. These were validated against secondary data from FAA and EASA reports, US ITAR guidelines, and company SEC filings. This approach ensures robust data triangulation.
Historical trendline analysis established foundational market trajectories across the analysis window. The quantitative framework modeled market dimensions including product type, manufacturing technology, end-use application, customer segment, and material type. Compound annual growth rates were derived from historical data, market dynamics, and expert projections. Key industry-specific forecast inputs included satellite constellation deployment rates and UAV program funding.
Inputs from public company filings and regulatory reports were available through the study window; gaps in proprietary production data introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical stability and technological advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Russia Space Electronics Market