
 Aircraft Engine Hoists Market | 2026-2036
Aircraft Engine Hoists Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Engine Hoists Market Analytics
Buyer concentration among MRO service providers is restructuring procurement patterns across the aircraft engine hoists landscape. Konecranes leverages its installed base in heavy aviation maintenance hangars to sustain recurring service contracts. Demag Cranes anchors European defense aviation programs with specialized high-capacity lifting systems. Columbus McKinnon competes on aftermarket parts availability, extending its footprint among independent repair stations.
Aircraft engine hoists are purpose-built material handling systems designed to lift, transport, and position turbine powerplants during installation, removal, and overhaul operations, typically rated for loads exceeding ten tons with precision boom articulation and load moment indicators. Hydraulic hoists dominate the product mix due to their controlled lifting velocity and compatibility with confined hangar spaces, while portable configurations are gaining traction among regional MRO facilities seeking flexible floor layouts. Military aviation applications command premium pricing because of corrosion-resistant finishes and electromagnetic interference shielding requirements, whereas commercial aviation represents the volume anchor driven by narrowbody fleet utilization cycles.
The FAA enforces crane operator certification and periodic load testing protocols that directly shape equipment specification sheets for US aviation maintenance facilities. EASA's ground handling equipment directives in Europe mandate redundant braking systems and documented traceability for critical lifting components. Stakeholders must monitor evolving airworthiness authority mandates for automated load verification, as regulatory divergence between FAA and EASA technical standards threatens to fragment supplier certification costs and complicate cross-border equipment deployment strategies.
Market Dynamics
Buyer consolidation among MRO service providers is compressing procurement timelines and favoring suppliers with integrated service capabilities. The FAA's enhanced crane safety standards are forcing equipment refresh cycles at US aviation maintenance facilities.
Growth Catalysts
- Aging Commercial Fleets:Narrowbody aircraft entering their third overhaul cycle drive scheduled engine removals. Regional MRO facilities expand capacity to capture this maintenance volume.
- FAA Load Monitoring Mandates:Updated aviation ground support equipment standards require retrofits of existing hoists with enhanced load moment indicators. Compliance deadlines accelerate replacement demand.
- Hydraulic Precision Controls:Controlled lifting velocity systems enable safer turbine positioning in confined hangar geometries. Adoption concentrates at legacy maintenance depots with space-constrained floor plans.
Market Restraints
- Specialized Steel Input Volatility:High-grade alloy demand from concurrent aerospace and energy sectors strains hoist structural component supply. Long-lead forgings extend production schedules.
- European Supplier Concentration:Defense-aviation certified lifting systems rely on a limited base of continental European foundries. Geopolitical friction threatens component availability.
- Electromagnetic Interference Shielding Costs:Military specification finishes add 40-60% material cost premiums. Commercial buyers rarely absorb this technical overhead.
Strategic Opportunities
- India MRO Infrastructure Buildout:The country's PLI scheme for aviation maintenance attracts foreign direct investment. Greenfield facilities require complete ground support equipment suites.
- Portable Configuration Demand:Regional repair stations seek reconfigurable floor layouts. Modular hoist designs penetrate independent operators previously locked into fixed gantry systems.
- EASA Automated Load Verification Trajectory:Anticipated ground handling equipment directives favor early movers in sensor integration. Suppliers pre-certifying to draft standards capture specification advantages.
Industry Challenges
- Certified Crane Operator Scarcity:FAA-mandated qualification programs face enrollment bottlenecks. Maintenance facilities delay equipment deployment pending licensed personnel availability.
- Cross-Border Certification Fragmentation:Divergent FAA and EASA technical standards complicate equipment redeployment. Suppliers absorb redundant testing costs for multi-jurisdiction fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Engine Hoists Market |
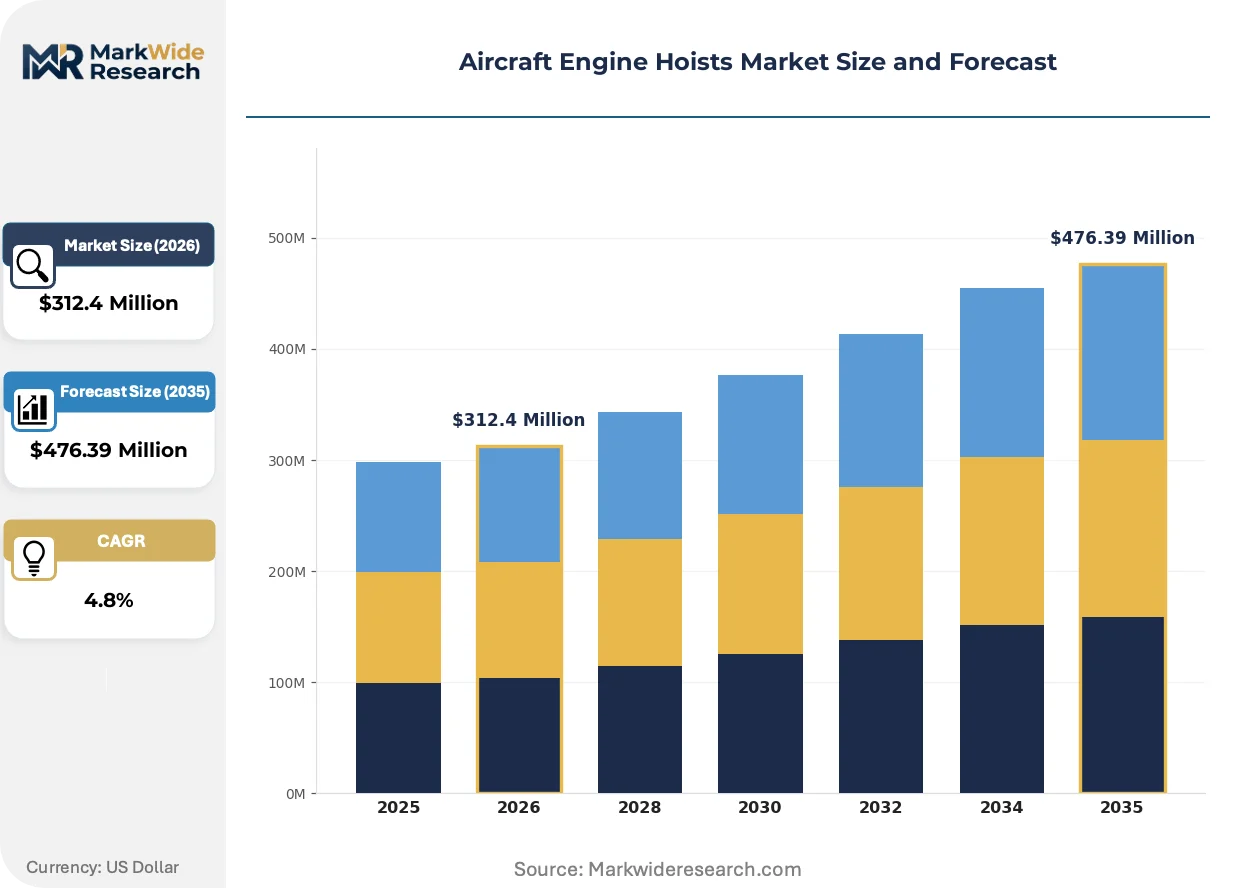
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable Hoists, Fixed Hoists, Hydraulic Hoists, Pneumatic Hoists Application: Military Aviation, Commercial Aviation, General Aviation, Helicopter Maintenance Capacity: 0-1 Ton, 1-5 Tons, 5-10 Tons, Above 10 Tons End User: Aviation Maintenance Facilities, Aircraft Manufacturers, MRO Service Providers, Airlines |
| Companies Covered | TC/American Crane Company, Spanco, Gardner Inc., Wallace Products, Airpes, Demag Cranes, Street Crane Company, Konecranes, Columbus McKinnon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Engine Hoists Market Evolving Landscape
Digital load monitoring and predictive maintenance architectures are displacing reactive service models. Equipment suppliers now compete on uptime guarantees rather than unit specifications.
Wireless sensor networks embedded in hoist structures transmit real-time load stress data to centralized maintenance dashboards. Regional MRO chains deploy these systems to consolidate fleet oversight across distributed hangars. The technology is decentralizing service expertise from centralized technical centers to individual facility managers.
EASA's evolving ground handling equipment directives mandate redundant braking systems and component-level traceability documentation. European defense aviation programs already enforce these protocols, creating specification precedents. Commercial operators in Germany and France pre-emptively adopt these standards to streamline future fleet interoperability.
Power-by-the-hour contracts now dominate narrowbody engine maintenance procurement. Independent repair stations unbundle hoist ownership from MRO service agreements, preferring leased equipment with embedded maintenance. This pattern concentrates in the United States, where airline outsourcing of heavy maintenance accelerates asset-light operating models.
Aircraft Engine Hoists Market Segmentation
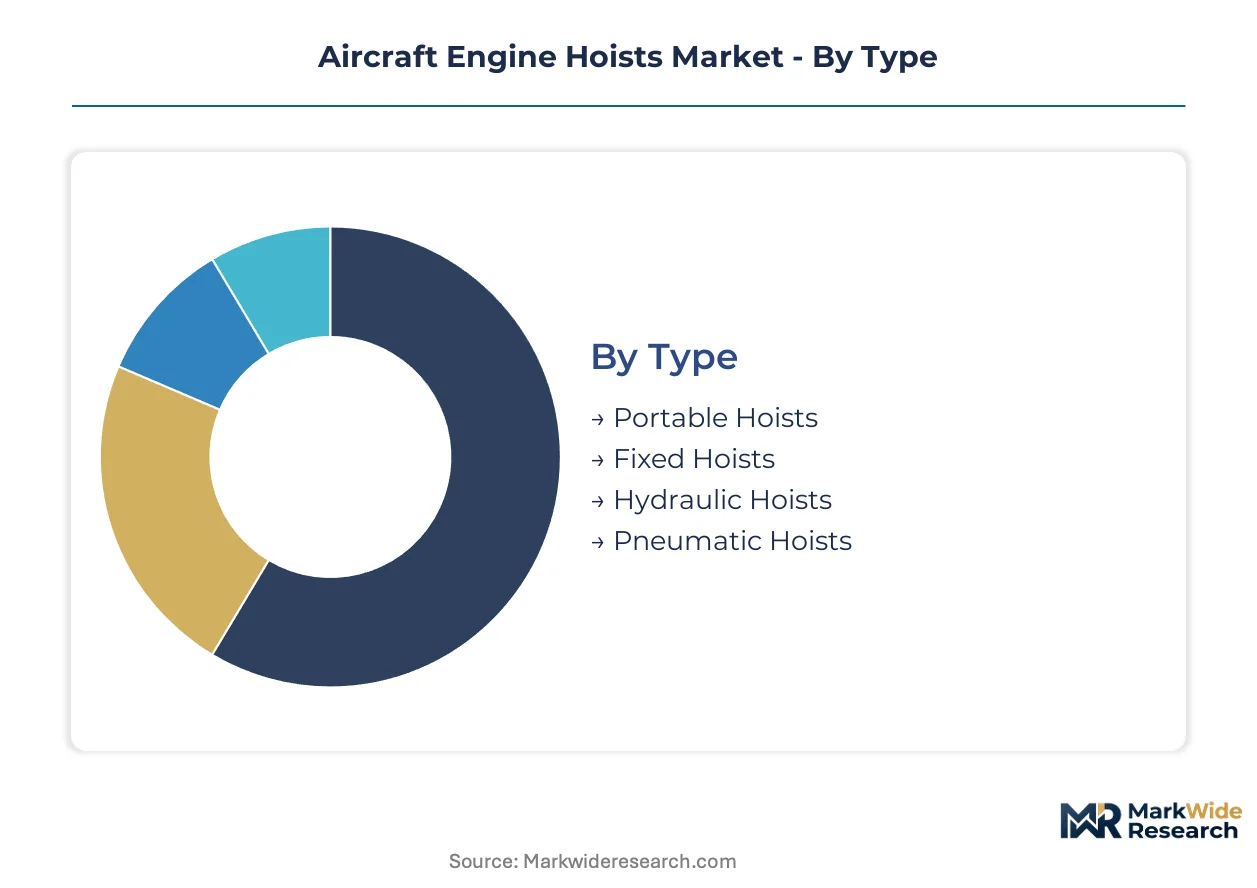
Aircraft engine hoists serve distinct operational profiles across aviation maintenance ecosystems. Equipment specifications diverge sharply between defense programs with electromagnetic shielding requirements and commercial narrowbody overhaul cycles driving volume procurement.
Type:
Supply concentrates among specialized manufacturers with certified foundry relationships for high-grade alloy structural components.
- Hydraulic Hoists:Controlled lifting velocity systems enable precise turbine positioning within confined hangar geometries. Demand clusters at legacy maintenance depots in the United States with space-constrained floor plans and aging infrastructure requiring equipment refresh cycles.
- Portable Hoists:Modular designs with reconfigurable mounting systems allow regional repair stations to optimize floor layouts without fixed gantry investments. Adoption accelerates among independent MRO operators in India seeking flexible capacity deployment.
- Fixed Hoists:Permanent overhead installations anchor high-volume engine removal schedules at major airline hubs.
- Pneumatic Hoists:Compressed-air drive systems serve specialized applications requiring spark-resistant operation in hazardous environments.
Today's leader: Hydraulic Hoists. Tomorrow's challenger: Portable Hoists.
Application:
Cost tier stratification separates military specification premiums from commercial aviation's volume-driven procurement economics.
- Commercial Aviation:Narrowbody fleet utilization cycles generate scheduled engine removals at scale. Procurement concentrates among MRO service providers expanding capacity to capture third-overhaul-cycle maintenance volume from aging aircraft.
- Military Aviation:Corrosion-resistant finishes and electromagnetic interference shielding add substantial material cost premiums. Defense aviation programs in Europe and the United States sustain premium pricing through specialized certification requirements.
- General Aviation:Smaller turbine and piston engine categories drive demand for lower-capacity lifting systems.
- Helicopter Maintenance:Compact powerplant geometries require specialized boom articulation and reduced vertical clearance profiles.
Commercial Aviation commands current procurement volumes. Military Aviation maintains pricing power through technical specification barriers.
Capacity:
Volume distribution skews toward upper load ratings as widebody and next-generation turbofan engines increase removal mass requirements.
- Above 10 Tons:Heavy-lift configurations handle modern high-bypass turbofan powerplants from widebody aircraft. Demand concentrates at major airline maintenance hubs and defense depots in the United States managing engine swaps for twin-aisle fleets.
- 5-10 Tons:Intermediate ratings serve narrowbody engine categories with precision load moment indicators. Regional MRO facilities in Europe adopt these systems for mixed fleet maintenance contracts.
- 1-5 Tons:Mid-range capacity supports regional jet and business aviation engine categories.
- 0-1 Ton:Light-duty systems address auxiliary power units and small turbine applications.
Above 10 Tons anchors current infrastructure investment. 5-10 Tons segments expand most quickly with narrowbody fleet renewal cycles.
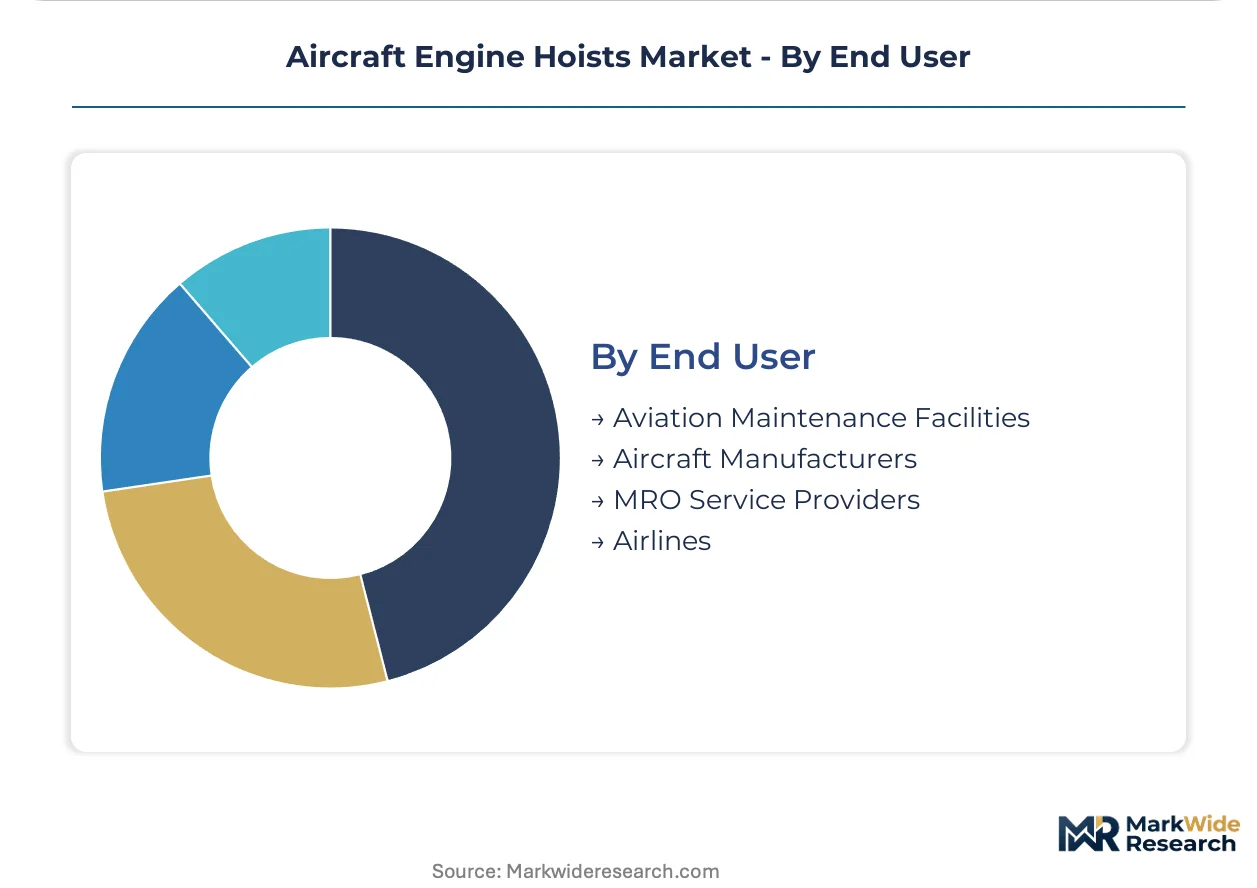
End User:
Customer type fragmentation creates divergent procurement patterns between asset-heavy operators and outsourced maintenance providers.
- MRO Service Providers:Independent repair stations drive demand for leased equipment with embedded maintenance under power-by-the-hour contracts. Concentration intensifies in the United States where airline outsourcing of heavy maintenance accelerates asset-light operating models.
- Aviation Maintenance Facilities:Integrated airline maintenance divisions prioritize uptime guarantees and predictive service architectures. FAA-mandated crane operator certification requirements shape equipment deployment timelines.
- Aircraft Manufacturers:Original equipment production lines require precision alignment systems for initial engine installation.
- Airlines:Direct procurement concentrates among carriers maintaining captive maintenance capabilities.
MRO Service Providers dominate current procurement restructuring. Aviation Maintenance Facilities retain influence through integrated service requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes outpace German defense aviation spending, while India's PLI scheme for aviation maintenance attracts foreign direct investment into greenfield MRO facilities. Regulatory divergence between FAA and EASA technical standards complicates cross-border equipment deployment strategies.
United States
FAA-mandated crane operator certification and enhanced load monitoring standards accelerate equipment refresh cycles at legacy maintenance depots. The FAA's updated aviation ground support equipment regulations require retrofits with load moment indicators. Major airline hubs in Atlanta, Dallas-Fort Worth, and Chicago sustain concentrated procurement volumes for heavy-lift configurations.
Germany
EASA ground handling equipment directives mandate redundant braking systems and component-level traceability documentation for defense aviation programs. The country's national aviation regulator enforces electromagnetic interference shielding requirements for military specification finishes. Industrial clusters in Bavaria and Baden-Württemberg anchor European foundry capacity for high-grade alloy structural components.
France
Commercial operators in Île-de-France and Provence-Alpes-Côte d'Azur pre-emptively adopt EASA defense aviation protocols to streamline future fleet interoperability. The national civil aviation authority anticipates automated load verification mandates in draft ground handling equipment standards. Paris-Le Bourget and Toulouse-Blagnac maintenance corridors concentrate narrowbody engine removal schedules.
India
Regional MRO facilities in Maharashtra and Karnataka seek portable hoist configurations for flexible floor layouts under the PLI scheme for aviation maintenance. The country's central aviation regulator aligns with draft EASA standards for sensor-integrated load verification systems. Greenfield facilities in Delhi-NCR and Hyderabad require complete ground support equipment suites.
United Kingdom
Independent repair stations in the Midlands and Southeast England drive leased equipment demand under power-by-the-hour contracts. The national aviation authority maintains crane operator certification reciprocity with FAA protocols. London Stansted and Manchester maintenance clusters expand capacity to capture third-overhaul-cycle volume from aging narrowbody fleets.
Aircraft Engine Hoists Market Competitive Landscape
United States producers anchor the aftermarket parts and service tier; European specialists hold defense-aviation certified lifting systems. The vendor base concentrates among heavy aviation maintenance hangar incumbents and regional modular fabricators. Three archetypes dominate: integrated service providers with recurring maintenance contracts, high-capacity system specialists for defense programs, and portable configuration innovators for independent operators. Competitive moves center on predictive maintenance architecture deployment and India MRO infrastructure partnerships.
Within the integrated service tier, Konecranes and Columbus McKinnon exemplify divergent geographic anchoring strategies. Konecranes occupies a position among Nordic-origin heavy-lift specialists with established aviation maintenance hangar footprints. Columbus McKinnon represents the North American aftermarket parts availability archetype, serving independent repair stations through distribution density. Demag Cranes sits within the European defense-aviation certification cluster, where specialized high-capacity lifting systems command premium positioning.
| Leading Market Players |
|---|
| TC/American Crane Company |
| Spanco |
| Gardner Inc. |
| Wallace Products |
| Airpes |
| Demag Cranes |
| Street Crane Company |
| Konecranes |
| Columbus McKinnon |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FAA-mandated load monitoring systems and standard commercial configurations creates parallel pricing tracks that reshape supplier economics and procurement patterns across aviation maintenance ecosystems. Premium-tier suppliers capture sustained margin advantages through embedded sensor architectures and predictive service contracts, while commodity-positioned fabricators compete on upfront equipment cost for independent repair stations with limited compliance exposure.
Pricing Analysis
Capacity additions in India are reshaping price floors for portable hoist configurations as greenfield MRO facilities negotiate volume procurement agreements. The market operates through a contract-based long-term offtake structure with power-by-the-hour bundling dominating narrowbody engine maintenance procurement. Price differentiation rests on certification grade — FAA-enhanced load moment indicators command substantial premiums over baseline hydraulic systems — and after-sales service integration. Cost compression in standard commercial tiers is intensifying because regional MRO chains consolidate fleet purchasing power. Independent repair stations exhibit highest price sensitivity, while defense aviation programs absorb electromagnetic interference shielding premiums without volume negotiation.
Supply Chain Analysis
Aviation-grade certification requirements gate foundry access for structural alloy components, concentrating qualified supplier relationships among a limited tier of continental European and North American metallurgical specialists. Geographic supply concentration centers on Germany, the United States, and India for finished hoist assemblies, with high-grade alloy forgings drawing from specialized Bavarian and Baden-Württemberg industrial clusters. Raw material dependencies include nickel-based superalloys, high-strength steel forgings, and precision hydraulic actuators. Single-source vulnerability threatens component availability where defense-aviation certified foundries face concurrent aerospace and energy sector demand. Distribution runs through authorized service networks with embedded maintenance rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as aging narrowbody fleets entering third overhaul cycles shift procurement specifications toward predictive maintenance architectures and uptime guarantees rather than unit cost optimization.
For Market Incumbents: Anticipate margin compression from modular portable configurations penetrating regional MRO facilities previously locked into fixed gantry systems. Consolidate service contract density through predictive maintenance architecture deployment across distributed hangar networks. Deepen backward integration into high-grade alloy forging relationships to secure long-lead structural component supply against defense aviation program competition. For New Entrants and Emerging Players: EASA's evolving automated load verification trajectory in Europe opens a window for sensor-integrated hoist designs that capture specification advantages ahead of mandate finalization. Target India's PLI scheme for aviation maintenance with portable configuration offerings that address greenfield facility demand for flexible floor layouts. Pursue lease-based go-to-market models with embedded maintenance to align with independent repair station preference for asset-light operating structures. For Investors and Strategic Acquirers: Consolidation pressure builds where FAA-mandated crane operator certification scarcity delays equipment deployment and compresses facility utilization rates. Long-term viability favors suppliers with integrated service capabilities and certified foundry access rather than pure equipment fabricators. Monitor India's central aviation regulator alignment with draft EASA standards as an inflection indicator for portable configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Architecture Deployment | Wireless sensor networks transmit real-time load stress data to centralized maintenance dashboards across distributed hangars. |
| India MRO Infrastructure Partnership | Greenfield facilities in Delhi-NCR and Hyderabad require complete ground support equipment suites under PLI scheme incentives. |
| Automated Load Verification Pre-Certification | Early movers in sensor integration capture specification advantages ahead of anticipated EASA ground handling equipment directives. |
| Backward Integration into Alloy Forging | Captive supply of high-grade structural components insulates against long-lead production schedule extensions from concurrent sector demand. |
| Power-by-the-Hour Contract Structuring | Independent repair stations prefer leased equipment with embedded maintenance under asset-light operating models. |
Research Methodology
Multiple input streams — primary interviews with MRO operations directors, aviation maintenance facility managers, and aftermarket service heads; secondary validation through FAA regulatory filings, EASA ground handling equipment directives, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates. Stakeholder consultations captured procurement pattern shifts, certification timeline pressures, and fleet utilization cycle dynamics across United States, European, and Indian aviation maintenance corridors.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through analytical framework modeling of hoist type, application tier, capacity rating, and end-user archetype dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating narrowbody fleet age distribution, regulatory compliance deadline clustering, and regional MRO capacity expansion schedules. Industry-specific forecast inputs included third-overhaul-cycle engine removal schedules and defense aviation program electromagnetic shielding specification evolution.
Revisions become necessary when FAA-EASA regulatory divergence accelerates, certified crane operator scarcity intensifies equipment deployment delays, or geopolitical friction disrupts continental European foundry component availability. Forecasts reflect documented assumptions regarding fleet utilization cycles and maintenance outsourcing trajectories. A model refresh is warranted upon material change in EASA automated load verification mandate timing or India PLI scheme aviation maintenance incentive structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market