
 Commercial Aircraft Fadec Market | 2026-2036
Commercial Aircraft Fadec Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Fadec Market Outlook
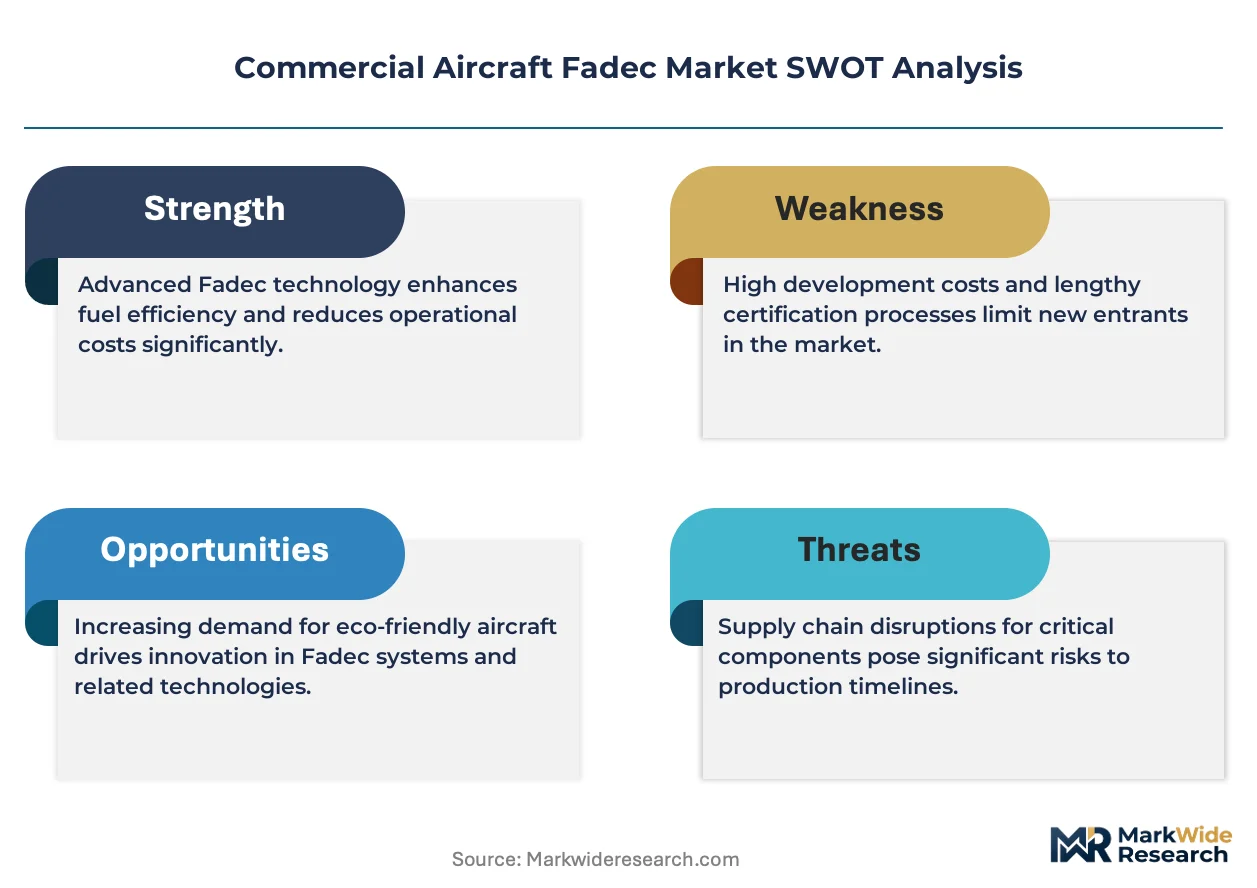
DO-178C DAL-A certification is collapsing the supplier base to vendors with proven safety-critical software track records. Collins Aerospace leverages decades of military-to-commercial technology transfer to sustain its installed base dominance. Honeywell International Inc. competes through integrated propulsion and flight control architectures. Safran anchors European supply chains with deep ties to CFM International engine programs.
A full authority digital engine control (FADEC) is an embedded electronic system that manages aircraft engine performance through real-time sensor fusion, closed-loop fuel metering, and variable stator vane scheduling to optimize thrust output while preventing surge, stall, and overtemperature events. Digital Fadec systems command the largest value share given their computational density and software content, while hybrid systems are gaining traction as regional jets and turboprops modernize legacy hydromechanical controls. Airlines drive the bulk of aftermarket demand as engine shop visits trigger mandatory FADEC software updates and hardware obsolescence replacements.
FAA certification under 14 CFR Part 33 and EASA CS-E frame hardware qualification and software integrity standards that OEMs must satisfy before entry into service. EPA emission standards under ICAO Annex 16 Volume II are forcing tighter fuel burn optimization algorithms that expand FADEC computational requirements. Stakeholders must weigh the capital intensity of dual-certification strategies against the volume concentration of single-aisle platforms.
Market Dynamics
DO-178C DAL-A certification requirements are compressing the supplier base to vendors with proven safety-critical software track records, fundamentally restructuring competitive entry barriers around demonstrated airworthiness validation rather than hardware capability alone.
Growth Catalysts
- ICAO Annex 16 Volume II emission mandates:Tighter EPA fuel burn standards force computational upgrades to FADEC fuel metering algorithms, expanding software content per engine.
- Narrow-body delivery concentration:Low-cost carrier fleet expansion in China and India drives volume demand for single-aisle FADEC configurations.
- Engine shop visit cycles:Mandatory software updates and hardware obsolescence replacements during scheduled maintenance create predictable aftermarket revenue streams.
Market Restraints
- Dual-certification capital intensity:FAA 14 CFR Part 33 and EASA CS-E parallel validation requires redundant testing infrastructure, elevating fixed costs for new entrants.
- Silicon supply concentration:Aerospace-grade FPGA and radiation-hardened processor sourcing depends on a limited qualified vendor pool concentrated in the United States.
- Hydromechanical legacy persistence:Regional jet and turboprop operators delay full digital retrofits due to airframe certification coupling constraints.
Strategic Opportunities
- India MRO infrastructure buildout:Emerging engine overhaul capabilities in Hyderabad and Bengaluru create localized FADEC service demand outside traditional North American and European hubs.
- Open systems architectures:ARINC 653-compliant partitioned operating systems enable third-party algorithm integration, loosening OEM software lock-in.
- Sustainable aviation fuel compatibility:FADEC thermal management recalibration for SAF blends requires updated sensor fusion protocols across existing installed bases.
Industry Challenges
- DO-178C tool qualification gaps:Automated code generation and model-based design validation lack standardized certification pathways, extending development timelines.
- Obsolescence management complexity:Long engine program lifecycles force continuous hardware refresh planning against discontinued semiconductor packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Fadec Market |
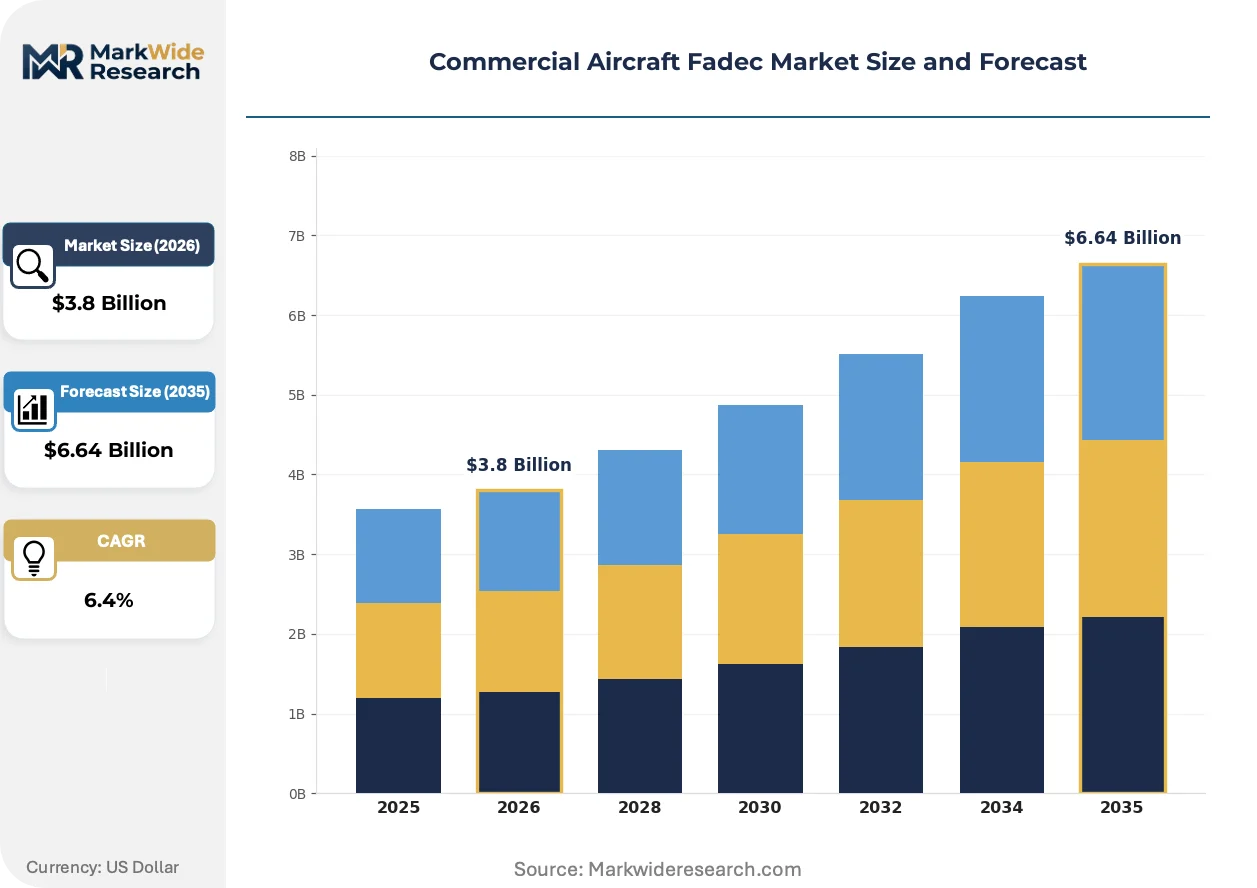
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly-by-Wire, Electronic Control System, Engine Control Unit, Autopilot System Application: Commercial Aviation, Cargo Transport, Business Jets, Regional Airlines End User: Airlines, Aircraft Manufacturers, Maintenance Providers, Flight Training Organizations Technology: Digital Fadec, Analog Fadec, Hybrid Systems, Advanced Algorithms |
| Companies Covered | Collins Aerospace (Rockwell Collins, Inc.), Thales Group, Honeywell International Inc., Woodward, Inc., Moog Inc., Safran, Triumph Group Inc., Rolls-Royce Holdings plc, BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Fadec Market Strategic Shifts
Embedded computing architectures are splitting between high-performance multi-core clusters for wide-body engines and constrained power envelopes for regional applications, reshaping R&D allocation across the supplier tier.
Model-based development environments with automatic code generation are bifurcating supplier capabilities between vendors with qualified toolchains and those dependent on manual verification. Tier-one engine OEMs now mandate ARP 4754A-compliant process evidence from FADEC integrators. This technical segmentation is compressing subcontractor margins while elevating system-level vendor pricing power.
EASA certification memoranda on artificial intelligence in safety-critical systems are forcing explicit algorithm interpretability requirements into FADEC fuel scheduling logic. European engine programs face additional validation burden for neural network components. Wide-body platform suppliers are responding with hybrid architectures that isolate deterministic control loops from adaptive optimization modules.
Power-by-the-hour maintenance contracts are unbundling FADEC software update responsibility from hardware warranty coverage. Airlines now negotiate separate service level agreements for algorithm revision deployment. This contractual fragmentation is most visible among Middle Eastern and Southeast Asian carriers with young, digitally-native fleet profiles.
Commercial Aircraft Fadec Market Segmentation
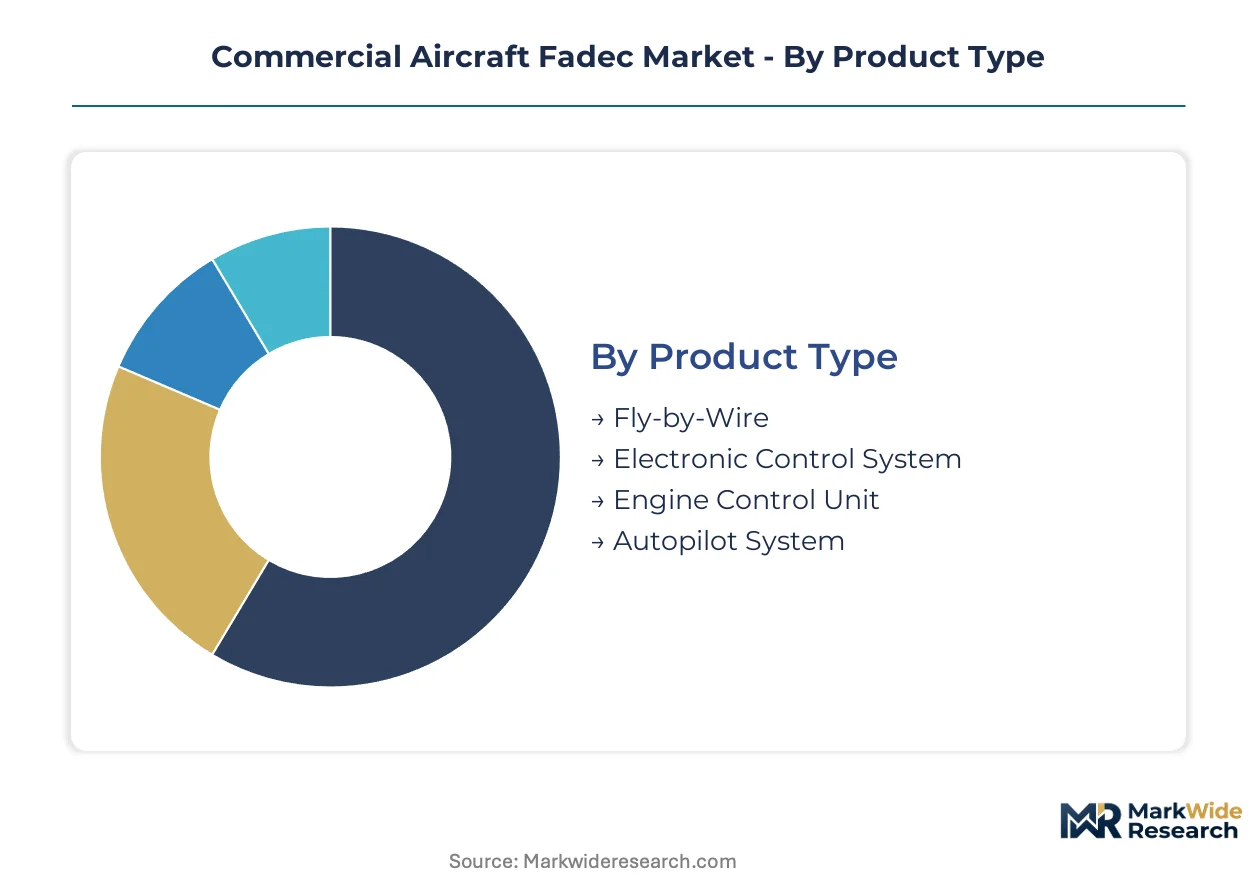
FADEC procurement patterns diverge sharply across product architectures and operational environments. Certification burdens and hardware refresh cycles reshape competitive positioning differently within each segment cluster.
Product Type:
Electronic Control System faces the most acute substitution pressure from integrated fly-by-wire architectures that absorb engine management into unified flight control computers.
- Fly-by-Wire:Integrated flight and propulsion control architectures consolidate sensor fusion across flight surfaces and engine parameters. Boeing 787 and Airbus A350 programs in the United States and France drive specification authority toward airframe OEMs rather than engine manufacturers.
- Electronic Control System:Modular engine-mounted units process thermocouple, pressure, and position signals through qualified FPGA platforms. Shop visit demand from Lufthansa Technik and ST Engineering concentrates aftermarket revenue in Germany and Singapore.
- Engine Control Unit:Compact single-board computers for turboprop and helicopter applications.
- Autopilot System:Flight deck integration modules with limited standalone FADEC functionality.
Electronic Control System retains volume leadership; Fly-by-Wire holds the steepest expansion curve.
Application:
Cost tier stratification separates wide-body platform investments from narrow-body fleet economics.
- Commercial Aviation:Scheduled passenger operations on single-aisle and twin-aisle aircraft command the dominant hardware procurement volume. IndiGo and Southwest Airlines fleet expansion in India and the United States sustains line-fit demand for CFM LEAP and Pratt & Whitney geared turbofan configurations.
- Cargo Transport:Dedicated freighter conversions and factory-built cargo aircraft require FADEC recalibration for extended-range operations and reduced-thrust climb profiles. Amazon Air and FedEx operations in Kentucky and Leipzig drive supplemental type certificate activity.
- Business Jets:Gulfstream and Dassault programs in Georgia and Bordeaux specify compact redundant architectures.
- Regional Airlines:ATR and Embraer turboprop fleets in Brazil and Italy retain hybrid hydromechanical systems.
Commercial Aviation absorbs the dominant procurement share; Cargo Transport gains share fastest on conversion demand.
End User:
Customer type determines whether procurement emphasizes initial acquisition cost or lifetime service economics.
- Airlines:Power-by-the-hour contracts with Rolls-Royce and GE Aviation shift FADEC software maintenance liability to engine OEMs. Emirates and Singapore Airlines negotiate separate algorithm update service level agreements distinct from hardware warranties.
- Aircraft Manufacturers:Boeing, Airbus, and COMAC in the United States, France, and China specify integrated system architectures during type certification.
- Maintenance Providers:Lufthansa Technik and HAECO in Germany and Hong Kong perform mandatory software updates during engine shop visits.
- Flight Training Organizations:CAE and L3Harris in Canada and the United Kingdom utilize desktop FADEC simulation for pilot type rating.
Airlines dominate installed base ownership; Maintenance Providers climb fastest on MRO regionalization.
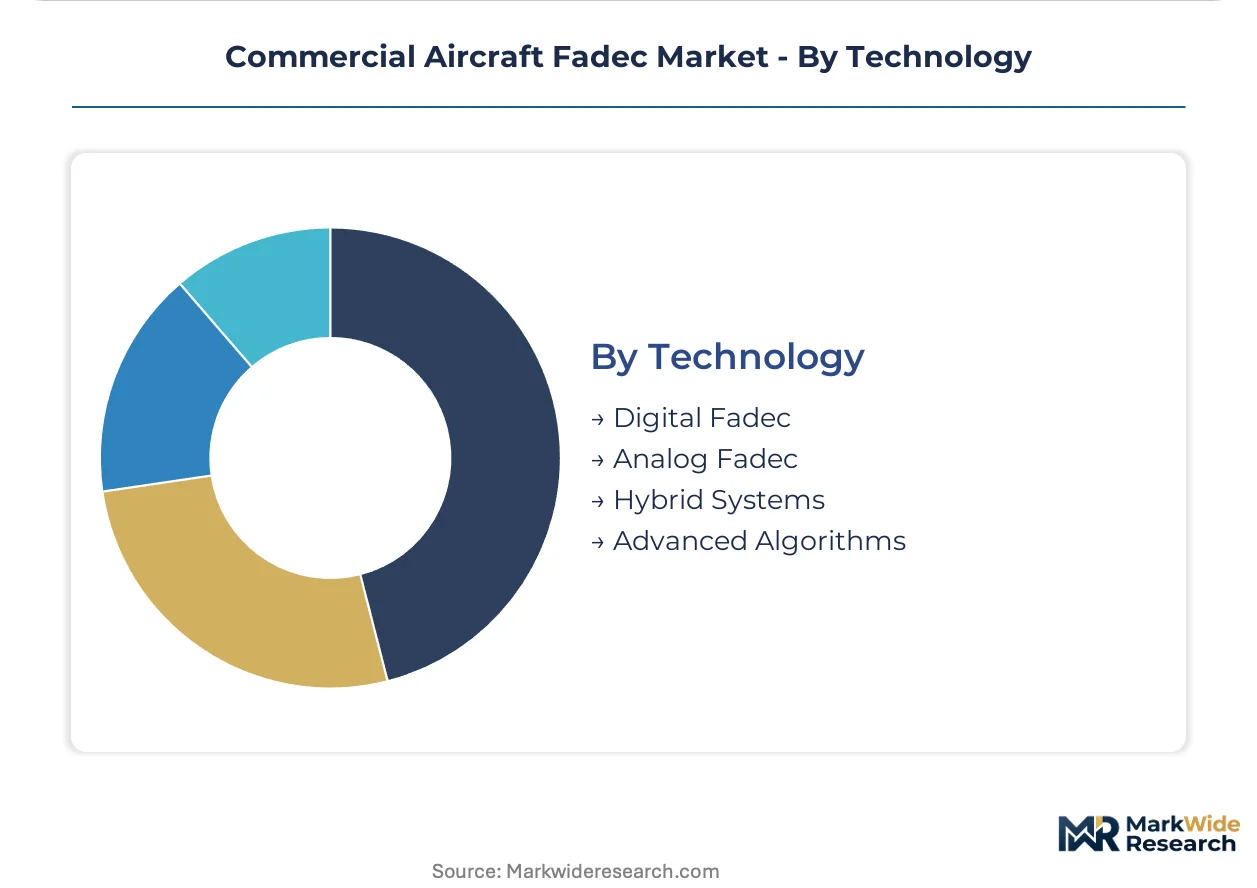
Technology:
Maturity gradients separate legacy analog preservation from digital upgrade pathways.
- Digital Fadec:Multi-core processor clusters execute fuel metering algorithms with DO-178C DAL-A software integrity. FAA 14 CFR Part 33 and EASA CS-E certification mandates in the United States and Germany compel computational upgrades for emission compliance.
- Hybrid Systems:Regional jet operators in Canada and Italy defer full digital retrofits due to airframe certification coupling constraints.
- Analog Fadec:Legacy hydromechanical backups persist in aging freighter conversions.
- Advanced Algorithms:EASA artificial intelligence memoranda impose interpretability requirements on adaptive fuel scheduling.
Digital Fadec commands the dominant value share; Advanced Algorithms face the steepest regulatory validation burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States FADEC exports flow predominantly to final assembly lines in France and China, while German engineering centers supply validation services back to American engine programs. This three-way trade corridor concentrates procurement authority in Seattle, Toulouse, and Shanghai.
United States
Boeing 737 MAX and 787 production in Washington State drives line-fit demand for Collins Aerospace and Honeywell systems. FAA 14 CFR Part 33 certification mandates enforce DO-178C DAL-A software standards across all new engine programs. Dallas-Fort Worth hosts American Airlines' technical operations center where power-by-the-hour contracts renegotiate FADEC maintenance liability.
Germany
Lufthansa Technik in Hamburg performs mandatory software updates during engine shop visits for CFM LEAP and Pratt & Whitney geared turbofan fleets. EASA CS-E regulations frame hardware qualification standards that German MRO providers must satisfy before return-to-service. Munich anchors MTU Aero Engines' engineering center where FADEC integration testing occurs for European engine programs.
China
COMAC C919 final assembly in Shanghai generates domestic FADEC procurement demand for LEAP-1C engine configurations. CAAC certification alignment with FAA and EASA standards requires parallel validation testing at Chinese aerospace institutes. Xi'an hosts AVIC's engine subsidiary where hybrid FADEC development proceeds for regional turboprop applications.
France
Airbus A320neo and A350 production in Toulouse specifies integrated fly-by-wire architectures that consolidate engine management into unified flight control computers. EASA artificial intelligence memoranda impose interpretability requirements on adaptive fuel scheduling algorithms developed in Paris engineering centers. Safran's Paris-Saclay facility anchors European supply chains with deep ties to CFM International engine programs.
India
IndiGo's fleet expansion drives volume demand for single-aisle FADEC configurations on CFM LEAP engines. DGCA certification convergence with FAA standards enables Indian carriers to accept factory-delivered systems without additional national validation. Hyderabad and Bengaluru are building engine overhaul capabilities that create localized FADEC service demand outside traditional North American and European MRO hubs.
Commercial Aircraft Fadec Market Competitive Environment
Listed leaders compete with private specialists across certification capability and installed base ownership. The supplier base compresses around vendors with proven DO-178C DAL-A track records, elevating entry barriers beyond hardware manufacturing alone. Three archetypes dominate: aerospace conglomerates with military-to-commercial technology transfer, diversified industrials with integrated propulsion architectures, and pure-play engine control specialists. Competitive moves center on M&A for software qualification assets and strategic partnerships for silicon supply security.
Among aerospace conglomerates, Collins Aerospace and BAE Systems occupy positions sustained by decades of safety-critical software validation. Honeywell International Inc. exemplifies the diversified industrial archetype with cross-divisional technology leverage. Safran anchors the European pure-play tier with captive supply relationships to CFM International programs.
| Leading Market Players |
|---|
| Collins Aerospace (Rockwell Collins, Inc.) |
| Thales Group |
| Honeywell International Inc. |
| Woodward, Inc. |
| Moog Inc. |
| Safran |
| Triumph Group Inc. |
| Rolls-Royce Holdings plc |
| BAE Systems plc |
| Others |
Value Chain & Pricing Dynamics
Forty-five-week lead times for radiation-hardened FPGA procurement concentrate pricing power among qualified silicon vendors in the United States, while engine OEMs absorb cost volatility through long-term supply agreements indexed to semiconductor foundry capacity. This inventory constraint cascades into FADEC module pricing, where DO-178C DAL-A certification costs dominate hardware bill-of-materials differentials across supplier tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around power-by-the-hour service bundles that unbundle software update liability from hardware warranty coverage. Three-tier pricing separates line-fit OEM configurations from aftermarket retrofits and MRO service exchanges, with certification grade and volume scale as primary differentiation levers. Cost compression in regional jet hybrid FADEC segments is intensifying because airframe certification coupling constraints delay full digital upgrades. Low-cost carriers exhibit highest price sensitivity on initial acquisition, while Middle Eastern flag carriers prioritize lifetime service economics over unit cost.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade semiconductors dominates inventory strategy, with engine OEMs maintaining 18-24 month safety stocks against foundry allocation volatility. Manufacturing concentration centers on the United States, Germany, and France, where final assembly lines and validation facilities cluster. The supply chain draws from qualified FPGA vendors, radiation-hardened processor fabricators, and specialty thermocouple suppliers. Single-source vulnerability in silicon wafer sourcing creates structural risk exposure. Distribution runs through engine OEM captive channels and authorized MRO networks rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated fly-by-wire architectures threaten to absorb standalone FADEC functionality into unified flight control computers, forcing incumbent suppliers to defend their installed base through certification moats and aftermarket lock-in.
For Market Incumbents: Consolidate software qualification assets through selective acquisition of DO-178C tool qualification specialists, while deepening backward integration into radiation-hardened semiconductor sourcing to secure silicon allocation priority against emerging engine programs. Lock-in long-term power-by-the-hour contracts with digitally-native fleet operators to algorithm update revenue streams. For New Entrants and Emerging Players: Lead with open systems architectures compliant with ARINC 653 partitioning standards, targeting India's emerging MRO infrastructure in Hyderabad and Bengaluru where localized FADEC service demand outpaces established supplier presence. Pursue supplemental type certificate partnerships with cargo conversion specialists seeking emission-compliant engine control recalibration. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FAA and EASA certification timelines create structural barriers that compound over engine program lifecycles. Target acquisition profiles should emphasize vendors with qualified model-based design toolchains and existing CFM International or Pratt & Whitney program relationships. Watch for EASA artificial intelligence memoranda implementation as the signal indicating validation burden inflection for adaptive control algorithms.| Strategic Initiative | Industry Significance |
|---|---|
| Software Qualification Asset Acquisition | DO-178C DAL-A track records compress to vendors with proven validation histories. |
| Open Systems Architecture Development | ARINC 653 compliance enables third-party algorithm integration loosening OEM lock-in. |
| Regional MRO Infrastructure Partnership | India's Hyderabad and Bengaluru buildouts create localized service demand outside traditional hubs. |
| Sustainable Aviation Fuel Compatibility Investment | FADEC thermal management recalibration for SAF blends requires updated sensor fusion protocols. |
| Radiation-Hardened Silicon Supply Agreement | Long-term foundry contracts secure FPGA allocation priority against semiconductor volatility. |
Study Parameters
A standing panel of engine control system engineers, FAA certification specialists, airline technical operations directors, and MRO software update managers provided ongoing calibration against secondary validation from EASA CS-E regulatory filings, ICAO Annex 16 emission databases, and engine OEM power-by-the-hour contract disclosures. Bottom-up triangulation across FADEC module shipment data and top-down reconciliation against engine delivery schedules anchored volume estimates.
Consistency checks validated outputs against external benchmarks including airframe production rates and engine shop visit cycle frequencies across the analysis window. Segmentation modeling incorporated product architecture, application platform, end-user type, and technology maturity dimensions. CAGRs derived from fitted growth curves applied to line-fit and aftermarket revenue splits, with inputs from narrow-body delivery concentration patterns and emission mandate compliance timelines.
Forecasts assume regulatory continuity in FAA 14 CFR Part 33 and EASA CS-E regimes; material policy shifts would require re-modeling of software validation burden and certification timeline assumptions. Revision becomes warranted when SAF blend mandates or artificial intelligence interpretability requirements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Cargo Systems Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
North America Helicopters Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Helicopter Wheels Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
GCC Business Jet Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
India Aviation Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Asia-Pacific General Aviation Market