
 Composites in United States Defense Market | 2026-2036
Composites in United States Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Composites in United States Defense Market Outlook
Carbon fiber is rebalancing structural economics in fighter airframes and unmanned platforms as it displaces heavier aluminum alloys. Hexcel Corporation sustains its position through captive carbon fiber production and qualification on multiple Department of Defense programs. DuPont anchors aramid fiber supply chains for personal armor systems, while Northrop Grumman Corporation leverages in-house composite fabrication for stealth aircraft manufacturing.
Composites in United States Defense encompass engineered material systems combining reinforcing fibers with polymer matrices, typically achieving specific tensile strengths exceeding 1500 MPa and weight reductions of 20-40% versus metallic alternatives, manufactured through processes optimized for ballistic tolerance, radar signature management, and fatigue resistance in extreme operational environments. Carbon fiber dominates aerospace structural applications where stiffness-to-weight ratios determine performance ceilings, while aramid fiber occupies personal armor and naval systems where ballistic energy absorption takes priority. Thermoplastic composites represent the fastest-expanding manufacturing process category as out-of-autoclave curing reduces cycle times and enables higher-rate production for next-generation platforms.
FAA airworthiness standards, DoD MIL-STD-810 environmental testing protocols, and NIST measurement traceability requirements collectively dictate material qualification timelines and supplier certification barriers for defense composite applications. Berry Amendment domestic sourcing mandates and Buy American Act provisions restrict foreign fiber and resin content, reshaping supply chain geography and vertical integration incentives among prime contractors. Stakeholders must monitor evolving Pentagon sustainment priorities as platform life-extension programs compete with next-generation development funding for composite engineering resources.
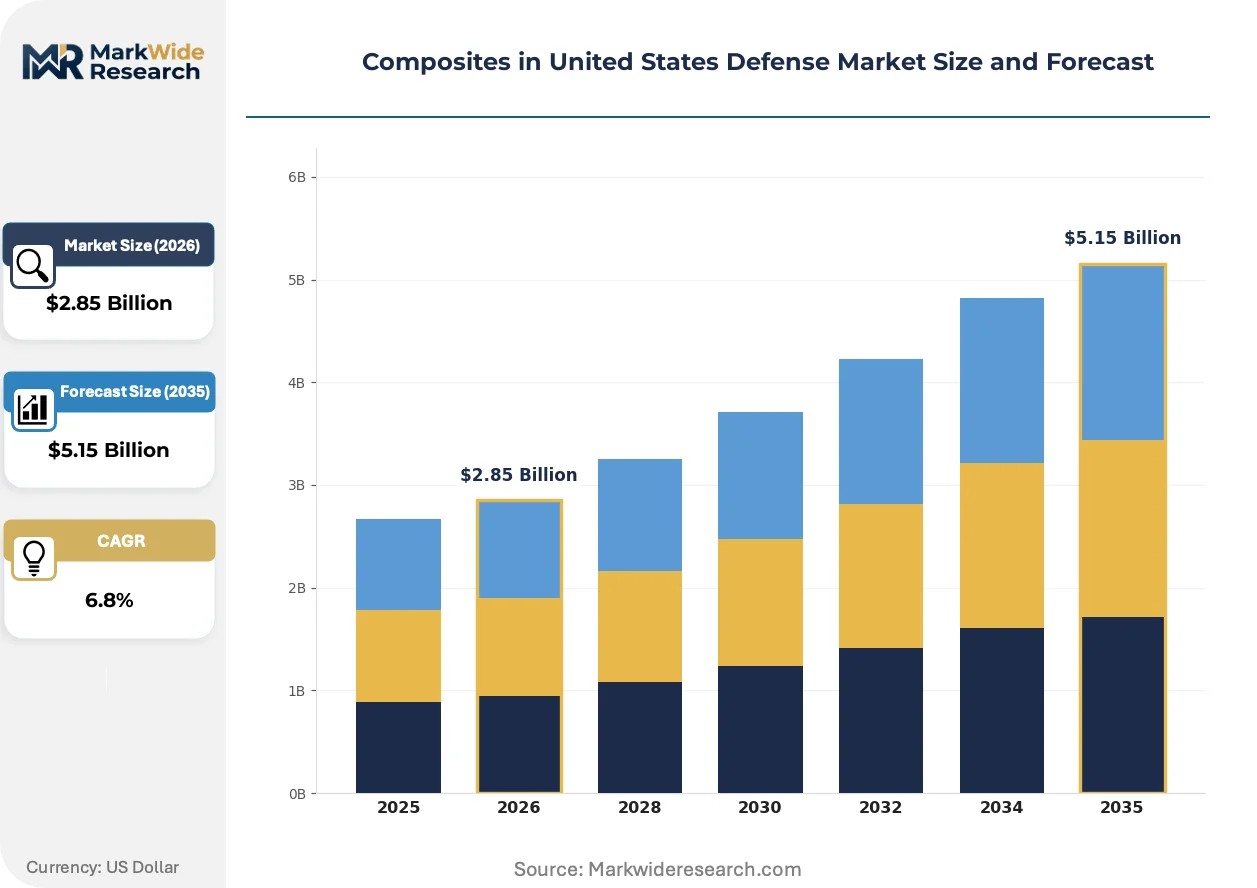
Market Dynamics
The Pentagon's sustainment-first budget posture is compressing composite engineering capacity between life-extension programs and next-generation platform development. This structural tension shapes supplier qualification timelines and capital allocation across the defense industrial base.
Growth Catalysts
- Stealth platform modernization:Low-observable requirements in sixth-generation fighter programs are expanding radar-absorbing composite laminates in airframe skins and engine inlets.
- Berry Amendment compliance:Domestic sourcing mandates for aramid and carbon fiber reinforcements are reshoring prepreg manufacturing to Texas and South Carolina production corridors.
- Unmanned systems proliferation:Group 4 and 5 UAS procurement targets are accelerating thermoplastic composite adoption for rapid fuselage fabrication.
Market Restraints
- Acrylonitrile feedstock volatility:Carbon fiber precursor costs fluctuate with petrochemical indices, compressing margin stability for prepreg suppliers.
- Single-source qualification risk:FAA and DoD dual-certification requirements lock airframe programs into approved fiber-matrix combinations with limited supplier redundancy.
- Metallic hybrid retention:Titanium and aluminum persist in high-temperature engine zones where thermo-oxidative stability limits polymer matrix viability.
Strategic Opportunities
- Hypersonic thermal protection:Ceramic matrix composites for leading edges and nose cones address surface temperatures exceeding 1,500°C in boost-glide vehicles.
- Army next-generation squad weapons:Lightweighting mandates for soldier-borne systems are opening aramid-composite applications in weapon receivers and support equipment.
- Out-of-autoclave process maturation:Electron beam curing and vacuum-assisted resin transfer molding are compressing cycle times for medium-rate tactical aircraft production.
Industry Challenges
- Non-destructive inspection technician scarcity:Ultrasonic and thermographic evaluation expertise concentrates at OEM facilities, constraining depot-level repair capacity expansion.
- Digital thread integration:Model-based definition handoffs between design authorities and subtier fabricators remain inconsistent across Navy and Air Force program offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composites in United States Defense Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Thermoplastic Composite Application: Aerospace, Naval Systems, Military Vehicle, Personal Armor End User: Government Agencies, Defense Contractors, Military, Research Institutions Manufacturing Process: Layup, Filament Winding, Resin Transfer Molding, Pultrusion |
| Companies Covered | DuPont, Huntsman International LLC, Hexcel Corporation, Owens Corning, Honeywell International Inc., Toray Industries Inc., The NORDAM Group LLC, Northrop Grumman Corporation, Solvay SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composites in United States Defense Market Strategic Shifts
Thermoplastic resins are displacing thermosets in structural applications where reworkability and recycling economics matter. Three converging developments are reshaping how defense composites are specified, processed, and fielded.
PEEK and PEKK matrix systems are electrifying damage tolerance standards in primary airframe structures. Naval Air Systems Command is qualifying these materials for arresting gear components and tailhook support structures where impact resistance governs service life. The shift is compressing repair cycle times from weeks to days while enabling in-situ welding for battlefield damage remediation.
Berry Amendment enforcement through the Defense Federal Acquisition Regulation Supplement is tightening traceability requirements for carbon fiber tow and epoxy resin origins. Contractors must now document domestic smelting and substantial transformation for precursor chemicals, forcing supply chain reconfiguration toward South Carolina and Texas chemical manufacturing corridors. Small fabricators without captive polymer production face qualification barriers that favor vertically integrated primes.
Performance-based logistics contracts are altering how composite component life is monetized across platform sustainment. Air Force Material Command now procures flight hours rather than discrete spares for selected F-35 subsystem lines, transferring fatigue risk to suppliers. This inversion concentrates predictive maintenance algorithm development at OEM engineering centers and marginalizes traditional depot repair stations in California and Georgia.
Composites in United States Defense Market Segmentation
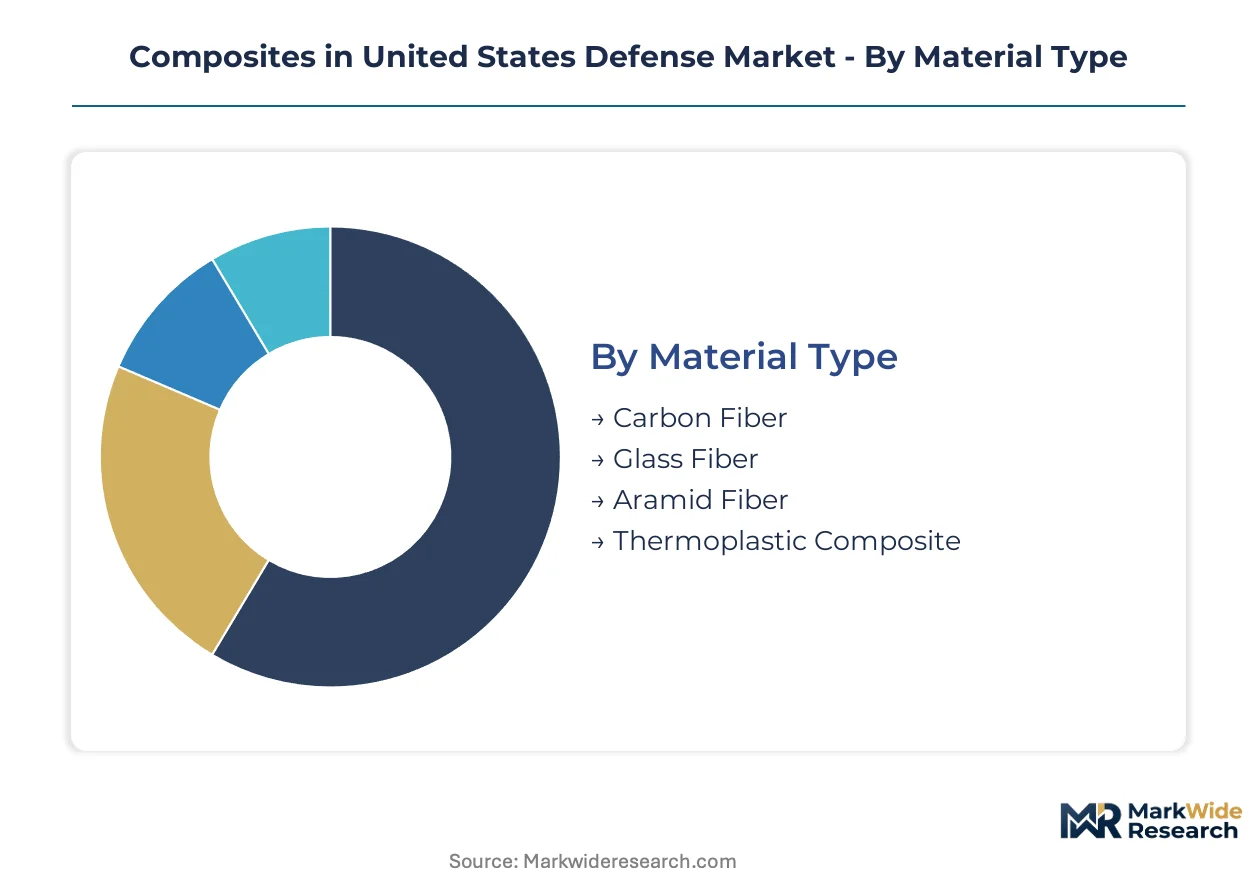
Defense composite procurement flows through distinct technical and organizational channels. Each segmentation axis reveals how Pentagon budget priorities reshape supplier positioning and manufacturing investment across the industrial base.
Material Type:
Domestic precursor production capacity concentrates in South Carolina and Texas chemical corridors, constraining which fiber grades achieve Berry Amendment qualification.
- Carbon Fiber:PAN-based and pitch-based variants achieve tensile strengths exceeding 5,000 MPa in aerospace primary structures. Demand concentrates in fighter airframes and unmanned platforms across California and Texas manufacturing clusters, where stiffness-to-weight ratios determine mission radius.
- Aramid Fiber:Para-aramid filaments deliver ballistic energy absorption through molecular chain orientation in shear-thickening configurations. Personal armor systems and naval soft-wall protection drive procurement from Virginia and Pennsylvania textile corridors, constrained by domestic spinning capacity.
- Glass Fiber:E-glass and S-glass reinforcements occupy cost-sensitive secondary structures where dielectric properties matter. Marine patrol craft and ground vehicle panels absorb volume from Ohio and Illinois fabricators.
- Thermoplastic Composite:PEEK and PEKK matrix systems enable weldable repairs and out-of-autoclave processing. Next-generation tactical aircraft and vertical lift programs are accelerating adoption through Naval Air Systems Command qualification pathways.
Today's leader: Carbon Fiber. Tomorrow's challenger: Thermoplastic Composite.
Application:
Platform-specific performance thresholds fragment engineering talent across divergent certification regimes.
- Aerospace:Primary airframe structures, control surfaces, and engine nacelles demand FAA-DoD dual certification. F-35 and B-21 programs anchor demand in Palmdale, California and Fort Worth, Texas production sites.
- Naval Systems:Hull structures, mast enclosures, and sonar domes require moisture ingress resistance and radar signature management. Virginia and Mississippi shipyards specify vinyl ester and epoxy formulations for surface combatant construction.
- Military Vehicle:Blast-resistant hull panels and turret structures integrate ceramic-composite hybrid laminates. Army Ground Vehicle Systems Center in Michigan drives specifications for next-generation combat vehicle prototypes.
- Personal Armor:Hard plate inserts and soft armor panels balance areal density against multi-hit ballistic performance. USSOCOM requirements from Tampa, Florida shape NIJ Level III and IV certification standards.
Aerospace commands the steepest expansion trajectory. Personal Armor faces procurement compression from platform modernization budgets.
End User:
Contracting authority distribution determines which specifications achieve program funding.
- Government Agencies:DARPA, ONR, and AFRL fund TRL advancement for novel matrix systems and manufacturing processes. SBIR pathways transition laboratory formulations to pilot production.
- Defense Contractors:Prime airframe integrators in California, Texas, and Maryland control subtier qualification and material release authority. Lockheed Martin, Northrop Grumman, and Boeing dictate fiber-matrix combinations through source control drawings.
- Military:Service-level material commands establish sustainment priorities and depot repair protocols. Tinker AFB, Ogden ALC, and Fleet Readiness Centers govern field-level composite remediation procedures.
- Research Institutions:University-affiliated research centers at MIT, Georgia Tech, and Penn State advance automated fiber placement and in-situ monitoring technologies.
Defense Contractors dominate specification authority. Research Institutions are gaining influence through Manufacturing Innovation Institutes.
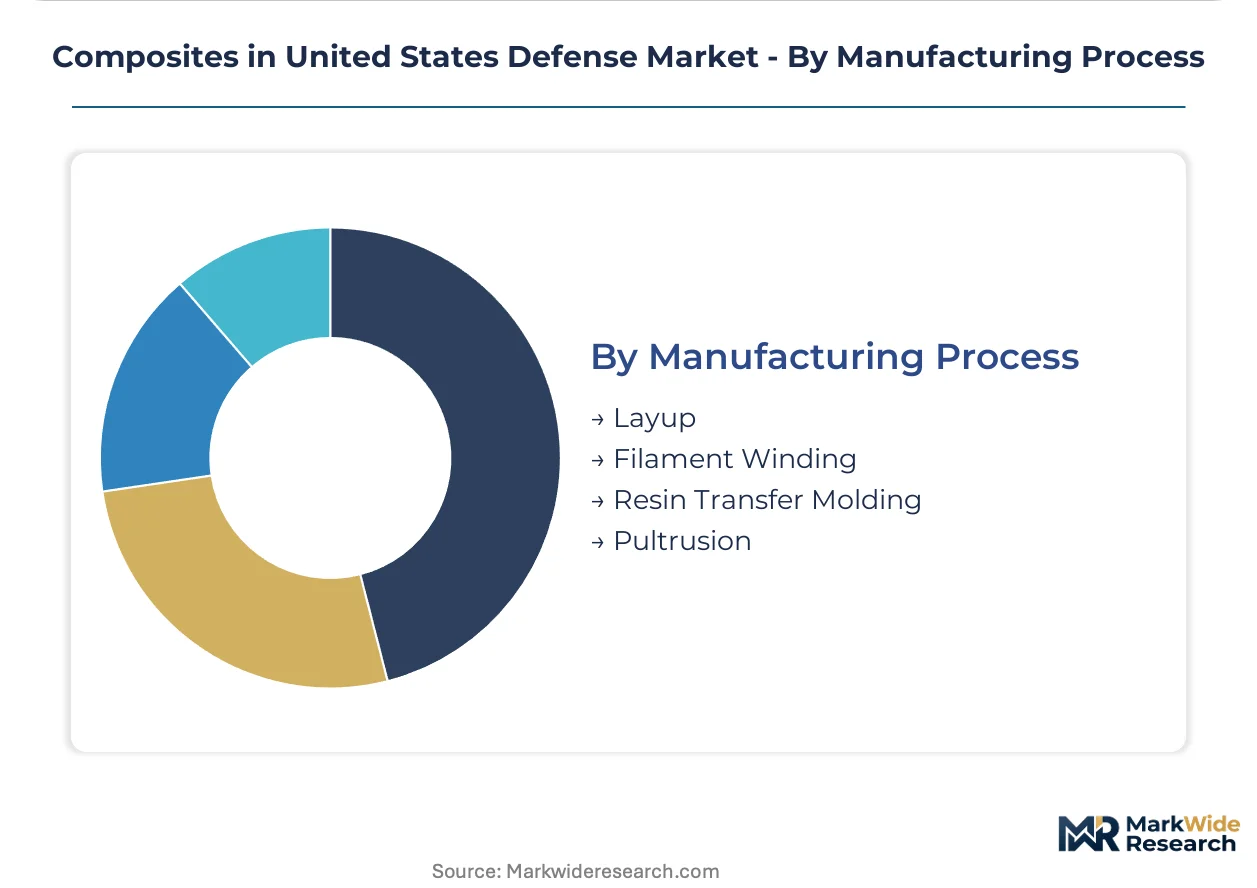
Manufacturing Process:
Capital equipment intensity and cycle time economics stratify supplier tiers.
- Layup:Manual and automated fiber placement of prepreg tapes and fabrics remains dominant for large aerospace structures. Autoclave curing constraints limit throughput for tactical aircraft production rates.
- Filament Winding:Computer-controlled fiber deposition produces pressure vessels, rocket motor cases, and drive shafts with optimized hoop strength. Utah and Alabama facilities serve missile defense and space launch programs.
- Resin Transfer Molding:Closed-mold infusion enables complex geometry fabrication with reduced volatile emissions. Marine and ground vehicle applications favor this route for OSHA compliance and surface finish requirements.
- Pultrusion:Continuous profile extraction delivers constant cross-section components for tentage, bridges, and infrastructure. Lower structural criticality permits higher production rates at reduced unit costs.
Layup retains volume leadership. Resin Transfer Molding is climbing fastest on environmental and rate advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's aerospace corridor anchors composite demand through stealth aircraft programs and unmanned systems manufacturing clusters. The Pentagon's Buy American mandates and Berry Amendment compliance requirements reshape material sourcing geography across defense manufacturing regions.
California
Palmdale and San Diego production sites drive carbon fiber consumption for F-35 and B-21 airframe assemblies. FAA and DoD dual-certification requirements concentrate engineering talent at Lockheed Martin Skunk Works and Northrop Grumman facilities. Los Angeles County hosts the densest concentration of automated fiber placement equipment for tactical aircraft skin fabrication.
Texas
Fort Worth anchors fighter jet final assembly with extensive composite wing and control surface production. Berry Amendment enforcement is reshoring prepreg manufacturing to Texas chemical corridors near Houston. Bell Textron in Fort Worth accelerates thermoplastic composite adoption for vertical lift platforms including the Future Long-Range Assault Aircraft program.
Virginia
Newport News Shipbuilding and Norfolk naval facilities specify vinyl ester composites for surface combatant hull structures. The Navy's radar signature management requirements drive demand for radar-absorbing laminates in mast enclosures. Hampton Roads hosts specialized sonar dome fabrication using glass fiber and syntactic foam cores.
Washington
Boeing's Puget Sound operations sustain carbon fiber demand for P-8 Poseidon maritime patrol aircraft and KC-46 tanker platforms. The Pacific Northwest cluster specializes in filament winding for missile defense pressure vessels. Washington State environmental regulations accelerate water-based resin system adoption in closed-mold processes.
Ohio
Wright-Patterson Air Force Base governs Air Force Research Laboratory composite qualification protocols for next-generation platforms. Cincinnati-area fabricators supply glass fiber panels for Army ground vehicle blast protection programs. Ohio's manufacturing base supports resin transfer molding for Marine Corps amphibious vehicle hull production.
Composites in United States Defense Market Competitive Environment
Global majors compete with regional champions across material qualification and defense program access. The vendor base stratifies into fiber producers, prepreg suppliers, and airframe integrators with captive fabrication capabilities. Three archetypes dominate: vertically integrated primes controlling source control drawings, specialty chemical suppliers with Berry Amendment-compliant precursor production, and tier-two fabricators dependent on prime contractor material release authority. Competitive moves concentrate on backward integration into carbon fiber production and strategic positioning for sixth-generation fighter qualification.
Among specialty chemical and fiber producers, Hexcel Corporation, DuPont, and Toray Industries Inc. exemplify contrasting strategic positions. Hexcel anchors the integrated prepreg-fiber archetype through captive carbon fiber production. DuPont occupies the aramid-dominated personal armor supply chain. Toray represents the multinational fiber producer navigating Buy American compliance through domestic manufacturing investments. Northrop Grumman Corporation and Honeywell International Inc. sit within the prime contractor tier where in-house composite fabrication enables stealth platform manufacturing control.
| Leading Market Players |
|---|
| DuPont |
| Huntsman International LLC |
| Hexcel Corporation |
| Owens Corning |
| Honeywell International Inc. |
| Toray Industries Inc. |
| The NORDAM Group LLC |
| Northrop Grumman Corporation |
| Solvay SA |
| Others |
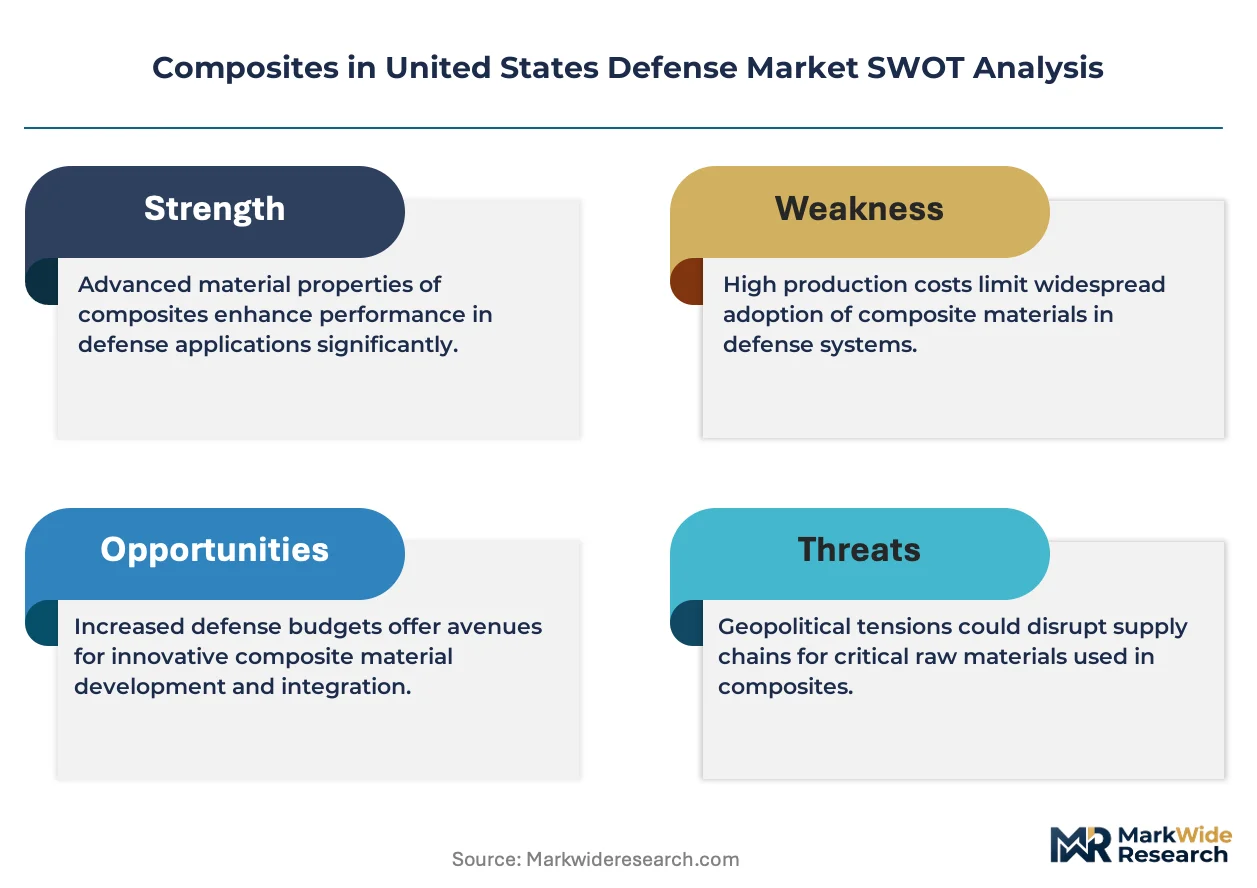
Value Chain & Pricing Dynamics
Acrylonitrile spot price volatility cascades through carbon fiber precursor economics into three-tier pricing structure across premium, standard, and economy levels. Berry Amendment compliance premiums and dual-certification overhead stratify supplier tiers, with Pentagon procurement officers absorbing cost pass-throughs for qualified fiber-matrix combinations while commercial buyers face steeper sensitivity.
Pricing Analysis
Input-cost pass-through from petrochemical indices governs prepreg supplier margins, with carbon fiber tow pricing tethered to acrylonitrile futures. Three-tier pricing structure across premium, standard, and economy levels separates FAA-DoD dual-certified aerospace grades from commercial-industrial specifications. Pricing pressure stems from metallic hybrid retention in engine zones, where titanium substitution limits polymer matrix premium capture. Defense contractors exhibit lowest price sensitivity due to sole-source program lock-in, while tier-two fabricators face acute margin compression from qualification cost amortization.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean carbon fiber precursor producers, constraining Berry Amendment-compliant domestic spinning capacity. The supply chain draws from Texas and South Carolina chemical corridors for acrylonitrile polymerization, with Utah and Alabama filament winding facilities serving missile defense programs. Tariff exposure on imported epoxy resin hardeners threatens prepreg margin stability. Distribution runs through prime contractor source control authority, with Lockheed Martin and Northrop Grumman governing subtier material release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with Pentagon sustainment budgets favoring suppliers qualified on sixth-generation fighter programs over commodity fabricators. Demand is shifting toward thermoplastic composites with weldable repair protocols, rewarding capital-intensive process investments.
For Market Incumbents: Deepen captive carbon fiber production to secure Berry Amendment-compliant precursor supply against Toray's domestic manufacturing investments. Accelerate automated fiber placement capacity in California and Texas corridors to capture B-21 and F-35 rate increases. Out-of-autoclave process patents represent the priority defensive moat against thermoplastic entrants. For New Entrants and Emerging Players: Capture Army next-generation squad weapon lightweighting mandates through aramid-composite weapon receiver development, bypassing saturated aerospace qualification queues. Naval Air Systems Command thermoplastic qualification pathways offer faster certification timelines than FAA-DoD dual-track protocols. Partner with university-affiliated research centers for electron beam curing technology access. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty chemical suppliers possessing domestic precursor production and Pentagon program access. The five-to-ten year viability window favors backward-integrated prepreg manufacturers over dependent fabricators. Watch for hypersonic thermal protection ceramic matrix composite qualification announcements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile polymerization secures Berry Amendment compliance and margin control against petrochemical volatility. |
| Out-of-Autoclave Process Scale-Up | Vacuum-assisted resin transfer molding compresses tactical aircraft cycle times for Future Long-Range Assault Aircraft production. |
| Thermoplastic Composite Qualification | PEEK matrix certification through Naval Air Systems Command enables weldable repair protocols and battlefield damage remediation. |
| Hypersonic Thermal Protection Development | Ceramic matrix composite leading edge supply positions vendors for boost-glide vehicle programs exceeding 1,500°C surface temperatures. |
| Performance-Based Logistics Contracting | Flight-hour procurement models transfer fatigue risk to suppliers and concentrate predictive maintenance algorithm development at OEMs. |
Study Parameters
Direct dialogue with Pentagon program officers, composite engineering directors at prime contractors, prepreg procurement managers, and non-destructive inspection technicians grounded qualitative assessment. Secondary validation drew from DoD budget justification documents, FAA airworthiness directives, SEC 10-K filings from listed fiber producers, and Berry Amendment enforcement determinations. Bottom-up program-level demand estimation triangulated against top-down defense industrial base capacity analysis.
Market size outputs across the analysis window reflect segment-level modeling of material type, application, and manufacturing process dimensions. CAGRs derived from platform procurement timelines and life-extension program funding trajectories. Forecast inputs incorporated F-35 and B-21 production rate assumptions, unmanned systems proliferation targets, and Army ground vehicle modernization schedules.
Acrylonitrile price shocks, Pentagon budget reprogramming actions, and thermoplastic qualification delays are the dominant revision risks. Forecasts reflect documented assumptions on platform procurement continuity and domestic precursor capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market