
 Aviation Coatings Market | 2026-2036
Aviation Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Coatings Market Analysis
AS9100 qualification is unwinding the supplier base into a smaller set of certified coating houses with airframe OEM approval. PPG Industries leverages its vertical integration from resin synthesis to approved applicator networks across North America and Europe. Akzo Nobel anchors its position through sustained R&D investment in chrome-free primer systems that meet Boeing and Airbus process specifications. BASSE competes on manufacturing scale, operating dedicated aerospace coating plants in Germany and the United States with tank-to-wing traceability systems.
Aviation coatings are engineered polymer systems—typically polyurethane, epoxy, or polysiloxane chemistries applied in 25–75 micron dry film thicknesses—that protect airframe substrates from ultraviolet degradation, fluid exposure, and aerodynamic erosion while managing radar signature and thermal loads. The product type dimension shows protective coatings occupying the largest volume pool due to mandatory reapplication intervals on leading edges and engine nacelles, while UV-curable formulations within the formulation dimension represent the fastest-expanding technology set as line-of-assembly cure cycles compress from hours to minutes. Application demand tilts toward commercial aircraft where production rate recovery at Airbus and Boeing drives OEM specification volume, with military aircraft commanding premium pricing through qualified specialty coatings with infrared suppression and radar-absorbing functionality.
EPA oversight on hazardous air pollutant emissions from coating operations and REACH restriction of hexavalent chromium compounds in Europe are forcing reformulation investments that favor suppliers with in-house toxicology and regulatory affairs capabilities. FAA airworthiness directives on corrosion prevention and EASA continuing airworthiness management organization requirements sustain aftermarket demand through mandated inspection and touch-up protocols. Stakeholders must monitor the pace of powder coating line conversions at tier-one aerostructures facilities, as capital deployment decisions there will reshape competitive access to next-generation narrowbody and regional jet platforms.
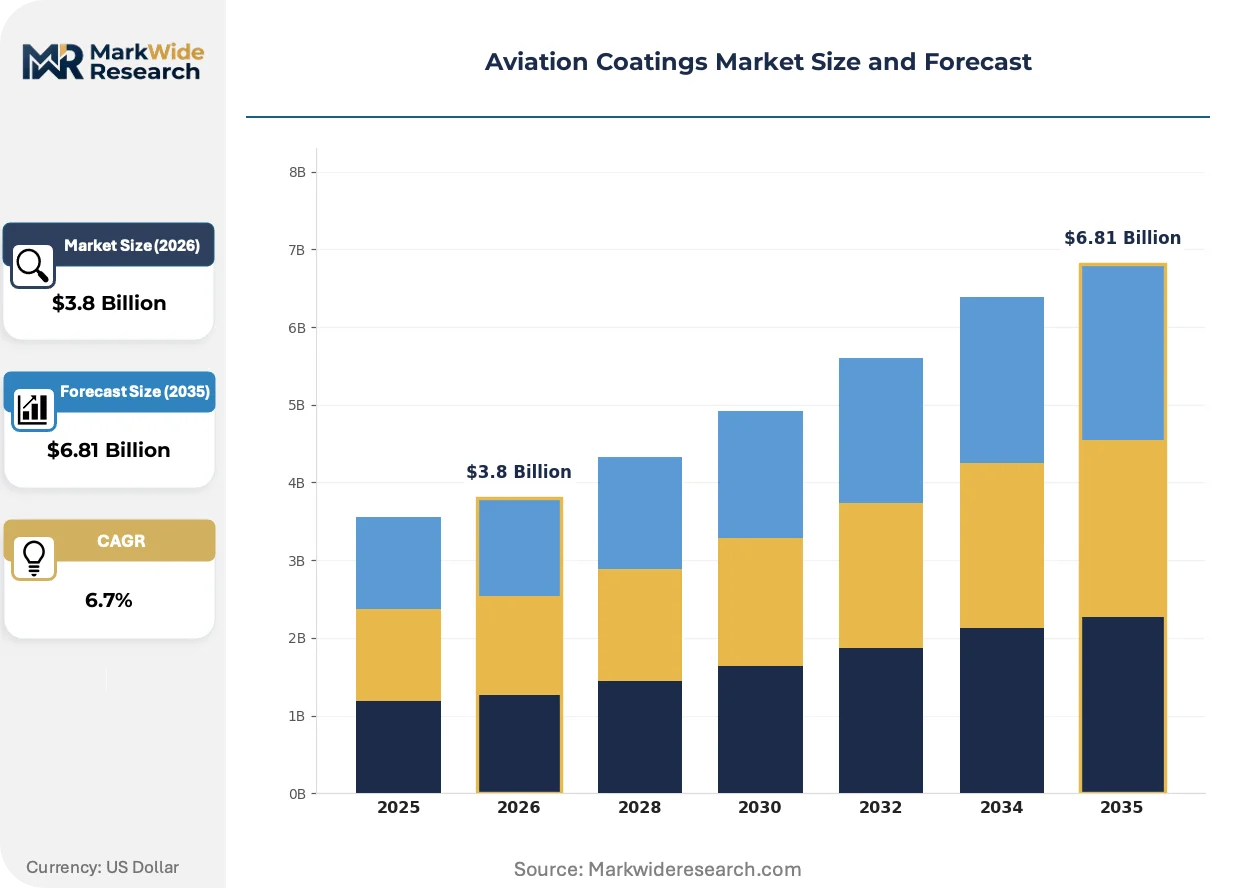
Market Dynamics
REACH restrictions on hexavalent chromium and EPA hazardous air pollutant rules are forcing simultaneous reformulation across solvent-based primer systems, compressing supplier R&D cycles while OEM qualification protocols extend validation timelines.
Growth Catalysts
- EU Green Deal VOC mandates:Aqueous and UV-curable formulations gain specification share as solvent-based systems face phase-down schedules across European MRO networks.
- China's COMAC C919 production ramp:Shanghai-Tianjin aerospace corridor demand concentrates domestic coating procurement toward qualified local applicators with AS9100 certification.
- FAA corrosion prevention directives:Mandatory inspection intervals on aging commercial fleets sustain aftermarket touch-up volume through scheduled maintenance protocols.
Market Restraints
- Titanium dioxide supply concentration:Pigment cost volatility ties formulation economics to Chinese sulfate-process capacity and export licensing.
- Chrome-free primer performance gap:Erosion resistance and adhesion metrics in alternative chemistries lag hexavalent chromium baselines on engine nacelle applications.
- AS9100 certification scarcity:Approved applicator networks concentrate in Germany, the United States, and Japan, limiting tier-two supplier access to OEM specification lists.
Strategic Opportunities
- India defense procurement expansion:Tejas and AMCA programs create qualified coating demand for radar-absorbing and infrared-suppression finishes on indigenous platforms.
- Powder coating line conversions:Capital deployment at tier-one aerostructures facilities in Brazil and Mexico opens specification access for regional jet platforms.
- Digital twin integration:Coating thickness monitoring via embedded sensors converges with predictive maintenance platforms to create outcome-based service contracts.
Industry Challenges
- Formulation chemist shortage:Expertise in polysiloxane and fluoropolymer synthesis concentrates at a handful of European and North American suppliers.
- OEM qualification timelines:Boeing and Airbus process specification approval cycles extend 18-36 months, freezing competitive entry for reformulated systems.
- Tank-to-wing traceability systems:Batch documentation and chain-of-custody requirements demand capital investment in ERP and laboratory information management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Coatings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Coatings, Decorative Coatings, Specialty Coatings, Primer Coatings Application: Commercial Aircraft, Military Aircraft, General Aviation, Helicopters Formulation: Aqueous Coatings, Solvent-based Coatings, Powder Coatings, UV-curable Coatings End User: Aerospace Manufacturers, Maintenance Repair Organizations, Airlines, Component Suppliers |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., Sherwin-Williams Company, Axalta Coating Systems Ltd., Mankiewicz Gebr. & Co., Henkel AG & Co. KGaA, Hentzen Coatings, Inc., BASF SE, Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Coatings Market Emerging Trajectories
Coating cure chemistry and application automation are compressing manufacturing cycle times while regulatory pressure on chromates and VOCs forces material substitution across the value chain.
UV-curable polyurethane topcoats are displacing conventional two-component systems on narrowbody assembly lines. Airbus and Boeing suppliers in Hamburg and Charleston adopt line-of-assembly cure cycles that compress drying from hours to minutes. This shift is displacing traditional spray-booth infrastructure and enabling higher throughput without footprint expansion.
REACH authorization requirements for chromium trioxide in surface treatment processes tighten through 2024-2027 sunset dates. European MRO facilities face reformulation deadlines that favor suppliers with in-house toxicology and regulatory affairs capabilities. Military platforms with extended service lives remain most affected, as alternative primer systems must demonstrate equivalent corrosion protection under salt-fog and fluid immersion protocols.
Buyer concentration at tier-one aerostructures suppliers is consolidating coating procurement under long-term supply agreements. Spirit AeroSystems and GKN Aerospace negotiate direct relationships with approved applicator networks, bypassing traditional distributor channels. This pattern concentrates specification influence at final assembly locations in Toulouse, Mobile, and Tianjin.
Aviation Coatings Market Segmentation
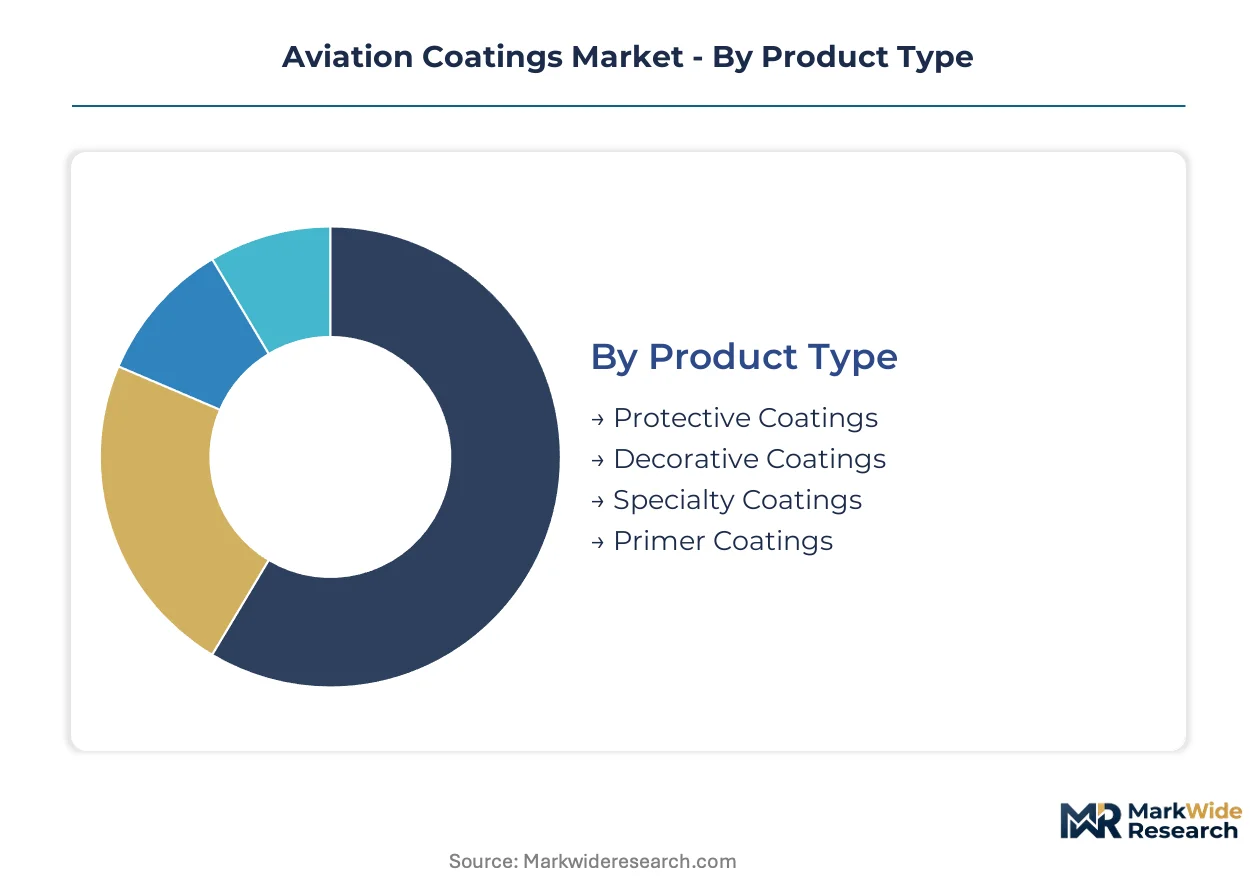
Aviation coatings demand fragments across product chemistry, aircraft platform, and supply chain position. Each dimension carries distinct qualification barriers and margin profiles that reshape competitive access.
Product Type:
Protective and primer systems concentrate procurement in domestic aerospace corridors; decorative and specialty coatings travel through export-qualified applicator networks.
- Protective Coatings:Polyurethane and polysiloxane topcoats engineered for ultraviolet degradation resistance and fluid exposure protection. Demand clusters at Airbus and Boeing final assembly locations in Hamburg, Toulouse, and Charleston where reapplication intervals on leading edges drive volume.
- Primer Coatings:Epoxy and chrome-free formulations providing substrate adhesion and corrosion inhibition under salt-fog protocols. Procurement concentrates in military maintenance depots across India and the United States where extended service lives mandate qualified alternatives to hexavalent chromium systems.
- Decorative Coatings:Pigmented finishes meeting airline livery specifications for colorfastness and gloss retention.
- Specialty Coatings:Radar-absorbing and infrared-suppression formulations for low-observable platforms.
Protective coatings hold the largest share; momentum sits with specialty coatings.
Application:
Commercial platforms dominate procurement volume; military and general aviation segments command premium pricing through specialized qualification protocols.
- Commercial Aircraft:Narrowbody and widebody production lines at Airbus, Boeing, and COMAC specification volume. Shanghai-Tianjin corridor procurement accelerates as C919 production rates climb.
- Military Aircraft:Fighter and transport platforms requiring radar signature management and thermal load dissipation. India's Tejas and AMCA programs anchor indigenous demand for qualified applicators with AS9100 certification.
- General Aviation:Business jet and turboprop refurbishment cycles at dedicated MRO facilities.
- Helicopters:Rotor blade erosion resistance and marine environment protection for offshore operations.
Commercial aircraft absorb the greatest volume; military platforms generate the steepest margin expansion.
Formulation:
Cost tier stratification separates capital-intensive UV-curable lines from established solvent-based infrastructure.
- UV-curable Coatings:Photoinitiator-activated polyurethane systems curing in minutes under LED arrays. Airbus suppliers in Hamburg adopt line-of-assembly application compressing cycle times from hours to minutes.
- Solvent-based Coatings:Conventional two-component epoxy and polyurethane systems facing phase-down schedules under EU Green Deal VOC mandates. European MRO networks convert aqueous alternatives ahead of regulatory deadlines.
- Aqueous Coatings:Water-borne resin systems meeting EPA hazardous air pollutant thresholds.
- Powder Coatings:Thermoset formulations requiring dedicated spray-booth infrastructure and elevated cure temperatures.
Solvent-based formulations retain the largest installed base; UV-curable systems are climbing the fastest.
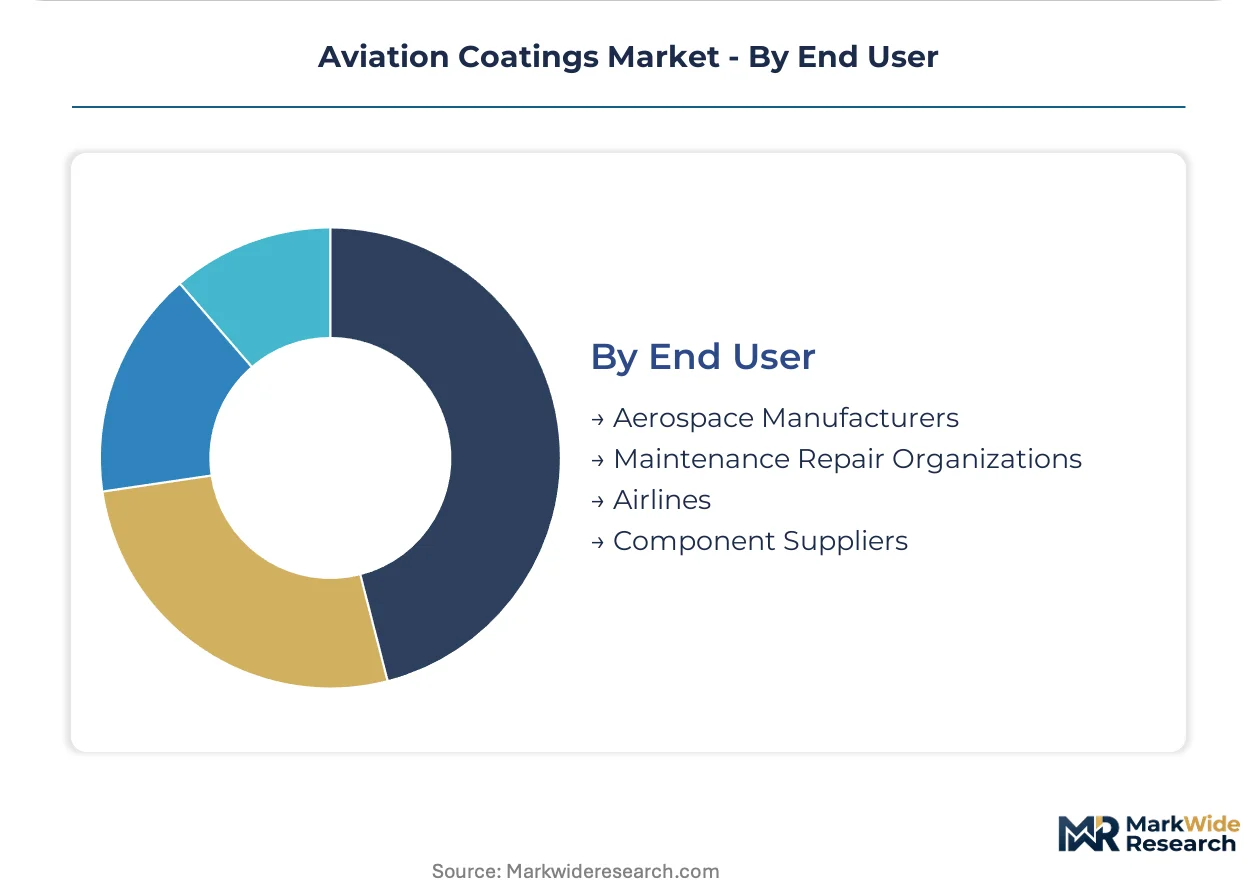
End User:
Customer type determines procurement pattern: manufacturers specify at design phase while MROs drive aftermarket replenishment.
- Aerospace Manufacturers:Airframe OEMs and tier-one aerostructures suppliers embedding coating specifications into bill-of-materials. Spirit AeroSystems and GKN Aerospace negotiate direct applicator relationships bypassing distributor channels.
- Maintenance Repair Organizations:European and North American facilities executing mandatory corrosion prevention protocols under FAA airworthiness directives. EASA continuing airworthiness management organization requirements sustain inspection-driven touch-up volume.
- Airlines:Fleet operators managing livery refresh and damage repair through approved vendor networks.
- Component Suppliers:Engine nacelle and landing gear manufacturers applying qualified primer systems with tank-to-wing traceability documentation.
Aerospace manufacturers capture the greatest specification influence; MROs provide the most stable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal VOC mandates and defense procurement expansions are redirecting coating formulation investments toward aqueous and UV-curable alternatives across major aerospace manufacturing corridors.
United States
FAA airworthiness directives on corrosion prevention sustain aftermarket demand through mandatory inspection intervals on aging commercial fleets. EPA hazardous air pollutant rules constrain solvent-based operations at MRO facilities in Georgia and Oklahoma. Charleston and Seattle aerospace clusters concentrate OEM specification volume as Boeing suppliers adopt line-of-assembly cure cycles.
China
COMAC C919 production ramp concentrates procurement toward qualified domestic applicators with AS9100 certification. MEE enforcement of dual carbon goals accelerates aqueous formulation adoption at Shanghai-Tianjin corridor facilities. Tianjin Binhai New Area hosts expanding coating applicator networks serving narrowbody final assembly lines.
Germany
REACH authorization deadlines for chromium trioxide drive chrome-free primer reformulation across Hamburg and Munich MRO networks. EASA continuing airworthiness management organization requirements sustain inspection-driven touch-up volume. Hamburg Airbus supplier ecosystem leads European adoption of UV-curable polyurethane topcoats.
India
Tejas and AMCA defense programs generate qualified demand for radar-absorbing and infrared-suppression finishes on indigenous platforms. DGFT import licensing frameworks shape pigment procurement patterns for domestic formulation houses. Bangalore-Hyderabad aerospace corridor attracts AS9100-certified applicator investments.
France
Airbus final assembly specifications at Toulouse consolidate coating procurement under long-term supply agreements with approved applicator networks. ANSM oversight of workplace chemical exposure influences reformulation timelines at Bordeaux and Nantes MRO facilities. Occitanie region hosts specialized military coating applicators serving Dassault Aviation platforms.
Aviation Coatings Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with aerospace-qualified resin synthesis capabilities. Supplier concentration intensifies as AS9100 certification requirements and OEM approval protocols compress the qualified applicator base. Three archetypes dominate: vertically integrated coating houses controlling resin-to-application value chains, specialized aerospace finish suppliers with dedicated regulatory affairs functions, and diversified industrial coating divisions leveraging parent-company R&D scale. Competitive dynamics center on chrome-free primer qualification speed and UV-curable line-of-assembly adoption at tier-one aerostructures facilities.
Among diversified chemical conglomerates, Akzo Nobel N.V., PPG Industries Inc., and BASF SE occupy positions exemplifying the integrated-resin-synthesis archetype. These entities anchor competitive positioning through captive supply of qualified primer and topcoat chemistries. Specialized aerospace finish suppliers including Hentzen Coatings, Inc. and Mankiewicz Gebr. & Co. represent the dedicated-aerospace-applicator archetype with concentrated AS9100 certification depth. The competitive terrain rewards backward integration into resin production and sustained regulatory compliance infrastructure investment.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| Sherwin-Williams Company |
| Axalta Coating Systems Ltd. |
| Mankiewicz Gebr. & Co. |
| Henkel AG & Co. KGaA |
| Hentzen Coatings, Inc. |
| BASF SE |
| Saint-Gobain S.A. |
| Others |
Supply Flow & Price Mechanics
Chrome-free primer substitution for hexavalent chromium systems simultaneously redraws raw material sourcing maps toward European and North American specialty chemical producers and compresses margin structures as reformulation R&D costs absorb pricing power. Buyers with captive resin synthesis capabilities extract favorable terms against dependent applicators facing titanium dioxide cost volatility.
Pricing Analysis
Cost-plus contracts with titanium dioxide and epoxy resin indexation dominate procurement between tier-one aerostructures suppliers and qualified coating houses. Price differentiation rests on AS9100 certification tier and tank-to-wing traceability documentation depth. Pricing pressure intensifies in solvent-based formulations as EU Green Deal VOC mandates accelerate aqueous conversion investments. Military platform buyers exhibit lowest price sensitivity due to radar-absorbing performance requirements, while regional MRO networks face acute cost compression.
Supply Chain Analysis
Inventory cycles extending twelve to eighteen months for photoinitiator-activated chemistries strain working capital at UV-curable coating lines. Manufacturing concentrates in Germany, the United States, and China where dedicated aerospace plants feed Airbus, Boeing, and COMAC assembly corridors. Raw material flows draw from Chinese sulfate-process titanium dioxide, German epoxy resin synthesis, and Japanese photoinitiator production. Single-source vulnerability in hexavalent chromium alternatives threatens qualification timelines. Distribution runs through direct applicator relationships that Spirit AeroSystems and GKN Aerospace negotiate, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation coatings constitute a cyclical recovery play as commercial aircraft production rates at Airbus and Boeing drive OEM specification volume through narrowbody assembly line expansions.
For Market Incumbents: Secure backward integration into photoinitiator and specialty resin production to buffer titanium dioxide cost volatility and capture margin from UV-curable formulation adoption. Defend specification position by accelerating chrome-free primer qualification ahead of REACH authorization deadlines. Concentrate capacity additions in the Shanghai-Tianjin corridor to anchor COMAC C919 supply relationships. For New Entrants and Emerging Players: Differentiate on digital twin integration capabilities that enable predictive coating thickness monitoring and outcome-based service contracts. Target the India defense procurement expansion around Tejas and AMCA programs where radar-absorbing specialty coating demand outstrips qualified applicator supply. Pursue joint qualification pathways with tier-one aerostructures suppliers converting powder coating lines in Brazil and Mexico. For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors specialized aerospace finish suppliers with concentrated AS9100 certification depth over diversified industrial coating divisions. Long-term viability hinges on regulatory compliance infrastructure and OEM approval protocol navigation rather than commodity scale. Monitor the pace of UV-curable line-of-assembly adoption at Hamburg and Charleston supplier ecosystems as the inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Primer Qualification | REACH authorization deadlines force reformulation investments that concentrate supplier base toward in-house toxicology capabilities. |
| UV-Curable Line Conversion | Airbus suppliers in Hamburg compress cure cycles from hours to minutes without footprint expansion. |
| AS9100 Certification Investment | OEM approval protocols compress qualified applicator networks and erect entry barriers for tier-two suppliers. |
| Direct Applicator Relationships | Spirit AeroSystems and GKN Aerospace bypass distributor channels and consolidate procurement influence. |
| Digital Twin Integration | Embedded coating thickness sensors converge with predictive maintenance platforms to create outcome-based service contracts. |
Methodological Framework
Operator-level perspectives from coating formulation chemists, tier-one aerostructures procurement directors, MRO facility managers, and regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined with secondary validation against FAA airworthiness directive databases, EASA continuing airworthiness management organization filings, EPA hazardous air pollutant enforcement records, and customs trade data for titanium dioxide and epoxy resin flows. Bottom-up volume estimates triangulated with top-down aerospace production forecasts across the analysis window.
Sensitivity analysis around COMAC C919 production ramp scenarios and REACH authorization timeline variations tested forecast robustness. Segmentation dimensions modeled include product chemistry tier, aircraft platform category, formulation technology, and end-user type. CAGRs derived from production rate trajectories at Airbus, Boeing, and COMAC final assembly locations, overlaid with mandatory reapplication interval protocols under FAA corrosion prevention directives.
Material uncertainties — defense procurement delays, titanium dioxide export licensing disruptions, and chrome-free primer performance gaps on engine nacelle applications — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM qualification protocol timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market