
 Aerospace Composite Ducting Market | 2026-2036
Aerospace Composite Ducting Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Composite Ducting Market Analysis
Market Context
North American Tier-1 aerostructures suppliers is restructuring composite ducting capacity to align with Boeing's 737 MAX and 787 production ramps. Parker-Hannifin Corporation leverages its integrated motion and control portfolio to dominate fluid conveyance systems for commercial platforms. AIM Aerospace anchors Pacific Northwest manufacturing with thermoplastic composite ducts for narrow-body environmental control systems. Senior Aerospace specializes in complex duct geometries for engine bleed air applications across European and North American OEM programs.
Technical Definition and Segment Structure
Aerospace composite ducting encompasses fiber-reinforced polymer conduit systems, typically manufactured from carbon fiber or glass fiber prepregs with service temperatures ranging from minus 54 degrees Celsius to 200 degrees Celsius, engineered to transport bleed air, fuel vapor, or conditioned air while minimizing weight penalties versus metallic alternatives. Rigid ducts command the largest revenue share due to their integration into fixed wing primary air distribution architectures, while flexible ducts represent the fastest-expanding category as adaptive routing solutions gain traction in next-generation compact engine nacelles. Carbon fiber material grades capture premium margin pools where specific strength requirements justify raw material cost premiums over glass fiber alternatives in military aviation exhaust system applications.
Regulatory Environment and Outlook
FAA Part 25 flammability standards, EASA CS-25 certification requirements, and ISO 2685 fire resistance test protocols collectively dictate material selection, laminate architecture, and qualification timelines for composite ducting suppliers seeking platform integration. Military aviation procurement through NAVAIR and the Defense Logistics Agency imposes additional ITAR-controlled supply chain constraints that filter eligible producers for fighter and rotorcraft programs. Stakeholders must monitor evolving EPA and REACH chemical restrictions on resin systems and flame retardant additives, as regulatory shifts in either jurisdiction could force reformulation cycles with multi-year requalification horizons.
Market Dynamics
OEM production rate volatility at Boeing and Airbus is compressing order visibility for composite ducting suppliers, forcing capacity commitments ahead of firm demand signals while thermoplastic processing investments lock in technology bets.
Growth Catalysts
- FAA Part 25 Amendment 25-116:Tightened flammability standards for interior components are mandating advanced resin formulations that favor composite ducts over aluminum in narrow-body environmental control systems.
- Bleed air system electrification:More-electric aircraft architectures from Boeing and Airbus are expanding duct counts per shipset as pneumatic systems fragment into distributed thermal management networks.
- Glass fiber prepregs:Cost-optimized material grades are penetrating regional jet and general aviation platforms where carbon fiber specific strength remains economically unjustified.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with oil and natural gas feedstock markets, compressing margin predictability for prepreg converters serving long-term OEM contracts.
- Autoclave capacity concentration:Large-diameter curing equipment for engine nacelle ducts clusters in Washington state and Toulouse, creating geographic single-points-of-failure in supply continuity.
- Metallic duct refurbishment:MRO facilities at Delta TechOps and Lufthansa Technik extend titanium duct service life through weld repair, delaying composite replacement cycles in aging fleets.
Strategic Opportunities
- Urban air mobility:eVTOL developers at Joby Aviation and Archer Aviation require lightweight, complex-geometry ducting for distributed electric propulsion thermal management at unit volumes absent in traditional aviation.
- REACH Annex XVII amendments:Pending restrictions on halogenated flame retardants are accelerating bio-based resin qualification programs that first-mover suppliers can leverage for EASA CS-25 certification advantages.
- Out-of-autoclave processing:Oven-curable thermoplastic composites are converging with automated fiber placement to enable duct geometries previously impossible in metallic or thermoset alternatives.
Industry Challenges
- Qualification engineer scarcity:FAA DERs with composite fireworthiness certification experience command premium compensation, constraining supplier expansion timelines.
- Platform-specific tooling amortization:Duct mandrels for 737 MAX nacelles lack transferability to A320neo geometries, stranding capital when production rates diverge from forecasts.
- ITAR-controlled technical data:Defense program participation requires segmented engineering teams and facility clearances that complicate commercial-military capacity flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Composite Ducting Market |
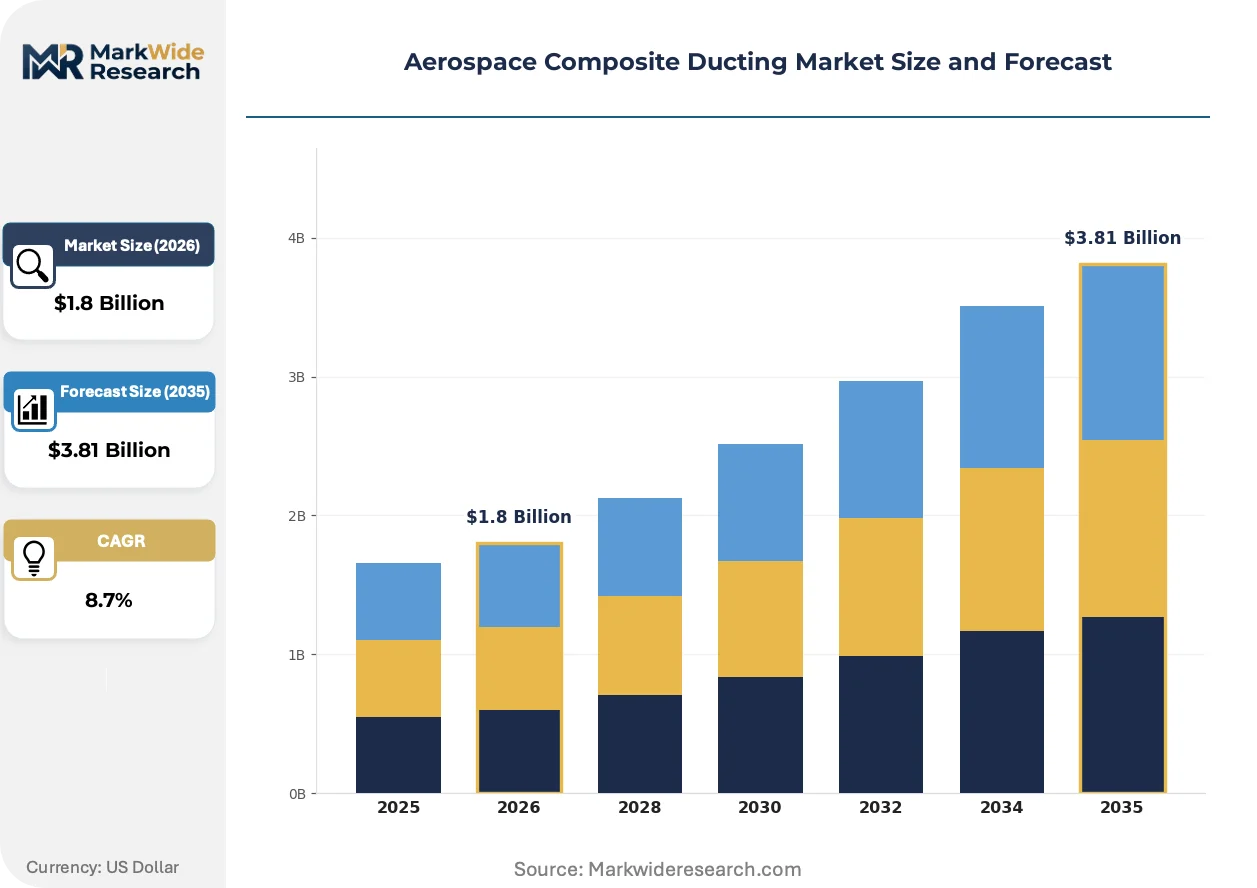
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Ducts, Rigid Ducts, Transition Ducts, Insulated Ducts Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Thermoplastic End User: Civil Aviation, Military Aviation, Space Exploration, Aerospace Maintenance Application: Air Conditioning, Air Distribution, Exhaust Systems, Fuel Delivery |
| Companies Covered | Parker-Hannifin Corporation, AIM Aerospace, Senior Aerospace, Saint-Gobain Performance Plastics, Stelia Aerospace, Triumph Group, Arrowhead Products, Eaton Aerospace, ITT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Composite Ducting Market Emerging Trajectories
Thermoplastic composite processing is overtaking thermoset dominance in duct manufacturing, driven by cycle time compression and recyclability pressures that reshape supplier technology roadmaps and capital allocation priorities.
Thermoplastic composite ducts manufactured from PEEK and PEKK matrices are overtaking epoxy-based thermosets in engine nacelle applications where service temperatures exceed 180 degrees Celsius. Airbus A350 and Boeing 787 program engineers specify these materials for thrust reverser bypass ducts, compressing part consolidation opportunities that previously required multi-piece metallic assemblies. The shift is overtaking traditional autoclave-dependent supply chains as press-forming and welding techniques enable out-of-autoclave production at significantly reduced cycle times.
EASA CS-25 Amendment 25-23 introduced more stringent smoke density and toxicity requirements for large transport aircraft cabin and cargo compartment materials. European OEM procurement teams now mandate optical smoke density testing per ASTM E662 and toxic gas generation per BSS 7239 for all ducting penetrating pressure bulkheads. Narrow-body programs at Airbus in Hamburg and Toulouse are responding by qualifying low-smoke phenolic resin systems that trade mechanical properties for regulatory compliance in specific routing zones.
Airline engineering departments are consolidating vendor bases from three-tier to two-tier structures, directly engaging composite duct specialists for integrated system responsibility rather than delegating through aerostructure tier-1s. This disintermediation is visible most acutely at Southwest Airlines and Ryanair, where direct technical relationships with duct manufacturers accelerate configuration changes and reduce latency in airworthiness directive response. The pattern compresses margin pools for traditional intermediaries while rewarding suppliers with in-house design certification capabilities.
Aerospace Composite Ducting Market Segmentation
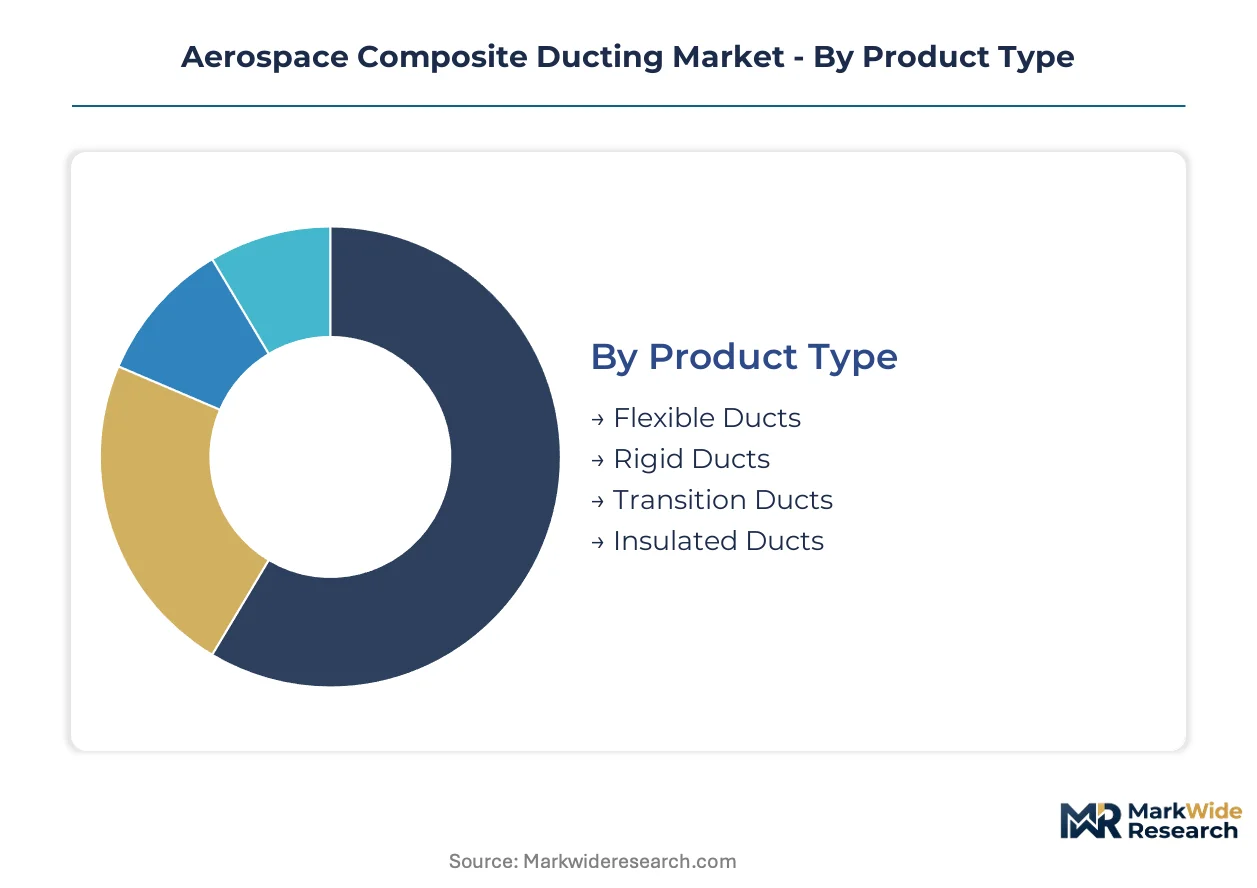
Composite ducting architectures diverge sharply across aircraft subsystems, with each segment demanding distinct material qualifications and manufacturing investments. Suppliers must align capacity with the upgrade cycles of specific platforms rather than treating aerospace as a monolithic demand pool.
Product Type:
Replacement decisions for aging metallic ducting favor segments that minimize shipset requalification burden while delivering immediate weight savings.
- Rigid Ducts:Fixed-geometry conduit systems fabricated from carbon fiber or glass fiber prepregs serve as primary air distribution backbones in narrow-body and wide-body airframes. Boeing 737 MAX and Airbus A320neo production lines in Renton and Hamburg anchor procurement volumes for these components.
- Flexible Ducts:Adaptive routing solutions constructed from multi-layer elastomeric composites accommodate thermal expansion and vibration isolation in compact engine nacelles. eVTOL developers at Joby Aviation and Archer Aviation specify these geometries for distributed electric propulsion thermal management, driving qualification activity outside traditional OEM channels.
- Transition Ducts:Geometric intermediaries connecting rigid and flexible sections require complex mandrel tooling that lacks transferability across platform families.
- Insulated Ducts:Multi-layer laminates with integrated thermal barriers address FAA Part 25 flammability requirements in bleed air routing near pressure bulkheads.
Rigid Ducts sits at the top of the volume ranking, with Flexible Ducts climbing the fastest.
Material:
Cost tier stratification separates premium fiber grades from volume-optimized alternatives, with qualification timelines locking in material choices for entire program generations.
- Carbon Fiber:High-modulus prepregs deliver specific strength ratios essential for military exhaust systems and high-temperature engine applications. NAVAIR procurement specifications for F-35 and next-generation fighter programs mandate these grades despite acrylonitrile precursor cost volatility.
- Thermoplastic:PEEK and PEKK matrix systems enable out-of-autoclave processing with cycle time compression exceeding 60% versus thermoset alternatives. Airbus A350 thrust reverser bypass ducts specify these materials for service temperatures above 180 degrees Celsius.
- Glass Fiber:Cost-optimized E-glass and S-glass prepregs penetrate regional jet and general aviation platforms where carbon fiber premiums remain economically unjustified.
- Aramid Fiber:Kevlar-reinforced laminates provide impact resistance and damage tolerance in rotorcraft ducting subject to foreign object debris exposure.
Carbon Fiber commands the premium price tier, while Thermoplastic materials are gaining share fastest through process economics.
End User:
Customer-type concentration shapes contracting structures, with defense procurement imposing ITAR constraints that segment engineering teams and facility clearances.
- Civil Aviation:Commercial OEM production at Boeing and Airbus drives recurring demand for narrow-body and wide-body shipsets, with direct airline engagement at Southwest and Ryanair compressing traditional tier-1 intermediaries.
- Military Aviation:Defense Logistics Agency and NAVAIR procurement channels require segmented supply chains with facility clearances, filtering eligible producers for fighter and rotorcraft programs.
- Space Exploration:Launch vehicle ducting for cryogenic propellant management demands ultra-low permeability laminates with limited supplier base.
- Aerospace Maintenance:MRO facilities at Delta TechOps and Lufthansa Technik extend metallic duct service life through weld repair, delaying composite replacement cycles in aging fleets.
Civil Aviation dominates absolute demand, with Military Aviation showing the steepest expansion trajectory through defense modernization programs.
Application:
Functional segmentation maps directly to thermal and pressure operating regimes, with each subsystem imposing distinct flammability and smoke toxicity requirements.
- Air Distribution:Environmental control system ducting transports conditioned cabin air across pressure bulkheads, requiring EASA CS-25 Amendment 25-23 compliance for optical smoke density and toxic gas generation.
- Exhaust Systems:Engine bleed air and thrust reverser bypass ducts encounter the most severe thermal environments, driving thermoplastic adoption for temperature thresholds above 180 degrees Celsius.
- Air Conditioning:Pack inlet and outlet ducting in compact nacelle geometries favors flexible composite solutions with adaptive routing capability.
- Fuel Delivery:Fuel vapor and inerting system ducting demands electrostatic discharge resistance and permeation barriers distinct from pneumatic applications.
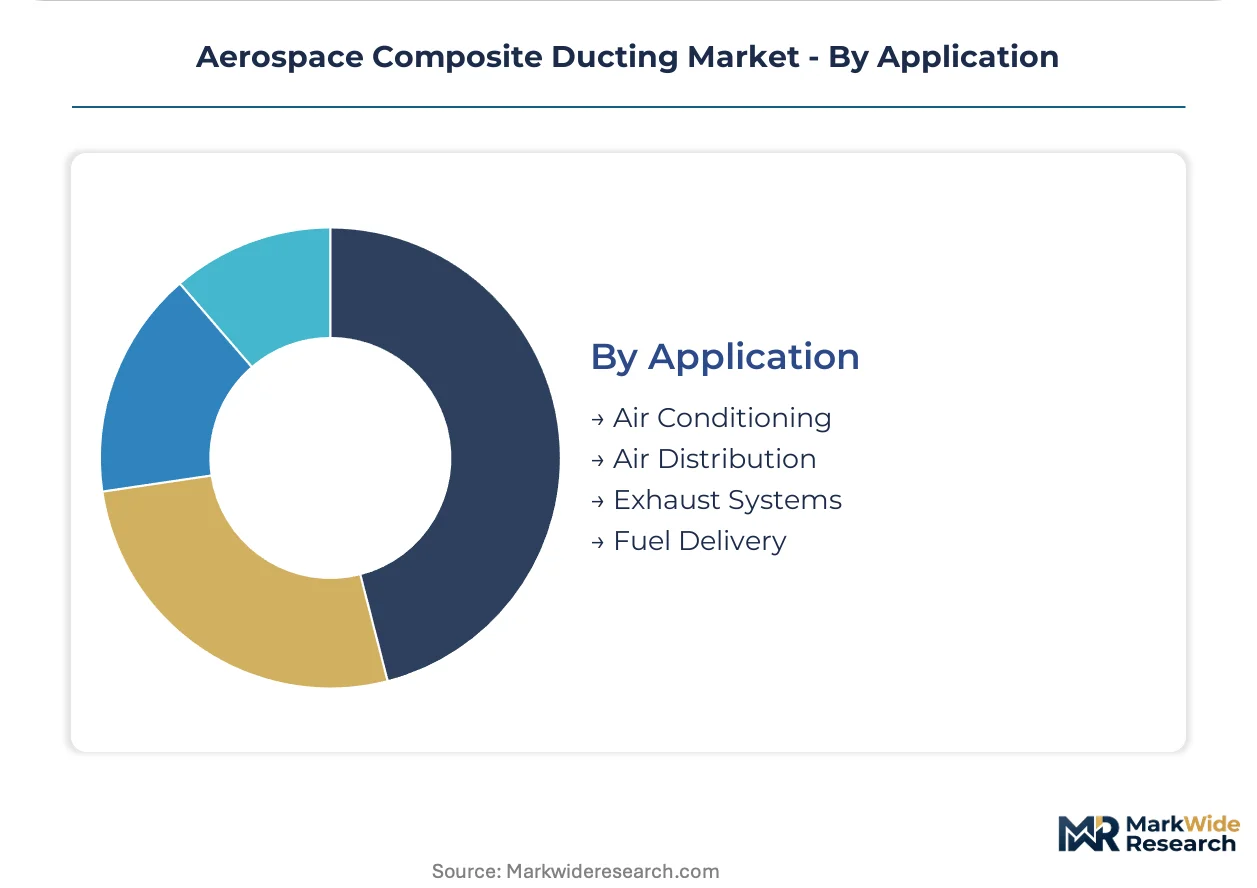
Air Distribution captures the largest installed base, with Exhaust Systems expanding most quickly through engine thermal management intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping composite ducting procurement as suppliers migrate capacity toward jurisdictions with streamlined FAA-EASA bilateral certification pathways, reducing duplicative qualification costs for dual-market platforms.
United States
Boeing 737 MAX and 787 production ramps in Renton and Charleston sustain procurement volumes for bleed air and environmental control system ducts. FAA Part 25 Amendment 25-116 enforcement tightens flammability compliance timelines, favoring domestic suppliers with established DER relationships. Washington state hosts concentrated autoclave capacity for large-diameter engine nacelle ducts, creating geographic clustering around Everett and Auburn manufacturing corridors.
France
Airbus A320neo and A350 final assembly lines in Toulouse and Hamburg anchor European demand for thermoplastic composite ducts in thrust reverser applications. EASA CS-25 Amendment 25-23 mandates optical smoke density testing per ASTM E662 for all pressure bulkhead penetrations, accelerating low-smoke phenolic resin qualifications. The Toulouse-Blagnac aerocluster integrates Stelia Aerospace and upstream prepreg converters within a 50-kilometer supply radius.
Germany
Premium automotive composite expertise in Bavaria and Baden-Württemberg transfers into aerospace ducting through shared thermoplastic processing infrastructure. REACH Annex XVII scrutiny of halogenated flame retardants drives bio-based resin development programs at Fraunhofer institutes in Augsburg and Stuttgart. Munich-based engineering consultancies specialize in out-of-autoclave process qualification for reduced cycle time manufacturing.
United Kingdom
Defense modernization through the Royal Air Force Tempest program channels ITAR-equivalent procurement for fighter exhaust system ducts. Senior Aerospace maintains manufacturing presence in the Midlands for complex engine bleed air geometries serving European and North American OEMs. The UK Civil Aviation Authority alignment with EASA post-Brexit preserves single-market certification access for composite duct suppliers.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries integrate composite ducting into regional jet and defense platforms, sourcing PEEK and PEKK matrices from domestic polymer compounders. METI industrial policy supports thermoplastic composite recycling infrastructure development in Nagoya and Osaka manufacturing belts. JIS standard harmonization with ISO 2685 fire resistance protocols streamlines export qualification for Southeast Asian MRO markets.
Aerospace Composite Ducting Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue thermoplastic processing specialization and out-of-autoclave capability. The supplier base concentrates around three archetypes: integrated motion and control conglomerates with fluid conveyance portfolios, aerostructures specialists with captive composite ducting divisions, and pure-play ducting manufacturers with design certification authority. Competitive moves center on capacity alignment with Boeing-Airbus production rate signals and technology licensing partnerships for thermoplastic welding processes.
Among North American fabricators, Parker-Hannifin Corporation exemplifies the integrated systems conglomerate archetype, while AIM Aerospace occupies a position within the Pacific Northwest aerostructures cluster. Senior Aerospace represents the European specialist tier with complex geometry capabilities. These three anchors illustrate divergent strategic postures: conglomerate breadth versus regional manufacturing concentration versus niche technical specialization.
| Leading Market Players |
|---|
| Parker-Hannifin Corporation |
| AIM Aerospace |
| Senior Aerospace |
| Saint-Gobain Performance Plastics |
| Stelia Aerospace |
| Triumph Group |
| Arrowhead Products |
| Eaton Aerospace |
| ITT Corporation |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile precursor costs flow through carbon fiber prepregs to compress margin predictability for converters serving Boeing and Airbus under long-term contracts, with thermoplastic material premiums widening the spread between rigid and flexible duct tiers.
Pricing Analysis
Distributor margins in legacy thermoset supply chains face compression as direct airline engagement at Southwest and Ryanair eliminates tier-1 intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber military grades from glass fiber regional jet alternatives and thermoplastic engine applications. Pricing pressure stems from acrylonitrile feedstock volatility tied to oil and natural gas markets. Defense procurement through NAVAIR shows least price sensitivity; regional jet operators exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Washington state autoclave clusters for large-diameter engine nacelle ducts, where Everett and Auburn corridors host irreplaceable curing capacity. Geographic concentration spans the United States, France, and Germany for qualified prepreg conversion. Raw material dependencies center on acrylonitrile precursors, PEEK and PEKK polymer feedstocks, and halogenated flame retardant additives. Tariff exposure on Chinese carbon fiber imports threatens cost structures. Distribution runs through OEM direct procurement and aerostructures tier-1 integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic processing economics and out-of-autoclave cycle time compression create margin expansion headroom as suppliers capture premium tiers from slower thermoset competitors.
For Market Incumbents: Lock in DER relationships with FAA Part 25 fireworthiness certification authority to constrain competitor qualification timelines. Deepen backward integration into PEEK and PEKK polymer compounding to insulate margins from specialty chemical supply shocks. Threat substitution from metallic duct refurbishment at Delta TechOps and Lufthansa Technik demands proactive fleet replacement programs. For New Entrants and Emerging Players: Out-of-autoclave thermoplastic welding expertise offers entry into eVTOL thermal management ducting where Joby Aviation and Archer Aviation lack incumbent supplier relationships. White-space targets include urban air mobility distributed propulsion systems and REACH-compliant bio-based resin formulations for EASA CS-25 certification. Go-to-market angle: direct technical engagement with airline engineering departments disintermediating traditional tier-1 channels. For Investors and Strategic Acquirers: Consolidation pressure builds where ITAR facility clearances and FAA DER scarcity fragment viable acquisition targets. Long-term viability favors suppliers with dual-use civil-military certification infrastructure and thermoplastic process IP. Target archetype: pure-play ducting manufacturers with in-house design authority. Signal to watch: Boeing-Airbus production rate divergence stranding platform-specific tooling capital.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Process Qualification | PEEK and PEKK welding expertise unlocks A350 and 787 thrust reverser bypass contracts. |
| Out-of-Autoclave Capacity Expansion | Oven-curable systems reduce cycle times 60% versus legacy autoclave-dependent supply chains. |
| Bio-Based Resin Development | REACH Annex XVII compliance accelerates EASA CS-25 certification advantages for first movers. |
| Direct Airline Engagement | Southwest and Ryanair vendor consolidation rewards suppliers with integrated system responsibility. |
| ITAR Facility Clearance Investment | NAVAIR and Defense Logistics Agency procurement filters eligible producers for fighter programs. |
Methodological Framework
Bottom-up aircraft program modeling reconciled against top-down prepreg converter capacity tracking forms the analytical core. Primary interviews with DER certification engineers, OEM platform procurement managers, airline engineering directors, and thermoplastic process R&D leads combined with secondary validation against FAA airworthiness directives, EASA CS-25 amendment filings, SEC 10-K aerostructures disclosures, and REACH regulatory updates. Triangulation between shipset demand projections and supply-side capital expenditure announcements ensures coherence.
Input-output matrices map duct counts per shipset across narrow-body, wide-body, and military platforms to material throughput at qualified prepreg converters. Segmentation dimensions include product architecture, fiber grade, matrix chemistry, end-user procurement channel, and thermal operating regime. CAGRs derive from production rate scenarios at Renton, Charleston, Toulouse, and Hamburg final assembly lines, cross-referenced against defense modernization program announcements. Industry-specific forecast inputs incorporate thermoplastic adoption curves and flammability standard amendment timelines.
The model holds under stable Boeing-Airbus production rate convergence; deviation in OEM order volatility or acrylonitrile feedstock shocks would shift capacity utilization assumptions. Forecasts reflect documented platform delivery schedules, regulatory amendment implementation dates, and disclosed supplier capital commitments. Specific risk factors include REACH chemical restriction scope expansion and ITAR technical data segmentation requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market