
 Middle-East and Africa Aerospace Composites Market | 2026-2036
Middle-East and Africa Aerospace Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aerospace Composites Market Foresight
Direct OEM supply agreements is reconfiguring how aerospace composite manufacturers access defense and commercial aviation programs across the Middle-East and Africa. Hexcel Corporation leverages its prepreg technology leadership to anchor long-term contracts with Gulf-based MRO facilities. Solvay SA sustains a differentiated position through specialized resin formulations tailored to regional temperature extremes. Toray Industries Inc competes on carbon fiber volume scale, extending its supply reach into emerging African aerospace maintenance hubs.
Middle-East and Africa aerospace composites are fiber-reinforced polymer materials engineered to withstand operational loads from minus 55 degrees Celsius to over 150 degrees Celsius while reducing airframe weight by 20 percent versus aluminum alloys. These materials primarily serve to improve fuel efficiency and extend aircraft range in high-temperature desert operating environments. Carbon fiber products dominate value capture given their stiffness-to-weight ratios in primary airframe structures, while thermoplastic composites represent the fastest-expanding category due to shorter processing cycles and recyclability advantages. Within applications, interior components constitute a mature margin pool driven by cabin retrofit cycles across Emirates and Qatar Airways fleets, whereas engine components command premium positioning due to thermal management requirements.
The UAE's General Civil Aviation Authority maintains alignment with EASA certification standards, while Saudi Arabia's Saudi Standards, Metrology and Quality Organization develops national technical regulations for defense procurement. South Africa's National Regulator for Compulsory Specifications enforces structural material standards for its domestic aerospace manufacturing base. Stakeholders must monitor how Gulf sovereign wealth fund investments in domestic MRO capacity reshape supplier qualification timelines and local content requirements.
Market Dynamics
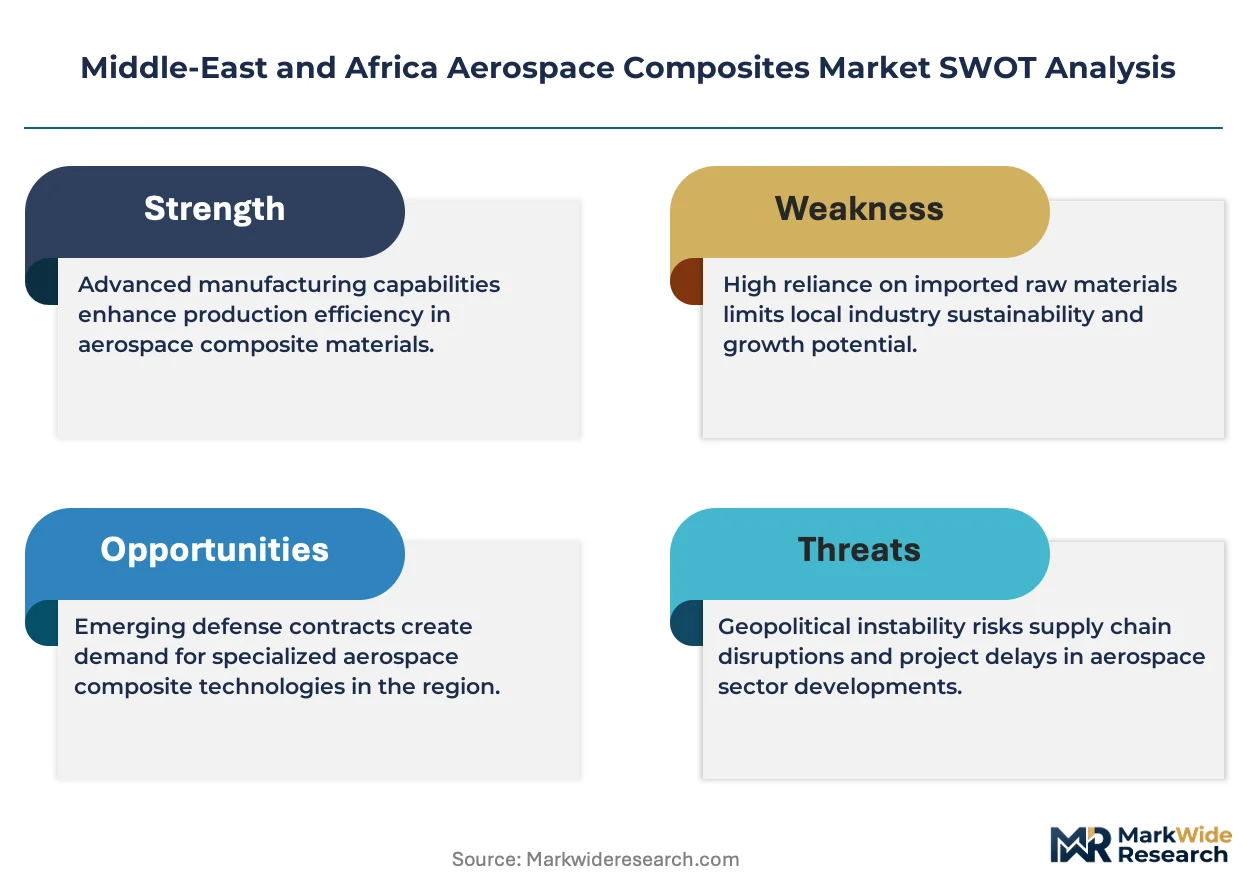
Gulf sovereign wealth fund capital injections into domestic MRO infrastructure are restructuring supplier qualification pathways and compressing procurement timelines for composite material vendors across the Middle-East and Africa.
Growth Catalysts
- Military Aviation Procurement:GCC defense modernization programs mandate lightweight structural materials for next-generation fighter and transport aircraft fleets.
- EASA Alignment:The UAE's General Civil Aviation Authority certification harmonization with European standards accelerates material qualification for regional suppliers.
- Thermoplastic Adoption:Shorter processing cycles and recyclability advantages drive replacement of thermoset systems in high-volume interior applications.
Market Restraints
- Carbon Fiber Supply Concentration:Precursor material production clusters in East Asia create input cost volatility and freight exposure for regional converters.
- Autoclave Capacity Scarcity:Large-diameter autoclave infrastructure remains concentrated in legacy aerospace manufacturing centers outside the region.
- Aluminum-Lithium Substitution:Third-generation Al-Li alloys compete for primary airframe applications where damage tolerance requirements exceed composite capabilities.
Strategic Opportunities
- South African Cluster Development:The country's aerospace manufacturing base offers underpenetrated entry points for prepreg distributors serving sub-Saharan maintenance hubs.
- Digital Thread Integration:Convergence of automated fiber placement with in-situ thermography enables real-time quality assurance for defense procurement.
- Saudi Localization Mandates:Vision 2030 domestic content requirements create qualified supplier status incentives for composite manufacturers establishing in-Kingdom production.
Industry Challenges
- Specialized Technician Shortage:Vacuum infusion and automated fiber placement operations lack sufficient trained workforce pools in emerging African aerospace hubs.
- Qualification Timeline Compression:Saudi Standards, Metrology and Quality Organization defense procurement cycles demand accelerated material certification without parallel track waivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aerospace Composites Market |
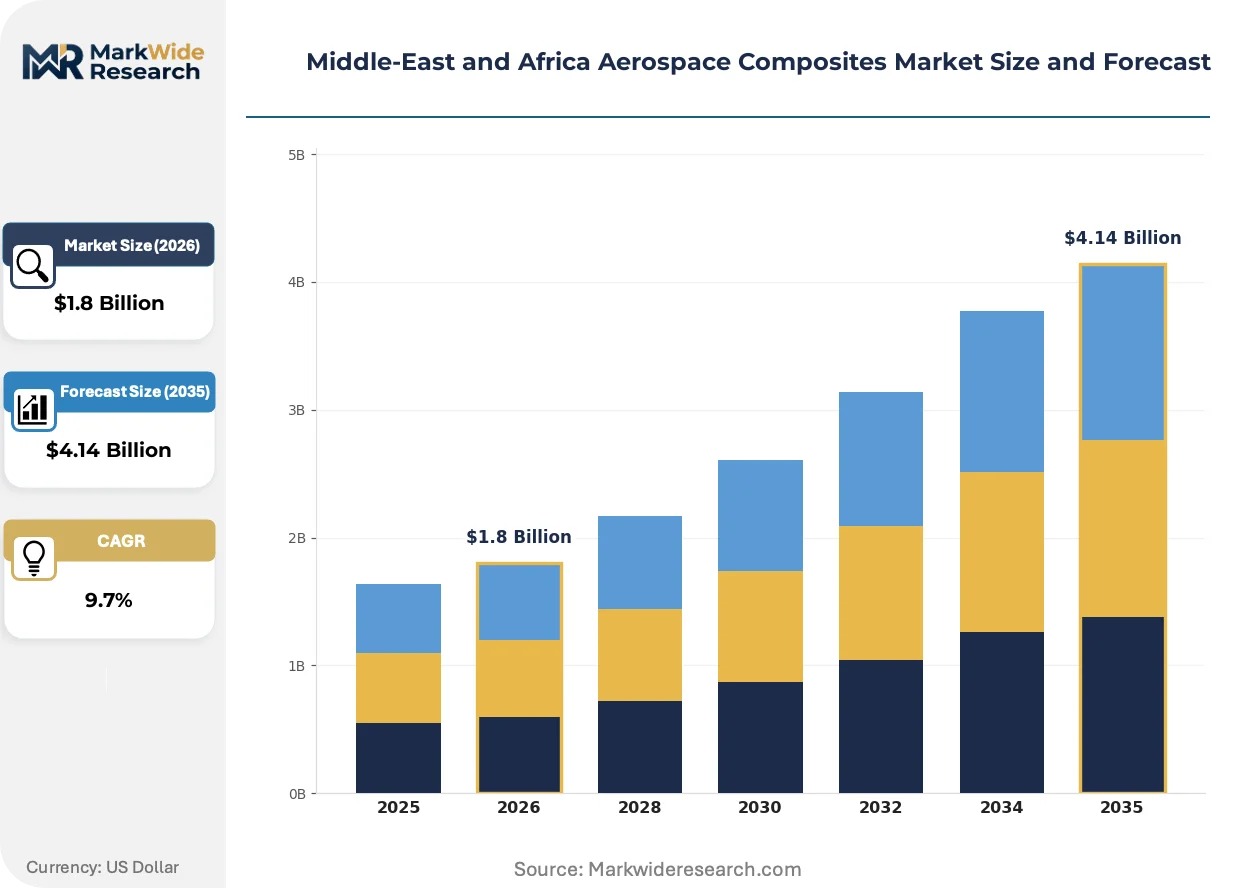
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Thermoplastic Composites Application: Airframe, Interior Components, Engine Components, Control Surfaces End User: Commercial Aviation, Military Aviation, Space Exploration, Unmanned Aerial Vehicles Manufacturing Process: Hand Lay-Up, Resin Transfer Molding, Prepreg Lay-Up, Filament Winding |
| Companies Covered | Hexcel Corporation, Solvay SA, DuPont de Nemours Inc, Kaman Corporation, Saint-Gobain SA, Toray Industries Inc, Notus Composites, Veplas Group, Victrex PLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aerospace Composites Market Shifts & Advancements
Digital manufacturing architectures and regulatory harmonization are compressing development cycles for high-temperature composite systems designed for desert operating environments across Middle-East and Africa aviation programs.
Out-of-autoclave thermoset prepregs are virtualizing traditional autoclave-dependent processing for large structural components. Saudi Arabia's Saudia Technic MRO expansion and emerging African maintenance hubs adopt these systems to bypass capital-intensive pressure vessel infrastructure. This shift is virtualizing the barrier between low-volume prototype and production-scale manufacturing.
Saudi Standards, Metrology and Quality Organization technical regulations for defense procurement are formalizing national material qualification pathways distinct from EASA-aligned civil frameworks. Industrial consequence includes bifurcated certification requirements for suppliers serving dual-use applications. Defense airframe segments face extended validation timelines as they navigate parallel civil-military approval tracks.
Airline fleet retrofit cycles for Emirates and Qatar Airways are compressing interior component replacement intervals from seven-year to five-year cycles. Traditional spot-buy procurement through tier-two distributors is yielding to direct OEM supply agreements with composite manufacturers holding line-fit approvals. This pattern concentrates most visibly in UAE-based MRO facilities managing A380 and 777 cabin reconfiguration programs.
Middle-East and Africa Aerospace Composites Market Segmentation
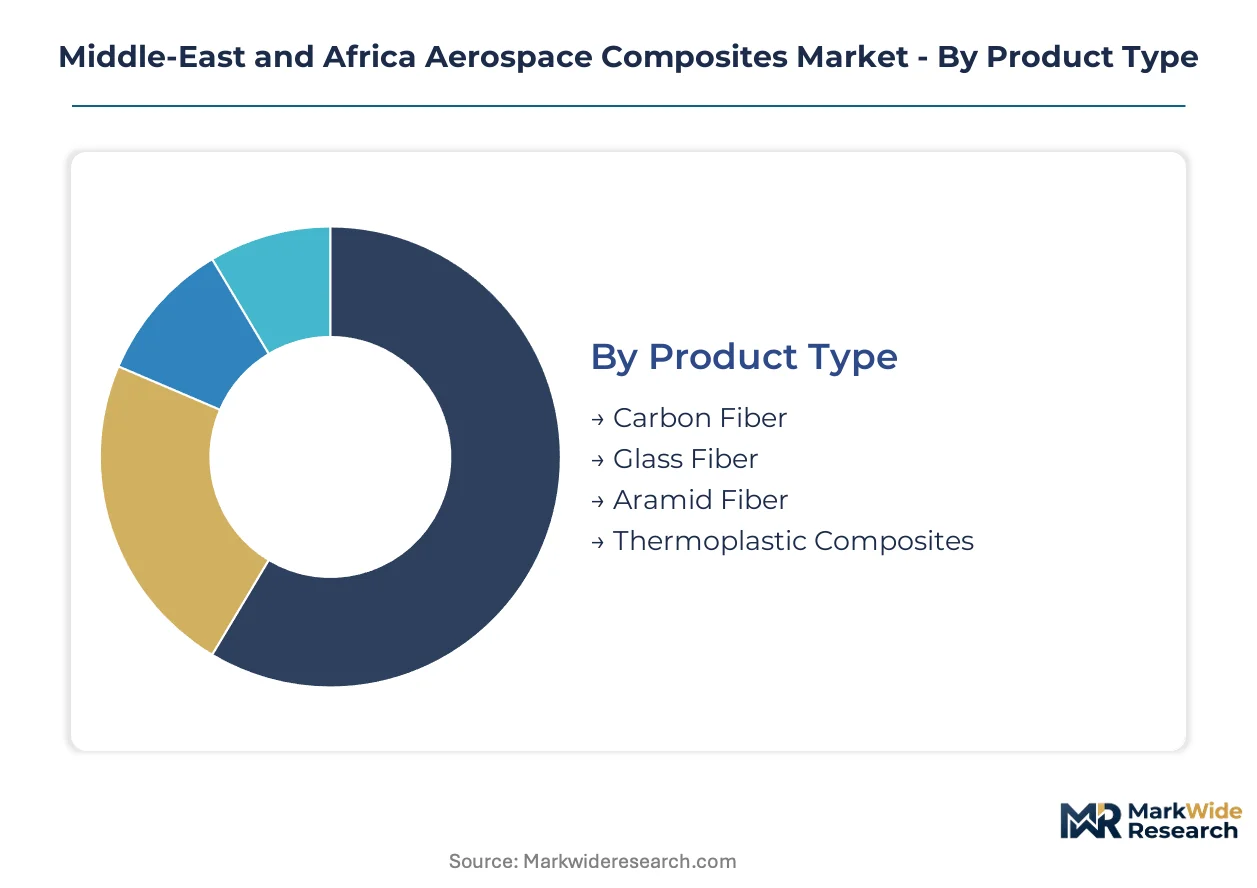
Segmentation reveals how material specifications, manufacturing constraints, and end-use requirements fragment procurement patterns across Middle-East and Africa aerospace programs. Each dimension exposes distinct margin pools and qualification barriers for composite suppliers.
Product Type:
Material selection spans stiffness-to-weight optimization, thermal resilience, and processing economics across desert operating environments and defense procurement cycles.
- Carbon Fiber:High-modulus PAN-based and pitch-based variants deliver specific stiffness ratios exceeding aluminum by 40 percent. Primary structures for Saudi fighter modernization and UAE commercial fleet retrofits concentrate demand in T800H and IM7 grades.
- Thermoplastic Composites:PEEK and PPS matrices enable sub-10-minute processing cycles versus 90-minute thermoset cures. Emirates MRO facilities adopt these for high-volume interior bracket production where recyclability mandates tighten.
- Glass Fiber:E-glass and S-glass reinforcements serve secondary structures and radome applications where electromagnetic transparency overrides stiffness requirements.
- Aramid Fiber:Kevlar and Twaron hybrids absorb impact energy in engine nacelles and control surface leading edges across Qatar Airways maintenance programs.
The dominant share belongs to carbon fiber, while thermoplastic composites are closing the gap fastest.
Application:
Structural versus non-structural deployment determines certification burden, damage tolerance thresholds, and supplier qualification depth.
- Interior Components:Sidewall panels, overhead bins, and galley structures utilize fire-resistant phenolic and thermoplastic systems. Five-year retrofit cycles at Emirates and Qatar Airways compress procurement timelines for line-fit approved suppliers.
- Engine Components:Fan blades, cowls, and thrust reversers endure thermal cycling from minus 55 to 150 degrees Celsius. Saudi defense procurement mandates ceramic matrix composite inserts for afterburner sections.
- Airframe:Fuselage barrels and wing boxes require automated fiber placement with in-situ consolidation. EASA-aligned UAE certification accelerates material qualification for these primary structures.
- Control Surfaces:Ailerons, flaps, and rudders balance aerodynamic load with lightning strike protection through copper mesh integration.
Interior components command volume leadership, yet engine components generate the steepest margin expansion.
End User:
Customer archetypes diverge sharply in technical specification, procurement protocol, and localization requirements.
- Military Aviation:Saudi Standards, Metrology and Quality Organization regulations impose distinct qualification tracks parallel to civil frameworks. Fighter and transport programs mandate damage-tolerant toughened resin systems.
- Commercial Aviation:Emirates, Qatar Airways, and Saudia fleet expansion drives line-fit and retrofit demand for lightweight cabin systems. EASA alignment through UAE GCAA streamlines supplier entry.
- Unmanned Aerial Vehicles:Surveillance and combat drone programs across the GCC prioritize cost-optimized glass fiber and thermoplastic constructions.
- Space Exploration:Satellite bus structures and launch vehicle fairings represent nascent demand concentrated in South African and UAE emerging programs.
Military aviation absorbs the largest procurement value, though unmanned aerial vehicles are expanding most quickly.
Manufacturing Process:
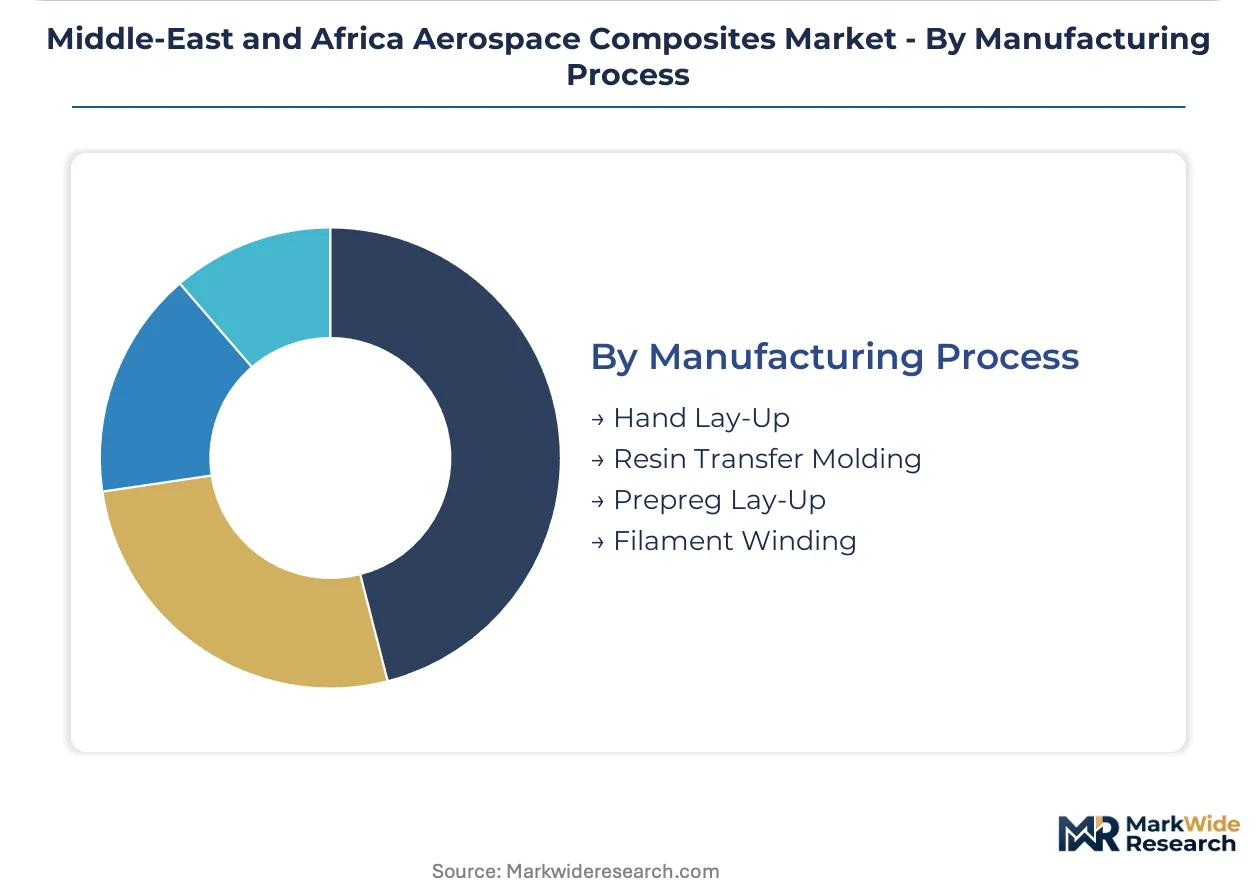
Process selection trades capital intensity against production rate, part complexity, and void content tolerance.
- Prepreg Lay-Up:Autoclave-cured unidirectional tapes and fabrics dominate primary airframe structures. Saudi MRO expansion and African maintenance hubs face autoclave capacity scarcity for large-diameter components.
- Resin Transfer Molding:Closed-mold infusion enables complex geometry production with reduced volatile emissions. South African aerospace clusters adopt RTM for control surface manufacturing.
- Hand Lay-Up:Open-mold wet lay-up persists in prototype and low-rate production where tooling investment must minimize.
- Filament Winding:Automated fiber deposition produces pressure vessels and cylindrical structures for space applications and auxiliary power units.
Prepreg lay-up retains process leadership, while resin transfer molding is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in UAE and Saudi Arabia, where defense procurement scales and MRO infrastructure investments outpace African maintenance hubs still negotiating supplier qualification timelines.
United Arab Emirates
Emirates and Etihad fleet retrofits drive carbon fiber demand for A380 and 777 cabin reconfigurations. The General Civil Aviation Authority maintains EASA alignment, compressing material qualification pathways for composite suppliers. Dubai-based MRO facilities anchor regional distribution for prepreg systems serving Gulf commercial aviation.
Saudi Arabia
Saudia Technic expansion and fighter modernization programs concentrate demand for high-modulus carbon fiber in Riyadh and Eastern Province clusters. The Saudi Standards, Metrology and Quality Organization develops parallel defense certification tracks distinct from civil frameworks. Vision 2030 localization mandates reshape supplier entry requirements for in-Kingdom production.
South Africa
Sub-Saharan maintenance hub development and satellite bus manufacturing generate thermoplastic composite demand in Gauteng and Western Cape aerospace clusters. The National Regulator for Compulsory Specifications enforces structural material standards for domestic manufacturing. Cape Town's aerospace corridor offers underpenetrated entry points for prepreg distributors.
Qatar
Qatar Airways five-year interior retrofit cycles compress procurement timelines for fire-resistant phenolic systems. The Qatar Civil Aviation Authority coordinates with EASA for streamlined supplier qualification. Doha-based MRO facilities specialize in control surface maintenance requiring aramid fiber hybrids.
Israel
Surveillance and combat drone programs prioritize cost-optimized glass fiber constructions for unmanned platforms. The Israel Civil Aviation Authority maintains distinct defense-civil regulatory frameworks for composite qualification. Tel Aviv-area engineering clusters concentrate on automated fiber placement for military airframe segments.
Middle-East and Africa Aerospace Composites Market Competitive Landscape
Prepreg technology leaders and resin formulation specialists split the market along material science differentiation vectors. The supplier base concentrates around three strategic archetypes: carbon fiber producers competing on precursor scale, thermoplastic innovators capturing processing efficiency premiums, and integrated composite manufacturers controlling qualification pathways. Dominant competitive moves include backward integration into precursor production and strategic partnerships with Gulf-based MRO facilities to secure long-term offtake agreements.
Within the integrated materials tier, Hexcel Corporation and Solvay SA exemplify divergent positioning strategies. Hexcel anchors prepreg supply relationships through technology licensing frameworks, while Solvay occupies a specialized position in high-temperature resin systems. Toray Industries Inc represents the scale-driven archetype, leveraging carbon fiber volume capabilities to extend distribution reach into emerging African maintenance infrastructure.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Solvay SA |
| DuPont de Nemours Inc |
| Kaman Corporation |
| Saint-Gobain SA |
| Toray Industries Inc |
| Notus Composites |
| Veplas Group |
| Victrex PLC |
| Others |
Supply & Pricing Matrix
Riyadh's Eastern Province industrial clusters concentrate autoclave-cured prepreg capacity for Saudi defense programs, concentrating pricing power with Hexcel and Solvay for high-modulus carbon fiber grades. This geographic concentration forces African maintenance hubs into longer qualification timelines and premium freight absorption for T800H and IM7 material inputs.
Pricing Analysis
The customization-premium spread between configured-to-order defense specifications and standard commercial grades exceeds three-to-one for primary airframe structures. Pricing stratifies across EASA-aligned civil certification, Saudi Standards parallel military tracks, and spot-buy distributor tiers. Cost compression in standard-grade thermoset prepregs is intensifying because Emirates and Qatar Airways fleet retrofit cycles compress procurement timelines. Commercial aviation procurement teams exhibit highest price sensitivity, while Saudi fighter modernization programs prioritize damage-tolerant resin systems over unit cost.
Supply Chain Analysis
Upstream acrylonitrile and pitch precursor production draws from Japan, the United States, and South Korean petrochemical complexes. PAN-based carbon fiber tow, PEEK thermoplastic resin, and toughened epoxy systems feed regional conversion at Saudia Technic and Dubai MRO facilities. Single-source vulnerability concentrates in large-diameter autoclave infrastructure, with no in-region capacity exceeding five-meter diameter. Distribution runs through direct OEM supply agreements displacing tier-two distributor channels for line-fit approved suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technician scarcity for automated fiber placement and vacuum infusion operations constrains production scale-up across Gulf MRO expansions and emerging African aerospace hubs. This capability gap defines competitive moats and acquisition premiums for firms holding trained workforce pools.
For Market Incumbents: Pre-empt thermoplastic composite adoption by securing PEEK and PPS resin supply agreements before qualification timelines compress further. Backward integration into precursor production hedges against East Asian carbon fiber supply volatility. Anchor long-term offtake with Saudia Technic and Emirates MRO facilities to lock out resin formulation specialists seeking Gulf market entry.
For New Entrants and Emerging Players: South African aerospace clusters in Gauteng and Western Cape offer underpenetrated entry points for prepreg distributors serving sub-Saharan maintenance hubs. Target thermoplastic interior bracket production where five-year retrofit cycles at Qatar Airways generate volume pull-through. Secure line-fit approval from the UAE General Civil Aviation Authority to bypass tier-two distributor margin extraction.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-civil dual-use materials play because Saudi Vision 2030 localization mandates and GCC fighter modernization programs create structural demand for qualified suppliers. Acquisition targets should exhibit in-Kingdom production assets and parallel civil-military certification capabilities. Watch for accelerated material qualification timeline compression as the Saudi Standards, Metrology and Quality Organization formalizes national technical regulations distinct from EASA frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile supply hedges Hexcel and Toray against East Asian input cost volatility. |
| In-Kingdom Manufacturing Establishment | Vision 2030 domestic content requirements reward Solvay with qualified supplier status for defense procurement. |
| Thermoplastic Processing Technology Licensing | Sub-10-minute PEEK cycle times enable Emirates MRO facilities to bypass autoclave capacity constraints. |
| Direct OEM Supply Agreement Conversion | Line-fit approvals with Qatar Airways compress procurement timelines and displace tier-two distributors. |
| Parallel Civil-Military Certification Investment | Dual-track qualification with Saudi Standards and UAE GCAA unlocks fighter and commercial retrofit demand. |
Research Methodology
A standing panel of prepreg manufacturing directors, MRO procurement leads at Emirates and Saudia Technic, defense program managers within Saudi Standards oversight, and thermoplastic composite R&D heads provided ongoing calibration across primary fieldwork. Secondary validation drew from EASA certification databases, Saudi Standards technical regulation filings, UAE GCAA airworthiness directives, and customs records of carbon fiber tow imports into Jeddah and Dubai. Bottom-up volume modeling of individual aerospace programs triangulated against top-down composites intensity benchmarks.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions spanned fiber type, application category, end-user archetype, and manufacturing process route. CAGRs derived from segment-level volume build-ups incorporating fleet expansion schedules, retrofit cycle compression, and defense procurement timelines. Forecast inputs included thermal cycling performance requirements for desert operating environments and qualification pathway divergence between EASA-aligned civil and Saudi military tracks.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by East Asian carbon fiber producers or accelerated thermoplastic substitution by Emirates would shift outcomes beyond modeled ranges. Cross-checking against EASA material certification databases and Saudi defense procurement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerographene Market