
 Aircraft Actuator Market | 2026-2036
Aircraft Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Actuator Market Intelligence
DO-160G environmental qualification tiers is bifurcating the competitive landscape as OEMs demand higher vibration and temperature resilience for next-generation platforms. Honeywell International Inc. leverages its integrated avionics-actuator architectures to capture positions on Boeing and Airbus programs. Parker-Hannifin Corporation anchors the hydraulic-to-electric transition through its flight control actuation systems. Safran SA competes on electromechanical specialization for narrowbody landing gear applications.
An aircraft actuator is a mechanical or electromechanical device that converts electrical, hydraulic, or pneumatic energy into controlled physical motion to position flight control surfaces, landing gear, or engine components, typically operating at pressures exceeding 3,000 psi in hydraulic configurations and requiring MIL-STD-810 environmental compliance. Its primary purpose is to enable precise, redundant control of critical aircraft functions under extreme altitude and temperature conditions. Electric actuator configurations are capturing margin pools as more-electric aircraft programs displace centralized hydraulic distribution architectures. Flight control systems applications dominate installed value, while unmanned aerial vehicle platforms represent the fastest-growing aircraft type segment as military and commercial drone fleets expand. Landing gear actuation sustains above-average pricing due to fail-operate redundancy requirements and overhaul cycles tied to airframe utilization rates.
FAA airworthiness standards under 14 CFR Part 25, EASA CS-25 certification requirements, and DO-178C software assurance guidelines collectively govern actuator design verification and market access for civil aviation applications. These frameworks mandate fault-tolerant architectures and traceable supply chain documentation that elevate engineering barriers for new entrants. Stakeholders must monitor the divergence between FAA and EASA electromechanical certification timelines as this gap shapes platform development budgets and supplier qualification schedules.
Market Dynamics
The transition from centralized hydraulic architectures to distributed electromechanical actuation systems is restructuring supplier relationships and qualification requirements across commercial aviation programs.
Growth Catalysts
- More-Electric Aircraft Mandates:FAA 14 CFR Part 25 airworthiness standards and EASA CS-25 certification frameworks are accelerating electromechanical actuator adoption on next-generation narrowbody platforms.
- Flight Control Surface Electrification:Primary flight control systems are replacing hydraulic servoactuators with electromechanical alternatives to reduce weight and maintenance intervals.
- Unmanned Aerial Vehicle Proliferation:Military and commercial drone fleet expansion is generating actuator demand for control surfaces, landing gear, and payload positioning systems.
Market Restraints
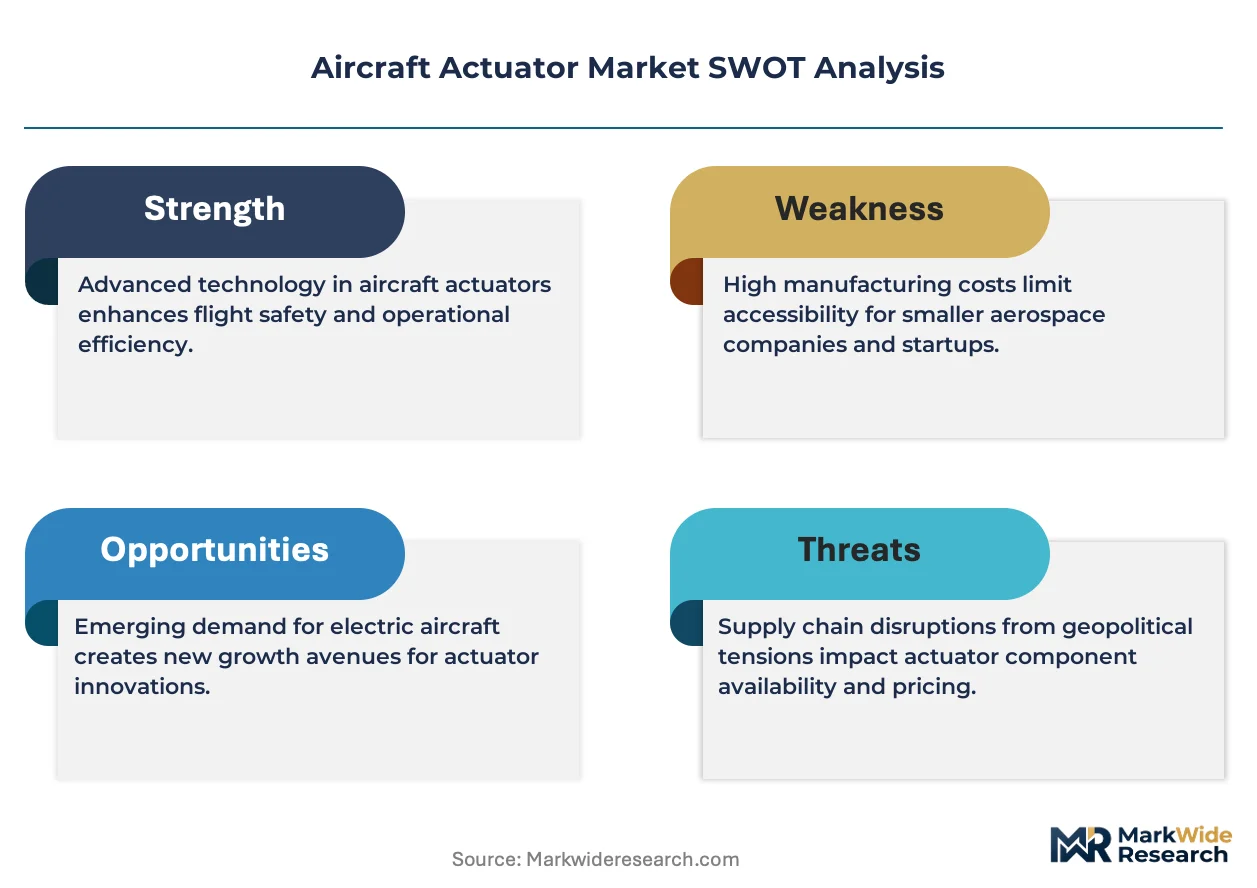
- Specialized Alloy Supply Concentration:Titanium and high-grade aluminum sourcing for actuator housings concentrates among a limited supplier base, creating input cost volatility.
- DO-178C Certification Burden:Software assurance guidelines for safety-critical control systems extend development timelines and elevate engineering costs for new market entrants.
- Hydraulic System Legacy Lock-in:Existing widebody fleets with decades of remaining service life sustain demand for hydraulic actuator spares, fragmenting R&D investment.
Strategic Opportunities
- Urban Air Mobility Integration:eVTOL platforms require compact, fault-tolerant electromechanical actuators for distributed propulsion and flight control architectures.
- Aftermarket Service Unbundling:Airlines are separating actuator overhaul contracts from airframe maintenance agreements, creating direct supplier-to-operator channels.
- India Defense Modernization:Indigenous fighter and transport programs under the country's defense procurement framework are qualifying domestic actuator suppliers.
Industry Challenges
- Embedded Software Talent Scarcity:DO-178C-qualified firmware engineers remain concentrated among incumbent suppliers, constraining development velocity.
- Multi-Platform Integration Complexity:Actuator suppliers must maintain parallel qualification tracks for Boeing, Airbus, and COMAC airframe specifications simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Actuator Market |
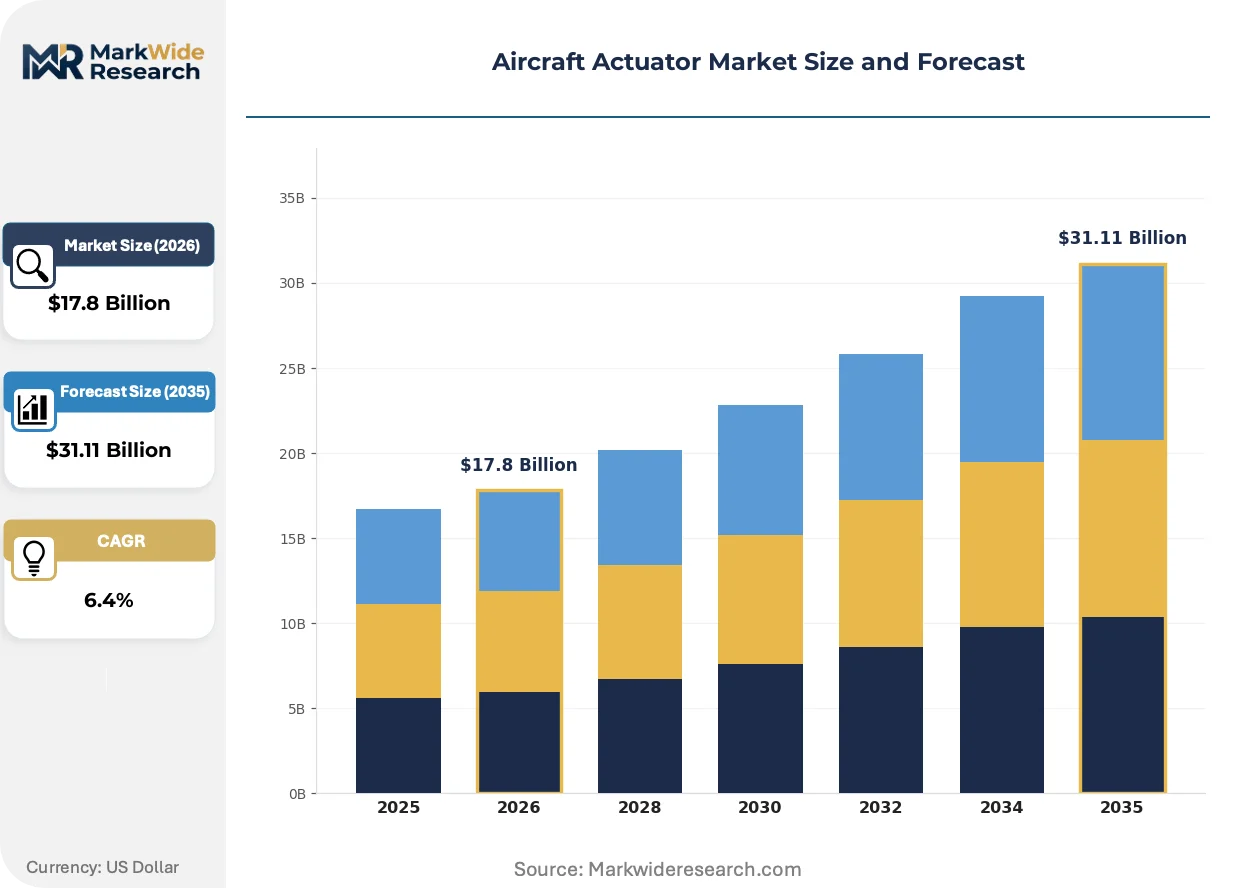
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Actuator Type: Electric, Hydraulic, Pneumatic, Electro-Hydraulic, Electro-Mechanical Aircraft Type: Commercial, Military, Business Jet, Unmanned Aerial Vehicle, Regional Application: Flight Control Systems, Landing Gear, Cargo Doors, Thrust Vectoring, Brake Systems, Environmental Control End User: Aircraft Manufacturers, Maintenance Providers, Retrofitters, Defense Contractors, Airlines |
| Companies Covered | Honeywell International Inc., Moog Inc., Parker-Hannifin Corporation, Safran SA, Collins Aerospace, Curtiss-Wright Corporation, Liebherr Group, AMETEK Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Actuator Market Strategic Shifts & Innovations
Power-by-wire architectures are collapsing the traditional boundary between flight control computers and surface actuators, demanding new competencies in electromechanical integration and thermal management.
Electromechanical actuator technology is supplanting hydraulic configurations in primary flight control applications. Commercial OEMs are embedding these systems on next-generation narrowbody programs to eliminate centralized hydraulic distribution. This transition is compressing the addressable market for hydraulic component specialists while expanding margin pools for integrated electromechanical suppliers.
EASA certification timelines for electromechanical landing gear actuators are diverging from FAA pathways, forcing suppliers to maintain dual qualification tracks. This regulatory friction is extending platform development budgets and reshaping supplier selection criteria. European-based tier-one suppliers are leveraging proximity to EASA to capture positions on Airbus programs.
Airlines are consolidating actuator procurement under fleet-wide performance-based logistics agreements rather than transactional spares purchasing. This behavioral shift is disintermediating traditional distribution channels and transferring inventory risk to original equipment manufacturers. North American carriers with large narrowbody fleets are pioneering these consolidated sourcing arrangements.
Aircraft Actuator Market Segmentation
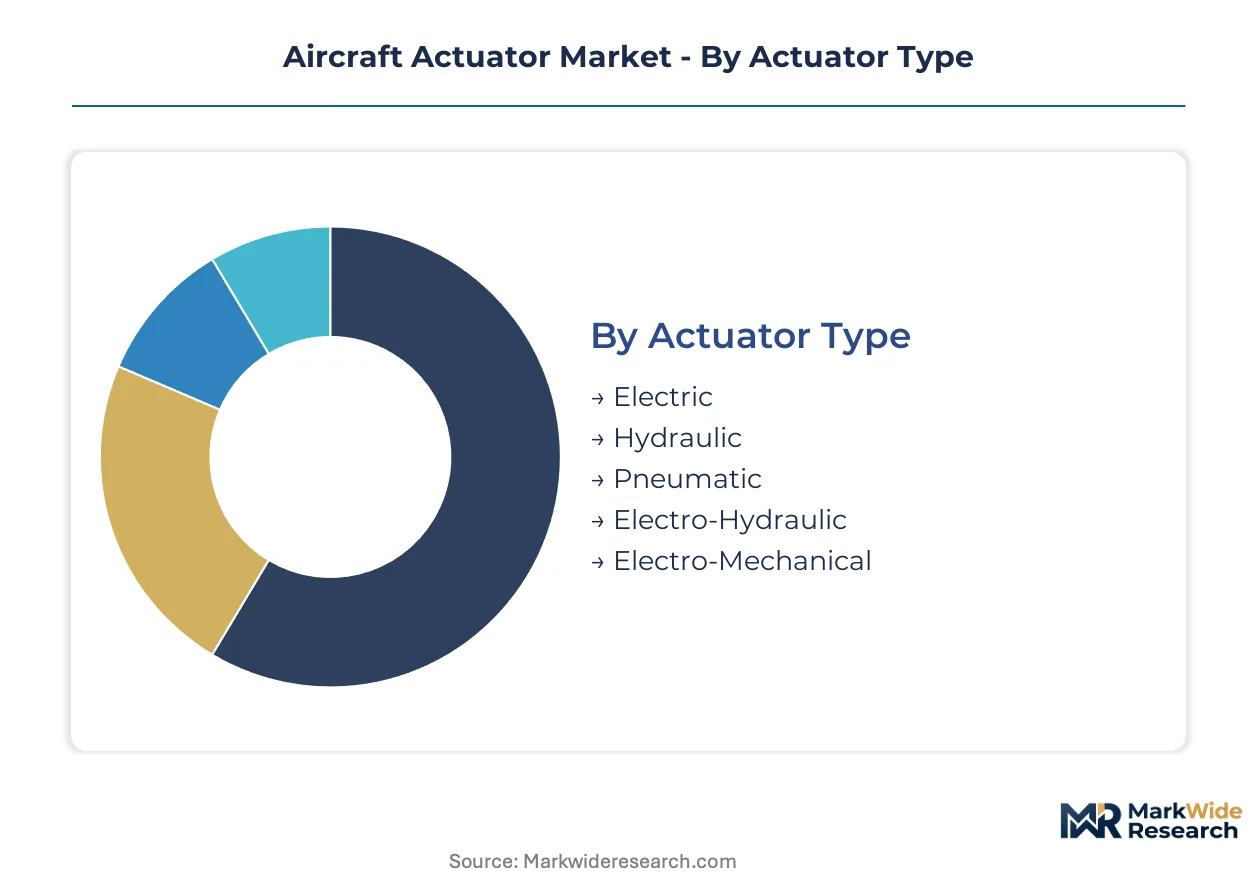
Aircraft actuator procurement splits across four dimensions that reshape supplier qualification requirements and margin structures. Regulatory differentiation between FAA 14 CFR Part 25 and EASA CS-25 certification pathways forces parallel development tracks for electromechanical architectures. Each segmentation layer concentrates value in distinct supply chain nodes.
Actuator Type:
FAA and EASA timelines for electromechanical certification are diverging, forcing suppliers to maintain dual qualification tracks for electric architectures while hydraulic configurations retain legacy fleet demand.
- Electric:Power-by-wire architectures convert electrical energy directly into mechanical motion without hydraulic intermediaries. Demand concentrates in next-generation narrowbody programs at Boeing and Airbus final assembly lines as more-electric mandates tighten. DO-160G environmental qualification tiers are bifurcating supplier competitiveness on vibration resilience.
- Hydraulic:Centralized hydraulic distribution systems operate at pressures exceeding 3,000 psi through servoactuators with decades of proven airworthiness. Existing widebody fleets with remaining service life sustain aftermarket spares demand, fragmenting R&D investment toward electromechanical alternatives.
- Pneumatic:Compressed air systems serve auxiliary functions where weight and simplicity outweigh precision requirements.
- Electro-Hydraulic:Hybrid architectures retain hydraulic power transmission while replacing mechanical control linkages with electronic signals.
- Electro-Mechanical:Integrated electromechanical units combine motor, gearbox, and position sensing in compact housings for distributed flight control surfaces.
Hydraulic handles the majority of installed base throughput; electric is the fastest mover on share.
Aircraft Type:
Volume concentration follows final assembly line geography, with procurement gravity centering on United States, China, and Germany production clusters.
- Commercial:Narrowbody and widebody platforms from Boeing, Airbus, and COMAC drive bulk actuator procurement for flight control and landing gear systems. Fleet expansion programs in China and the United States are accelerating electromechanical adoption rates.
- Unmanned Aerial Vehicle:Military and commercial drone fleets require compact actuators for control surfaces, landing gear, and payload positioning. Defense procurement frameworks in India and the United States are qualifying domestic suppliers for indigenous programs.
- Military:Fighter and transport platforms demand fault-tolerant architectures with combat redundancy specifications.
- Business Jet:Premium cabin and performance requirements sustain above-average pricing for precision actuation.
- Regional:Turboprop and regional jet programs balance cost constraints with EASA and FAA certification requirements.
Commercial absorbs the dominant procurement volume; unmanned aerial vehicle climbs the fastest on fleet expansion.
Application:
Margin stratification reflects certification burden and failure-mode criticality, with primary flight control systems commanding premium positioning.
- Flight Control Systems:Primary and secondary surface actuation demands MIL-STD-810 environmental compliance and fault-tolerant architectures. Honeywell and Parker-Hannifin anchor positions on Boeing and Airbus programs through integrated avionics-actuator architectures.
- Landing Gear:Fail-operate redundancy requirements and overhaul cycles tied to airframe utilization rates sustain above-average pricing. Safran competes on electromechanical specialization for narrowbody applications.
- Cargo Doors:Powered door actuation requires moderate force precision with lower criticality classification.
- Thrust Vectoring:Military fighter platforms demand high-frequency response actuators for nozzle positioning.
- Brake Systems:Electromechanical brake actuation is displacing hydraulic alternatives on new platforms.
- Environmental Control:Cabin pressure and temperature modulation actuators operate at reduced duty cycles.
Flight control systems capture the dominant value share; brake systems is gaining share fastest on electrification.
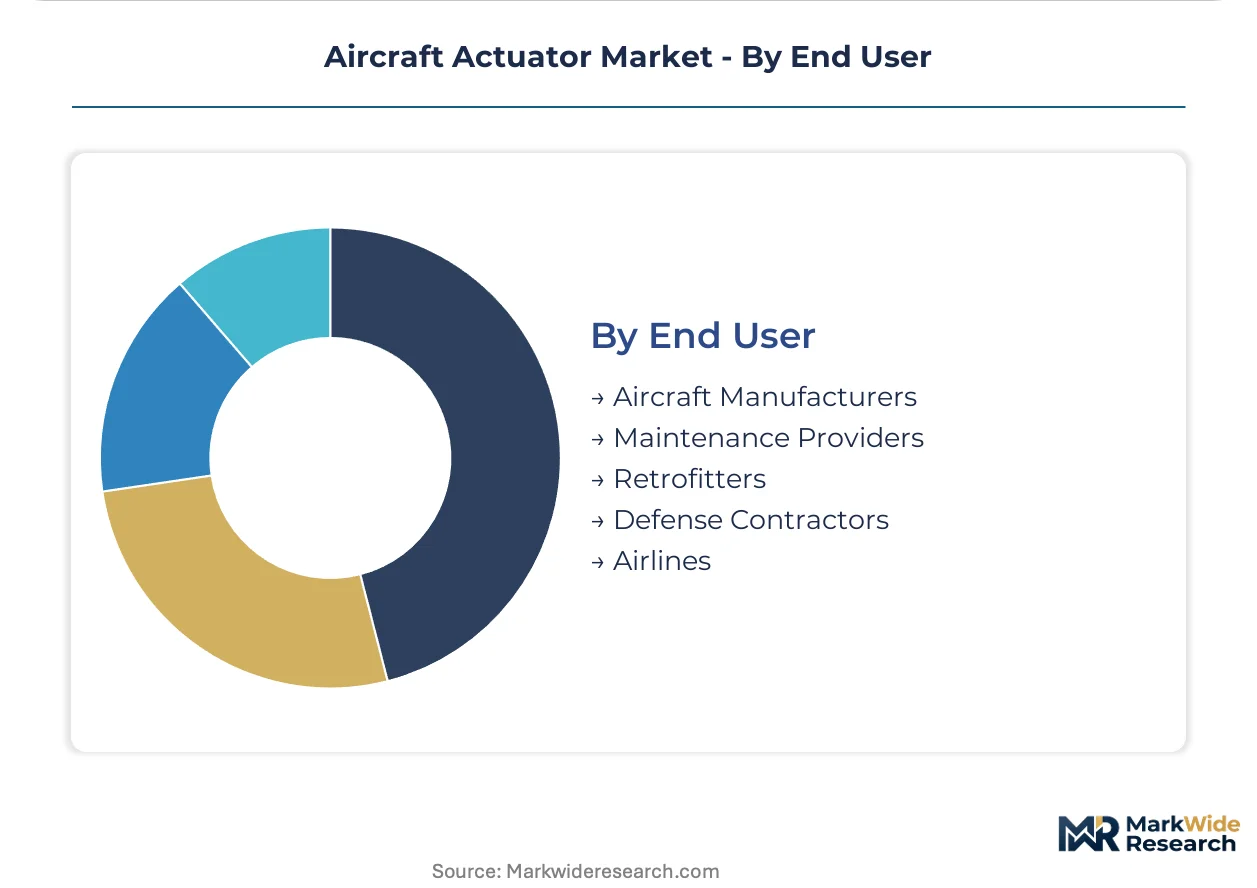
End User:
Procurement pattern shifts are disintermediating traditional distribution channels as airlines consolidate under performance-based logistics agreements.
- Aircraft Manufacturers:Boeing, Airbus, and COMAC final assembly lines specify actuator architectures during platform development. Tier-one supplier clusters in Germany and the United States concentrate qualification relationships.
- Airlines:North American carriers with large narrowbody fleets are pioneering consolidated sourcing arrangements that transfer inventory risk to original equipment manufacturers.
- Maintenance Providers:Independent MRO facilities handle hydraulic actuator overhaul for legacy fleet support.
- Retrofitters:Supplemental type certificate holders modify existing airframes with upgraded actuation.
- Defense Contractors:Military prime contractors integrate actuators into weapon systems under national procurement frameworks.
Aircraft manufacturers control the dominant specification authority; airlines is expanding most quickly on unbundled aftermarket contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Final assembly line geography concentrates actuator procurement in three dominant clusters. Boeing and Airbus production networks in the United States, Germany, and France anchor tier-one supplier relationships. Chinese COMAC expansion and Indian defense modernization are redistributing qualification activity toward emerging manufacturing hubs.
United States
Boeing's 737 MAX and 777X programs in Washington and South Carolina drive electromechanical actuator specification. FAA 14 CFR Part 25 airworthiness standards govern certification pathways for more-electric architectures. Wichita's aviation cluster hosts precision machining suppliers feeding actuator housing production for flight control systems.
Germany
Airbus final assembly in Hamburg and Bremen sustains demand for integrated avionics-actuator systems. EASA CS-25 certification requirements for electromechanical landing gear are diverging from FAA timelines. Munich's aerospace corridor concentrates electromechanical specialization suppliers serving narrowbody programs.
France
Toulouse anchors Airbus A320 family and A350 production with embedded actuator procurement authority. ANSM and DGAC coordination shapes national aerospace regulatory positioning within EASA frameworks. Paris-Saclay's research cluster advances power-by-wire thermal management for distributed flight control.
China
COMAC C919 narrowbody certification is qualifying domestic actuator suppliers for indigenous platforms. MIIT and CAAC alignment on more-electric standards accelerates electromechanical adoption rates. Shanghai's Pudong aerospace zone concentrates tier-two machining capacity for landing gear actuation components.
India
Defense Procurement Framework indigenous fighter programs are qualifying domestic actuator manufacturers for military applications. BIS aerospace standards development supports tier-one supplier qualification for export markets. Bangalore's aerospace park hosts precision engineering firms targeting unmanned aerial vehicle actuator contracts.
Aircraft Actuator Market Key Industry Players
Concentration sits with integrated electromechanical specialists and legacy hydraulic system incumbents restructuring for power-by-wire transitions. The vendor base separates into three functional tiers: diversified industrial conglomerates with avionics integration capabilities, pure-play actuation specialists with deep aerospace qualification histories, and emerging electromechanical component suppliers capturing narrowbody electrification programs. Dominant competitive moves include strategic partnerships between actuator suppliers and flight control computer integrators, plus capacity expansion in electromechanical assembly to serve more-electric aircraft mandates.
Among diversified industrial conglomerates, Honeywell International Inc. and Parker-Hannifin Corporation exemplify the integrated systems archetype, while Safran SA occupies a position within the electromechanical specialization tier. These entities represent contrasting strategic postures: conglomerate-scale diversification against focused aerospace-actuation depth. Their competitive positioning reflects divergent bets on the pace of hydraulic displacement versus electromechanical adoption curves across Boeing, Airbus, and COMAC platform portfolios.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Moog Inc. |
| Parker-Hannifin Corporation |
| Safran SA |
| Collins Aerospace |
| Curtiss-Wright Corporation |
| Liebherr Group |
| AMETEK Inc. |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-day qualification cycles for titanium alloy housings concentrate supplier pricing power among German and United States machining clusters serving Boeing and Airbus final assembly lines. This lead-time band tightens procurement flexibility for electromechanical actuator programs while hydraulic legacy spares compete on shorter fulfillment windows.
Pricing Analysis
FAA 14 CFR Part 25 and EASA CS-25 certification tiers dictate the pricing structure across electromechanical actuator configurations. Three-tier pricing stratifies by DO-160G environmental qualification grade, with vibration-resilient architectures commanding premium positioning over standard commercial grades. Cost compression in hydraulic aftermarket spares intensifies as airlines consolidate fleet-wide performance-based logistics agreements. Defense contractors exhibit lowest price sensitivity due to combat redundancy specifications, while regional turboprop operators face acute pressure on landing gear overhaul budgets.
Supply Chain Analysis
Strategic stockpiling of high-grade aluminum and titanium forgings prevails over just-in-time preferences given twelve-month mill lead times from specialty metal suppliers. Component sourcing draws from United States, Germany, and China production clusters, with precision machining concentrated in Wichita and Munich aerospace corridors. Single-source vulnerability concentrates in titanium sponge feedstock from limited smelter capacity. Distribution runs through tier-one supplier direct channels to Boeing, Airbus, and COMAC final assembly lines, bypassing traditional aerospace distributors for flight control system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service unbundling from airframe maintenance agreements expands recurring revenue faster than original equipment hardware sales, creating attach-rate opportunities for overhaul and fleet management contracts.
For Market Incumbents: Shield margin pools in electromechanical flight control systems by deepening backward integration into motor and gearbox subassemblies. Accelerate DO-178C firmware qualification capacity to constrain development velocity for emerging competitors. Capture urban air mobility qualification positions before eVTOL platform specifications solidify.
For New Entrants and Emerging Players: Anchor in unmanned aerial vehicle actuator contracts where military and commercial drone fleet expansion outpaces qualification requirements for manned aviation platforms. Target India's defense procurement framework for indigenous fighter programs with relaxed legacy certification burdens. Pursue direct airline channel development as North American carriers separate actuator overhaul from airframe maintenance agreements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core aerospace actuation divisions. Long-term viability hinges on electromechanical specialization depth rather than hydraulic legacy service revenue. Monitor divergence between FAA and EASA electromechanical certification timelines as inflection signal for platform development budget reallocations.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Qualification Investment | DO-160G Tier G certification unlocks Boeing 737 MAX and Airbus A320 family positions. |
| Backward Integration into Motor Assemblies | In-house production of brushless DC motors compresses cost structures for narrowbody programs. |
| Urban Air Mobility Partnership | eVTOL platform development agreements establish specifications for distributed propulsion architectures. |
| Performance-Based Logistics Contracting | Fleet-wide aftermarket consolidation transfers inventory risk from airlines to actuator manufacturers. |
| Dual-Track Regulatory Qualification | Parallel FAA and EASA certification pathways capture positions on both Boeing and Airbus programs. |
Research Approach
Desk research of FAA airworthiness directives, EASA certification databases, and OEM procurement disclosures preceded structured interviews with flight control system engineers, airline fleet managers, tier-one supplier procurement leads, and MRO facility directors. Primary fieldwork combined with secondary validation through customs trade data, aerospace component shipment records, and defense procurement announcements. Bottom-up actuator unit economics triangulated against top-down fleet expansion projections across commercial, military, and unmanned aerial vehicle platforms.
Variance decomposition across actuator type, aircraft platform, application criticality, and end-user procurement pattern shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level unit demand multiplied by average selling price trajectories, with electromechanical share gain curves calibrated against more-electric aircraft adoption rates. Forecast inputs incorporated narrowbody production schedules from Boeing, Airbus, and COMAC final assembly lines alongside defense procurement frameworks in India and the United States.
Decision-makers should treat outputs as directional under assumptions of sustained more-electric aircraft mandates and stable titanium alloy supply; material deviation in regulatory divergence timelines or specialty metal sourcing constraints would warrant model refresh. Revision becomes warranted when EASA-FAA certification gap duration crosses thresholds that reshape platform development budgets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market