
 Aircraft Drive Shaft and Couplings Market | 2026-2036
Aircraft Drive Shaft and Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Drive Shaft and Couplings Market Analysis
AS9100-rev D certification tiers are redrawing supplier eligibility across the aerospace supply base. GKN Aerospace leverages its integrated metallurgy and forging capabilities to sustain long-term contracts with major airframers. Kaman dominates the military helicopter drivetrain segment through specialized torque tube engineering. Honeywell International Inc. navigates dual-use commercial and defense applications with advanced composite shaft architectures.
Aircraft drive shafts and couplings are mechanical power transmission components engineered to transfer torque between engine outputs and rotating assemblies, typically manufactured from alloy steel or titanium with critical tolerances below 0.001 inches for rotational balance. These components serve the essential function of maintaining synchronized power delivery across variable load conditions in turbine and piston-driven aircraft systems. Titanium material grades command premium positioning due to strength-to-weight advantages in commercial aviation propulsion linkages. Flexible coupling configurations represent the fastest-expanding product category as geared turbofan architectures multiply connection points across intermediate casings. Helicopter applications concentrate aftermarket demand through high-cycle fatigue replacement schedules driven by mast and tail rotor drivetrain duty.
FAA airworthiness directives and EASA certification specifications govern material traceability, non-destructive testing protocols, and fatigue life documentation for all flight-critical rotating components. The EU Green Deal emissions framework and REACH chemical compliance are reshaping surface treatment and coating specifications for European-registered fleet suppliers. Stakeholders must monitor evolving MRO digitization requirements and additive manufacturing qualification pathways as these technologies redefine spare part sourcing economics and airworthiness substantiation methods.
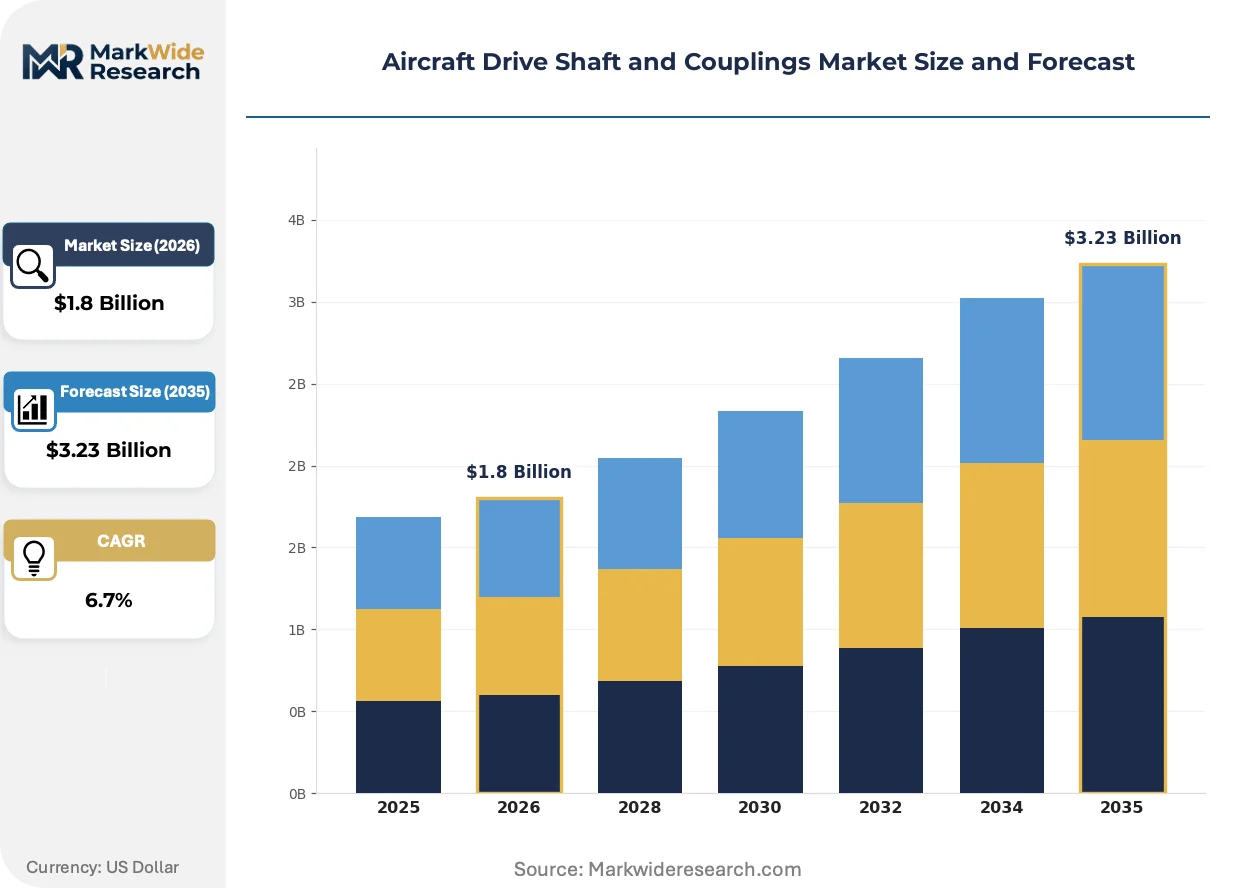
Market Dynamics
Geared turbofan proliferation is multiplying intermediate casing connection points across commercial propulsion architectures, fundamentally restructuring procurement volumes for flexible coupling configurations. FAA fatigue life documentation mandates and EASA material traceability requirements are simultaneously tightening supplier qualification thresholds.
Growth Catalysts
- FAA Airworthiness Directives:Fatigue-resistant material mandates are expanding replacement cycles for legacy drivetrain components in narrow-body fleet renewals.
- Titanium Grade 5 Adoption:Strength-to-weight advantages in propulsion linkages are pulling material specification upgrades across Boeing and Airbus supply chains.
- Helicopter Mast Duty Cycles:High-cycle fatigue replacement schedules in military and civil rotorcraft are concentrating aftermarket demand in torque tube and tail rotor drivetrain segments.
Market Restraints
- Titanium Sponge Volatility:Russian and Chinese supply concentration for aerospace-grade titanium feedstock exposes margin compression risks during geopolitical disruptions.
- AS9100-Rev D Certification Barriers:Quality management system upgrades impose six-figure compliance costs that filter small machine shops from tier-one supplier pools.
- Electrification Substitution:Distributed electric propulsion architectures in urban air mobility prototypes threaten mechanical drivetrain content per aircraft.
Strategic Opportunities
- Additive Manufacturing Qualification:FAA Engineering Brief 18-006B pathways for laser powder bed fusion are opening topology-optimized spare part production economics.
- India Defense Procurement:Indigenous helicopter programs under the Ministry of Defence offset mandates are creating localized drivetrain sourcing requirements.
- REACH-Compliant Surface Treatments:EU Green Deal coating specifications are forcing chromium-free conversion coating adoption, advantaging European chemistry suppliers.
Industry Challenges
- NDT Technician Scarcity:Ultrasonic and eddy-current inspection certification pipelines are failing to match airframe production rate ramps.
- Legacy Platform Documentation Gaps:Cold War-era military aircraft lack complete forging and heat treatment records required for AS9100 traceability audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Drive Shaft and Couplings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Shaft, Flexible Coupling, Rigid Coupling, Universal Joint Material: Alloy Steel, Aluminum, Titanium, Composite Application: Commercial Aviation, Military Aviation, Business Jets, Helicopters End User: OEMs, Aftermarket Providers, Maintenance Facilities, Aircraft Manufacturers |
| Companies Covered | Kaman, GKN Aerospace, UTC Aerospace Systems, Pankl Racing Systems, Northstar Aerospace, Safran Transmission Systems, Liebherr Group, Eaton Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Drive Shaft and Couplings Market Emerging Trajectories
Digital thread integration across design, manufacturing, and airworthiness documentation is collapsing traditional stage-gate timelines for rotating component qualification. Three convergent developments are restructuring competitive capability requirements.
Carbon fiber-reinforced polymer composite shafts are fragmenting metallurgical dominance in auxiliary power unit and environmental control system linkages. Tier-two suppliers in Japan and Italy are adopting automated fiber placement for hollow torque tubes with 40% mass reduction. This material transition is fragmenting incumbent forging capacity utilization and compressing acceptable lead times for prototype deliveries.
REACH Annex XIV authorization requirements for hexavalent chromium surface treatments are forcing chemistry substitutions across European-registered fleet suppliers. ECHA compliance deadlines are accelerating plasma electrolytic oxidation process qualification. Military helicopter OEMs with dual-use civil certification exposure are most affected, diverting engineering resources toward coating redevelopment.
Power-by-the-hour contracts are consolidating airline technical procurement decisions under airframe OEM captive MRO networks. Independent component repair stations face disintermediation as Rolls-Royce and Pratt & Whitney expand TotalCare and EngineWise coverage to drivetrain accessories. This channel compression is most visible in Southeast Asia, where low-cost carrier fleet expansion has concentrated aftermarket spend under OEM-direct service agreements.
Aircraft Drive Shaft and Couplings Market Segmentation
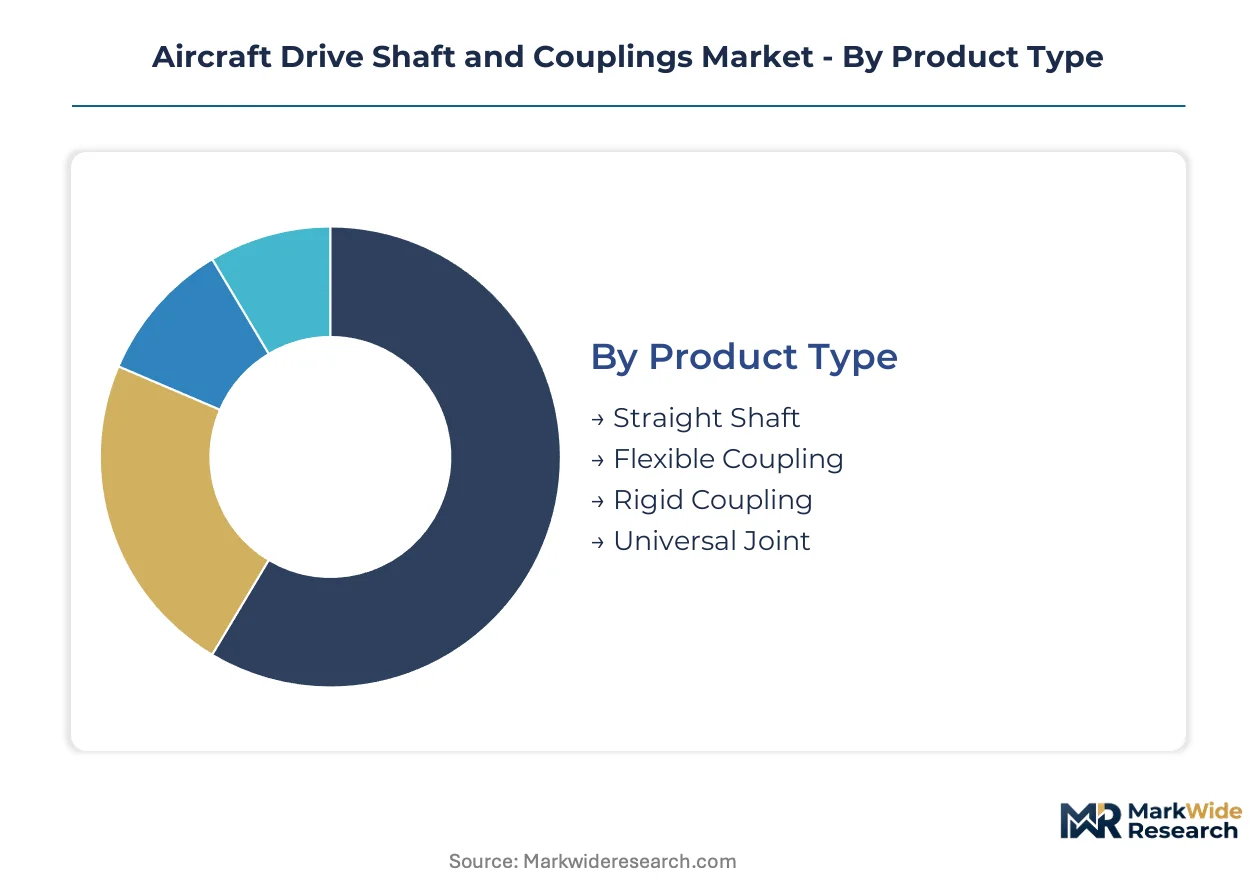
Component specification tiers in aircraft drivetrains diverge sharply by mission profile and certification burden. Procurement patterns across these segments reveal where engineering investment concentrates versus where price competition dominates.
Product Type:
Flexible coupling architectures face the strongest substitution pressure from integrated gearbox designs in next-generation turbofan programs, while straight shafts defend their position through legacy fleet lock-in.
- Straight Shaft:Solid or tubular torque transmission elements machined from bar stock with surface finishes below 16 RMS for high-RPM balance. Commercial narrow-body production lines in Renton and Toulouse anchor procurement volumes, though geared turbofan intermediate casings are displacing some linkages with integral spline designs.
- Flexible Coupling:Elastomeric or metallic disc configurations accommodating angular misalignment between engine and accessory gearbox interfaces. Helicopter mast and tail rotor drivetrains in the United States concentrate demand as high-cycle fatigue replacement schedules accelerate aftermarket throughput.
- Rigid Coupling:Bolted flange assemblies for precision-aligned shafts in auxiliary power unit and environmental control system linkages. Boeing 787 and Airbus A350 programs specify these for constant-speed drive applications.
- Universal Joint:Cardan-style cross-and-bearing assemblies for angular power transmission in landing gear retraction and flap actuation systems. Regional turboprop programs specify these for propeller pitch change mechanisms.
Straight shafts retain volume leadership; flexible couplings hold the steepest expansion curve.
Material:
Cost tier stratification separates aerospace-grade titanium from commodity alloy steel, with composite grades commanding prototype premiums that have yet to achieve production scale economics.
- Alloy Steel:4340M or 300M vacuum arc remelt grades dominate legacy military helicopter torque tubes and cargo aircraft flap drives. The Pentagon's Defense Logistics Agency maintains strategic stockpiles of qualified bar stock.
- Titanium:Ti-6Al-4V Grade 5 forgings specify propulsion linkages on Boeing 737 MAX and Airbus A320neo families. Russian VSMPO-AVISMA supply disruptions are forcing Western mills to expand sponge-to-mill vertical integration.
- Aluminum:7075-T6 extrusions serve low-torque auxiliary systems where mass reduction outweighs strength requirements. Business jet environmental control system ducting uses these for thermal management.
- Composite:Carbon fiber-reinforced polymer hollow shafts achieve 40% mass reduction in experimental APU linkages. Japanese Toray and Italian Leonardo suppliers pilot automated fiber placement for qualification.
Alloy steel retains volume leadership; composites hold the steepest expansion curve.
Application:
Customer type fragmentation splits procurement between airframe OEM captive engineering and independent MRO channel decisions, with helicopter aftermarket operating on entirely different contract structures than fixed-wing programs.
- Commercial Aviation:Narrow-body fleet renewal programs at Boeing and Airbus specify fatigue-resistant materials for main engine and APU drivetrains. Power-by-the-hour contracts concentrate aftermarket spend under Rolls-Royce TotalCare and Pratt & Whitney EngineWise networks.
- Military Aviation:Fighter and transport programs through the US Air Force Life Cycle Management Center mandate AS9100-Rev D traceability for all flight-critical rotating components. Foreign Military Sales channels replicate these specifications for allied operators.
- Business Jets:Gulfstream and Bombardier programs emphasize cabin-quiet drivetrain architectures with tuned elastomeric couplings. Low production volumes favor flexible manufacturing cells over dedicated transfer lines.
- Helicopters:Sikorsky and Bell military contracts specify torque tube replacement intervals based on mast duty cycle accumulation. Indian Ministry of Defence indigenous helicopter programs are creating localized sourcing mandates.
Commercial aviation retains volume leadership; helicopters hold the steepest expansion curve.
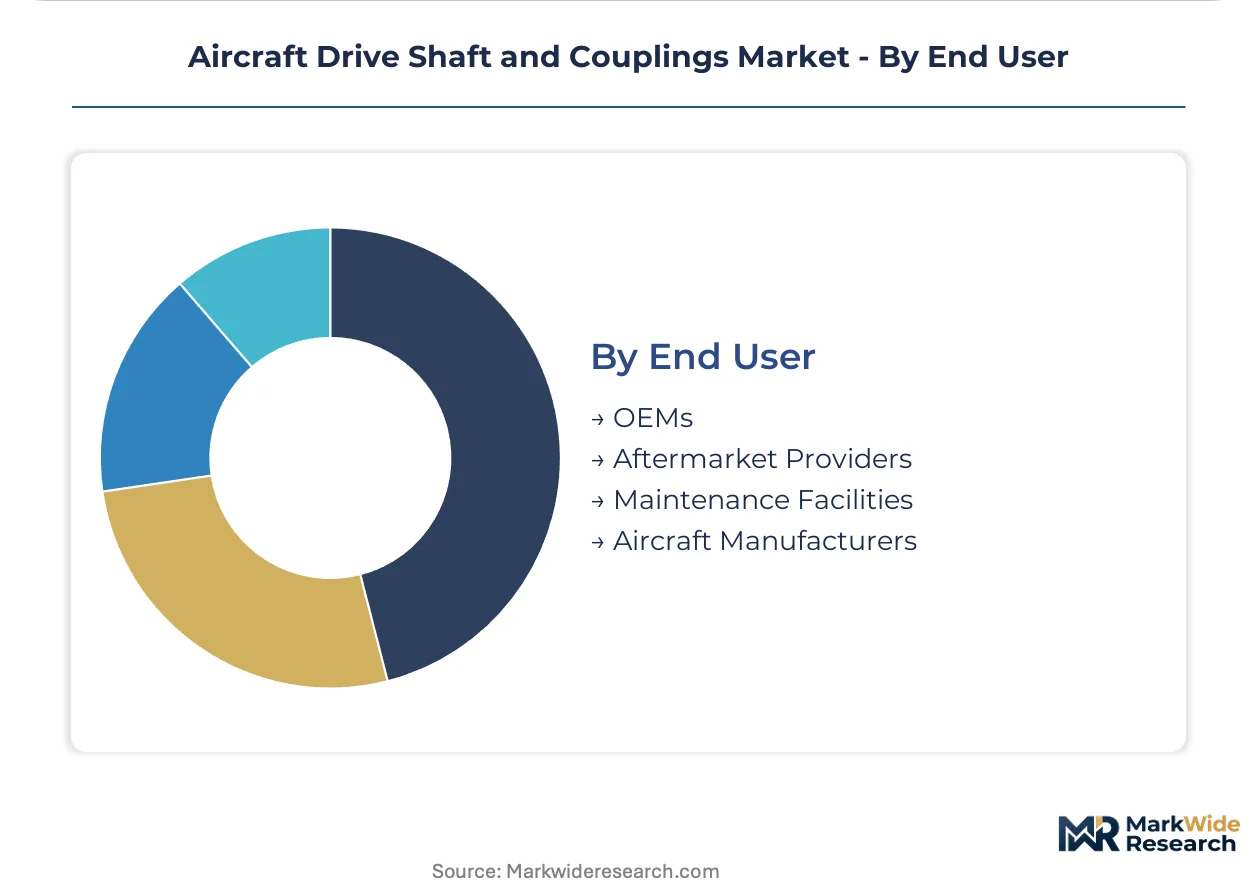
End User:
Supply concentration among tier-one aerostructures suppliers filters qualification pathways, with AS9100 certification barriers excluding machine shops from OEM direct contracts while preserving aftermarket repair station niches.
- OEMs:Boeing Commercial Airplanes and Airbus S.A.S. specify drivetrain architectures at platform definition, locking in suppliers for program life. GKN Aerospace and Spirit AeroSystems hold long-term agreements for propulsion system torque transmission.
- Aftermarket Providers:Independent component repair stations face disintermediation as OEMs expand captive MRO networks. Southeast Asian low-cost carrier fleet expansion concentrates spend under OEM-direct service agreements.
- Maintenance Facilities:FAA Part 145 repair stations perform coupling replacement and balancing services. NDT technician scarcity limits inspection throughput against airframe production ramps.
- Aircraft Manufacturers:Tier-one aerostructures integrators source finished drivetrain modules rather than raw shafting. Leonardo Helicopters and Kaman Corporation maintain in-house torque tube engineering for rotorcraft programs.
OEMs retain volume leadership; aftermarket providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier qualification thresholds concentrate manufacturing capacity in jurisdictions with established aerospace certification infrastructure. Boeing and Airbus final assembly locations anchor procurement decisions for flight-critical rotating components. FAA and EASA regulatory reciprocity agreements shape cross-border sourcing patterns for drivetrain assemblies.
United States
Boeing Commercial Airplanes in Renton and Everett drives specification authority for narrow-body propulsion linkages. FAA airworthiness directives mandate fatigue-resistant material documentation for all flight-critical shafts. Wichita, Kansas hosts a dense cluster of tier-one aerostructures suppliers performing precision machining and non-destructive testing for military and commercial programs.
France
Airbus final assembly in Toulouse concentrates demand for titanium Grade 5 torque transmission components. EASA certification specifications govern material traceability and heat treatment record retention for European-registered fleet suppliers. Safran Transmission Systems in Colombes anchors domestic engineering capacity for geared turbofan intermediate casing architectures.
Germany
MTU Aero Engines in Munich specifies drivetrain architectures for Pratt & Whitney GTF powerplants. REACH Annex XIV authorization deadlines for hexavalent chromium coatings force chemistry substitutions across surface treatment suppliers. Bavaria's precision forging cluster around Augsburg maintains vacuum arc remelt capacity for aerospace-grade alloy steel bar stock.
United Kingdom
Rolls-Royce in Derby drives specification authority for wide-body propulsion systems and power-by-the-hour contract structures. AS9100-Rev D quality management system upgrades filter small machine shops from tier-one supplier pools. GKN Aerospace's Western Approach facility near Bristol integrates metallurgy and forging capabilities for long-term airframer agreements.
India
Indigenous helicopter programs under the Ministry of Defence create localized drivetrain sourcing mandates for military rotorcraft. DGFT offset requirements force foreign OEMs to establish domestic manufacturing joint ventures. Bengaluru's aerospace cluster hosts emerging precision machining capacity serving Hindustan Aeronautics Limited torque tube requirements.
Aircraft Drive Shaft and Couplings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the supplier base. Integrated aerostructures conglomerates with captive metallurgy capabilities dominate long-term OEM contracts, while specialized torque tube engineers capture military helicopter aftermarket cycles. Three archetypes define competitive positioning: diversified aerospace conglomerates with forging-to-flight vertical control, precision machining specialists focused on rotorcraft drivetrains, and composite materials innovators disrupting legacy metallurgical supply chains. Consolidation pressure operates through airframe OEM captive MRO network expansion and additive manufacturing qualification barriers that favor capital-intensive incumbents.
Among diversified aerospace suppliers, GKN Aerospace and Honeywell International Inc. exemplify the integrated conglomerate archetype with cross-program engineering leverage. Kaman occupies a distinct position within the military rotorcraft specialization tier, anchoring torque tube engineering capabilities for high-cycle fatigue replacement schedules. These three companies represent the span of competitive positioning from commercial propulsion system scale to defense aftermarket focus.
| Leading Market Players |
|---|
| Kaman |
| GKN Aerospace |
| UTC Aerospace Systems |
| Pankl Racing Systems |
| Northstar Aerospace |
| Safran Transmission Systems |
| Liebherr Group |
| Eaton Corporation |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Boeing, Airbus, and tier-one aerostructures suppliers lock in multi-year price visibility for titanium Grade 5 forgings while securing dedicated vacuum arc remelt capacity at Western mills. These contracts insulate procurement teams from Russian VSMPO-AVISMA supply disruptions that have destabilized spot-market titanium sponge pricing since geopolitical tensions escalated.
Pricing Analysis
AS9100-Rev D certification dictates the pricing tier structure across the supplier base, with fatigue-resistant material documentation and non-destructive testing protocols separating premium-qualified forgers from standard-grade machine shops. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, titanium grade specification, and traceability depth. Cost compression in the standard tier is intensifying because small machine shops face six-figure compliance upgrades that filter them from OEM direct contracts. Independent MRO providers demonstrate the highest price sensitivity due to disintermediation pressure from Rolls-Royce TotalCare and Pratt & Whitney EngineWise captive networks.
Supply Chain Analysis
Strategic stockpile preferences dominate titanium procurement as defense agencies and major airframers maintain qualified bar stock reserves against Russian and Chinese supply concentration. Manufacturing gravity centers on the United States, France, and Germany where FAA and EASA certification infrastructure supports precision forging clusters. Raw material flows draw from aerospace-grade titanium sponge, vacuum arc remelt alloy steel, and carbon fiber prepreg. Single-source vulnerability in Russian titanium feedstock exposes margin compression risks during geopolitical disruptions. Distribution runs through airframe OEM captive MRO networks that consolidate aftermarket procurement decisions under power-by-the-hour contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
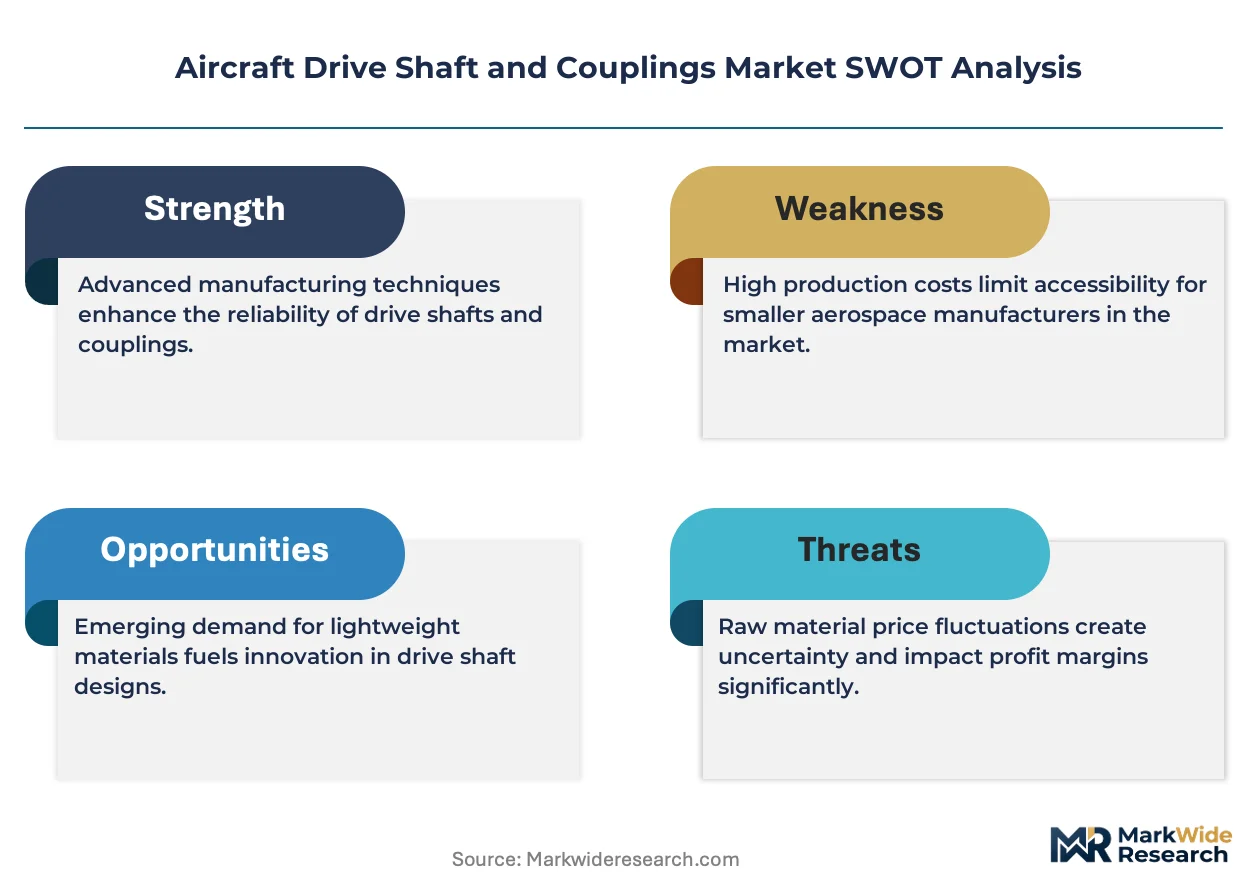
Distributed electric propulsion architectures in urban air mobility prototypes threaten mechanical drivetrain content per aircraft, forcing incumbents to defend their installed base through aftermarket lock-in and certification barriers.
For Market Incumbents: Consolidate aftermarket channel control through expanded power-by-the-hour coverage that captures drivetrain accessory spend under Rolls-Royce TotalCare and Pratt & Whitney EngineWise networks. Deepen backward integration into titanium sponge-to-mill capacity to insulate against Russian supply disruptions while securing AS9100-Rev D qualified forging capacity for narrow-body fleet renewal programs. For New Entrants and Emerging Players: Differentiate on additive manufacturing qualification for topology-optimized spare parts under FAA Engineering Brief 18-006B pathways that collapse traditional stage-gate timelines. Target Indian Ministry of Defence indigenous helicopter programs where offset mandates create localized drivetrain sourcing requirements without incumbent lock-in. Pursue plasma electrolytic oxidation process qualification for REACH-compliant surface treatments as European coating substitution accelerates. For Investors and Strategic Acquirers: Precision machining specialists with NDT technician pipelines and AS9100-Rev D certification represent the most defensible acquisition targets as airframe production rate ramps outpace inspection capacity expansion. Long-term viability hinges on aftermarket exposure in helicopter high-cycle fatigue replacement schedules rather than OEM content per aircraft in electrifying platforms. Watch FAA additive manufacturing qualification expansion as the inflection signal that redefines spare part sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100-Rev D Certification Investment | Quality management system upgrades filter small machine shops from tier-one supplier pools at Boeing and Airbus. |
| Additive Manufacturing Qualification | FAA Engineering Brief 18-006B pathways open topology-optimized spare part production for laser powder bed fusion. |
| Backward Integration into Titanium Sponge | Western mills expand vacuum arc remelt capacity to reduce Russian VSMPO-AVISMA supply dependency. |
| REACH-Compliant Surface Treatment Adoption | Plasma electrolytic oxidation process qualification accelerates as ECHA deadlines force chromium-free coating chemistry. |
| Captive MRO Network Expansion | Rolls-Royce TotalCare and Pratt & Whitney EngineWise consolidate airline technical procurement decisions under OEM-direct agreements. |
Methodological Framework
A standing panel of airframe OEM procurement directors, tier-one aerostructures supplier engineering leads, FAA certification specialists, and independent MRO operations managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FAA airworthiness directive filings, EASA certification specification updates, SEC 10-K disclosures from publicly traded aerostructures suppliers, and customs trade data for titanium sponge and alloy steel bar stock imports. Bottom-up build-ups of segment-level demand were cross-checked against top-down aerospace production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled demand by product type, material grade, application segment, and end-user channel, with propulsion architecture content per aircraft serving as a key scaling variable. CAGRs were derived from fitted growth curves applied to airframe delivery schedules and fleet renewal timelines, with helicopter mast duty cycle accumulation rates informing aftermarket replacement demand.
The analysis sits within stated boundaries; outcomes outside sustained narrow-body production rates at Renton and Toulouse or accelerated electrification substitution would require recalculation. Forecasts reflect assumptions about AS9100 certification barrier persistence and titanium supply chain restructuring. Revision becomes warranted when distributed electric propulsion architectures cross commercialization thresholds or when additive manufacturing qualification pathways expand beyond current FAA guidance scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market