
 Aircraft Electric Motor Market | 2026-2036
Aircraft Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Electric Motor Market Insights
EU Green Deal aviation clauses are consolidating the cost-of-entry calculus for electric motor suppliers serving next-generation aircraft programs. Safran Electrical & Power leverages its integrated power distribution architecture to anchor European electrification roadmaps. GE Aerospace competes through deep R&D intensity in high-temperature superconducting motor designs for hybrid-electric propulsion. Honeywell Aerospace differentiates via flight control motor systems that occupy critical safety-certification tiers across narrowbody and business jet platforms.
Aircraft electric motors are electromechanical devices converting electrical energy into mechanical torque for flight-critical and auxiliary functions, typically operating at voltage classes from 28V DC to 270V AC or higher in advanced architectures and achieving power densities exceeding 5 kW/kg in brushless permanent-magnet configurations. Their primary purpose is to replace or supplement hydraulic and pneumatic actuation systems, reducing weight, maintenance cycles, and fuel consumption across propulsion, environmental control, and flight surface applications. Brushless DC motor types dominate installed base volumes due to superior thermal performance and reliability in avionics cooling and actuator roles, while permanent magnet technology leads R&D investment flows as magnet material formulations advance. Propulsion systems represent the fastest-growing application segment as turboelectric and hybrid-electric architectures displace conventional turbine power take-off mechanisms.
FAA Part 33 certification standards and EASA CS-E engine regulations are tightening electromagnetic compatibility and fault-containment requirements for electric motors installed in primary propulsion paths. EPA aircraft engine emission guidelines and ICAO Carbon Offsetting and Reduction Scheme thresholds are accelerating OEM procurement timelines for electric alternatives to bleed-air and hydraulic systems. The EU AI Act and emerging cybersecurity frameworks from EASA are layering software-assurance obligations onto digitally controlled motor drives. Stakeholders must monitor how multi-agency certification convergence between FAA, EASA, and national military airworthiness boards reshapes development cycles and supplier qualification protocols for next-generation electric propulsion architectures.
Market Dynamics
The transition from centralized hydraulic and pneumatic systems to distributed electric actuation architectures is compressing powertrain integration cycles and forcing OEMs to requalify entire subsystem portfolios around electromagnetic compatibility thresholds.
Growth Catalysts
- EU Green Deal aviation clauses:Binding emissions reduction mandates are accelerating fleet electrification timelines and expanding procurement budgets for electric propulsion components.
- Brushless permanent-magnet configurations:Advances in magnet material formulations are pushing power densities past thermal limits that previously constrained actuator miniaturization.
- France:The Safran-Airbus supplier cluster is concentrating R&D investment and creating spillover demand for specialized winding and thermal management subcomponents.
Market Restraints
- Rare earth magnet supply concentration:Processing and refining capacity for neodymium-dysprosium-terbium alloys concentrates in China, exposing motor manufacturers to export quota volatility and price spikes.
- FAA Part 33 electromagnetic compatibility requirements:Tightened fault-containment standards for primary propulsion paths are extending certification timelines and inflating pre-market testing budgets.
- High-temperature superconducting motor cooling systems:Cryogenic infrastructure demands and liquid hydrogen integration complexity limit near-term deployability outside experimental demonstrator programs.
Strategic Opportunities
- Urban air mobility platforms:eVTOL manufacturers are specifying distributed electric propulsion architectures that multiply per-aircraft motor counts by 8-16x relative to conventional turbofan designs.
- EU AI Act software-assurance frameworks:Emerging cybersecurity certification tiers for digitally controlled motor drives create first-mover advantage for suppliers with embedded functional safety expertise.
- Hybrid-electric regional aircraft:Turboelectric power take-off mechanisms are opening retrofit and clean-sheet design windows for megawatt-class motor-generator units in 50-100 seat segments.
Industry Challenges
- Multiphysics simulation talent scarcity:Electromagnetic-thermal-structural co-design for aviation-grade motors requires specialized competency sets that outpace current university pipeline output.
- Legacy hydraulic system integration:Retrofit programs for in-service narrowbody fleets face airframe modification complexity and weight-and-balance recertification bottlenecks.
- Cross-agency certification convergence:Divergent electromagnetic interference test protocols between FAA, EASA, and military airworthiness boards force redundant validation campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Electric Motor Market |
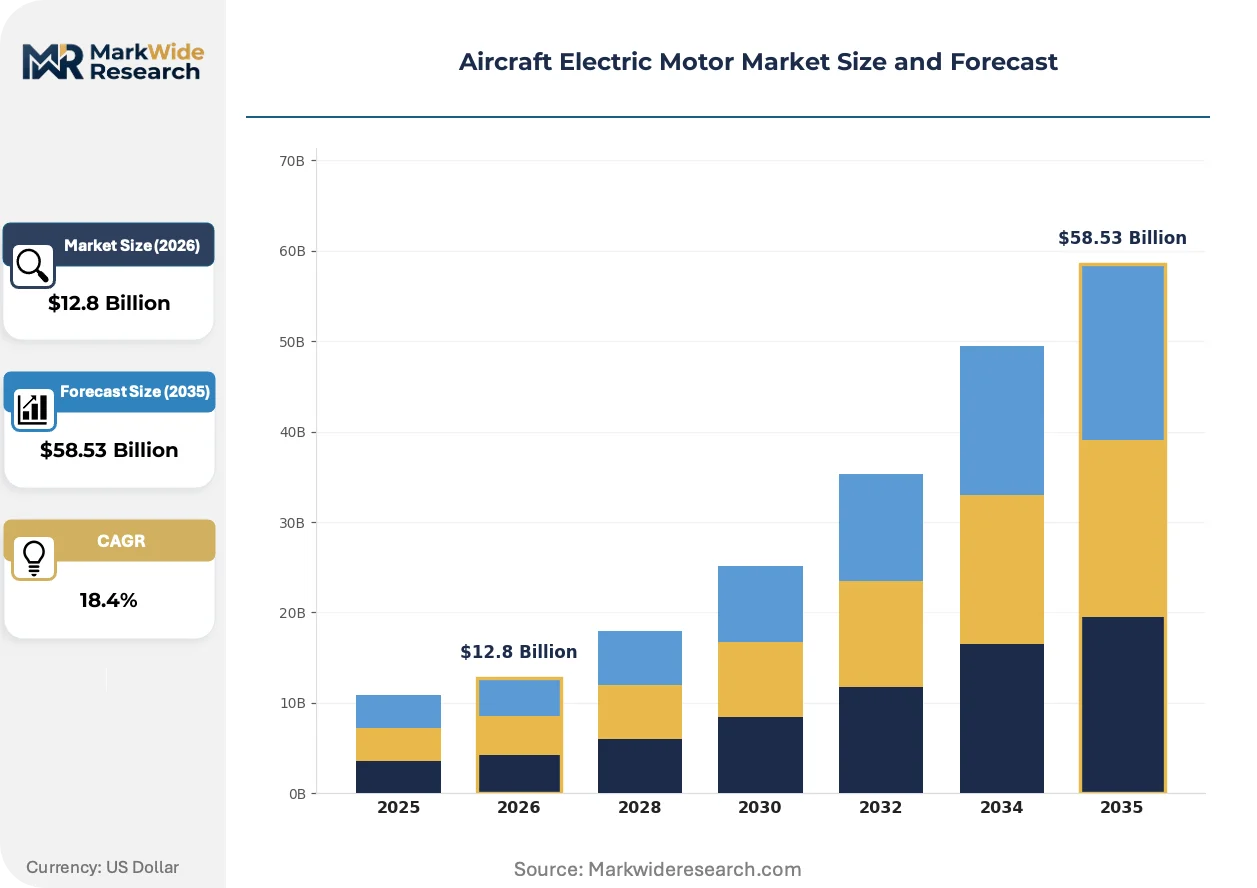
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless DC, AC Induction, Synchronous, Stepper, Switched Reluctance Technology: Permanent Magnet, Induction, Linear, Servo, Coreless Application: Propulsion Systems, Environmental Control, Avionics, Flight Control, Auxiliary Power Units End User: Commercial Airlines, Defense Aviation, General Aviation, Aircraft Manufacturers |
| Companies Covered | Moog Inc., Safran Electrical & Power, GE Aerospace, Collins Aerospace, Honeywell Aerospace, AMETEK Inc., Woodward Inc., Rolls-Royce plc, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Electric Motor Market Trends and Innovations
Distributed power electronics and solid-state switching architectures are collapsing traditional boundaries between motor, inverter, and thermal management subsystems, compressing supplier tiers and redefining value capture points.
Silicon carbide power semiconductors are replacing silicon IGBTs in motor drive inverters, enabling switching frequencies above 20 kHz that reduce filter mass and improve torque ripple control. Business jet and regional turboprop OEMs are specifying SiC-based architectures for new programs entering preliminary design. This frequency scaling is decentralizing thermal management design authority from airframers to motor-inverter subsystem suppliers.
EASA CS-E engine regulations and FAA Part 33 amendments are tightening electromagnetic emissions limits for electric motors in primary propulsion paths, forcing redesigns of shielding geometries and cable routing protocols. Manufacturers are responding by integrating composite motor housings with embedded conductive meshes. The narrowbody retrofit segment faces the steepest compliance cost escalation due to legacy wiring harness constraints.
Airline procurement organizations are unbundling aftermarket service contracts from initial motor supply agreements, creating standalone digital health monitoring and predictive maintenance revenue streams. Lessors and fleet managers are driving this disintermediation to capture operational data ownership. North American and European flag carriers are piloting power-by-the-hour arrangements for electric actuation systems on next-generation single-aisle deliveries.
Aircraft Electric Motor Market Segmentation
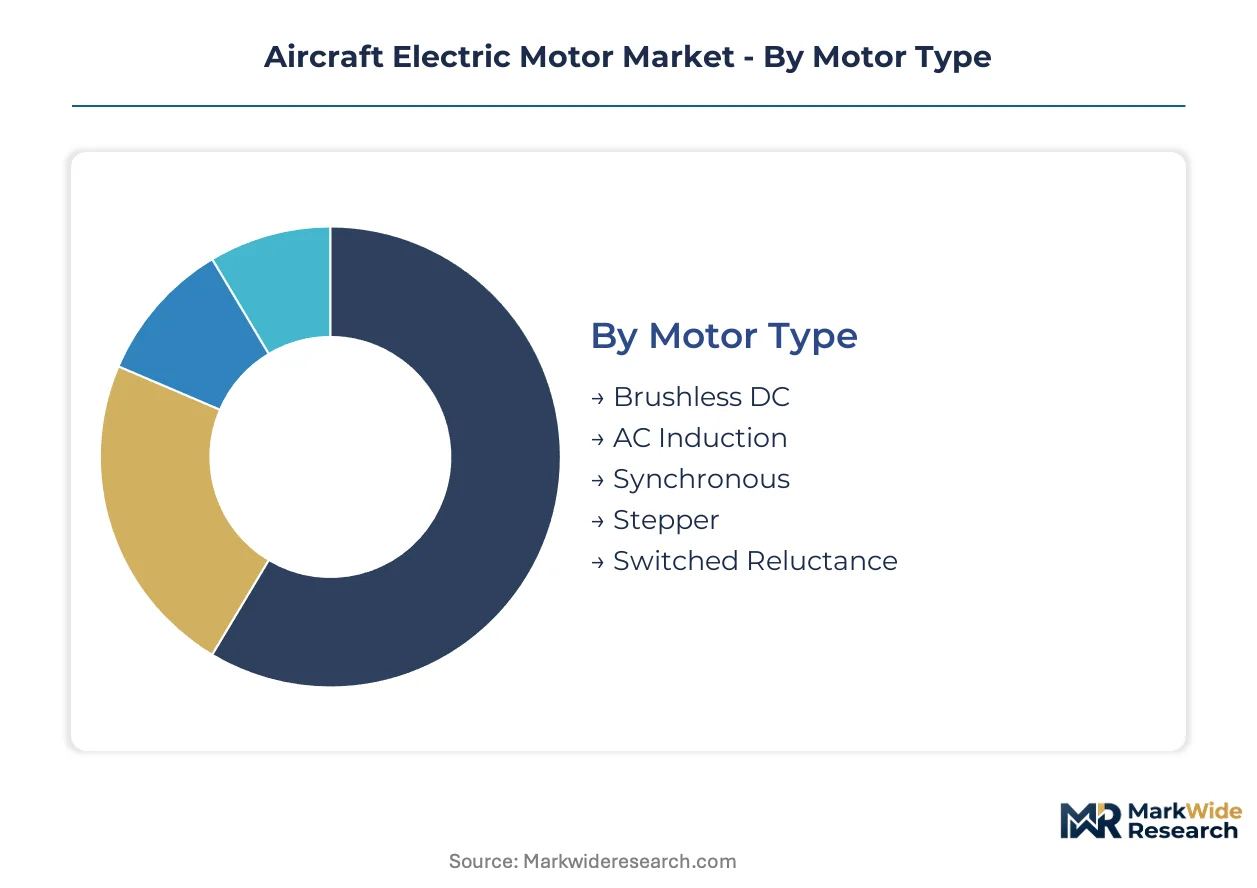
Segmentation in aircraft electric motors reveals how procurement priorities diverge across certification tiers, thermal performance thresholds, and integration complexity. Understanding these fault lines exposes where supplier margins concentrate and which technology transitions will reshape competitive positioning.
Motor Type:
Buyers differentiate primarily by thermal endurance requirements and maintenance interval expectations, with propulsion-grade applications demanding fault-tolerant architectures that auxiliary systems can bypass.
- Brushless DC:Permanent-magnet rotors eliminate brush wear, enabling power densities above 5 kW/kg in avionics cooling and actuator roles. Commercial airlines in France specify these for narrowbody flight control retrofits under EU Green Deal fleet modernization timelines.
- AC Induction:Squirrel-cage rotors operate without rare earth magnets, insulating defense procurement from supply chain volatility. The US Department of Defense favors these for tactical aircraft where magnet sourcing constraints threaten readiness.
- Synchronous:Field-excited rotors deliver precise speed control for environmental control system compressors.
- Stepper:Discrete angular positioning suits fuel valve and landing gear sequencing applications.
- Switched Reluctance:Magnet-free construction tolerates extreme temperature swings in engine nacelle zones.
Brushless DC leads volumes today; switched reluctance is gaining share fastest in high-temperature propulsion applications.
Technology:
Technology selection tracks power density targets against material availability risk, with permanent magnet formulations dominating where weight reduction justifies supply chain exposure.
- Permanent Magnet:Neodymium-iron-boron formulations achieve the highest torque-to-inertia ratios in turboelectric generator applications. Safran and GE Aerospace anchor R&D investment here, though Chinese rare earth processing concentration constrains European OEM procurement security.
- Induction:Copper-bar rotors withstand thermal overload without demagnetization failure modes. General aviation manufacturers in Germany specify these for piston-to-turboprop conversions where magnet replacement logistics burden remote operators.
- Linear:Direct thrust generation eliminates rotary-to-linear conversion losses in electromagnetic catapult systems.
- Servo:Closed-loop position feedback enables sub-arcminute precision for fly-by-wire surface actuation.
- Coreless:Ironless stators eliminate cogging torque in high-bandwidth stabilization platforms.
Permanent magnet commands premium pricing; induction is climbing the fastest as supply security reshapes procurement criteria.
Application:
Application segmentation follows airworthiness criticality tiers, with primary propulsion paths facing the steepest electromagnetic compatibility certification escalation.
- Propulsion Systems:Megawatt-class motors in turboelectric architectures replace mechanical power take-off shafts. Airbus and Boeing next-generation programs in the US and France are specifying these for hybrid-electric regional aircraft, though FAA Part 33 fault-containment requirements extend development cycles.
- Flight Control:Redundant electromechanical actuators displace hydraulic lines in fly-by-wire retrofits. Honeywell Aerospace dominates this segment through safety-certification depth across narrowbody platforms.
- Environmental Control:High-speed compressors replace bleed-air systems to reduce fuel burn.
- Avionics:Cooling fans and antenna positioning drives demand minimal electromagnetic interference signatures.
- Auxiliary Power Units:Starter-generator integration consolidates functions to reduce part count.
Flight control leads installed base volumes; propulsion systems show the steepest expansion trajectory as turboelectric architectures mature.
End User:
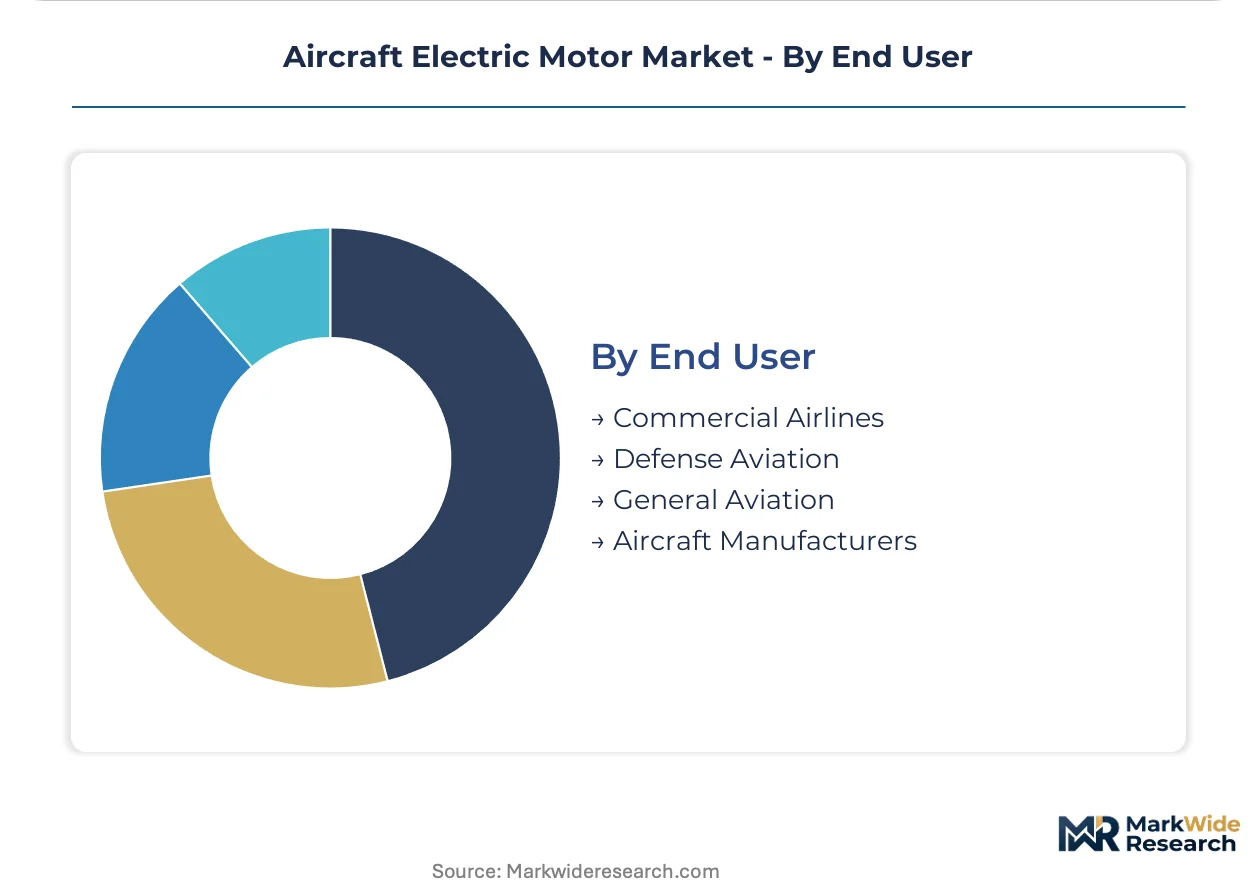
End user segmentation reflects procurement authority concentration, with aircraft manufacturers integrating motors at production and airlines driving aftermarket retrofit demand.
- Commercial Airlines:Fleet operators specify electric actuation retrofits to meet EU Green Deal emissions thresholds and capture fuel burn reductions. Air France-KLM and Lufthansa Group procurement organizations are unbundling service contracts to retain operational data ownership.
- Aircraft Manufacturers:OEMs like Airbus in Toulouse and Boeing in Seattle qualify motor suppliers during preliminary design, locking architectures for program lifecycles. Their power-by-the-hour arrangements with tier-one suppliers reshape aftermarket revenue capture.
- Defense Aviation:Military airworthiness boards impose electromagnetic pulse hardening requirements that civilian regulators do not replicate.
- General Aviation:Owner-operators prioritize first-cost minimization over lifecycle operating economics.
Aircraft manufacturers dominate new production value; commercial airlines are expanding fastest in aftermarket retrofit procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation electrification originated in post-war France and the United States, where early fly-by-wire experiments established the technical foundations for distributed electric actuation. These historical clusters continue to anchor supplier ecosystems and certification expertise.
United States
Boeing's next-generation program offices in Seattle and Everett drive specification authority for megawatt-class turboelectric architectures. FAA Part 33 amendments tightening electromagnetic compatibility thresholds are extending supplier qualification timelines. The Pacific Northwest corridor concentrates motor-inverter subsystem development alongside Honeywell Aerospace and GE Aerospace R&D facilities.
France
Airbus headquarters in Toulouse and Safran's integrated power distribution operations anchor European electrification roadmaps. EU Green Deal aviation clauses are binding fleet operators to emissions reduction mandates that expand procurement budgets. The Occitanie-Auvergne-Rhône-Alpes corridor hosts specialized winding and thermal management subcomponent suppliers serving the Safran-Airbus cluster.
Germany
MTU Aero Engines and Diehl Aviation coordinate hybrid-electric propulsion research for regional turboprop applications. EASA CS-E engine regulations are tightening fault-containment standards for primary propulsion paths. The Bavaria and Baden-Württemberg regions concentrate electromagnetic-thermal-structural simulation talent pools that outpace university pipeline output elsewhere in Europe.
United Kingdom
Rolls-Royce Electrical and BAE Systems anchor defense and civil electrification programs from Derby and Bristol. The country's national military airworthiness board imposes electromagnetic pulse hardening requirements that civilian regulators do not replicate. The Midlands and South West England clusters specialize in high-temperature superconducting motor demonstrators for experimental hybrid-electric programs.
Japan
METI-funded programs at JAXA and Mitsubishi Heavy Industries advance cryogenic motor cooling for hydrogen-powered regional aircraft concepts. JIS standards for aerospace electromagnetic compatibility are converging toward FAA and EASA test protocols. The Nagoya aerospace cluster in Aichi Prefecture integrates electric actuator production with existing turbine engine supply chains.
Aircraft Electric Motor Market Competitive Landscape
The competitive structure tilts toward diversified aerospace conglomerates with integrated power distribution portfolios. Tier-one suppliers with safety-certification depth dominate flight control and propulsion-grade segments, while specialized motor fabricators compete on thermal performance customization. Three archetypes predominate: integrated power systems houses, flight-critical actuator specialists, and emerging turboelectric propulsion developers. Consolidation through strategic partnerships and technology licensing agreements is compressing supplier tiers around silicon carbide inverter integration.
Among diversified aerospace conglomerates, Safran Electrical & Power and GE Aerospace exemplify the integrated power systems archetype, anchoring European and North American electrification roadmaps respectively. Honeywell Aerospace occupies a position within the flight-critical actuator specialist tier, leveraging safety-certification depth across narrowbody platforms. These three entities represent the dominant competitive anchors shaping procurement authority and R&D investment flows in next-generation electric propulsion architectures.
| Leading Market Players |
|---|
| Moog Inc. |
| Safran Electrical & Power |
| GE Aerospace |
| Collins Aerospace |
| Honeywell Aerospace |
| AMETEK Inc. |
| Woodward Inc. |
| Rolls-Royce plc |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed rare earth processors in China anchor magnet supply for permanent-magnet motors, compressing pricing discipline among European and North American suppliers who must absorb volatility or qualify alternative chemistries. This ownership pattern concentrates upstream bargaining power while forcing downstream motor manufacturers into long-term offtake contracts that lock in cost structures across program lifecycles.
Pricing Analysis
Power-by-the-hour contracting dominates aftermarket electric actuation, separating hardware supply from digital health monitoring and predictive maintenance revenue streams. Price differentiation hinges on FAA Part 33 certification tier and thermal performance grade, with propulsion-grade motors commanding substantial premiums over auxiliary systems. Pricing pressure stems from airline procurement organizations unbundling service contracts to retain operational data ownership. Regional turboprop operators exhibit highest price sensitivity due to thin operating margins, while narrowbody fleet managers prioritize lifecycle reliability over first cost.
Supply Chain Analysis
Certification gating through FAA Part 33 and EASA CS-E standards concentrates qualified supplier pools, extending qualification timelines for new entrants. Magnet processing concentrates in China, with winding and thermal management subcomponent fabrication clustering in France and Germany. Raw material dependencies center on neodymium-dysprosium-terbium alloys, silicon carbide wafers, and high-temperature insulation systems. Single-source vulnerability in rare earth refining exposes motor manufacturers to export quota disruptions. Distribution runs through tier-one aerospace conglomerates who integrate motor-inverter subsystems for OEM direct supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aircraft electric motors rests on silicon carbide inverter integration collapsing subsystem boundaries, enabling suppliers to capture value previously ceded to discrete component vendors while meeting escalating power density requirements.
For Market Incumbents: To counter rare earth supply concentration, deepen backward integration into magnet recycling and alternative chemistry qualification programs. Anchor certification investment in FAA-EASA harmonized electromagnetic compatibility standards to compress redundant validation cycles. Prioritize captive supply of silicon carbide power modules through foundry partnerships or in-house packaging capabilities. For New Entrants and Emerging Players: Enter via urban air mobility motor supply, where eVTOL manufacturers lack incumbent supplier relationships and specify distributed architectures multiplying per-aircraft motor counts. Target thermal management subcomponent specialization for the Safran-Airbus cluster in France, where winding expertise scarcity creates qualification bottlenecks. Pursue power-by-the-hour service contracts as primary go-to-market mechanism rather than hardware-only supply. For Investors and Strategic Acquirers: Valuations sit cheapest among electromagnetic-thermal-structural simulation boutiques with aviation-specific competency sets that outpace university pipeline output. Long-term viability favors targets with embedded functional safety expertise aligned to EU AI Act cybersecurity certification tiers. Monitor EASA-FAA electromagnetic interference test protocol convergence as inflection indicator for qualification cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Enables switching frequencies above 20 kHz that reduce filter mass for Honeywell and GE Aerospace programs. |
| Rare Earth Magnet Recycling | Insulates Safran and European suppliers from Chinese export quota volatility through closed-loop material recovery. |
| EU AI Act Cybersecurity Certification | Creates first-mover advantage for motor drive suppliers with embedded functional safety software assurance. |
| Urban Air Mobility Motor Supply | Captures 8-16x per-aircraft motor multipliers as Archer and Joby specify distributed electric propulsion. |
| Power-by-the-Hour Service Contracts | Disintermediates aftermarket revenue from initial supply, responding to Air France-KLM data ownership demands. |
Research Methodology
Direct dialogue with electric propulsion program managers, electromagnetic compatibility test engineers, airline fleet procurement directors, and thermal management subsystem suppliers grounded qualitative findings. Secondary validation drew from FAA Part 33 certification databases, EASA CS-E amendment filings, EU Green Deal aviation clause documentation, and customs records tracking rare earth alloy trade flows. Bottom-up motor shipment estimates triangulated against top-down OEM procurement budget disclosures.
Segment-level value outputs across the projection horizon reflect motor type, technology formulation, application criticality tier, and end-user procurement authority. Modeled dimensions included power density class, voltage architecture, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, fleet electrification timelines, and turboelectric architecture penetration curves. Forecast inputs incorporated silicon carbide adoption rates and rare earth price elasticity assumptions.
Inputs from airline procurement organizations and tier-one supplier program offices were available through the study window; gaps in eVTOL manufacturer production volume disclosures introduce uncertainty bands around urban air mobility segment projections. Forecasts reflect assumptions regarding FAA-EASA certification harmonization progress and magnet supply diversification initiatives. A model refresh is warranted upon material change in Chinese rare earth export policy or EASA electromagnetic emissions standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market