
 Commercial Aircraft Actuation System Market | 2026-2036
Commercial Aircraft Actuation System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Actuation System Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from original equipment sales toward lifetime maintenance contracts. Honeywell International Inc. leverages its integrated avionics-actuation portfolio to capture recurring overhaul streams. Safran S.A. anchors European aftermarket capacity through its CFM engine control actuator installed base. Curtiss-Wright Corporation specializes in ruggedized electromechanical units for landing gear extensions, competing on mean-time-between-failure metrics.
A commercial aircraft actuation system converts electrical, hydraulic, or pneumatic energy into controlled mechanical motion to position flight surfaces, landing gear, and engine components, typically operating at pressures up to 5,000 psi in hydraulic variants and requiring fault-tolerant architectures with 10^-9 probability of catastrophic failure per flight hour. Electro-mechanical systems displace legacy hydraulic architectures in wing control applications, driven by weight reduction targets and simplified line-replaceable unit logistics. Fly-by-wire technology dominates new platform procurement, while direct cable systems persist in regional jet retrofits where certification costs constrain technology refresh cycles.
The Federal Aviation Administration mandates redundant actuation channels under FAR 25.671, compelling dual-source qualification for critical flight control surfaces. The European Union Aviation Safety Agency enforces CS-25 certification standards that harmonize with FAA requirements while adding environmental qualification protocols under REACH substance restrictions. Stakeholders must monitor emerging adaptive control architectures and their interaction with evolving airworthiness frameworks as more-electric aircraft programs advance toward production readiness.
Market Dynamics
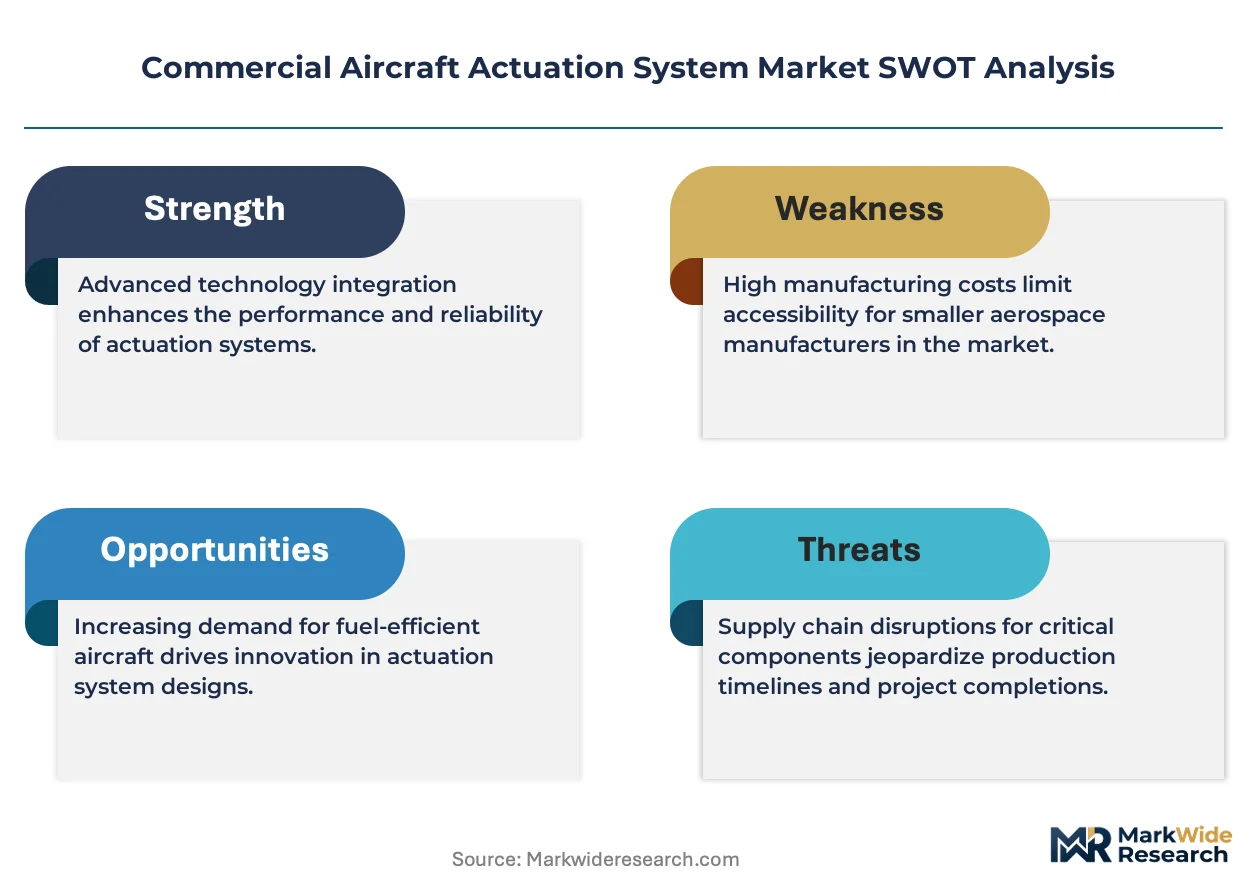
Electro-mechanical actuation architectures are compressing hydraulic system share in next-generation narrow-body programs, forcing suppliers to retool production lines and recertify component portfolios under tightened airworthiness protocols.
Growth Catalysts
- FAR 25.671 Redundancy Mandates:FAA flight control reliability standards compel dual-channel actuator configurations across primary surfaces, expanding addressable hardware volumes per airframe.
- CFRP Wing Integration:Composite airframe structures in Boeing 787 and Airbus A350 programs demand lighter electromechanical units that reduce cumulative weight penalties in control surface linkages.
- Narrow-Body Fleet Renewal:Airlines in the United States are retiring aging 737NG and A320ceo fleets, triggering procurement waves for integrated actuation packages in successor platforms.
Market Restraints
- Titanium Input Volatility:Precision-machined actuator housings depend on aerospace-grade titanium sponge, with spot price swings compressing fabrication margins.
- Single-Source Hydraulic Component Risk:Legacy pump and valve suppliers concentrate in the United States Midwest, creating geographic vulnerability to regional logistics disruptions.
- Electromechanical Torque Density Limits:Current motor-drive combinations fail to match hydraulic power-to-weight ratios in high-load primary flight control applications above single-aisle scale.
Strategic Opportunities
- Urban Air Mobility Electrification:eVTOL developers in Germany and the United States require fault-tolerant electromechanical actuators for distributed propulsion tilt-rotor mechanisms.
- REACH-Compliant Fluid Substitution:ECHA substance restrictions on phosphate ester hydraulic fluids create retrofit demand for sealed electromechanical alternatives in European-registered fleets.
- Predictive Maintenance Analytics:Sensor-embedded smart actuators enable condition-based overhaul scheduling, shifting revenue from scheduled maintenance to performance-guaranteed service agreements.
Industry Challenges
- DO-178C Software Certification Bottlenecks:Digital motor controllers require extensive verification cycles, stretching development timelines for fly-by-wire actuator programs.
- Legacy System Integration Friction:Hybrid architectures mixing electromechanical and hydraulic channels demand specialized test rigs that extend qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Actuation System Market |
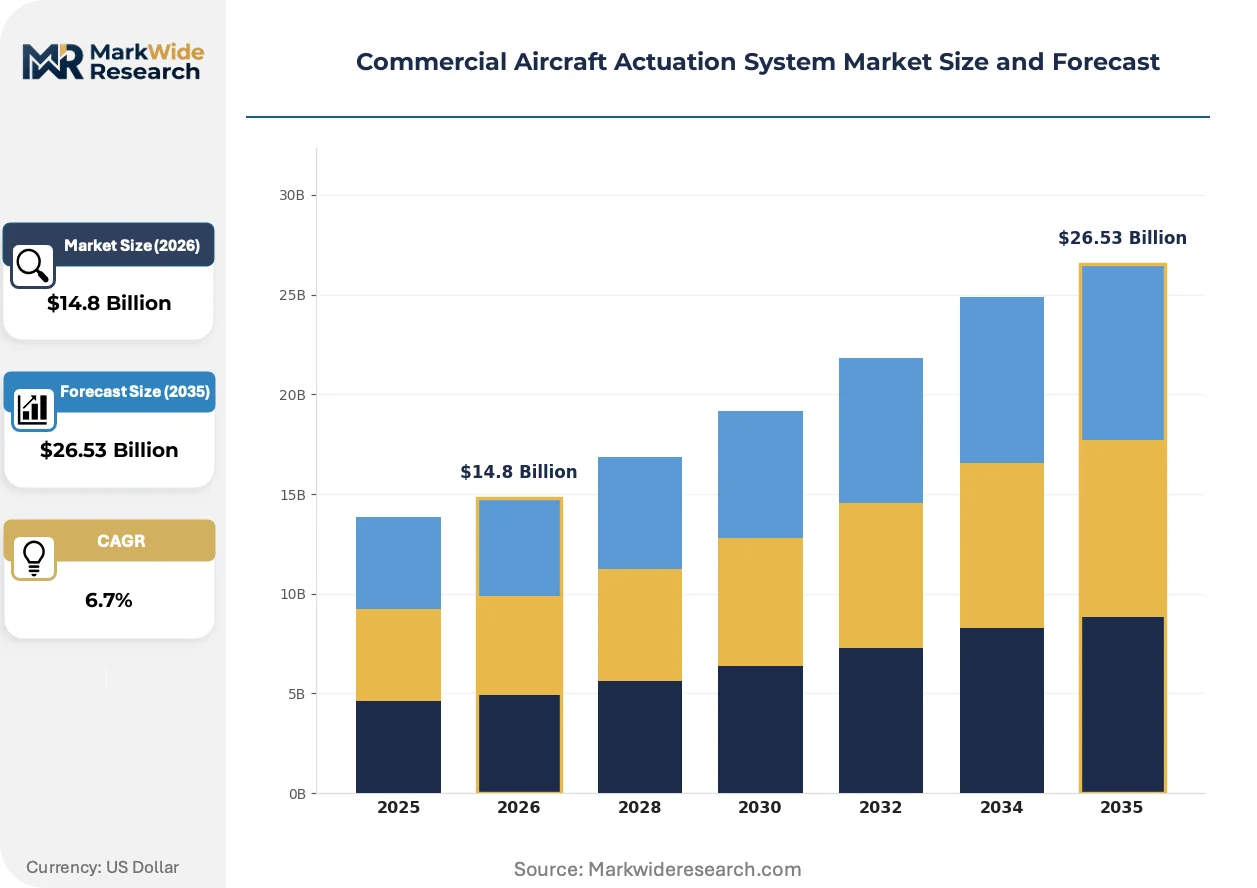
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Systems, Electrical Systems, Electro-Mechanical Systems, Pneumatic Systems Application: Wing Control, Landing Gear, Engine Control, Flight Control End User: Commercial Airlines, MRO Providers, OEMs, Aircraft Manufacturers Technology: Fly-By-Wire, Fly-By-Light, Direct Cable, Adaptive Control |
| Companies Covered | Honeywell International Inc., Safran S.A., Curtiss-Wright Corporation, Raytheon Technologies Corporation, Moog Inc., Parker Hannifin Corporation, Thales Group, Liebherr Group, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Actuation System Market Strategic Shifts
Power-by-wire architectures are collapsing the traditional boundary between flight control computers and surface actuators, embedding intelligence at the point of mechanical action and rewriting supplier value capture models.
Brushless DC torque motors with integrated position sensing are rendering obsolete centralized hydraulic distribution manifolds in spoiler and flap actuation. Airbus A220 and Embraer E2 programs specify these units for secondary flight surfaces. The shift eliminates miles of pressurized tubing, reducing leak-path failure modes and maintenance labor hours per flight cycle.
EASA CS-25 environmental qualification amendments now mandate extended temperature cycling and humidity exposure for electromechanical units installed in unpressurized wing bays. Manufacturers must demonstrate 60,000-hour operational life under combined thermal-mechanical stress profiles. European suppliers are accelerating investment in accelerated-life test chambers to compress certification timelines for next-generation narrow-body competitions.
Airline engineering departments are unbundling actuator overhaul contracts from airframe maintenance agreements, creating direct procurement relationships with component OEMs. Lufthansa Technik and Delta TechOps now negotiate power-by-the-hour arrangements bypassing traditional airframe MRO intermediaries. This restructuring concentrates pricing leverage with high-volume fleet operators in Germany and the United States.
Commercial Aircraft Actuation System Market Segmentation
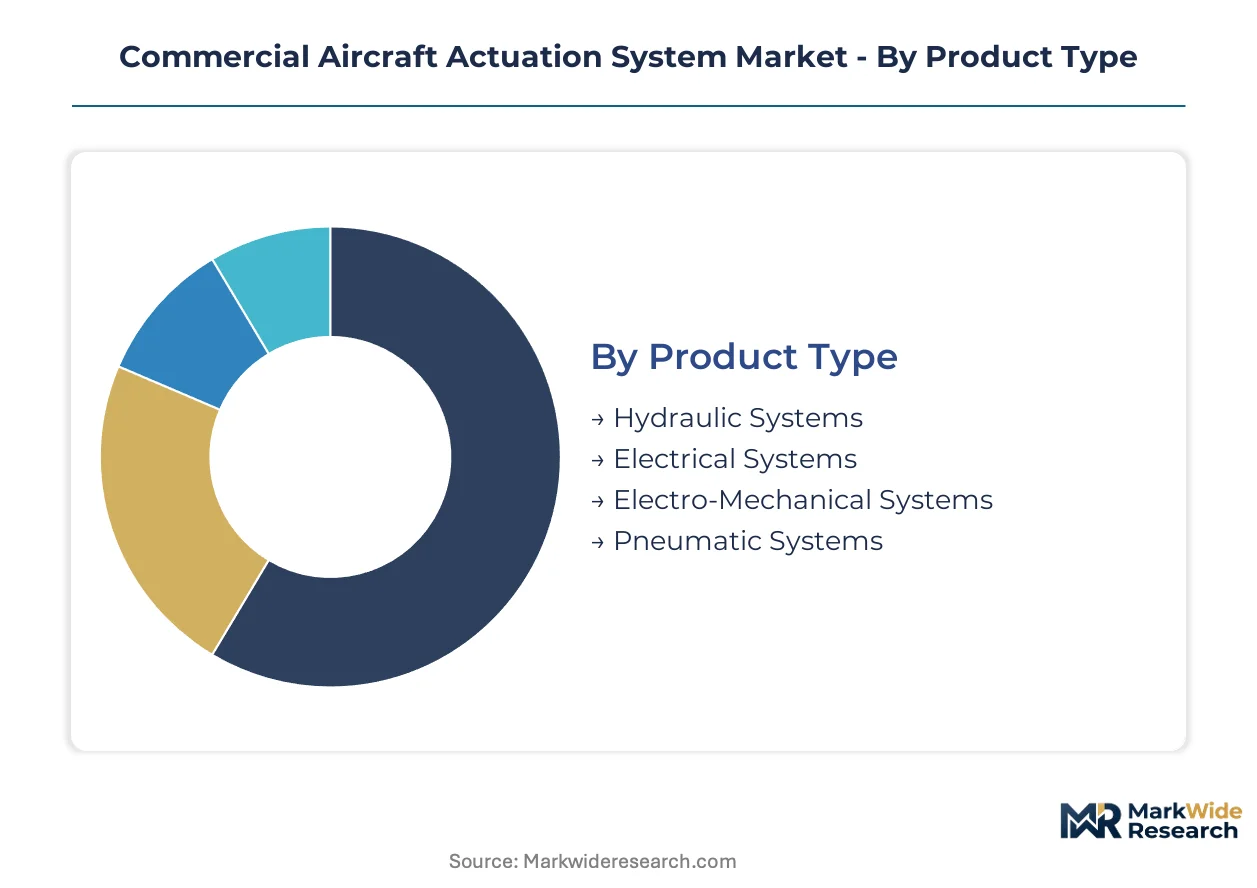
Actuation system procurement patterns diverge sharply across flight-criticality tiers and platform generations. Segment boundaries increasingly blur as hybrid architectures replace pure hydraulic or electromechanical implementations in next-generation narrow-body programs.
Product Type:
Platform weight targets and fault-tolerance requirements distribute demand across four energy conversion architectures with distinct power density and maintenance profiles.
- Hydraulic Systems:Pressurized fluid networks operating at 3,000-5,000 psi deliver unmatched force density for primary flight control surfaces in wide-body aircraft. Boeing 787 and Airbus A350 programs in the United States and France retain centralized hydraulic distribution for rudder and elevator actuation despite electromechanical encroachment elsewhere.
- Electro-Mechanical Systems:Brushless DC motor-gearbox combinations with integrated position feedback displace hydraulic units in spoiler and flap linkages where load cycles are moderate. CFRP wing structures in next-generation narrow-bodies favor these sealed units to eliminate leak-path corrosion risks in unpressurized bays.
- Electrical Systems:Pure electric architectures without mechanical gearing serve low-torque applications such as trim tabs and cargo door latches.
- Pneumatic Systems:Compressed air actuation persists in engine bleed valve control and emergency landing gear extension backups.
Established volume favors hydraulic systems; emerging adoption favors electro-mechanical systems.
Application:
Flight surface criticality determines certification rigor and supplier qualification barriers across four functional domains.
- Flight Control:Primary surface actuators for aileron, elevator, and rudder channels demand dual-redundant configurations under FAA FAR 25.671. Honeywell and Safran dominate procurement for these safety-critical channels in United States and European flagship programs.
- Landing Gear:High-load extension and retraction mechanisms combine hydraulic power with mechanical locking for fail-safe positioning. Curtiss-Wright electromechanical units are gaining share in regional jet nose gear applications where weight reduction offsets higher unit cost.
- Wing Control:Secondary surfaces including flaps, slats, and spoilers tolerate simpler single-channel architectures.
- Engine Control:Thrust reverser and variable stator vane actuation operates in extreme thermal environments.
Procurement concentration sits with flight control; technology refresh cycles are shortest in wing control.
End User:
Maintenance contract unbundling restructures purchasing relationships across four stakeholder categories with diverging technical capabilities.
- OEMs:Airframe manufacturers Boeing and Airbus source integrated actuation packages through multi-year sole-source agreements with tier-one suppliers. These contracts specify performance guarantees spanning development, production, and initial provisioning.
- MRO Providers:Delta TechOps and Lufthansa Technik negotiate direct component-level overhaul agreements bypassing traditional airframe maintenance intermediaries. Power-by-the-hour arrangements shift inventory risk to suppliers while capturing predictive maintenance value.
- Commercial Airlines:Fleet operators with in-house engineering capabilities increasingly specify actuator refurbishment protocols independent of airframe MRO contracts.
- Aircraft Manufacturers:Regional jet and business aviation OEMs procure off-the-shelf actuation modules with reduced customization.
Contracting leverage concentrates with MRO providers; specification authority remains with OEMs.
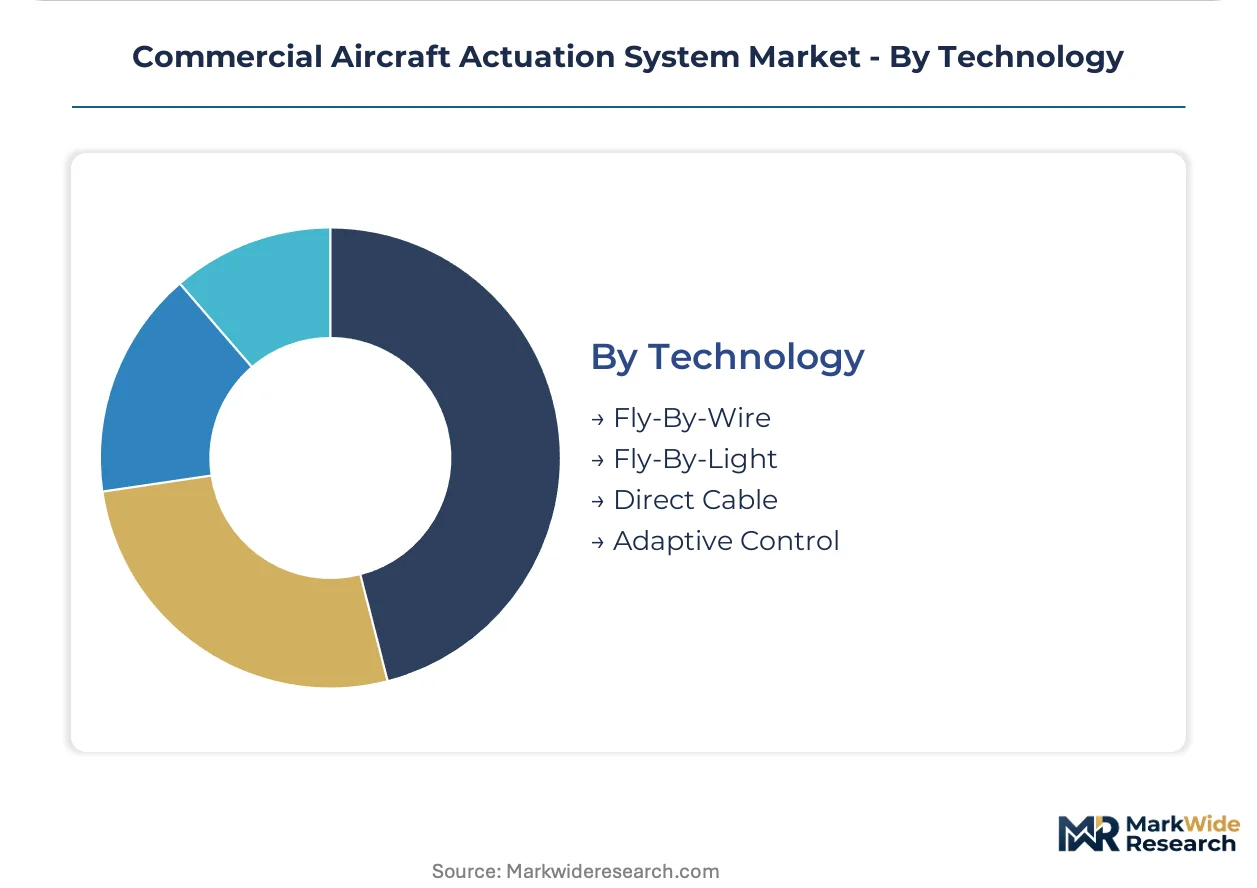
Technology:
Control signal transmission methods segment by platform vintage and certification investment capacity across four architectural generations.
- Fly-By-Wire:Digital flight control computers command surface actuators through shielded data buses, eliminating mechanical linkages. Airbus A320 family and Boeing 777 programs established this architecture; all clean-sheet narrow-bodies now mandate FBW for handling quality and envelope protection.
- Adaptive Control:Real-time gain scheduling and fault-accommodation algorithms embed intelligence at actuator nodes. These architectures support more-electric aircraft programs advancing toward production readiness in Germany and the United States.
- Fly-By-Light:Optical fiber transmission offers electromagnetic immunity for military derivatives and future commercial platforms.
- Direct Cable:Mechanical pushrod and cable systems persist in regional jet retrofits where certification costs constrain technology refresh.
Fly-by-wire anchors current production; adaptive control architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: mature aviation markets prioritize aftermarket service contracts and fleet renewal actuation packages, while emerging aerospace clusters concentrate on component fabrication and MRO capacity expansion.
United States
Boeing's supply chain in Washington State and South Carolina drives procurement volumes for next-generation narrow-body actuation platforms. FAA FAR 25.671 redundancy mandates compel dual-channel configurations across primary flight surfaces. Wichita, Kansas anchors a dense cluster of hydraulic component fabricators serving both OEM and MRO channels.
Germany
Lufthansa Technik's power-by-the-hour arrangements reshape direct procurement relationships with component OEMs. EASA CS-25 environmental qualification amendments mandate extended temperature cycling for electromechanical units. Hamburg and Munich host specialized test chamber facilities compressing certification timelines for European-registered fleet retrofits.
France
Airbus final assembly lines in Toulouse generate integrated actuation package demand for A320neo and A350 programs. REACH substance restrictions on phosphate ester hydraulic fluids create retrofit demand for sealed electromechanical alternatives. The Paris-Saclay corridor concentrates adaptive control architecture development for more-electric aircraft initiatives.
China
Comac C919 production ramp-up stimulates domestic qualification of flight control actuation suppliers. The country's national aviation regulator enforces airworthiness standards harmonized with FAA and EASA frameworks. Xi'an and Chengdu industrial zones attract joint ventures for landing gear electromechanical unit fabrication.
United Kingdom
Rolls-Royce engine programs in Derby sustain demand for thrust reverser and variable stator vane actuation. The Civil Aviation Authority maintains certification reciprocity with EASA post-Brexit, preserving market access for UK-based suppliers. Bristol's aerospace cluster specializes in sensor-embedded smart actuators enabling predictive maintenance analytics.
Commercial Aircraft Actuation System Market Competitive Environment
Capability concentration sits with tier-one integrated system suppliers; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: full-flight-control integrators, component specialists, and regional MRO service providers. Strategic archetypes include avionics-actuation portfolio bundlers, electromechanical ruggedization experts, and aftermarket overhaul capacity builders. Dominant competitive moves encompass dual-source qualification partnerships and predictive maintenance service contract capture.
Among North American diversified industrials, Honeywell International Inc. and Curtiss-Wright Corporation exemplify contrasting positioning archetypes. Honeywell occupies a position as an integrated avionics-actuation portfolio bundler capturing recurring overhaul streams. Curtiss-Wright represents specialization in ruggedized electromechanical units competing on reliability metrics. Safran S.A. anchors European aftermarket capacity through its installed base presence. These three entities collectively illustrate the geographic bifurcation between United States-based system integrators and European component OEMs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran S.A. |
| Curtiss-Wright Corporation |
| Raytheon Technologies Corporation |
| Moog Inc. |
| Parker Hannifin Corporation |
| Thales Group |
| Liebherr Group |
| Leonardo S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Wichita, Kansas anchors North American hydraulic component fabrication, and its capacity utilization rates directly modulate pricing power for precision-machined actuator housings across OEM and MRO channels. Titanium sponge spot volatility feeds through this cluster, compressing margins on long-term offtake contracts while spot purchasers absorb sharper cost swings.
Pricing Analysis
Long-term offtake agreements dominate procurement between Boeing, Airbus, and tier-one suppliers, locking in volume commitments across multi-year production horizons. Price differentiation rests on FAA dual-source qualification status and after-sales service bundling, with certified redundant-channel actuators commanding substantial premiums over single-source alternatives. Cost compression in narrow-body electromechanical tiers is intensifying because CFRP wing integration mandates lighter sealed units with accelerated certification timelines. Fleet operators with power-by-the-hour arrangements exhibit lowest price sensitivity; regional jet OEMs purchasing off-the-shelf modules face acute margin pressure.
Supply Chain Analysis
Parker Hannifin and Moog operate captive manufacturing facilities across the United States, France, and Germany, concentrating precision machining and motor-drive assembly in aerospace-qualified zones. Raw material flows draw from aerospace-grade titanium sponge, rare-earth permanent magnets, and high-temperature electrical steels. Single-source hydraulic pump concentration in the Midwest creates geographic vulnerability to regional logistics disruptions. Distribution runs through Boeing and Airbus final assembly lines, with secondary channels serving Lufthansa Technik and Delta TechOps for direct overhaul procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-by-wire architectures are collapsing traditional boundaries between flight control computers and actuators, embedding intelligence at mechanical nodes and rewriting supplier value capture models around predictive maintenance ecosystems.
For Market Incumbents: Entrench dual-source qualification partnerships with Boeing and Airbus to lock out electromechanical specialists from primary flight control channels. Accelerate in-house production of brushless DC torque motors to offset rare-earth magnet supply exposure, while embedding sensor arrays that enable condition-based overhaul scheduling before competitors capture MRO relationships.
For New Entrants and Emerging Players: China's Comac C919 supplier qualification gap offers the most penetrable entry point for electromechanical landing gear units, as domestic joint ventures in Xi'an and Chengdu seek foreign technology transfer. Target eVTOL tilt-rotor mechanisms in Germany and the United States, where fault-tolerant distributed propulsion actuators lack established supply bases. Pursue EASA REACH-compliant fluid substitution retrofits as a regulatory-mandated wedge into European-registered fleets.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because aftermarket service contracts are unbundling from airframe MRO agreements and concentrating pricing leverage with high-volume fleet operators. Acquisition targets should display sensor-embedded smart actuator portfolios with demonstrated predictive maintenance analytics. Monitor EASA CS-25 environmental qualification amendment implementation timelines as the signal for electromechanical certification bottleneck resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Qualification Partnership | Locks in Boeing 737 MAX and Airbus A320neo primary flight control actuator volumes under FAR 25.671 mandates. |
| Predictive Maintenance Platform Development | Enables power-by-the-hour contracts with Delta TechOps and Lufthansa Technik bypassing traditional MRO intermediaries. |
| REACH-Compliant Electromechanical Retrofit | Captures European fleet demand as ECHA phosphate ester restrictions phase out legacy hydraulic architectures. |
| Rare-Earth Magnet Supply Securement | Mitigates brushless DC motor cost volatility through long-term offtake with Chinese or Australian rare-earth processors. |
| eVTOL Tilt-Rotor Actuator Certification | Positions for Urban Air Mobility distributed propulsion requirements in German and US regulatory frameworks. |
Study Parameters
Initial hypotheses were tested against primary input from flight control system engineers, airline fleet procurement managers, MRO overhaul specialists, and FAA certification leads, and refined through secondary validation against EASA CS-25 amendment documentation, FAA airworthiness directive filings, SEC 10-K aerospace segment disclosures, and customs trade data on titanium sponge and rare-earth magnet flows. Bottom-up actuator unit demand estimates were triangulated with top-down commercial aircraft production forecasts across the analysis window.
Demand-supply-balance framing anchored the analytical approach, modeling narrow-body and wide-body platform delivery schedules against tier-one supplier capacity expansion timelines throughout the forecast period. Segmentation dimensions included actuation architecture type, flight criticality tier, end-user contracting structure, and regional regulatory cluster. CAGRs were derived from production ramp assumptions and fleet renewal cycle phasing, with specific inputs from Boeing and Airbus order backlogs and Lufthansa Technik power-by-the-hour contract penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese joint ventures or accelerated eVTOL certification timelines would shift outcomes beyond modeled boundaries. Quarterly review of EASA environmental qualification amendment implementation, Comac C919 production rate achievements, and titanium sponge spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market