
 Air Independent Propulsion Systems (AIP) Market | 2026-2036
Air Independent Propulsion Systems (AIP) Market Size, Share, and Industry Trends Forecast 2026-2036
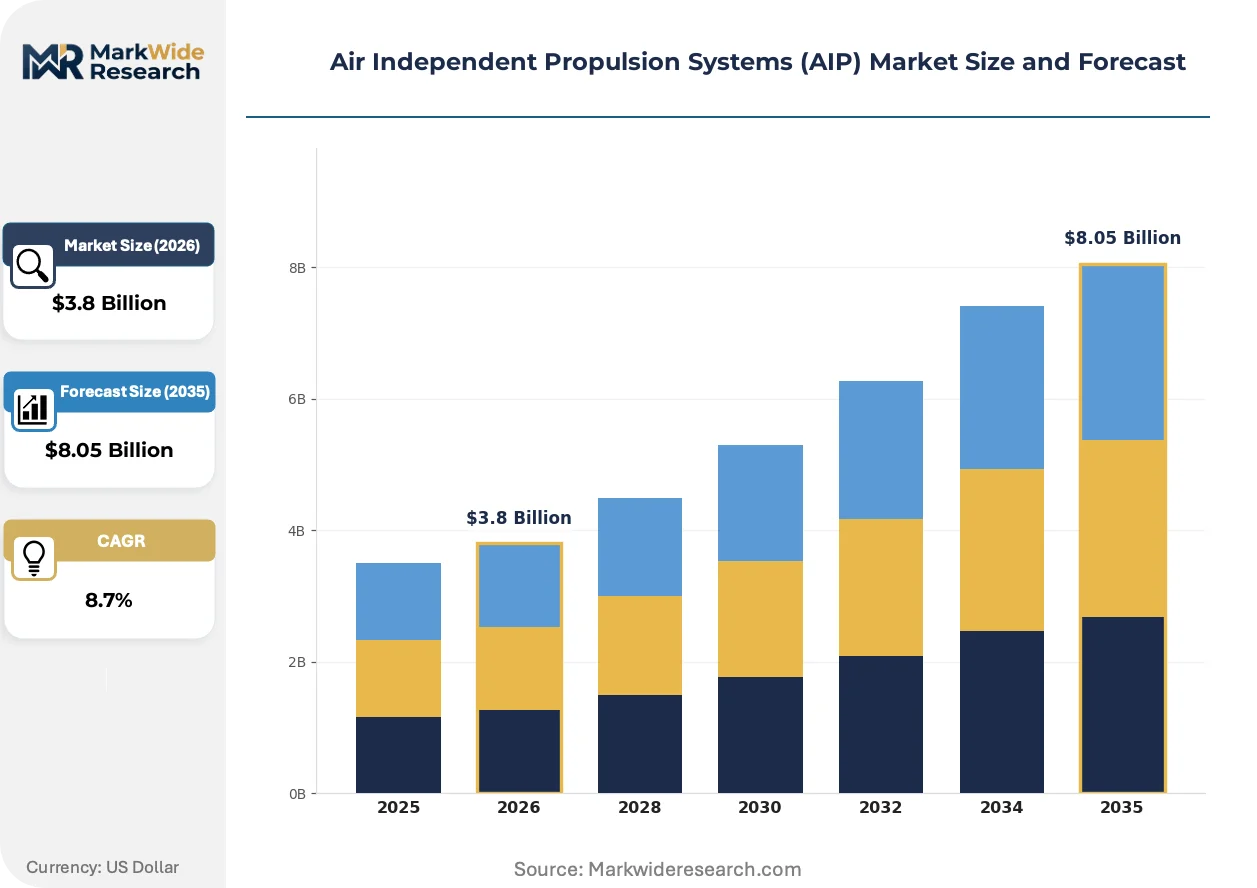
Air Independent Propulsion Systems (AIP) Market Outlook
The divergence between premium fuel-cell AIP systems and commodity Stirling-based alternatives is hardening as defense procurement prioritizes stealth endurance over cost minimization. Thyssenkrupp Marine Systems leverages its integrated submarine architecture to dominate European naval programs. Saab AB anchors Nordic supply chains through specialized Stirling engine production for Gotland-class upgrades. Siemens AG competes on fuel cell stack density, positioning its proton-exchange membrane technology for next-generation U-boat contracts.
Air Independent Propulsion Systems enable submerged operation without atmospheric oxygen intake, typically achieving two to four weeks of submerged endurance through closed-cycle combustion or electrochemical generation. Fuel cell technology leads segment margins due to minimal thermal signature and hydrogen-oxygen reaction efficiency, while Stirling engine systems retain cost advantages in retrofit programs. Military submarines command the dominant application share as naval forces replace diesel-electric fleets with AIP-enhanced vessels; underwater drones represent the fastest-growing application as autonomous systems extend mission duration for mine countermeasures and intelligence collection.
German procurement authorities under BAAINBw enforce Bundeswehr Technical Requirement standards that mandate specific acoustic and magnetic signature thresholds for AIP integration. France's DGA applies MCO certification protocols that constrain foreign subsystem access in Barracuda-class programs. Sweden's FMV coordinates Nordic interoperability standards through joint submarine development with Saab. Stakeholders must monitor how export control tightening around fuel cell membranes and hydrogen storage alloys reshapes supplier qualification timelines and program risk profiles.
Market Dynamics
Naval procurement offices across NATO member states are consolidating submarine modernization budgets around fuel-cell AIP architectures, compressing Stirling engine margins while elevating electrochemical system suppliers into long-term fleet partnerships.
Growth Catalysts
- NATO acoustic signature mandates:Alliance submarine interoperability standards now require thermal and magnetic suppression thresholds that only fuel-cell systems reliably achieve, redirecting procurement toward electrochemical platforms.
- Hydrogen storage alloy advances:Solid-state metal hydride containment systems enable safer high-pressure hydrogen carriage aboard compact submarine hulls, extending submerged endurance without atmospheric intake.
- Mine countermeasure drone programs:Naval forces in Germany, France, and Sweden are commissioning extended-range autonomous underwater vehicles requiring AIP modules for covert seabed operations.
Market Restraints
- Platinum group metal supply concentration:Proton-exchange membrane fuel cells require iridium and platinum catalysts sourced primarily from South African and Russian mining operations, exposing stack production to geopolitical disruption.
- France's DGA MCO certification barriers:Defense procurement protocols for Barracuda-class submarines restrict foreign subsystem participation, fragmenting supplier qualification timelines across European programs.
- Stirling engine cost floor:Mature closed-cycle combustion technology retains installed base economics that slow fuel-cell conversion in budget-constrained retrofit contracts.
Strategic Opportunities
- Underwater intelligence platform expansion:Signals intelligence collection missions by autonomous underwater vehicles create demand for compact, silent AIP modules in Sweden's Gotland archipelago and German Baltic deployments.
- EU Green Deal defense procurement alignment:Carbon-neutral hydrogen production mandates for military applications are steering R&D funding toward renewable electrolysis integration with submarine fueling infrastructure.
- Modular AIP retrofit kits:Containerized plug-in systems enable diesel-electric submarine life extension without hull reconstruction, opening mid-tier naval forces to technology insertion.
Industry Challenges
- Submarine-qualified fuel cell engineering talent scarcity:The intersection of marine pressure vessel certification and electrochemical stack design demands specialists that naval contractors in Germany and France struggle to recruit.
- Hydrogen embrittlement material validation:High-pressure containment systems require decade-long fatigue testing under NATO STANAG protocols before hull integration approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Independent Propulsion Systems (AIP) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fuel Cells, Stirling Engine, Biofuel Systems, Thermal Electric Application: Military Submarines, Research Vessels, Commercial Shipping, Underwater Drones Component: Energy Storage, Generator, Propulsor, Control Systems End User: Defense Contractors, Shipping Companies, Research Institutions, Government Agencies |
| Companies Covered | Saab AB, Thyssenkrupp Marine Systems, Naval Group, Siemens AG, Lockheed Martin Corporation, General Dynamics Corporation, China Shipbuilding Industry Co. Ltd, Kongsberg Gruppen ASA, United Shipbuilding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Independent Propulsion Systems (AIP) Market Strategic Shifts
Electrochemical generation architectures are displacing thermal combustion across submarine propulsion, while regulatory pressure on acoustic signatures accelerates material science investment in hydrogen containment and membrane density.
Solid-state proton-exchange membrane technology is absorbing development resources from Stirling engine programs as naval architects prioritize thermal signature elimination over mechanical simplicity. German procurement authorities under BAAINBw are specifying membrane power densities above four kilowatts per cubic meter for next-generation U-boat contracts. This electrochemical shift is compressing the addressable market for closed-cycle combustion suppliers while elevating fuel-cell stack manufacturers into prime contractor relationships.
Germany's KBA and BAAINBw are enforcing Bundeswehr Technical Requirement standards that mandate specific acoustic and magnetic signature thresholds for all AIP-integrated submarine platforms. These regulations disqualify louder thermal combustion systems from new-build competitions while creating compliance documentation burdens that favor established fuel-cell suppliers with certification histories. French and Swedish procurement offices are harmonizing their technical specifications with these German standards through NATO working groups.
Naval procurement offices are consolidating vendor relationships around single-source fuel-cell system integrators capable of delivering complete propulsion architectures rather than discrete subcomponents. This buyer concentration is displacing modular procurement models where shipyards sourced Stirling engines, hydrogen tanks, and control electronics from separate suppliers. The shift is most visible in German and French submarine programs, where Thyssenkrupp Marine Systems and Naval Group now specify fully integrated AIP packages from qualified system houses.
Air Independent Propulsion Systems (AIP) Market Segmentation
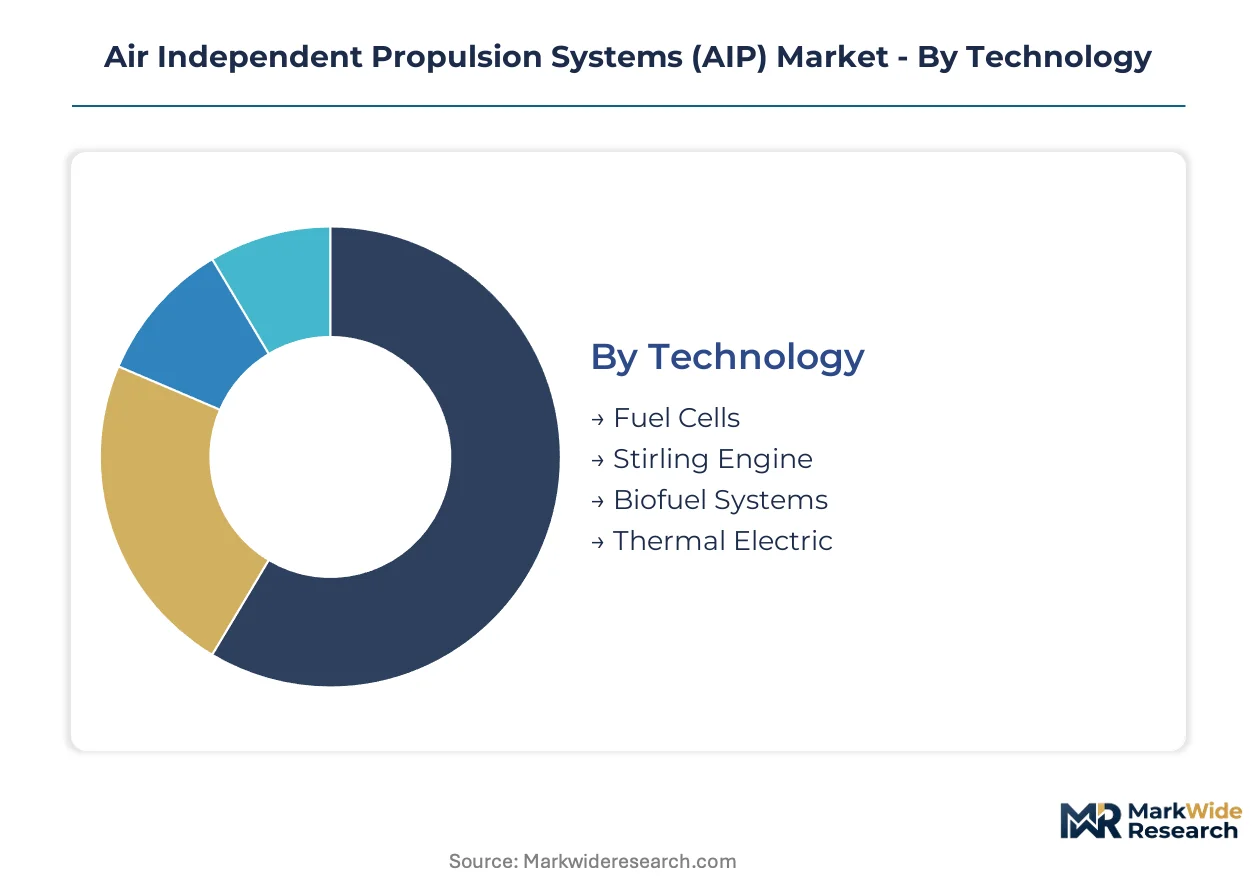
Segmentation in AIP markets reveals how procurement priorities diverge across stealth requirements, endurance specifications, and platform integration complexity. Buyers select technology architectures based on signature thresholds, mission duration needs, and hull modification feasibility.
Technology:
Defense procurement offices prioritize thermal signature suppression when selecting propulsion architectures, elevating electrochemical systems over combustion alternatives in NATO fleet modernization.
- Fuel Cells:Proton-exchange membrane stacks generate power through hydrogen-oxygen electrochemical reaction, eliminating exhaust thermal signatures. German BAAINBw specifications for next-generation U-boats mandate fuel-cell architectures for Barracuda-class and Type 212CD programs, with Siemens AG and Thyssenkrupp Marine Systems dominating stack density competitions above four kilowatts per cubic meter.
- Stirling Engine:Closed-cycle external combustion converts heat to mechanical work through helium or hydrogen working fluid displacement. Saab AB anchors Nordic supply chains for Gotland-class upgrades, where Sweden's FMV coordinates interoperability standards permitting cost-effective retrofit without hull reconstruction.
- Biofuel Systems:Synthetic hydrocarbon derivatives enable carbon-neutral submerged operation through reformer-integrated fuel processing.
- Thermal Electric:Solid-state thermocouple arrays convert temperature differentials directly to electrical output for low-power auxiliary applications.
Fuel Cells lead on scale; Underwater Drones lead on momentum when considering technology-platform intersections.
Application:
Mission profile determines endurance requirements, with intelligence collection and seabed warfare driving demand for extended submerged operation without atmospheric intake.
- Military Submarines:Diesel-electric fleet replacement programs across Germany, France, and Sweden mandate AIP integration for operational stealth. BAAINBw, DGA, and FMV procurement timelines concentrate demand in European naval modernization budgets, with fuel-cell systems displacing Stirling alternatives in new-build competitions.
- Underwater Drones:Autonomous mine countermeasure platforms require compact silent propulsion for covert seabed operations. German and Swedish naval forces commission extended-range AUV programs, with modular fuel-cell units enabling intelligence collection missions in the Gotland archipelago and Baltic deployments.
- Research Vessels:Scientific submersibles employ AIP for deep-ocean survey endurance without surface support.
- Commercial Shipping:Cargo submarine concepts explore AIP for Arctic route feasibility under ice cover.
Military Submarines lead on scale; Underwater Drones expand most quickly.
Component:
System integration complexity concentrates procurement around qualified suppliers capable of delivering pressure-rated subassemblies under NATO STANAG protocols.
- Energy Storage:Solid-state metal hydride containment systems enable safer high-pressure hydrogen carriage aboard compact submarine hulls, extending submerged endurance.
- Generator:Fuel-cell stack and Stirling engine power units demand marine pressure vessel certification intersecting electrochemical engineering specialization.
- Propulsor:Magnetohydrodynamic and pump-jet configurations integrate with AIP power profiles for acoustic signature minimization.
- Control Systems:Automated power management balances oxygen consumption rates against mission duration requirements.
Energy Storage leads on scale; Control Systems lead on momentum.
End User:
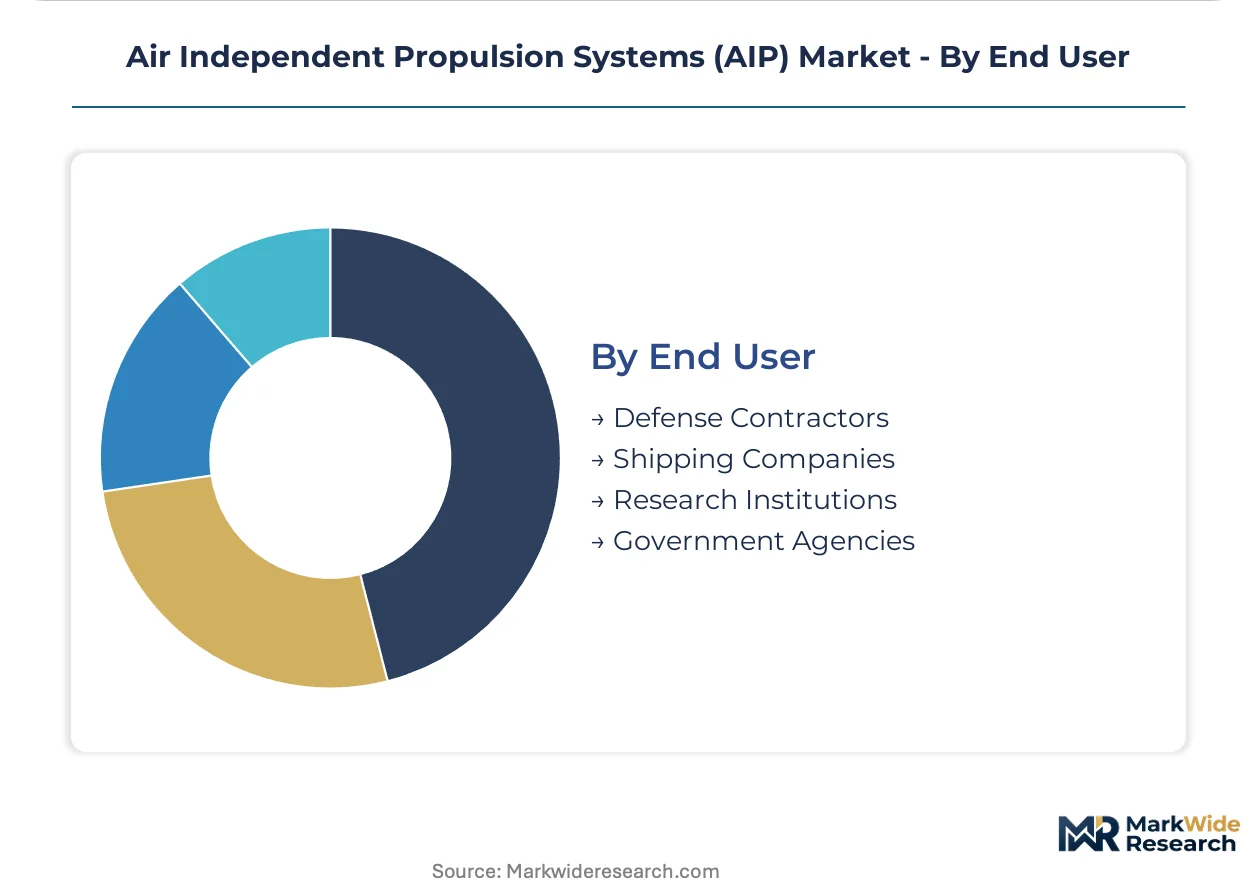
Contractual risk allocation differs between sovereign procurement offices and commercial operators, with defense agencies absorbing certification timelines unavailable to private buyers.
- Defense Contractors:Naval Group, Thyssenkrupp Marine Systems, and Saab AB integrate AIP as prime contractor responsibility under government fleet replacement programs.
- Government Agencies:BAAINBw, DGA, and FMV specify technical requirements and certify subsystem qualification for national security applications.
- Research Institutions:Oceanographic organizations procure AIP modules for crewed and uncrewed deep-sea exploration platforms.
- Shipping Companies:Commercial submarine operators evaluate AIP for specialized cargo routes requiring ice-capable transit.
Defense Contractors lead on scale; Government Agencies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine propulsion engineers concentrate in Northern European naval clusters, where submarine-qualified electrochemical stack designers and pressure vessel certification specialists anchor the industry's geographic footprint.
Germany
BAAINBw procurement timelines drive fuel-cell AIP demand for Type 212CD submarine programs. The Bundeswehr Technical Requirement standards mandate acoustic and magnetic signature thresholds that disqualify thermal combustion alternatives. Kiel and Hamburg host Thyssenkrupp Marine Systems and Siemens AG engineering centers where proton-exchange membrane stack density competitions exceed four kilowatts per cubic meter.
France
DGA MCO certification protocols constrain foreign subsystem participation in Barracuda-class submarine programs. The country's national defense procurement agency enforces qualification barriers that fragment supplier timelines across European naval modernization efforts. Cherbourg and Toulon cluster Naval Group integration facilities where fully packaged AIP architectures displace modular procurement models.
Sweden
FMV coordinates Nordic interoperability standards through joint submarine development with Saab AB. Gotland-class upgrade programs sustain Stirling engine production for cost-effective retrofit without hull reconstruction. Karlskrona anchors specialized closed-cycle combustion engineering where Sweden's defense materiel administration balances stealth requirements against budget constraints.
United States
Naval Sea Systems Command specifications for next-generation autonomous underwater vehicles create demand for compact silent propulsion modules. The country's defense procurement offices prioritize mine countermeasure drone programs requiring extended submerged endurance. Newport News and Groton cluster submarine engineering centers where General Dynamics Corporation and Lockheed Martin Corporation advance fuel-cell integration for intelligence collection platforms.
China
China Shipbuilding Industry Co. Ltd dominates domestic submarine construction with indigenous AIP development programs. The country's naval modernization accelerates closed-cycle propulsion adoption across diesel-electric fleet replacements. Dalian and Wuhan host pressure vessel certification facilities where state-owned shipyards integrate metal hydride hydrogen storage systems for extended submerged operations.
Air Independent Propulsion Systems (AIP) Market Competitive Environment
Capital-heavy systems integrators compete with specialized component designers across submarine propulsion architectures. Market structure concentrates around prime contractors capable of delivering complete AIP packages under NATO STANAG protocols, compressing margins for discrete subsystem suppliers. Three archetypes dominate: integrated platform builders, electrochemical stack specialists, and closed-cycle combustion engineers. Competitive moves center on long-term fleet partnership consolidation and certification history accumulation rather than price-based rivalry.
Among European integrated platform builders, Thyssenkrupp Marine Systems and Naval Group occupy positions as prime contractors specifying fully packaged AIP architectures for national submarine programs. Siemens AG represents the electrochemical stack specialist archetype, competing on proton-exchange membrane power density metrics for next-generation U-boat contracts. Saab AB anchors the closed-cycle combustion tier, exemplifying Nordic supply chain concentration for Stirling engine production in regional retrofit programs.
| Leading Market Players |
|---|
| Saab AB |
| Thyssenkrupp Marine Systems |
| Naval Group |
| Siemens AG |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| China Shipbuilding Industry Co. Ltd |
| Kongsberg Gruppen ASA |
| United Shipbuilding Corporation |
| Others |
Value Chain & Pricing Dynamics
Naval procurement offices in Germany, France, and Sweden concentrate demand around integrated platform builders, compressing margins for discrete subsystem suppliers and elevating long-term contract pricing over transactional component sales. BAAINBw and DGA fleet replacement programs anchor pricing power with prime contractors capable of delivering complete AIP architectures under NATO STANAG protocols.
Pricing Analysis
Bundled system integration dominates procurement, with Thyssenkrupp Marine Systems and Naval Group commanding premium pricing for fully packaged fuel-cell architectures while unbundled Stirling engine components face commoditization. Price differentiation rests on NATO certification history and membrane power density performance, with certified suppliers capturing fleet partnership premiums. Cost compression runs through Stirling retrofit tiers as budget-constrained navies prioritize hull-compatible upgrades over new-build electrochemical systems. Government defense contractors exhibit lowest price sensitivity; commercial shipping operators evaluating cargo submarine concepts demonstrate highest elasticity.
Supply Chain Analysis
Platinum group metal supply rests on South African and Russian mining operations, exposing proton-exchange membrane fuel cell production to geopolitical disruption. Solid-state metal hydride hydrogen storage systems draw from Japanese and German specialty alloy producers, while pressure vessel certification concentrates in Northern European naval clusters. Single-source vulnerability around iridium and platinum catalysts creates supply chain risk given limited alternative sourcing. Distribution runs through sovereign procurement channels where BAAINBw, DGA, and FMV qualify subsystem suppliers under national security protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory mandate intensity, with NATO acoustic signature standards for thermal and magnetic suppression driving procurement toward electrochemical platforms and away from legacy combustion alternatives.
For Market Incumbents: To counter margin compression from Stirling engine commoditization, fuel-cell specialists should deepen backward integration into membrane catalyst production and secure captive hydrogen storage alloy supply. Naval Group and Thyssenkrupp Marine Systems must accumulate NATO STANAG certification histories that create qualification barriers for emerging stack suppliers. For New Entrants and Emerging Players: Modular AIP retrofit kits for mid-tier diesel-electric fleets represent the most penetrable white-space, with containerized plug-in systems enabling technology insertion without hull reconstruction. Underwater drone propulsion modules for mine countermeasure programs offer secondary entry, with compact fuel-cell units serving Swedish and German Baltic deployments. Go-to-market positioning should emphasize STANAG pre-certification investment to accelerate sovereign procurement timelines. For Investors and Strategic Acquirers: Defense prime contractors are the most active acquirer in this space, with Naval Group and Lockheed Martin Corporation consolidating fuel-cell stack specialists to secure vertical control over propulsion architectures. Long-term viability favors targets with decade-long NATO certification histories and active fleet service records. The signal to watch is export control tightening around fuel cell membranes and hydrogen storage alloys, which would accelerate supplier qualification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Power Density Advancement | Siemens AG and competitors race to exceed BAAINBw's four kilowatt-per-cubic-meter threshold for Type 212CD programs. |
| Metal Hydride Hydrogen Storage Scale-Up | Solid-state containment systems enable safer high-pressure carriage aboard compact submarine hulls. |
| Modular AIP Retrofit Kit Development | Containerized systems open mid-tier naval forces to technology insertion without hull reconstruction. |
| NATO STANAG Certification Accumulation | Qualification histories create supplier barriers that compress competitor addressable markets. |
| Underwater Drone Propulsion Integration | Autonomous mine countermeasure programs in Germany and Sweden demand compact silent modules. |
Study Parameters
Direct dialogue with submarine program managers at BAAINBw, DGA, and FMV; fuel-cell stack engineering directors at Siemens AG and Thyssenkrupp Marine Systems; and NATO standardization committee members grounded qualitative assessment. Secondary validation drew from naval procurement budget disclosures, submarine construction contract awards, and STANAG protocol documentation. Bottom-up segment sizing triangulated against top-down fleet replacement projections across the analysis window.
Model outputs span value and volume trajectories across technology, application, component, and end-user dimensions, with electrochemical versus thermal combustion splits and military submarine versus underwater drone growth differentials explicitly parameterized. CAGRs derive from regression against historical procurement cycles and fleet modernization announcements. Hydrogen storage alloy cost curves and platinum group metal supply elasticity informed fuel-cell system cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control tightening around catalyst materials and Nordic defense budget allocation shifts. Assumptions reflect sovereign procurement timelines and NATO standardization harmonization progress. Geopolitical disruption to South African or Russian platinum group metal supply and DGA MCO certification barrier evolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market