
 Hydrogen-Powered Aircraft Market | 2026-2036
Hydrogen-Powered Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen-Powered Aircraft Market Insights
A capital-intensity divergence between well-funded incumbents and venture-backed startups is reorganizing competitive dynamics in hydrogen aviation. Airbus SE leverages its integrated airframe-engineering ecosystem to validate cryogenic hydrogen architectures at scale. ZeroAvia Inc anchors its position through intensive ground-testing of fuel-cell propulsion stacks for regional turboprop retrofits.
Hydrogen-powered aircraft are fixed-wing, rotary-wing, or unmanned aerial vehicles that utilize hydrogen fuel cells, combustion turbines, or hybrid-electric systems to generate thrust, typically storing fuel in liquid or compressed gaseous form at sub-zero temperatures to achieve energy density sufficient for commercial flight operations. The primary purpose is to eliminate carbon dioxide emissions from aviation propulsion while maintaining payload-range economics comparable to conventional kerosene aircraft. Fuel cell propulsion systems currently attract the majority of R&D investment due to their superior thermal efficiency and zero nitrogen oxide emissions at point of use. Commuter aviation applications lead near-term deployment timelines, as short-haul routes minimize hydrogen storage volume constraints and enable faster regulatory certification cycles.
The EU Green Deal and its accompanying ReFuelEU Aviation mandate shape product standards by requiring progressive blending of sustainable aviation fuels, with hydrogen explicitly recognized as a zero-emission pathway. The FAA and EASA coordinate certification frameworks for novel propulsion architectures, creating dual-track compliance requirements for manufacturers targeting transatlantic markets. Stakeholders must monitor hydrogen liquefaction infrastructure buildouts and airport fueling standardization to time fleet deployment decisions against operational readiness thresholds.
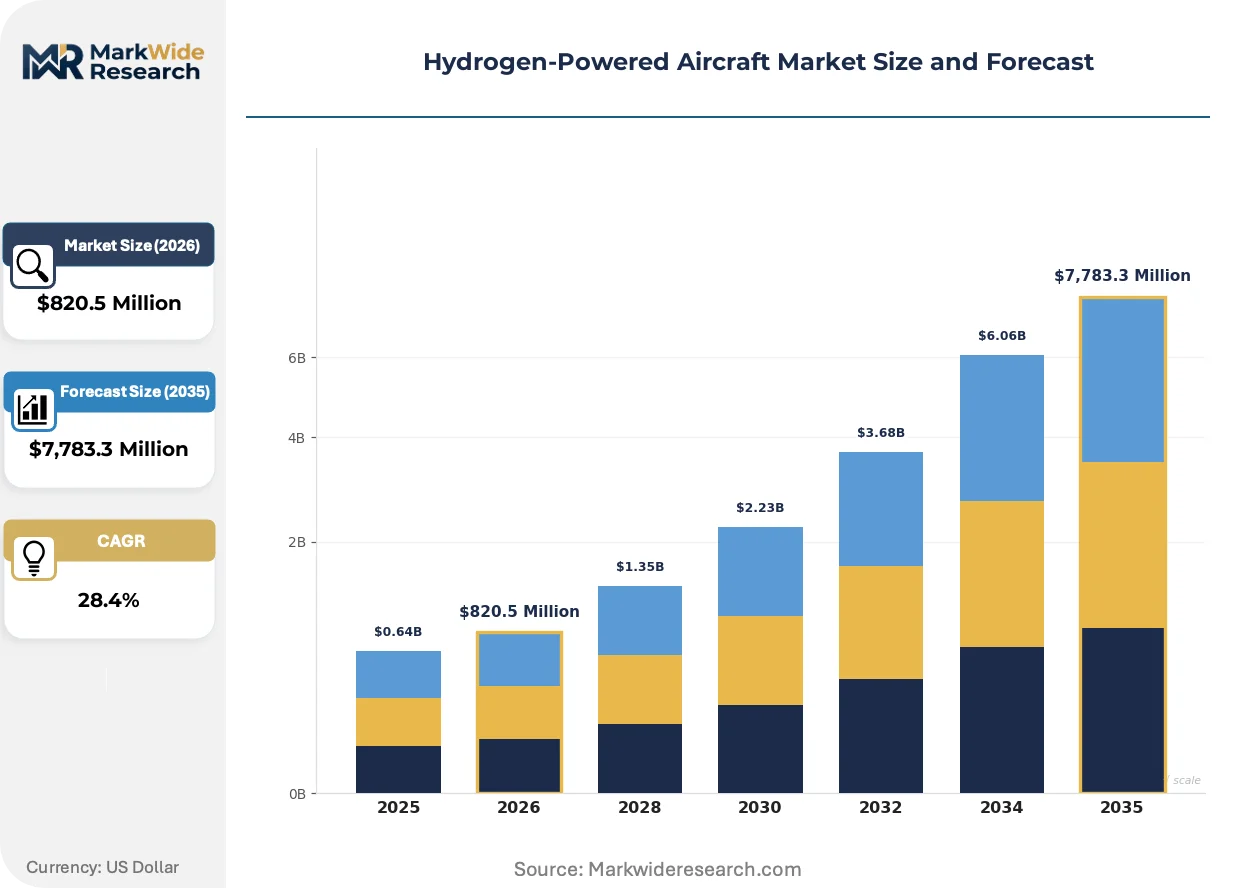
Market Dynamics
Cryogenic hydrogen storage architectures are concentrating R&D investment among aerospace clusters in Germany, France, and the Netherlands, forcing airframe manufacturers to reconfigure supply partnerships around liquefaction infrastructure timelines rather than traditional engine procurement cycles.
Growth Catalysts
- EU Green Deal aviation mandates:The ReFuelEU Aviation regulation requires progressive sustainable fuel blending, explicitly recognizing hydrogen as a zero-emission compliance pathway for regional carriers.
- Fuel-cell thermal efficiency gains:Proton-exchange membrane stacks now achieve 60% system efficiency, attracting capital from commuter aviation operators seeking to eliminate nitrogen oxide emissions at point of use.
- German aerospace cluster concentration:Hamburg and Munich host concentrated cryogenic engineering talent pools, accelerating prototype-to-test-flight cycles for liquid hydrogen tank integration.
Market Restraints
- Liquid hydrogen boil-off rates:Current cryogenic storage systems lose 1-3% fuel daily, imposing range penalties that constrain viable route networks for commercial operators.
- Electrolyzer supply concentration:Proton-exchange membrane electrolyzer manufacturing concentrates in Norwegian and Canadian facilities, creating input bottlenecks for aviation-grade hydrogen production.
- FAA-EASA dual-track certification:Divergent airworthiness standards for novel propulsion architectures force manufacturers to maintain parallel compliance documentation, extending type certification timelines.
Strategic Opportunities
- Norwegian short-haul network electrification:Widerøe's coastal route density matches hydrogen-electric range envelopes, positioning the country as an early deployment testbed.
- Airport hydrogen hub integration:Amsterdam Schiphol and Frankfurt Airport are retrofitting fueling infrastructure, creating captive demand for regional turboprop retrofits.
- Hybrid-electric architecture convergence:Combining fuel cells with turbine boost systems enables 500 nautical mile range thresholds, opening thin-haul routes currently served by aging regional jets.
Industry Challenges
- Cryogenic systems engineering talent scarcity:Qualified thermal management specialists command premium compensation, constraining workforce scaling for tank and fuel-line subsystem development.
- Type certification timeline uncertainty:EASA's SC-VTOL and FAA's Part 23 rewrite for hydrogen propulsion lack precedent cases, forcing manufacturers to fund extended validation campaigns without revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen-Powered Aircraft Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $7,783.3 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Fuel Cell, Turbine Engine, Internal Combustion, Hybrid, Electric Application: Commuter Aviation, Air Cargo, Regional Transport, Private Jets, Surveillance Drones Aircraft Category: Fixed-Wing, Rotary-Wing, Unmanned Aerial Vehicle, Experimental End User: Airlines, Government Agencies, Defense Contractors, Research Institutions, Charter Operators |
| Companies Covered | Airbus SE, ZeroAvia Inc, The Boeing Company, GKN Aerospace, Universal Hydrogen Co, Urban Aeronautics Ltd, AeroDelft, Pipistrel, H2FLY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen-Powered Aircraft Market Trends and Innovations
Aviation propulsion is pivoting from turbine-centric architectures toward integrated fuel-cell-electric systems, with airframe design, thermal management, and ground infrastructure evolving in lockstep rather than sequential development cycles.
Liquid hydrogen storage systems are displacing compressed gaseous alternatives in regional aircraft design envelopes. Commuter operators in Scandinavia and the North Sea corridor are specifying cryogenic tanks for 19-seat retrofits, prioritizing energy density over refueling simplicity. This displacement is compressing the addressable market for gaseous hydrogen conversions to unmanned cargo drones and training aircraft below 5,000 feet operational ceilings.
ReFuelEU Aviation mandates under the EU Green Deal are binding fuel suppliers to progressive sustainable aviation fuel quotas, with hydrogen explicitly classified as a zero-emission pathway. The regulation forces network carriers to contract for hydrogen supply agreements a decade ahead of fleet availability, shifting capital allocation from carbon offset purchases to infrastructure prepayments. Regional airlines in France and Germany are responding by forming procurement consortia to aggregate hydrogen offtake commitments.
Airframe OEMs are unbundling propulsion system integration from traditional engine-airframe bundled sales. Lessors and regional carriers now specify fuel-cell stack and tank suppliers separately, compressing supplier negotiation cycles and fragmenting maintenance contract structures. This procurement fragmentation is most visible in the Netherlands, where KLM Cityhopper and its lessor partners are piloting split-responsibility operating leases separating airframe, powertrain, and fuel infrastructure obligations.
Hydrogen-Powered Aircraft Market Segmentation
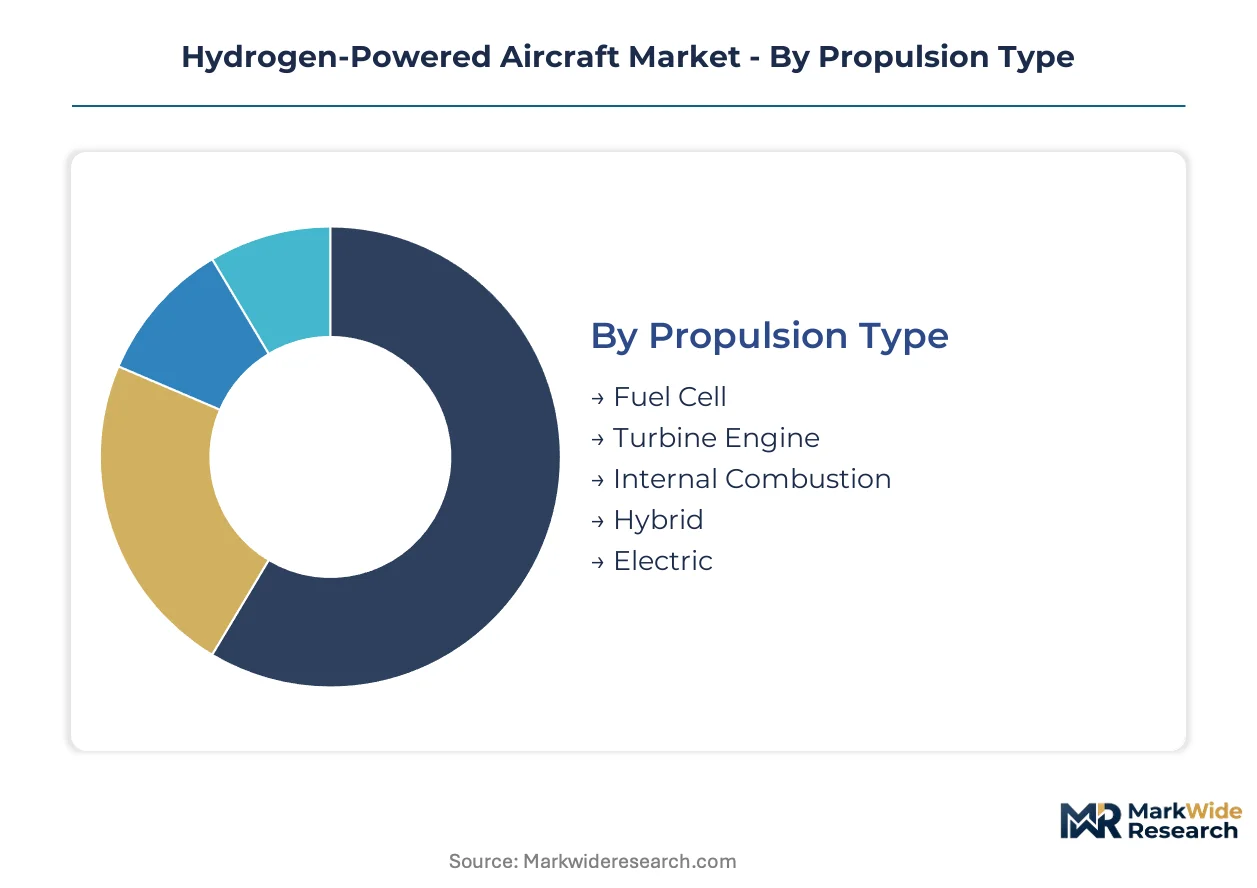
Hydrogen aviation segments diverge sharply in capital intensity and certification timelines. Propulsion architecture determines thermal management complexity, while application focus dictates infrastructure dependencies and route economics.
Propulsion Type:
Fuel cell systems command premium engineering margins due to proton-exchange membrane stack complexity and balance-of-plant integration.
- Fuel Cell:Electrochemical conversion of hydrogen to electricity drives electric motors with 60% system efficiency. Scandinavian commuter operators concentrate procurement around zero nitrogen oxide emissions compliance under EU Green Deal mandates.
- Hybrid:Fuel-cell-turbine combinations extend range envelopes to 500 nautical miles through boost power during climb phases. German aerospace clusters in Hamburg prioritize this architecture for regional jet retrofits facing cryogenic storage volume constraints.
- Turbine Engine:Direct hydrogen combustion in modified gas turbines preserves existing airframe integration patterns.
- Internal Combustion:Piston-engine conversions for general aviation training aircraft below 5,000 feet operational ceilings.
- Electric:Battery-dominant systems with hydrogen range extenders for unmanned cargo applications.
The dominant share belongs to Fuel Cell, while Hybrid is closing the gap fastest.
Application:
Route distance and passenger density determine hydrogen storage feasibility and infrastructure payback periods.
- Commuter Aviation:Short-haul networks under 300 nautical miles minimize cryogenic tank volume penalties. Norwegian coastal routes operated by Widerøe anchor early deployment timelines due to high frequency and predictable demand.
- Air Cargo:Unmanned and thin-haul freight prioritizes payload flexibility over passenger comfort systems. Dutch airport hubs at Amsterdam Schiphol concentrate investment for last-mile distribution integration.
- Regional Transport:19-to-50-seat turboprop replacements face extended certification cycles with EASA and FAA dual-track requirements.
- Private Jets:Owner-operated aircraft with customized range specifications and premium pricing tolerance.
- Surveillance Drones:Government and defense endurance requirements favor liquid hydrogen energy density for extended loiter missions.
Commuter Aviation holds the installed base lead, though Air Cargo is expanding most quickly through unmanned platform adoption.
Aircraft Category:
Airframe configuration dictates thermal management architecture and certification pathway complexity.
- Fixed-Wing:Conventional tube-and-wing designs integrate cryogenic tanks in aft fuselage sections behind passenger cabins. French aerospace engineering centers prioritize this category for regional jet replacement programs under ReFuelEU Aviation compliance timelines.
- Unmanned Aerial Vehicle:Remotely piloted systems bypass pilot oxygen and pressurization requirements, simplifying hydrogen system integration. German drone manufacturers target cargo and surveillance segments with compressed gaseous alternatives below 50 kg payload classes.
- Rotary-Wing:Helicopter configurations face rotor downwash thermal management challenges and limited tank placement options.
- Experimental:Technology demonstrators and record-attempt aircraft with bespoke certification exemptions.
Fixed-Wing dominates current development pipelines, while Unmanned Aerial Vehicle categories are gaining share fastest through reduced regulatory barriers.
End User:
Procurement authority and risk tolerance split between commercial operators with fleet standardization needs and government buyers with mission-specific requirements.
- Airlines:Network carriers and regional operators face binding sustainable aviation fuel quotas under EU Green Deal mandates. French and German carriers form procurement consortia to aggregate hydrogen offtake commitments and secure infrastructure access at Frankfurt and Paris hub airports.
- Defense Contractors:Military endurance and low-observable requirements prioritize energy density over commercial operating economics. Government-funded research programs in Germany and France provide non-recurring engineering coverage for prototype development.
- Government Agencies:Environmental monitoring and border patrol missions with public procurement transparency requirements.
- Research Institutions:Technology validation and flight test programs with grant-funded equipment acquisition.
- Charter Operators:On-demand services with flexible scheduling and premium pricing structures.
Airlines command the dominant procurement volume, while Defense Contractors are climbing the fastest through classified endurance platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with European carriers prioritizing regulatory compliance through fleet retrofits while North American operators emphasize greenfield platform development and Asian markets concentrate on unmanned cargo applications.
Germany
Hamburg and Munich aerospace clusters anchor liquid hydrogen tank integration programs for regional turboprop retrofits. The EU Green Deal's ReFuelEU Aviation mandate binds German carriers to sustainable fuel quotas, accelerating procurement consortium formation. Bavaria's engineering talent pools command premium compensation for cryogenic thermal management specialization.
France
Paris-based network carriers aggregate hydrogen offtake commitments to secure infrastructure access at Charles de Gaulle hub airports. EASA coordinates dual-track certification frameworks with FAA counterparts, extending type validation timelines for novel propulsion architectures. Toulouse aerospace engineering centers prioritize fixed-wing regional jet replacement programs under compliance deadlines.
United States
FAA Part 23 rewrites for hydrogen propulsion lack precedent cases, forcing manufacturers to fund extended validation campaigns. California and Pacific Northwest unmanned cargo operators specify compressed gaseous alternatives for below-50-kilogram payload classes. Defense contractors prioritize energy density for classified endurance platform development.
Norway
Widerøe's coastal route density matches hydrogen-electric range envelopes, positioning the country as an early deployment testbed. The country's short-haul network electrification concentrates procurement around zero nitrogen oxide emissions compliance. Stavanger and Bergen airport hubs retrofit fueling infrastructure for regional turboprop retrofits.
Netherlands
Amsterdam Schiphol's hydrogen hub integration creates captive demand for split-responsibility operating leases. KLM Cityhopper pilots procurement fragmentation separating airframe, powertrain, and fuel infrastructure obligations. Dutch airport engineering clusters concentrate investment for last-mile distribution integration with unmanned cargo platforms.
Hydrogen-Powered Aircraft Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence reorganizing competitive dynamics. Tier-one players leverage integrated airframe-engineering ecosystems to validate cryogenic architectures at scale. Specialist fabricators anchor positions through intensive ground-testing of fuel-cell propulsion stacks for regional applications. Dominant competitive moves include strategic partnerships around liquefaction infrastructure timelines and portfolio diversification into hybrid-electric architecture convergence.
Among Europe-based integrated aerospace conglomerates, Airbus SE exemplifies the full-stack validation archetype, while ZeroAvia Inc occupies a specialist position within the fuel-cell propulsion tier. The Boeing Company represents the North American platform development anchor, with GKN Aerospace sitting within the tiered supplier base for cryogenic subsystem integration.
| Leading Market Players |
|---|
| Airbus SE |
| ZeroAvia Inc |
| The Boeing Company |
| GKN Aerospace |
| Universal Hydrogen Co |
| Urban Aeronautics Ltd |
| AeroDelft |
| Pipistrel |
| H2FLY |
| Others |
Pricing and Supply Chain Analysis
Prototype-to-production scale economies in German and French aerospace clusters compress unit economics for cryogenic tank systems while elevating price floors for qualified thermal management engineering. This scale concentration fragments supplier pricing power between integrated airframe OEMs and specialized fuel-cell stack fabricators.
Pricing Analysis
After-sales service contracts and extended maintenance agreements capture lifetime value exceeding original equipment sales by factors of two to three in hydrogen propulsion retrofits. The dominant pricing structure runs through long-term offtake agreements bundling airframe lease, powertrain service, and hydrogen supply obligations. Price differentiation hinges on EASA certification tier and fleet scale commitments, with regional carriers facing acute price sensitivity compared to defense contractors funding non-recurring engineering. Pricing pressure stems from electrolyzer supply bottlenecks in Norwegian and Canadian facilities, forcing operators to absorb input cost volatility.
Supply Chain Analysis
Inventory lead times for proton-exchange membrane stacks extend eighteen to thirty-six months, constraining fleet deployment timelines regardless of airframe availability. Manufacturing concentrates in Germany, France, and the Netherlands for cryogenic subsystem integration, while electrolyzer production draws from Norwegian and Canadian facilities. Critical dependencies include liquid hydrogen liquefaction capacity, carbon-fiber tank winding equipment, and aviation-grade fuel-cell membranes. Single-source vulnerability pervades electrolyzer supply, with distribution running through airport hub retrofit programs at Amsterdam Schiphol and Frankfurt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades hydrogen aviation as procurement unbundling separates airframe, powertrain, and fuel infrastructure obligations, creating specialist niches for subsystem integrators and hydrogen hub operators.
For Market Incumbents: Shield installed base relationships through captive liquefaction infrastructure investments at hub airports, while accelerating EASA-FAA dual-track certification coverage to forestall venture-backed entrants. Vertical integration into cryogenic tank manufacturing in Hamburg and Munich clusters defends margin position against specialist fabricators. For New Entrants and Emerging Players: Anchor in unmanned cargo applications below fifty-kilogram payload classes, where compressed gaseous hydrogen bypasses cryogenic certification barriers and compressed development timelines. Norwegian coastal route networks offer the most penetrable geography, with Widerøe's electrification commitments creating anchor demand for fuel-cell retrofit specialists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subsystem specialists with demonstrated flight hours and EASA SC-VTOL certification progress over pre-revenue platform developers. Long-term viability hinges on liquefaction infrastructure buildout pacing across the analysis window. The signal to watch is airport hydrogen hub commissioning timelines at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle as fleet deployment inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Tank Manufacturing Scale-Up | Captive supply of liquid hydrogen storage systems secures position in German aerospace clusters. |
| Airport Hydrogen Hub Partnership | Amsterdam Schiphol retrofit creates captive demand for split-responsibility operating lease structures. |
| EASA-FAA Dual-Track Certification Investment | Parallel validation campaigns accelerate transatlantic market access for regional turboprop retrofits. |
| Electrolyzer Supply Agreement | Long-term offtake from Norwegian facilities hedges input cost volatility for aviation-grade hydrogen. |
| Fuel-Cell Stack Ground-Testing Expansion | Intensive validation protocols de-risk proton-exchange membrane integration for commuter operators. |
Research Methodology
The analysis maps fuel-cell propulsion, hybrid-electric architectures, cryogenic storage systems, and unmanned aerial platforms, each validated through airframe engineering directors, airline fleet procurement managers, airport infrastructure planners, and hydrogen supply specialists. Primary interviews combined with secondary validation from EASA certification databases, EU Green Deal regulatory filings, FAA Part 23 rewrite documentation, and airport capital expenditure disclosures. Bottom-up segment sizing triangulated against top-down aerospace industry production forecasts.
Consistency checks validated volume and value outputs against external benchmarks from aerospace manufacturing databases and sustainable aviation fuel procurement registries. The analytical framework modeled propulsion type, application focus, aircraft category, and end-user procurement authority across the projection horizon. CAGRs derived from segment-level unit economics and infrastructure readiness timelines, with forecast inputs including electrolyzer manufacturing capacity, airport hydrogen hub commissioning schedules, and EASA-FAA certification precedent case accumulation.
Decision-makers should treat outputs as directional under assumptions of EU Green Deal mandate continuity and liquefaction infrastructure buildout pacing; material deviation in regulatory enforcement or electrolyzer supply expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Propulsion System Market