
 Titanium Aerospace Forgings Market | 2026-2036
Titanium Aerospace Forgings Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Aerospace Forgings Market Insights
China is narrowing the titanium aerospace forging capability gap through state-backed capacity additions at multiple production complexes. VSMPO-AVISMA Corporation leverages its integrated titanium sponge-to-forging vertical chain to dominate supply for Western engine programs. ATI Inc. sustains competitive position through advanced melting and radial forging investments in North Carolina. Howmet Aerospace Inc. specializes in precision forged rotating components for turbine applications, occupying a defensible niche against generalist competitors.
Titanium aerospace forgings are metallurgical components produced from titanium alloys such as Ti-6Al-4V through hammer, press, or isothermal deformation processes, typically achieving tensile strengths exceeding 900 MPa while maintaining density roughly half that of steel. These components serve as load-bearing structural elements and critical rotating parts in airframes and propulsion systems where strength-to-weight ratio and fatigue resistance determine operational safety margins. Forged discs and forged rings command premium positioning within the product mix, as engine manufacturers specify these geometries for high-stress turbine and compressor sections where material integrity requirements exclude cast alternatives. Among end users, commercial aviation absorbs the dominant volume share, though space exploration represents the fastest-expanding demand category as reusable launch vehicle programs multiply flight cycles per airframe. Isothermal forging garners disproportionate engineering attention due to its capacity for near-net-shape production of complex titanium alloys, reducing subsequent machining waste and lead times.
FAA airworthiness directives and EASA certification specifications govern titanium forging qualification for flight-critical applications, mandating lot-level chemical analysis, mechanical testing, and non-destructive inspection protocols that extend supplier onboarding timelines. China's GB standards and NMPA oversight for civil aviation imports impose parallel conformity requirements, fragmenting certification burdens across regulatory jurisdictions. Stakeholders must monitor evolving sustainability disclosure obligations under EU CSRD and emerging scope-three emissions tracking demands from tier-one aerospace OEMs, as titanium production energy intensity attracts procurement scrutiny.
Market Dynamics
Isothermal forging technology is compressing lead times for complex titanium geometries while FAA and EASA lot-level traceability mandates extend supplier qualification cycles, creating asymmetric pressure on forging capacity expansion.
Growth Catalysts
- Narrowbody production ramp:Boeing's 737 MAX and Airbus A320neo output schedules are pulling titanium disc and ring forgings into long-term procurement agreements with penalty clauses for delivery failure.
- Reusable launch vehicle flight cycles:SpaceX Starship and Blue Origin New Glenn programs are multiplying titanium structural demand per airframe compared to expendable architectures.
- EU Green Deal scope-three tracking:Aerospace OEM procurement teams are embedding titanium forging energy intensity metrics into supplier scorecards, favorizing low-carbon sponge sources.
Market Restraints
- Titanium sponge supply concentration:VSMPO-AVISMA's vertical control over Russian sponge output exposes Western forging supply chains to sanctions-driven input volatility.
- Isothermal press capex barriers:Single isothermal forging cell investments exceed $50 million, restricting capacity additions to balance-sheet-heavy incumbents.
- Aluminum-lithium substitution in airframes:Airbus A350 wing structures have displaced titanium forgings with Al-Li alloys in non-rotating applications, compressing addressable volume.
Strategic Opportunities
- India defense aerospace localization:Hindustan Aeronautics Limited's Tejas Mk2 and AMCA programs are mandating indigenous titanium forging qualification under import substitution directives.
- Digital twin process control:Real-time thermal mapping and predictive deformation modeling are converging to reduce isothermal forging scrap rates and accelerate first-article approval.
- EU CSRD supplier disclosure mandates:Tier-one OEMs are cascading emissions accounting requirements downstream, creating competitive wedge for forgers with verified low-carbon titanium sourcing.
Industry Challenges
- Non-destructive inspection technician scarcity:Ultrasonic and radiographic certification for titanium rotating components requires 18-24 month training pipelines that outpace workforce expansion.
- Multi-jurisdiction qualification stacking:Suppliers seeking Boeing, Airbus, and COMAC concurrent approval face divergent NDT acceptance criteria that fragment testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Aerospace Forgings Market |
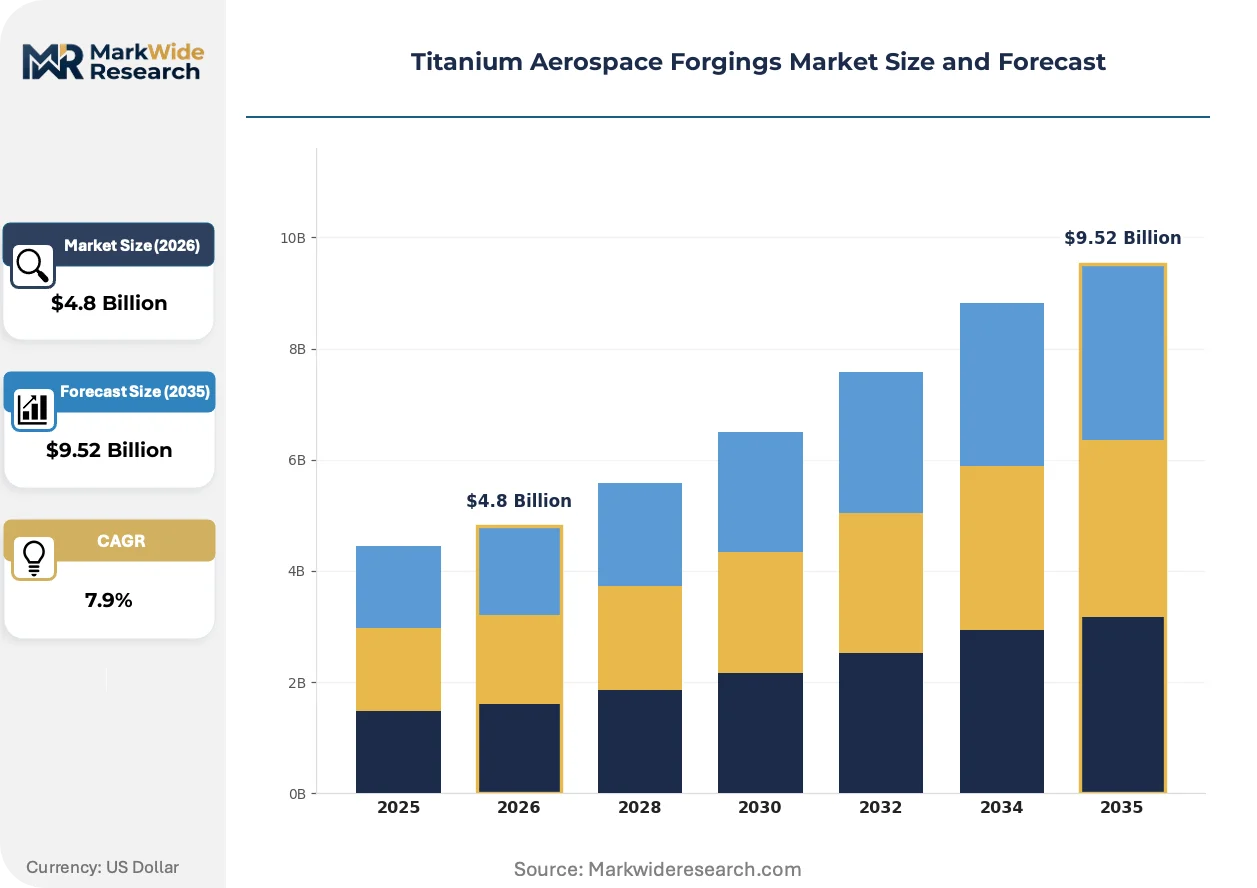
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Rings, Forged Discs, Forged Blocks, Forged Shafts End User: Commercial Aviation, Military Aviation, Space Exploration, Helicopters Application: Airframe Components, Engine Components, Landing Gear, Structural Parts Manufacturing Process: Hot Forging, Cold Forging, Isothermal Forging, Precision Forging |
| Companies Covered | Precision Castparts Corp., VSMPO-AVISMA Corporation, ATI Inc., Howmet Aerospace Inc., Arconic Corporation, Weldaloy Specialty Forgings Company, Scot Forge Company, Bharat Forge, Aubert & Duval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Aerospace Forgings Market Trends and Innovations
Digital process twinning and closed-loop thermal control are virtualizing traditional forging development cycles, while regulatory emissions disclosure and procurement model evolution reshape competitive positioning.
Isothermal forging with real-time die temperature monitoring is virtualizing the iterative die trial process that historically consumed 12-18 months for complex titanium geometries. Engine manufacturers including Pratt & Whitney and Rolls-Royce are specifying near-net-shape isothermal forgings for high-pressure compressor discs, compressing machining waste by 60-70 percent. This technology is virtualizing the traditional make-test-iterate development model into simulation-validated first-article production.
EASA's evolving certification specifications for critical rotating components now mandate digital thread documentation from melt to final inspection, with lot-level chemical and mechanical data archived for airframe operational life. The regulation forces forging suppliers to deploy manufacturing execution systems with blockchain-anchored traceability or risk disqualification from engine OEM approved vendor lists. European suppliers are responding fastest, with German and French forgers leading implementation of CSRD-aligned emissions reporting integrated into quality management systems.
Long-term throughput agreements are displacing spot procurement for titanium forgings as OEMs seek to lock capacity amid narrowbody production surges. Tier-one aerostructures suppliers are consolidating forging sourcing into single-source partnerships with penalty-backed volume guarantees, compressing the approved supplier base. This pattern is most visible in the United States Pacific Northwest, where Boeing's supplier development programs are concentrating titanium forging procurement among three qualified domestic sources.
Titanium Aerospace Forgings Market Segmentation
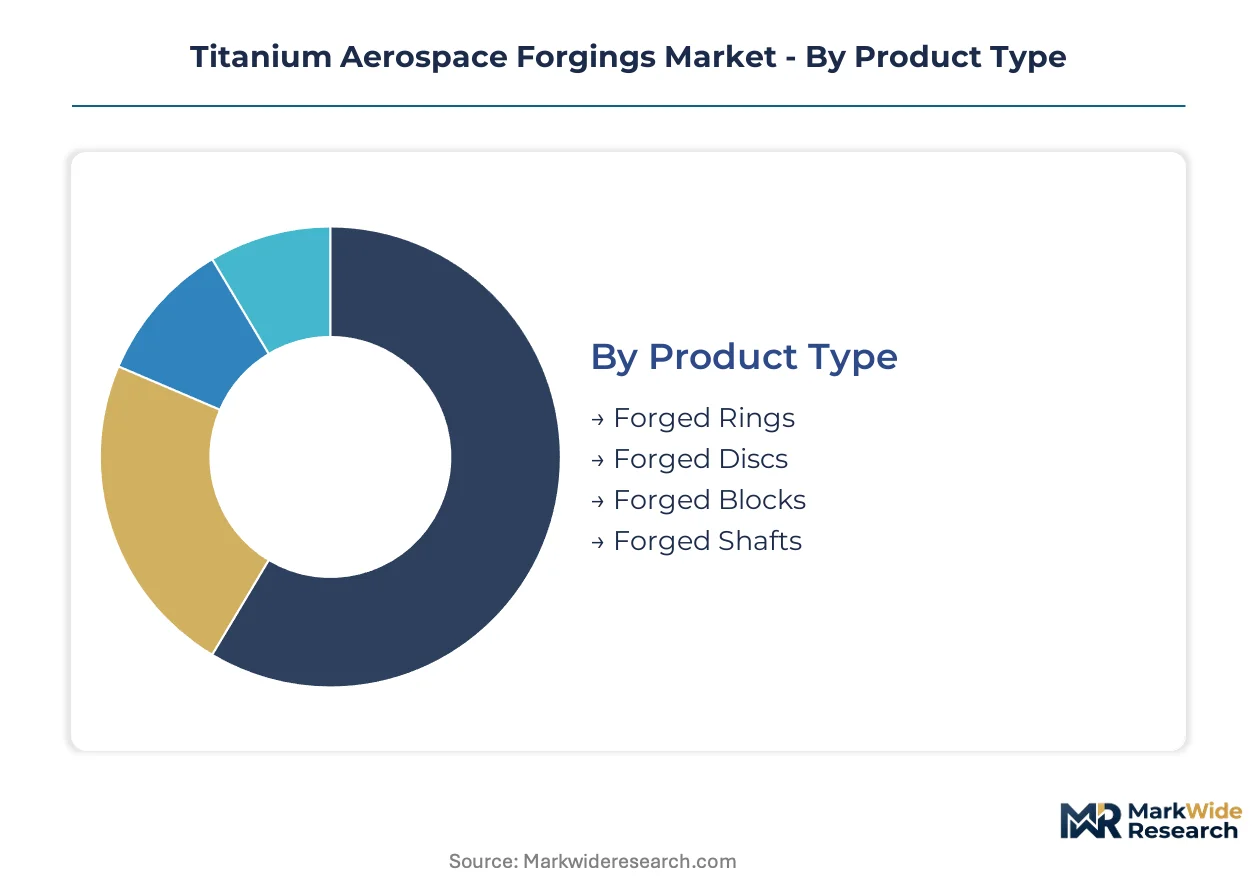
Titanium aerospace forgings segment across product geometries, end-use sectors, and manufacturing methodologies that each impose distinct metallurgical specifications and qualification protocols. Understanding these divisions reveals where forging capacity concentrates and which process innovations command premium positioning.
Product Type:
Geometry dictates the stress distribution characteristics and machining requirements that differentiate forging categories.
- Forged Rings:Annular components produced through radial forging or ring rolling achieve circumferential grain flow optimized for hoop stress resistance. Rolls-Royce and Pratt & Whitney specify these geometries for turbine casings and compressor seals where fatigue life determines maintenance intervals.
- Forged Discs:High-pressure compressor and turbine discs require unidirectional grain structure and zero internal defects detectable through ultrasonic inspection. Boeing and Airbus engine programs anchor demand in the United States Pacific Northwest and southwestern Germany.
- Forged Blocks:Rectangular billets serve as feedstock for subsequent machining of complex structural brackets and pylon attachments.
- Forged Shafts:Longitudinal components transmit torque in auxiliary power units and transmission systems.
Forged discs command the established base. The steepest expansion runs through forged rings as geared turbofan architectures multiply seal ring counts per engine.
End User:
Customer categories diverge in procurement volume, qualification timelines, and sensitivity to supply chain disruption.
- Commercial Aviation:Narrowbody production rates at Boeing and Airbus pull the dominant volume share of titanium forgings into multi-year procurement agreements with penalty clauses. FAA and EASA dual certification requirements extend supplier onboarding to 24-36 months for rotating components.
- Space Exploration:Reusable launch vehicle programs at SpaceX and Blue Origin multiply flight cycles per airframe, accelerating structural fatigue and replacement demand compared to expendable architectures.
- Military Aviation:Lockheed Martin F-35 and Dassault Rafale programs specify titanium forgings for airframe durability under combat load factors.
- Helicopters:Sikorsky and Leonardo rotor systems utilize titanium forgings for hub assemblies and transmission housings.
Commercial aviation absorbs the volume base. Space exploration climbs the fastest as Starship and New Glenn flight rates scale.
Application:
Functional placement determines the strength-to-weight ratios and damage tolerance specifications governing alloy selection.
- Engine Components:High-pressure compressor discs, turbine blades, and seal rings operate above 500°C where Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr alloys resist creep and thermal fatigue. GE Aerospace and Safran specify these forgings with lot-level chemical traceability from sponge source.
- Airframe Components:Wing carry-through structures and fuselage frames leverage titanium's galvanic compatibility with carbon fiber composites. Boeing 787 and Airbus A350 programs concentrate demand in Japan and Italy through tier-one aerostructures suppliers.
- Landing Gear:Trunnions and torque links absorb impact loads where toughness supersedes elevated temperature performance.
- Structural Parts:Secondary brackets and fasteners complete the application matrix with lower qualification barriers.
Engine components anchor procurement value. Airframe applications gain share fastest as composite primary structures expand titanium interface requirements.
Manufacturing Process:
Process technology stratifies suppliers by capital intensity, scrap rates, and dimensional precision capabilities.
- Isothermal Forging:Die and workpiece maintained at identical elevated temperatures enable near-net-shape production of complex geometries with 60-70 percent machining waste reduction. Howmet Aerospace and ATI have deployed isothermal cells exceeding $50 million per installation, creating balance-sheet barriers to competitive entry.
- Hot Forging:Conventional hammer and press deformation above beta transus temperature remains the volume foundation for less complex geometries.
- Precision Forging:Closed-die configurations with tight tolerance control serve rotating component specifications.
- Cold Forging:Limited titanium application due to alloy work hardening characteristics; restricted to fastener and small component production.
Hot forging maintains the capacity base. Isothermal forging shows the steepest capability expansion as engine OEMs specify near-net-shape compressor discs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor qualification protocols in the United States, while EASA specifications govern European supply chains and China's NMPA imposes parallel conformity requirements for civil aviation imports.
United States
Boeing's 737 MAX production ramp and Pratt & Whitney's geared turbofan programs pull titanium disc and ring forgings into multi-year procurement agreements. FAA lot-level traceability mandates from sponge source to final inspection extend supplier onboarding timelines to 24-36 months for rotating components. The Pacific Northwest cluster around Seattle anchors domestic forging consumption, with ATI and Howmet Aerospace operating qualified production cells for airframe and engine applications.
China
State-backed capacity additions at multiple production complexes are narrowing the titanium aerospace forging capability gap for COMAC's C919 narrowbody program. GB standards and NMPA oversight impose chemical analysis and mechanical testing protocols that fragment certification burdens for Western suppliers. The Yangtze River Delta and Shaanxi province host expanding forging complexes serving both civil aviation import substitution and military aerospace programs.
Russia
VSMPO-AVISMA Corporation's integrated titanium sponge-to-forging vertical chain dominates supply for Western engine programs despite sanctions-driven input volatility. The country's national aerospace regulator maintains certification specifications that diverge from FAA and EASA acceptance criteria, complicating multi-jurisdiction qualification. The Sverdlovsk Oblast concentration around Verkhnyaya Salda anchors global sponge production and primary forging capacity.
France
Safran and Airbus anchor demand for precision-forged rotating components across the A320neo and A350 programs. EASA certification specifications for critical rotating components now mandate digital thread documentation from melt to final inspection, forcing blockchain-anchored traceability adoption. The Auvergne-Rhône-Alpes cluster around Grenoble and Saint-Étienne hosts Aubert & Duval and specialized forging operations serving European engine OEMs.
India
Hindustan Aeronautics Limited's Tejas Mk2 and AMCA programs mandate indigenous titanium forging qualification under import substitution directives. The Directorate General of Civil Aviation imposes conformity requirements that parallel FAA and EASA protocols for imported components. Karnataka and Maharashtra host emerging forging capacity serving defense aerospace localization, with Bharat Forge expanding qualified production for domestic and export programs.
Titanium Aerospace Forgings Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base stratifies between balance-sheet-heavy incumbents operating isothermal forging cells exceeding fifty million dollars per installation and regional specialists serving non-rotating structural applications. Three archetypes dominate: integrated titanium sponge-to-forging operators, precision-forged rotating component specialists, and diversified metals fabricators with aerospace divisions. Capacity expansion and strategic partnerships represent the dominant competitive moves, as OEMs consolidate approved supplier bases into single-source partnerships with penalty-backed volume guarantees.
Within the integrated supply chain tier, VSMPO-AVISMA Corporation exemplifies backward integration from sponge production through finished forgings. ATI Inc. and Howmet Aerospace Inc. occupy positions among North American operators with qualified isothermal forging capacity for engine rotating components. Precision Castparts Corp. represents the diversified precision components archetype, while Bharat Forge anchors the emerging India-based qualification pathway.
| Leading Market Players |
|---|
| Precision Castparts Corp. |
| VSMPO-AVISMA Corporation |
| ATI Inc. |
| Howmet Aerospace Inc. |
| Arconic Corporation |
| Weldaloy Specialty Forgings Company |
| Scot Forge Company |
| Bharat Forge |
| Aubert & Duval |
| Others |
Pricing and Supply Chain Analysis
Sanctions-driven titanium sponge supply volatility compresses pricing power across Western forging tiers while simultaneously reshaping procurement geography toward dual-source qualification mandates. This structural input risk widens spreads between premium isothermal-forged rotating components and standard hot-forged structural grades, as OEMs absorb security-of-supply premiums into long-term contracting frameworks.
Pricing Analysis
North American titanium forging deliveries command 15-25 percent premiums over comparable Asian-origin components due to FAA traceability certification and logistics reliability. Contract-based long-term offtake agreements dominate procurement, with pricing stratifying across premium isothermal-forged discs, standard hot-forged rings, and economy-grade structural blocks. Cost compression in standard grades intensifies as Chinese capacity additions enter COMAC qualification pipelines. Defense aerospace programs exhibit lowest price sensitivity due to national security sourcing mandates, while commercial aviation procurement teams leverage volume scale for tiered pricing concessions.
Supply Chain Analysis
VSMPO-AVISMA's captive titanium sponge production in Russia, ATI's integrated melting capacity in North Carolina, and China's state-backed sponge-to-forging complexes anchor global primary supply. Western forging supply chains draw from Russian sponge, Australian rutile concentrates, and Japanese premium-grade inputs. Single-source vulnerability concentrates in isothermal forging cell capacity, where three qualified North American operators serve Boeing and Pratt & Whitney programs. Distribution runs through tier-one aerostructures suppliers consolidating approved vendor lists into single-source partnerships with penalty-backed volume guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium aerospace forging demand tracks commercial aviation production cycles, with narrowbody output schedules at Boeing and Airbus signaling recovery momentum through multi-year procurement commitments.
For Market Incumbents: Insulate qualification moats by accelerating FAA-EASA digital thread certification investments before blockchain-anchored traceability mandates harden. Deepen backward integration into low-carbon titanium sponge sources as EU CSRD scope-three disclosure requirements cascade downstream. Prioritize isothermal forging capacity expansion in the United States Pacific Northwest to capture Boeing supplier consolidation programs. For New Entrants and Emerging Players: Pursue defense aerospace localization opportunities in India where HAL's Tejas Mk2 and AMCA programs mandate indigenous forging qualification under import substitution directives. Target non-rotating structural applications with lower NDT certification barriers as the most penetrable entry segment. Differentiate through verified low-carbon titanium sourcing credentials aligned with tier-one OEM procurement scorecards. For Investors and Strategic Acquirers: Precision-forged rotating component specialists with qualified isothermal capacity represent the highest-conviction acquisition archetype given OEM supplier base consolidation trends. Long-term viability hinges on 5-10 year narrowbody production rate sustainability and space exploration flight cycle expansion. Monitor quarterly Boeing 737 MAX and Airbus A320neo delivery schedules as the primary inflection indicator for forging demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Isothermal Forging Capacity Expansion | Howmet Aerospace and ATI deploy cells exceeding $50 million to capture Pratt & Whitney geared turbofan specifications. |
| Backward Integration into Sponge Supply | ATI sustains competitive positioning through captive titanium melting investments reducing Russian sponge dependency. |
| Digital Thread Traceability Implementation | EASA mandates force blockchain-anchored lot-level documentation from melt to final inspection for rotating components. |
| Defense Aerospace Localization Partnership | Bharat Forge expands qualified production for HAL programs under India's import substitution directives. |
| Low-Carbon Titanium Sourcing Certification | EU CSRD-aligned emissions reporting creates procurement wedge for forgers with verified sustainable sponge supply. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with titanium forging procurement directors, quality assurance leads at engine OEMs, and aerospace supply chain strategists; and secondary validation through FAA airworthiness directives, EASA certification specifications, customs trade data, and SEC filings from qualified suppliers. Bottom-up segment sizing across product geometries and end-use sectors triangulated against top-down aerospace production forecasts.
Forecast inputs span narrowbody delivery schedules, reusable launch vehicle flight rate projections, and defense aerospace program milestones across the analysis window. Segmentation modeling incorporates product type, manufacturing process technology tier, end-user category, and regional regulatory cluster. CAGRs derive from production rate elasticity analysis and titanium content per airframe benchmarks, with isothermal forging adoption curves and CSRD compliance timelines as industry-specific modifiers.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price trajectories, interest rate environments affecting aircraft financing, or escalation in titanium sponge supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding Boeing-Airbus production rate recovery and space exploration program scaling. Quarterly review of narrowbody delivery data, isothermal forging capacity utilization indicators, and sanctions regime developments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market