
 Middle East Commercial Aircraft Cabin Lighting Market | 2026-2036
Middle East Commercial Aircraft Cabin Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Commercial Aircraft Cabin Lighting Market Foresight
A shortage of avionics-certified lighting engineers across the Gulf is redrawing supplier engagement models in the Middle East commercial aircraft cabin lighting market. Collins Aerospace leverages its integrated systems portfolio to sustain long-term MRO contracts with flag carriers based in Dubai and Abu Dhabi. Diehl Aerospace GmbH anchors its regional presence through specialized LED retrofit kits designed for narrow-body Airbus platforms operating Saudi domestic routes.
Middle East commercial aircraft cabin lighting encompasses engineered illumination systems installed within passenger compartments, incorporating color-temperature-tunable LED arrays, photometrically certified emergency floor-path marking, and MIL-STD-810H vibration-resistant housing for pressurized cabin environments. These systems serve the dual purpose of passenger circadian rhythm management during ultralong-haul flights and regulatory-compliant evacuation pathway visibility. LED product types command the dominant share of new installations given their weight reduction and programmable spectral output, while smart lighting technology represents the fastest-expanding segment as carriers deploy app-controlled mood scenes tied to flight-phase automation. Fluorescent systems occupy a shrinking but persistent niche in legacy fleet maintenance schedules across second-tier operators.
GCAA mandates on emergency lighting minimum luminance, EASA CS-25 airworthiness codes adopted by most Middle East regulators, and ICAO Annex 6 operational standards collectively shape product certification requirements and aftermarket retrofit cycles for cabin lighting suppliers. The UAE's General Civil Aviation Authority has tightened inspection intervals for aging incandescent emergency systems, accelerating fleet-wide LED transitions. Stakeholders must monitor how Saudi Arabia's GACA alignment with EU MDR-equivalent medical-device lighting standards for premium cabin wellness features will reshape R&D investment priorities among regional distributors and OEM partners.
Market Dynamics
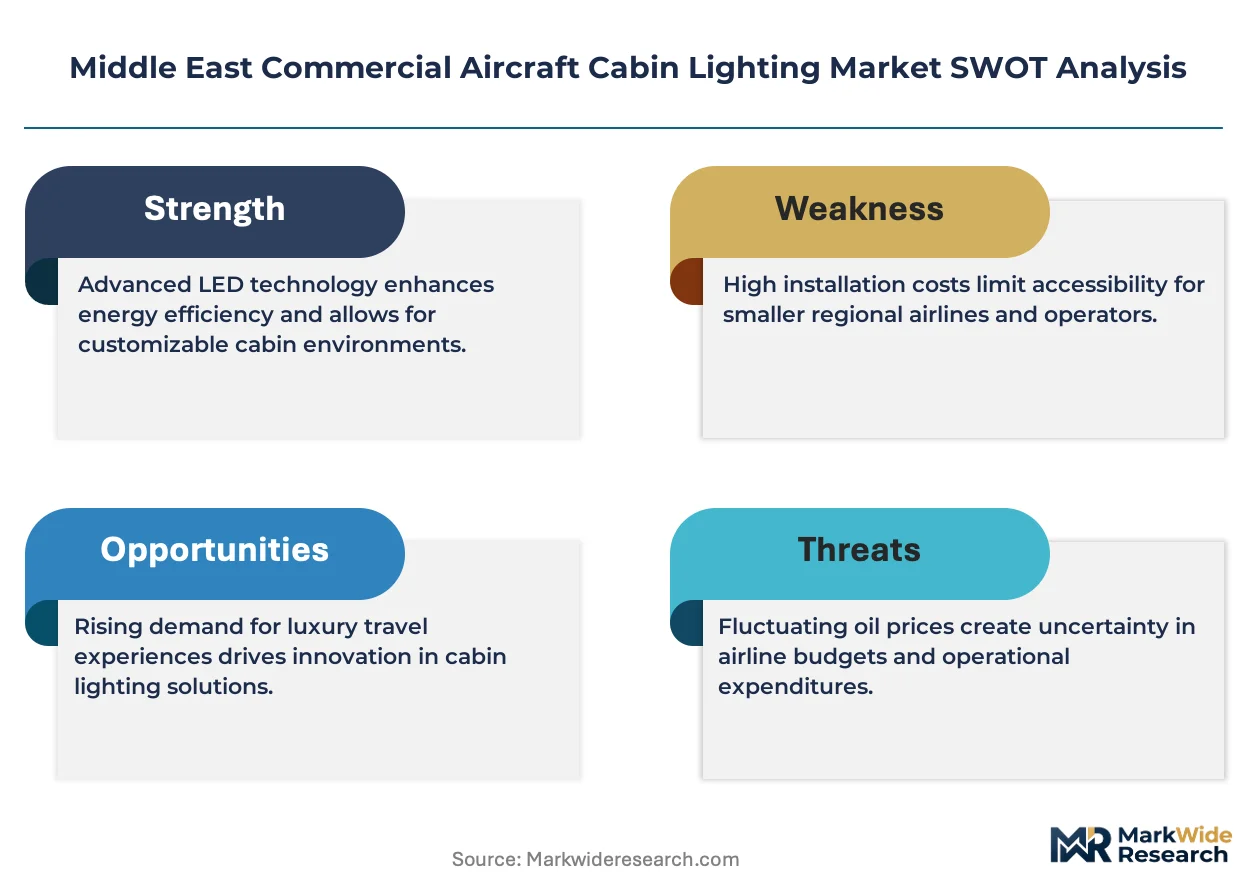
GCAA and EASA airworthiness directives on emergency egress illumination are compressing retrofit timelines, forcing Gulf carriers to accelerate fleet-wide LED transitions ahead of scheduled maintenance cycles.
Growth Catalysts
- LED weight reduction mandates:GCAA inspection intervals for aging incandescent emergency systems now require demonstrable photometric performance gains, pushing operators toward solid-state retrofits.
- Ultralong-haul circadian management:Emirates Airline and Etihad Airways deploy programmable spectral output across A380 and 787 fleets to differentiate passenger experience on Dubai-Sydney and Abu Dhabi-Los Angeles routes.
- EASA CS-25 adoption:Saudi Arabia's GACA alignment with EU airworthiness codes creates harmonized certification pathways for regional suppliers serving Riyadh-based maintenance facilities.
Market Restraints
- Avionics-certified engineer scarcity:The Gulf's shortage of qualified lighting systems specialists concentrates MRO dependency on Collins Aerospace and Diehl Aerospace service networks.
- Legacy fluorescent inventory:Second-tier Saudi domestic operators maintain shrinking but persistent fluorescent maintenance schedules, fragmenting supplier production runs.
- MIL-STD-810H vibration housing costs:Pressurized cabin certification requirements for LED arrays inflate unit economics relative to non-aviation commercial lighting.
Strategic Opportunities
- App-controlled mood automation:Smart lighting technology converging with flight-phase automation software creates white space for system integrators targeting premium cabin wellness features.
- Saudi Vision 2030 fleet expansion:Riyadh Air's orderbook growth and Saudia's narrow-body renewal programs generate demand for specialized LED retrofit kits on A320neo family aircraft.
- GACA medical-device alignment:Saudi Arabia's adoption of EU MDR-equivalent standards for premium cabin wellness lighting redirects R&D investment toward circadian-rhythm-certified products.
Industry Challenges
- Photometric certification timelines:EASA CS-25 and GCAA parallel approval processes for emergency floor-path marking systems extend product launch cycles by 8-14 months.
- Legacy system integration friction:Retrofit installations on aging wide-body fleets require custom harness adapters, complicating inventory management for Dubai-based MRO providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Commercial Aircraft Cabin Lighting Market |
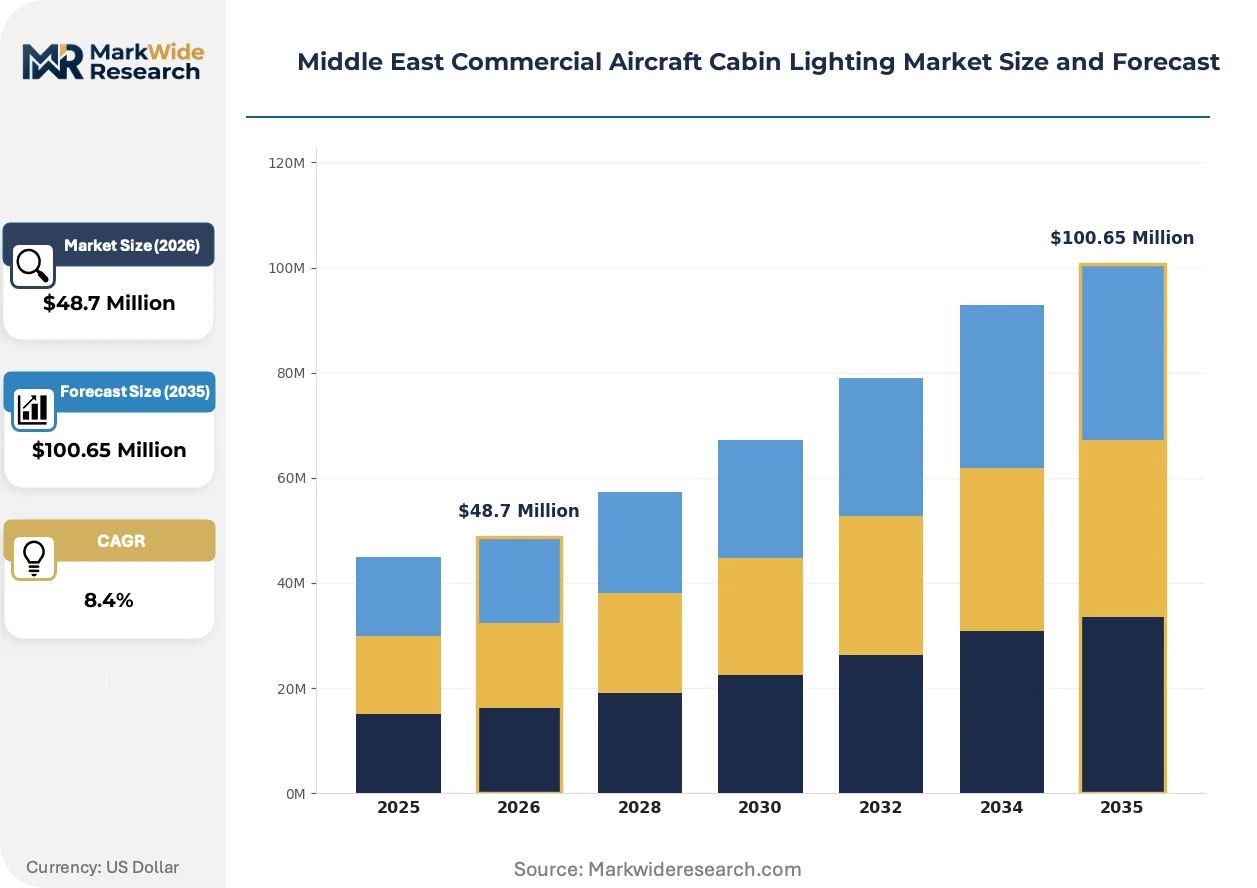
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent Application: Cabin Lighting, Cockpit Lighting, Emergency Lighting, Galley Lighting End User: Airlines, Charter Services, OEMs, Maintenance Providers Technology: Smart Lighting, Dimming Systems, Color Change Technology, Integrated Control Systems |
| Companies Covered | Astronics Corporation, Collins Aerospace, Diehl Aerospace GmbH, Luminator Technology Group, STG Aerospace, Honeywell International, Safran SA, Raytheon Technologies Corporation, Thales Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Commercial Aircraft Cabin Lighting Market Shifts & Advancements
Programmable LED spectral output is displacing fixed-color cabin illumination across Gulf carrier fleets, compressing supplier margins on legacy product lines while opening premium tiers for automation-integrated systems.
Tunable white LED arrays with Kelvin-temperature control are displacing binary on-off cabin lighting in Emirates and Etihad premium cabins. These systems synchronize with flight-phase data to suppress melatonin-disrupting blue wavelengths during overnight sectors. The technology is displacing incandescent-derived color temperature limitations that previously constrained circadian-focused cabin design.
EASA CS-25 amendments on emergency lighting minimum luminance are tightening photometric certification requirements for suppliers serving UAE and Saudi operators. GCAA has adopted these standards verbatim, eliminating grandfathering provisions for aging incandescent egress systems. Narrow-body retrofit programs in Saudi domestic routes face compressed compliance deadlines as GACA inspection intervals tighten.
Carrier procurement teams are unbundling lighting system purchases from full-cabin interior packages, shifting toward standalone subsystem contracts with specialized LED vendors. Dubai-based MRO facilities now source mood-scene controllers separately from seat and monument integrators. This pattern concentrates in UAE flag carrier fleets where specialized A380 and 787 configurations demand custom photometric solutions.
Middle East Commercial Aircraft Cabin Lighting Market Segmentation
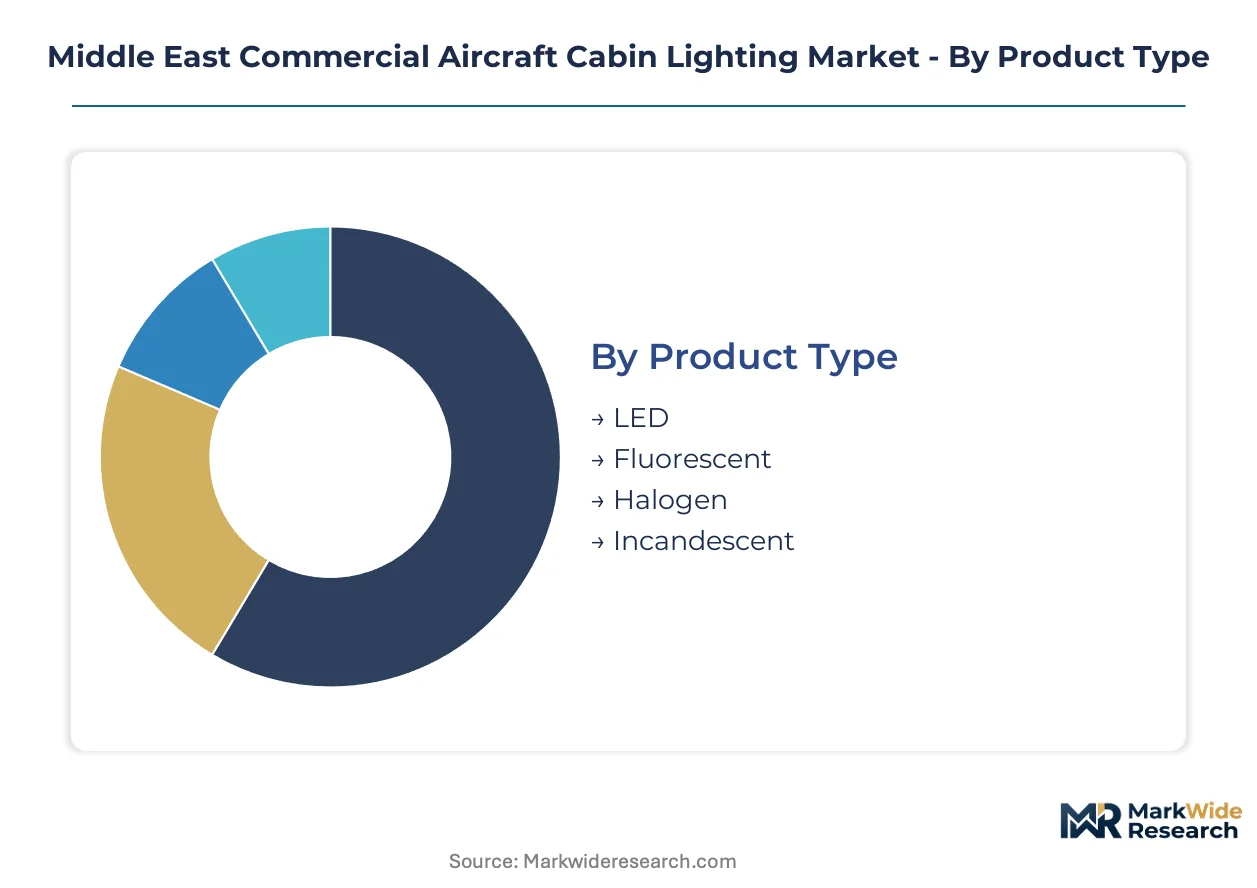
Segmentation in the Middle East commercial aircraft cabin lighting market reveals how procurement decisions bifurcate between retrofit urgency and new-build specifications. Understanding where carriers prioritize weight reduction against circadian wellness features shapes supplier positioning across Dubai and Riyadh maintenance corridors.
Product Type:
Margin pools concentrate in solid-state technologies where GCAA-mandated photometric upgrades command premium pricing over legacy replacements.
- LED:Color-temperature-tunable arrays with programmable spectral output dominate Emirates and Etihad fleet retrofits. Emirates Airline's A380 configurations require specialized Kelvin-control systems for ultralong-haul circadian management on Dubai-Sydney routes.
- Fluorescent:Linear tube systems persist in second-tier Saudi domestic operator maintenance schedules where compressed retrofit timelines have not yet reached smaller fleets. GACA inspection interval extensions for aging narrow-body fleets sustain residual demand.
- Halogen:Tungsten-halogen spot fixtures retain niche applications in legacy VIP cabin configurations where warm color rendering remains specified.
- Incandescent:Filament-based emergency systems face accelerated phase-out as GCAA eliminates grandfathering provisions for egress illumination compliance.
The dominant share belongs to LED, while smart-integrated LED variants are climbing the fastest as carriers unbundle lighting from full-cabin packages.
Application:
Retrofit intensity varies sharply by cabin zone, with passenger-facing systems attracting investment priority over crew-operational spaces.
- Cabin Lighting:Mood-scene LED arrays with flight-phase automation command premium positioning in Emirates and Etihad premium cabins. Programmable spectral output suppresses melatonin-disrupting wavelengths during overnight sectors on Abu Dhabi-Los Angeles routes.
- Emergency Lighting:Photometrically certified floor-path marking systems face compressed EASA CS-25 compliance timelines across UAE and Saudi fleets. GCAA-adopted minimum luminance standards eliminate grandfathering for aging incandescent egress installations.
- Cockpit Lighting:NVIS-compatible LED panels serve flight deck retrofit requirements with MIL-STD-810H vibration resistance specifications.
- Galley Lighting:Task-optimized LED strips address crew workspace illumination with lower customization complexity than passenger cabin zones.
Passenger cabin applications capture the dominant share, though emergency systems are expanding most quickly as regulatory deadlines compress.
End User:
Procurement authority fragmentation between fleet operators and third-party MRO providers shapes contract structuring across the Gulf.
- Airlines:Emirates Airline and Etihad Airways drive specifications for specialized A380 and 787 configurations with custom photometric requirements. Direct airline procurement of standalone lighting subsystems is displacing bundled interior packages.
- Maintenance Providers:Dubai-based MRO facilities now source mood-scene controllers separately from seat integrators, concentrating demand for Collins Aerospace and Diehl Aerospace service networks.
- OEMs:Airbus and Boeing line-fit programs for Riyadh Air's orderbook generate demand for factory-installed LED systems on A320neo family aircraft.
- Charter Services:VIP configuration specialists in Abu Dhabi sustain demand for bespoke warm-color rendering systems in executive cabin retrofits.
Flag carriers hold the dominant share, while maintenance providers are gaining procurement authority fastest as fleet-wide retrofit programs accelerate.
Technology:
Integration depth with flight management systems separates premium-tier suppliers from component vendors in technology procurement.
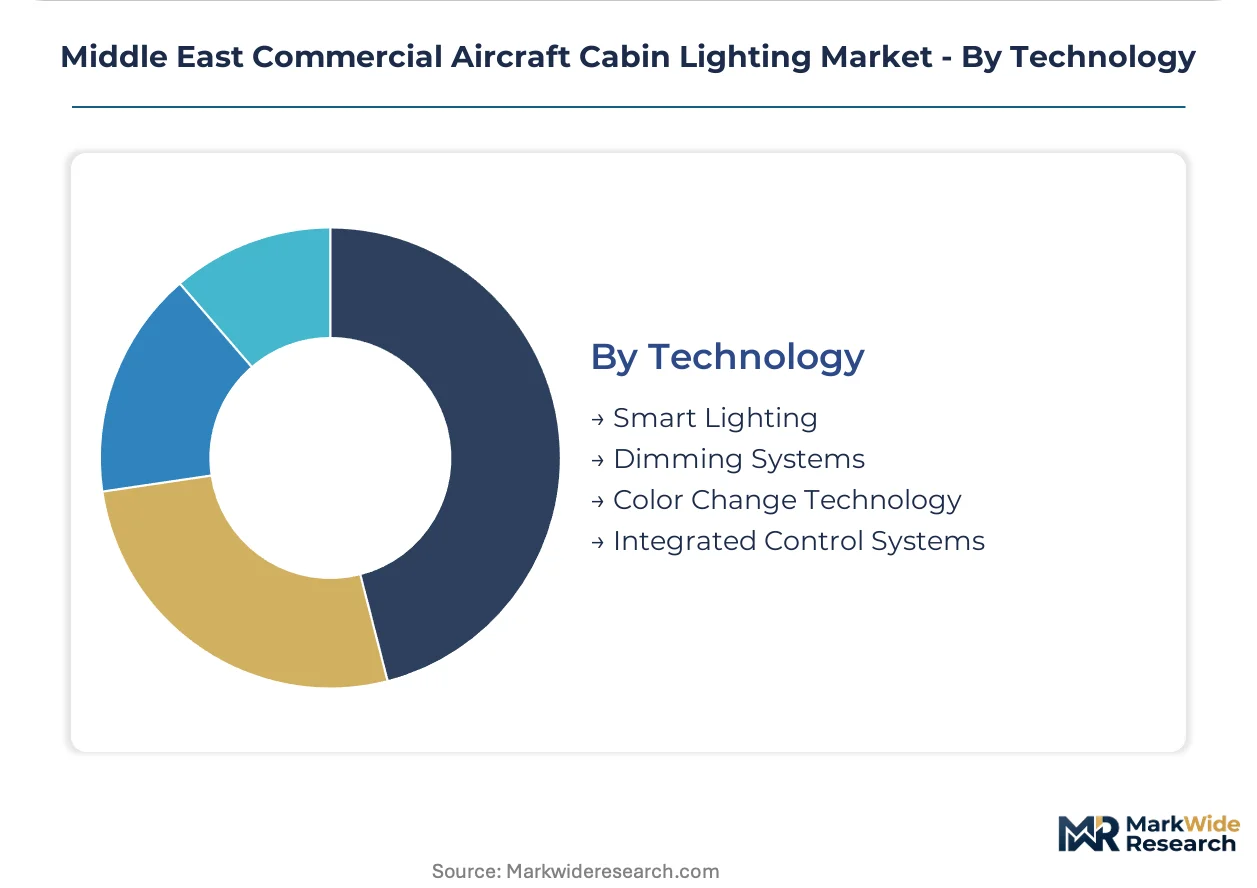
- Smart Lighting:App-controlled mood scenes tied to flight-phase automation represent the steepest expansion trajectory as Saudia and Riyadh Air deploy wellness-focused cabin experiences. GACA alignment with EU MDR-equivalent standards redirects R&D toward circadian-rhythm-certified products.
- Integrated Control Systems:Centralized cabin management interfaces consolidate lighting, climate, and entertainment controls for Emirates A380 premium cabin configurations.
- Dimming Systems:Analog and digital dimming architectures serve legacy fleet retrofits where full smart-system integration proves cost-prohibitive.
- Color Change Technology:RGB-LED arrays without full automation capability occupy mid-tier positioning in narrow-body retrofit programs.
Smart lighting claims the dominant share, while integrated control systems are advancing most rapidly as carriers converge lighting with comprehensive cabin management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Middle East diverge sharply between ultralong-haul flag carriers prioritizing circadian wellness systems and domestic operators managing compressed retrofit budgets on aging narrow-body fleets.
United Arab Emirates
Emirates Airline and Etihad Airways drive demand for specialized A380 and 787 LED configurations with programmable Kelvin-temperature control. GCAA mandates on emergency egress illumination compress compliance timelines for Dubai-based maintenance facilities. Dubai International Airport's MRO corridor concentrates supplier service networks for Collins Aerospace and Diehl Aerospace.
Saudi Arabia
Saudia's narrow-body renewal programs and Riyadh Air's expanding orderbook generate factory-install demand for LED systems on A320neo family aircraft. GACA alignment with EASA CS-25 airworthiness codes harmonizes certification pathways for regional suppliers. Riyadh's emerging aviation cluster attracts lighting subsystem specialists targeting Vision 2030 fleet expansion.
Qatar
Qatar Airways operates one of the youngest wide-body fleets globally, limiting retrofit intensity but sustaining line-fit specification influence. The national civil aviation regulator maintains EASA-derived standards for emergency lighting minimum luminance. Doha's Hamad International Airport maintenance zone serves as a secondary hub for Gulf-wide lighting system distribution.
Kuwait
Kuwait Airways' modest fleet size constrains direct procurement volume, though the carrier participates in regional consortium purchasing for LED retrofit kits. The country's civil aviation authority applies GCAA-aligned inspection intervals for aging egress systems. Kuwait International Airport's limited MRO capacity routes complex installations to Dubai-based service providers.
Israel
El Al and Israeli carriers operate mixed fleets with distinct security-driven cabin configuration requirements affecting lighting system specifications. The country's national aviation regulator maintains independent certification standards while recognizing EASA technical guidance. Tel Aviv's Ben Gurion Airport technical zone hosts specialized integrators serving narrow-body retrofit programs.
Middle East Commercial Aircraft Cabin Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated control over long-term MRO contracts and fragmented competition in component supply. The upper tier commands premium positioning through bundled system integration and regulatory certification depth. Specialist archetypes include LED retrofit kit designers, emergency egress photometric specialists, and flight-phase automation software integrators. Dominant competitive moves center on securing exclusive airline service agreements and developing GACA-preferred supplier status for Saudi fleet programs.
Within the integrated systems tier, Collins Aerospace anchors long-term MRO relationships with Dubai and Abu Dhabi flag carriers through comprehensive cabin management portfolios. Diehl Aerospace GmbH exemplifies the retrofit kit specialist archetype, occupying a position in narrow-body LED transitions for Saudi domestic operators. Safran SA and Honeywell International sit within the avionics-integrated lighting segment, representing scale-driven suppliers with factory-install access to OEM line-fit programs. These three companies collectively illustrate how supplier archetypes map to distinct procurement channels across Gulf carrier fleets.
| Leading Market Players |
|---|
| Astronics Corporation |
| Collins Aerospace |
| Diehl Aerospace GmbH |
| Luminator Technology Group |
| STG Aerospace |
| Honeywell International |
| Safran SA |
| Raytheon Technologies Corporation |
| Thales Group |
| Others |
Supply & Pricing Matrix
Long-term MRO service agreements between Gulf flag carriers and integrated systems providers lock in multi-year supply access while embedding price visibility through performance-based contracting structures. These arrangements concentrate procurement authority with Collins Aerospace and Diehl Aerospace service networks, compressing margin flexibility for component specialists competing on standalone LED retrofit kits.
Pricing Analysis
Project-based contracting dominates procurement for wide-body fleet retrofits, with Emirates Airline and Etihad Airways negotiating fixed-scope LED installations tied to EASA CS-25 certification milestones. Price differentiation rests on photometric certification grade and after-sales service bundling, with GCAA-aligned emergency egress systems commanding premiums over non-certified alternatives. Cost compression in narrow-body retrofit tiers is intensifying because second-tier Saudi domestic operators prioritize unit economics over circadian wellness features. Maintenance providers exhibit the highest price sensitivity, while flag carriers prioritize certification depth and automation integration over per-unit costs.
Supply Chain Analysis
Germany and the United States anchor avionics-certified LED component fabrication, with specialized semiconductor substrates and MIL-STD-810H-rated vibration housings feeding final assembly operations. The supply chain draws from rare-earth phosphor deposits for spectral tuning, precision optical-grade polymers for lens arrays, and aerospace-grade aluminum extrusions for thermal management. Single-source vulnerability concentrates in EASA-recognized test laboratory capacity for photometric certification. Distribution runs through Dubai International Airport's MRO corridor, with Riyadh's emerging aviation cluster gaining secondary hub status for Saudi Vision 2030 fleet programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East commercial aircraft cabin lighting market is approaching a platform-economics inflection as flight-phase automation software converges with lighting hardware, creating interoperability standards that will consolidate supplier tiers around system-integrator ecosystems.
For Market Incumbents: Shield long-term MRO contract renewal rates by embedding proprietary flight-phase automation interfaces that increase switching costs for Emirates and Etihad procurement teams. Deepen backward integration into photometric certification laboratory capacity to compress EASA CS-25 approval timelines and defend margin position against emerging LED retrofit specialists targeting Saudi narrow-body programs.
For New Entrants and Emerging Players: Anchor in the smart lighting technology segment where app-controlled mood scene development remains fragmented and carrier procurement teams actively unbundle lighting from full-cabin interior packages. Target Riyadh Air's A320neo factory-install programs as the most penetrable entry point, leveraging GACA's alignment with EU MDR-equivalent standards as a certification differentiation angle against established Gulf service networks.
For Investors and Strategic Acquirers: Avionics-certified software integrators with demonstrated flight management system interoperability represent the highest-conviction acquisition target archetype for exposure to platform consolidation dynamics. Monitor GCAA inspection interval enforcement intensity as the critical signal for retrofit cycle acceleration and LED transition inflection timing across second-tier operator fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Photometric Certification Laboratory Expansion | EASA CS-25 recognition compresses product launch cycles for Dubai-based MRO providers. |
| Flight-Phase Automation Software Integration | App-controlled mood scene convergence locks in Emirates and Etihad premium cabin specifications. |
| Backward Integration into LED Component Supply | In-house production of Kelvin-tunable arrays defends margin against narrow-body retrofit price compression. |
| GACA-Preferred Supplier Status Development | EU MDR-equivalent alignment opens Riyadh Air and Saudia factory-install procurement channels. |
| Emergency Egress System Retrofit Specialization | GCAA-mandated LED transitions create recurring revenue streams across aging wide-body fleets. |
Research Methodology
A spread of perspectives from fleet engineering directors, MRO procurement managers, avionics certification specialists, and regulatory affairs leads at GCAA and GACA converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EASA CS-25 amendment documentation, GCAA airworthiness directive filings, and OEM line-fit program disclosures from Airbus and Boeing. Customs records for LED component imports into the UAE and Saudi Arabia, alongside SEC 10-K segment disclosures from listed avionics suppliers, provided demand-side triangulation. Bottom-up fleet retrofit cycle modeling and top-down regulatory compliance timeline analysis were cross-referenced for convergence.
Segmentation dimensions modeled span product type, application zone, end-user procurement authority, and technology integration depth across the projection horizon. The analytical framework incorporated aircraft fleet age profiles, regulatory inspection interval schedules, and carrier route structure characteristics as industry-specific forecast inputs. CAGRs were derived from installed base replacement velocity projections and new-build line-fit penetration assumptions, with sensitivity analysis applied to GACA-EASA harmonization timing scenarios.
Material uncertainties — regulatory inspection interval acceleration, avionics engineer labor pool expansion rates, and wide-body fleet retirement decisions — sit outside the modeled envelope. Forecasts reflect assumptions about continued GCAA-EASA regulatory alignment and sustained ultralong-haul route expansion by Gulf flag carriers. Recalibration cycles align with material shifts in GACA enforcement posture and Saudi Vision 2030 fleet delivery schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market