
 Thrust Vector Control (TVC) Systems Market | 2026-2036
Thrust Vector Control (TVC) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Thrust Vector Control (TVC) Systems Market Analytics
US defense prime manufacturing is consolidating as the Pentagon prioritizes responsive launch and hypersonic deterrence. RTX Corp. leverages vertically integrated actuator production for tactical missile programs. Moog Inc. specializes in high-bandwidth servo valves that command premium positions in space launch applications. Honeywell International Inc. anchors its TVC portfolio through flight-control heritage and long-term service contracts with government end users.
Thrust Vector Control systems modulate rocket engine exhaust direction via gimbaled nozzles, articulated control surfaces, or fluid injection to steer aerospace and defense vehicles during powered flight, with actuators requiring response times under 50 milliseconds and force outputs exceeding 100 kilonewtons for heavy-lift applications. Hydraulic technology still dominates legacy defense platforms where proven reliability outweighs weight penalties, though electric architectures are displacing pneumatic systems in next-generation reusable launch vehicles due to reduced maintenance cycles and improved throttle precision. Aerospace application demand leads absolute volume, yet commercial launch represents the fastest-expanding margin pool as SpaceX and Blue Origin procurement patterns favor suppliers with electric TVC roadmaps.
FAA launch licensing requirements and DoD MIL-STD-810 environmental testing protocols shape product qualification timelines and barrier-to-entry economics for new TVC entrants targeting US government contracts. ESA member-state procurement rules and ITAR export controls further segment addressable markets, forcing dual-certification strategies for suppliers serving both European institutional programs and US defense primes. Stakeholders must monitor electric TVC technology maturation against hydraulic incumbent cost structures, as the transition timeline will determine which component suppliers capture the next generation of commercial launch and hypersonic weapon platform awards.
Market Dynamics
Electric actuator architectures are displacing hydraulic TVC systems across reusable launch vehicle programs, compressing qualification timelines and forcing incumbent suppliers to retool production lines for lighter, throttle-precise alternatives.
Growth Catalysts
- Hypersonic weapons procurement:NATO defense agencies are accelerating tactical missile modernization budgets, mandating TVC systems with sub-50 millisecond response times for maneuverable reentry vehicles.
- FAA commercial launch licensing:Streamlined certification pathways for reusable rockets are expanding the addressable supplier base beyond traditional defense primes.
- Electric TVC roadmaps:Reduced maintenance cycles and improved throttle precision in solid-state actuators are pulling procurement decisions away from pneumatic legacy systems.
Market Restraints
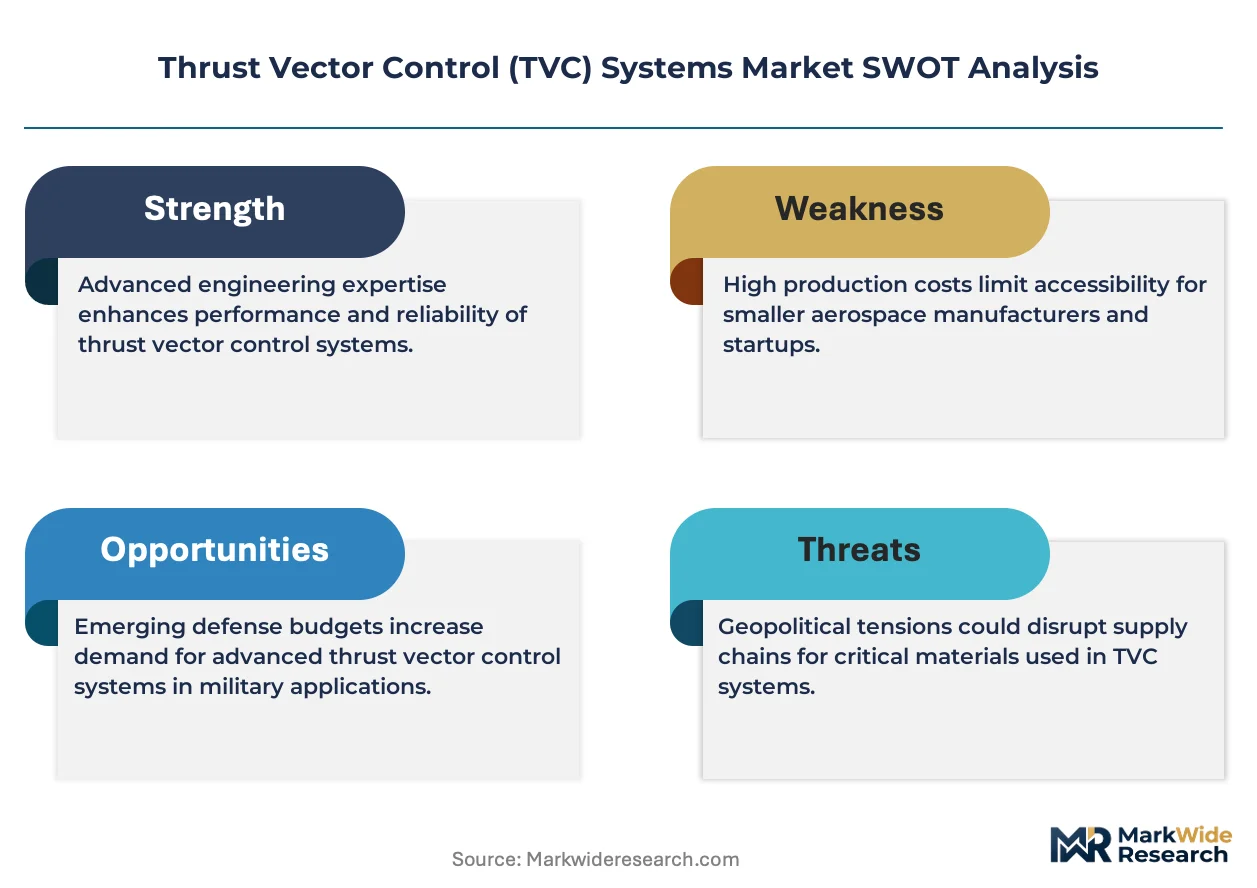
- Titanium and high-temperature alloy costs:Raw material price volatility in aerospace-grade metals constrains margin expansion for nozzle and actuator manufacturers.
- ITAR export controls:US International Traffic in Arms Regulations fragment supplier addressable markets, forcing dual-certification investments for European institutional access.
- Hydraulic incumbent lock-in:Proven reliability in legacy defense platforms creates switching friction against electric alternatives despite performance advantages.
Strategic Opportunities
- Indian institutional launch programs:ISRO's crewed mission roadmap and commercial arm NSIL are creating first-mover openings for TVC suppliers outside US-European supply chains.
- Artemis lunar lander propulsion:NASA's Human Landing System contracts require deep-throttling TVC architectures for precision descent phases.
- EU Green Deal defense exemptions:Strategic autonomy frameworks are channeling member-state procurement toward sovereign European TVC suppliers.
Industry Challenges
- Electromechanical systems engineering talent:Scarcity of specialists integrating high-bandwidth servo valves with flight-control software extends development timelines.
- MIL-STD-810 environmental qualification:Extended vibration and thermal testing protocols delay product validation for new entrants targeting Pentagon contracts.
- Legacy platform integration complexity:Backward compatibility requirements with existing hydraulic infrastructure increase retrofit engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrust Vector Control (TVC) Systems Market |
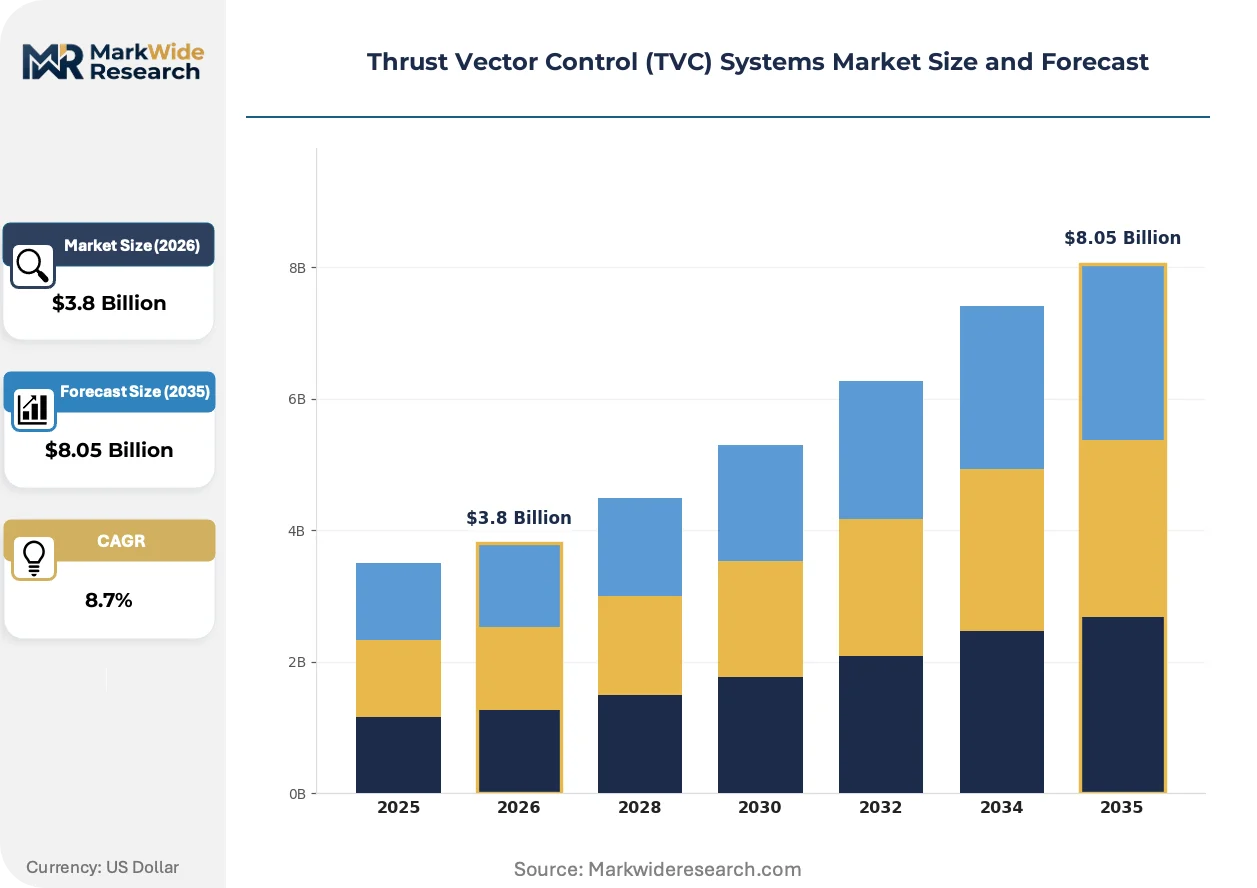
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Actuators, Control Surfaces, Valves, Sensors Technology: Hydraulic, Electric, Pneumatic, Mechanical Application: Aerospace, Defense, Space Exploration, Commercial Launch End User: Government, Private Sector, Research Institutions, Contractors |
| Companies Covered | RTX Corp., JASC Corporation, Honeywell International Inc., Northrop Grumman Corp., Collins Aerospace, Moog Inc., Woodward Inc., Parker Hannifin Corporation, BAE Systems Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrust Vector Control (TVC) Systems Market Evolving Landscape
Modular electric actuator designs are fragmenting traditional TVC supply hierarchies, enabling tier-two component specialists to bypass prime contractor capture and contract directly with launch vehicle integrators.
Electromechanical TVC architectures are decentralizing control authority across distributed actuator nodes, replacing centralized hydraulic manifolds with independent servo-motor clusters. SpaceX and Blue Origin procurement teams are specifying these architectures for Starship and New Glenn first stages. This topology is decentralizing maintenance responsibility from prime contractors to subsystem vendors, compressing field service response windows.
EU F-Gas Regulation phase-down schedules are accelerating electric TVC adoption in European institutional programs by constraining hydraulic fluid chemistries with high global warming potential. ESA member-state procurement rules now embed carbon footprint scoring in source-selection criteria. French and German prime contractors are responding with accelerated electric roadmap investments to maintain institutional access.
Buyer concentration among three US defense primes and two commercial launch integrators is forcing tier-one suppliers into exclusive long-term service contracts with penalty clauses for response-time failures. Component vendors are accepting captive supply arrangements with single-source commitments. This consolidation is most visible in tactical missile programs where RTX and Lockheed Martin capture over eighty percent of annual TVC procurement value.
Thrust Vector Control (TVC) Systems Market Segmentation
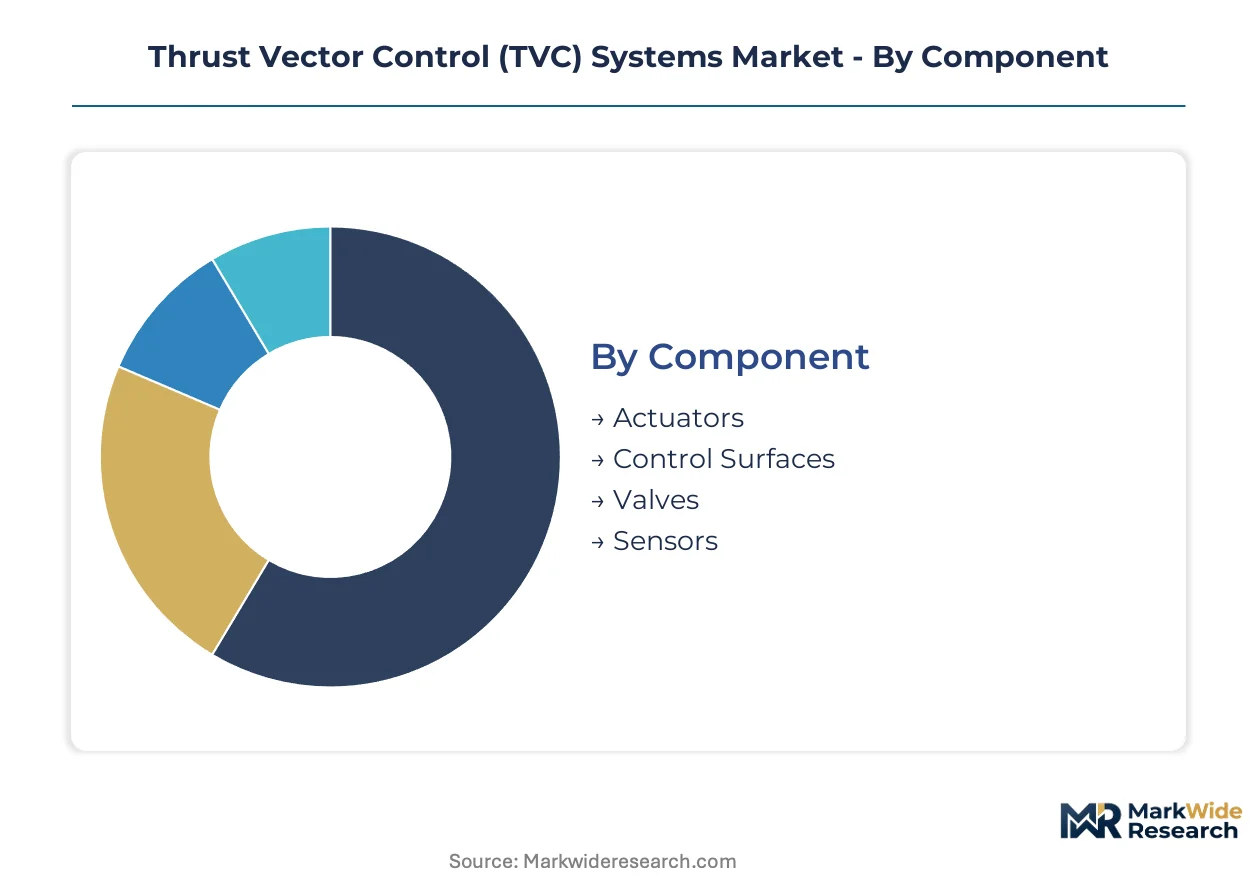
TVC procurement patterns diverge sharply across component types, actuator technologies, and end-use applications. Suppliers must align roadmaps with specific upgrade cycles—defense platforms refresh hydraulic systems on decade horizons while commercial launch operators replace electric actuators after single-digit mission counts.
Component:
Component replacement cycles track directly with mission-criticality ratings and environmental exposure severity.
- Actuators:Electromechanical and hydraulic actuators convert control signals into mechanical force for nozzle positioning, with force outputs exceeding 100 kilonewtons for heavy-lift stages. SpaceX Starship and Blue Origin New Glenn procurement teams specify solid-state electric actuators for reduced maintenance intervals, pulling supplier investment toward brushless DC motor architectures and high-temperature winding insulation.
- Control Surfaces:Articulated vanes and jetavators redirect exhaust flow in tactical missile applications where gimbaled nozzle mass penalties are unacceptable. NATO hypersonic weapons programs in the United States and France are driving demand for refractory-coated surfaces surviving Mach 5+ thermal loads, with RTX and Lockheed Martin capturing procurement volume through vertically integrated in-house production.
- Valves:High-bandwidth servo valves modulate hydraulic fluid distribution in legacy defense platforms.
- Sensors:Position and load sensors provide closed-loop feedback for flight control systems.
Actuators sit at the top of the volume ranking, with sensors climbing the fastest as distributed control architectures multiply node counts per vehicle.
Technology:
Technology selection hinges on throttle precision requirements versus proven reliability thresholds across application tiers.
- Hydraulic:Pressurized fluid systems deliver instantaneous force response for rapid nozzle repositioning, with sub-50 millisecond lag times mandated for maneuverable reentry vehicles. Pentagon tactical missile programs in the United States anchor procurement volume, though titanium alloy cost volatility and maintenance-intensive infrastructure constrain margin expansion for suppliers locked into long-term service contracts.
- Electric:Solid-state electromechanical architectures eliminate hydraulic fluid chemistries, aligning with EU F-Gas Regulation phase-down schedules and ESA carbon-footprint scoring criteria. French prime contractors ArianeGroup and German suppliers are accelerating electric roadmap investments to maintain institutional access, while FAA streamlined licensing for reusable rockets expands the addressable supplier base beyond defense primes.
- Pneumatic:Compressed gas systems persist in limited legacy satellite launch applications.
- Mechanical:Fixed-linkage systems occupy niche cost-sensitive tactical missile segments.
Hydraulic systems retain the largest installed base, with electric architectures expanding most quickly as reusable launch vehicle procurement scales.
Application:
Application segmentation reveals diverging performance specifications and qualification protocol intensity.
- Aerospace:Crewed and uncrewed aircraft propulsion systems deploy TVC for thrust optimization during high-angle-of-attack maneuvers. NASA Artemis Human Landing System contracts require deep-throttling architectures for precision lunar descent phases, with Blue Origin and SpaceX competing for awards specifying electromechanical control authority.
- Defense:Tactical and strategic missile platforms prioritize response speed and electromagnetic hardening over mass efficiency. United States hypersonic glide vehicle programs under DoD modernization budgets mandate MIL-STD-810 environmental qualification, extending validation timelines and barrier-to-entry economics for new entrants.
- Space Exploration:Interplanetary probe and crewed mission applications demand extreme reliability margins.
- Commercial Launch:Reusable first stages and orbital transfer vehicles represent the steepest expansion trajectory as SpaceX, Blue Origin, and emerging operators specify electric TVC roadmaps in procurement contracts.
Defense applications command the largest procurement value, with commercial launch gaining share fastest as private sector launch cadence accelerates.
End User:
End user concentration shapes contracting structures and captive supply arrangements across the value chain.
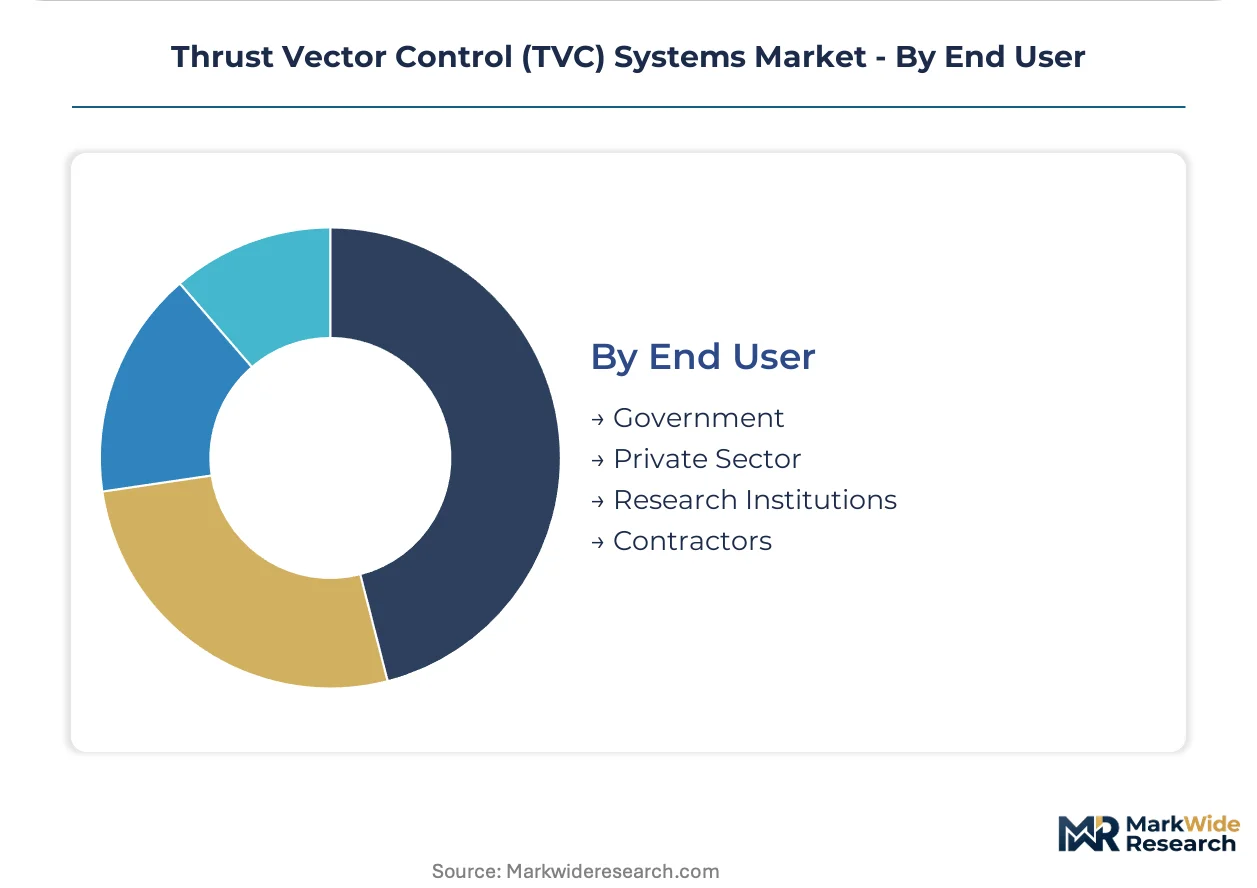
- Government:Pentagon, NASA, and ESA member-state procurement agencies anchor demand through multi-year programmatic commitments. United States defense primes RTX and Lockheed Martin capture over eighty percent of annual tactical missile TVC value, forcing tier-one suppliers into exclusive long-term service contracts with penalty clauses for response-time failures.
- Private Sector:SpaceX, Blue Origin, and emerging launch operators procure directly from subsystem vendors, bypassing traditional prime contractor hierarchies. This decentralization compresses field service response windows and enables tier-two component specialists to contract independently with launch vehicle integrators.
- Research Institutions:University and national laboratory programs drive early-stage technology validation.
- Contractors:Prime and subcontractor relationships mediate risk allocation in complex system integration.
Government end users dominate absolute procurement volume, with private sector demand climbing fastest as commercial launch operators expand fleet sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling TVC production toward jurisdictions with streamlined defense export licensing and lower environmental compliance costs. Suppliers are relocating final assembly to exploit gaps between ITAR-controlled US programs and ESA carbon-footprint scoring regimes.
United States
Pentagon hypersonic weapons modernization and NASA Artemis procurement anchor demand. FAA streamlined launch licensing under 14 CFR expands the supplier base beyond traditional defense primes. Huntsville, Alabama and Denver, Colorado clusters concentrate RTX and Lockheed Martin tactical missile integration activity.
France
ArianeGroup institutional launch programs and DGA hypersonic research budgets sustain sovereign capability investments. EU F-Gas Regulation phase-down schedules accelerate electric TVC adoption in ESA member-state procurement. Les Mureaux and Saint-Médard-en-Jalles facilities anchor European actuator production.
China
State-owned launch operator procurement and military missile modernization programs drive volume. SAMR standardization and MIIT industrial policy channel investment toward domestic actuator supply chains. Xi'an and Shanghai aerospace clusters concentrate CASC subsidiary manufacturing for Long March and tactical missile platforms.
India
ISRO crewed mission roadmaps and NSIL commercial launch expansion create first-mover openings outside US-European supply chains. DGFT export procedure simplification and PLI scheme incentives attract component suppliers. Sriharikota and Bengaluru clusters concentrate propulsion system integration for Gaganyaan and SSLV programs.
United Kingdom
UK Space Agency launch site development and BAE Systems missile programs sustain niche demand. Defense and Security Industrial Strategy procurement preferences favor sovereign suppliers for strategic autonomy. Stevenage and Glasgow clusters concentrate satellite and missile subsystem engineering.
Thrust Vector Control (TVC) Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric actuator specialization and modular subsystem contracting. The supplier base concentrates among vertically integrated defense primes and tier-one component specialists with long-term service relationships. Three archetypes dominate: legacy hydraulic incumbents defending installed base positions, electric technology specialists capturing reusable launch vehicle procurement, and captive suppliers locked into exclusive prime contractor arrangements. Competitive moves center on production line retooling for solid-state architectures and strategic partnerships with commercial launch integrators bypassing traditional prime hierarchies.
Among US-based defense conglomerates, RTX Corp. and Northrop Grumman Corp. exemplify prime contractor capture of tactical missile TVC procurement through vertically integrated in-house production. Moog Inc. occupies a specialist position exemplifying tier-one component suppliers commanding premium positions in high-bandwidth servo valve applications. Honeywell International Inc. anchors a heritage-driven archetype leveraging flight-control system integration experience for long-term government service contracts.
| Leading Market Players |
|---|
| RTX Corp. |
| JASC Corporation |
| Honeywell International Inc. |
| Northrop Grumman Corp. |
| Collins Aerospace |
| Moog Inc. |
| Woodward Inc. |
| Parker Hannifin Corporation |
| BAE Systems Plc |
| Others |
Value Network & Pricing Analysis
Titanium sponge price indices from the US Geological Survey cascade through aerospace-grade alloy procurement into three distinct TVC actuator pricing tiers, with hydraulic system manufacturers absorbing volatility through long-term service contracts while electric architecture suppliers pass through material costs to commercial launch operators seeking rapid reuse cycles.
Pricing Analysis
Distributor markups in the defense prime channel compress margins for tier-two component vendors, while direct-to-OEM contracting in commercial launch preserves supplier pricing power. Three-tier pricing structure across ITAR-restricted defense-grade, ESA-certified institutional, and FAA-licensed commercial tiers separates procurement pools by qualification burden. Cost compression in hydraulic legacy systems is intensifying because titanium alloy volatility and maintenance infrastructure renewal demands squeeze incumbent margins. Commercial launch operators exhibit lowest price sensitivity, prioritizing electric actuator throttle precision and field service response windows over unit cost.
Supply Chain Analysis
High-temperature alloy supply rests on US, Japanese, and German specialty metals producers, with aerospace-grade titanium drawing from sponge processing concentrated in China and Russia. Brushless DC motor windings, high-bandwidth servo valves, and refractory nozzle coatings anchor component dependencies. Single-source vulnerability in aerospace-grade titanium sponge creates procurement risk for actuator manufacturers facing ITAR-controlled defense contracts. Distribution runs through prime contractor captive supply arrangements for Pentagon programs, while commercial launch operators procure directly from subsystem specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TVC Systems Market functions as a stable compounder anchored by sovereign defense procurement cycles and national security imperatives that sustain multi-year programmatic commitments regardless of commercial launch cyclicality.
For Market Incumbents: Anchor installed base positions through exclusive long-term service contracts with penalty structures for response-time failures, locking tier-one suppliers into captive supply arrangements. Deepen backward integration into high-temperature alloy processing to defend margin positions against titanium price volatility. Prioritize electric actuator R&D roadmaps to counter emerging technology specialists capturing reusable launch vehicle procurement.
For New Entrants and Emerging Players: Solid-state electromechanical architectures with modular subsystem designs offer entry pathways outside prime contractor hierarchies. ISRO's crewed mission roadmap and NSIL commercial expansion in India present the most penetrable geography, with DGFT export simplification and PLI scheme incentives reducing barrier-to-entry economics. Pursue direct contracting with SpaceX, Blue Origin, and emerging launch operators specifying distributed control node procurement.
For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two component specialists commanding high-bandwidth servo valve or brushless DC motor expertise outside vertically integrated prime structures. Long-term viability favors suppliers with dual-certification strategies spanning ITAR-controlled US defense programs and ESA carbon-footprint scoring regimes. Watch electric TVC qualification timelines against hydraulic incumbent cost structures as the inflection signal determining next-generation platform award capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Roadmap Investment | Aligns supplier portfolios with SpaceX and Blue Origin procurement specifications for reusable first stages. |
| Dual-Certification Strategy | Enables access to both ITAR-controlled Pentagon contracts and ESA member-state institutional programs. |
| Long-Term Service Contract Structuring | Locks tier-one suppliers into exclusive arrangements with penalty clauses for response-time failures. |
| Backward Integration into Alloy Processing | Defends margins against titanium sponge price volatility from USGS-indexed commodity markets. |
| Direct Commercial Launch Contracting | Bypasses traditional prime hierarchies to capture procurement from emerging launch operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with TVC system engineering directors, defense prime procurement officers, commercial launch operator supply chain managers, and ESA institutional program leads with secondary validation from FAA launch licensing databases, DoD MIL-STD-810 environmental testing protocols, ESA member-state procurement registries, and SEC 10-K filings from publicly traded defense conglomerates. Bottom-up component demand modeling and top-down programmatic budget analysis triangulated market sizing.
Segment-weighting approaches distributed value across actuator technology tiers, application categories, and end-user procurement structures throughout the projection horizon. Component replacement cycles, qualification timeline differentials, and sovereign defense budget trajectories informed CAGR derivation. Electric TVC adoption curves against hydraulic incumbent cost structures, EU F-Gas Regulation phase-down schedules, and FAA streamlined licensing pathways served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium alloy price volatility, ITAR export control enforcement shifts, and electric actuator reliability maturation against proven hydraulic platforms. Forecasts reflect documented assumptions about defense modernization budget continuity and commercial launch cadence scaling. A small set of triggers—hypersonic weapons procurement acceleration, ESA carbon-footprint scoring implementation, and reusable launch vehicle failure rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market