
 Aircraft Line Maintenance Market | 2026-2036
Aircraft Line Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Line Maintenance Market Intelligence
The structure of maintenance provision is reconfiguring as airlines weigh in-house capabilities against outsourcing to third-party MROs. Lufthansa Technik AG leverages its global footprint and OEM relationships to serve major international carriers. AAR Corporation competes through its integrated parts supply and logistics network, offering a distinct value proposition. ST Engineering Aerospace differentiates with comprehensive nose-to-tail services across a wide array of commercial and military aircraft platforms, securing contracts with diverse customer types.
Aircraft line maintenance encompasses all routine tasks performed on an aircraft while it remains in active service, typically at the airport gate or on the ramp. These activities, including transit checks and pre-flight inspections, are designed to ensure immediate airworthiness and minimize operational disruptions between flights. The wide-body aircraft segment represents a high-value area due to the complexity of its systems and longer maintenance intervals. Within service types, avionics testing and engine checks are becoming more data-intensive, requiring advanced diagnostic tools and specialized technicians.
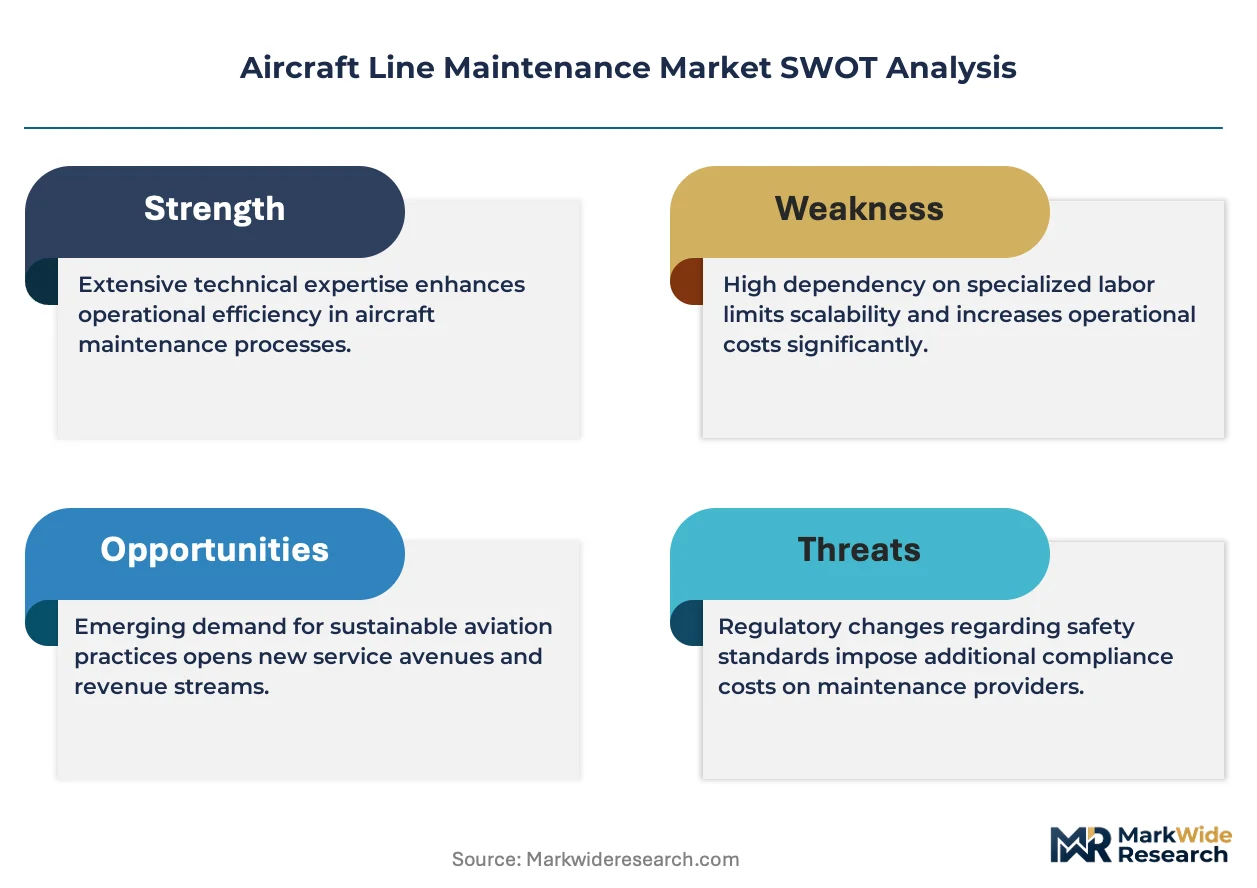
Regulatory oversight from bodies like the U.S. Federal Aviation Administration (FAA) and Europe's primary aviation safety agency sets stringent standards for all maintenance activities. These regulations dictate technician certification, parts traceability, and documentation, forming a high barrier to entry for new service providers. Navigating the choice between investing in proprietary digital maintenance platforms and adopting third-party solutions is a critical strategic decision for all MROs and airline maintenance departments.
Market Dynamics
The aircraft line maintenance market is being reshaped by the imperative to reduce aircraft-on-ground (AOG) time. This pressure is accelerating the adoption of digital tools and predictive analytics, shifting the entire maintenance paradigm from a reactive to a proactive model.
Growth Catalysts
- Predictive Analytics Adoption:The use of AI and machine learning platforms to analyze flight data and predict component failures enables proactive maintenance, reducing unscheduled service needs and maximizing aircraft availability.
- Air Cargo Expansion:Sustained growth in e-commerce and global trade is driving demand for dedicated freighter aircraft, creating a specialized and consistent need for line maintenance services at major cargo hubs like Memphis, Dubai, and Hong Kong.
- Regulatory Harmonization:Ongoing efforts by the U.S. Federal Aviation Administration (FAA) and Europe's primary aviation safety agency to align certification and maintenance standards reduce compliance costs and operational friction for MROs serving a global clientele.
Market Restraints
- Spare Parts Logistics:High costs and long lead times for proprietary, certified aircraft components, particularly for new-generation wide-body models, act as a significant constraint on the speed and profitability of line maintenance operations.
- Legacy System Integration:The technical difficulty and expense of integrating modern digital maintenance software with airlines' decades-old legacy IT and enterprise resource planning systems slows the adoption of efficiency-enhancing technologies.
- Technician Certification Standards:Stringent and lengthy certification processes mandated by regulators like the FAA for aircraft maintenance technicians create a high barrier to entry and contribute to skilled labor shortages.
Strategic Opportunities
- Emerging Market Expansion:Establishing line maintenance stations in rapidly growing aviation markets in Southeast Asia and the Middle East offers access to new airline customers and fleet types currently underserved by established MRO networks.
- Augmented Reality (AR) Solutions:Developing AR-based remote assistance tools allows experienced engineers to virtually guide on-site technicians through complex repairs, improving first-time fix rates and mitigating skill gaps across the network.
- Sustainable Aviation Services:Creating specialized maintenance protocols and training for aircraft modified to use sustainable aviation fuels (SAF) or new propulsion systems presents a long-term opportunity as the industry decarbonizes.
Industry Challenges
- Avionics Skills Gap:A critical shortage of technicians with dual certification in both traditional airframe mechanics and modern, software-intensive avionics systems challenges the ability of MROs to service next-generation aircraft efficiently.
- Data Standardization:The lack of a universal standard for data formats from various OEMs, sensors, and airline systems complicates the development of unified predictive maintenance platforms, creating significant data integration hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Line Maintenance Market |
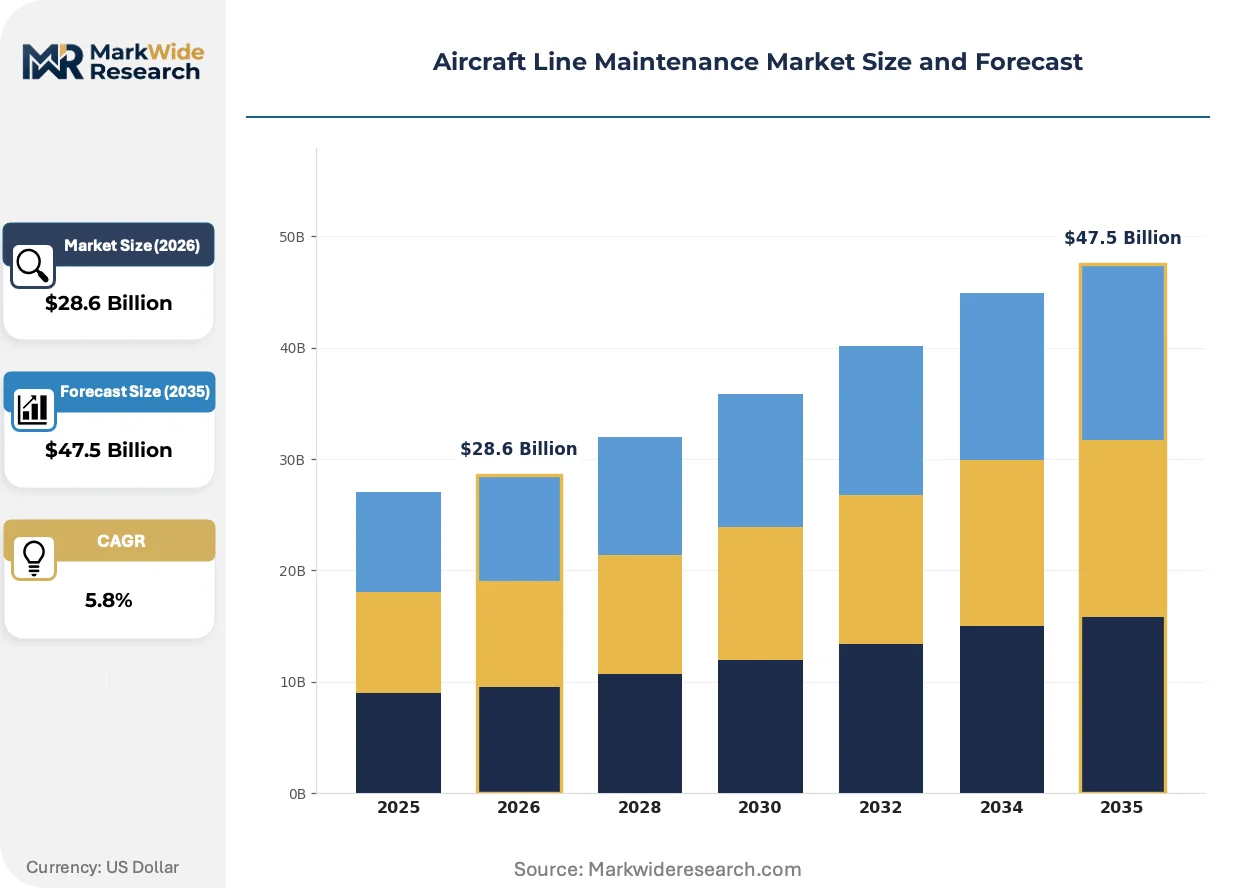
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Inspections, Engine Checks, Tire Replacements, Avionics Testing, Fuel System Servicing Maintenance Provider: Airlines, Independent MROs, OEM Service Centers, Specialized Workshops, Ground Handling Agencies Aircraft Type: Single-Aisle Jets, Wide-Body Aircraft, Regional Jets, Business Jets, Cargo Planes Customer Type: Commercial Airlines, Government Operators, Charter Companies, Leasing Firms, Corporate Fleets |
| Companies Covered | Air France Industries KLM Engineering & Maintenance, AAR Corporation, Lufthansa Technik AG, Ameco, SR Technics, Delta TechOps, ST Engineering Aerospace, ANA Line Maintenance Technics Co., Ltd., HAECO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Line Maintenance Market Strategic Shifts & Innovations
A fundamental shift from scheduled, interval-based maintenance to condition-based, predictive servicing defines the market's current trajectory. This evolution is driven by the deployment of advanced sensor technology and data analytics platforms that monitor aircraft health in real time.
Digital twin technology is a key innovation where a virtual replica of a physical aircraft or component is created. Airlines and MROs are adopting this for high-value assets like engines to simulate operational stress and forecast maintenance needs with greater precision. This technology is digitizing the entire process of maintenance planning and record-keeping, replacing manual logs with dynamic, data-rich models.
New sustainability mandates, such as the EU's directives within its Green Deal framework, are influencing engine maintenance practices. These regulations compel airlines to adopt cleaner technologies and fuels, which in turn requires MROs to develop new inspection and repair procedures for modified engines and fuel systems. Engine maintenance specialists serving European carriers are most directly affected, investing in updated tooling and technician training.
Airlines are altering their service purchasing models by unbundling large, comprehensive MRO contracts. Instead of single-source agreements, carriers are selectively contracting with specialized providers for discrete tasks like avionics testing, engine services, or component repair. This trend, most prominent in the mature North American market, allows airlines to optimize costs and access best-in-class expertise for specific high-value maintenance functions.
Aircraft Line Maintenance Market Segmentation
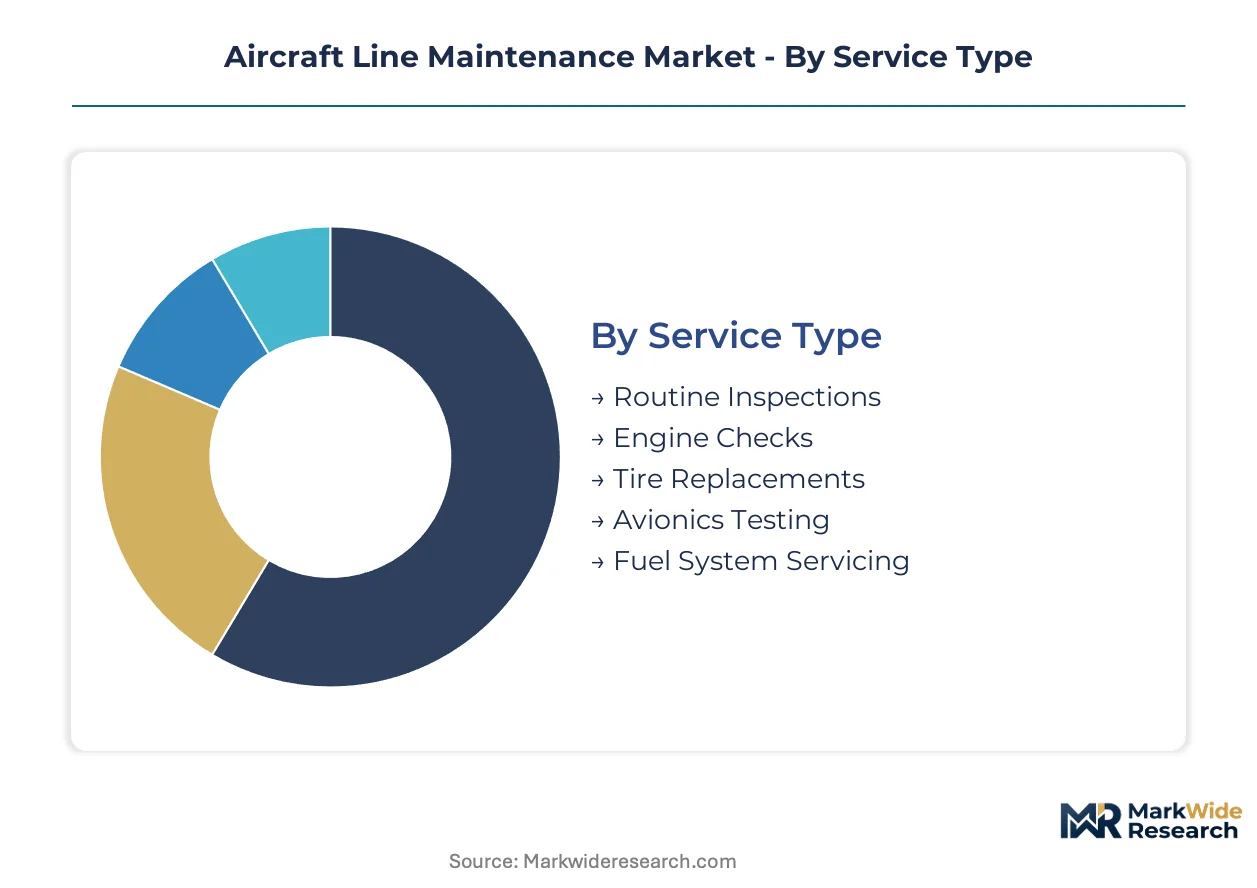
The aircraft line maintenance market is fundamentally segmented by the distinct operational needs of various service types, provider models, aircraft categories, and customer profiles. Understanding these divisions is crucial for MROs to tailor offerings and for airlines to optimize their maintenance strategies effectively.
Service Type:
The service type segment reveals a blend of mature, established practices and rapidly evolving, technology-driven maintenance activities.
- Routine Inspections:These fundamental checks ensure immediate airworthiness and involve visual examinations and basic system tests. Demand for these high-volume tasks is concentrated at major airport hubs due to frequent aircraft turnarounds.
- Avionics Testing:This involves complex diagnostics of integrated digital systems and software, crucial for modern aircraft. Demand is rising for next-generation aircraft at specialized MRO centers due to increasing technological sophistication.
- Engine Checks:Detailed examinations of propulsion systems require specialized tooling and adherence to OEM protocols.
- Tire Replacements:Essential safety tasks performed at regular intervals, critical for landing and takeoff performance.
- Fuel System Servicing:Ensures the integrity and functionality of fuel delivery components, vital for operational safety.
Routine Inspections handles the majority of throughput; Avionics Testing is the fastest mover on share.
Maintenance Provider:
The market for maintenance providers exhibits varying degrees of supply concentration, from integrated airline operations to niche specialists.
- Independent MROs:These offer flexible, multi-fleet services to a broad customer base. Demand is strong in regions with diverse aircraft types seeking cost-effective solutions and specialized expertise.
- Airlines:Many large carriers maintain internal capabilities for immediate operational control and proprietary fleet knowledge. Demand is driven by these operators prioritizing in-house efficiency and direct oversight.
- OEM Service Centers:These provide specialized, often warranty-backed maintenance for specific aircraft models or components.
- Specialized Workshops:These focus on particular tasks like composite repair or component overhaul, serving as expert subcontractors.
- Ground Handling Agencies:These often provide basic line maintenance tasks as part of broader airport services, supporting quick turnarounds.
Independent MROs and Airlines collectively manage the largest share of maintenance volume, reflecting their extensive operational footprints.
Aircraft Type:
Aircraft type segmentation highlights the differing volumes and complexities associated with various fleet categories.
- Single-Aisle Jets:Constitute the largest segment by fleet numbers, requiring high-frequency, standardized line maintenance. Demand is constant across all major commercial aviation markets due to their widespread use.
- Wide-Body Aircraft:These feature complex systems and longer maintenance intervals, leading to higher-value, specialized tasks. Demand is concentrated at major international hubs for long-haul operations.
- Regional Jets:These serve shorter routes and smaller airports, driving demand for localized, efficient maintenance solutions.
- Business Jets:These require discreet, highly responsive maintenance services tailored to individual owner schedules.
- Cargo Planes:These experience heavy utilization cycles, creating consistent demand for line maintenance at global logistics hubs.
Single-Aisle Jets generate the greatest service frequency, while Cargo Planes are experiencing a rapid expansion in maintenance requirements.
Customer Type:
The customer type segment delineates distinct operational requirements and procurement behaviors across various aviation stakeholders.
- Commercial Airlines:Represent the largest customer base, driving demand for scalable, cost-efficient maintenance solutions across extensive fleets. Demand is global, influenced by passenger traffic and fleet size.
- Leasing Firms:These require maintenance services to maintain asset value and ensure airworthiness for re-leasing to operators. Demand is concentrated in major aircraft financing centers.
- Government Operators:These demand specialized, high-security maintenance for military and public service aircraft.
- Charter Companies:These seek responsive, flexible maintenance to minimize aircraft-on-ground time and maximize availability.
- Corporate Fleets:These prioritize reliability and rapid turnaround times for their executive transport aircraft, often requiring on-demand services.
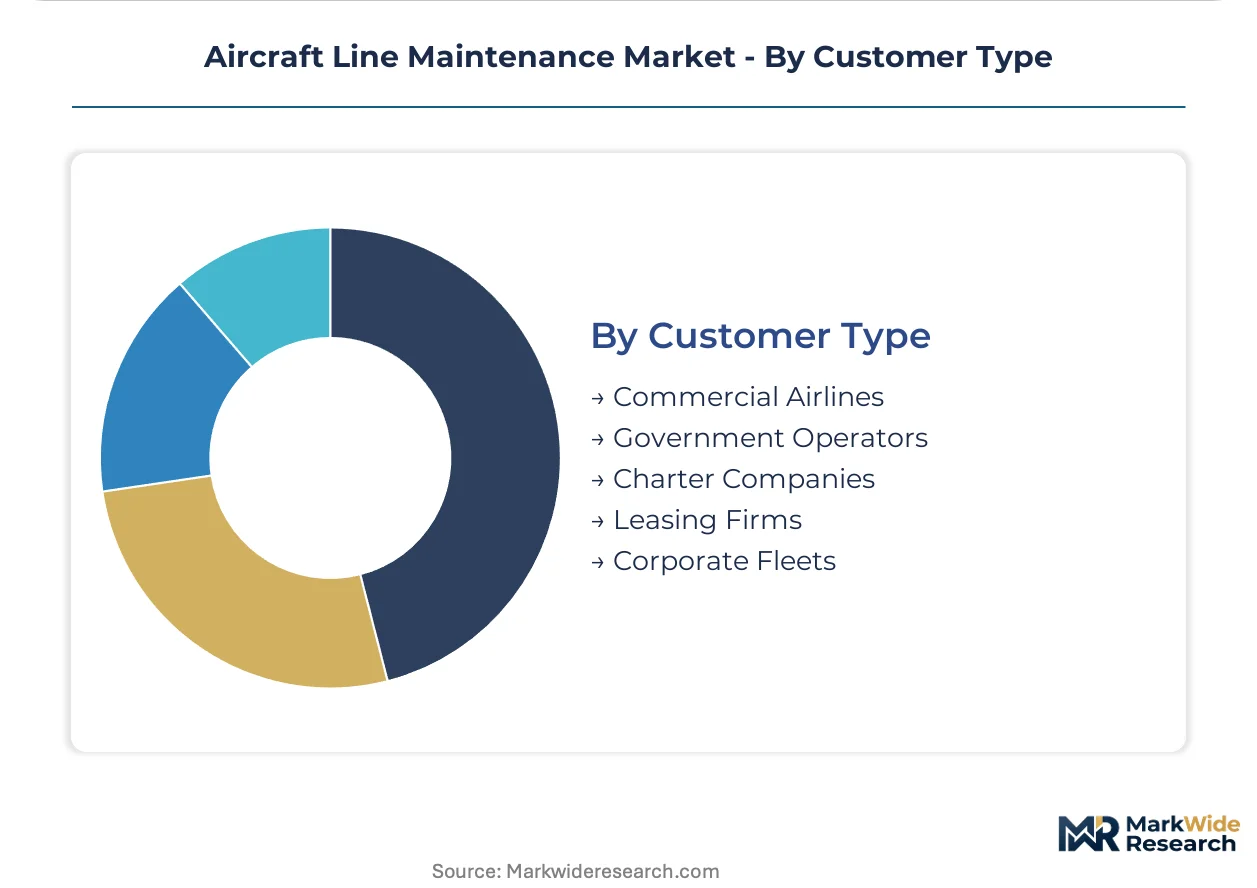
Commercial Airlines dominate overall demand, yet Leasing Firms are increasingly influencing maintenance procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global air transportation network underwrites the diverse geographical distribution of aircraft line maintenance activities. Major international airports, serving as crucial hubs, facilitate high-volume maintenance operations for commercial and cargo fleets. This infrastructure supports the immediate airworthiness requirements of a constantly moving global fleet.
United States
Extensive domestic air travel and significant air cargo operations drive consistent demand for line maintenance services across the country. The U.S. Federal Aviation Administration (FAA) dictates stringent maintenance standards and technician certification for all aviation activities. Major MRO hubs like those in Atlanta and Dallas-Fort Worth support high-frequency line maintenance for various aircraft types.
United Arab Emirates
Rapid growth in international passenger traffic and expanding cargo operations position the UAE as a key regional hub for line maintenance. The General Civil Aviation Authority (GCAA) oversees aviation safety and maintenance standards across the Emirates. Dubai International Airport and Al Maktoum International Airport serve as critical line maintenance centers, attracting significant investment in MRO facilities.
Germany
Germany's significant base of major international carriers and strong engineering heritage contribute to robust line maintenance demand. Europe's primary aviation safety agency (EASA) sets comprehensive regulatory frameworks for aircraft maintenance across the region. Frankfurt Airport, a major Lufthansa Technik AG hub, handles extensive line maintenance for wide-body and narrow-body aircraft.
Singapore
Singapore's strategic position in Southeast Asia and its burgeoning aviation market underpin strong demand for advanced MRO capabilities. The Civil Aviation Authority of Singapore (CAAS) enforces rigorous safety and maintenance protocols for all aircraft operations. Changi Airport's MRO ecosystem, including facilities by ST Engineering Aerospace, provides nose-to-tail services for diverse fleet types.
China
The rapid expansion of domestic and international air travel, coupled with growing freighter fleets, boosts line maintenance requirements. The Civil Aviation Administration of China (CAAC) implements strict regulations for aircraft airworthiness and maintenance personnel. Major aviation hubs such as Beijing Capital International Airport and Shanghai Pudong International Airport manage high volumes of line maintenance for commercial jets.
Aircraft Line Maintenance Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large, integrated MROs, airline in-house maintenance divisions, and specialized component repair shops. Strategic archetypes include global service providers leveraging extensive networks and OEM relationships, and agile independent MROs focusing on cost-efficiency and niche services. Competitive moves involve strategic partnerships for technology adoption and geographic expansion into underserved markets. Portfolio diversification across aircraft types also remains a core strategy.
Global service providers leveraging extensive networks, such as Germany-based Lufthansa Technik AG, exemplify the integrated MRO model with deep OEM relationships. AAR Corporation, a US-based entity, represents a distinct value proposition through its integrated parts supply and logistics network, emphasizing operational efficiency. Singapore-headquartered ST Engineering Aerospace occupies a position offering comprehensive nose-to-tail services across a wide array of commercial and military aircraft platforms, securing diverse customer types. These entities collectively underscore the market's reliance on established expertise and broad service capabilities.
| Leading Market Players |
|---|
| Air France Industries KLM Engineering & Maintenance |
| AAR Corporation |
| Lufthansa Technik AG |
| Ameco |
| SR Technics |
| Delta TechOps |
| ST Engineering Aerospace |
| ANA Line Maintenance Technics Co., Ltd. |
| HAECO Group |
| Others |
Cost & Logistics Intelligence
Dubai's expanding MRO facilities, driven by significant investment, directly influence pricing power for specialized line maintenance services across the Middle East. This regional capacity shapes both service availability and cost structures for airlines operating in the area.
Pricing Analysis
Contract-based long-term agreements dominate pricing across the Aircraft Line Maintenance Market. Pricing stratifies across premium, standard, and economy tiers, influenced by the certification level of MRO providers and the volume scale of contracted services. Pricing softness affects routine inspections due to increased competition from smaller independent MROs. Commercial Airlines exhibit the highest price sensitivity, while government operators prioritize reliability over cost.
Supply Chain Analysis
Air France Industries KLM Engineering & Maintenance and Lufthansa Technik AG hold significant capacity for complex engine and airframe components. Geographic supply concentration for critical spare parts centers in the United States and Germany. The market relies on a complex global network of certified component manufacturers and logistics providers. Spare parts logistics, particularly long lead times for proprietary components, pose a structural risk. Distribution runs through a blend of direct OEM channels and third-party MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Line Maintenance Market is entering a cyclical recovery phase, driven by the rebound in global air travel demand post-pandemic. This resurgence creates significant opportunities for strategic positioning across the value chain.
For Market Incumbents: Insulate core revenue streams by deepening vertical integration into component manufacturing for new-generation aircraft. This counters the threat of rising spare parts costs and supply chain disruptions. Expand specialized technician training programs for avionics to maintain service quality. Invest in digital twin technology to enhance predictive maintenance capabilities.
For New Entrants and Emerging Players: Establish a beachhead in emerging markets like Southeast Asia by offering cost-effective line maintenance for regional jets. The most penetrable segment lies in supporting growing low-cost carriers with flexible, on-demand services. Focus on digital-first solutions, leveraging augmented reality for remote assistance, to differentiate from established players.
For Investors and Strategic Acquirers: Long-term, this sits as a specialized infrastructure play because air travel remains a fundamental global connector. Acquisition targets should focus on mid-sized MROs with strong capabilities in avionics or engine services, particularly those in strategic growth geographies. The signal to watch is the sustained increase in new aircraft orders, indicating future maintenance demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into Southeast Asia | Secures new customer bases in a rapidly growing aviation market. |
| Investment in Predictive Maintenance Platforms | Reduces aircraft-on-ground time and optimizes operational efficiency for airlines. |
| Advanced Avionics Technician Training Programs | Addresses the critical skills gap for servicing modern, software-intensive aircraft. |
| Development of Sustainable Aviation Fuel (SAF) Protocols | Positions MROs to support industry decarbonization mandates and new engine types. |
| Strategic Partnerships with OEM Component Suppliers | Mitigates spare parts logistics risks and ensures access to certified parts. |
Research Approach
Initial hypotheses were tested against primary input from airline maintenance directors, MRO operations managers, OEM service representatives, and aviation regulatory bodies, and refined through iterative analysis. This involved in-depth interviews with key industry stakeholders, complemented by extensive secondary research. Secondary sources included FAA and EASA reports, ICAO statistics, airline fleet data, and MRO financial statements, all contributing to a robust bottom-up and top-down triangulation.
The analytical framework balanced demand-side dynamics with supply-side capabilities across the analysis window. Segmentation dimensions modeled included service type, maintenance provider, aircraft type, customer type, and regional MRO hub capacity. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected market shifts, incorporating industry-specific forecast inputs such as global passenger traffic forecasts and cargo volume projections.
Sensitivities concentrate around geopolitical events impacting air travel, new regulatory mandates for maintenance, and significant shifts in fuel prices. Forecasts reflect assumptions regarding these external factors and their potential influence on market trajectories. Quarterly review of airline fleet utilization and MRO contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market