
 Aircraft Auxiliary Power Unit Gearbox Market | 2026-2036
Aircraft Auxiliary Power Unit Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Auxiliary Power Unit Gearbox Market Analysis
Defense procurement offices and commercial fleet managers is redrawing the buyer landscape for APU gearboxes as military sustainment budgets expand faster than commercial OEM order books. Safran leverages its integrated propulsion systems portfolio to bundle gearbox offerings with full APU packages. United Technologies anchors North American supply through its Pratt & Whitney Canada division, which dominates regional turboprop auxiliary power applications. Liebherr competes on precision gear grinding capacity, sustaining long-term contracts with European airframers through captive aerospace manufacturing in Germany and Switzerland.
An aircraft auxiliary power unit gearbox transmits rotational energy from a small gas turbine or electric motor to drive aircraft systems including electrical generators, hydraulic pumps, and air conditioning compressors when main engines are offline. These gearboxes typically operate at input speeds exceeding 40,000 RPM and require case-hardened alloy steel gearing with surface fatigue ratings above 1,500 MPa to withstand thermal cycling and torsional vibration loads inherent to auxiliary turbine operation. Turbocharged product configurations lead current production volumes due to their established integration with conventional gas turbine APUs, while electric and hybrid architectures represent the fastest-growing segment as airframers pursue more electric aircraft initiatives that eliminate pneumatic bleed systems. Commercial aviation applications command the largest installed base, though military aviation and helicopter segments concentrate higher-margin aftermarket demand through specialized overhaul protocols and shorter replacement cycles.
FAA airworthiness standards under 14 CFR Part 33 govern APU gearbox certification in the United States, while EASA CS-E requirements shape European market access through comparable endurance and containment testing mandates. The EPA's evolving aircraft engine emission regulations indirectly influence gearbox design by driving APU efficiency improvements that require optimized speed reduction ratios and reduced mechanical losses. Stakeholders must monitor how emerging FAA electrification guidance and EASA more-electric aircraft certification pathways reshape qualification requirements for non-traditional hybrid-electric gearbox architectures.
Market Dynamics
FAA airworthiness directives on APU containment are forcing suppliers to redesign case-hardened alloy steel gearing with enhanced surface fatigue ratings, compressing development cycles while military sustainment budgets expand procurement velocity.
Growth Catalysts
- 14 CFR Part 33 containment mandates:FAA tightening of debris shielding requirements drives replacement demand for legacy gearbox installations across narrow-body retrofit programs.
- More-electric aircraft architectures:Airframers eliminating pneumatic bleed systems accelerate procurement of optimized speed reduction ratios for hybrid-electric auxiliary power configurations.
- Domestic MRO network expansion:United States maintenance facility buildouts concentrate gearbox overhaul demand near OEM final assembly clusters.
Market Restraints
- Case-hardened alloy steel supply concentration:Specialty steel mills in Germany and Japan control premium aerospace-grade material flows, creating input cost volatility.
- EASA CS-E endurance testing duration:European certification timelines extend 18-24 months for new gearbox architectures, freezing design capital.
- Electric motor direct-drive substitution:Elimination of mechanical speed reduction in fully electric APUs threatens traditional gearbox volumes in regional turboprop segments.
Strategic Opportunities
- Helicopter specialized overhaul protocols:Military rotorcraft operators require shorter replacement cycles than fixed-wing fleets, creating aftermarket margin expansion.
- EPA emission regulation tailwinds:APU efficiency improvements mandated under evolving aircraft engine standards reward optimized mechanical loss reduction.
- Hybrid-electric certification pathways:Emerging FAA electrification guidance opens qualification routes for non-traditional gearbox architectures serving more-electric initiatives.
Industry Challenges
- Precision gear grinding talent scarcity:Captive aerospace manufacturing in Switzerland and Germany faces machinist pipeline gaps for case-hardened surface finishing.
- Torsional vibration load simulation capex:Thermal cycling test rigs for input speeds exceeding 40,000 RPM require eight-figure facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Auxiliary Power Unit Gearbox Market |
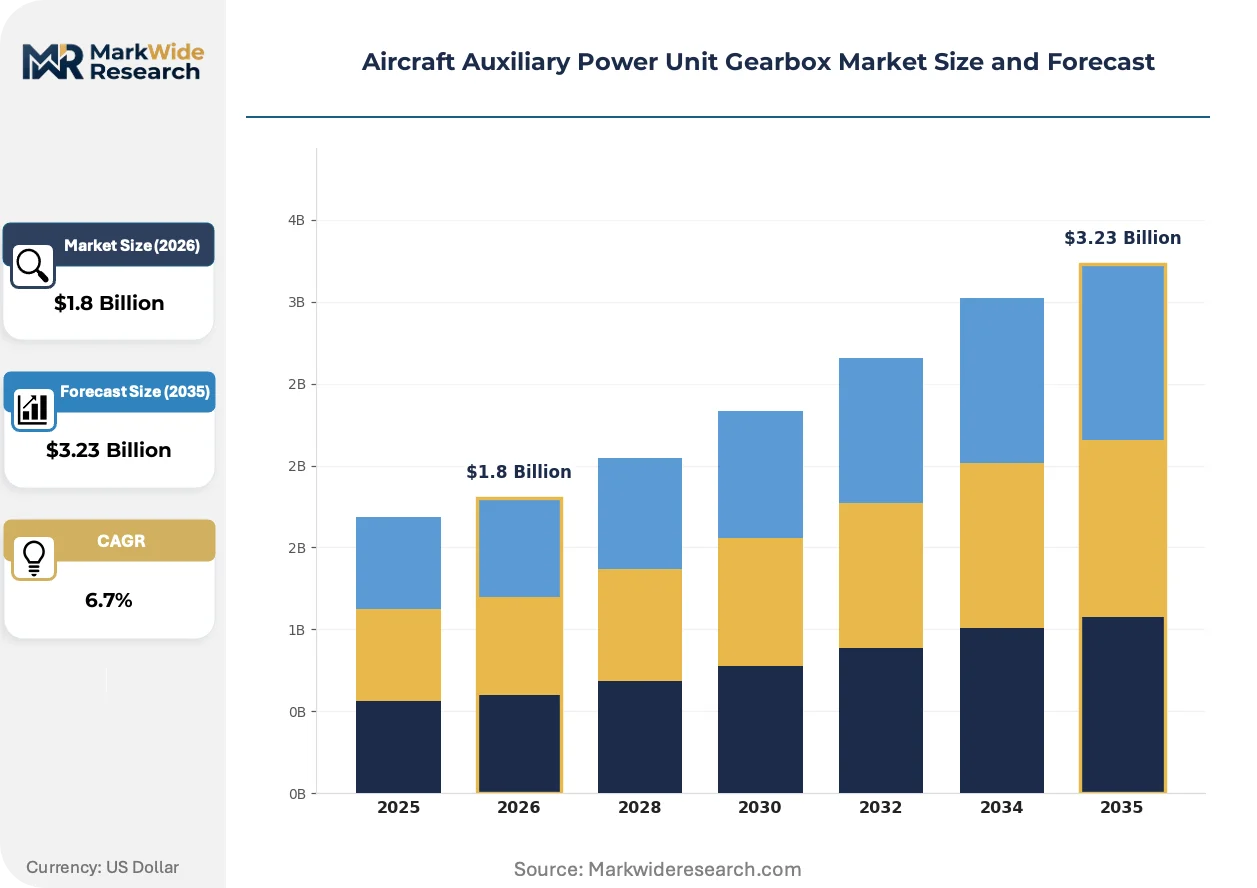
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbocharged, Gear Driven, Electric, Hybrid Application: Commercial Aviation, Military Aviation, Helicopters, UAVs Power Rating: Below 100 kW, 100-300 kW, 300-500 kW, Above 500 kW End User: OEMs, Maintenance Providers, Operators, Fleet Managers |
| Companies Covered | Safran, United Technologies, Liebherr, Northstar Aerospace, Triumph Group, SKF, CEF Industries, GE Aviation, Avion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Auxiliary Power Unit Gearbox Market Emerging Trajectories
Electrification of auxiliary power architectures is compressing traditional mechanical transmission designs while regulatory pressure on containment and emissions accelerates material and testing innovation cycles.
Additive manufacturing of case-hardened alloy steel gear blanks is miniaturizing prototype lead times for complex helical geometries. Tier-one suppliers deploy laser powder bed fusion for low-volume military helicopter gearboxes where traditional forging economics fail. This technology is miniaturizing the barrier between concept and airworthiness qualification.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent alternatives for corrosion protection. European suppliers face reformulation of established passivation chemistries while maintaining 1,500 MPa fatigue ratings. Commercial aviation applications absorb the bulk of compliance costs as military programs secure exemption pathways.
Fleet managers unbundle aftermarket service contracts from OEM gearbox supply agreements. Low-cost MRO providers in the United States capture overhaul volume through third-party DER repairs, displacing factory-authorized rebuild channels. Narrow-body operators lead this pattern as fuel hedging pressures compress maintenance discretionary spend.
Aircraft Auxiliary Power Unit Gearbox Market Segmentation
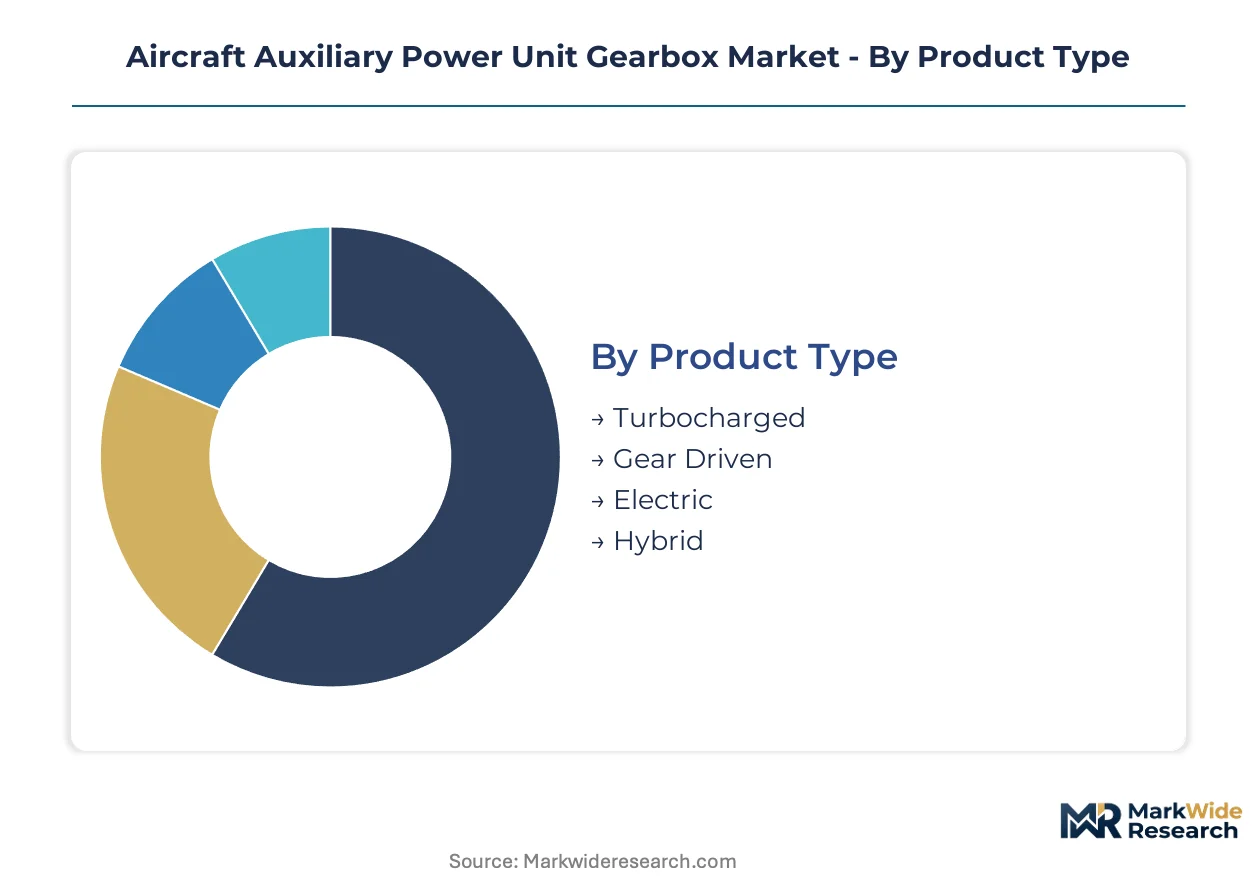
Segmentation in the APU gearbox market reveals divergent margin structures across propulsion architectures and customer types. Procurement patterns vary sharply between commercial fleet retrofits and military sustainment programs.
Product Type:
Margin pools concentrate in legacy turbocharged configurations while electric and hybrid architectures command development premiums.
- Turbocharged:Conventional gas turbine integration dominates current production volumes. Narrow-body retrofit programs in the United States drive replacement demand as FAA containment directives tighten.
- Electric:Direct-drive motor architectures eliminate mechanical reduction stages entirely. Regional turboprop segments face substitution pressure as airframers pursue more-electric aircraft initiatives.
- Gear Driven:Mechanical speed reduction systems serve conventional APU installations. Established supply chains in Germany and Switzerland maintain cost advantages through precision grinding capacity.
- Hybrid:Dual-mode architectures combining turbine and electric power sources represent the steepest expansion trajectory. Emerging FAA electrification guidance opens certification pathways for non-traditional gearbox designs.
Turbocharged holds installed capacity. Hybrid is rotating up the share rankings.
Application:
Volume concentrates in commercial fixed-wing fleets while margin density favors military rotorcraft with specialized overhaul protocols.
- Commercial Aviation:Narrow-body and wide-body fleets constitute the largest installed base. Domestic MRO network expansion in the United States concentrates overhaul demand near OEM assembly clusters.
- Military Aviation:Defense sustainment budgets expand procurement velocity faster than commercial OEM order books. Shorter replacement cycles and specialized testing requirements protect aftermarket margins.
- Helicopters:Military rotorcraft operators demand higher surface fatigue ratings for torsional vibration loads. Case-hardened alloy steel gearing with 1,500 MPa ratings commands premium positioning.
- UAVs:Unmanned platforms favor compact electric architectures with minimal mechanical complexity. Procurement volumes remain constrained by payload optimization priorities.
Commercial Aviation anchors volume throughput. Military Aviation is climbing the fastest on margin contribution.
Power Rating:
Mid-range ratings capture the bulk of narrow-body and regional turboprop demand while extreme ratings serve specialized military applications.
- 100-300 kW:Standard auxiliary power range for single-aisle commercial aircraft. Fleet managers in the United States prioritize this segment for retrofit compliance with 14 CFR Part 33 mandates.
- Below 100 kW:Compact units serve business aviation and light helicopter categories. Electric motor direct-drive substitution threatens mechanical gearbox volumes in this range.
- 300-500 kW:Wide-body and heavy military transport applications require enhanced thermal cycling resistance. EASA CS-E endurance testing extends certification timelines for new architectures.
- Above 500 kW:Specialized military and large commercial platforms demand custom-engineered solutions. Low production volumes sustain premium pricing through captive manufacturing relationships.
100-300 kW holds installed capacity. Below 100 kW is gaining share fastest through electrification displacement.
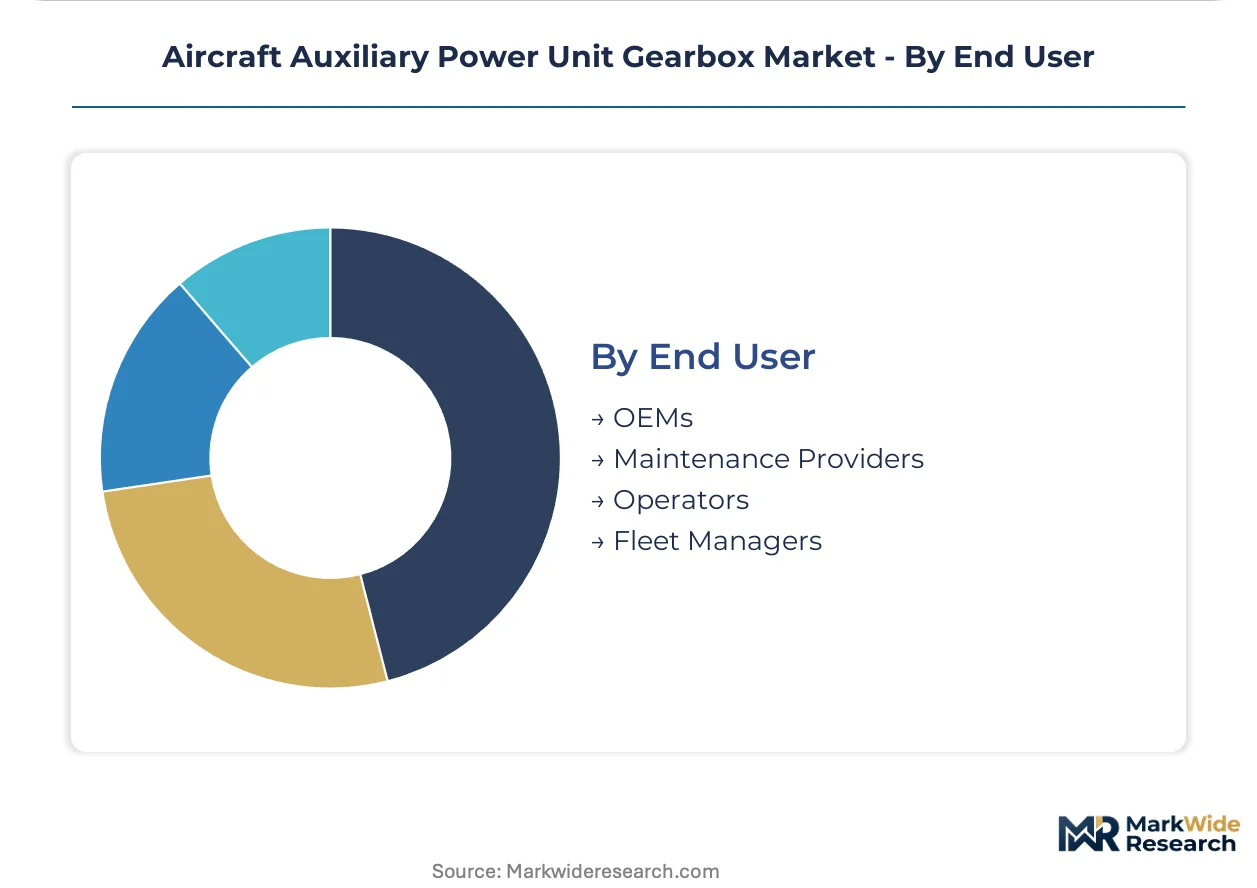
End User:
Procurement authority is fragmenting as fleet managers unbundle aftermarket contracts from OEM supply agreements.
- OEMs:Final assembly manufacturers integrate gearboxes into full APU packages. Safran and United Technologies dominate through bundled propulsion system offerings.
- Maintenance Providers:Third-party MRO facilities in the United States capture overhaul volume through DER repairs. Low-cost providers displace factory-authorized rebuild channels.
- Operators:Commercial airlines direct retrofit procurement for narrow-body compliance programs. Fuel hedging pressures compress maintenance discretionary spend.
- Fleet Managers:Consolidated leasing and management companies negotiate enterprise-scale supply agreements. Unbundling of service contracts accelerates price transparency.
OEMs hold installed capacity. Maintenance Providers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision gear manufacturers export case-hardened alloy steel components to United States-based MRO networks serving narrow-body retrofit programs. This transatlantic supply corridor channels European surface fatigue technology into North American airworthiness compliance workflows.
United States
Domestic MRO facility buildouts concentrate gearbox overhaul demand near Seattle, Wichita, and Charleston final assembly clusters. FAA airworthiness directives under 14 CFR Part 33 drive replacement procurement for legacy narrow-body installations. United Technologies anchors supply through Pratt & Whitney Canada division dominance in regional turboprop applications.
Germany
Captive aerospace manufacturing in Bavaria and Baden-Württemberg sustains long-term contracts with European airframers through precision gear grinding capacity. EASA CS-E endurance testing mandates shape certification timelines for new gearbox architectures. Stuttgart industrial corridor houses specialty steel mills controlling premium aerospace-grade material flows.
Switzerland
Liebherr competes on precision finishing capacity from Swiss manufacturing bases serving helicopter and military rotorcraft segments. REACH restrictions on hexavalent chromium surface treatments force torsent passivation chemistry reformulation. Zurich-Geneva aerospace cluster maintains captive supply relationships for 1,500 MPa fatigue-rated gearing.
Japan
Specialty alloy steel mills in Nagoya and Osaka control premium aerospace-grade input material flows, creating cost volatility for downstream fabricators. METI industrial standards influence thermal cycling test rig specifications for input speeds exceeding 40,000 RPM. Kansai manufacturing belt supplies case-hardened gear blanks to global tier-one integrators.
France
Safran leverages integrated propulsion systems portfolio from Toulouse and Paris-Saclay engineering centers to bundle gearbox offerings with full APU packages. ANSM oversight of aerospace manufacturing quality systems shapes supplier qualification pathways. Île-de-France aerospace cluster concentrates systems integration expertise for hybrid-electric auxiliary power architectures.
Aircraft Auxiliary Power Unit Gearbox Market Vendor Landscape
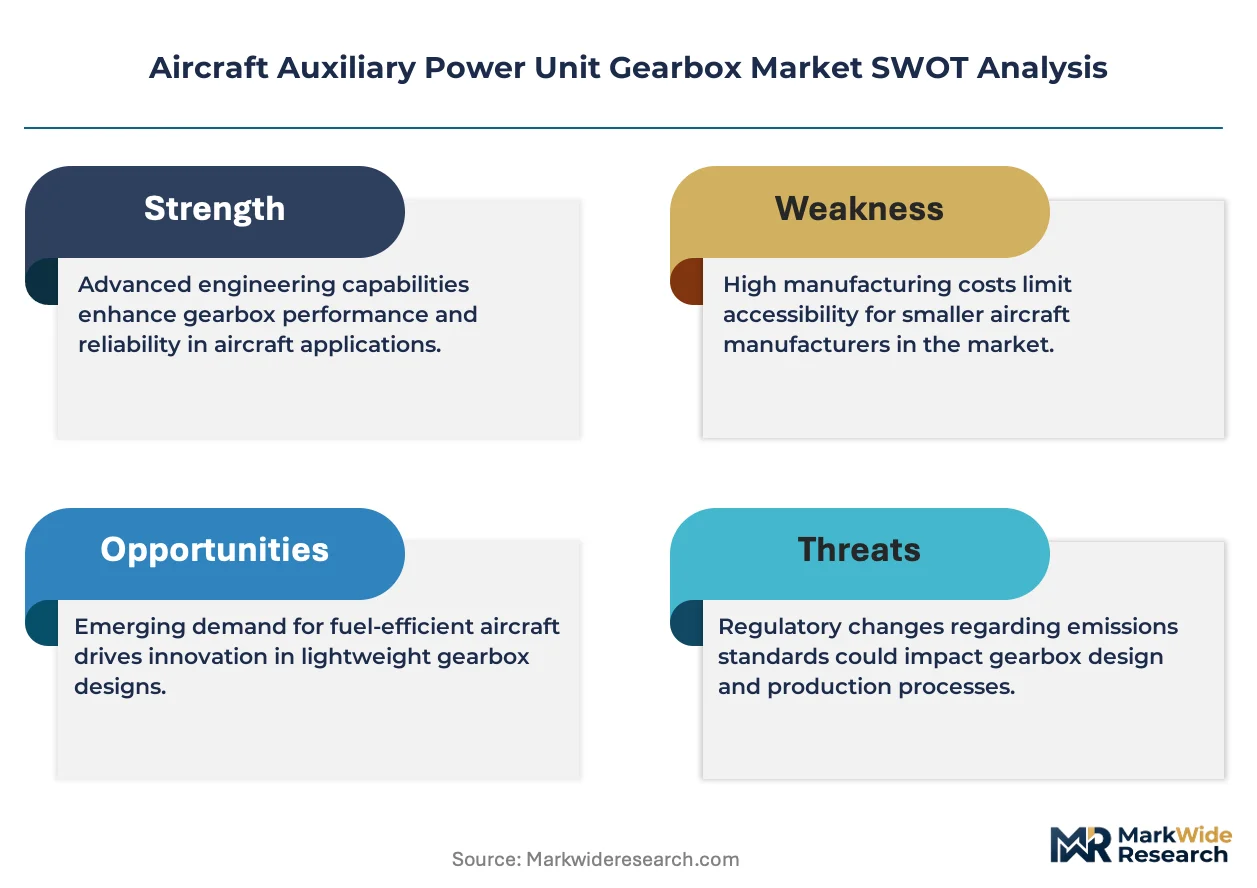
Listed leaders compete with private specialists across bundled propulsion versus component supply positioning. The supplier base concentrates around three structural tiers: integrated systems houses, precision manufacturing specialists, and aftermarket service providers. Strategic archetypes include full-package bundlers, captive precision grinders, and unbundled MRO challengers. Competitive moves center on backward integration into specialty steel supply and geographic co-location with OEM final assembly clusters.
Among the integrated systems tier, Safran and United Technologies exemplify full-package positioning through bundled APU and gearbox offerings. Liebherr occupies a precision manufacturing anchor role from European captive aerospace bases. These three names represent divergent competitive vectors: French propulsion integration, American regional turboprop dominance, and Swiss-German precision finishing specialization.
| Leading Market Players |
|---|
| Safran |
| United Technologies |
| Liebherr |
| Northstar Aerospace |
| Triumph Group |
| SKF |
| CEF Industries |
| GE Aviation |
| Avion Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-month certification timelines for new gearbox architectures compress procurement cycles and amplify pricing power for incumbent suppliers with established 14 CFR Part 33 approvals. This lead-time environment rewards captive precision grinding capacity in Germany and Switzerland while squeezing margins for second-tier fabricators dependent on spot-market specialty steel.
Pricing Analysis
Current-generation turbocharged configurations trade at standard contract rates while next-generation hybrid-electric architectures command development premiums reflecting EASA CS-E endurance testing costs. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified containment-compliant units from pre-directive legacy inventory and military-specified rotorcraft variants. Price differentiation hinges on surface fatigue certification tier and after-sales overhaul bundling. Cost compression in standard-tier commercial aviation retrofits is intensifying because fleet managers unbundle service contracts to capture third-party DER repair savings. Narrow-body operators exhibit highest price sensitivity; military helicopter programs show lowest sensitivity due to specialized overhaul protocol requirements.
Supply Chain Analysis
Specialty alloy steel mill concentration in Germany and Japan creates single-source vulnerability for case-hardened gear blank feedstock. Stuttgart and Nagoya industrial corridors control premium aerospace-grade material flows, while Swiss precision finishing centers in Zurich-Geneva depend on these inputs for 1,500 MPa fatigue-rated output. Raw material dependencies center on vacuum-arc-remelted alloy steel, trivalent chromium passivation chemistries, and thermal cycling test rig capacity. Distribution runs through captive aerospace manufacturing relationships rather than merchant spot markets, with tier-one integrators maintaining direct mill contracts and long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision gear grinding talent scarcity in Bavaria and Baden-Württemberg constrains output expansion for case-hardened surface finishing, creating asymmetric returns for suppliers with established machinist pipelines.
For Market Incumbents: Secure captive supply relationships with specialty steel mills in Stuttgart and Nagoya to insulate against input cost volatility from REACH-compliant chemistry reformulation. Add precision grinding capacity in Switzerland to capture military helicopter aftermarket margin expansion as torsional vibration load requirements tighten. Electric motor direct-drive substitution in regional turboprop segments threatens traditional gearbox volumes; respond with hybrid-electric certification investments under emerging FAA electrification guidance. For New Entrants and Emerging Players: Lead with additive manufacturing capabilities for low-volume military helicopter gearboxes where traditional forging economics fail and prototype lead times determine contract awards. Unbundled MRO providers in the United States represent the most penetrable channel, particularly for narrow-body retrofit compliance programs where fleet managers prioritize cost over factory-authorized rebuild channels. Target third-party DER repair qualification as the fastest path to overhaul revenue without OEM bundling constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized aerospace gear divisions lacking standalone certification infrastructure. Long-term viability over the projection horizon rests on positioning for hybrid-electric architecture transition rather than legacy turbocharged maintenance. Watch FAA electrification guidance publication as the inflection signal for non-traditional gearbox architecture qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Supply | Captive mill relationships in Stuttgart insulate against REACH-driven chemistry reformulation cost spikes. |
| Hybrid-Electric Certification Investment | FAA electrification guidance opens qualification routes for dual-mode architectures serving more-electric aircraft initiatives. |
| Precision Grinding Capacity Expansion | Bavaria and Baden-Württemberg machinist pipeline gaps create scarcity rents for established Swiss-German finishing centers. |
| Third-Party DER Repair Qualification | United States MRO network expansion captures narrow-body retrofit overhaul volume from unbundling fleet managers. |
| Additive Manufacturing Scale-Up | Laser powder bed fusion miniaturizes prototype lead times for complex helical geometries in military helicopter segments. |
Methodological Framework
A standing panel of APU systems engineers, MRO procurement directors, FAA certification specialists, and specialty steel mill technical sales managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with tier-one integrators and precision manufacturing specialists with secondary validation against FAA airworthiness directive filings, EASA CS-E certification databases, and METI industrial standard specifications. Bottom-up build from gearbox unit economics and top-down cross-check against APU propulsion system forecasts ensured triangulation integrity.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled product type, application, power rating, and end user dimensions alongside airworthiness certification tier. CAGRs derived from segment-level unit projections and average selling price trajectories, with hybrid-electric architecture penetration and military sustainment budget velocity as key forecast inputs.
Forecasts assume regulatory continuity in FAA 14 CFR Part 33 and EASA CS-E regimes; material policy shifts on containment or electrification would require re-modeling. Commodity price volatility in specialty alloy steel, machinist pipeline constraints in precision finishing centers, and electric motor substitution rates in regional turboprop segments represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aviation High Speed Motor Market