
 Aircraft Fluid Power Components Market | 2026-2036
Aircraft Fluid Power Components Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Fluid Power Components Market Analysis
Power-by-the-hour leasing and asset-light fleet management is reconfiguring how airlines procure fluid power systems, shifting capital burdens onto OEMs and tier-one integrators. Parker Hannifin Corporation leverages its aftermarket service networks to capture recurring revenue from these long-term contracts. Eaton Corporation anchors its position through backward integration into precision pump manufacturing. Safran competes by specializing in electromechanical actuation hybrids that reduce hydraulic dependency on next-generation narrowbody platforms.
Aircraft fluid power components encompass pumps, actuators, valves, and filters engineered to operate at pressures exceeding 3,000 psi while tolerating temperature swings from -65°F to 275°F, serving as the muscle layer for flight-critical mechanical systems. Aluminum and titanium material segments command premium positioning where weight reduction translates directly into fuel efficiency gains on long-haul platforms. The flight control application category sustains the deepest specification barriers due to fail-operate redundancy requirements, while landing gear systems occupy a more mature replacement cycle with predictable aftermarket timing.
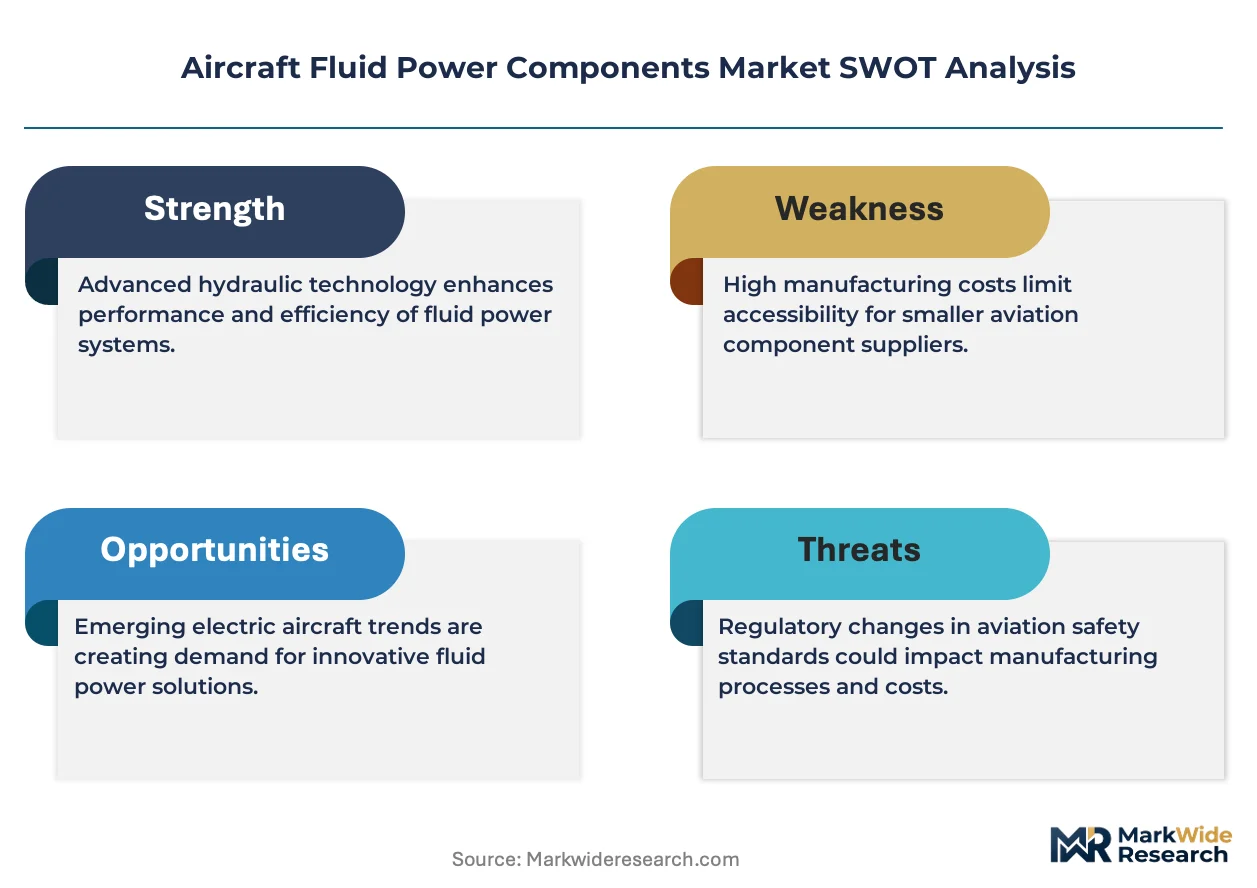
The FAA's Part 25 airworthiness standards and EASA's CS-25 certification framework jointly dictate hydraulic fluid compatibility, fire resistance, and fatigue testing protocols that OEMs must satisfy for market access. The EPA's emerging restrictions on phosphate ester hydraulic fluids are forcing material transitions that favor suppliers with active synthetic fluid R&D programs. Stakeholders must monitor how electrification of flight control surfaces reshapes the addressable hydraulic component envelope without assuming complete displacement timelines.
Market Dynamics
Electrification of flight control surfaces is compressing the addressable hydraulic envelope while simultaneously elevating performance specifications for remaining fluid power systems on hybrid architectures.
Growth Catalysts
- Military procurement waves:NATO-aligned defense budgets are expanding fleet modernization programs, driving sustained demand for high-pressure hydraulic actuators in tactical aircraft platforms.
- FAA Part 25 revisions:Updated airworthiness standards for hydraulic system redundancy are mandating component upgrades across certified commercial fleets, creating replacement pull-through.
- Power-by-the-hour contracts:Asset-light fleet management models are transferring component lifecycle responsibility to OEM service networks, embedding fluid power systems into long-term revenue streams.
Market Restraints
- Titanium input volatility:Aerospace-grade titanium sponge pricing swings directly compress margin structures for precision pump and actuator manufacturers.
- Supplier concentration in US defense industrial base:Lockheed Martin and Boeing supply chain lock-in limits tier-two component makers' pricing leverage and route-to-market flexibility.
- Electromechanical substitution:Electromechanical actuation hybrids are progressively displacing hydraulic dependency on next-generation narrowbody platforms, constraining long-term volume growth.
Strategic Opportunities
- Synthetic fluid R&D positioning:EPA restrictions on phosphate ester hydraulic fluids are creating competitive moats for suppliers with active synthetic formulation programs.
- Aftermarket service unbundling:Airlines are separating component maintenance from airframe contracts, opening direct supplier relationships for filter and seal replacement cycles.
- Electro-hydraulic convergence:Integration of smart sensors with traditional hydraulic circuits enables predictive maintenance offerings that command premium positioning.
Industry Challenges
- Specialized technician scarcity:Maintenance organizations face acute shortages of personnel certified to service 3,000+ psi hydraulic systems with fail-operate redundancy protocols.
- CS-25/FAA dual certification timelines:Parallel EASA and FAA validation processes for new hydraulic components extend time-to-revenue by 18-24 months.
- Legacy fleet integration friction:New lightweight aluminum-titanium alloys require compatibility verification against existing hydraulic fluid chemistries in aging aircraft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Fluid Power Components Market |
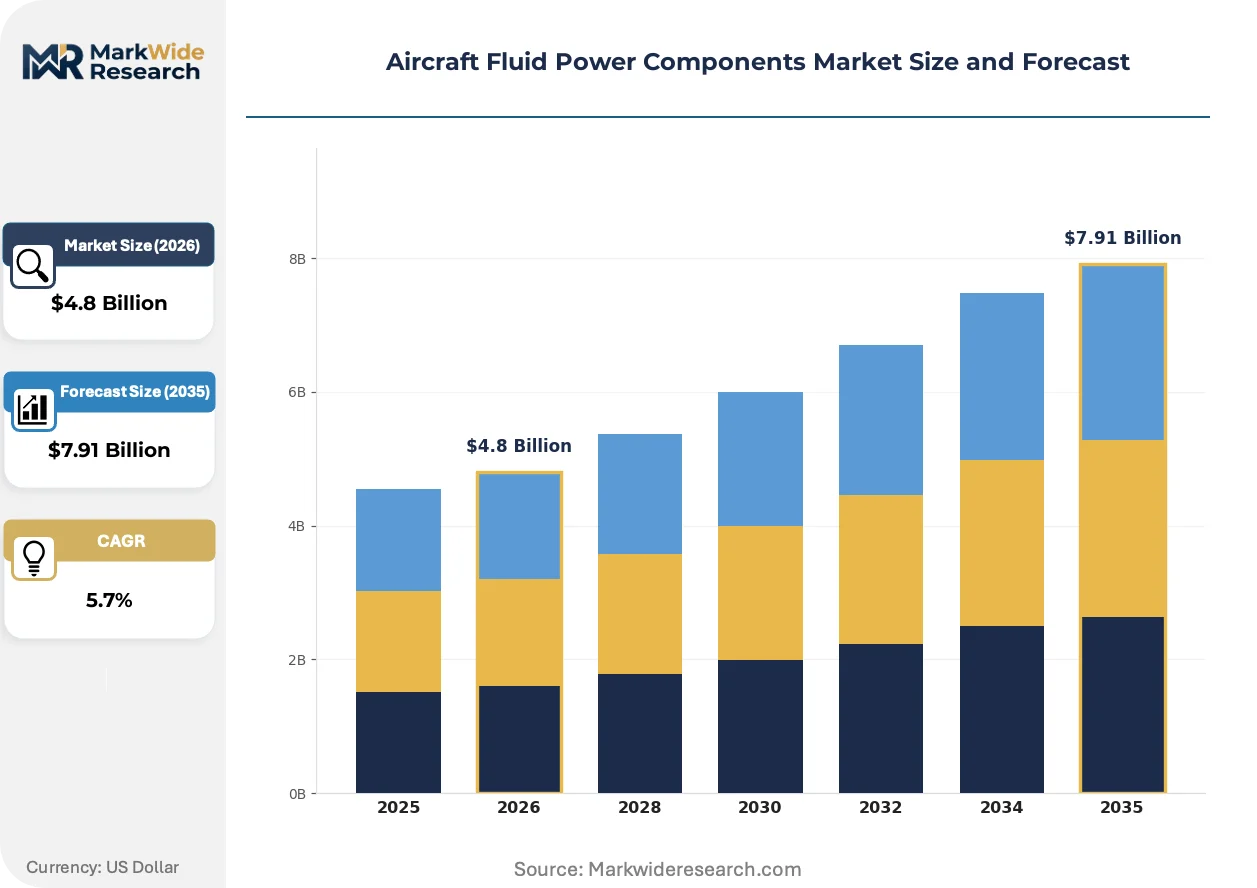
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Pumps, Actuators, Valves, Filters Application: Landing Gear, Flight Control, Engine Control, Fuel Systems End User: Commercial Aviation, Military Aviation, General Aviation, Cargo Material: Aluminum, Steel, Titanium, Composite |
| Companies Covered | Parker Hannifin Corporation, Eaton Corporation, Safran, Collins Aerospace, Woodward, CIRCOR International, Liebherr Group, Moog, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Fluid Power Components Market Emerging Trajectories
Active materials science breakthroughs and regulatory chemistry transitions are rewriting component specifications faster than traditional certification cycles can accommodate.
Additive manufacturing of titanium hydraulic manifolds is collapsing lead times for complex internal channel geometries while maintaining fatigue ratings equivalent to machined billet. Tier-one integrators are qualifying laser powder bed fusion for flight-critical pump housings on narrowbody programs. This process compression is enabling economic production of low-volume legacy spares without dedicated tooling investment.
REACH restrictions on fire-resistant hydraulic fluid formulations are forcing material transitions across European-registered fleets, with EASA CS-25 compliance deadlines accelerating supplier qualification timelines. The EPA's parallel scrutiny of phosphate ester chemistries is extending this pressure to US operators. Component manufacturers with captive synthetic fluid R&D are capturing specification-setting roles previously held by fluid specialists.
Power-by-the-hour leasing is restructuring airline capital deployment, transferring fluid power component ownership risk onto OEM balance sheets. Maintenance providers are unbundling hydraulic system servicing from airframe contracts to capture direct aftermarket relationships. This channel reconfiguration is most advanced in North American and Western European flag carrier fleets, where asset-light fleet management has achieved critical adoption mass.
Aircraft Fluid Power Components Market Segmentation
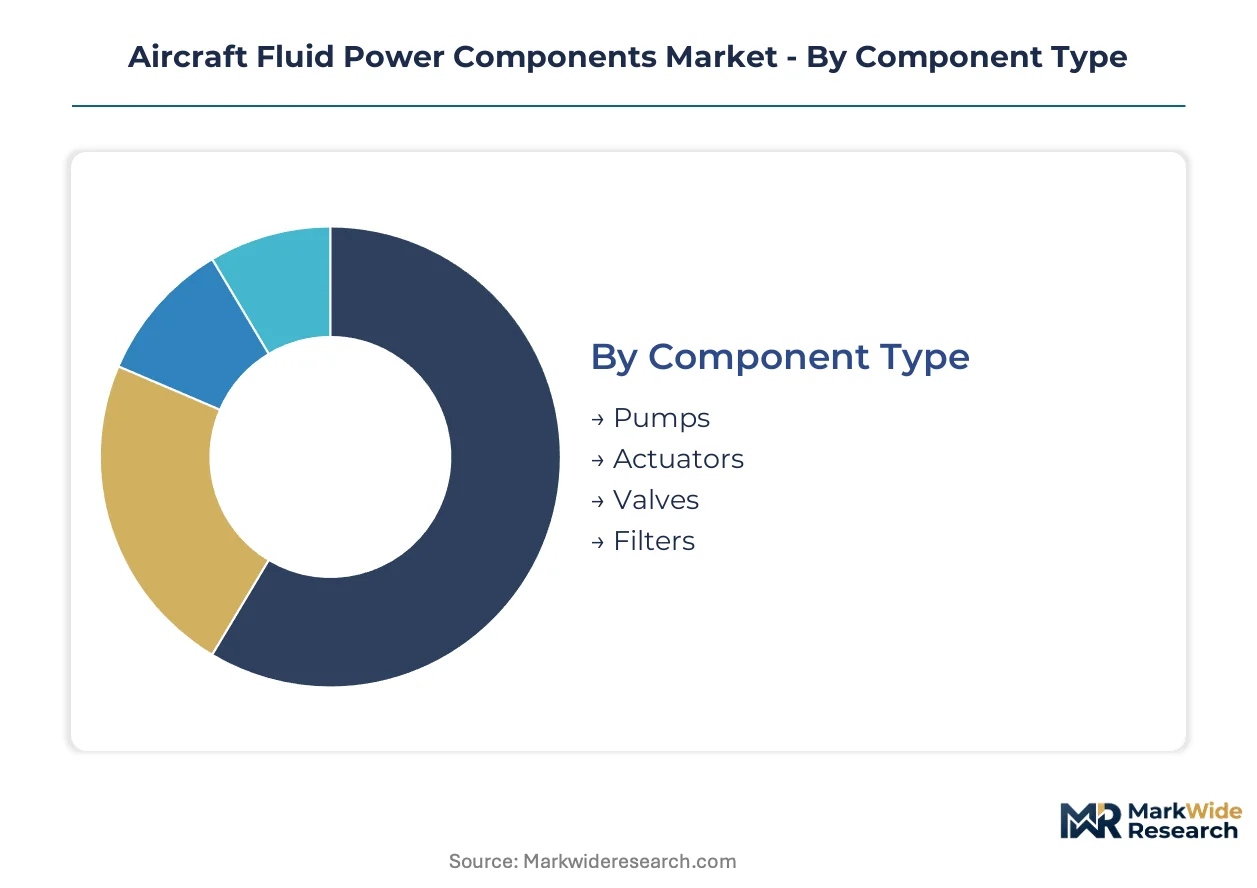
Fluid power component segmentation in aerospace tracks divergent certification burdens, material science trajectories, and fleet management models across defense and commercial channels. Each dimension carries distinct margin structures and aftermarket timing that reshape supplier portfolio priorities.
Component Type:
Mature hydraulic architectures dominate installed base volumes while electro-hydraulic hybrids redefine specification boundaries for new platform awards.
- Pumps:Precision-machined gear and piston configurations deliver 3,000+ psi output for primary flight control circuits. Demand clusters in United States defense industrial base programs where backward integration into pump manufacturing anchors supplier positioning against titanium input volatility.
- Actuators:Linear and rotary hydraulic actuators translate fluid pressure into mechanical force for flight surface deployment. Military aviation procurement across NATO-aligned fleets sustains order visibility for high-pressure tactical variants with fail-operate redundancy.
- Valves:Directional and pressure-control valves regulate flow distribution across distributed hydraulic networks.
- Filters:High-efficiency filtration elements protect precision clearances in pump and actuator circuits from contamination-induced wear.
Pumps handle the majority of throughput; actuators are gaining share fastest on military platform modernization cycles.
Application:
Specification intensity varies sharply between safety-critical flight systems and mature mechanical functions with predictable replacement intervals.
- Flight Control:Primary and secondary flight surface actuation demands fail-operate redundancy with triple-modular hydraulic channel architectures. FAA Part 25 airworthiness standards for hydraulic system redundancy drive replacement pull-through across certified commercial fleets.
- Landing Gear:Gear extension and braking systems operate at lower duty cycles with established aftermarket timing. United States and Western European flag carrier fleets concentrate power-by-the-hour contract demand for these replacement cycles.
- Engine Control:Fuel metering and variable geometry actuation integrates with full-authority digital engine control systems.
- Fuel Systems:Refueling and in-flight fuel transfer functions utilize lower-pressure hydraulic assistance.
Flight control commands the steepest specification barriers; landing gear offers the most predictable aftermarket revenue timing.
End User:
Procurement concentration and contract structure diverge between asset-light commercial operators and long-cycle defense programs.
- Commercial Aviation:Narrowbody and widebody fleet operators are unbundling hydraulic maintenance from airframe contracts to establish direct supplier relationships. Power-by-the-hour leasing transfers component lifecycle ownership onto OEM balance sheets across North American and Western European networks.
- Military Aviation:Tactical and strategic aircraft programs sustain multi-year procurement visibility through NATO defense budget expansion. Lockheed Martin and Boeing supply chain lock-in limits tier-two component pricing leverage.
- General Aviation:Business jet and turboprop operators demand cost-optimized maintenance solutions.
- Cargo:Freighter conversion programs and dedicated cargo fleets prioritize reliability-centered maintenance.
Commercial aviation generates the deepest aftermarket volume; military aviation offers the longest contract visibility.
Material:
Weight-performance tradeoffs and regulatory chemistry transitions are accelerating material substitution timelines.
- Titanium:Aerospace-grade titanium alloys deliver strength-to-weight ratios essential for high-pressure pump housings and actuator cylinders on long-haul platforms. Additive manufacturing of titanium hydraulic manifolds is collapsing lead times for complex internal geometries while maintaining fatigue ratings.
- Aluminum:Lightweight aluminum alloys serve moderate-pressure applications where cost efficiency outweighs extreme weight reduction. EPA restrictions on phosphate ester hydraulic fluids force compatibility verification against existing fluid chemistries in aging aluminum-component fleets.
- Steel:High-strength steel variants retain cost advantage for legacy fleet support and ground support equipment.
- Composite:Advanced polymer composites are penetrating non-structural housings and insulation applications.
Aluminum retains the broadest installed base; titanium is expanding most quickly on next-generation narrowbody specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 25 revisions and NATO defense budget expansions are redirecting procurement flows toward jurisdictions with established certification infrastructure and military aerospace industrial bases.
United States
Defense procurement through Lockheed Martin and Boeing supply chains sustains demand for high-pressure hydraulic actuators. The FAA's updated Part 25 airworthiness standards mandate component upgrades across certified commercial fleets. Wichita, Kansas and the Pacific Northwest aerospace corridor concentrate precision pump manufacturing and MRO facilities serving both military and commercial channels.
Germany
EASA CS-25 certification requirements and REACH fluid chemistry restrictions are accelerating supplier qualification timelines. The country's national aerospace regulator enforces dual certification protocols that extend time-to-revenue for new hydraulic components. Bavaria's aerospace cluster around Munich anchors precision actuator production for narrowbody and regional jet platforms.
France
Military aviation procurement through Dassault Aviation and Airbus Defence programs drives demand for fail-operate redundant hydraulic systems. EASA's CS-25 framework dictates hydraulic fluid compatibility standards for European-registered fleets. The Toulouse aerospace cluster specializes in electromechanical actuation hybrids that reduce hydraulic dependency on next-generation platforms.
United Kingdom
NATO-aligned defense modernization and power-by-the-hour fleet management adoption concentrate aftermarket demand. The Civil Aviation Authority enforces hydraulic system redundancy standards aligned with FAA-EASA harmonization. The Midlands aerospace cluster around Birmingham and Derby houses precision filtration and valve manufacturing for legacy fleet support.
Japan
Commercial narrowbody production through Mitsubishi Heavy Industries and subcontractor networks sustains component demand. METI industrial policy supports precision manufacturing capabilities for high-pressure hydraulic circuits. The Nagoya aerospace corridor integrates fluid power systems into regional jet and turboprop platforms for Asia-Pacific operators.
Aircraft Fluid Power Components Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Consolidation around United States defense industrial base programs limits route-to-market flexibility for tier-two component manufacturers. Three archetypes dominate: full-system integrators with captive aftermarket networks, precision component specialists with backward integration into materials, and electromechanical hybrid developers. Competitive moves concentrate on M&A for certification portfolio expansion and strategic partnerships for synthetic fluid R&D positioning.
Within the full-system integrator tier, Parker Hannifin Corporation and Eaton Corporation exemplify channel control through aftermarket service networks. Safran occupies a position within the electromechanical convergence archetype, specializing in actuation hybrids that reshape hydraulic dependency on next-generation narrowbody platforms. These three anchors represent distinct strategic vectors: recurring revenue capture through long-term contracts, upstream control over precision manufacturing inputs, and technology transition positioning ahead of regulatory chemistry shifts.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Eaton Corporation |
| Safran |
| Collins Aerospace |
| Woodward |
| CIRCOR International |
| Liebherr Group |
| Moog |
| Raytheon Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Aerospace-grade titanium sponge concentration in Japan and Russia directly determines margin retention for precision pump and actuator manufacturers serving Lockheed Martin and Boeing supply chains. This upstream lock-in forces tier-two component makers to absorb volatility through long-term power-by-the-hour contracts that transfer ownership risk onto OEM balance sheets.
Pricing Analysis
Certification level creates the primary spread between FAA Part 25-compliant flight control components and standard landing gear replacements. Three-tier pricing structure across premium flight-critical, standard commercial, and economy legacy support segments reflects fail-operate redundancy requirements. Pricing pressure stems from electromechanical actuation hybrids displacing hydraulic volume on next-generation narrowbody platforms. Military aviation procurement shows lowest price sensitivity due to NATO defense budget expansion, while general aviation operators demand cost-optimized maintenance solutions.
Supply Chain Analysis
Aerospace-grade titanium sponge draws from Japan, Russia, and Kazakhstan, with precision machining capabilities concentrating in the United States, Germany, and Japan. High-strength aluminum alloys and synthetic hydraulic fluids represent secondary input dependencies. Single-source vulnerability around titanium sponge exposes pump housing manufacturers to commodity price swings. Distribution runs through OEM captive service networks and tier-one integrator channels rather than open aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-by-the-hour platform economics are reconfiguring component ownership toward recurring revenue models, with interoperability between predictive maintenance sensors and legacy hydraulic circuits emerging as the critical ecosystem battleground.
For Market Incumbents: Entrench aftermarket control by deepening backward integration into titanium additive manufacturing for flight-critical pump housings, insulating against raw material volatility. Lock in power-by-the-hour contract extensions with North American flag carriers before electromechanical substitution accelerates on next-generation narrowbody platforms. Prioritize synthetic fluid R&D positioning ahead of EPA phosphate ester restrictions. For New Entrants and Emerging Players: Japan's precision manufacturing subcontractor networks offer the most penetrable entry point for electro-hydraulic convergence technologies targeting regional jet platforms. Target aftermarket service unbundling opportunities where airlines are separating hydraulic maintenance from airframe contracts. Establish direct supplier relationships through predictive maintenance sensor integration rather than competing on component manufacturing scale. For Investors and Strategic Acquirers: Capital is best deployed toward specialists with captive synthetic fluid R&D and active additive manufacturing qualifications for titanium hydraulic manifolds. Long-term viability hinges on positioning ahead of regulatory chemistry transitions rather than volume exposure to hydraulic displacement. Monitor EASA CS-25 and FAA Part 25 harmonization timelines as inflection indicators for certification-intensive component categories.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Fluid R&D Investment | EPA phosphate ester restrictions favor suppliers with captive formulation programs. |
| Additive Manufacturing Qualification | Laser powder bed fusion for titanium manifolds collapses lead times for legacy spares. |
| Power-by-the-Hour Contract Expansion | North American flag carriers are transferring component lifecycle ownership onto OEM balance sheets. |
| Electro-Hydraulic Sensor Integration | Predictive maintenance offerings command premium positioning in unbundled aftermarket channels. |
| Dual Certification Portfolio Buildout | Parallel FAA-EASA validation extends time-to-revenue for new hydraulic components. |
Methodological Framework
A standing panel of hydraulic system design engineers, MRO facility directors, OEM procurement managers, and fleet technical advisors provided ongoing calibration against secondary validation. Primary interviews combined with FAA certification databases, EASA CS-25 submission records, defense procurement disclosures, and aerospace trade flow data. Bottom-up triangulation across component-level production estimates and top-down reconciliation against fleet installed base metrics anchored volume forecasts.
Scenario-bracketing around electrification adoption curves and military procurement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include component type, application criticality, end-user contract structure, and material specification tier. CAGRs derived from fleet replacement cycle timing, platform production rates, and aftermarket contract penetration curves. Titanium input pricing volatility and REACH fluid chemistry transitions represented key industry-specific forecast inputs.
Practitioners should monitor EPA synthetic fluid rulemaking and EASA CS-25 harmonization deadlines for early signals of specification disruption. Forecasts reflect assumptions about NATO defense budget continuity and narrowbody platform electrification timelines. Cross-checking against IATA fleet forecasts and DoD procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aerospace Electrical Inserts Market