
 Aerospace Battery Technology Market | 2026-2036
Aerospace Battery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Battery Technology Market Outlook
The EU Green Deal's Fit for 55 aviation decarbonization targets are shifting procurement criteria toward high-specific-energy storage systems across European aerospace OEMs and their tier suppliers. Saft Groupe S.A. leverages its Bordeaux manufacturing base to sustain long-cycle contracts with Airbus and Dassault Aviation. EaglePicher Technologies anchors the U.S. defense segment through captive qualification programs with the Department of Defense. EnerSys competes aggressively in the nickel-cadmium replacement market for regional turboprop fleets.
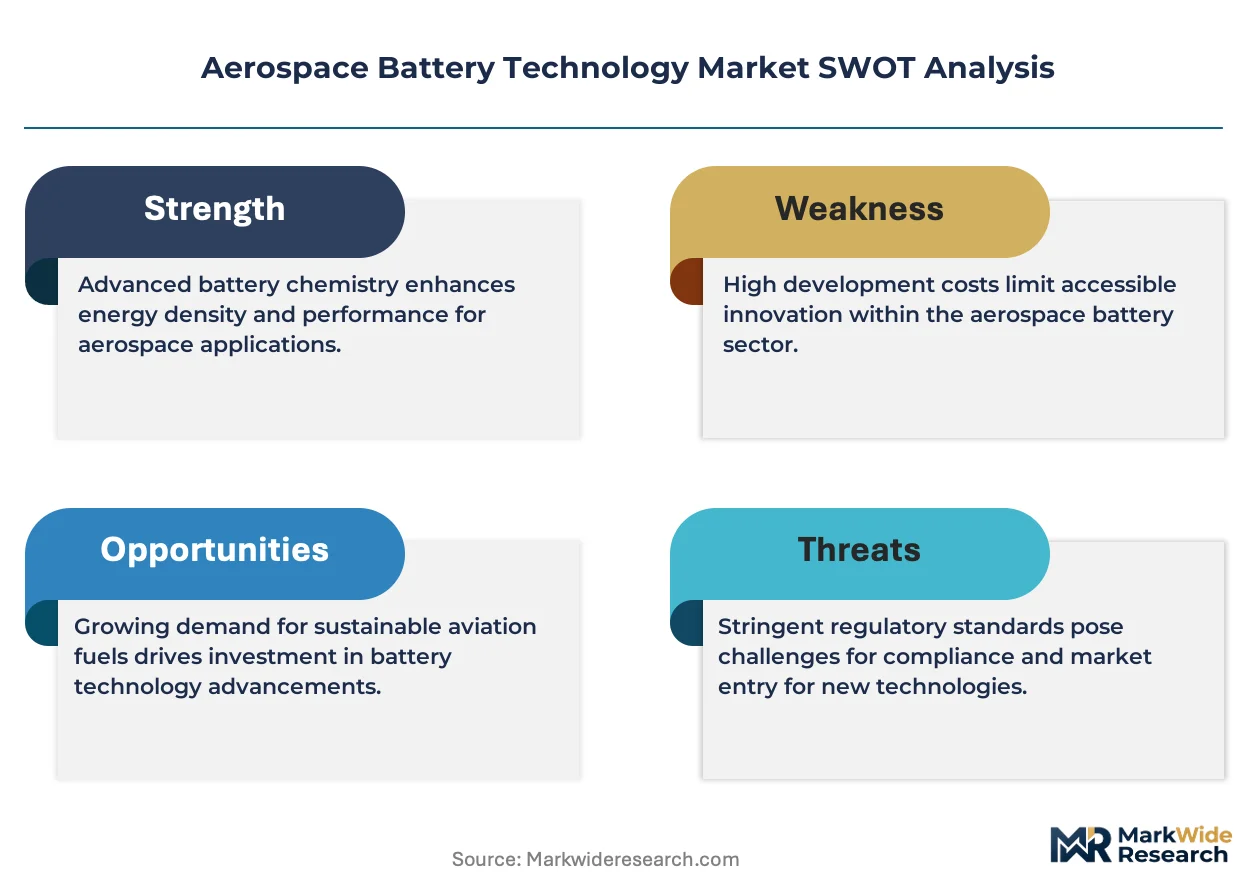
Aerospace battery technology encompasses electrochemical energy storage systems engineered to deliver specific energy exceeding 200 Wh/kg, operate across temperature extremes from minus 40 to plus 71 degrees Celsius, and withstand mechanical shock loads per RTCA DO-311A standards; these systems power engine starting, auxiliary power units, flight control actuation, and increasingly, hybrid-electric propulsion architectures. Li-Ion dominates installed base value due to its maturity in commercial aviation, while solid-state chemistry captures R&D margin pools as developers chase the 500 Wh/kg threshold required for thin-haul electric aircraft. Military aircraft application segments absorb premium pricing for crashworthy, battle-hardened configurations that civilian regulators do not require.
FAA Special Conditions, EASA Certification Memoranda, and China's GB/T standards for aviation lithium batteries collectively tighten thermal runaway containment mandates, forcing cell-to-pack architectural redesigns and inflating non-recurring engineering costs for market entrants. The U.S. Department of Transportation's Pipeline and Hazardous Materials Safety Administration coordinates with ICAO to harmonize shipping classification rules for prototype cells, creating transatlantic regulatory friction for developers with dual certification ambitions. Stakeholders must monitor which jurisdiction first certifies a solid-state battery for manned flight, as that regulatory precedent will reshape competitive positioning across OEM qualification programs.
Market Dynamics
Electric propulsion architectures in urban air mobility and next-generation defense platforms are compressing qualification timelines for lithium-sulfur and solid-state chemistries, forcing cell manufacturers to bridge the gap between laboratory performance and airworthiness certification.
Growth Catalysts
- Urban Air Mobility Electrification:Electric vertical take-off and landing platforms require battery systems exceeding 300 Wh/kg specific energy, pulling advanced lithium-sulfur formulations from research into active flight testing programs.
- FAA Special Conditions:The regulator's thermal runaway containment mandates for transport-category lithium-ion installations are accelerating architectural redesigns that favor next-generation solid-state architectures with inherent safety advantages.
- Department of Defense Vertical Lift Modernization:Next-generation rotorcraft programs are creating dual-use procurement channels that subsidize civilian certification costs for battle-hardened battery configurations.
Market Restraints
- Cathode Material Supply Concentration:Cobalt and nickel processing capacity concentrates in the Democratic Republic of Congo and Indonesia, exposing cell manufacturers to geopolitical disruption and ESG compliance costs.
- Non-Recurring Engineering Burden:RTCA DO-311A qualification testing for thermal runaway propagation consumes 18-24 months and seven-figure capital outlays, freezing out venture-stage entrants.
- Silicon Anode Degradation:Volume expansion during lithiation cycles limits silicon-anode lithium-ion cells to sub-500-cycle lifespans, disqualifying them from commercial aviation applications requiring 2,000+ cycles.
Strategic Opportunities
- Regional Turboprop Fleet Electrification:Nickel-cadmium replacement demand across ATR and Bombardier turboprop fleets offers a lower-certification-barrier entry point for lithium-ion system integrators.
- EU Green Deal Aviation Decarbonization:The Fit for 55 framework is mandating high-specific-energy storage procurement criteria across European aerospace OEMs and their tier-one suppliers.
- Solid-State Ceramic Electrolyte Convergence:Sulfide-based solid electrolytes paired with lithium-metal anodes are approaching the 500 Wh/kg threshold required for thin-haul electric aircraft with meaningful payload-range economics.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:The intersection of ionic conductivity engineering and flammability suppression requires rare dual-competency chemists, constraining R&D velocity at mid-tier cell developers.
- Legacy Aircraft Electrical Architecture Integration:28-volt DC and 115-volt AC bus standards in existing fleets force expensive power conversion hardware additions for lithium-ion retrofits, complicating value proposition articulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Battery Technology Market |
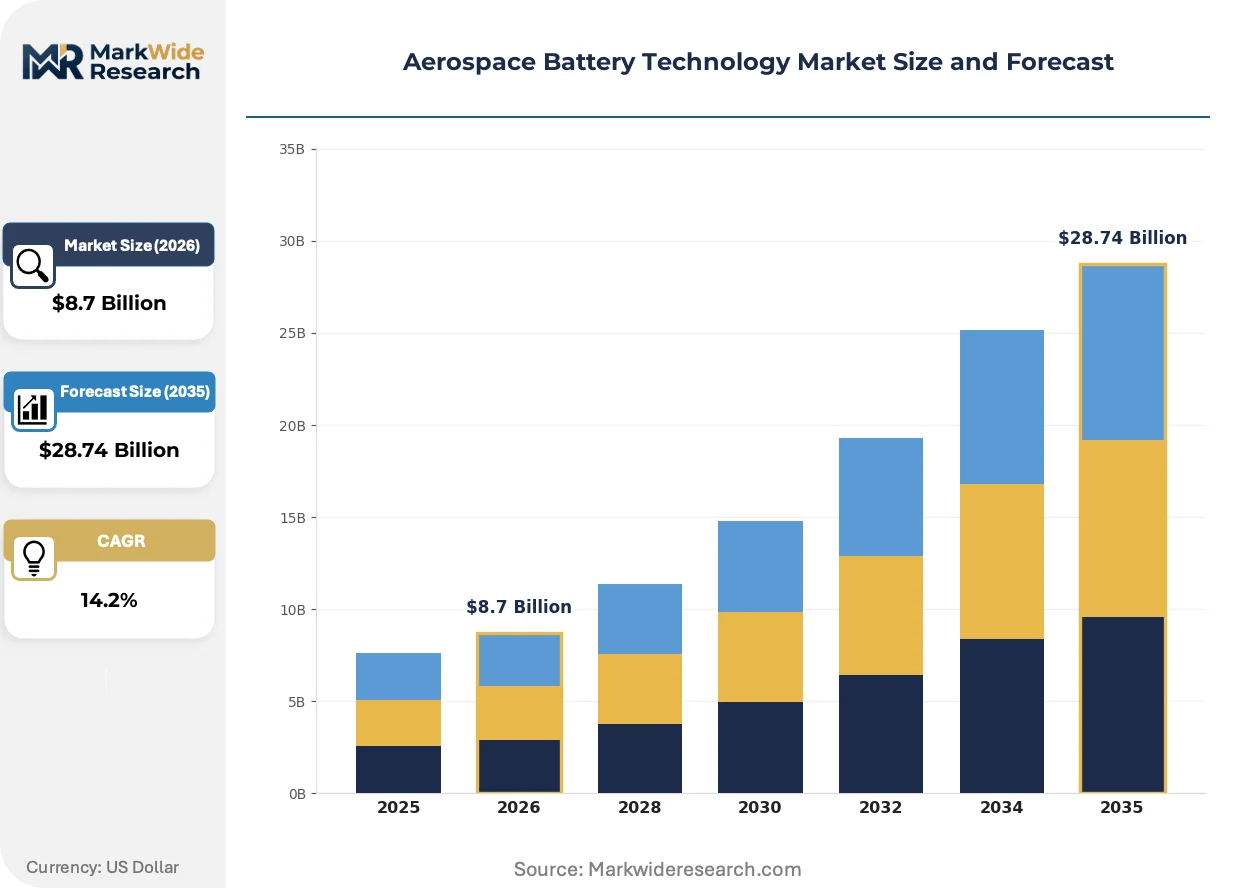
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-Ion, NiMH, Solid-State, Flow Batteries Application: Commercial Aircraft, Military Aircraft, Drones, Spacecraft Technology: Energy Density, Power Density, Charging Speed, Thermal Management End User: Aerospace OEMs, Defense Contractors, R&D Institutions, Airlines |
| Companies Covered | EnerSys, Saft Groupe S.A., EaglePicher Technologies, GS Yuasa Corporation, Concorde Battery Corporation, Teledyne Technologies Incorporated, Sion Power Corporation, Raytheon Technologies Corporation, A123 Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Battery Technology Market Strategic Shifts
Solid-state battery architectures are modularizing the aerospace energy storage supply chain, separating cell manufacturing from pack integration and enabling new entrants to specialize without full-stack capital requirements.
Lithium-metal anodes paired with sulfide ceramic electrolytes are modularizing how cell manufacturers approach energy density scaling. Urban air mobility developers in California and Texas are adopting these configurations for flight demonstrators ahead of full commercial certification. The technology is modularizing the traditional relationship between cell chemistry and system-level safety engineering, allowing thermal management to shift from active suppression to passive material properties.
EASA Certification Memoranda for aviation lithium batteries are tightening cell-to-pack containment mandates across European commercial aviation procurement. OEMs are redesigning battery management system architectures to satisfy propagating thermal runaway test protocols. Regional turboprop operators in Scandinavia and the Baltic states are accelerating retrofit timelines to preempt regulatory sunset dates for nickel-cadmium systems.
Defense procurement offices are unbundling battery system specification from platform prime contracts, creating direct purchasing relationships with cell manufacturers. This channel disintermediation is compressing qualification cycle visibility and forcing tier-one aerospace suppliers to compete on cell-level performance rather than system integration lock-in. The shift is most visible in Army Future Vertical Lift and Air Force Agility Prime programs, where battery developers now contract directly with program offices.
Aerospace Battery Technology Market Segmentation
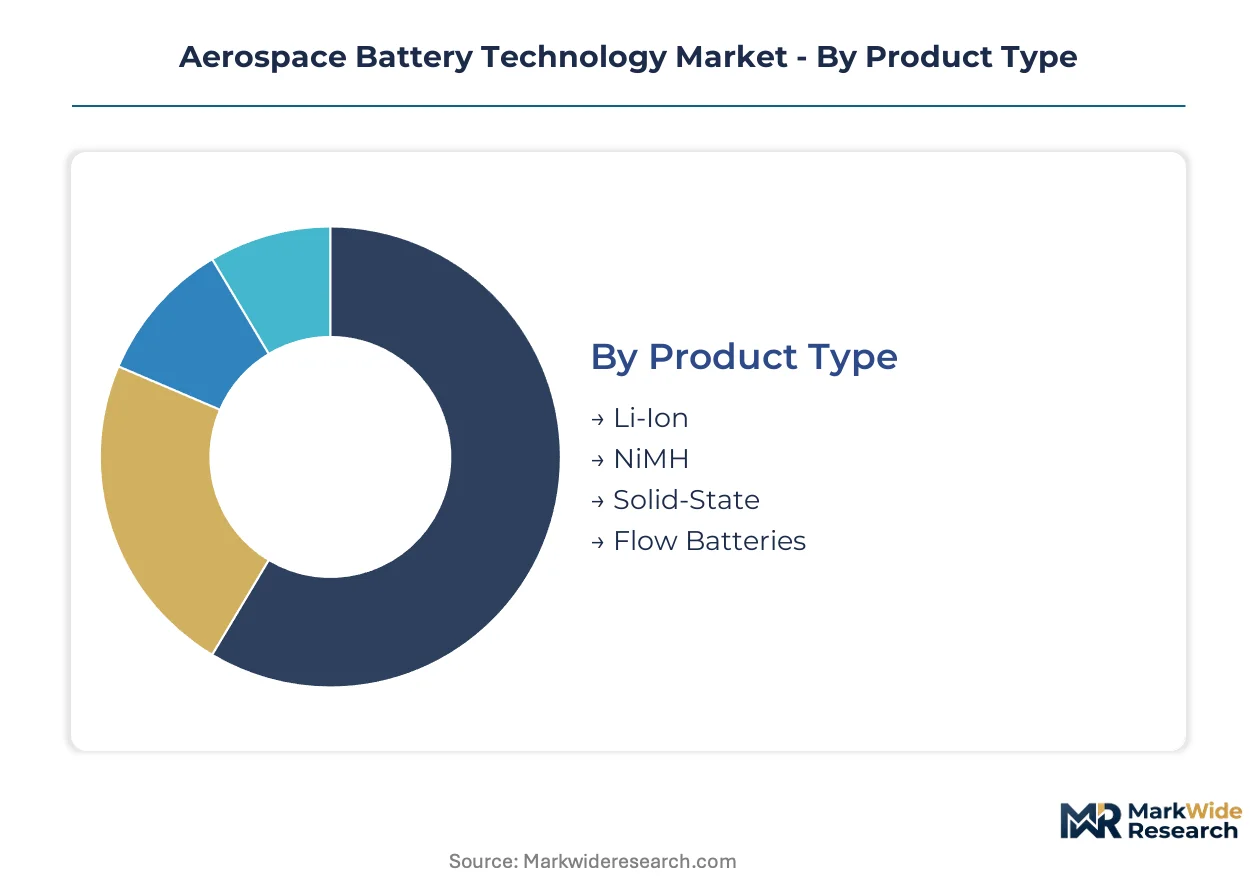
Aerospace battery procurement channels fragment sharply across certification regimes. RTCA DO-311A compliance for commercial aviation, MIL-STD-810G for defense platforms, and NASA-STD-4003 for spacecraft applications create divergent qualification pathways that reshape competitive positioning within each segment.
Product Type:
Certification burden varies dramatically by chemistry maturity, with established technologies requiring incremental recertification and emerging architectures facing de novo airworthiness validation.
- Li-Ion:Nickel-cobalt-aluminum and lithium-iron-phosphate cathodes dominate installed base value. FAA Special Conditions for thermal runaway containment have forced cell-to-pack architectural redesigns across Boeing and Airbus supply chains. Leading the category by volume: Li-Ion. Growing fastest: Solid-State.
- Solid-State:Sulfide ceramic electrolytes paired with lithium-metal anodes are approaching the 500 Wh/kg threshold required for thin-haul electric aircraft. EASA Certification Memoranda for inherent flame resistance are accelerating OEM qualification timelines for urban air mobility platforms in Germany and France.
- NiMH:Rare-earth metal hydride anodes persist in legacy military applications where thermal stability outweighs specific energy requirements.
- Flow Batteries:Vanadium redox systems remain laboratory-scale for spacecraft backup power due to mass penalties from liquid electrolyte reservoirs.
Margin concentration follows certification maturity: Li-Ion commands volume, Solid-State captures R&D premium.
Application:
Platform-specific duty cycles dictate cell selection, with engine starting loads, auxiliary power unit cycling, and propulsion continuous discharge imposing divergent degradation mechanisms.
- Commercial Aircraft:Narrow-body and wide-body fleets require 2,000+ cycle lifespans for auxiliary power unit starting. Nickel-cadmium replacement demand across ATR and Bombardier turboprop fleets offers lower-certification-barrier entry points for lithium-ion integrators. Dominant by fleet count: Commercial Aircraft. Steepest expansion trajectory: Drones.
- Drones:Electric vertical take-off and landing platforms require battery systems exceeding 300 Wh/kg specific energy, pulling advanced lithium-sulfur formulations from research into active flight testing programs in California and Texas.
- Military Aircraft:Crashworthy, battle-hardened configurations absorb premium pricing for mechanical shock tolerance per MIL-STD-810G that civilian regulators do not require.
- Spacecraft:NASA-STD-4003 qualification for vacuum thermal cycling and radiation tolerance limits qualified suppliers to heritage aerospace battery manufacturers.
Defense procurement offices are unbundling battery specifications from platform prime contracts, creating direct purchasing relationships with cell manufacturers.
Technology:
Performance metric prioritization shifts with application: energy density for range-extended platforms, power density for engine starting, thermal management for safety-critical installations.
- Energy Density:Gravimetric and volumetric metrics determine payload-range economics for electric propulsion architectures. Urban air mobility developers in the United States and Germany are specifying 300-400 Wh/kg cell-level targets for thin-haul certification.
- Thermal Management:Active liquid cooling versus passive phase-change materials represents a system-level architectural choice with cascading weight and reliability implications. Largest addressable spend: Thermal Management. Climbing fastest: Charging Speed.
- Power Density:High-rate discharge capability for flight control actuation and emergency power prioritizes electrode surface area over total capacity.
- Charging Speed:Fast-charge protocols for urban air mobility turnaround operations are stressing anode lithiation kinetics and accelerating silicon-anode degradation research.
System integrators are modularizing the traditional relationship between cell chemistry and thermal engineering, allowing passive material properties to substitute for active suppression hardware.
End User:
Procurement authority concentration varies: aerospace OEMs specify tier-one, defense contractors direct-buy for classified programs, airlines defer to lessor specifications.
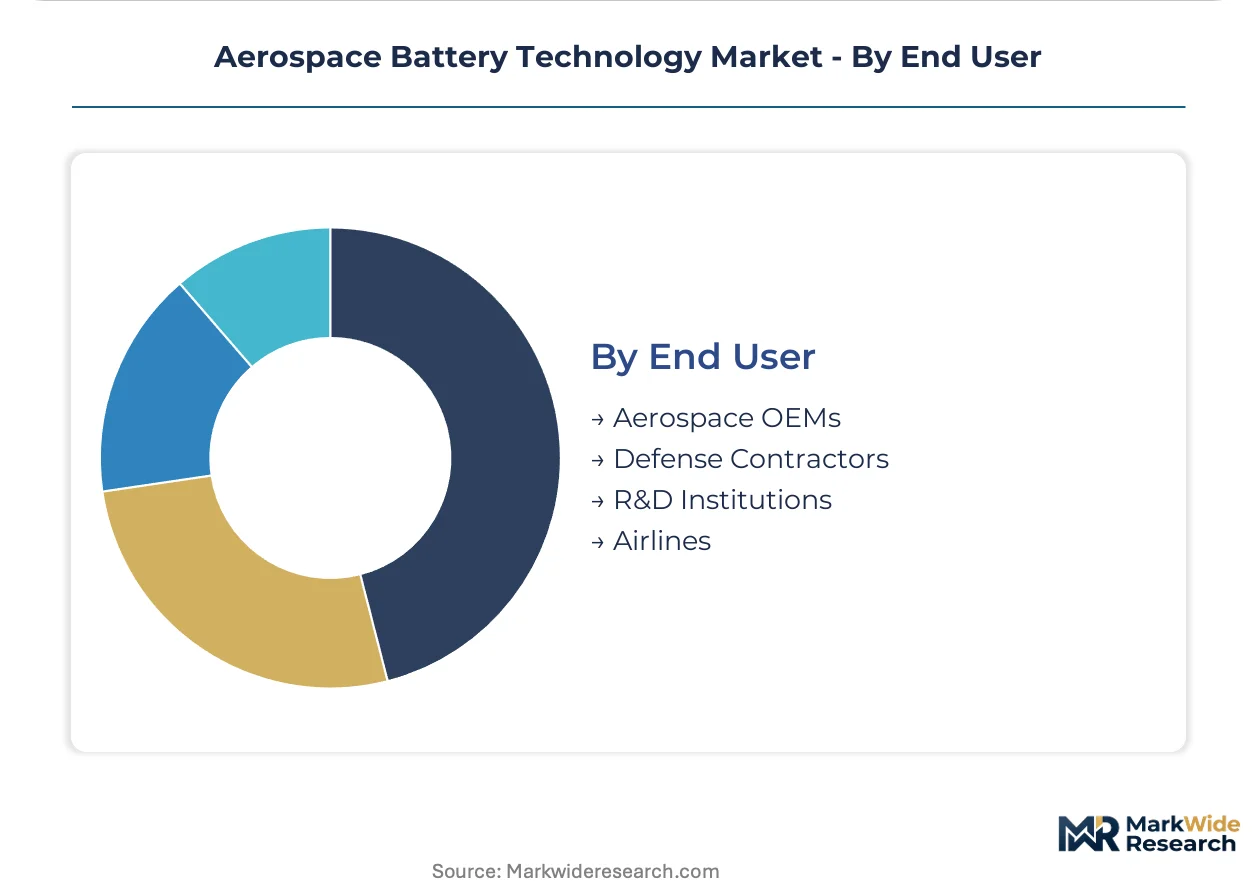
- Aerospace OEMs:Airbus and Boeing qualification programs impose 18-24 month RTCA DO-311A testing cycles that freeze out venture-stage cell developers. Highest procurement authority concentration: Aerospace OEMs. Gaining share fastest: Defense Contractors.
- Defense Contractors:Army Future Vertical Lift and Air Force Agility Prime programs are compressing qualification timelines and contracting directly with cell manufacturers rather than through system integrators.
- Airlines:Regional turboprop operators in Scandinavia and the Baltic states are accelerating retrofit timelines to preempt regulatory sunset dates for nickel-cadmium systems.
- R&D Institutions:NASA's Artemis program and Department of Energy laboratories are subsidizing solid-state ceramic electrolyte convergence through dual-use procurement channels.
Channel disintermediation is compressing qualification cycle visibility and forcing tier-one aerospace suppliers to compete on cell-level performance rather than system integration lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's urban air mobility corridor from San Francisco to Los Angeles hosts the densest cluster of electric vertical take-off and landing battery developers, with flight testing programs pulling advanced cell chemistries toward commercialization.
United States
NASA's Artemis program and the Department of Defense's next-generation vertical lift initiatives create dual-use procurement channels for high-specific-energy storage systems. FAA Special Conditions for lithium-ion thermal runaway containment force architectural redesigns across Boeing and Airbus supply chains. EaglePicher Technologies anchors defense segment qualification programs from its Joplin, Missouri manufacturing base.
Germany
EASA Certification Memoranda for aviation lithium batteries tighten cell-to-pack containment mandates across Airbus qualification programs. The EU Green Deal's Fit for 55 aviation decarbonization targets mandate high-specific-energy procurement criteria for European aerospace OEMs. Urban air mobility developers in Munich and Hamburg accelerate solid-state battery flight demonstrator timelines.
France
Saft Groupe S.A. leverages its Bordeaux manufacturing base to sustain long-cycle contracts with Airbus and Dassault Aviation. EASA regulatory harmonization with FAA thermal runaway standards accelerates OEM qualification timelines for next-generation chemistries. The Toulouse aerospace cluster concentrates battery management system redesign activity for commercial aviation applications.
Japan
GS Yuasa Corporation maintains heritage aerospace battery manufacturing relationships with domestic and export defense platforms. METI subsidizes solid-state ceramic electrolyte convergence through dual-use procurement channels linking commercial aviation and space applications. The Nagoya industrial corridor hosts concentrated electrode material research for lithium-metal anode configurations.
China
GB/T standards for aviation lithium batteries establish parallel certification pathways to FAA and EASA regimes, creating regulatory friction for developers with dual certification ambitions. The Civil Aviation Administration of China accelerates domestic urban air mobility platform approvals. Shenzhen and Chengdu clusters concentrate cell-to-pack integration capacity for electric propulsion systems.
Aerospace Battery Technology Market Competitive Environment
The competitive structure tilts toward defense-anchored heritage manufacturers with captive qualification programs. Tier-one aerospace suppliers face channel disintermediation as defense procurement offices unbundle battery specifications from platform prime contracts. Three archetypes dominate: legacy defense contractors with MIL-STD-810G heritage, commercial aviation specialists with RTCA DO-311A portfolios, and venture-backed solid-state developers chasing urban air mobility qualification. Capacity expansion and strategic partnerships represent the dominant competitive vectors as developers bridge laboratory performance to airworthiness certification.
Among heritage defense-anchored manufacturers, EaglePicher Technologies and Saft Groupe S.A. exemplify the qualification-intensive tier where long-cycle contracts with Department of Defense and European aerospace OEMs create defensive positioning. EnerSys occupies a position representing the nickel-cadmium replacement specialists competing aggressively in regional turboprop retrofit markets. These three entities collectively anchor the competitive spectrum from mature chemistry volume to next-generation architecture premium.
| Leading Market Players |
|---|
| EnerSys |
| Saft Groupe S.A. |
| EaglePicher Technologies |
| GS Yuasa Corporation |
| Concorde Battery Corporation |
| Teledyne Technologies Incorporated |
| Sion Power Corporation |
| Raytheon Technologies Corporation |
| A123 Systems LLC |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate benchmark indices from South American salt flats cascade through cathode precursor pricing tiers, compressing margins for cell manufacturers serving commercial aviation while elevating premium capture for solid-state developers with cobalt-free formulations.
Pricing Analysis
Certification-grade pricing anchors aerospace battery procurement, with RTCA DO-311A qualification status commanding substantial premiums over MIL-STD-810G military specifications. Three-tier pricing structure across premium, standard, and economy levels separates crashworthy defense configurations from regional turboprop retrofits and experimental urban air mobility prototypes. Pricing pressure stems from cathode material cost volatility in Indonesian nickel processing and Congolese cobalt supply chains. Regional turboprop operators exhibit highest price sensitivity due to thin margins on short-haul routes, while defense procurement offices absorb premium pricing for battle-hardened configurations.
Supply Chain Analysis
Regional distribution centers in Missouri, Bordeaux, and Nagoya anchor hub-and-spoke patterns for qualified cell delivery to aerospace OEM final assembly lines. Manufacturing concentration centers on China for cathode active material, South Korea for separator films, and Japan for electrolyte salts. Raw material dependencies draw from Chilean lithium brine, Australian spodumene, and Indonesian nickel laterite. Single-source vulnerability concentrates in sulfide ceramic electrolyte precursors where Japanese chemical houses maintain process exclusivity. Distribution runs through tier-one system integrators holding airworthiness delegation authority from FAA and EASA regulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where cathode precursor supply and pack-level airworthiness certification represent the decisive upstream and downstream levers. Players pursuing captive control over sulfide electrolyte synthesis or RTCA DO-311A testing infrastructure capture structural margin.
For Market Incumbents: Anticipate channel disintermediation by defense procurement offices contracting directly with cell manufacturers, eroding system integrator lock-in. Fortify position through backward integration into lithium-metal anode production and captive qualification laboratory capacity. Accelerate solid-state R&D to preempt venture-backed developers from achieving first-mover airworthiness certification. For New Entrants and Emerging Players: Regional turboprop nickel-cadmium replacement demand offers the most penetrable entry point with lower certification barriers than narrow-body commercial aviation. Urban air mobility battery developers in Texas and California present partnership opportunities for cell qualification flight testing. Pursue direct contracting relationships with Army Future Vertical Lift program offices rather than competing through established tier-one suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor solid-state electrolyte specialists with EASA pre-certification engagement in Germany and France. Five-to-ten year viability hinges on which jurisdiction first certifies lithium-metal anode configurations for manned flight. Monitor FAA Special Conditions revision timelines as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Supply | Captive nickel sulfate and lithium hydroxide supply insulates margin from Indonesian and Chilean commodity volatility. |
| RTCA DO-311A Qualification Laboratory Investment | In-house thermal runaway testing compresses 18-24 month certification cycles for urban air mobility customers. |
| Sulfide Ceramic Electrolyte Scale-Up Partnership | Joint development with Japanese chemical houses secures exclusive supply for 500 Wh/kg solid-state configurations. |
| Defense Procurement Channel Disintermediation | Direct Army Future Vertical Lift contracting bypasses tier-one system integrator margin extraction. |
| Regional Turboprop Retrofit Fleet Targeting | Nickel-cadmium replacement demand across ATR and Bombardier operators offers near-term revenue anchoring. |
Study Parameters
SEC 10-K filings, EASA certification databases, and Department of Defense contract award records formed the secondary backbone, cross-referenced with primary interviews with cell engineering directors, airworthiness qualification leads, defense procurement officers, and regional airline fleet managers. Bottom-up and top-down triangulation validated segment-level projections against OEM production forecasts and military platform development timelines.
Bottom-up modeling of cell-level shipments by chemistry and application converged with top-down aerospace electrification expenditure analysis across the projection horizon. Segmentation dimensions encompassed product type, platform application, performance technology, and end-user procurement authority. CAGRs derived from fitted growth curves against historical certification cycle durations and regulatory precedent timelines. NASA Artemis program procurement schedules and EU Green Deal aviation decarbonization mandates served as demand-side calibration inputs.
Revisions become necessary when solid-state airworthiness certification precedents emerge, cobalt supply disruptions from the Democratic Republic of Congo materialize, or FAA-EASA regulatory harmonization fractures. Forecasts reflect documented assumptions regarding qualification timeline compression and cathode material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Thrust Reverser Market