
 GCC General Aviation Market | 2026-2036
GCC General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
GCC General Aviation Market Foresight
Saudi Arabia's maintenance, repair, and overhaul capacity is decoupling from its historical dependence on European service networks. Textron Inc. leverages its King Air turboprop platform to anchor aftermarket revenue across the Gulf. Leonardo S.p.A. sustains helicopter dominance through its AW139 family, which occupies the offshore energy transport segment. Gulfstream Aerospace Corporation differentiates on ultra-long-range performance, positioning its G700 for Riyadh-Jeddah nonstop corporate missions.
General aviation encompasses all civil aviation operations excluding scheduled commercial airline services, typically involving aircraft below 19 passenger seats with maximum takeoff weights under 12,500 pounds for fixed-wing types. These aircraft serve executive transport, emergency medical evacuation, pilot certification, and geospatial data collection functions across dispersed desert and coastal terrains. Fixed-wing jets command premium pricing among corporate end users, while rotary-wing platforms generate recurring revenue through offshore oil-and-gas crew rotations. Charter flights and flight training represent the fastest-expanding service categories as Saudi Vision 2030 and Qatar's tourism diversification stimulate pilot pipeline investments.
The UAE's General Civil Aviation Authority enforces airworthiness directives aligned with EASA frameworks, while Saudi Arabia's GACA implements nationality-specific operational certificates for private operators. GCAA mandates on avionics modernization and GACA's emerging carbon-offset requirements for business aviation reshape fleet replacement timelines and import compliance costs. Stakeholders must monitor regulatory divergence between Emirates-level standards and emerging Saudi localization rules as fleet planning decisions lock in multi-year ownership structures.
Market Dynamics
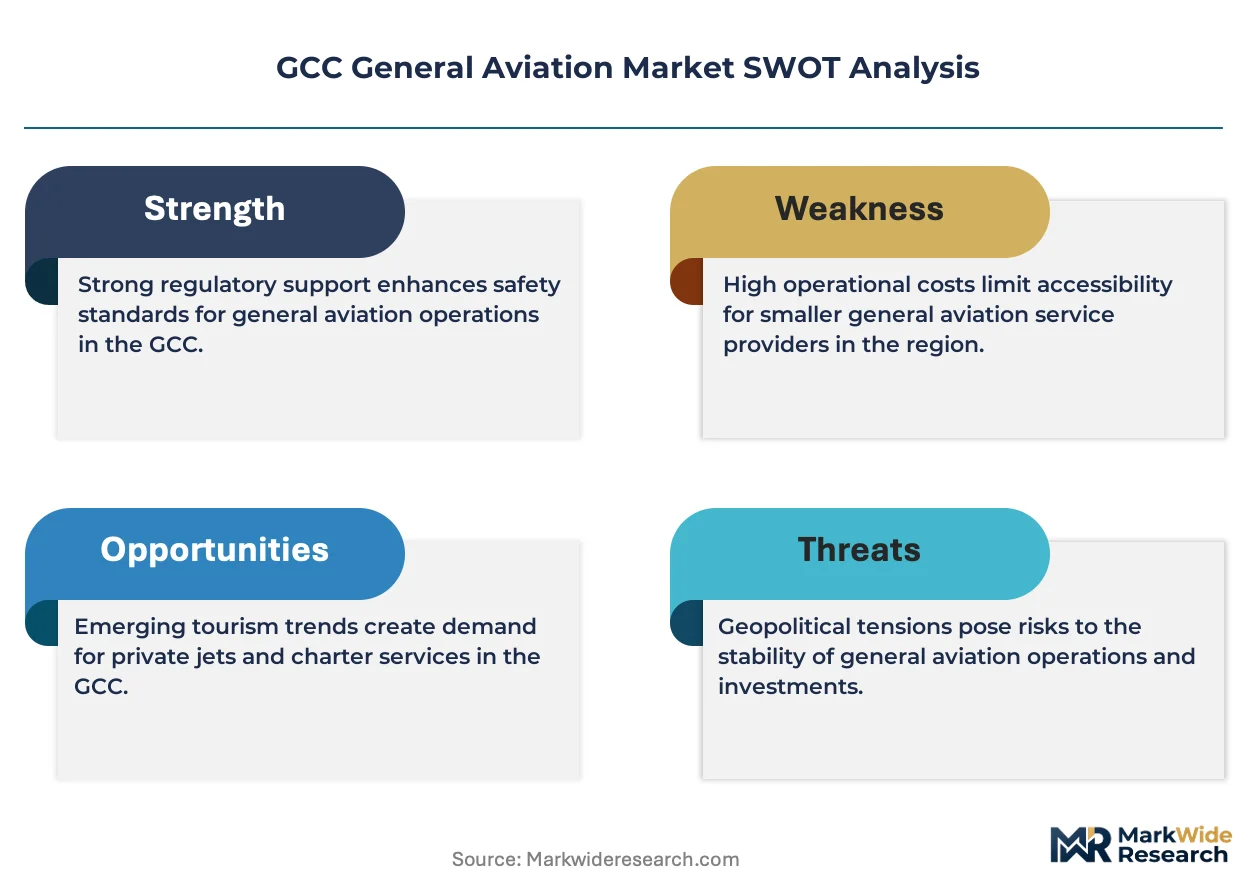
The GCC General Aviation Market is experiencing a structural recalibration as Saudi Arabia's GACA localization mandates and UAE's GCAA airworthiness directives simultaneously reshape fleet planning horizons. Operators now face divergent compliance timelines across Riyadh and Dubai hubs, forcing multi-jurisdictional certification strategies.
Growth Catalysts
- Offshore Energy Logistics:Helicopter crew rotations to Saudi Aramco and ADNOC platforms sustain rotary-wing utilization rates above fixed-wing averages. The AW139 family dominates this segment.
- Saudi Vision 2030 Tourism Diversification:Red Sea Project and NEOM developments are generating air taxi and scenic flight demand that did not exist five years prior.
- GCAA Avionics Modernization Mandates:The UAE regulator's phased ADS-B and FANS requirements are compressing legacy fleet replacement cycles among Dubai-based charter operators.
Market Restraints
- Jet A-1 Fuel Price Volatility:Gulf refiners' export parity pricing ties regional aviation fuel costs to Singapore spot markets, eroding fixed-cost budgeting precision for flight schools.
- European MRO Dependency:Saudi Arabia's limited engine overhaul capacity forces King Air and Phenom operators to ferry aircraft to Lufthansa Technik or Jet Aviation Basel, inflating downtime.
- Pilot Certification Bottlenecks:GACA's theoretical examination backlog and limited examiner pool constrain fleet expansion timelines for nascent charter entrants.
Strategic Opportunities
- Qatar's Untapped Corporate Aviation:Doha's FBO infrastructure remains underdeveloped relative to Dubai, creating first-mover positioning for fixed-base operators targeting FIFA World Cup legacy traffic.
- Electric Vertical Takeoff Convergence:Battery-electric airframes and autonomous flight management systems are converging to enable intra-city shuttle services between Riyadh's King Khalid Airport and the Diriyah Gate development.
- GACA Carbon Offset Incentives:Saudi Arabia's emerging business aviation sustainability credits reward early SAF adopters with accelerated operational certificate processing.
Industry Challenges
- Airframe Maintenance Engineer Scarcity:The GCC produces fewer than 200 licensed aircraft maintenance engineers annually, forcing operators to recruit from Philippines and Eastern European labor pools.
- Type Rating Certification Delays:GACA's validation of FAA and EASA pilot certificates requires 90-120 day administrative windows that disrupt seasonal charter staffing.
- Legacy Avionics Integration Friction:GCAA-mandated cockpit upgrades on pre-2010 King Air and Citation fleets demand custom STC approvals that Gulf-based MROs cannot yet execute in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC General Aviation Market |
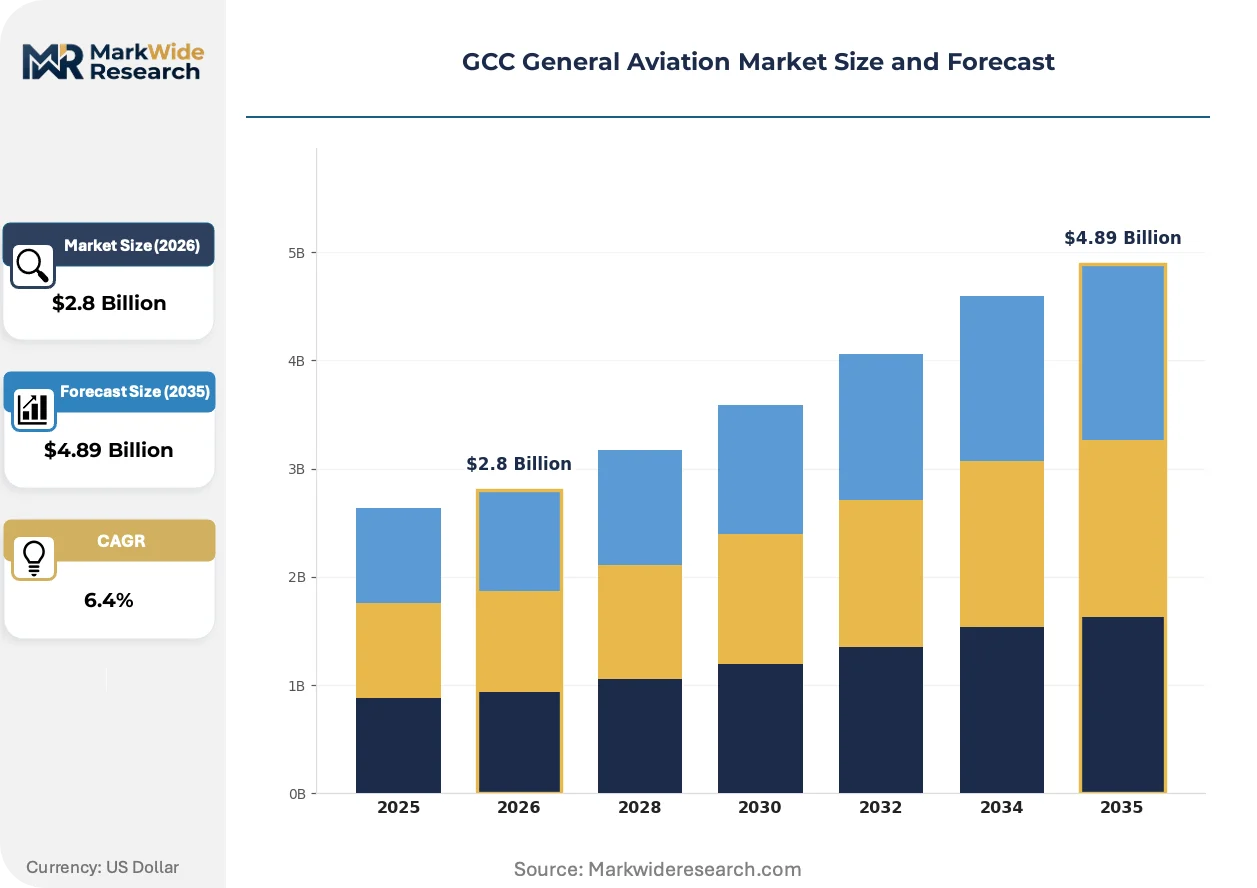
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fixed-Wing, Rotary-Wing, Turboprop, Jet, Amphibious Service Type: Charter Flights, Air Ambulance, Flight Training, Aerial Survey, Crop Dusting End User: Private Pilots, Corporate Executives, Government Agencies, Flight Schools, Tourism Operators Distribution Channel: Direct Sales, Brokers, Online Platforms, Aviation Events, Leasing Firms |
| Companies Covered | Textron Inc., Leonardo S.p.A., Gulfstream Aerospace Corporation, MD Helicopters LLC, Airbus SE, Bombardier Inc., Dassault Aviation SA, Diamond Aircraft Industries GmbH, Embraer S.A., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC General Aviation Market Shifts & Advancements
Avionics architecture is fragmenting from integrated proprietary systems toward interoperable component ecosystems. This shift is compressing upgrade cycles and redistributing value capture from airframers to specialized avionics houses.
Integrated modular avionics suites are replacing federated legacy architectures in new Gulf deliveries. King Air and PC-12 operators in Abu Dhabi and Dubai are adopting these platforms at twice the rate of rotary-wing fleets. The technology is modularizing maintenance planning, allowing operators to swap line-replaceable units without airframe downtime.
GACA's emerging carbon-offset framework for private operators is reshaping fleet composition decisions. The regulation imposes graduated fees on aircraft over 15 years of age unless operators demonstrate SAF blending or operational efficiency improvements. Corporate flight departments in Riyadh are responding by accelerating G650 and Falcon 6X deliveries while retiring legacy Globals.
Charter brokerage platforms are disintermediating traditional FBO relationship networks. High-net-worth individuals in Kuwait and Bahrain now book directly through smartphone applications that aggregate fractional ownership availability across Dubai, Riyadh, and Doha. This behavioral shift is most visible among technology sector executives under 45, who prioritize price transparency over legacy relationship-based booking.
GCC General Aviation Market Segmentation
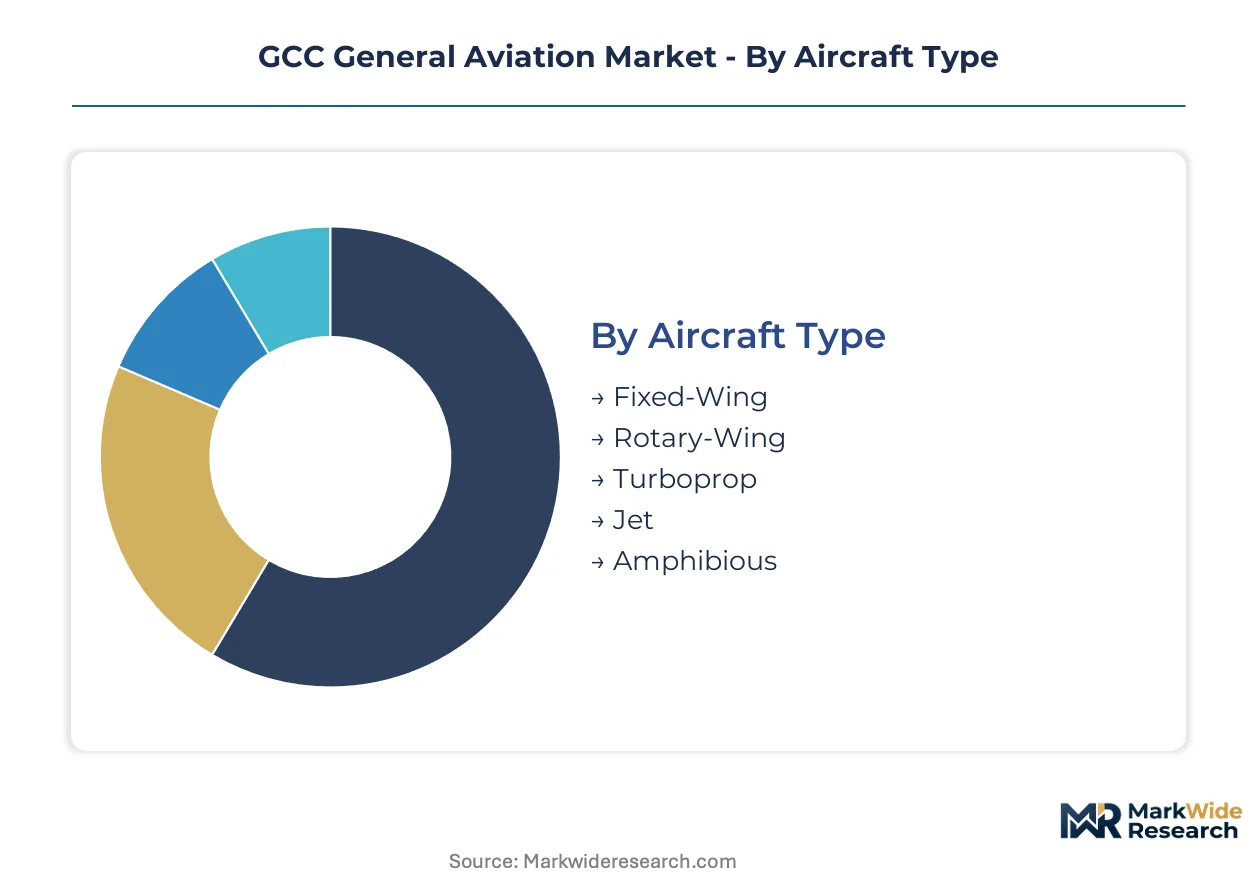
Segmentation in the GCC general aviation market reveals how regulatory divergence between Saudi Arabia and the UAE fragments procurement patterns. Fleet composition decisions now hinge on whether operators prioritize GACA localization credits or GCAA airworthiness timelines. Understanding these splits enables suppliers to calibrate certification investments and aftermarket service networks.
Aircraft Type:
Buyers in this category differentiate primarily by mission range requirements and airfield infrastructure limitations across Saudi Arabia's dispersed development sites versus the UAE's established FBO clusters.
- Fixed-Wing:Corporate turboprops and light jets dominate executive transport between Riyadh, Jeddah, and the Eastern Province. Demand concentrates among Saudi Aramco contractors requiring nonstop access to remote drilling operations where rotary-wing range proves insufficient.
- Rotary-Wing:Twin-engine helicopters configured for offshore crew change cycles sustain the highest utilization rates in the Gulf. ADNOC and Saudi Aramco platform logistics in Abu Dhabi and the Arabian Gulf drive AW139 and H175 fleet placements.
- Turboprop:King Air and PC-12 platforms serve medevac and surveillance missions across Qatar's North Field expansion and Oman's coastal monitoring corridors. Lower operating economics appeal to government flight departments with constrained fuel budgets.
- Jet:Ultra-long-range aircraft address Riyadh-Jeddah corporate missions and Dubai-London nonstop requirements. GACA's emerging carbon fees on older airframes accelerate replacement cycles among Saudi private flight departments.
- Amphibious:Seaplane configurations support Red Sea Project tourism circuits and Maldives-connecting leisure routes from Dubai. Limited water landing infrastructure restricts deployment to coastal resort developments.
Volume sits with Fixed-Wing; growth tilts toward Rotary-Wing.
Service Type:
Margin profiles diverge sharply in this category, with asset-heavy charter operations yielding lower returns than specialized aerial services requiring minimal fleet investment.
- Charter Flights:On-demand executive transport generates recurring revenue through membership programs and fractional ownership structures. Dubai-based operators capture premium pricing from technology sector executives prioritizing schedule flexibility over scheduled airline reliability.
- Air Ambulance:Dedicated medevac configurations with ICU-capable interiors serve Saudi Arabia's hospital network gaps and remote oilfield trauma response. GACA's operational certificate requirements for air ambulance providers create barriers to rapid market entry.
- Flight Training:Pilot certification demand surges under Saudi Vision 2030's aviation workforce targets and Qatar's tourism diversification mandates. GACA's theoretical examination backlog constrains throughput despite expanding simulator investments in Riyadh and Doha.
- Aerial Survey:LiDAR and hyperspectral imaging platforms support NEOM geospatial planning and UAE infrastructure monitoring. Survey contracts from Saudi Arabia's Red Sea Development Company and Dubai's Roads and Transport Authority sustain specialized operator revenue.
- Crop Dusting:Agricultural aviation serves Saudi Arabia's wheat and date palm cultivation in the Qassim and Al-Jouf regions. Limited arable land area confines this segment to niche seasonal deployment.
Revenue concentrates in Charter Flights; the steepest expansion trajectory belongs to Flight Training.
End User:
Procurement authority patterns split this category between centralized government tenders and fragmented private decisions influenced by personal relationship networks.
- Private Pilots:Individual owners operating under Part 91 equivalents purchase single-engine pistons and light sport aircraft for recreational flying. UAE-based owners favor Dubai-Al Ain weekend routes; Saudi owners concentrate around Jeddah's coastal corridor.
- Corporate Executives:Flight departments at Saudi sovereign wealth funds and UAE family offices specify long-range jets with cabin productivity features. GACA's localization mandates increasingly require Saudi-registered aircraft for government-linked entities.
- Government Agencies:Border patrol, coast guard, and ministry transport operations constitute the largest fleet procurement volume in Saudi Arabia and the UAE. Tender processes favor established suppliers with in-country maintenance partnerships.
- Flight Schools:Training organizations in Riyadh, Jeddah, and Doha acquire Cessna 172 and Diamond DA40 fleets under GACA and Qatar Civil Aviation Authority approvals. Aircraft selection prioritizes dispatch reliability over performance specifications.
- Tourism Operators:Scenic flight and air taxi providers emerging around NEOM, the Red Sea Project, and Qatar's cultural sites purchase rotorcraft and amphibious platforms. Seasonal demand fluctuations challenge year-round fleet utilization.
Fleet size sits with Government Agencies; growth tilts toward Tourism Operators.
Distribution Channel:
Channel selection reflects buyer sophistication tiers, with established operators leveraging direct manufacturer relationships while new entrants depend on intermediary guidance through complex import compliance.
- Direct Sales:Gulfstream, Bombardier, and Dassault maintain Riyadh and Dubai sales offices for large-cabin jet transactions. Direct relationships enable customized cabin completions and accelerated delivery scheduling for priority clients.
- Brokers:Independent acquisition advisors serve first-time buyers navigating GACA import documentation and GCAA registration transfers. Broker commissions typically structure around pre-owned aircraft transactions where valuation uncertainty is highest.
- Online Platforms:Digital marketplaces aggregate fractional ownership availability and charter brokerage across Dubai, Riyadh, and Doha. Technology sector executives under 45 demonstrate highest adoption rates for app-based booking interfaces.
- Aviation Events:Dubai Airshow and Saudi International Airshow generate qualified leads for manufacturers targeting defense and civilian dual-use platforms. Event-derived sales cycles extend 18-24 months for complex configured deliveries.
- Leasing Firms:Operating lessors provide short-term capacity for seasonal charter demand and flight school fleet expansion. Lease rates reflect residual value risk on avionics-mandated upgrade timelines.
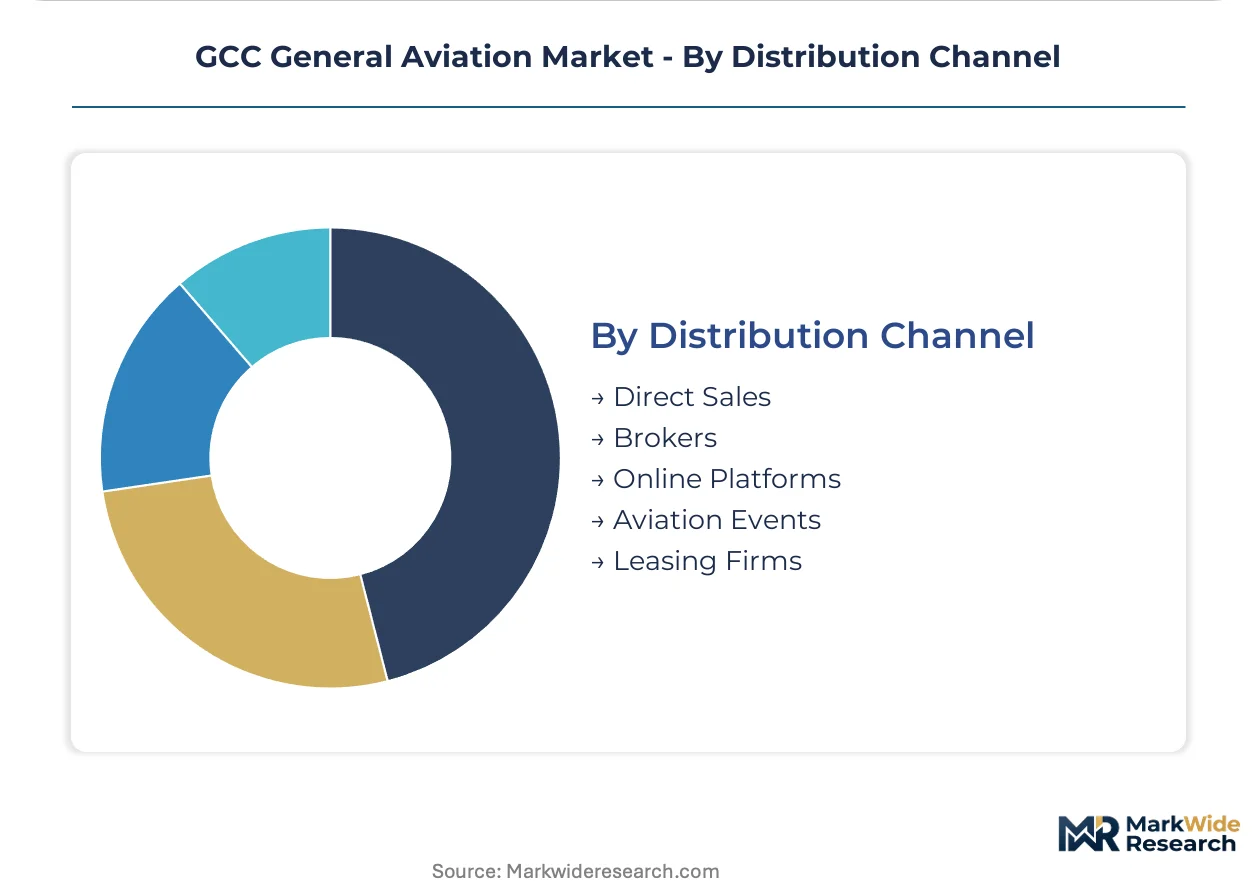
Transaction volume concentrates with Brokers; the fastest channel expansion belongs to Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel refining capacity along the Arabian Gulf shoreline anchors general aviation logistics across the peninsula. Saudi Aramco's Ras Tanura complex and ADNOC's Ruwais facilities supply the Avgas and Jet A-1 that power fixed-wing and rotary fleets. This feedstock proximity shapes where MRO investments cluster and where flight schools expand simulator capacity.
United Arab Emirates
Dubai's FBO infrastructure concentrates charter demand from technology executives and sovereign wealth fund principals. GCAA mandates on ADS-B Out and FANS-1/A avionics are compressing replacement cycles for pre-2010 King Air and Citation fleets. Al Maktoum International Airport's dedicated general aviation terminal anchors the Gulf's largest private jet handling cluster.
Saudi Arabia
NEOM and Red Sea Project developments are generating air taxi and scenic flight demand absent from the market five years prior. GACA's localization requirements increasingly mandate Saudi-registered aircraft for government-linked flight departments. Riyadh's King Khalid Airport private aviation terminal is expanding hangar capacity to accommodate G650 and Falcon 6X deliveries.
Qatar
Doha's underdeveloped FBO infrastructure relative to Dubai creates positioning opportunities for operators targeting post-FIFA World Cup corporate traffic. The Qatar Civil Aviation Authority's streamlined operational certificate processing attracts flight schools expanding from capacity-constrained Saudi and UAE markets. Lusail's planned vertiport network aims to connect Hamad International Airport with West Bay financial district.
Kuwait
Kuwait Oil Company helicopter contracts sustain AW139 utilization for offshore platform crew rotations in the Partitioned Neutral Zone. The Directorate General of Civil Aviation's emerging medevac certification framework is expanding air ambulance fleet requirements. Kuwait International Airport's general aviation apron remains capacity-constrained, pushing operators toward Sheikh Saad Terminal.
Oman
Coastal surveillance and pipeline monitoring missions drive Diamond DA42 and PC-12 acquisitions for government flight departments. The Public Authority for Civil Aviation's alignment with EASA airworthiness standards simplifies import compliance for European-registered pre-owned aircraft. Muscat's Seeb district clusters MRO providers serving offshore energy and tourism rotorcraft.
GCC General Aviation Market Competitive Landscape
Global majors compete with regional champions across certification pathways and aftermarket service networks. The market structure tiers between full-service airframers with Gulf-based completion centers and specialized turboprop or helicopter manufacturers with localized dealer networks. Three archetypes dominate: ultra-long-range jet specialists targeting Riyadh-Jeddah corporate missions; offshore helicopter providers securing Aramco and ADNOC logistics contracts; and turboprop platforms serving medevac and surveillance missions. Competitive moves concentrate on M&A for MRO capability and strategic partnerships for avionics upgrade STC approvals.
Among North American conglomerates with diversified aerospace portfolios, Textron Inc. and Gulfstream Aerospace Corporation exemplify contrasting scale strategies. Textron anchors the turboprop segment through established King Air dealer networks across Dubai and Riyadh. Gulfstream occupies the ultra-long-range tier, positioning its platforms for nonstop GCC-Europe missions. Leonardo S.p.A. represents the European helicopter specialist archetype, with its AW139 family dominating offshore energy logistics. These three entities collectively illustrate how certification breadth, regional service presence, and mission-specific performance differentiate positioning.
| Leading Market Players |
|---|
| Textron Inc. |
| Leonardo S.p.A. |
| Gulfstream Aerospace Corporation |
| MD Helicopters LLC |
| Airbus SE |
| Bombardier Inc. |
| Dassault Aviation SA |
| Diamond Aircraft Industries GmbH |
| Embraer S.A. |
| Others |
Supply & Pricing Matrix
Ultra-long-range jet premiums versus turboprop economy tiers bifurcate procurement patterns across GCC flight departments, with GACA carbon fees on older airframes compressing residual values and GCAA avionics mandates accelerating replacement demand. This tier divergence concentrates pricing power with manufacturers offering integrated completion and warranty bundles, while fragmenting aftermarket margins across dispersed MRO networks.
Pricing Analysis
Warranty bundling separates Gulfstream and Dassault direct sales from broker-mediated pre-owned transactions, with factory-certified programs commanding 15-25% premiums over third-party coverage. Price differentiation hinges on avionics compliance tier—ADS-B Out and FANS-1/A equipped aircraft trade at substantial premiums to legacy cockpit fleets—and on GACA localization credits for Saudi-registered units. Pricing pressure stems from European MRO dependency inflating King Air and Phenom downtime costs, eroding turboprop operating economics. Corporate flight departments at sovereign wealth funds demonstrate lowest price sensitivity, prioritizing schedule reliability and cabin productivity features over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle large-cabin jet demand from Riyadh and Dubai flight departments, while independent brokers and online platforms aggregate fractional ownership for technology sector buyers. Manufacturing concentration rests on Textron's Wichita turboprop lines, Leonardo's AW139 production in Italy and Poland, and Gulfstream's Savannah completion centers. Critical dependencies include Pratt & Whitney Canada PT6 engines, Honeywell avionics suites, and Safran landing systems. Single-source vulnerability on engine overhaul capacity forces Saudi operators to ferry aircraft to Lufthansa Technik or Jet Aviation Basel, extending AOG windows. Distribution runs through manufacturer-owned sales offices in Riyadh and Dubai, supplemented by regional dealer networks for turboprop and helicopter platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as GACA localization mandates and GCAA avionics deadlines simultaneously strain smaller operators lacking multi-jurisdictional certification resources. Regulatory compliance cost escalation will eliminate undercapitalized charter entrants unable to fund accelerated fleet replacement cycles.
For Market Incumbents: Lock in MRO capability through strategic partnerships or acquisitions targeting STC approval authority for GCAA-mandated cockpit upgrades. Secure exclusive distribution rights for next-generation avionics suites to capture aftermarket value migrating from airframers to component suppliers. Defend against charter brokerage platform disintermediation by embedding membership programs with technology sector executives under 45. For New Entrants and Emerging Players: The price-point gap between Dubai's premium FBO infrastructure and Doha's underdeveloped private aviation terminal creates entry positioning for fixed-base operators targeting post-FIFA World Cup corporate traffic. Qatar's streamlined operational certificate processing offers the most penetrable regulatory pathway for flight schools and charter operators. Pursue direct relationships with Red Sea Project developers for air taxi and scenic flight contracts absent established incumbent relationships. For Investors and Strategic Acquirers: Re-rating potential sits with specialized avionics houses possessing GCAA STC approval authority given the regulator's phased ADS-B and FANS mandates compressing upgrade cycles. Long-term viability favors MRO platforms with in-country engine overhaul capability, reducing Saudi operators' European dependency. Monitor GACA carbon-offset framework implementation as inflection indicator for SAF adoption rates and accelerated G650 and Falcon 6X delivery schedules.| Strategic Initiative | Industry Significance |
|---|---|
| MRO Capability Acquisition | In-country engine overhaul authority eliminates European ferry downtime for Saudi King Air and Phenom operators. |
| Avionics STC Partnership | GCAA-mandated cockpit upgrades on pre-2010 fleets demand specialized approval expertise concentrated among few providers. |
| Qatar FBO Infrastructure Buildout | First-mover positioning in Doha captures corporate traffic underserved relative to Dubai's established private jet clusters. |
| Flight School Capacity Expansion | GACA theoretical examination backlog constrains pilot pipeline throughput despite Vision 2030 workforce targets. |
| SAF Supply Agreement | GACA carbon-offset incentives reward early adopters with accelerated operational certificate processing for private operators. |
Research Methodology
Document review covered GCAA airworthiness directives, GACA operational regulations, EASA framework alignments, and OEM technical documentation, complemented by interviews with flight department managers at Saudi sovereign wealth funds, Dubai-based charter operators, GACA certification officials, and MRO engineering directors. Secondary validation drew from civil aviation authority filings, fleet registration databases, and energy sector logistics contracts. Bottom-up triangulation across operator fleet plans and top-down reconciliation against OEM delivery disclosures anchored market sizing.
Model outputs span aircraft type, service category, end-user archetype, and distribution channel across the analysis window, with CAGRs derived from regression against macroeconomic indicators and fleet age demographics. Segmentation incorporated regulatory compliance tier as distinct dimension given divergence between GACA localization credits and GCAA avionics timelines. Forecast inputs included Saudi Vision 2030 tourism infrastructure deployment schedules and Qatar Civil Aviation Authority operational certificate processing rates.
Inputs from GCAA and GACA regulatory filings were available through the study window; gaps in proprietary operator financial disclosures introduce uncertainty bands around charter revenue estimates. Forecasts reflect assumptions on regulatory implementation pace and SAF infrastructure buildout. Periodic stress-testing of base assumptions is recommended given volatility in Jet A-1 export parity pricing and pilot certification throughput constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Oxygen System Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
Military Aircraft Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Air Speed Indicator Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
North America Aviation Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Aircraft Window Frame Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Vietnam Business Jets and Helicopters Market