
 Low-Carbon Propulsion Market | 2026-2036
Low-Carbon Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Carbon Propulsion Market Analysis
Fleet procurement channels is tilting toward direct manufacturer relationships as large operators bypass traditional dealers. Tesla leverages its supercharger network to lock in fleet loyalty across North America. BYD Company Ltd. anchors battery cell production with in-house lithium iron phosphate chemistry. Siemens dominates rail electrification contracts through integrated power electronics portfolios.
Low-carbon propulsion encompasses drivetrain systems that minimize greenhouse gas emissions through battery electric, hydrogen fuel cell, hybrid, or biofuel architectures, typically achieving zero tailpipe emissions or sub-50 g CO2/km equivalent depending on energy source and duty cycle. These systems convert stored chemical or electrical energy into mechanical torque for vehicle traction, with thermal efficiency reaching 90% in electric motors versus 30-40% in conventional internal combustion engines. Battery Electric technology leads installed capacity but Hydrogen Fuel Cell commands premium margins in heavy-duty Commercial Trucks where energy density requirements exceed 300 Wh/kg. Fleet Operators represent the fastest-growing end user segment as total cost of ownership parity shifts procurement decisions away from sticker price toward lifecycle economics.
The EPA tailpipe standards and California Air Resources Board mandates compel OEMs to achieve fleet-average CO2 reductions or face credit penalties, directly shaping product mix toward zero-emission platforms. EU Green Deal benchmarks enforced by EMA and national type-approval bodies restrict market access for vehicles exceeding g CO2/km thresholds. Stakeholders must monitor hydrogen refueling infrastructure buildout rates against battery charging density to calibrate technology bets across vehicle weight classes.
Market Dynamics
Fleet operators now demand total cost of ownership parity rather than sticker price acceptance, forcing OEMs to restructure pricing models around lifecycle economics and energy contracts rather than hardware margins alone.
Growth Catalysts
- EU Green Deal Fit for 55 package:Binding CO2 reduction mandates for new vehicles accelerate zero-emission platform development and procurement commitments across European commercial fleets.
- Hydrogen fuel cell energy density:Heavy-duty commercial trucks exceeding 300 Wh/kg requirements drive premium system adoption where battery weight penalties compromise payload economics.
- China's coastal manufacturing clusters:Battery-electric bus procurement concentrates procurement volume and supplier localization, compressing delivery timelines and system costs.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings destabilize battery pack cost forecasting and contract pricing for multi-year fleet agreements.
- Electrolyzer manufacturing concentration:European and East Asian suppliers dominate green hydrogen production equipment, creating supply bottleneck risks for fuel cell system integrators.
- Refueling infrastructure gap:Hydrogen station deployment rates lag vehicle certification timelines in North American and European corridors, constraining route flexibility for early adopters.
Strategic Opportunities
- Maritime freight propulsion:Coastal shipping and port handling equipment present untapped demand for hydrogen fuel cell systems where shore power limitations and emissions regulations intersect.
- Rail electrification retrofit:Diesel locomotive replacement programs in India and Southeast Asia create demand for hybrid-electric and hydrogen traction systems on non-electrified track segments.
- Supercharger network access:Charging infrastructure exclusivity agreements lock fleet loyalty and create recurring revenue streams beyond vehicle hardware sales.
Industry Challenges
- Power electronics engineering talent:Scarcity of specialists in wide-bandgap semiconductor integration slows inverter development cycles and raises compensation costs.
- Multi-homologation complexity:Divergent type-approval requirements between EPA, California Air Resources Board, and EU member state bodies extend certification timelines and testing expenditures.
- Legacy fleet integration:Telematics and depot management systems require middleware development to coordinate mixed-powertrain operations during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Carbon Propulsion Market |
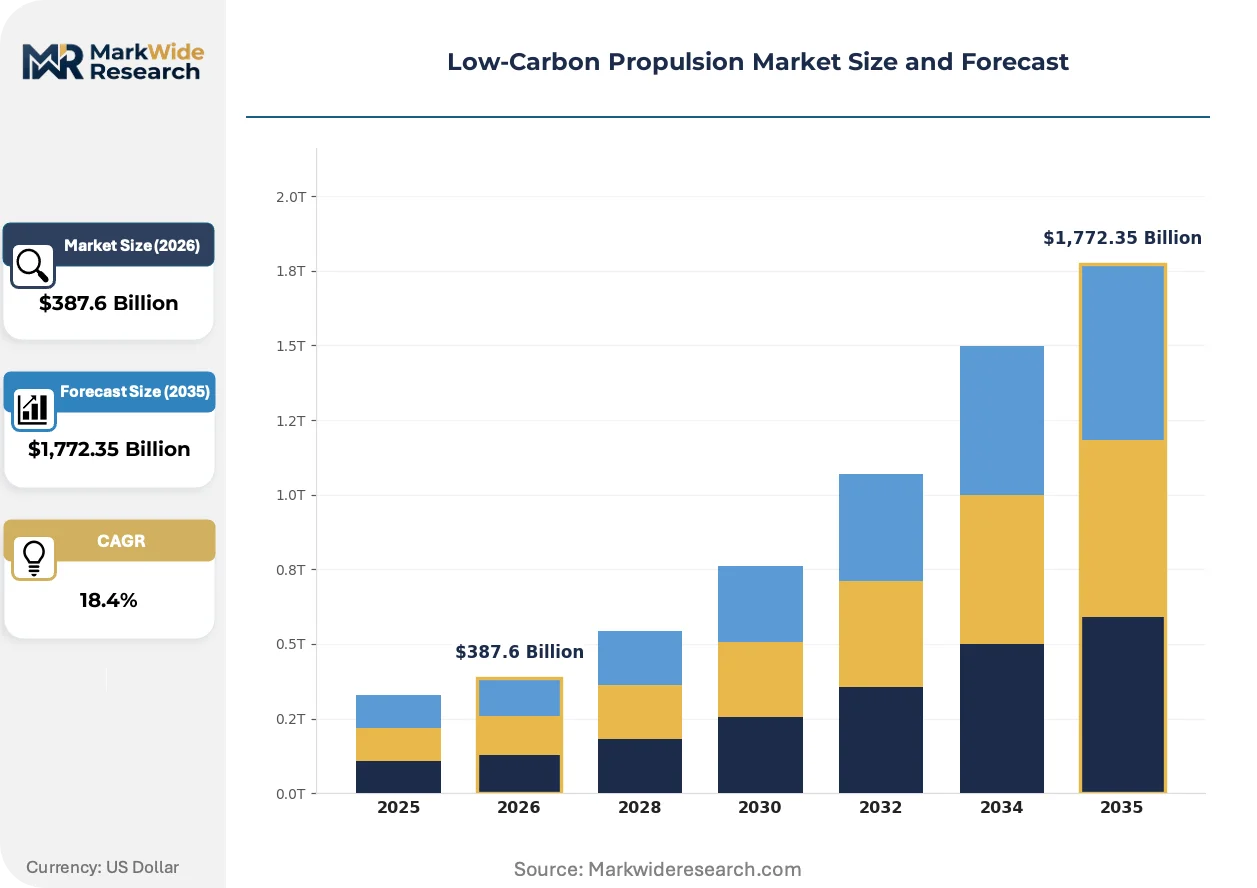
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,772.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Battery Electric, Hydrogen Fuel Cell, Hybrid, Biofuel Vehicle Type: Passenger Cars, Commercial Trucks, Buses, Motorcycles End User: Fleet Operators, Private Consumers, Government Entities, Logistics Companies Component: Powertrain, Charging Infrastructure, Energy Storage, Control Systems |
| Companies Covered | Tesla, BYD Company Ltd., YUTONG, Proterra, Nissan, Bombardier, Siemens, Alstom, Toyota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Carbon Propulsion Market Emerging Trajectories
Digital twin architectures and predictive maintenance algorithms now permeate powertrain development, compressing validation cycles and enabling remote performance optimization across distributed fleet operations.
Solid-state battery cell chemistries are digitizing energy management architectures through embedded sensors and real-time state-of-health monitoring. Commercial bus operators in South Korea and Japan are piloting these systems for route optimization and warranty risk reduction. The technology is digitizing fleet asset utilization models by enabling precise range prediction and dynamic charging scheduling.
The EPA tailpipe standards and California Air Resources Board mandates now require fleet-average CO2 reductions with credit penalty mechanisms. OEM product mix shifts toward zero-emission platforms accelerate as compliance costs exceed electrification investment thresholds. Heavy-duty commercial truck segments face the steepest compliance gradient and are responding with accelerated hydrogen fuel cell platform launches.
Direct manufacturer relationships now displace traditional dealer networks for large fleet operators seeking volume pricing and custom specification control. Procurement teams negotiate energy-as-a-service contracts bundling vehicles, charging infrastructure, and electricity supply. This pattern concentrates in North American logistics corridors where mega-fleets operate dedicated terminal networks and standardize equipment specifications across thousands of units.
Low-Carbon Propulsion Market Segmentation
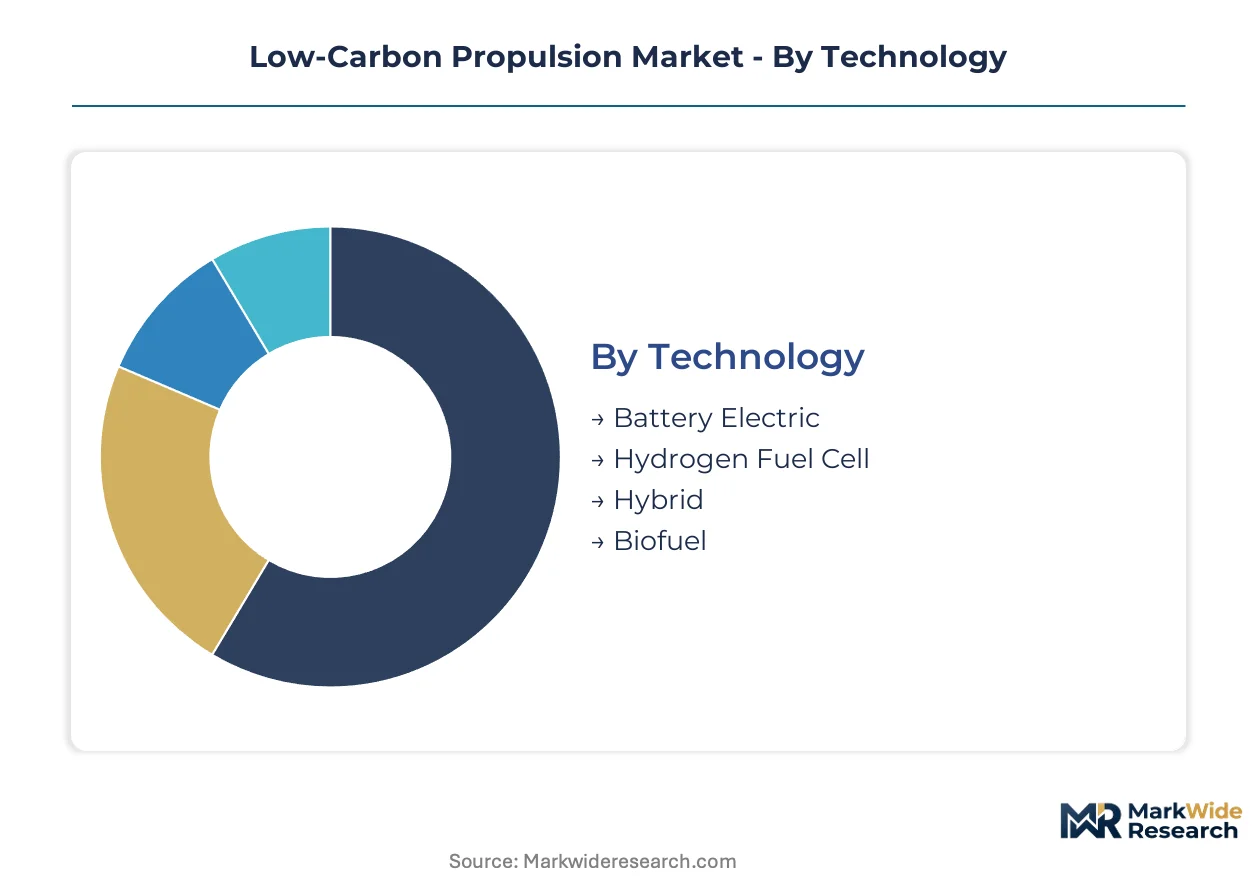
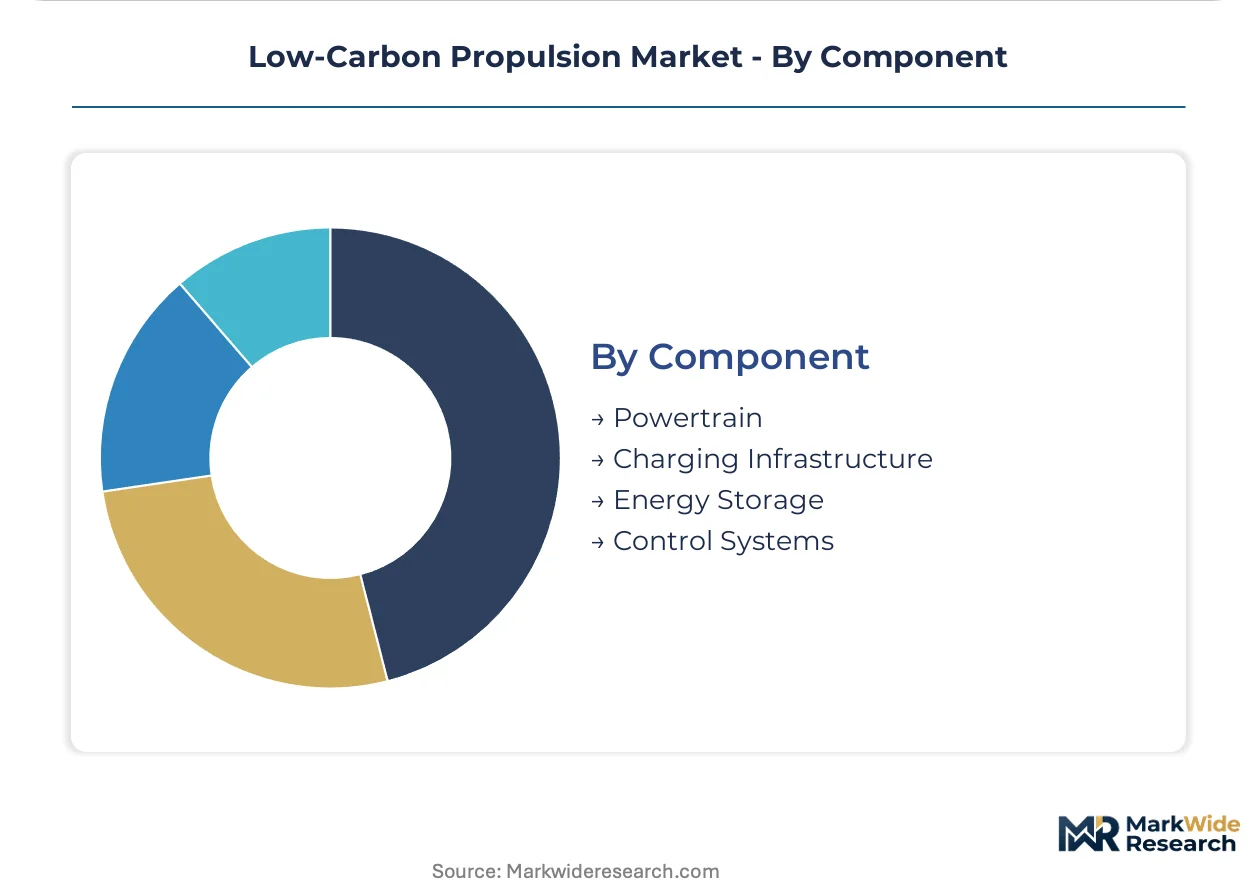
Segmentation reveals how service intensity, component lifecycle, and procurement scale reshape profitability across the low-carbon propulsion value chain. Technology and vehicle type classifications determine aftermarket revenue potential, while end-user and component segments expose diverging margin structures.
Technology:
After-sales service intensity varies dramatically across propulsion architectures, with fuel cell systems demanding specialized technician networks and battery-electric platforms requiring predictive battery management contracts.
- Battery Electric:Lithium-ion cell packs with integrated thermal management dominate installed capacity. Demand concentrates in China's coastal manufacturing clusters where battery-electric bus procurement accelerates under municipal fleet electrification mandates.
- Hydrogen Fuel Cell:Proton exchange membrane stacks paired with high-pressure hydrogen storage achieve energy density exceeding 300 Wh/kg. Heavy-duty commercial trucks in European freight corridors drive premium adoption where payload economics outweigh infrastructure constraints.
- Hybrid:Combines downsized combustion engines with electric assist for transitional fleet applications. Government Entities in India and Southeast Asia favor this architecture for route flexibility on non-electrified corridors.
- Biofuel:Drop-in renewable diesel and sustainable aviation fuel compatibility extends legacy asset lifecycles. Maritime freight operators in EU port zones deploy biofuel retrofits while awaiting hydrogen infrastructure maturity.
Battery Electric holds the largest share; momentum sits with Hydrogen Fuel Cell.
Vehicle Type:
Cost tier stratification separates premium technology integration in heavy commercial platforms from commoditized passenger applications.
- Commercial Trucks:Class 8 long-haul and regional delivery vehicles face the steepest regulatory compliance gradients. Fleet Operators in North American logistics corridors negotiate direct manufacturer relationships bypassing traditional dealer networks.
- Buses:Urban transit and intercity coaches require depot charging or hydrogen refueling infrastructure alignment. China's coastal manufacturing clusters concentrate procurement volume, compressing delivery timelines and system costs through supplier localization.
- Passenger Cars:Battery-electric platforms achieve manufacturing scale through shared skateboard architectures. Private Consumers respond to total cost of ownership parity rather than sticker price acceptance.
- Motorcycles:Two-wheel electric platforms address last-mile delivery and urban commuting density. Logistics Companies in Southeast Asian megacities pilot battery swap networks to eliminate charging downtime.
Commercial Trucks command premium system margins; Buses are expanding most quickly.
End User:
Customer type determines contract structure, with fleet-scale procurement enabling energy-as-a-service bundling unavailable to fragmented private demand.
- Fleet Operators:Mega-fleets operating dedicated terminal networks standardize specifications across thousands of units. These entities negotiate lifecycle economics contracts bundling vehicles, charging infrastructure, and electricity supply.
- Logistics Companies:E-commerce delivery networks and cold-chain operators prioritize route reliability over capital expenditure minimization. Hydrogen fuel cell trials concentrate in European freight corridors where EU Green Deal mandates enforce CO2 reduction timelines.
- Government Entities:Municipal transit authorities and defense procurement agencies specify domestic content requirements. India's diesel locomotive replacement programs create demand for hybrid-electric traction systems.
- Private Consumers:Individual purchasers respond to purchase incentives and charging network accessibility. Tesla's supercharger exclusivity agreements lock loyalty beyond vehicle hardware sales.
Fleet Operators anchor procurement volume; Logistics Companies show steepest expansion trajectory.
Component:
Supply concentration in power electronics and energy storage creates margin capture opportunities for integrated system suppliers.
- Powertrain:Electric motors, inverters, and transmissions convert stored energy into mechanical torque. Wide-bandgap semiconductor integration in silicon carbide inverters achieves 90% thermal efficiency versus 30-40% in conventional engines.
- Energy Storage:Battery packs and hydrogen tanks determine vehicle range and refueling patterns. Lithium carbonate price volatility destabilizes cost forecasting for multi-year fleet agreements.
- Charging Infrastructure:Depot charging, opportunity charging, and hydrogen refueling stations enable fleet operations. European and East Asian electrolyzer manufacturing concentration creates supply bottleneck risks.
- Control Systems:Battery management systems and vehicle control units optimize energy dispatch. Digital twin architectures and predictive maintenance algorithms compress validation cycles across distributed fleet operations.
Powertrain captures the largest value share; Control Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy regimes and emissions mandates in major economies are accelerating fleet electrification timelines and reshaping procurement geography. National regulators calibrate incentive intensity against domestic manufacturing capacity, creating divergent adoption velocities across vehicle weight classes.
China
Coastal manufacturing clusters in Guangdong and Jiangsu provinces concentrate battery-electric bus production for municipal fleet operators. The Ministry of Industry and Information Technology enforces dual carbon goals through production quotas for new energy vehicles. Shenzhen and Shanghai anchor procurement volume through integrated charging infrastructure deployment and state-owned fleet standardization.
Germany
Heavy-duty freight corridors between Hamburg and Munich drive hydrogen fuel cell trials for long-haul commercial trucks. The KBA enforces EU Green Deal CO2 reduction mandates through type-approval restrictions on diesel platforms. Baden-Württemberg hosts power electronics engineering clusters supplying inverter systems for rail electrification retrofits.
United States
California Air Resources Board mandates compel Class 8 truck operators toward zero-emission platforms through fleet-average credit mechanisms. The EPA tailpipe standards extend these requirements to interstate operators, accelerating hydrogen infrastructure investment along I-5 and I-10 corridors. Tesla's supercharger network locks fleet loyalty through exclusive access agreements in Western states.
India
Diesel locomotive replacement programs create demand for hybrid-electric traction systems on non-electrified railway segments. The Bureau of Indian Standards and Central Electricity Authority coordinate standards for depot charging infrastructure at state transport undertakings. Maharashtra and Gujarat concentrate battery pack assembly through production-linked incentive schemes for cell manufacturing.
Japan
Commercial bus operators in Tokyo and Osaka pilot solid-state battery systems for route optimization and warranty risk reduction. METI coordinates hydrogen refueling infrastructure buildout rates against fuel cell vehicle certification timelines. Nagoya's industrial corridor anchors power electronics semiconductor fabrication for wide-bandgap inverter components.
Low-Carbon Propulsion Market Vendor Landscape
On the supply side, the industry is consolidating around integrated system suppliers with captive energy storage and power electronics capabilities. Tiered competitive positioning separates premium technology integrators from volume-focused platform specialists. Three archetypes dominate: automotive OEMs with charging network assets, industrial conglomerates with rail electrification portfolios, and battery-centric specialists with in-house cell chemistry. Dominant competitive moves include strategic partnerships bundling vehicles with energy contracts and backward integration into lithium refining and semiconductor fabrication.
Within the integrated automotive tier, Tesla and BYD Company Ltd. exemplify divergent geographic anchoring and business model architecture. Tesla represents the charging-infrastructure-locked archetype through network exclusivity agreements, while BYD Company Ltd. occupies a position emphasizing captive battery cell production with lithium iron phosphate specialization. Siemens anchors the industrial electrification segment, sitting within the rail and heavy-duty power electronics tier where integrated portfolio breadth determines contract capture.
| Leading Market Players |
|---|
| Tesla |
| BYD Company Ltd. |
| YUTONG |
| Proterra |
| Nissan |
| Bombardier |
| Siemens |
| Alstom |
| Toyota |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price volatility determines both tier spreads in battery-electric platforms and the geographic sourcing strategies of fleet-scale integrators. Procurement teams now hedge raw material exposure through multi-year offtake contracts that compress margin buffers at the standard tier while premium hydrogen fuel cell systems maintain pricing power through electrolyzer supply scarcity.
Pricing Analysis
Certification level under EU Green Deal and EPA tailpipe standards creates the primary spread between compliant premium tiers and transitional economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects battery chemistry grade, with lithium iron phosphate systems commanding mid-tier positioning against nickel-cobalt-manganese premium packs. Cost compression in standard-tier bus platforms is intensifying because China's coastal manufacturing clusters concentrate procurement volume. Fleet operators show lowest price sensitivity due to lifecycle economics contracts, while private consumers remain most responsive to sticker price differentials.
Supply Chain Analysis
Tariff exposure between China and North American corridor operators dominates supply chain risk calculus for battery pack integrators. Manufacturing gravity centers on China, South Korea, and Japan for lithium-ion cell production, with Germany and the United States anchoring power electronics fabrication. The supply chain rests on lithium carbonate, rare earth permanent magnets, and wide-bandgap silicon carbide wafers as critical inputs. Single-source vulnerability concentrates in electrolyzer stack assembly where European and East Asian suppliers control green hydrogen production equipment. Distribution runs through direct manufacturer relationships for fleet operators, bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-carbon propulsion is shifting toward platform economics where charging infrastructure access locks fleet loyalty beyond vehicle hardware. Interoperability between hydrogen refueling networks and battery charging protocols is reshaping competitive moats.
For Market Incumbents: Entrench position through backward integration into lithium refining and captive semiconductor fabrication for wide-bandgap inverters. Secure electrolyzer supply agreements ahead of fuel cell platform scaling. Threat of emerging battery swap network operators in Southeast Asian logistics corridors demands preemptive charging infrastructure exclusivity in Western markets. For New Entrants and Emerging Players: Build out presence in maritime freight propulsion where shore power limitations and emissions regulations intersect with hydrogen fuel cell applicability. India's diesel locomotive replacement programs present the most penetrable geography for hybrid-electric traction systems on non-electrified rail segments. Go-to-market through energy-as-a-service bundling with port authority terminal operators. For Investors and Strategic Acquirers: EU Green Deal Fit for 55 enforcement reshapes the acquisition landscape toward integrated system suppliers with captive energy storage capabilities. Long-term viability favors entities controlling both vehicle platforms and refueling infrastructure assets. Target power electronics engineering specialists with silicon carbide inverter portfolios. Watch hydrogen station deployment rates against vehicle certification timelines as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium iron phosphate cell access for fleet-scale procurement commitments. |
| Charging Infrastructure Partnership | Creates recurring revenue streams through supercharger network exclusivity agreements. |
| Platform Standardization | Reduces per-unit engineering costs across shared skateboard architectures for passenger cars. |
| Backward Integration into Refining | Captures margin from lithium carbonate volatility through captive supply chain control. |
| Software-Defined Vehicle Investment | Enables predictive maintenance algorithms and digital twin architectures for fleet optimization. |
Methodological Framework
A standing panel of fleet procurement directors, OEM platform engineers, power electronics R&D leads, and hydrogen infrastructure developers provided ongoing calibration against operating reality. Primary interviews with Tier 1 supplier procurement teams and aftermarket service heads were cross-validated against secondary sources including EPA tailpipe standard filings, EU EMA type-approval databases, IEA hydrogen project trackers, and vehicle production registration data. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring.
Scenario bracketing around electrolyzer manufacturing capacity buildout and lithium carbonate price bands bounded the projection horizon. Segmentation dimensions modeled include propulsion architecture, vehicle weight class, end-user procurement scale, and regional regulatory cluster intensity. CAGRs were derived from installed base growth rates and replacement cycle compression. Industry-specific inputs incorporated fleet-average CO2 compliance cost trajectories and energy density requirements for heavy-duty commercial applications.
Stress conditions across lithium raw material availability, hydrogen station deployment velocity, and wide-bandgap semiconductor fabrication capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement timelines and infrastructure investment commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Actuator Market