
 Airborne Telemetry Market | 2026-2036
Airborne Telemetry Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Telemetry Market Analysis
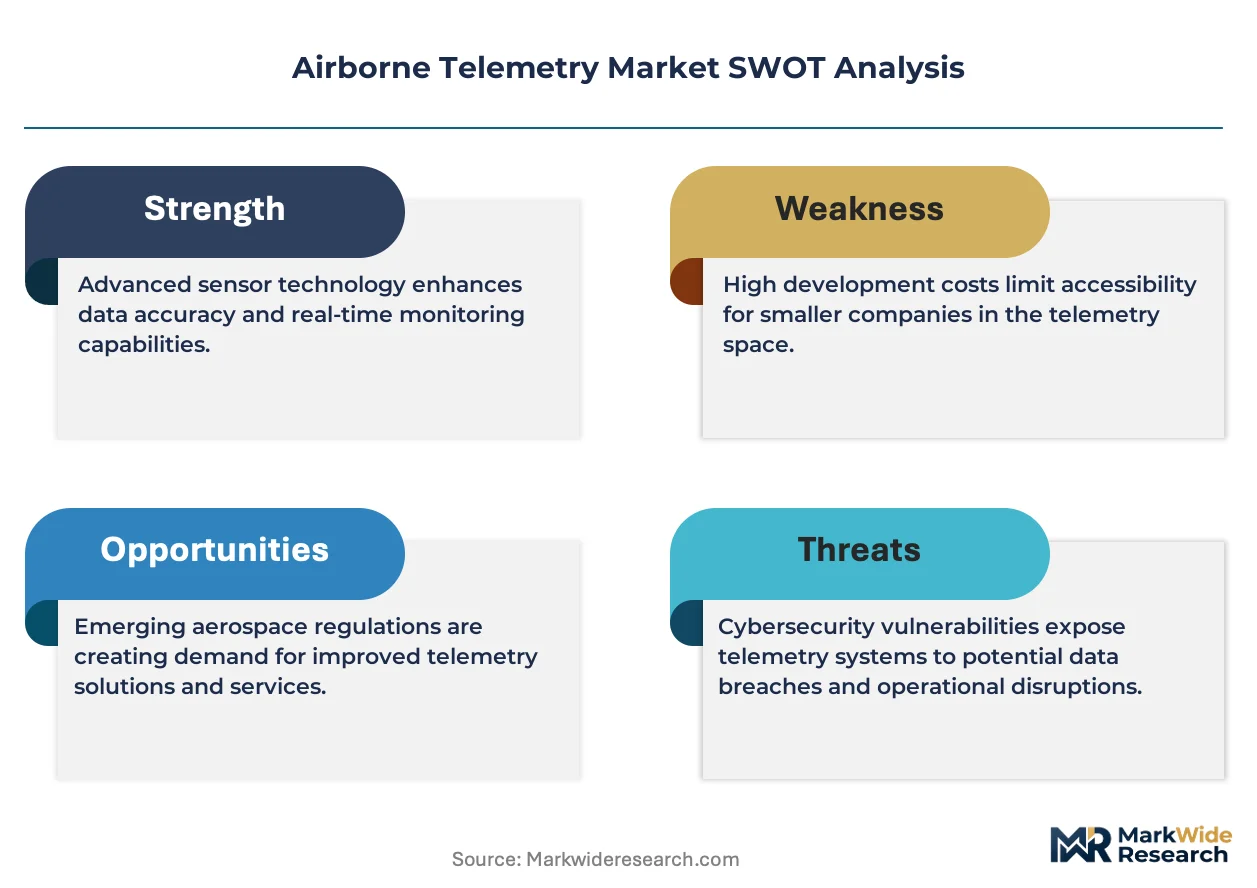
DO-178C qualification for safety-critical software is reorganizing supplier eligibility across the Airborne Telemetry Market, raising barriers for vendors lacking certified development processes. L3Harris Technologies leverages its RF systems heritage to sustain dominance in military flight-test programs. BAE Systems plc anchors European defense telemetry through its UK manufacturing base and transatlantic program participation. Curtiss-Wright Corporation specializes in ruggedized data acquisition hardware for extreme-environment test campaigns.
Airborne telemetry encompasses the wireless transmission of flight performance, structural health, and payload data from aircraft to ground stations using S-band through Ka-band frequencies, with modern systems achieving sustained data rates exceeding 20 Mbps. Its primary purpose is enabling real-time safety monitoring and post-flight engineering analysis for military, commercial, and experimental aviation programs. RF-Based technology leads deployment volume owing to proven reliability in contested electromagnetic environments, while Satellite-Based systems represent the fastest-growing segment as beyond-line-of-sight requirements expand for unmanned platforms operating across Pacific test ranges. Cloud-Based deployment is gaining traction among research institutions seeking elastic compute for massive telemetry dataset processing.
FAA airworthiness standards and DoD MIL-STD-1553 databus specifications shape hardware interoperability requirements, while ITAR export controls restrict technology transfer to approved defense partner nations. The EU AI Act and emerging autonomous flight frameworks in Europe will impose additional algorithmic transparency obligations on telemetry systems supporting unmanned operations. Stakeholders must monitor evolving spectrum allocation decisions by national regulators, as 5G expansion threatens to encroach on legacy telemetry frequency bands and force costly retuning or replacement cycles.
Market Dynamics
Software-defined radio architectures are decomposing legacy hardware-defined telemetry stacks, forcing suppliers to requalify entire product lines under DO-178C and MIL-STD-1553B while defense procurement agencies consolidate vendor pools around certified development processes.
Growth Catalysts
- Hypersonic vehicle testing mandates:US federal R&D budgets for Mach 5+ flight programs are scaling operational requirements for real-time data relay across Pacific test ranges. This creates sustained demand for Ka-band telemetry systems capable of 20+ Mbps sustained throughput.
- EU AI Act compliance pathways:Emerging autonomous flight frameworks in Europe are imposing algorithmic transparency obligations on telemetry systems supporting unmanned operations. Vendors with certified safety-critical software processes capture preferential positioning in NATO member state procurements.
- Satellite-based beyond-line-of-sight expansion:Unmanned platforms operating across dispersed test ranges require continuous data relay without ground station proximity. This technical requirement accelerates migration from RF-based point-to-point architectures to satellite-integrated telemetry networks.
Market Restraints
- Spectrum congestion from 5G expansion:National regulators in the United States and European Union are reallocating S-band and C-band segments previously reserved for telemetry applications. This forces costly retuning cycles or complete system replacement for legacy installations.
- ITAR export control restrictions:Technology transfer limitations confine defense-grade telemetry hardware to approved partner nations. Suppliers face revenue ceiling effects when excluded from growth markets lacking bilateral defense agreements with the United States.
- Specialized RF engineering talent scarcity:Deep expertise in microwave frequency design for contested electromagnetic environments concentrates among a narrow cohort of experienced practitioners. This supply constraint extends development timelines and elevates compensation costs for qualified personnel.
Strategic Opportunities
- Cloud-based telemetry analytics for research institutions:Elastic compute infrastructure enables massive dataset processing without capital-intensive ground station buildouts. Universities and commercial test facilities in Germany and the United Kingdom are piloting subscription-based telemetry data processing services.
- Modular software-defined payload integration:Convergence of general-purpose computing with RF front-ends allows single hardware platforms to support multiple mission profiles through firmware reconfiguration. This reduces platform-specific inventory requirements for fleet operators.
- Indo-Pacific unmanned systems proliferation:Australian and Japanese defense modernization programs are expanding telemetry requirements for long-endurance drone operations across maritime test corridors. Regional suppliers with localized manufacturing presence capture preferential procurement access.
Industry Challenges
- DO-178C certification timeline compression:Safety-critical software qualification processes require 18-36 month development cycles. Procurement agencies demand compressed delivery schedules that strain verification and validation resource allocation.
- Legacy databus integration complexity:MIL-STD-1553B and ARINC 429 interfaces persist in operational aircraft fleets. New telemetry hardware must maintain backward compatibility with obsolete protocols while delivering modern throughput capabilities.
- Electromagnetic interference hardening:Contested spectrum environments require sophisticated anti-jam and low-probability-of-intercept waveform design. This specialized capability development demands sustained R&D investment with uncertain procurement volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Telemetry Market |
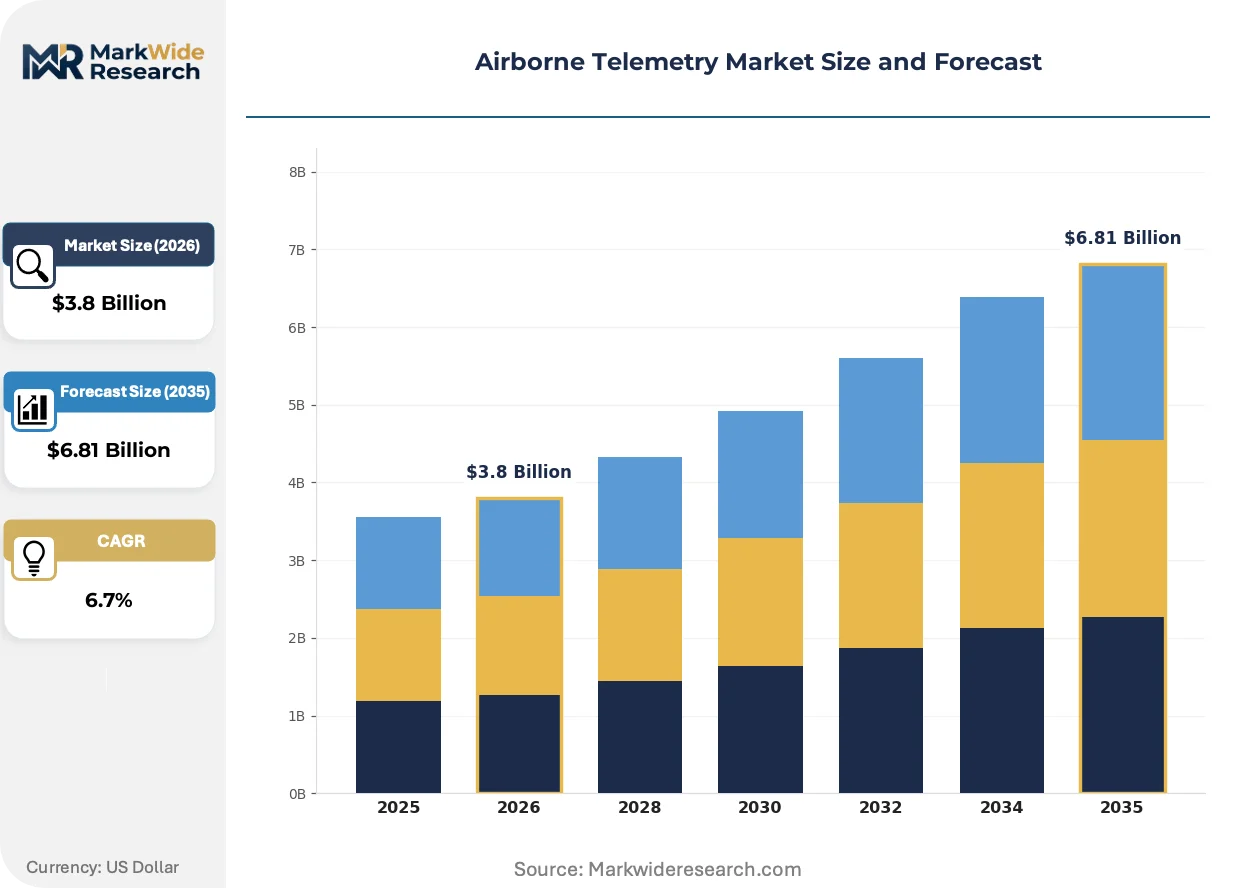
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RF-Based, Satellite-Based, Infrared, Laser End User: Aerospace, Defense, Automotive, Research Institutions Application: Monitoring, Data Collection, Communication, Navigation Deployment: On-Premises, Cloud-Based, Hybrid, Integrated |
| Companies Covered | Honeywell International Inc., BAE Systems plc, L3Harris Technologies, Lockheed Martin Corporation, RTX Corporation, Safran SA, Cobham plc, Curtiss-Wright Corporation, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Telemetry Market Emerging Trajectories
Telemetry system architectures are undergoing fundamental restructuring as software-defined principles penetrate RF subsystem design, regulatory frameworks impose algorithmic accountability requirements, and procurement patterns favor integrated platform-as-a-service models over discrete hardware acquisition.
Software-defined radio is decomposing traditional hardware-defined telemetry stacks into modular firmware-configurable layers. Defense flight-test programs across NATO member states are adopting these architectures to reduce platform-specific spare parts inventory. This decomposition compresses supplier margins on dedicated hardware while expanding recurring revenue from software maintenance and feature licensing.
EU AI Act algorithmic transparency mandates are reshaping telemetry system validation protocols for autonomous flight applications. Manufacturers must now document decision pathways within flight-critical data processing software. Unmanned aerial system segments operating in European airspace face the steepest compliance burden, with several consortia pooling certification costs through shared validation frameworks.
Integrated telemetry-as-a-service contracts are displacing discrete hardware procurement in commercial flight-test markets. Airlines and airframe manufacturers in the United States are consolidating vendor relationships around multi-year performance-based agreements. This model transfers operational risk to telemetry providers while capturing predictable cost structures for fleet operators with variable test schedules.
Airborne Telemetry Market Segmentation
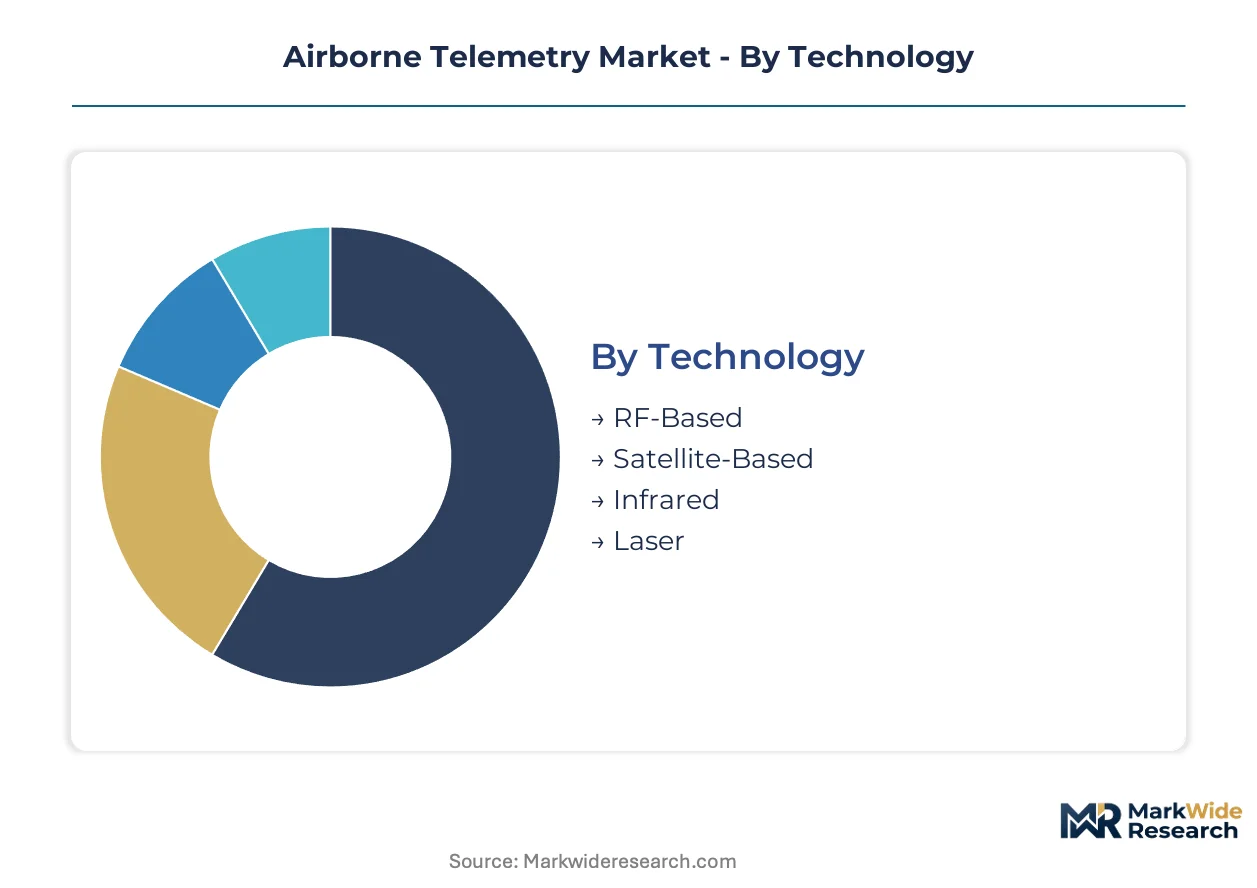
Airborne telemetry procurement patterns diverge sharply across technology architectures and operational environments. Defense agencies prioritize electromagnetic resilience and spectrum sovereignty, while commercial operators optimize for cost-per-flight-hour and dataset scalability.
Technology:
Margin pools concentrate in RF-based systems where military qualification cycles create vendor lock-in and recurring sustainment revenue.
- RF-Based:Systems transmit flight performance data across S-band through Ka-band frequencies with sustained throughput exceeding 20 Mbps. US Pacific test ranges and NATO flight-test programs drive procurement volume for hardware hardened against contested electromagnetic environments.
- Satellite-Based:Beyond-line-of-sight architectures relay telemetry from unmanned platforms operating across dispersed maritime corridors. Australian and Japanese defense modernization programs are expanding requirements for continuous data relay without ground station proximity.
- Infrared:Short-range optical links provide low-probability-of-intercept transmission for sensitive payload data.
- Laser:Free-space optical systems deliver extremely high bandwidth for experimental hypersonic vehicle programs with minimal spectrum footprint.
The dominant share belongs to RF-Based, while Satellite-Based is closing the gap fastest.
End User:
Application complexity varies dramatically across customer types, with defense procurement imposing the steepest certification burdens.
- Aerospace:Commercial airframe manufacturers and airlines utilize telemetry for structural health monitoring and powerplant performance validation during extended flight-test campaigns.
- Defense:Military flight-test programs across NATO member states require DO-178C qualified software and MIL-STD-1553B databus interoperability. Procurement agencies consolidate vendor pools around certified development processes, elevating barriers for uncertified suppliers.
- Automotive:Emerging aerial mobility developers leverage lightweight telemetry packages for urban air vehicle prototyping.
- Research Institutions:Universities in Germany and the United Kingdom pilot subscription-based telemetry data processing services using elastic cloud infrastructure.
Defense commands the largest procurement volume, though Research Institutions are expanding most quickly through cloud-based service adoption.
Application:
Functional requirements shape hardware specifications, with safety-critical monitoring demanding the highest reliability tiers.
- Monitoring:Real-time safety surveillance of flight envelope parameters, structural loads, and propulsion system health. FAA airworthiness certification mandates drive hardware redundancy and fail-operational architectures.
- Data Collection:High-fidelity recording of aerodynamic, thermal, and acoustic measurements for post-flight engineering analysis. Hypersonic vehicle testing programs generate massive datasets requiring sustained 20+ Mbps throughput.
- Communication:Two-way command and telemetry links for unmanned platform control.
- Navigation:Position and timing data relay for autonomous flight systems operating in GPS-denied environments.
Monitoring retains the foundational revenue base, while Data Collection is gaining share fastest on hypersonic program scaling.
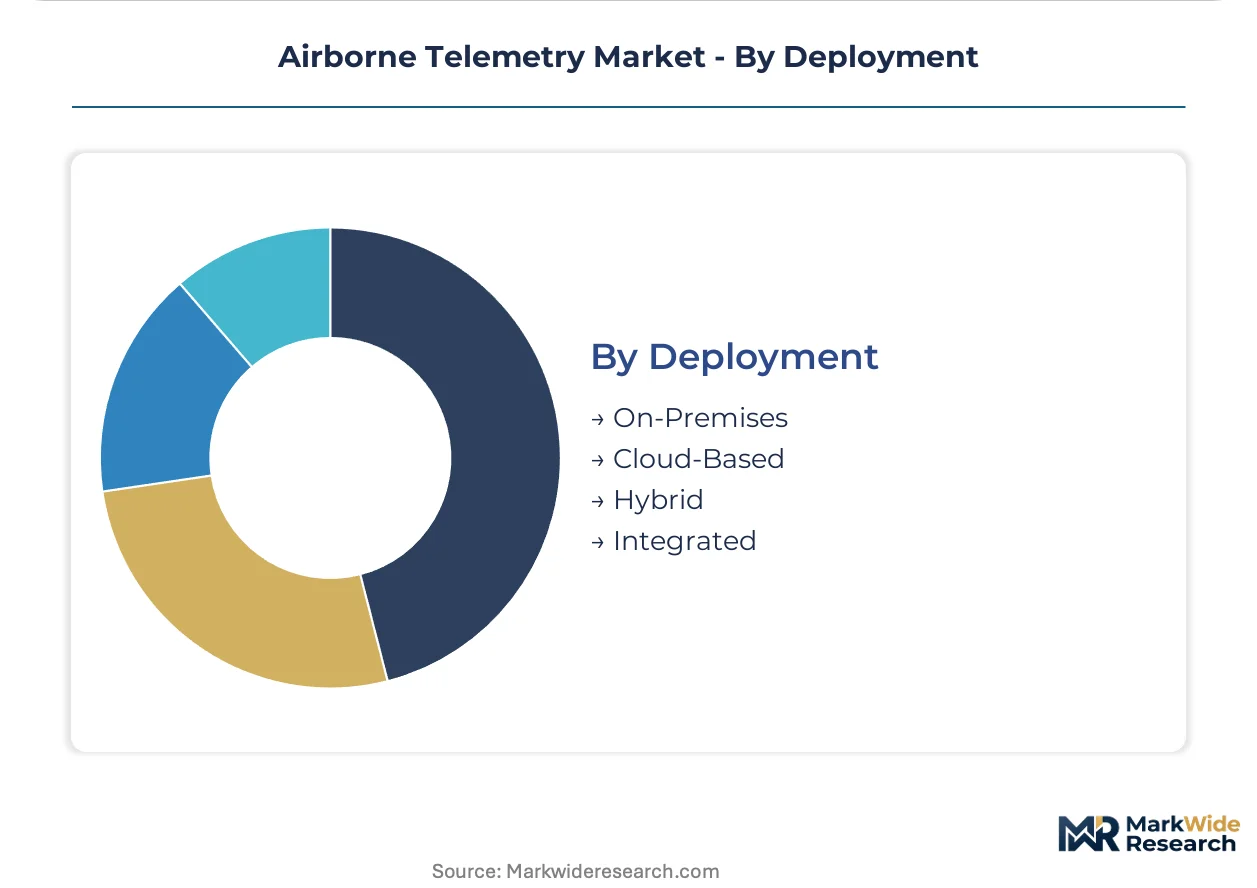
Deployment:
Capital intensity and operational control preferences segment procurement between ownership and service models.
- On-Premises:Dedicated ground station infrastructure with captive hardware and personnel. Legacy defense programs maintain this model for classified data handling and spectrum sovereignty.
- Cloud-Based:Elastic compute infrastructure for massive telemetry dataset processing without capital-intensive buildouts. Commercial operators and research institutions favor subscription economics and variable cost structures.
- Hybrid:Edge preprocessing with cloud analytics for latency-sensitive applications.
- Integrated:Platform-as-a-service contracts transferring operational risk to telemetry providers.
On-Premises still anchors revenue, yet Cloud-Based deployment is climbing the fastest as commercial flight-test markets consolidate around multi-year performance agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal R&D allocations for hypersonic vehicle testing are reshaping procurement patterns across key defense markets. National spectrum regulators are reallocating legacy telemetry bands, forcing infrastructure retuning cycles. Industrial clusters concentrate around established flight-test corridors and defense manufacturing hubs.
United States
Pacific test range expansion for Mach 5+ programs sustains demand for Ka-band systems exceeding 20 Mbps throughput. The FAA imposes airworthiness standards on commercial telemetry hardware while DoD MIL-STD-1553B specifications govern military databus interoperability. Edwards Air Force Base and Naval Air Weapons Station China Lake anchor concentrated supplier ecosystems serving both developmental test and operational flight programs.
Germany
Research institutions in Bavaria and Baden-Württemberg pilot cloud-based telemetry analytics using elastic compute infrastructure. The EU AI Act imposes algorithmic transparency obligations on autonomous flight telemetry systems entering European airspace. Munich and Stuttgart host specialized engineering clusters developing modular software-defined payload architectures for unmanned platform integration.
United Kingdom
Transatlantic program participation sustains demand for ITAR-compatible telemetry hardware across NATO flight-test campaigns. The UK Civil Aviation Authority coordinates with military procurement agencies on unmanned systems certification pathways. BAE Systems manufacturing presence in Lancashire and Hampshire anchors a supplier network serving both domestic and export defense contracts.
Australia
Defense modernization programs expand telemetry requirements for long-endurance drone operations across maritime test corridors. The country's defense department prioritizes localized manufacturing presence in procurement criteria for Indo-Pacific unmanned systems. Woomera Test Range and RAAF Edinburgh sustain concentrated demand for beyond-line-of-sight satellite-based telemetry architectures.
Japan
Joint development programs with US defense agencies drive adoption of DO-178C qualified software processes in domestic flight-test infrastructure. METI coordinates spectrum allocation to protect legacy telemetry bands from 5G encroachment. Nagoya aerospace manufacturing clusters and Gifu flight-test facilities concentrate specialized RF engineering talent for contested electromagnetic environment applications.
Airborne Telemetry Market Vendor Landscape
Player mix skews toward defense-electronics conglomerates with established RF systems heritage and certified safety-critical software processes. Market structure concentrates around vendors possessing DO-178C qualification and MIL-STD-1553B interoperability credentials. Two strategic archetypes dominate: integrated platform providers bundling hardware with multi-year service contracts, and specialized component suppliers focusing on ruggedized data acquisition for extreme-environment test campaigns. Competitive moves center on strategic partnerships for satellite network integration and portfolio diversification into cloud-based analytics services.
Among US-based defense-electronics specialists, L3Harris Technologies, Curtiss-Wright Corporation, and RTX Corporation exemplify the integrated platform archetype, each occupying positions where RF subsystem expertise converges with flight-test program sustainment relationships. BAE Systems plc represents the transatlantic model, anchoring European defense telemetry through UK manufacturing presence and NATO program participation. Safran SA and Leonardo S.p.A. sit within the continental European tier, leveraging aerospace manufacturing integration to capture unmanned systems procurement. These six entities collectively illustrate how certification credentials and geographic manufacturing presence stratify competitive positioning across defense procurement markets.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| BAE Systems plc |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| RTX Corporation |
| Safran SA |
| Cobham plc |
| Curtiss-Wright Corporation |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at specialized RF component foundries in the United States and Germany shapes both supply concentration and price floors for DO-178C qualified telemetry hardware. Defense procurement consolidation around certified vendors compresses margins for uncertified suppliers while sustaining premium pricing for qualified development processes.
Pricing Analysis
Certification level creates the primary spread across the Airborne Telemetry Market, with DO-178C qualified systems commanding substantial premiums over commercial-grade alternatives. Three-tier pricing structure separates military-qualified hardware from industrial-grade equipment and research-tier configurations. Cost compression in commercial telemetry tiers is intensifying because cloud-based service models displace capital-intensive ground station purchases. Research institutions exhibit highest price sensitivity through subscription-based procurement, while defense agencies prioritize electromagnetic resilience over unit cost.
Supply Chain Analysis
Inbound logistics costs through Los Angeles-Long Beach and Rotterdam ports constrain just-in-time delivery of specialized gallium nitride substrates and ceramic packaging materials. Manufacturing concentration centers on the United States, United Kingdom, and Germany for final assembly of qualified telemetry systems. Supply chains draw from Japanese substrate suppliers and Taiwanese semiconductor foundries for critical RF components. Single-source vulnerability persists in radiation-hardened FPGA supply. Distribution runs through defense primes and specialized avionics distributors serving flight-test programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined radio architectures threaten hardware-centric incumbents with platform commoditization, demanding defensive repositioning around firmware and service revenue.
For Market Incumbents: Compound certification advantages by deepening DO-178C qualified software portfolios before procurement consolidation freezes vendor pools. Acquire specialized RF engineering teams in Japan and Australia to capture Indo-Pacific unmanned systems growth. Satellite-based telemetry networks represent the most credible substitute threat to traditional RF point-to-point architectures.
For New Entrants and Emerging Players: Lead with cloud-based analytics services targeting German and United Kingdom research institutions seeking elastic compute without capital-intensive ground station buildouts. Modular software-defined payload integration offers the most penetrable entry point, enabling single hardware platforms to serve multiple mission profiles through firmware reconfiguration. Partner with established satellite network operators to bypass terrestrial infrastructure barriers.
For Investors and Strategic Acquirers: Boutique telemetry software houses with existing DO-178C qualification pathways offer the most attractive acquisition profile for platform consolidation plays. Long-term viability hinges on exposure to hypersonic vehicle testing budgets and autonomous flight regulatory frameworks. Watch FAA spectrum reallocation decisions as the critical inflection signal for legacy hardware replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Certification Investment | Procurement consolidation around qualified vendors elevates barriers for uncertified competitors. |
| Satellite Network Integration Partnership | Beyond-line-of-sight architectures capture unmanned platform demand across Pacific test ranges. |
| Cloud-Based Telemetry Analytics Launch | Subscription models attract German and United Kingdom research institutions seeking variable cost structures. |
| Modular Software-Defined Payload Development | Firmware-configurable layers reduce platform-specific inventory for defense fleet operators. |
| Indo-Pacific Manufacturing Footprint Expansion | Localized presence satisfies Australian and Japanese procurement criteria for unmanned systems. |
Methodological Framework
A standing panel of flight-test program directors, RF systems engineers, defense procurement officers, and satellite network operators provided ongoing calibration throughout the research process. Primary interviews combined with secondary validation against FAA airworthiness directives, DoD MIL-STD specifications, EU AI Act regulatory texts, and ITAR compliance documentation. Bottom-up demand modeling across technology segments triangulated with top-down federal R&D budget allocations.
Consistency checks validated volume and value outputs against defense electronics trade flows and hypersonic vehicle program procurement disclosures across the analysis window. The analytical framework modeled technology architecture, end-user vertical, application function, and deployment mode as primary segmentation dimensions. CAGRs derived from year-over-year expenditure patterns in federal flight-test budgets and commercial airline fleet modernization schedules.
The analysis sits within stated boundaries; outcomes outside sustained hypersonic vehicle R&D scaling or accelerated 5G spectrum reallocation would require recalibration. Forecasts reflect assumptions regarding NATO defense spending continuity and unmanned systems regulatory clarity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Interface Device Market