
 Aerospace and Defense Telemetry Market | 2026-2036
Aerospace and Defense Telemetry Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Telemetry Market Intelligence
Project finance and long-term leasing of telemetry ground station networks is reshaping competitive entry barriers for mid-tier defense suppliers. L3Harris Technologies leverages its integrated RF communication portfolio to sustain multi-band telemetry contracts across Pentagon test ranges. Safran S.A. anchors European flight testing capabilities through specialized data acquisition systems for military aircraft programs. Curtiss-Wright Corporation differentiates via ruggedized transmitter hardware that dominates missile launch monitoring applications in harsh environments.
Aerospace and defense telemetry encompasses the end-to-end capture, transmission, and processing of flight performance data from test articles, weapons systems, and operational platforms using RF links operating across L-band through Ka-band frequencies with real-time data rates exceeding 20 Mbps. The primary purpose is to validate aerodynamic models, assess structural integrity, and certify operational safety before full-rate production or deployment. RF communication and satellite communication segments lead technology investment as programs shift from line-of-sight ground stations to beyond-line-of-sight relay architectures for Pacific test corridors. Ground stations retain the largest installed base but face margin compression as software-defined radio architectures consolidate transmitter and receiver functions onto unified hardware platforms.
FCC spectrum auctions and NTIA frequency coordination requirements in the United States compress available telemetry bandwidth and force migration to higher frequencies or commercial satellite relay services. EASA and military airworthiness standards in Europe mandate redundant data links for unmanned systems certification, expanding dual-channel telemetry procurement. Stakeholders must monitor emerging spectrum policy decisions and satellite constellation interoperability standards to secure test range access before competitor systems achieve de facto adoption.
Market Dynamics
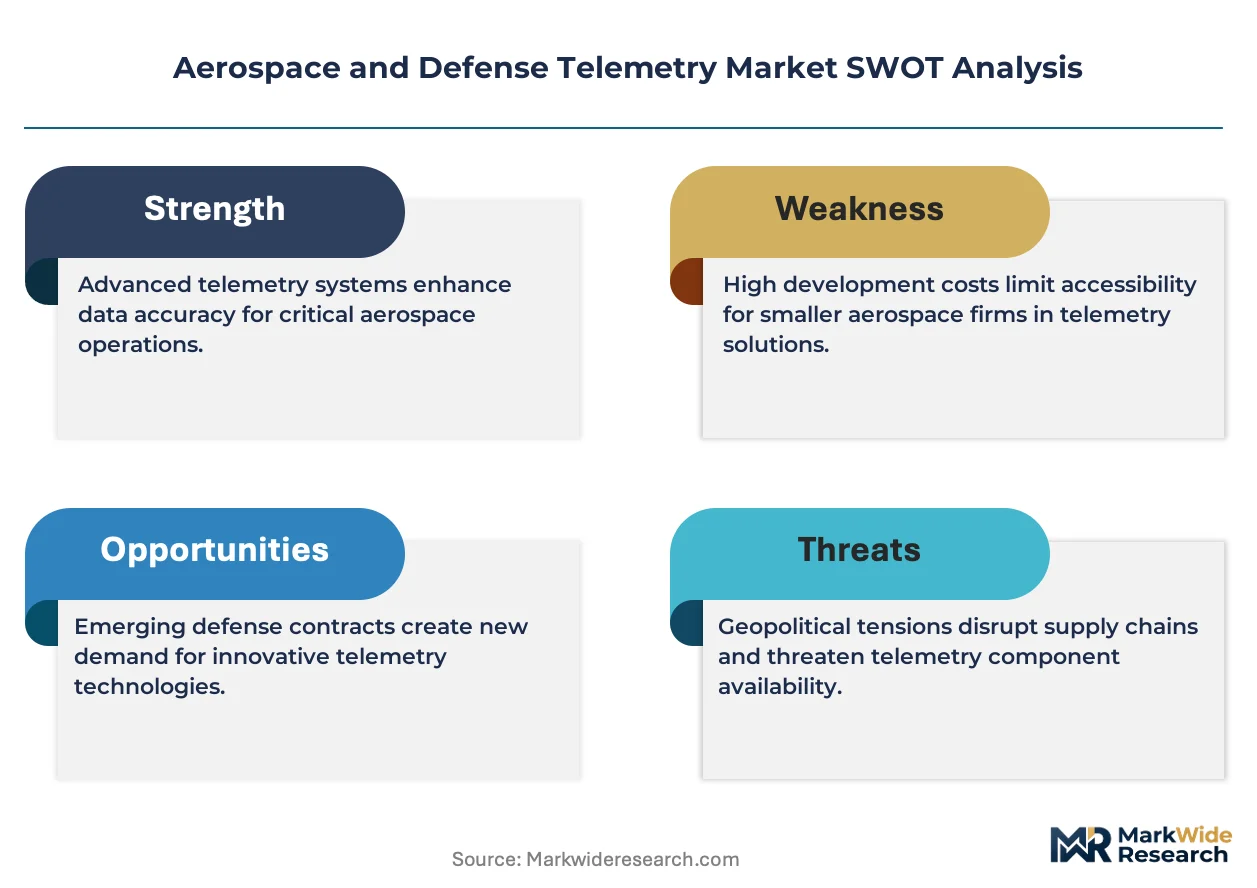
FCC spectrum reallocation is compressing available RF bandwidth for telemetry operations while simultaneously accelerating migration toward satellite relay architectures and higher-frequency bands across Pentagon test ranges.
Growth Catalysts
- Next-Generation Missile Test Programs:Sustained Department of Defense modernization budgets in the United States are expanding flight test cadence for hypersonic weapons systems requiring real-time telemetry validation.
- REACH and RoHS Compliance Mandates:European military airworthiness standards are mandating redundant data links for unmanned systems certification, expanding dual-channel telemetry procurement across NATO flight test programs.
- Software-Defined Radio Architectures:Consolidation of transmitter and receiver functions onto unified hardware platforms is reducing ground station footprint while enabling multi-band frequency agility for test range operators.
Market Restraints
- RF Component Supply Concentration:Gallium nitride power amplifier manufacturing concentrates among a limited supplier base in the United States and Japan, creating input cost volatility for ruggedized transmitter production.
- NTIA Frequency Coordination Requirements:National Telecommunications and Information Administration licensing timelines extend 18-24 months for new telemetry band allocations, delaying test range modernization schedules.
- Optical Telemetry Substitution Threat:Free-space laser communication systems are displacing RF links for certain satellite-to-ground applications, compressing addressable market scope in space launch monitoring.
Strategic Opportunities
- Pacific Test Corridor Expansion:Beyond-line-of-sight relay architectures for the Ronald Reagan Ballistic Missile Defense Test Site in the Marshall Islands create demand for commercial satellite interoperability standards.
- Modular Ground Station-as-a-Service:Project finance and long-term leasing of telemetry networks is lowering capital barriers for mid-tier defense suppliers entering flight test services.
- EASA CS-23 Certification Pathways:European Union Aviation Safety Agency regulatory frameworks for unmanned aircraft systems are creating dedicated procurement channels for civil-military dual-use telemetry platforms.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in microwave circuit design for Ka-band transmitters remains concentrated among aging workforce cohorts at established defense contractors.
- Legacy System Integration Complexity:Test ranges must maintain backward compatibility with 1960s-era pulse code modulation formats while deploying Internet Protocol-based packet telemetry architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Telemetry Market |
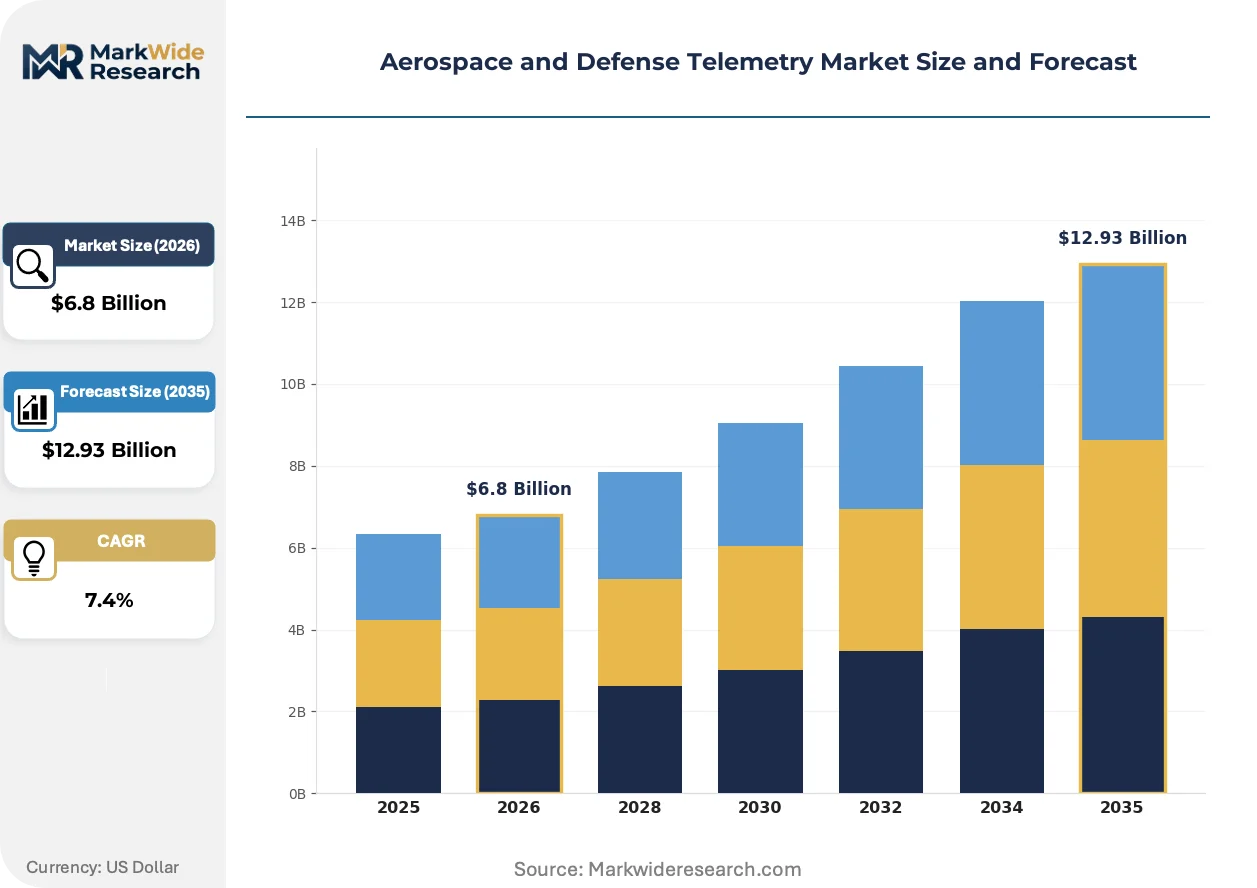
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Radar, RF Communication, Satellite Communication Application: Flight Testing, Vehicle Tracking, Data Acquisition, Missile Launch Monitoring End User: Government Agencies, Defense Contractors, Aerospace Manufacturers, Research Institutions Product Type: Ground Stations, Transmitters, Receivers, Data Processors |
| Companies Covered | L3Harris Technologies, Honeywell International Inc., Lockheed Martin Corporation, BAE Systems, General Dynamics Corporation, Northrop Grumman Corporation, RTX Corporation, Curtiss-Wright Corporation, Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Telemetry Market Strategic Shifts & Innovations
Spectrum scarcity and satellite constellation proliferation are fundamentally restructuring how flight test data moves from airborne platforms to ground analysts, compressing the traditional ground station value chain.
Software-defined telemetry transceivers are hybridizing analog RF front-ends with digital baseband processing to enable real-time frequency hopping across L-band through Ka-band allocations. Defense test ranges at Edwards Air Force Base and Naval Air Weapons Station China Lake are deploying these units to avoid interference from commercial 5G deployments in adjacent spectrum. This hybridizing architecture is collapsing the historical separation between telemetry and electronic warfare test equipment, forcing vendors to compete across previously distinct procurement categories.
The FCC's 3.45 GHz auction and subsequent band reassignments are mandating telemetry system relocations for weapons programs operating in previously reserved federal spectrum. Manufacturers must now certify equipment for new frequency assignments while maintaining operational continuity for active test programs. Small-diameter bomb and cruise missile flight test divisions are absorbing the highest compliance costs as their legacy S-band links face forced migration.
Performance-based telemetry service contracts are displacing capital equipment purchases at major defense primes, with Lockheed Martin and Raytheon favoring per-flight-hour pricing for Pacific range operations. This model transfers obsolescence risk to ground station operators while locking in multi-year revenue streams. The shift is most visible in California and Florida test corridors where range consolidation has concentrated buyer power among a handful of program offices.
Aerospace and Defense Telemetry Market Segmentation
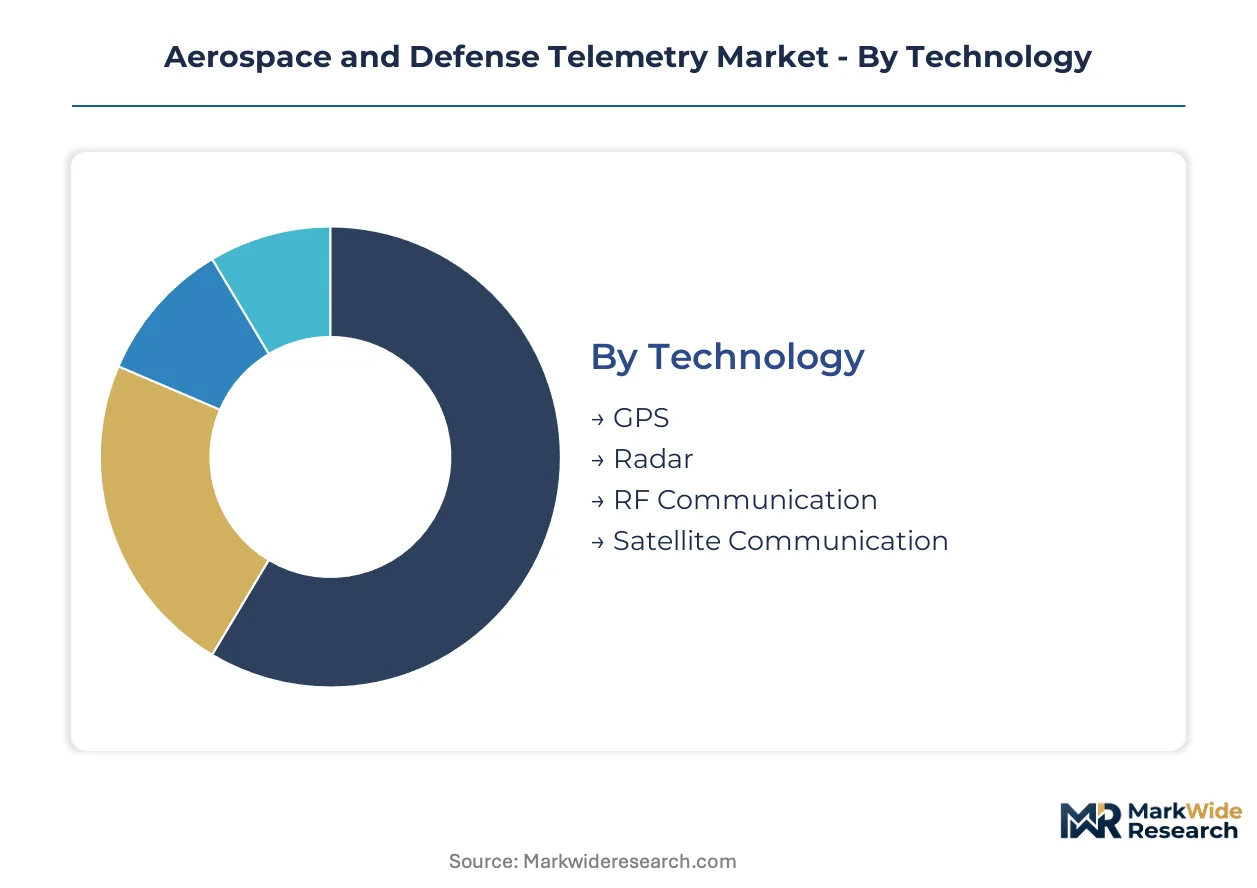
Telemetry procurement patterns diverge sharply across technology generations and operational environments. Equipment refresh cycles stretch from five years for ground infrastructure to eighteen months for airborne transmitters, creating distinct inventory management challenges for defense program offices.
Technology:
RF Communication and Satellite Communication systems turn over fastest as spectrum policy forces equipment replacement, while GPS and Radar platforms exhibit longer depreciation schedules tied to constellation stability and hardware durability.
- RF Communication:L-band through Ka-band radio links dominate missile test range operations, with real-time data rates exceeding 20 Mbps for hypersonic weapons validation. Edwards Air Force Base and Naval Air Weapons Station China Lake are consolidating multi-band frequency agility to evade 5G interference from adjacent commercial spectrum.
- Satellite Communication:Beyond-line-of-sight relay architectures are displacing traditional ground station networks for Pacific test corridors, particularly at the Ronald Reagan Ballistic Missile Defense Test Site in the Marshall Islands. FCC spectrum reallocation is compressing available RF bandwidth and accelerating migration toward commercial satellite services.
- GPS:Positioning augmentation for telemetry geolocation relies on hardened receiver modules with anti-jam capabilities for contested electromagnetic environments.
- Radar:Tracking radars provide independent trajectory verification for safety-critical flight termination decisions during weapons testing.
RF Communication anchors the volume base while Satellite Communication gains share at the steepest rate.
Application:
Cost tier separation distinguishes capital-intensive flight testing infrastructure from portable vehicle tracking deployments, with missile launch monitoring commanding premium pricing for environmental hardening.
- Flight Testing:End-to-end aerodynamic validation and structural integrity assessment for military aircraft and weapons systems requires synchronized multi-platform data acquisition across Pentagon test ranges. Department of Defense modernization budgets sustain elevated flight test cadence for next-generation hypersonic programs.
- Missile Launch Monitoring:Ruggedized transmitter hardware operates across extreme temperature, vibration, and pressure profiles during boost-phase and reentry vehicle assessment. Small-diameter bomb and cruise missile divisions absorb the highest compliance costs as legacy S-band links face forced migration under FCC 3.45 GHz reassignments.
- Vehicle Tracking:Mobile telemetry units support range safety and asset recovery for unmanned systems operating beyond visual line of sight.
- Data Acquisition:Sensor fusion platforms aggregate structural, propulsion, and avionics parameters into unified telemetry streams for real-time analyst review.
Flight Testing commands the dominant revenue share while Missile Launch Monitoring expands most quickly under Pacific range modernization.
End User:
Customer type determines procurement modality, with government agencies favoring long-term capital programs and defense contractors migrating toward performance-based service contracts.
- Government Agencies:Department of Defense program offices and test range directors specify multi-year telemetry infrastructure modernization with NTIA frequency coordination requirements extending 18-24 months for new band allocations.
- Defense Contractors:Lockheed Martin and Raytheon are shifting Pacific range operations toward per-flight-hour pricing models that transfer obsolescence risk to ground station operators while locking in multi-year revenue streams.
- Aerospace Manufacturers:Commercial-military dual-use platform developers require EASA CS-23 certification pathways for unmanned aircraft systems entering European procurement channels.
- Research Institutions:University-affiliated test ranges prioritize modular ground station-as-a-service arrangements to lower capital barriers for experimental flight programs.
Government Agencies dominate installed base procurement while Defense Contractors are climbing the fastest toward service-based contracting models.
Product Type:
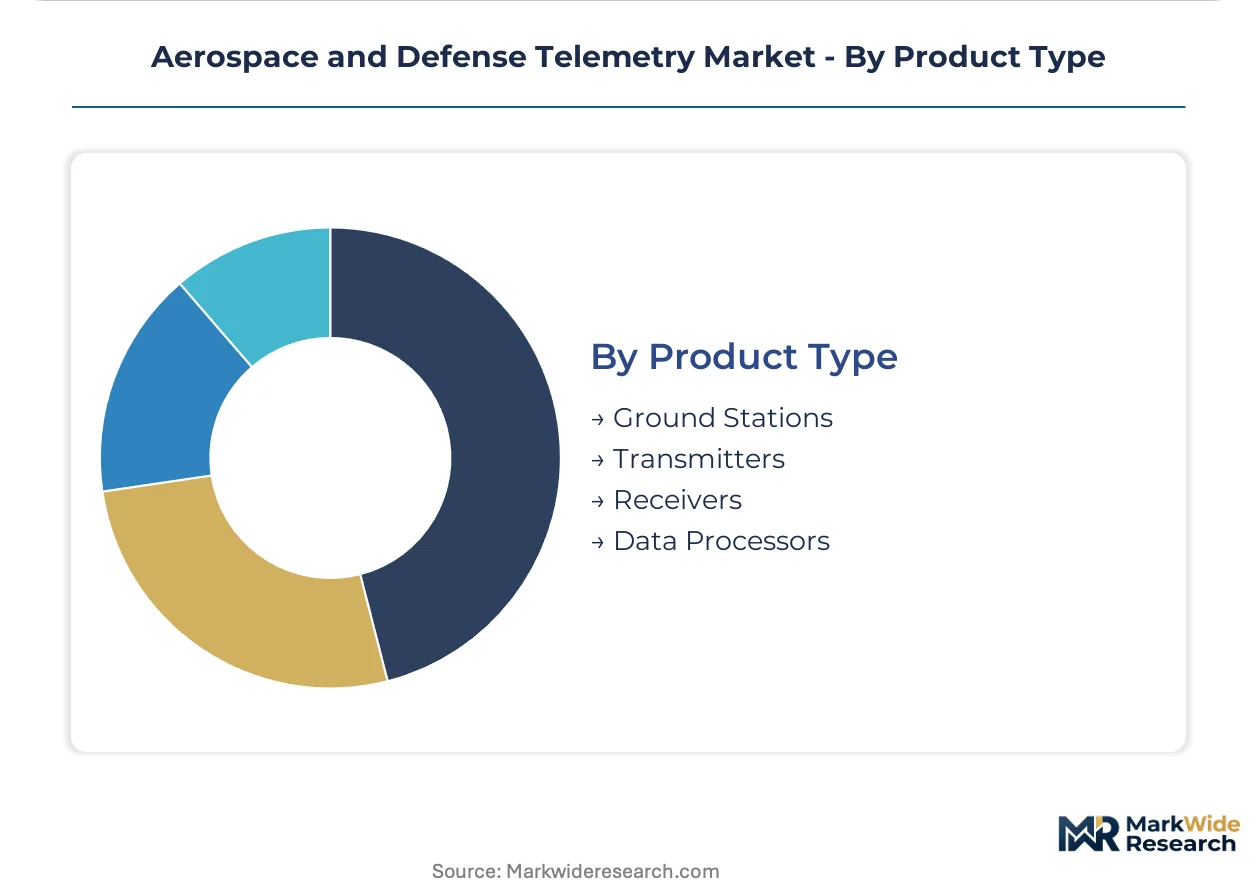
Margin structure varies by hardware-software composition, with software-defined radio architectures consolidating transmitter and receiver functions onto unified platforms and compressing traditional equipment categories.
- Transmitters:Gallium nitride power amplifier manufacturing concentrates among limited United States and Japan suppliers, creating input cost volatility for ruggedized production. Ka-band microwave circuit design expertise remains concentrated among aging workforce cohorts at established defense contractors.
- Ground Stations:Project finance and long-term leasing arrangements are reshaping competitive entry barriers for mid-tier defense suppliers entering flight test services. Software-defined architectures are collapsing historical separation between telemetry and electronic warfare test equipment procurement categories.
- Receivers:Digital baseband processing units hybridize analog RF front-ends with real-time frequency hopping capabilities.
- Data Processors:Internet Protocol-based packet telemetry architectures must maintain backward compatibility with 1960s-era pulse code modulation formats during range modernization.
Ground Stations retain the largest installed base while Transmitters face the steepest technology refresh pressure from spectrum reallocation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum reallocation in the United States compresses available RF bandwidth for telemetry operations while EASA airworthiness standards in Europe mandate redundant data links for unmanned systems certification. Defense modernization budgets across multiple geographies drive demand concentration in established test range networks.
United States
Department of Defense modernization budgets sustain next-generation hypersonic weapons test programs requiring real-time telemetry validation. NTIA frequency coordination requirements extend 18-24 months for new telemetry band allocations, delaying range modernization schedules. Edwards Air Force Base and Naval Air Weapons Station China Lake deploy multi-band frequency agility systems to evade 5G interference from adjacent commercial spectrum.
Germany
REACH and RoHS compliance mandates reshape component sourcing for military airworthiness certification across NATO flight test programs. The country's national defense procurement office specifies redundant data link requirements for unmanned systems entering European operational service. Bavaria hosts specialized telemetry ground station development clusters serving continental test range interoperability standards.
United Kingdom
Defense contractors migrate Pacific range operations toward per-flight-hour pricing models that transfer obsolescence risk to ground station operators. Military airworthiness standards from the national aviation regulator mandate dual-channel telemetry procurement for experimental aircraft programs. The southwest England aerospace corridor concentrates flight test service providers integrating satellite relay architectures for beyond-line-of-sight operations.
France
EASA CS-23 certification pathways for unmanned aircraft systems create dedicated procurement channels for civil-military dual-use telemetry platforms. National defense procurement directives prioritize modular ground station-as-a-service arrangements to lower capital barriers for experimental flight programs. The Île-de-France region anchors European flight testing capabilities through specialized data acquisition system development for military aircraft programs.
Japan
Gallium nitride power amplifier manufacturing concentrates among limited supplier bases, creating input cost volatility for ruggedized transmitter production. METI industrial standards coordinate frequency allocation policies for defense test range operations across Pacific archipelago territories. The Nagoya aerospace manufacturing cluster integrates Ka-band microwave circuit design expertise for missile launch monitoring applications in harsh environments.
Aerospace and Defense Telemetry Market Key Industry Players
On the supply side, the industry is consolidating around integrated RF communication portfolios and specialized data acquisition capabilities. Tiered competitive positioning separates full-spectrum defense primes from component specialists and regional service providers. Three strategic archetypes dominate: vertically integrated systems houses, ruggedized hardware specialists, and flight test service operators. M&A activity concentrates multi-band telemetry contract portfolios while strategic partnerships address satellite constellation interoperability requirements.
Within the integrated systems tier, L3Harris Technologies and Lockheed Martin Corporation exemplify defense primes sustaining multi-band telemetry contracts across Pentagon test ranges. Curtiss-Wright Corporation occupies a position among ruggedized hardware specialists dominating missile launch monitoring applications. Safran S.A. anchors European capabilities through specialized data acquisition systems development.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| BAE Systems |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| Curtiss-Wright Corporation |
| Safran S.A. |
| Others |
Cost & Logistics Intelligence
Nagoya's aerospace manufacturing cluster anchors gallium nitride power amplifier production, concentrating supplier leverage over ruggedized transmitter pricing for missile launch monitoring applications. This geographic concentration amplifies input cost volatility while downstream defense primes negotiate multi-year telemetry service contracts.
Pricing Analysis
Certification level (MIL-STD-810/DO-160 environmental qualification) creates the primary spread between premium and standard telemetry hardware tiers. Three-tier pricing structure across flight-qualified, industrial-grade, and developmental units reflects testing burden and traceability documentation. Pricing pressure stems from FCC spectrum reallocation forcing premature equipment refresh cycles. Government agencies exhibit lowest price sensitivity due to mission-critical requirements, while research institutions prioritize modular ground station-as-a-service arrangements to minimize capital outlay.
Supply Chain Analysis
Contract manufacturing for RF front-end assemblies concentrates among specialized EMS providers in Japan, the United States, and Germany. Gallium nitride substrates, ceramic packaging, and precision microwave substrates feed from limited qualified foundries. Single-source vulnerability pervades Ka-band power amplifier supply given sole-source qualification requirements for defense programs. Distribution runs through prime contractor integration facilities rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypersonic weapons test program expansion signals early-cycle telemetry infrastructure investment, with Pacific range modernization accelerating beyond-line-of-sight relay adoption ahead of traditional replacement schedules.
For Market Incumbents: Insulate multi-band contract portfolios through captive gallium nitride foundry partnerships or long-term supply agreements with Japanese substrate suppliers. Accelerate software-defined radio certification across Pentagon test ranges before competitor architectures achieve de facto standard status. Vertical integration into satellite constellation interoperability standards represents the critical defensive lever against commercial relay service displacement. For New Entrants and Emerging Players: Modular ground station-as-a-service for university-affiliated test ranges represents the most penetrable entry point given compressed capital barriers and limited incumbent service presence. EASA CS-23 certification pathways for civil-military dual-use unmanned platforms offer regulatory-aligned procurement channels distinct from saturated defense prime supply chains. Go-to-market execution should emphasize per-flight-hour pricing models that transfer obsolescence risk from operator to service provider. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ruggedized hardware specialists with proven environmental qualification heritage over software-centric challengers lacking flight heritage. Long-term viability rests on spectrum policy adaptation capability and satellite relay integration expertise. Monitor NTIA frequency coordination timeline compression as inflection signal for equipment refresh acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Migration Certification | FCC 3.45 GHz reallocation forces S-band equipment recertification for active weapons programs. |
| Satellite Relay Partnership | Beyond-line-of-sight architectures at Ronald Reagan Test Site demand commercial constellation interoperability standards. |
| GaN Supply Security | Long-term substrate agreements with Nagoya manufacturing cluster reduce power amplifier input volatility. |
| Software-Defined Platform Launch | Multi-band frequency agility consolidates transmitter-receiver functions at Edwards Air Force Base deployments. |
| Ground Station-as-a-Service Rollout | Project finance leasing lowers capital barriers for mid-tier defense suppliers entering flight test services. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with test range directors, RF engineering program managers, defense procurement officers, and satellite constellation operators; and secondary validation against FCC spectrum allocation dockets, NTIA frequency coordination records, DoD budget justification documents, and EASA certification pathway filings. Bottom-up equipment shipment estimates triangulated against top-down defense modernization budget allocation analysis.
Forecast inputs encompassed technology substitution rates across RF-to-satellite relay migration, segment-level procurement modality shifts from capital purchase to service contracting, and regional regulatory timeline variations for spectrum reallocation compliance. Modeled dimensions span technology generation, application environment harshness, end-user contracting type, and product hardware-software composition. CAGRs derived from equipment refresh cycle compression analysis and Pacific range infrastructure investment pipeline assessment.
Practitioners should monitor NTIA frequency coordination timeline extensions and commercial 5G deployment proximity to federal test ranges for early signals of equipment migration acceleration. Forecasts reflect assumptions regarding sustained DoD modernization budget authorization and satellite constellation interoperability standard convergence. Quarterly review of FCC spectrum auction outcomes and EASA unmanned systems certification queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market