
 Connected Aircraft Market | 2026-2036
Connected Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Aircraft Market Analysis
Aftermarket service revenue is narrowing as original equipment manufacturers bundle connectivity hardware with long-term software subscriptions. Gogo leverages its air-to-ground network infrastructure to dominate the North American retrofit segment. Honeywell International anchors its position through integrated flight management and satellite communications suites. Thales Group competes on cybersecurity-hardened avionics platforms for military and dual-use applications.
Connected aircraft refers to commercial and military aviation platforms equipped with integrated satellite communication terminals, Ka/Ku-band transceivers, and IP-based airborne networking architectures enabling real-time data exchange between airframe systems, ground stations, and cloud infrastructure. These systems operate across L-band, Ku-band, and Ka-band spectra with throughput rates exceeding 100 Mbps per aircraft, supporting predictive maintenance, passenger broadband, and cockpit situational awareness. Satellite Communication commands the largest installed base due to coverage requirements over oceanic and remote airspace, while IoT Sensors represents the fastest-expanding technology segment as engine and landing gear health monitoring shifts from scheduled to condition-based protocols. Flight Operations applications capture disproportionate margin pools because fuel optimization and trajectory management software deliver quantifiable cost savings per flight hour.
The FAA mandates Automatic Dependent Surveillance-Broadcast (ADS-B) Out equipage under 14 CFR 91.225, compelling connectivity upgrades across the US-registered fleet. EASA enforces cybersecurity certification requirements through ED-203/DO-326A airworthiness security process specifications, reshaping supplier qualification timelines for European operators. Military procurement through the US Department of Defense MIL-STD-1553 and NATO STANAG 4586 interfaces further segments vendor addressable markets. Stakeholders must weigh spectrum allocation decisions at the International Telecommunication Union against proprietary constellation deployments by vertically integrated service providers.
Market Dynamics
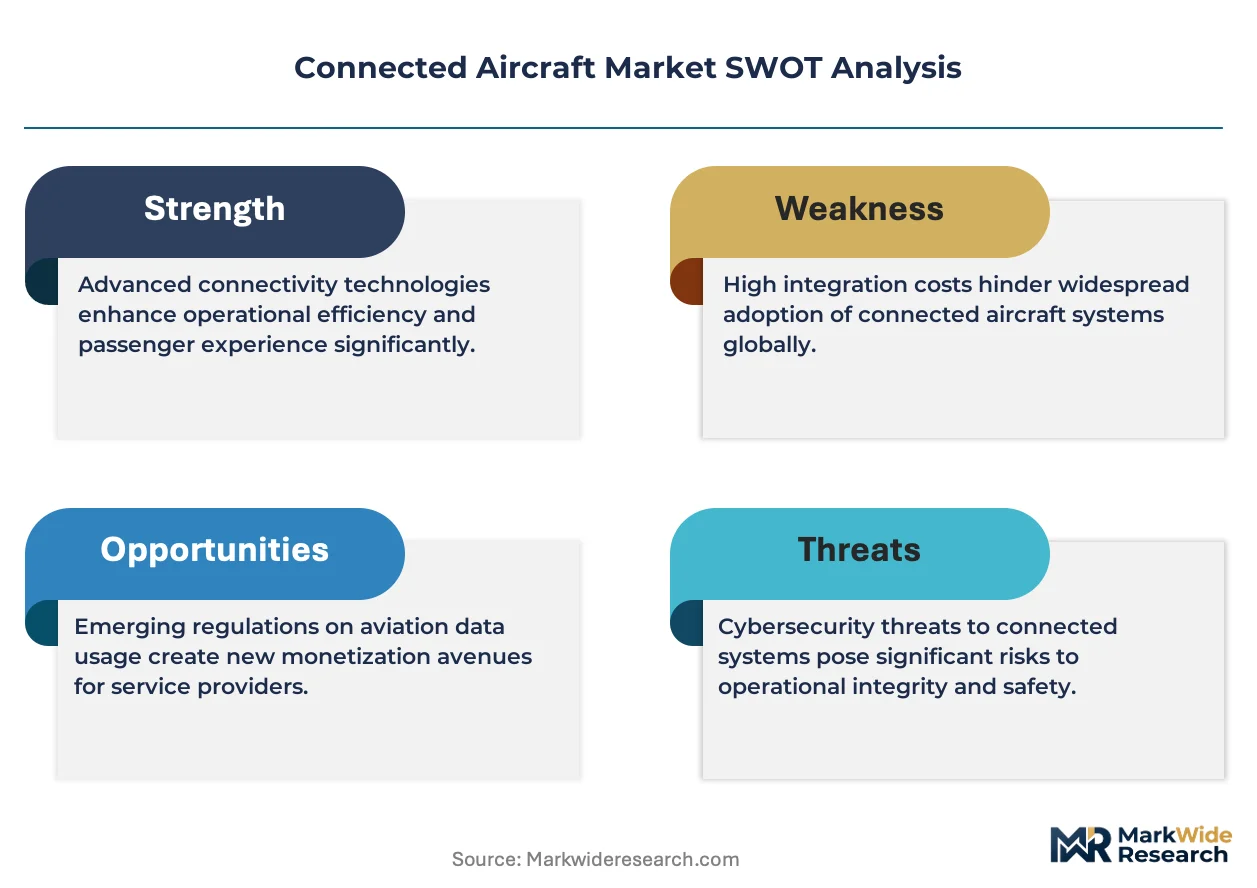
The connected aircraft market is being restructured by the FAA's ADS-B Out mandate under 14 CFR 91.225, which forces satellite communication hardware retrofits across the US-registered commercial fleet and creates immediate, non-discretionary demand for Ka/Ku-band terminal suppliers.
Growth Catalysts
- NextGen Modernization:The FAA's air traffic overhaul compels connectivity upgrades for trajectory-based operations and reduced separation standards in congested corridors.
- Condition-Based Maintenance:IoT sensor networks on engine and landing gear systems shift airlines from scheduled to predictive protocols, driving data throughput requirements.
- Passenger Expectation:Business travelers now treat gate-to-gate broadband as a booking criterion, pressuring narrow-body fleet retrofit commitments from major carriers.
Market Restraints
- Spectrum Scarcity:Ka-band congestion over North Atlantic routes limits concurrent high-bandwidth sessions per satellite footprint.
- Input Concentration:Gallium nitride semiconductor substrates for high-power amplifiers depend on a concentrated supply base in East Asian foundries.
- Airworthiness Security:EASA's ED-203/DO-326A certification timeline adds 18-24 months to European operator equipment approvals.
Strategic Opportunities
- Defense Dual-Use:MIL-STD-1553 and NATO STANAG 4586 interface requirements open military retrofit contracts for commercial-derivative platforms.
- Software-Defined Radios:Convergence of programmable waveform processors with satellite modems enables multi-constellation roaming without hardware swaps.
- India Fleet Expansion:IndiGo and Air India's narrow-body order backlogs create greenfield installation demand absent legacy equipment migration costs.
Industry Challenges
- Cybersecurity Talent Gap:Airborne network hardening against intrusion requires scarce aviation-specific security architects familiar with ARINC 664 and DO-326A.
- Retrofit Downtime Compression:Narrow-body aircraft must complete terminal installation during overnight maintenance windows to preserve daily utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Aircraft Market |
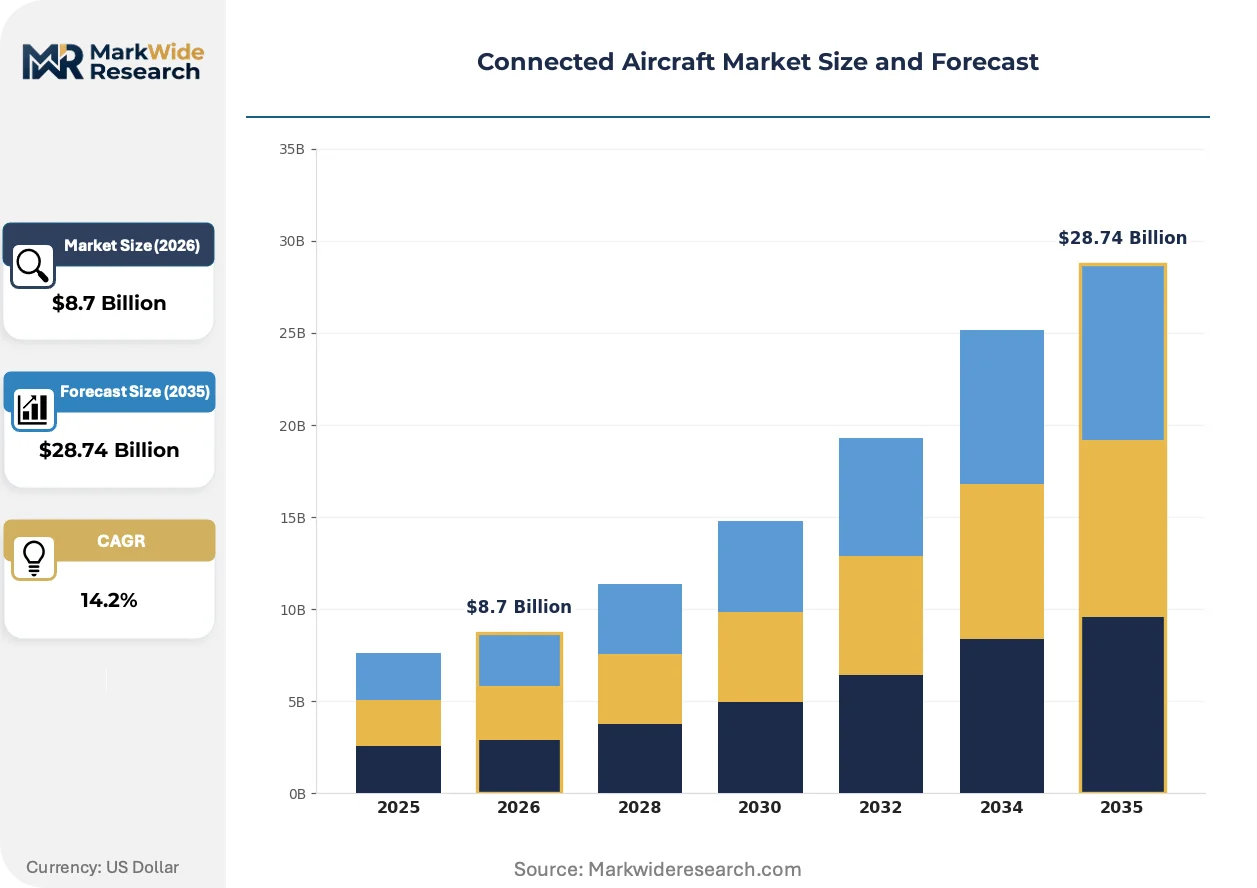
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Satellite Communication, In-flight Wi-Fi, Airborne Networking, IoT Sensors Application: Passenger Connectivity, Flight Operations, Maintenance Tracking, Cockpit Management End User: Airlines, Private Operators, Military, Charter Services Service Type: Data Management, Flight Support Services, Software Solutions, Communication Services |
| Companies Covered | Gogo, Viasat, Honeywell International, BAE Systems, Inmarsat, Thales Group, Collins Aerospace, SITA, Panasonic Avionics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Aircraft Market Emerging Trajectories
Virtualization of airborne networking functions is collapsing the traditional hardware stack and enabling software-defined service models that decouple connectivity from specific satellite constellations.
Software-defined wide area networking (SD-WAN) is virtualizing routing and traffic management functions that previously required dedicated avionics line-replaceable units. Low-cost carriers are adopting these platforms fastest to simplify multi-provider roaming across oceanic and terrestrial coverage zones. This virtualization is compressing equipment refresh cycles from seven years to three-year software subscription terms.
EASA's ED-203/DO-326A airworthiness security process specifications now mandate formal threat assessment and mitigation verification for all new connectivity installations. European operators face extended type certification timelines as suppliers revalidate hardware against these cybersecurity benchmarks. The regulation is reshaping supplier qualification most severely for dual-use military-commercial platforms where classified and unclassified networks must coexist.
Airlines are unbundling connectivity hardware procurement from long-term service contracts, reversing the bundled subscription model that dominated the 2015-2022 period. Procurement teams now negotiate terminal purchases separately from bandwidth commitments, treating satellite capacity as a commodity input. This disintermediation is most advanced among US legacy carriers with dedicated vendor management functions and sufficient fleet scale to justify direct constellation negotiations.
Connected Aircraft Market Segmentation
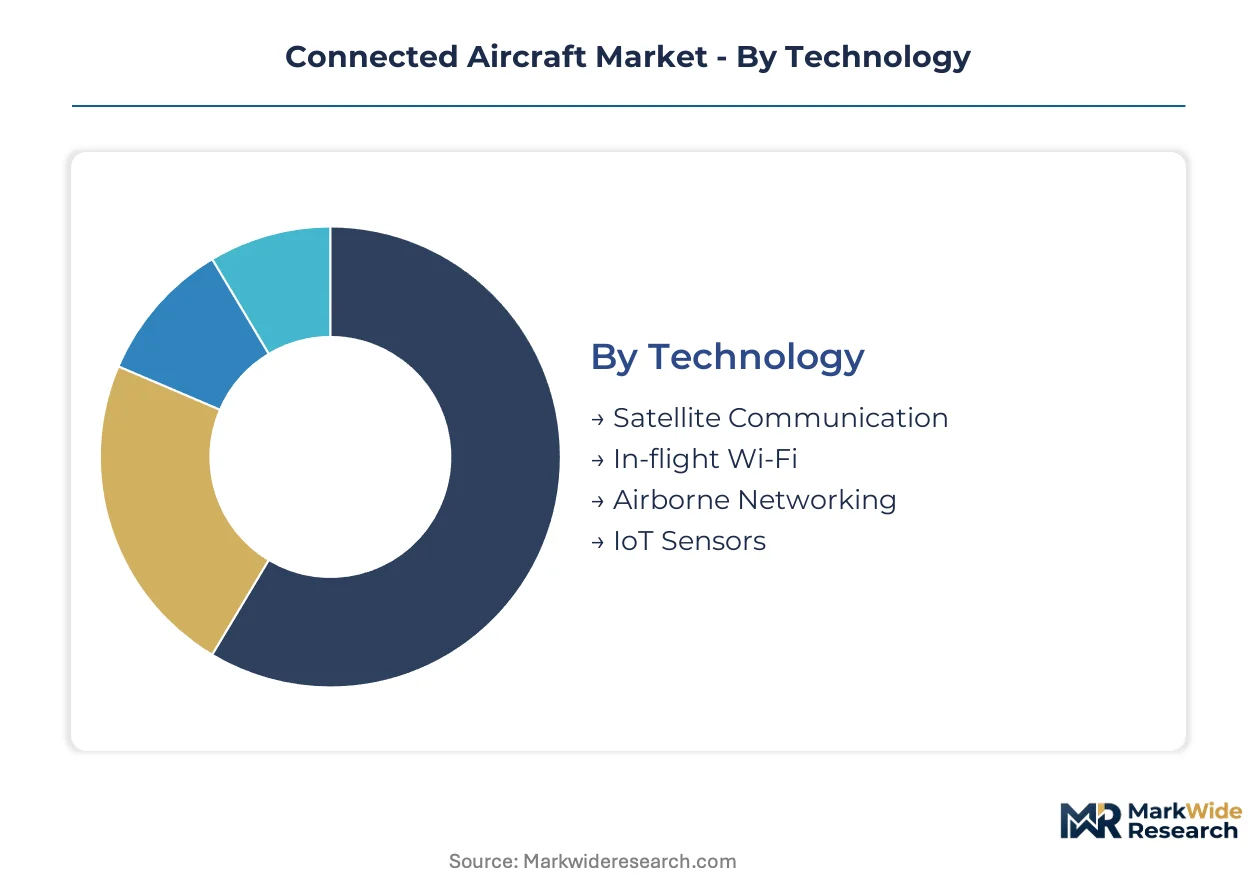
Connected aircraft procurement cycles vary dramatically across technology layers, with hardware refresh periods stretching to seven years while software subscriptions turn over every 18-36 months. Understanding these differential replacement rhythms helps suppliers align inventory and service revenue models with actual customer purchasing behavior.
Technology:
Satellite communication terminals exhibit the longest installed lifecycles, while sensor networks and networking software refresh at substantially compressed intervals.
- Satellite Communication:Ka/Ku-band and L-band transceiver systems integrate with aircraft avionics bays and antenna fairings, delivering 100+ Mbps throughput over oceanic and remote corridors. Demand concentrates among US legacy carriers retrofitting narrow-body fleets under FAA NextGen timelines, constrained by airframe downtime availability and STC certification lead times.
- IoT Sensors:Engine health monitoring nodes and landing gear strain gauges operate on condition-based protocols rather than scheduled replacement. Airlines in North America are prioritizing these installations to shift from calendar-driven to predictive maintenance, though sensor calibration cycles create recurring service touchpoints.
- In-flight Wi-Fi:Cabin distribution systems and passenger access points require refresh every 3-4 years as bandwidth expectations escalate. Low-cost carriers in India and Southeast Asia are driving greenfield demand absent legacy infrastructure migration costs.
- Airborne Networking:IP-based avionics data buses and router platforms virtualize routing functions previously handled by dedicated line-replaceable units. European operators face extended EASA ED-203/DO-326A cybersecurity certification timelines that compress effective deployment windows.
Satellite Communication anchors the volume base while IoT Sensors gains share at the steepest rate.
Application:
Margin profiles diverge sharply between passenger-facing services with commoditizing bandwidth and flight operations with quantifiable fuel savings per flight hour.
- Flight Operations:Trajectory optimization software and fuel management systems integrate with FMS platforms to deliver measurable cost reductions per departure. US network carriers are prioritizing these applications under FAA trajectory-based operations mandates, with deployment constrained by pilot training and procedural approval cycles.
- Passenger Connectivity:Gate-to-gate broadband services have shifted from premium ancillary to baseline expectation among business travelers. Narrow-body fleet commitments from major North American carriers are driving retrofit demand, though pricing pressure intensifies as airlines unbundle hardware from service contracts.
- Maintenance Tracking:Real-time engine parameter streaming and component lifecycle databases enable predictive intervention scheduling. Military operators through US Department of Defense procurement are expanding these capabilities on commercial-derivative platforms under MIL-STD-1553 interface requirements.
- Cockpit Management:Electronic flight bag integration and synthetic vision systems require hardened cybersecurity architectures. EASA airworthiness security specifications are reshaping supplier qualification timelines most severely for European operators.
Passenger Connectivity generates the largest addressable revenue pool while Flight Operations delivers the highest margin capture per installed unit.
End User:
Procurement sophistication and contract structures vary from military specification-driven tenders to charter operator spot purchases.
- Airlines:Full-service and low-cost carriers operate on fleet-scale deployment schedules with dedicated vendor management functions. US legacy carriers with sufficient scale are negotiating direct constellation agreements, disintermediating traditional service providers.
- Military:Defense procurement through US Department of Defense and NATO STANAG 4586 interfaces demands hardened dual-use platforms with classified-unclassified network segregation. Certification requirements segment addressable markets from commercial suppliers lacking security clearances.
- Private Operators:Business aviation fleets prioritize installation speed and minimal downtime over unit economics. Fractional ownership providers are consolidating purchasing power across managed fleets.
- Charter Services:Ad-hoc operators select connectivity solutions on trip-specific bases with limited forward commitment. Seasonal demand fluctuations complicate service provider capacity planning.
Airlines dominate absolute installation volumes while Military contracts command the longest contract durations and highest security premiums.
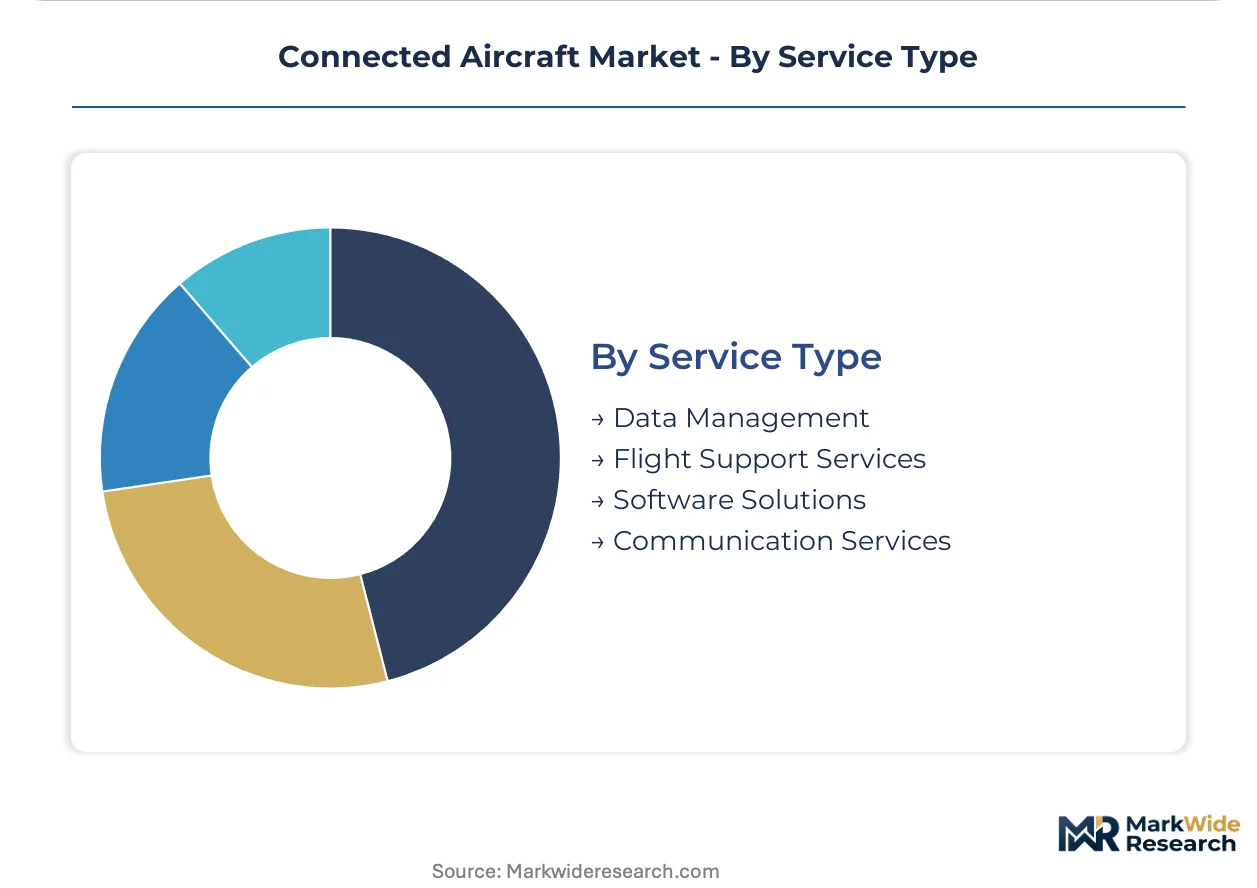
Service Type:
Revenue model evolution is shifting hardware vendors toward recurring software subscriptions and managed service arrangements.
- Communication Services:Satellite bandwidth provisioning and multi-constellation roaming agreements are increasingly unbundled from terminal hardware. Airlines with dedicated procurement teams are treating capacity as commodity input subject to annual renegotiation.
- Software Solutions:Predictive analytics platforms and flight optimization applications deploy on three-year subscription terms rather than perpetual licenses. This compression doubles customer touchpoint frequency versus traditional avionics refresh cycles.
- Data Management:Cloud-based storage and analytics pipelines for sensor-derived operational data require ongoing integration support. Cybersecurity hardening against intrusion demands scarce aviation-specific security architects familiar with ARINC 664 protocols.
- Flight Support Services:Real-time weather, NOTAM distribution, and ATC communication relay operate on mission-critical reliability requirements. Service level agreements specify 99.9% uptime guarantees with financial penalties for breach.
Communication Services represents the largest revenue category while Software Solutions is expanding most quickly as virtualization collapses traditional hardware refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connected aircraft deployment patterns diverge sharply by geography, with North American carriers prioritizing passenger broadband monetization while Asian operators emphasize predictive maintenance and flight operations optimization.
United States
FAA NextGen mandates and ADS-B Out requirements under 14 CFR 91.225 drive non-discretionary retrofit demand across the US-registered fleet. Major carriers in Dallas-Fort Worth and Atlanta are retrofitting narrow-body aircraft with Ka-band satellite terminals during overnight maintenance windows. Chicago-based maintenance providers report compressed installation schedules to preserve daily aircraft utilization rates.
China
Domestic carriers under MIIT oversight are expanding connected fleet deployments to support trajectory-based operations across congested air corridors. The Civil Aviation Administration of China enforces cybersecurity protocols for airborne data systems that mirror EASA ED-203 specifications. Shanghai Pudong and Beijing Capital airports serve as testbeds for integrated flight-ground data exchange platforms.
Germany
Lufthansa Group's fleet modernization anchors European demand for cybersecurity-hardened avionics under EASA ED-203/DO-326A certification timelines. The Federal Aviation Office enforces airworthiness security specifications that extend equipment approval cycles by 18-24 months. Hamburg and Munich maintenance clusters specialize in dual-use military-commercial platform retrofits.
India
IndiGo and Air India's narrow-body order backlogs create greenfield installation demand without legacy equipment migration costs. DGCA regulations align with ICAO standards for automatic dependent surveillance. Bengaluru and Hyderabad engineering hubs are scaling satellite terminal installation capacity to match fleet delivery schedules.
United Kingdom
BAE Systems and Rolls-Royce supply chain integration drives demand for military-grade connectivity on commercial-derivative platforms. The UK Civil Aviation Authority implements cybersecurity certification parallel to EASA frameworks. Farnborough and Bristol aerospace clusters concentrate on NATO STANAG 4586 interface compliance for dual-use aircraft.
Connected Aircraft Market Vendor Landscape
Capability concentration sits with defense-heritage specialists; scale advantage sits with commercial connectivity providers. The vendor base organizes around three tiers: vertically integrated satellite operators controlling constellation access, avionics incumbents bundling hardware with flight management integration, and pure-play service providers managing multi-constellation roaming agreements. Strategic moves center on unbundling hardware from long-term subscriptions and compressing equipment refresh cycles through software-defined architectures.
Within the defense-commercial dual-use tier, BAE Systems and Thales Group exemplify cybersecurity-hardened platform specialists. Gogo and Viasat occupy positions at the commercial service-provider end, with Gogo leveraging air-to-ground infrastructure for North American retrofit dominance and Viasat representing satellite constellation vertical integration. Honeywell International anchors the integrated avionics tier through flight management system bundling.
| Leading Market Players |
|---|
| Gogo |
| Viasat |
| Honeywell International |
| BAE Systems |
| Inmarsat |
| Thales Group |
| Collins Aerospace |
| SITA |
| Panasonic Avionics Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in East Asian gallium nitride foundries is compressing amplifier substrate pricing while simultaneously eroding supplier willingness to hold inventory, forcing terminal manufacturers toward dual-source qualification to maintain component availability for narrow-body retrofit programs.
Pricing Analysis
Long-term offtake agreements dominate satellite bandwidth procurement as airlines with dedicated vendor management functions negotiate direct constellation access, displacing the bundled hardware-subscription model that prevailed through 2022. Price differentiation rests on certification tier—EASA ED-203/DO-326A-compliant hardware commands substantial premiums over baseline FAA configurations—and fleet scale, with network carriers extracting volume discounts unavailable to fractional ownership providers. Pricing pressure stems from unbundling trends that expose hardware margins to commodity satellite capacity markets. Low-cost carriers exhibit acute price sensitivity, while military operators prioritize security premiums over unit economics.
Supply Chain Analysis
Gallium nitride semiconductor substrates feed from concentrated East Asian foundry capacity, with Japan and South Korea anchoring high-reliability amplifier production for Ka/Ku-band terminals. Raw material dependencies span rare earth elements for antenna ceramics, specialized aluminum alloys for radome fabrication, and precision-machined waveguide components. Single-source vulnerability concentrates in qualified GaN substrate suppliers meeting MIL-STD-1553 thermal specifications. Distribution runs through OEM-authorized maintenance clusters at Dallas-Fort Worth, Hamburg, and Bengaluru, with overnight installation windows dictating just-in-time terminal logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of aviation-cybersecurity architects familiar with ARINC 664 and DO-326A protocols is constraining European certification throughput and inflating implementation costs for dual-use platforms, creating structural advantage for incumbent suppliers with cleared personnel pipelines.
For Market Incumbents: Insulate terminal hardware margins by embedding software-defined radio architectures that extend equipment lifecycles beyond traditional seven-year refresh periods, countering disintermediation pressure from airlines negotiating direct constellation access. Prioritize backward integration into GaN amplifier substrate supply through joint development agreements with East Asian foundries, mitigating single-source exposure as retrofit demand concentrates in North American narrow-body fleets. For New Entrants and Emerging Players: Build out greenfield installation capabilities targeting IndiGo and Air India narrow-body delivery schedules, where absence of legacy equipment migration costs accelerates procurement cycles relative to retrofit-constrained competitors. Position software-defined networking platforms for low-cost carrier adoption in Southeast Asia, emphasizing multi-constellation roaming without hardware swap requirements as the primary go-to-market wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated satellite operators controlling constellation access and managing multi-tenant bandwidth provisioning, offering superior cash flow predictability versus hardware-centric terminal suppliers. Long-term viability favors acquisition targets with established EASA cybersecurity certification pipelines and military security clearances, as these barriers compound over the projection horizon. Watch for inflection in direct airline-constellation negotiation announcements as signal of service-provider margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Integration | Enables multi-constellation roaming without hardware swaps, extending terminal lifecycles for narrow-body retrofits. |
| Cybersecurity Certification Pipeline Investment | Accelerates EASA ED-203/DO-326A approval timelines, unlocking European operator procurement constrained by 18-24 month delays. |
| Direct Constellation Negotiation Capability | Allows network carriers to disintermediate traditional service providers, capturing bandwidth margin pools previously held by intermediaries. |
| Dual-Use Military-Commercial Platform Development | Opens MIL-STD-1553 and NATO STANAG 4586 retrofit contracts with security-premium pricing unavailable in commercial aviation. |
| Greenfield Installation Partnership in India | Captures IndiGo and Air India narrow-body delivery schedules absent legacy migration costs that compress retrofit margins elsewhere. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet engineering directors, MRO procurement managers, avionics certification specialists, and satellite service provider account executives, and refined through secondary validation against FAA ADS-B Out equipage databases, EASA airworthiness security bulletins, airline 10-K fleet disclosure filings, and International Telecommunication Union spectrum allocation records. Bottom-up terminal installation forecasts triangulated with top-down satellite bandwidth demand projections across the analysis window.
Demand-supply-balance framing anchored the quantitative model, with segmentation across technology layer, application priority, and end-user procurement sophistication—specifically distinguishing hardware refresh cycles from software subscription turnover rates, and retrofit-constrained from greenfield installation environments. CAGRs derived from fitted adoption curves calibrated to regulatory mandate deadlines and fleet delivery schedules, incorporating trajectory-based operations penetration and predictive maintenance protocol shift as aviation-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by satellite constellation operators into terminal manufacturing would shift outcomes materially. Cross-checking against FAA ADS-B equipage compliance reports and airline capital expenditure disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market