
 Defense Advanced GPS Receiver (DAGR) Market | 2026-2036
Defense Advanced GPS Receiver (DAGR) Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Advanced GPS Receiver (DAGR) Market Insights
Gallium nitride is realigning radio-frequency front-end economics in next-generation DAGR units by replacing legacy gallium arsenide amplifiers with higher power-efficiency substrates. Rockwell Collins leverages in-house semiconductor foundry partnerships to control wafer supply for military-grade RF components. Northrop Grumman anchors its position through sustained R&D allocation toward multi-band anti-jam architectures. BAE Systems competes on geographic dominance, with production lines serving UK Ministry of Defence and Commonwealth export programs.
The Defense Advanced GPS Receiver constitutes a militarized handheld or platform-integrated terminal that processes encrypted P(Y)-code and emerging M-Code signals across L1/L2 frequencies, achieving cold-start acquisition under fifty seconds in denied environments. Its primary purpose is to provide assured position-navigation-timing data to dismounted soldiers and weapons platforms when satellite constellations face jamming or spoofing threats. Handheld receivers occupy the largest revenue pool due to soldier-modernization budgets, while airborne systems represent the fastest-expanding category as manned and unmanned platforms integrate anti-jam GPS into flight-critical avionics. Multi-band receiver technology concentrates margin pools where contractors combine encrypted signal processing with high-sensitivity acquisition engines for contested spectrum operations.
The U.S. Department of Defense, NATO Standardization Office, and EU Electronic Warfare standards frameworks collectively shape DAGR procurement through interoperability mandates and electromagnetic resilience certification requirements. FAA and FCC regulations indirectly influence dual-use export variants by restricting civilian signal-processing capabilities in military hardware sold abroad. Stakeholders must monitor M-Code deployment timelines and allied nation encryption-key agreements to align production capacity with shifting procurement windows.
Market Dynamics
Gallium nitride RF amplifiers are compressing power budgets while M-Code mandates force hardware refresh cycles across NATO arsenals, creating simultaneous pull on next-generation receiver architectures.
Growth Catalysts
- U.S. DoD M-Code Mandate:Military departments must field M-Code-capable terminals by operational deadlines, accelerating replacement of legacy P(Y)-code equipment across ground and airborne platforms.
- Indo-Pacific Theater Demand:Contested electromagnetic environments in the South China Sea and Taiwan Strait drive procurement of anti-jam receivers for dismounted special operations forces.
- Gallium Nitride Substrate Adoption:Higher power-efficiency RF front-ends extend battery life in handheld units while reducing thermal signatures detectable by adversary sensors.
Market Restraints
- Semiconductor Foundry Concentration:Military-grade GaN wafer supply clusters in U.S. and Japanese foundries, exposing programs to single-source fragility during geopolitical tension.
- Encryption Key Management Complexity:Bilateral key-sharing agreements between NATO members and partner nations create certification bottlenecks that delay fielding schedules.
- SWaP-C Tradeoffs:Size, weight, power, and cost constraints limit integration of multi-band anti-jam architectures into legacy soldier-worn systems without platform redesign.
Strategic Opportunities
- Unmanned Platform Integration:Group 1-3 UAVs and loitering munitions represent untapped demand for miniaturized DAGR modules with embedded anti-spoofing engines.
- EU Electronic Warfare Standards Alignment:The EU's emerging electromagnetic resilience certification framework creates harmonized procurement pathways for cross-border joint programs.
- Multi-Constellation Receiver Convergence:Combining GPS with Galileo PRS and QZSS signals in single terminals opens allied interoperability contracts previously locked to single-system vendors.
Industry Challenges
- Secure Firmware Talent Scarcity:Cryptographic implementation expertise for M-Code signal processing remains concentrated among cleared personnel pools in U.S. defense corridors.
- Legacy System Integration Friction:Backward compatibility requirements with Vietnam-era radio mounts and power interfaces constrain industrial design freedom for next-generation form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Advanced GPS Receiver (DAGR) Market |
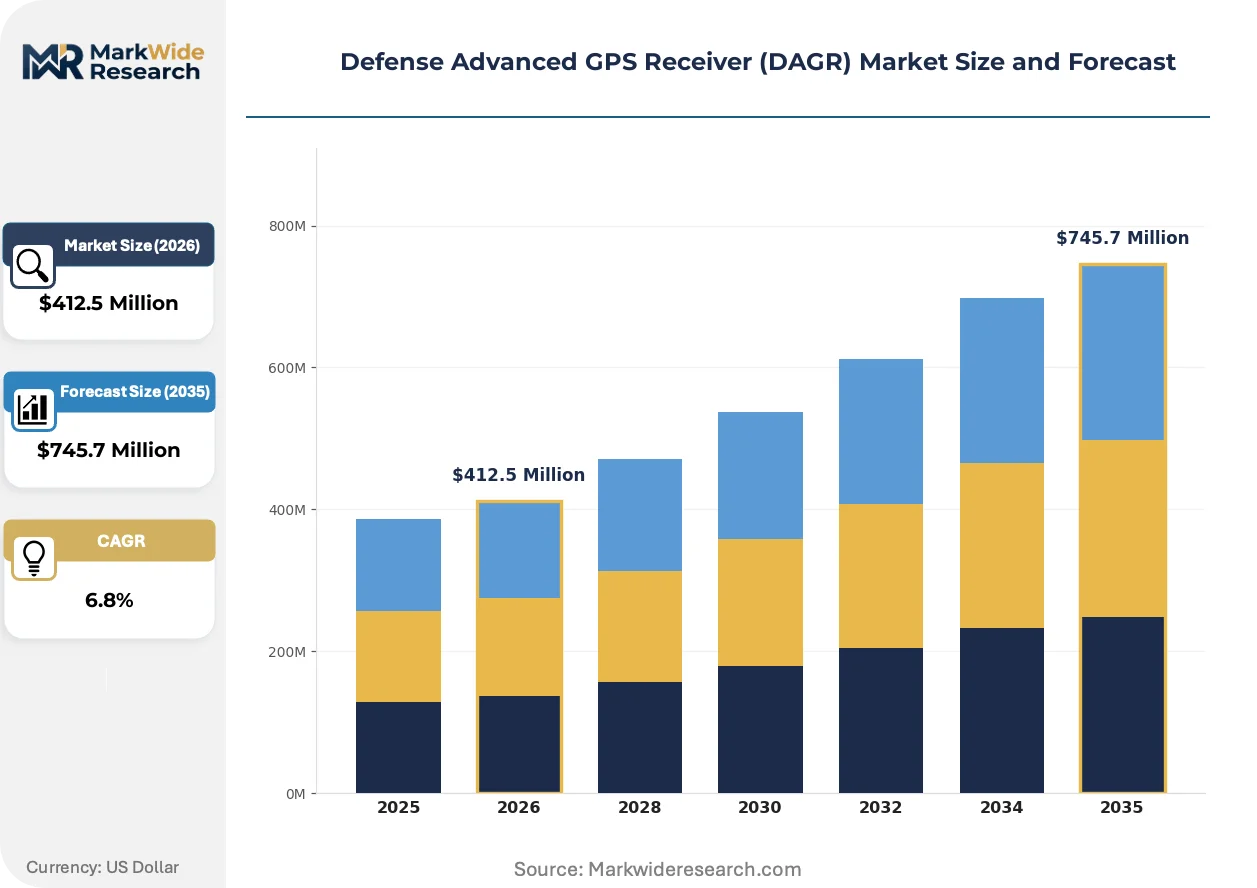
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Receivers, Vehicle-Mounted Units, Airborne Systems, Portable Modules Technology: Encrypted Signal Processing, Anti-Jamming, High-Sensitivity, Multi-Band Receivers, Cold Start Optimization Application: Navigation Assistance, Target Acquisition, Artillery Coordination, Search and Rescue, Mission Planning End User: Military Personnel, Defense Contractors, Intelligence Agencies, Special Forces, Law Enforcement Units |
| Companies Covered | Rockwell Collins, Northrop Grumman, BAE Systems, Hertz Systems, Thales Group, Raytheon Technologies, L3 Technologies, Mayflower Communications, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Advanced GPS Receiver (DAGR) Market Trends and Innovations
Receiver architectures are converging around software-defined signal processing that collapses multiple hardware functions into reprogrammable firmware, compressing upgrade cycles from years to months.
Multi-band digital beamforming is unifying L1/L2/M-Code acquisition into single RF chains, eliminating redundant front-end components. Special Forces units in Australia and the United Kingdom are piloting these consolidated terminals for reduced loadout weight. The technology is unifying previously separate anti-jam and standard-precision modules into common hardware platforms, forcing vendors to compete on firmware differentiation rather than discrete circuit design.
The EU Electronic Warfare standards framework is mandating electromagnetic resilience certification for all military GPS equipment procured through pooled defense funds. This regulatory pressure is compressing vendor qualification timelines and elevating documentation burdens for non-EU suppliers. Airborne platforms operating across European theaters face the steepest compliance ramps, with integrators redesigning avionics bays to accommodate certified receiver form factors.
Defense ministries are consolidating procurement through framework contracts that bundle hardware, encryption-key lifecycle management, and depot-level maintenance into single vendor relationships. This buyer-behavior shift is displacing transactional spot purchases of receivers alone. The United Kingdom Ministry of Defence and Australian Defence Force have adopted this model most aggressively, locking in five-year managed service agreements that transfer obsolescence risk to contractors.
Defense Advanced GPS Receiver (DAGR) Market Segmentation
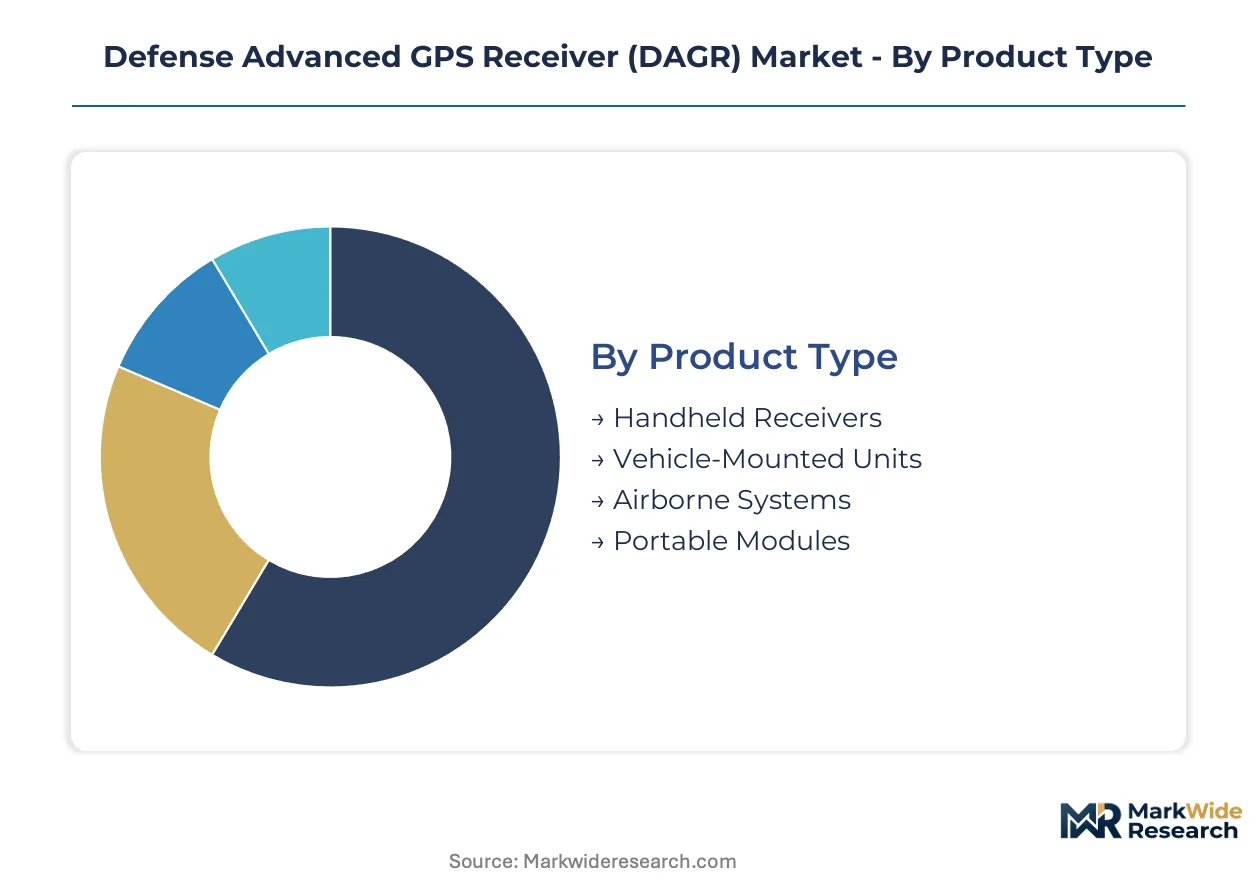
DAGR procurement splits across platform integration depth, electromagnetic resilience requirements, mission-critical applications, and cleared user categories. Each segmentation axis reflects distinct certification pathways, encryption-key hierarchies, and operational deployment constraints that shape vendor positioning and contract structures.
Product Type:
Standardization dominates soldier-worn configurations while vehicle and airborne platforms demand customized form-factor integration against legacy power and mounting interfaces.
- Handheld Receivers:Battery-operated terminals processing L1/L2/M-Code signals with sub-fifty-second cold-start acquisition. Soldier-modernization budgets in the United States and United Kingdom concentrate procurement here, driven by dismounted infantry modernization programs and special forces loadout reductions.
- Airborne Systems:Flight-critical avionics modules integrating anti-jam GPS into manned and unmanned platform navigation suites. Integration into Group 1-3 UAVs and loitering munitions in the Indo-Pacific theater accelerates demand, as contested electromagnetic environments mandate assured position-navigation-timing for beyond-line-of-sight operations.
- Vehicle-Mounted Units:Ruggedized terminals hardened against platform vibration and thermal cycling for armored and tactical vehicle integration.
- Portable Modules:Modular receiver units adaptable across temporary installations and expeditionary command posts requiring rapid deployment.
Leading the category by volume: Handheld Receivers. Expanding most quickly: Airborne Systems.
Technology:
Cost tiers separate legacy P(Y)-code architectures from premium M-Code-capable systems with gallium nitride RF front-ends and software-defined signal processing.
- Multi-Band Receivers:Unified L1/L2/M-Code acquisition chains eliminating redundant front-end components through digital beamforming. Australian and United Kingdom special forces pilot these consolidated terminals, compressing anti-jam and standard-precision modules into common hardware platforms.
- Encrypted Signal Processing:Cryptographic engines for P(Y)-code and M-Code signal authentication with tamper-resistant firmware. United States Department of Defense procurement deadlines for M-Code compatibility concentrate demand here, accelerating hardware refresh cycles across NATO arsenals.
- Anti-Jamming:Spatial and temporal filtering architectures suppressing intentional interference in contested spectrum environments.
- High-Sensitivity:Extended correlation engines enabling signal acquisition under foliage canopy and urban canyon conditions.
- Cold Start Optimization:Rapid ephemeris and almanac recovery protocols for denied-environment initialization.
Margin concentrates in Multi-Band Receivers. Steepest expansion trajectory: Encrypted Signal Processing.
Application:
Customer type stratification separates tactical operators requiring real-time navigation from indirect-fire coordinators and intelligence analysts with distinct latency and precision tolerances.
- Navigation Assistance:Real-time position-navigation-timing feeds for dismounted soldier situational awareness and route planning. Contested electromagnetic environments in the South China Sea and Taiwan Strait drive Indo-Pacific procurement, where denied GPS conditions threaten force maneuverability.
- Target Acquisition:Precision coordinate generation for sensor-to-shooter chains and close air support coordination. Special operations forces in NATO member states expand encrypted handheld unit procurement here, integrating DAGR output with laser designators and digital fire support systems.
- Artillery Coordination:Survey and registration support for indirect-fire platforms requiring geodetic precision.
- Search and Rescue:Distress beacon localization and recovery team coordination in denied or degraded communications environments.
- Mission Planning:Pre-operation route analysis and time-space force management in command elements.
Deployment frequency highest in Navigation Assistance. Climbing the fastest: Target Acquisition.
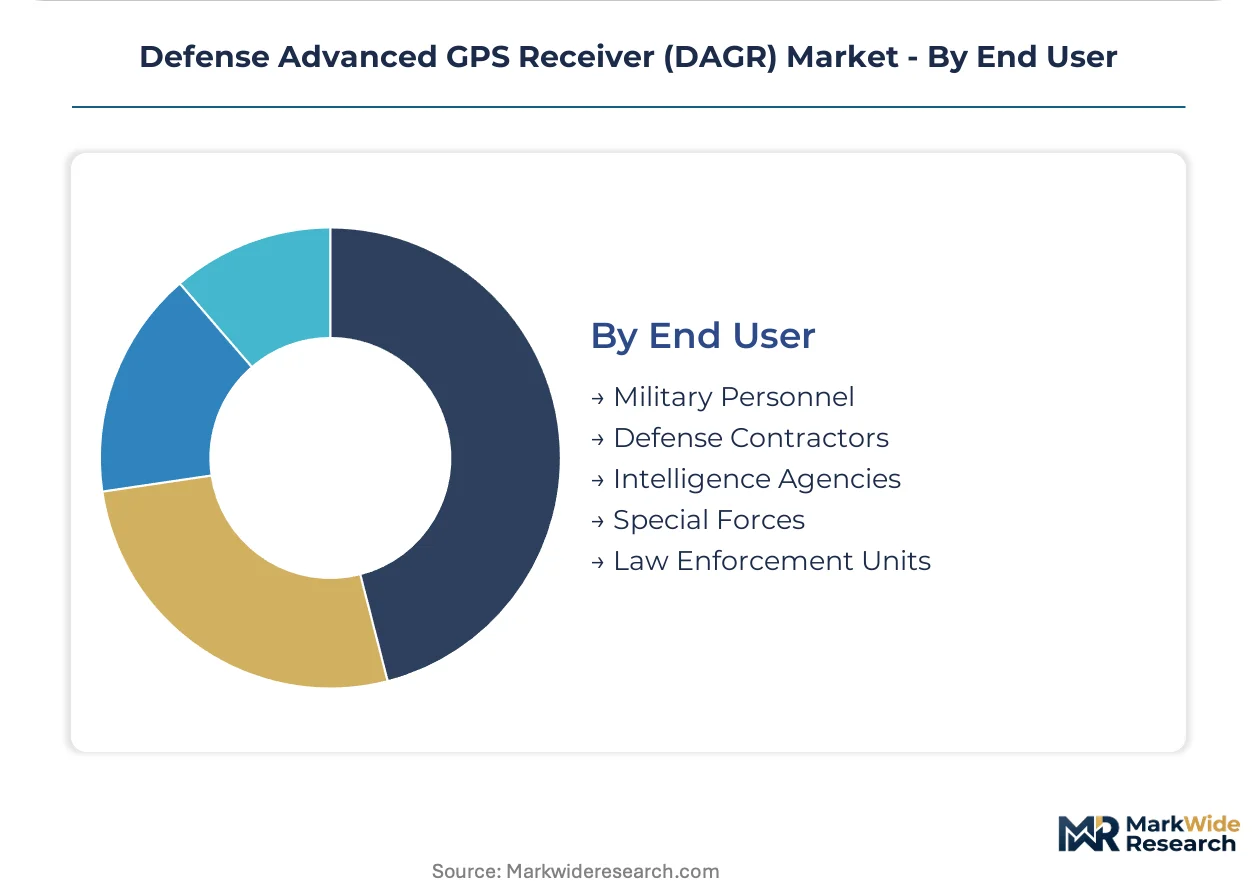
End User:
Maturity gradients separate cleared defense personnel with access to cryptographic key material from law enforcement and contractor categories operating under restricted encryption tiers.
- Military Personnel:Standard-issue terminals for conventional force elements across army, navy, marine, and air service branches. United States Department of Defense M-Code mandate timelines accelerate fielding schedules here, with operational deadlines forcing replacement of legacy P(Y)-code equipment.
- Special Forces:Tier-one operators requiring minimized size-weight-power signatures and enhanced anti-spoofing capabilities. NATO special operations command procurement concentrates demand in this segment, with bilateral key-sharing agreements creating certification bottlenecks that constrain supply.
- Defense Contractors:System integrators and platform manufacturers embedding DAGR modules into weapon systems and vehicles.
- Intelligence Agencies:Clandestine operators with specialized requirements for low-probability-of-intercept signal acquisition.
- Law Enforcement Units:Domestic security forces operating under civilian regulatory constraints with degraded encryption access.
Procurement volume concentrates with Military Personnel. Gaining share fastest: Special Forces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense Advanced GPS Receiver procurement concentrates in jurisdictions with active special operations modernization programs and contested electromagnetic environment exposure. National security tax incentives in the United States accelerate domestic foundry capacity for military-grade gallium nitride substrates. Allied encryption-key sharing agreements create procurement clusters where bilateral defense treaties align with industrial base access.
United States
The U.S. Department of Defense M-Code mandate drives hardware refresh cycles across Army, Navy, Marine Corps, and Air Force platforms. FCC and FAA regulations shape dual-use export variants by restricting civilian signal-processing capabilities in military hardware sold abroad. Defense contractors in Arizona and California concentrate gallium nitride foundry partnerships for RF front-end production serving NATO arsenals.
United Kingdom
UK Ministry of Defence framework contracts bundle hardware, encryption-key lifecycle management, and depot-level maintenance into single vendor relationships. The country's national defense procurement regulator mandates electromagnetic resilience certification for all military GPS equipment. Production lines in Scotland and England serve Commonwealth export programs with anti-jam receiver architectures.
Australia
Australian Defence Force five-year managed service agreements transfer obsolescence risk to contractors while accelerating special forces loadout modernization. The country's defense procurement framework emphasizes interoperability with Five Eyes intelligence-sharing partners. Industrial activity in Victoria and New South Wales concentrates on miniaturized DAGR modules for Group 1-3 UAV integration.
Germany
Bundeswehr procurement prioritizes multi-constellation receivers combining GPS with Galileo PRS signals for allied interoperability. The EU Electronic Warfare standards framework mandates electromagnetic resilience certification for equipment procured through pooled defense funds. Bavaria-based system integrators redesign avionics bays to accommodate certified receiver form factors for airborne platforms.
Japan
Japan Ministry of Defense procurement accelerates anti-jam GPS integration into manned and unmanned platforms for Indo-Pacific theater operations. METI industrial policy supports domestic RF component supply chains for military-grade receiver production. Manufacturing clusters in the Nagoya and Tokyo regions focus on high-sensitivity acquisition engines for contested spectrum environments.
Defense Advanced GPS Receiver (DAGR) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators capturing premium margins in airborne platforms while component suppliers serve volume handheld markets. The vendor base concentrates around defense primes with in-house semiconductor foundry access and sustained R&D allocation toward multi-band architectures. Three archetypes dominate: gallium nitride substrate specialists, encryption-key lifecycle managers, and software-defined signal processing integrators. Competitive moves center on strategic partnerships for wafer supply security and geographic expansion through Commonwealth and NATO framework contract capture.
Within the defense prime tier, Rockwell Collins, Northrop Grumman, and BAE Systems occupy positions reflecting distinct competitive vectors. Rockwell Collins exemplifies the foundry-integrated archetype through captive gallium nitride wafer supply chains. Northrop Grumman anchors the multi-band anti-jam specialization segment with sustained R&D concentration. BAE Systems represents geographic dominance through UK Ministry of Defence and Commonwealth export program alignment. These three entities collectively illustrate how vendor positioning stratifies around semiconductor supply security, firmware differentiation, and bilateral defense treaty access rather than discrete hardware competition alone.
| Leading Market Players |
|---|
| Rockwell Collins |
| Northrop Grumman |
| BAE Systems |
| Hertz Systems |
| Thales Group |
| Raytheon Technologies |
| L3 Technologies |
| Mayflower Communications |
| General Dynamics |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride wafer costs cascade through DAGR manufacturing tiers, with U.S. and Japanese foundry premiums compressing margins on handheld units while captive supply arrangements insulate integrated primes from spot-market volatility. Defense ministries absorb these input costs through multi-year framework contracts that bundle hardware, encryption-key lifecycle management, and depot-level maintenance into single vendor relationships.
Pricing Analysis
Lead-time premiums dominate DAGR procurement economics, with urgent operational requirements for M-Code-capable terminals commanding substantial markups over standard-delivery schedules. Three-tier pricing structure across mission-critical airborne, standard soldier-worn, and economy export-restricted levels separates certification-grade tiers. Pricing pressure stems from gallium nitride foundry capacity constraints as U.S. Department of Defense deadlines accelerate demand. Special Forces units exhibit lowest price sensitivity due to minimized size-weight-power requirements, while conventional military personnel procurement shows higher elasticity under consolidated defense budgets.
Supply Chain Analysis
Domestic-content mandates in U.S. and Japanese defense procurement regulations are reshaping sourcing patterns for military-grade RF components. Gallium nitride wafer supply concentrates in U.S. and Japanese foundries, with silicon-germanium and indium phosphide serving legacy P(Y)-code architectures. Single-source vulnerability pervades the tier-one foundry tier, where geopolitical tension threatens wafer allocation for NATO arsenals. Distribution runs through prime contractor integration channels rather than component spot markets, with BAE Systems, Rockwell Collins, and Northrop Grumman controlling downstream assembly and firmware loading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. Department of Defense M-Code mandate operates as a cost-of-compliance moat, elevating barriers for non-cleared vendors while concentrating margin pools among primes with cryptographic implementation expertise and bilateral key-sharing agreements.
For Market Incumbents: Deepen captive gallium nitride foundry partnerships to secure wafer allocation against single-source fragility, while accelerating firmware differentiation investments to compete as hardware platforms consolidate. Emerging software-defined signal processing integrators threaten discrete circuit design margins. Vertical integration into semiconductor supply chains represents the critical defensive lever. For New Entrants and Emerging Players: Capture unmanned platform integration white space in Group 1-3 UAVs and loitering munitions, where miniaturized DAGR modules with embedded anti-spoofing engines face limited incumbent penetration. The Indo-Pacific theater offers the most penetrable geography given contested electromagnetic environment demand and less consolidated procurement frameworks. A go-to-market angle through Australian Defence Force five-year managed service agreements bypasses direct prime competition. For Investors and Strategic Acquirers: EU Electronic Warfare standards framework certification timelines are the leading indicator that electromagnetic resilience compliance capabilities will concentrate acquisition value in the defense electronics segment. Long-term viability over the projection horizon favors targets with in-house cryptographic firmware talent and multi-constellation receiver architectures. Watch for bilateral NATO encryption-key agreement expansions as the inflection signal for contract flow acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Receiver Convergence | Combining GPS with Galileo PRS signals opens allied interoperability contracts previously locked to single-system vendors. |
| Gallium Nitride Foundry Partnership | Captive wafer supply arrangements insulate primes from spot-market volatility in U.S. and Japanese semiconductor channels. |
| Software-Defined Signal Processing Migration | Collapsing hardware functions into reprogrammable firmware compresses upgrade cycles from years to months for fielded units. |
| Framework Contract Consolidation | UK Ministry of Defence and Australian Defence Force bundled agreements transfer obsolescence risk while locking five-year revenue streams. |
| M-Code Certification Investment | U.S. Department of Defense operational deadlines for encrypted signal compatibility accelerate hardware refresh cycles across NATO arsenals. |
Research Methodology
Multi-period observation of M-Code deployment timelines, gallium nitride foundry capacity allocations, and NATO encryption-key agreement expansions anchored the trend analysis, supplemented by interviews with defense procurement officers, RF component engineering directors, special forces equipment program managers, and electromagnetic resilience certification leads. Secondary validation drew from U.S. Department of Defense budget justification documents, EU Electronic Warfare standards framework publications, FCC and FAA regulatory filings, and customs trade data for military-grade semiconductor imports. Bottom-up unit economics triangulated against top-down defense expenditure forecasts across the analysis window.
Input-output matrices mapped gallium nitride wafer supply through RF front-end assembly to finished DAGR unit production, with segmentation dimensions spanning platform integration depth, electromagnetic resilience certification tier, and end-user clearance category. CAGRs derived from deployment schedule phasing against procurement framework renewal cycles. Industry-specific forecast inputs included M-Code operational deadline acceleration rates and bilateral key-sharing agreement negotiation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical disruption of U.S.-Japan foundry supply chains and EU Electronic Warfare standards framework implementation delays. Forecasts reflect documented assumptions regarding encryption-key management complexity and semiconductor foundry concentration risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market