
 Air Traffic Control Market | 2026-2036
Air Traffic Control Market Size, Share, and Industry Trends Forecast 2026-2036
Air Traffic Control Market Analysis
FAA NextGen is recalibrating the cost-of-entry calculus for domestic air traffic modernization, forcing legacy system vendors to demonstrate interoperability with satellite-based trajectory management. L3Harris Technologies leverages its vertical integration across surveillance and communication payloads to sustain program wins on long-term federal contracts. Thales Group anchors European export competitiveness through certified automation platforms that compete directly in NATO-aligned procurement channels.
Air traffic control encompasses the ground-based and airborne systems that manage aircraft separation, sequencing, and flow across controlled airspace, integrating primary and secondary radar with VHF voice relay and automatic dependent surveillance-broadcast transponders operating on 1090 MHz to maintain safe longitudinal and lateral spacing. Automated Systems within the Technology dimension are displacing legacy radar consoles as the fastest-growing category, while Ground-Based Control retains the largest installed base and associated maintenance revenue pool. Within End User segmentation, Government Agencies command the deepest procurement budgets, though Airports represent the most fragmented and price-sensitive buyer set across municipal and regional authorities.
The FAA, EUROCONTROL, and ICAO collectively enforce interoperability standards that determine product certification pathways and cross-border system compatibility for any vendor seeking multi-jurisdictional deployment. EASA's certification requirements for safety-critical software add substantial validation costs that filter out smaller suppliers from European tender processes. Stakeholders must weigh the capital intensity of remote tower virtualization against the operational flexibility these Cloud-Based deployments offer to low-density airfields.
Market Dynamics
Satellite-based surveillance architectures are dismantling the radar-centric procurement models that defined air traffic modernization for five decades, forcing infrastructure operators to revalue ground-based assets against orbital alternatives.
Growth Catalysts
- FAA NextGen Mandate:The Federal Aviation Administration's trajectory-based operations directive compels domestic operators to replace aging radar consoles with ADS-B and data-link systems across congested corridors.
- Remote Tower Virtualization:Cloud-Based deployment models enable low-density airfields to consolidate air traffic services through centralized sensor feeds, reducing per-site infrastructure expenditure.
- EUROCONTROL Interoperability Standards:Cross-border harmonization requirements drive synchronized procurement cycles among NATO-aligned member states, creating bundled tender opportunities for integrated surveillance platforms.
Market Restraints
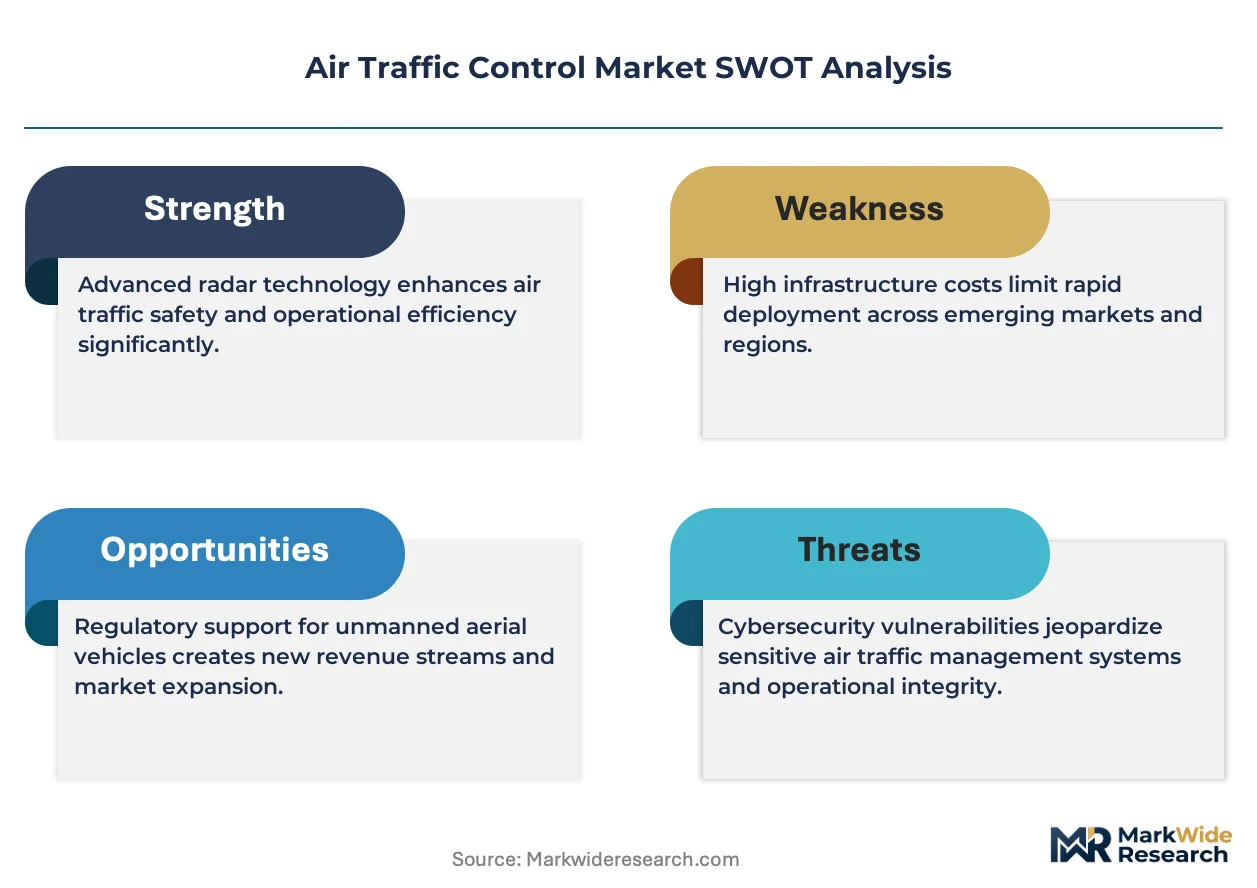
- Certification Cost Burden:EASA's DO-178C software validation requirements for safety-critical automation impose multi-year validation timelines that exclude smaller developers from European tenders.
- Legacy System Entrenchment:Ground-Based Control installations from the 1980s-1990s retain functional service life, depressing replacement demand despite performance limitations.
- RF Spectrum Congestion:VHF voice relay and 1090 MHz transponder channels face interference saturation in high-density terminal areas, constraining capacity expansion without frequency reallocation.
Strategic Opportunities
- Unmanned Aircraft System Integration:Beyond-visual-line-of-sight drone corridors require new separation management protocols, opening automation contracts for mixed-use airspace in the United States.
- Urban Air Mobility Infrastructure:Vertiport control systems for electric vertical take-off aircraft represent greenfield deployment categories without incumbent vendor relationships.
- ICAO Global Aeronautical Distress and Safety System:The international mandate for autonomous distress tracking creates retrofit demand for ADS-B In capability across commercial fleets.
Industry Challenges
- Controller Workforce Shortage:FAA and EUROCONTROL training pipelines fail to replace retiring certified professionals, compressing implementation timelines for new automation interfaces.
- Cyber-Physical Security Convergence:IP-enabled surveillance networks expose legacy ground systems to ransomware vectors previously isolated from air-gapped radar architectures.
- Multi-Vendor Integration Complexity:Procurement fragmentation across communication, navigation, and surveillance subsystems generates interoperability failures during commissioning phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Traffic Control Market |
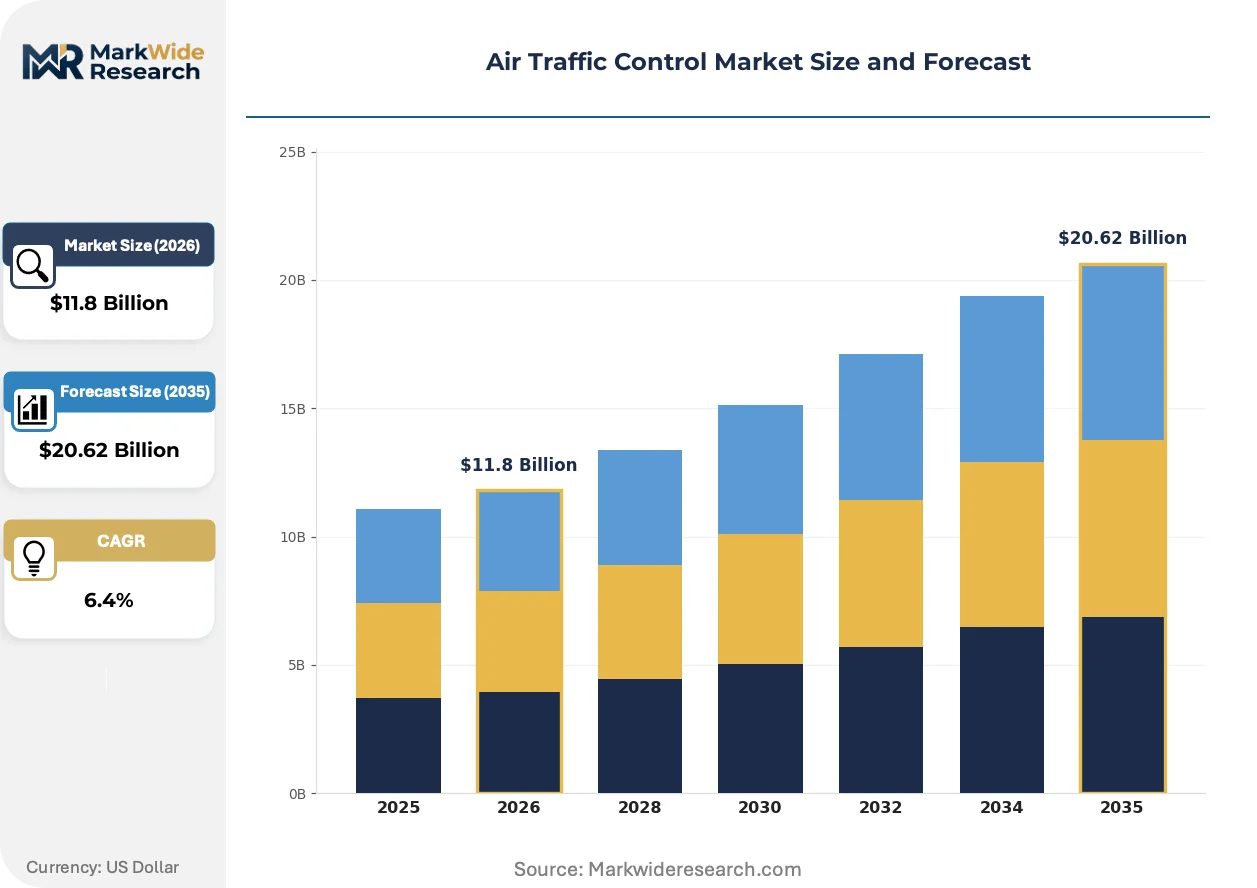
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, Satellite Communication, Ground-Based Control, Automated Systems End User: Airports, Airlines, Government Agencies, Military Service Type: Air Traffic Management, Communications Services, Navigation Services, Surveillance Services Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Remote Management |
| Companies Covered | L3Harris Technologies Inc., BAE Systems PLC, Thales Group, Northrop Grumman Corporation, Frequentis AG, Raytheon Technologies Corporation, Indra Sistemas S.A., Saab AB, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Traffic Control Market Emerging Trajectories
Automation architectures are compressing the human-in-the-loop role from tactical separation assurance toward strategic flow management, reallocating capital toward predictive analytics and machine-learning trajectory optimization.
Artificial intelligence-based conflict detection systems are integrating probabilistic trajectory modeling with real-time weather feeds to generate resolution advisories before conventional radar alerts trigger. Major ANSPs in the United States and Germany are piloting these platforms for oceanic and remote airspace sectors where radar coverage gaps persist. The technology is integrating predictive capabilities that reduce controller workload per aircraft by automating routine sequencing decisions.
EUROCONTROL's Single European Sky ATM Research deployment mandates are accelerating the transition from fixed airspace structures to dynamic sector configurations based on traffic demand. The regulation compels member states to dismantle national airspace boundaries and implement functional airspace blocks by performance targets. Air navigation service providers in France, Germany, and the Netherlands are consolidating control centers to meet interoperability requirements.
Municipal airport authorities are unbundling long-term maintenance contracts from initial system procurement, creating discrete service markets for automation software updates and sensor calibration. This purchasing pattern shift fragments vendor revenue streams and elevates lifecycle cost transparency in tender evaluations. The phenomenon is most visible across regional airports in Spain and Italy where budget constraints dominate capital planning cycles.
Air Traffic Control Market Segmentation
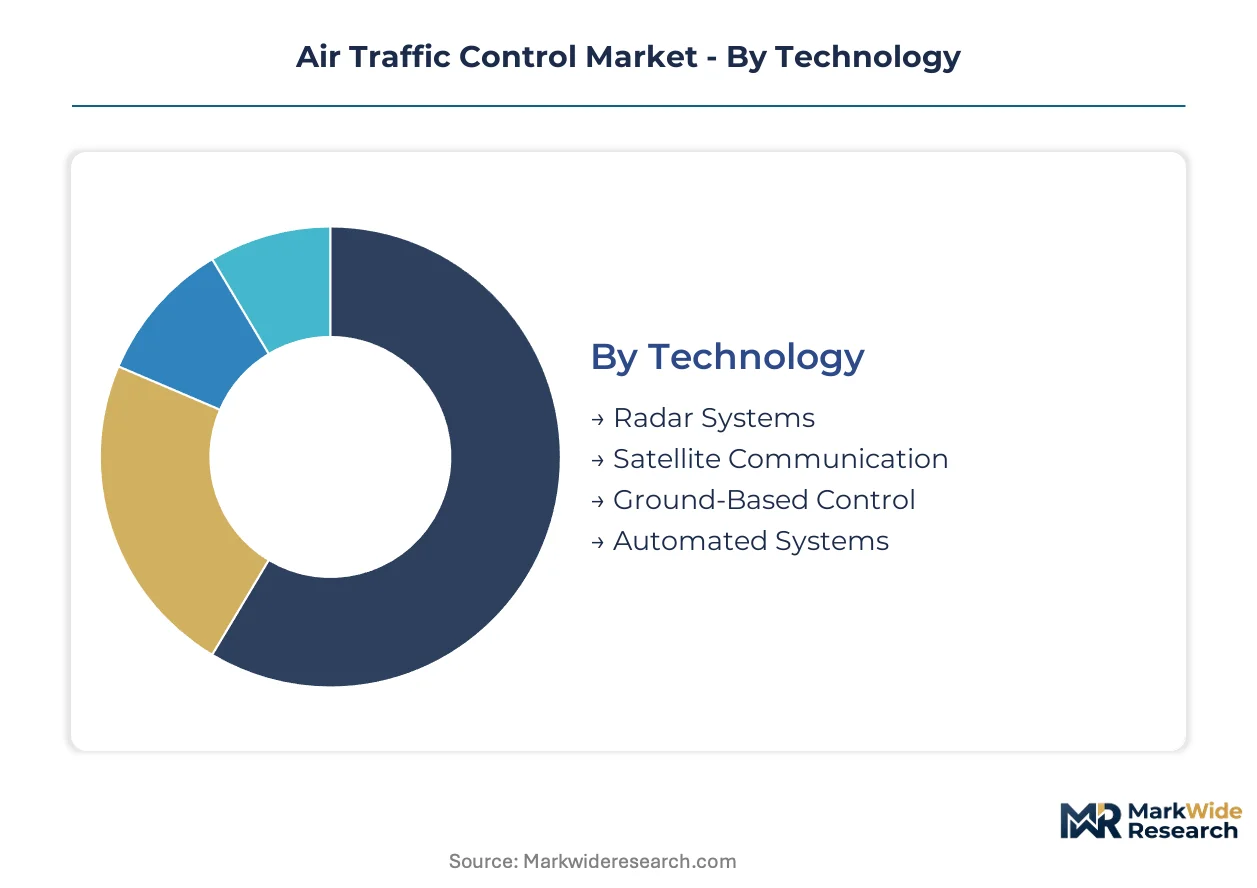
Air traffic control procurement splits across incompatible technology generations and divergent buyer budgets, forcing vendors to maintain parallel product lines. Segmentation reveals where federal mandates override cost sensitivity and where commercial operators retain discretion over refresh cycles.
Technology:
Capital intensity varies by an order of magnitude across these segments, with orbital infrastructure and automation platforms demanding sustained R&D commitment while legacy radar installations amortize over decades.
- Automated Systems:Machine-learning trajectory optimization and conflict detection algorithms reduce controller workload per aircraft. FAA NextGen procurement concentrates demand in the United States as en-route centers modernize oceanic and remote sectors where radar coverage gaps persist.
- Ground-Based Control:Legacy radar consoles and VHF voice relay installations from the 1980s-1990s retain functional service life across congested terminal areas. Municipal airport authorities in Spain and Italy defer replacement despite performance limitations, compressing vendor maintenance revenue.
- Radar Systems:Primary and secondary surveillance radar operating on 1030/1090 MHz frequencies maintains aircraft separation in high-density corridors.
- Satellite Communication:ADS-B transponders and data-link infrastructure enable trajectory-based operations beyond ground radar range.
Most installed capacity flows through Ground-Based Control. Expansion is steepest in Automated Systems.
End User:
Budget authority and procurement timelines diverge sharply between sovereign entities with multi-year appropriations and commercial operators managing quarterly capital cycles.
- Government Agencies:FAA, EUROCONTROL, and national air navigation service providers command multi-billion-dollar modernization mandates with decade-long implementation horizons. Certification requirements for safety-critical software filter out smaller suppliers from federal tenders.
- Airports:Municipal and regional authorities across fragmented ownership structures face acute budget constraints. Unbundling of maintenance contracts from initial procurement creates discrete service markets for software updates and sensor calibration.
- Airlines:Commercial fleet operators retrofit ADS-B In capability to comply with ICAO distress tracking mandates.
- Military:NATO-aligned defense ministries procure hardened surveillance platforms with interoperability requirements for joint operations.
Procurement volume concentrates with Government Agencies. Commercial flexibility is greatest among Airlines.
Service Type:
Revenue recognition patterns split between long-term managed service contracts and discrete hardware installations with attached maintenance riders.
- Air Traffic Management:Integrated flow management and separation assurance across en-route, terminal, and surface operations. EUROCONTROL Single European Sky mandates drive synchronized procurement cycles among member states dismantling national airspace boundaries.
- Surveillance Services:Radar and ADS-B sensor networks with real-time aircraft positioning. Remote tower virtualization enables low-density airfields to consolidate services through centralized feeds, reducing per-site infrastructure expenditure.
- Communications Services:VHF voice relay and data-link infrastructure for controller-pilot exchanges.
- Navigation Services:Ground-based and satellite augmentation systems for precision approach guidance.
Contract duration is longest for Air Traffic Management. Technology refresh cycles are shortest in Surveillance Services.
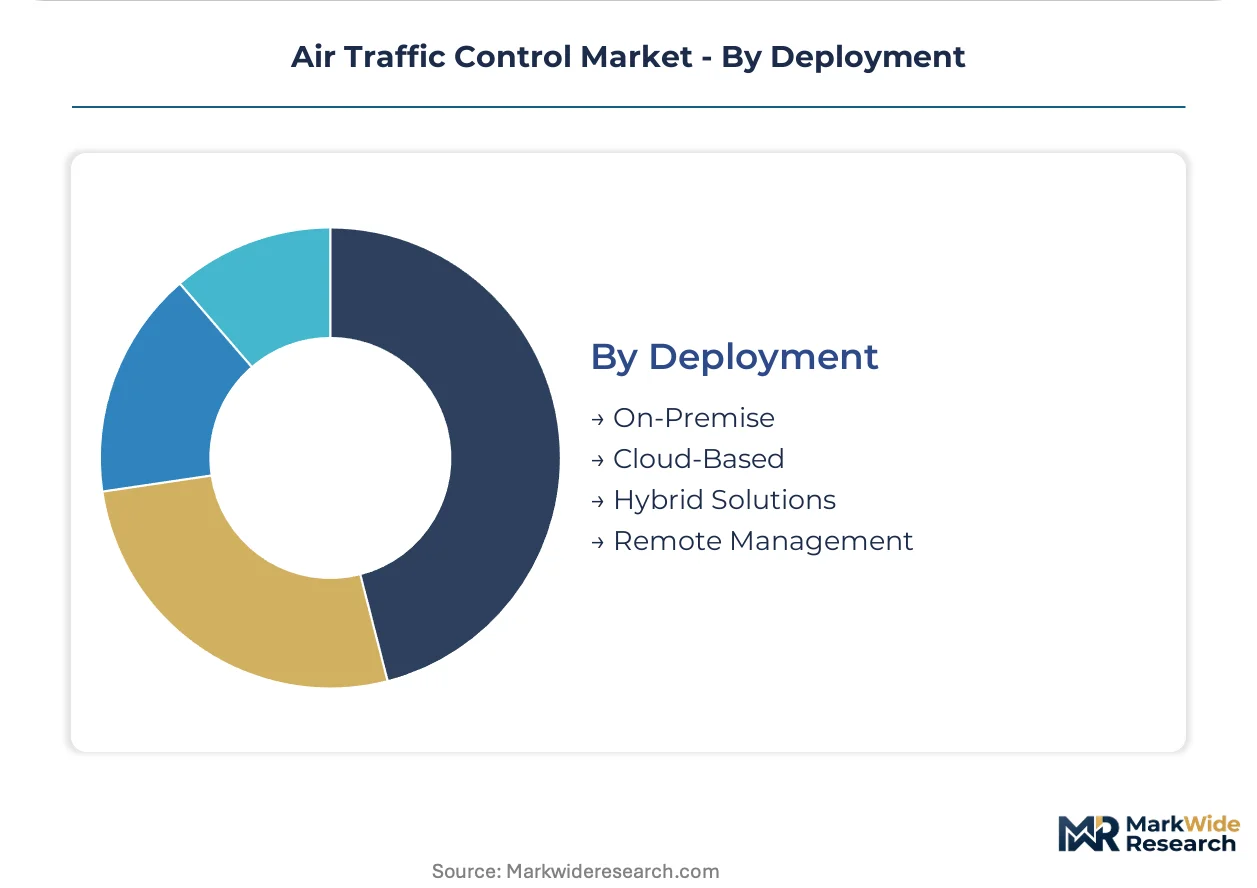
Deployment:
Operational risk tolerance determines architecture selection, with sovereign operators maintaining physical control over critical infrastructure while commercial adopters pursue cost elasticity.
- On-Premise:Dedicated hardware installations with air-gapped security architectures. FAA and EUROCONTROL control centers mandate physical isolation for radar data processing, excluding cloud alternatives from core safety-critical functions.
- Cloud-Based:Centralized sensor feeds and virtualized control positions for low-density airfields. Municipal authorities in Italy and Spain pilot these deployments where budget constraints dominate capital planning.
- Hybrid Solutions:Mixed architectures retaining on-premise safety functions with cloud-enabled administrative systems.
- Remote Management:Distributed technical oversight of geographically dispersed sensor networks.
Security certification requirements favor On-Premise for core functions. Cost pressure drives adoption of Cloud-Based for peripheral operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air traffic control infrastructure traces its modern lineage to post-war developments in the United States, where radar-based separation management first achieved operational scale before diffusing across NATO-aligned European states and Asia-Pacific commercial hubs.
United States
FAA NextGen mandates drive satellite-based surveillance procurement across congested coastal corridors and oceanic sectors. The Federal Aviation Administration's trajectory-based operations directive compels replacement of aging radar consoles with ADS-B infrastructure. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate en-route center modernization contracts.
Germany
EUROCONTROL Single European Sky requirements synchronize procurement cycles with France and the Netherlands for cross-border airspace consolidation. EASA DO-178C certification standards filter automation vendors for safety-critical software validation. Frankfurt and Munich airport authorities unbundle maintenance contracts from initial system procurement.
France
Functional airspace block implementation with neighboring Benelux states creates bundled tender opportunities for integrated surveillance platforms. The country's national aviation regulator enforces interoperability standards aligned with NATO procurement channels. Toulouse and Paris-Le Bourget aerospace clusters anchor radar and communication subsystem development.
United Kingdom
NATS Holdings manages North Atlantic corridor traffic through hybrid ground-satellite architectures serving transoceanic routes. CAA certification requirements maintain alignment with EASA safety-critical software standards post-Brexit. London Terminal Control Centre at Swanwick consolidates approach services for southeast England density.
Japan
METI coordinates civil-military airspace integration for Tokyo-Osaka corridor congestion relief through new route structures. JCAB procures automation platforms compatible with ICAO Global Aeronautical Distress and Safety System mandates. Osaka and Nagoya control centers pilot AI-based conflict detection for oceanic sector coverage gaps.
Air Traffic Control Market Vendor Landscape
The competitive structure tilts toward federally-anchored system integrators with multi-decade procurement relationships. Prime contractors maintain positions through air-gapped security clearances and safety-critical software certification rather than price competition. Two strategic archetypes dominate: vertically integrated electronics conglomerates spanning surveillance and communication payloads, and specialized automation software houses with ANSP-specific validation histories. Consolidation moves center on acquiring niche sensor technology, while portfolio diversification targets unmanned aircraft system integration contracts.
Among US-based defense-electronics conglomerates, L3Harris Technologies Inc. and Northrop Grumman Corporation occupy positions sustained by FAA and Pentagon dual-channel procurement. Thales Group represents the European archetype with certified automation platforms serving EUROCONTROL member states and NATO export channels. These three exemplify how long-term federal relationships and security-cleared engineering workforces function as structural barriers to new market entry.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| BAE Systems PLC |
| Thales Group |
| Northrop Grumman Corporation |
| Frequentis AG |
| Raytheon Technologies Corporation |
| Indra Sistemas S.A. |
| Saab AB |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Semiconductor-grade gallium nitride substrates for radar transmitters flow from specialist foundries through defense-certified tiers to municipal airport procurement desks, with EASA DO-178C validation costs separating premium automation vendors from price-competitive challengers serving fragmented regional authorities.
Pricing Analysis
Project-based contracting with decade-long maintenance riders dominates federal procurement, while subscription-based SaaS tiers emerge for remote tower virtualization deployments. Price differentiation hinges on safety-critical software certification grade and geographic delivery complexity for on-premise installations. Cost compression in the municipal airport tier intensifies because Italian and Spanish authorities unbundle maintenance from initial capital outlays. Government agencies exhibit least price sensitivity due to FAA NextGen mandate timelines, whereas regional airport authorities face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with precision radar magnetron suppliers concentrated in the United States, Germany, and Japan. Raw material dependencies span rare-earth elements for antenna arrays, high-purity aluminum for waveguides, and radiation-hardened semiconductors for safety-critical processing. Tariff exposure on Chinese-sourced rare-earth magnets generates supply chain risk for European automation vendors. Distribution runs through federally-cleared system integrators with multi-decade ANSP relationships rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air traffic control market functions as a regulatory compounder where FAA NextGen trajectory-based operations mandates and EUROCONTROL Single European Sky interoperability requirements generate sustained procurement velocity regardless of commercial aviation cyclicality.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Deepen software validation capabilities for EASA DO-178C compliance to exclude emerging automation challengers from European tenders. Acquire niche sensor technology specialists to close capability gaps in AI-based conflict detection systems before cloud-native entrants achieve safety-critical certification. For New Entrants and Emerging Players: Remote tower virtualization SaaS platforms represent the most penetrable entry vector. Target municipal airport authorities in Spain and Italy where budget constraints override incumbent loyalty and cloud-based deployment models bypass capital approval cycles. Lead with outcome-based pricing tied to per-aircraft-handled metrics rather than upfront infrastructure costs. For Investors and Strategic Acquirers: Consolidation pressure builds where AI-based trajectory optimization capabilities fragment across specialist software houses lacking federal certification histories. Frame long-term viability around 5-10 year regulatory refresh cycles rather than commercial aviation traffic growth. Watch for ICAO distress tracking mandate implementation timelines as the inflection signal for ADS-B In retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Safety-Critical Software Certification | EASA DO-178C validation opens EUROCONTROL tender access for automation vendors. |
| Remote Tower Virtualization Deployment | Cloud-based sensor feeds reduce per-site infrastructure for Italian municipal airports. |
| AI Conflict Detection Integration | Machine-learning trajectory modeling addresses oceanic radar coverage gaps for FAA. |
| Unmanned Aircraft System Protocol Development | Beyond-visual-line-of-sight drone corridors create mixed-use airspace automation contracts. |
| Urban Air Mobility Infrastructure Buildout | Vertiport control systems for electric aircraft establish greenfield vendor relationships. |
Methodological Framework
Bottom-up air navigation service provider procurement tracking reconciled against top-down defense electronics manufacturer order intake forms the analytical core of this study. Primary interviews with FAA program directors, EUROCONTROL procurement leads, airport authority capital planners, and automation software engineering heads combined with secondary validation from FAA NextGen implementation reports, EUROCONTROL SESAR deployment databases, EASA certification registries, and national ANSP annual procurement disclosures.
Input-output matrices map technology refresh cycles across automated systems, ground-based control, radar installations, and satellite communication infrastructure against end-user budget authority from government agencies, airports, airlines, and military operators. CAGRs derive from segmented demand modeling across deployment architectures including on-premise, cloud-based, hybrid solutions, and remote management configurations. Forecast inputs incorporate FAA NextGen mandate compliance timelines and EUROCONTROL interoperability standard implementation schedules.
Regulatory mandate delays, controller workforce shortage acceleration, and cyber-physical security incident frequency are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about sustained federal modernization appropriations and cross-border airspace consolidation political will. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Europe Inertial Systems Market