
 In Flight Connectivity Market | 2026-2036
In Flight Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
In Flight Connectivity Market Intelligence
A bifurcated demand from consolidated legacy carriers seeking fleet-wide standards and a fragmented base of low-cost airlines needing modular solutions is restructuring the supplier landscape. Panasonic Avionics Corporation leverages its entrenched position in in-flight entertainment systems to bundle connectivity. Viasat Inc. competes aggressively on bandwidth capacity using its proprietary satellite infrastructure. Thales Group differentiates through its integrated cockpit and cabin electronics portfolio.
In-flight connectivity comprises the hardware and services enabling internet and data transmission to aircraft during flight. Systems typically involve a fuselage-mounted antenna, onboard modem, and local network servers communicating via satellite or ground-based towers. Satellite technology, particularly Ka-band and emerging LEO constellations, now dominates the market for long-haul routes. Within service types, basic internet access is becoming a standard expectation, shifting the value proposition toward tiered bandwidth options and on-demand content.
Regulatory approvals from bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) are critical for market access. These agencies mandate rigorous testing for Supplemental Type Certificates (STCs) to ensure new antenna installations do not compromise aircraft safety or avionics. Future competitive advantage will depend on a provider's ability to secure multi-region certifications efficiently and offer a clear upgrade path for new satellite networks.
Market Dynamics
The accelerated deployment of multi-orbit satellite constellations, particularly in Low Earth Orbit, is the central force reordering the market. This technological shift is creating intense price and performance competition, forcing incumbent providers to adapt their hardware and service models to compete with new entrants.
Growth Catalysts
- Passenger Demand:A baseline expectation for reliable Wi-Fi from commercial aviation passengers, especially on long-haul flights, compels airlines to invest in connectivity as a competitive differentiator and a source of ancillary revenue.
- LEO Satellite Technology:The operational rollout of Low Earth Orbit (LEO) satellite networks provides a step-change in available bandwidth and lower latency, enabling services previously not possible, such as high-definition video streaming and real-time gaming.
- Regulatory Streamlining:Efforts by agencies like the US Federal Aviation Administration to create more efficient pathways for Supplemental Type Certificates (STCs) reduce the time and cost for airlines to equip or retrofit their fleets with new systems.
Market Restraints
- High Capital Expenditure:The significant upfront cost of aircraft hardware, including radomes, antennas, and modems, combined with the expense of installation and certification, presents a major barrier, particularly for smaller airlines or older fleets.
- Long Installation Cycles:Taking an aircraft out of service for connectivity system installation represents a substantial loss of revenue, leading airlines to align retrofits with heavy maintenance checks, which can delay fleet-wide deployment.
- Bandwidth Scarcity in High-Traffic Corridors:Despite new capacity, popular flight routes like the North Atlantic or trans-pacific corridors can experience bandwidth contention during peak hours, degrading service quality for existing geostationary satellite systems.
Strategic Opportunities
- Business and Private Aviation:The business and general aviation segments remain underpenetrated with high-throughput systems, offering a significant growth opportunity for providers who can offer scalable, lightweight, and cost-effective hardware solutions.
- Operational Data Services:Connectivity can be leveraged for non-passenger applications, including real-time aircraft health monitoring, predictive maintenance data offloading, and enhancing electronic flight bag capabilities for pilots.
- Tiered Service Monetization:The move from offering free basic connectivity to a model with multiple paid tiers for higher bandwidth and specific applications allows airlines to generate direct revenue from their investment.
Industry Challenges
- System Integration Complexity:Integrating new connectivity hardware and software with a diverse array of existing aircraft types, legacy avionics, and in-flight entertainment platforms presents a considerable technical and logistical challenge for providers and airlines.
- Multi-Region Certification Hurdles:Securing the necessary STCs and operational approvals from different national and regional aviation authorities, such as the FAA and EASA, is a complex and time-consuming process that can delay service launches.
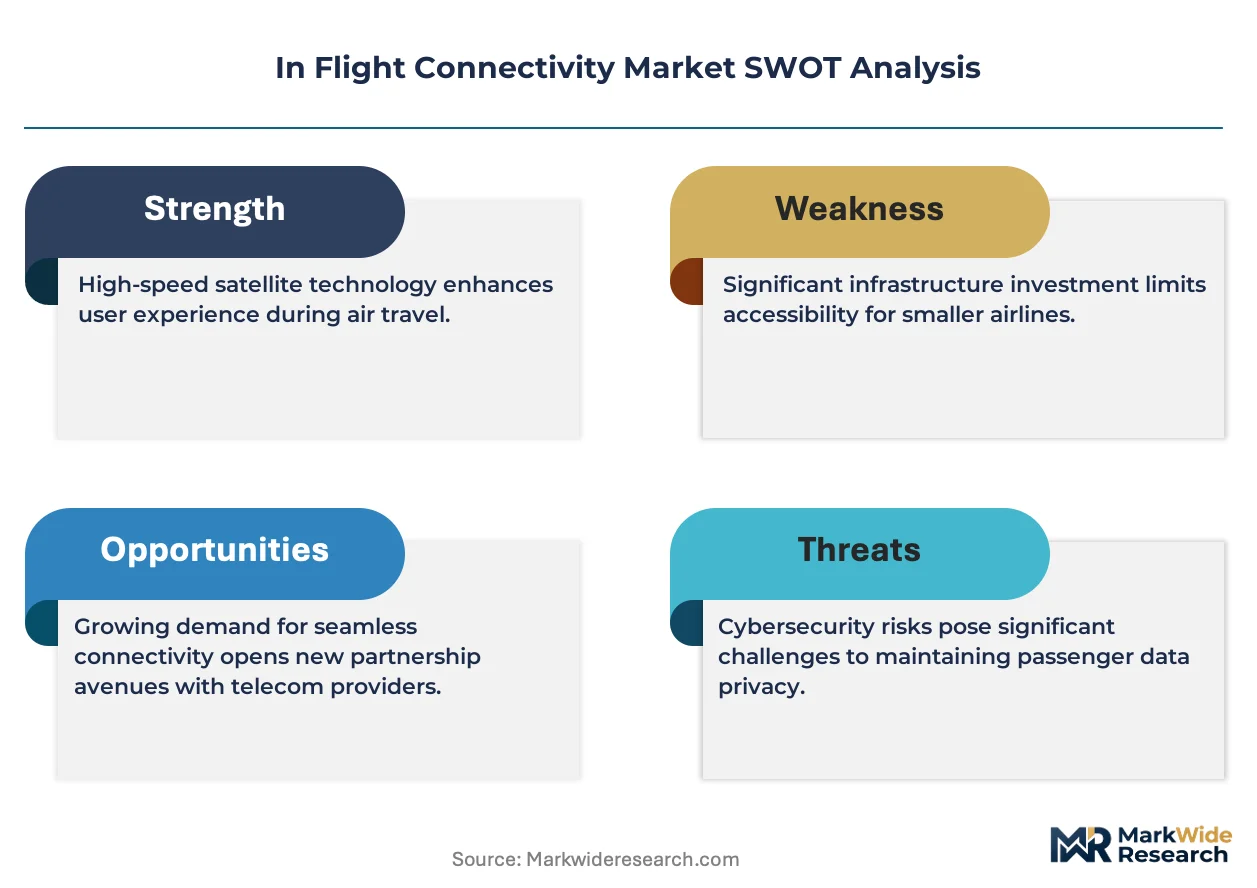
- Cybersecurity Vulnerabilities:As aircraft become more connected, they also become more exposed to cybersecurity threats, requiring robust security architectures to protect both passenger data and critical aircraft systems from intrusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Flight Connectivity Market |
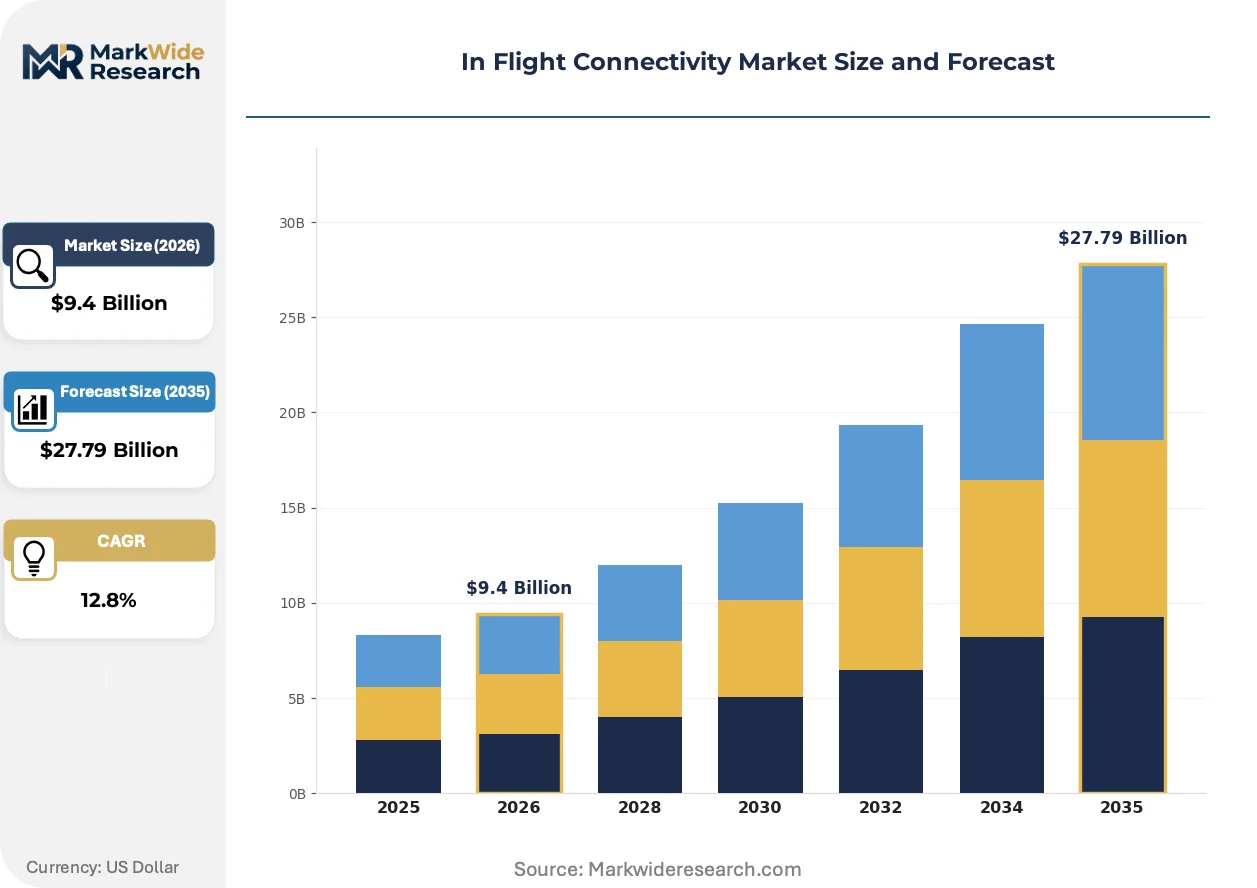
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $27.79 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Satellite, Air-to-Ground, Hybrid, Direct Line Service Type: Internet Access, In-flight Entertainment, On-demand Content, Voice Services End User: Commercial Airlines, Private Jets, Military Aircraft, Charter Services Installation: Line-fit, Retrofit, Modular, Integrated Systems |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Gogo Inc., Viasat Inc., Intelsat S.A., Inmarsat Global Ltd., Collins Aerospace, Anuvu, Astronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Flight Connectivity Market Strategic Shifts & Innovations
A fundamental shift from hardware-centric sales to software-defined, service-oriented business models is underway. This transition reflects the commoditization of bandwidth and the growing importance of the passenger experience and operational data analytics as key value drivers for airlines.
Electronically steered antennas (ESAs) represent a pivotal evolution in aircraft connectivity hardware. These low-profile, solid-state antennas can track and switch between satellites without mechanical parts. Airlines operating mixed fleets for both regional and intercontinental routes are the primary adopters, valuing the flexibility and reduced drag of ESAs. This technology is modularizing the hardware installation, enabling future upgrades and connections to different satellite networks, including LEO and GEO, through software rather than physical replacement.
The International Telecommunication Union (ITU) is actively managing radio-frequency spectrum allocation for non-geostationary satellite orbit (NGSO) constellations. This global coordination provides the regulatory framework necessary for LEO and MEO operators to deploy and operate their networks without signal interference. The commercial aviation sector benefits directly from this process, as it fosters a competitive supply of satellite bandwidth, which is expected to drive down costs and improve service availability.
Airlines are increasingly unbundling hardware procurement from long-term service contracts. This change disrupts the traditional integrated supplier model, creating space for new players focused purely on service delivery or specialized hardware. The trend is most visible within the North American low-cost carrier segment, where airlines prioritize operational agility and avoid vendor lock-in to adapt quickly to new technologies and pricing models as they emerge.
In Flight Connectivity Market Segmentation
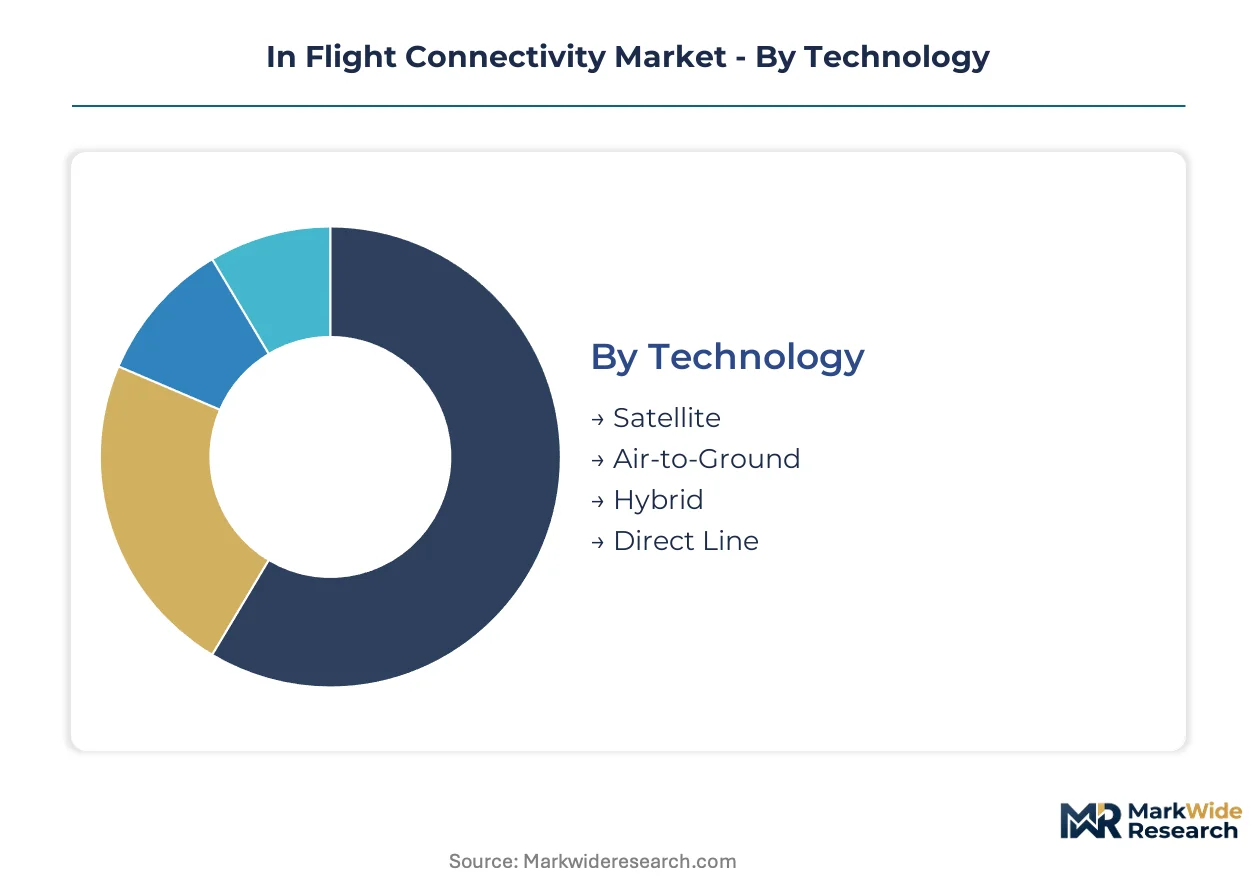
Understanding the In Flight Connectivity Market requires a detailed segmentation analysis to identify distinct customer needs and technological preferences. This breakdown illuminates varied adoption patterns across different aircraft types and operational models. Market participants can strategically tailor their offerings by recognizing these granular differences.
Technology:
Buyer differentiation in the In Flight Connectivity Market is fundamentally driven by the underlying technology's performance and coverage capabilities.
- Satellite:This technology utilizes geostationary (GEO) or low Earth orbit (LEO) satellites to provide internet access, dominating long-haul routes. The deployment of LEO constellations, like Starlink, significantly boosts bandwidth and reduces latency for airlines globally.
- Hybrid:Hybrid systems integrate multiple connectivity technologies, often combining satellite with air-to-ground (ATG) or other solutions for optimized performance and redundancy. Airlines value hybrid setups for seamless coverage transitions across diverse flight geographies, enhancing passenger experience.
- Air-to-Ground:ATG systems rely on ground-based cellular towers, offering high bandwidth and low latency over landmasses, primarily used in North America and Europe.
- Direct Line:Direct line solutions often refer to point-to-point connections or specialized military/government links, providing secure and dedicated bandwidth for specific operational needs.
Satellite technology leads volumes today; Hybrid systems are gaining share fastest.
Service Type:
Service type segmentation reflects the diverse applications for in-flight connectivity, ranging from basic communication to advanced entertainment options.
- Internet Access:This service provides passengers with basic web browsing, email, and messaging capabilities, now considered a standard offering on most commercial flights. Demand for reliable internet access drives airline investment, especially on international routes.
- On-demand Content:On-demand content delivery allows passengers to stream movies, TV shows, and music directly to their personal devices or seat-back screens. This service type generates significant ancillary revenue for airlines, enhancing the overall in-flight experience.
- In-flight Entertainment:Traditional IFE systems offer pre-loaded media, games, and flight information, often delivered via seat-back screens, complementing or integrating with connectivity services.
- Voice Services:Voice services enable passengers to make calls or use VoIP applications during flight, though adoption remains limited due to regulatory restrictions and passenger preference for quiet cabins.
Demand for Internet Access remains strong, while On-demand Content shows significant expansion.
End User:
Customer type dictates connectivity requirements, with each end-user segment prioritizing different aspects of service delivery and cost efficiency.
- Commercial Airlines:This segment includes major and low-cost carriers, representing the largest volume demand for in-flight connectivity solutions. Commercial airlines seek robust, scalable systems to meet passenger expectations and generate ancillary revenue.
- Private Jets:Private aviation clients demand highly reliable, high-bandwidth connectivity for business productivity and personal entertainment, often prioritizing bespoke service and discreet installations. This segment remains underpenetrated by advanced systems.
- Military Aircraft:Military applications require highly secure, resilient, and specialized connectivity for operational communications and data transfer, often involving custom hardware and encryption.
- Charter Services:Charter operators require flexible connectivity solutions that can adapt to varied client needs and aircraft types, balancing cost-effectiveness with service quality.
While Commercial Airlines accounts for the largest share, Private Jets is experiencing substantial uptake.
Installation:
Installation methods define the operational approach for integrating connectivity systems, influencing deployment timelines and long-term upgrade pathways.
- Retrofit:Retrofit installations involve integrating connectivity systems into existing aircraft fleets, often performed during scheduled maintenance checks. This approach allows airlines to upgrade older aircraft without immediate replacement, extending their operational lifespan.
- Modular:Modular systems are designed for flexible integration and future upgrades, allowing components to be swapped out or added as technology evolves. This approach reduces vendor lock-in and simplifies transitions to new satellite networks for airlines.
- Line-fit:Line-fit installations occur during the aircraft manufacturing process, integrating connectivity systems directly into new aircraft designs. This method ensures optimal system integration and aerodynamic efficiency from the outset.
- Integrated Systems:Integrated systems combine connectivity hardware with other aircraft systems, such as in-flight entertainment or avionics, for streamlined operation and reduced complexity.
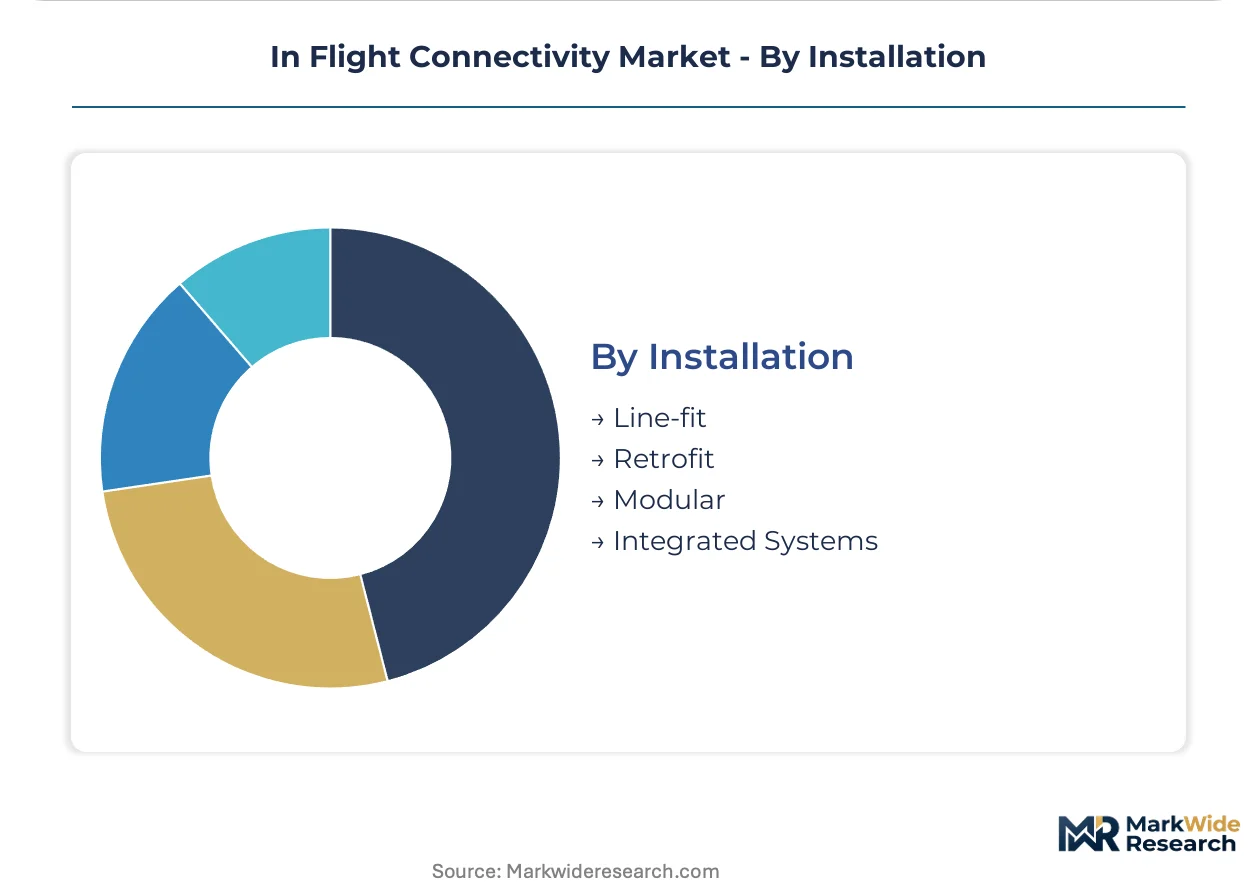
The shift towards Retrofit and Modular solutions reflects evolving airline operational strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States passenger demand for reliable in-flight Wi-Fi sets a high benchmark, while China's rapidly expanding domestic aviation market drives significant investment in connectivity infrastructure. Both nations prioritize seamless air travel experiences for their vast populations. European Union Aviation Safety Agency (EASA) regulations also influence technology choices across the continent.
United States
A large domestic aviation market and high passenger expectation for Wi-Fi compel airlines to upgrade their fleets. The US Federal Aviation Administration (FAA) Supplemental Type Certificate (STC) process is crucial for new installations on aircraft. Seattle's aerospace hub fosters innovation in aircraft system integration and connectivity solutions.
Germany
This nation serves as a major European hub for long-haul carriers and business travel, creating substantial demand for robust connectivity. European Union Aviation Safety Agency (EASA) certification defines market access and operational standards for in-flight systems. Hamburg hosts significant aircraft maintenance facilities, facilitating retrofit projects for connectivity solutions.
China
Rapid growth in domestic air travel and increasing demand for digital services from passengers are key drivers for connectivity adoption. Civil Aviation Administration of China (CAAC) approvals are essential for system deployment and operational compliance. Beijing and Shanghai airports drive demand for advanced connectivity solutions across commercial fleets.
India
An expanding middle-class air travel segment and strong digital adoption trends among consumers fuel the demand for in-flight Wi-Fi. The Directorate General of Civil Aviation (DGCA) mandates safety and operational standards for all aircraft modifications. Bengaluru's tech ecosystem supports local development of digital in-flight services and hardware integration.
Japan
High-speed rail competition and premium passenger experience expectations incentivize airlines to invest in superior connectivity. The Japan Civil Aviation Bureau (JCAB) oversees stringent aviation safety requirements for all installed systems. Tokyo's major international airports serve as key deployment sites for advanced in-flight connectivity solutions.
In Flight Connectivity Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic market structure for in-flight connectivity. The market is bifurcated between legacy players offering integrated solutions and agile new entrants bringing specialized satellite technology. Strategic archetypes include satellite operators leveraging proprietary infrastructure, avionics integrators bundling solutions, and service providers focusing on software and content. Dominant competitive moves involve strategic partnerships to expand coverage and technology licensing to integrate new Low Earth Orbit capabilities.
Panasonic Avionics Corporation exemplifies an entrenched player, leveraging its well-established position in in-flight entertainment systems to offer bundled connectivity solutions to commercial airlines. Thales Group, a France-based aerospace and defense company, occupies a distinct position as an integrated cockpit and cabin electronics provider, differentiating through its comprehensive portfolio offerings that span multiple aircraft systems. Viasat Inc., a US-based satellite communications company, represents a specialist focused on aggressive bandwidth capacity, utilizing its proprietary satellite infrastructure to compete effectively in the market. These companies collectively illustrate the varied approaches to market penetration and service delivery within the in-flight connectivity sector.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Gogo Inc. |
| Viasat Inc. |
| Intelsat S.A. |
| Inmarsat Global Ltd. |
| Collins Aerospace |
| Anuvu |
| Astronics Corporation |
Cost & Logistics Intelligence
The global semiconductor price index influences hardware costs, which then cascade through the in-flight connectivity supply chain, affecting system pricing and service tier differentiation for airlines.
Pricing Analysis
Capacity additions in Low Earth Orbit (LEO) satellite constellations are reshaping price floors for in-flight connectivity solutions. The dominant pricing model is subscription-based, often with tiered service levels reflecting bandwidth and content access. Price differentiation stems from guaranteed throughput, system integration complexity, and comprehensive after-sales support. Pricing pressure intensifies due to commoditization of basic internet access and aggressive LEO competition, with low-cost carriers exhibiting high price sensitivity compared to private jet operators prioritizing bespoke reliability.
Supply Chain Analysis
Domestic-content mandates in aviation, such as those encouraged by US federal programs, are reshaping sourcing for in-flight connectivity hardware. The supply chain concentrates electronics manufacturing in China and the US, with Europe providing critical avionics integration. Key dependencies include advanced semiconductors, proprietary antenna arrays, and robust radome materials. Single-source vulnerability for next-generation LEO satellite terminals poses a structural risk, while distribution primarily runs through direct sales from system integrators to airlines via MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In Flight Connectivity Market is a stable compounder, driven by the persistent passenger demand for ubiquitous and reliable internet access during air travel. Airlines view connectivity as both a competitive differentiator and a source of ancillary revenue.
For Market Incumbents: To counter aggressive LEO new entrants and the commoditization of basic connectivity, incumbents must deepen integration with in-flight entertainment platforms. They should prioritize investment in next-generation Electronically Steered Antenna (ESA) technology to offer modular, future-proof hardware. Securing multi-region certifications efficiently represents a critical lever for market access and fleet-wide deployment, solidifying their entrenched positions.
For New Entrants and Emerging Players: LEO satellite capabilities offer a technology-first wedge into the market, enabling superior bandwidth and lower latency services. Target the underpenetrated business and private aviation segments with lightweight, scalable hardware solutions. Focus on operational data services for airlines as a distinct revenue stream. A go-to-market angle emphasizing flexible, usage-based service models will appeal to North American low-cost carriers seeking agility.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hardware developers and software-defined service providers in the in-flight connectivity sector. The market demonstrates long-term viability over the next decade, driven by sustained passenger demand and global LEO network expansion. Acquisition targets should include agile pure-play specialists with proprietary LEO-compatible hardware or advanced operational data analytics platforms. Rapid adoption rates of Electronically Steered Antenna (ESA) technology in retrofit programs serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Multi-Orbit ESAs | Enables airlines to seamlessly switch between LEO and GEO networks, enhancing flexibility and coverage. |
| Secure Multi-Region STCs | Accelerates market access for new systems by meeting diverse regulatory approvals from FAA and EASA. |
| Expand Operational Data Services | Leverages connectivity for real-time aircraft health monitoring and predictive maintenance data offloading. |
| Form LEO Satellite Partnerships | Ensures access to next-generation high-bandwidth, low-latency connectivity for global airline fleets. |
| Offer Modular Hardware Solutions | Reduces vendor lock-in for airlines and simplifies future upgrades to new satellite technologies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary research involved discussions with airline procurement managers, avionics engineers, satellite operators, and MRO facility heads. Secondary data sources included FAA and EASA regulatory filings, ITU spectrum allocation documents, and aerospace industry publications. This approach ensured comprehensive bottom-up and top-down triangulation of market data.
The segment-weighting approach systematically modeled the market across the analysis window, integrating various dimensions including technology, service type, end user, and installation method. This analytical framework also considered aircraft fleet age as an industry-specific dimension. Compound Annual Growth Rates were derived from historical trends and projected technological advancements in satellite communication. Key forecast inputs included LEO satellite deployment schedules and global aircraft delivery forecasts.
The model holds under current regulatory stability and projected LEO satellite rollout; deviation in unforeseen geopolitical conflicts or major aviation demand shifts would shift forecast trajectories. Forecasts reflect these underlying assumptions and acknowledged risks like cybersecurity vulnerabilities or satellite launch delays. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market